
 Iridescent Pigments Market | 2026-2036
Iridescent Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Iridescent Pigments Market Foresight
Asset-light leasing arrangements for specialized milling and coating equipment is fragmenting competitive entry barriers in iridescent pigment production. Merck KGaA leverages its vertically integrated mica supply chain to sustain premium positioning in optical interference flakes. BASF SE anchors high-volume powder production through controlled precipitation chemistry at scale. PPG Industries competes via direct channel relationships with automotive OEMs for custom color-matching programs.
Iridescent pigments are thin-film optical materials, typically constructed from metal-oxide-coated mica substrates or synthetic silica flakes ranging from 5 to 200 micrometers, engineered to produce angle-dependent color shifts through light interference. Their primary commercial purpose is to impart dynamic visual effects to coatings, plastics, and cosmetic formulations where static colorants fail to achieve dimensional depth. The coatings application segment leads absolute volume due to automotive and industrial maintenance demand, while cosmetics represents the fastest-expanding margin pool as prestige brands seek differentiated packaging and formulation aesthetics. Flake-based products dominate technical specifications for high-performance aerospace and automotive finishes, whereas liquid dispersions are gaining share in inkjet and flexographic printing systems.
REACH registration requirements and RoHS substance restrictions in Europe compel reformulation away from cadmium and lead-based precursors, directly redirecting R&D budgets toward synthetic substrate development. The EPA oversees comparable heavy-metal discharge limits in US manufacturing facilities, while China's MEE enforces dual carbon goals that elevate energy costs for wet-processing pigment operations. Stakeholders must monitor evolving per- and polyfluoroalkyl substance regulations, as fluoropolymer-treated iridescent grades face prospective substitution mandates across multiple jurisdictions.
Market Dynamics
Automotive OEM color-matching programs are compressing formulation cycles and forcing pigment suppliers to co-locate technical service teams near assembly plants, restructuring the traditional distributor-led supply model.
Growth Catalysts
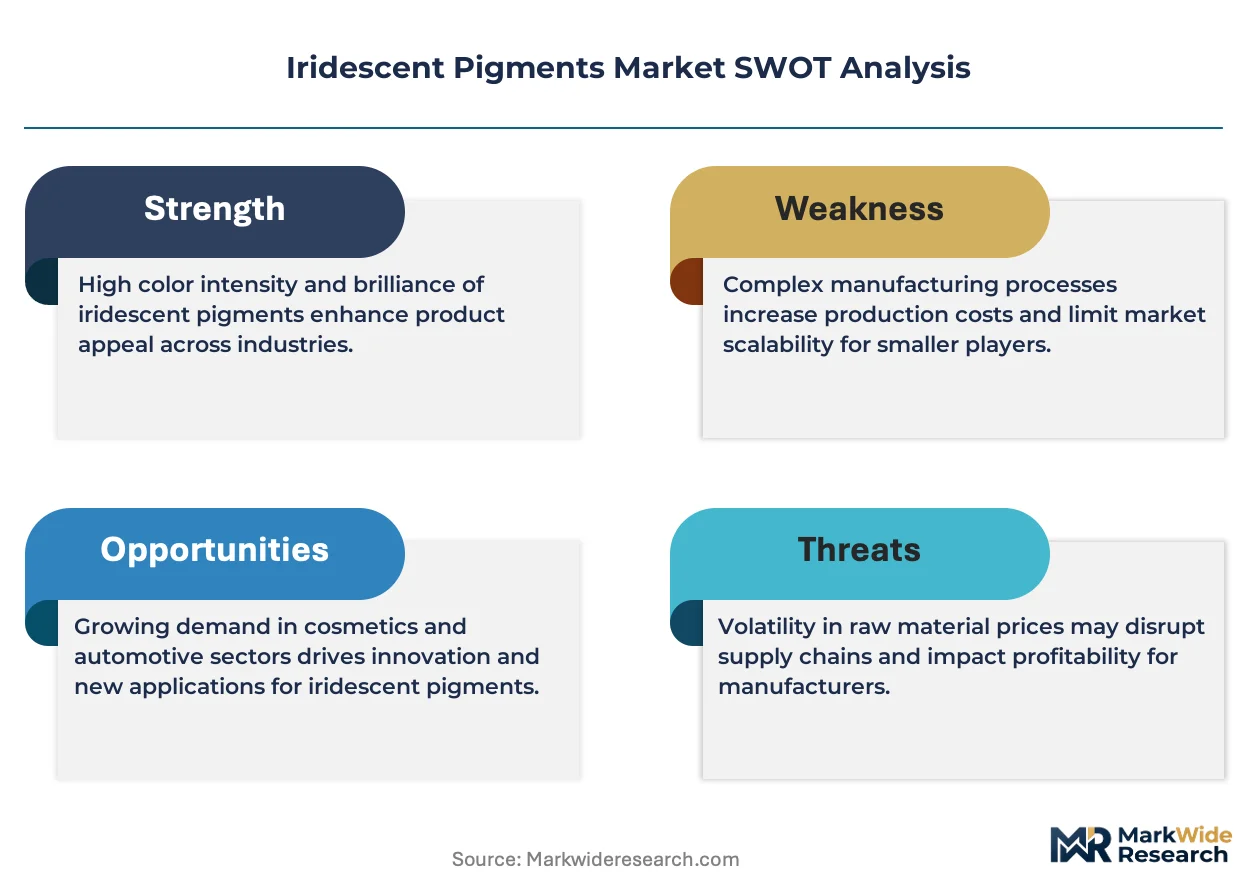
- REACH substance registration:European reformulation mandates away from cadmium and lead precursors are redirecting R&D budgets toward synthetic silica substrates. This creates first-mover advantages for compliant suppliers.
- Prestige cosmetics packaging:Luxury brands are specifying iridescent effects for limited-edition launches, expanding margin pools beyond industrial coatings into high-value personal care applications.
- Asset-light equipment leasing:Specialized milling and coating machinery available through operating leases is lowering capital barriers for regional pigment compounders in Southeast Asia.
Market Restraints
- Mica supply concentration:High-purity natural mica deposits concentrate in India and Madagascar, exposing processors to export licensing volatility and geopolitical friction.
- Fluoropolymer regulatory exposure:Per- and polyfluoroalkyl substance restrictions under EPA and state-level frameworks threaten treated iridescent grades across multiple jurisdictions.
- Energy-intensive wet processing:China's dual carbon goals enforced by MEE are elevating power costs for aqueous precipitation operations, compressing margins for commodity flake producers.
Strategic Opportunities
- India personal care penetration:Domestic prestige cosmetics brands are accelerating iridescent adoption for festival-season packaging, outpacing industrial coating demand growth.
- Inkjet dispersion formats:Liquid iridescent concentrates compatible with drop-on-demand printheads are opening customized short-run packaging for craft beverage and direct-to-consumer beauty.
- EU Green Deal procurement incentives:Public sector purchasing guidelines favoring low-heavy-metal coatings are creating preferential access lanes for compliant pigment suppliers in municipal fleet and infrastructure projects.
Industry Challenges
- Optical interference formulation expertise:Thin-film physics competency required for custom color travel effects remains scarce, constraining technical service expansion for automotive direct accounts.
- Multi-jurisdiction substance dossier management:Parallel REACH, TSCA, and emerging chemical inventory registrations demand dedicated regulatory affairs headcount that mid-scale producers struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iridescent Pigments Market |
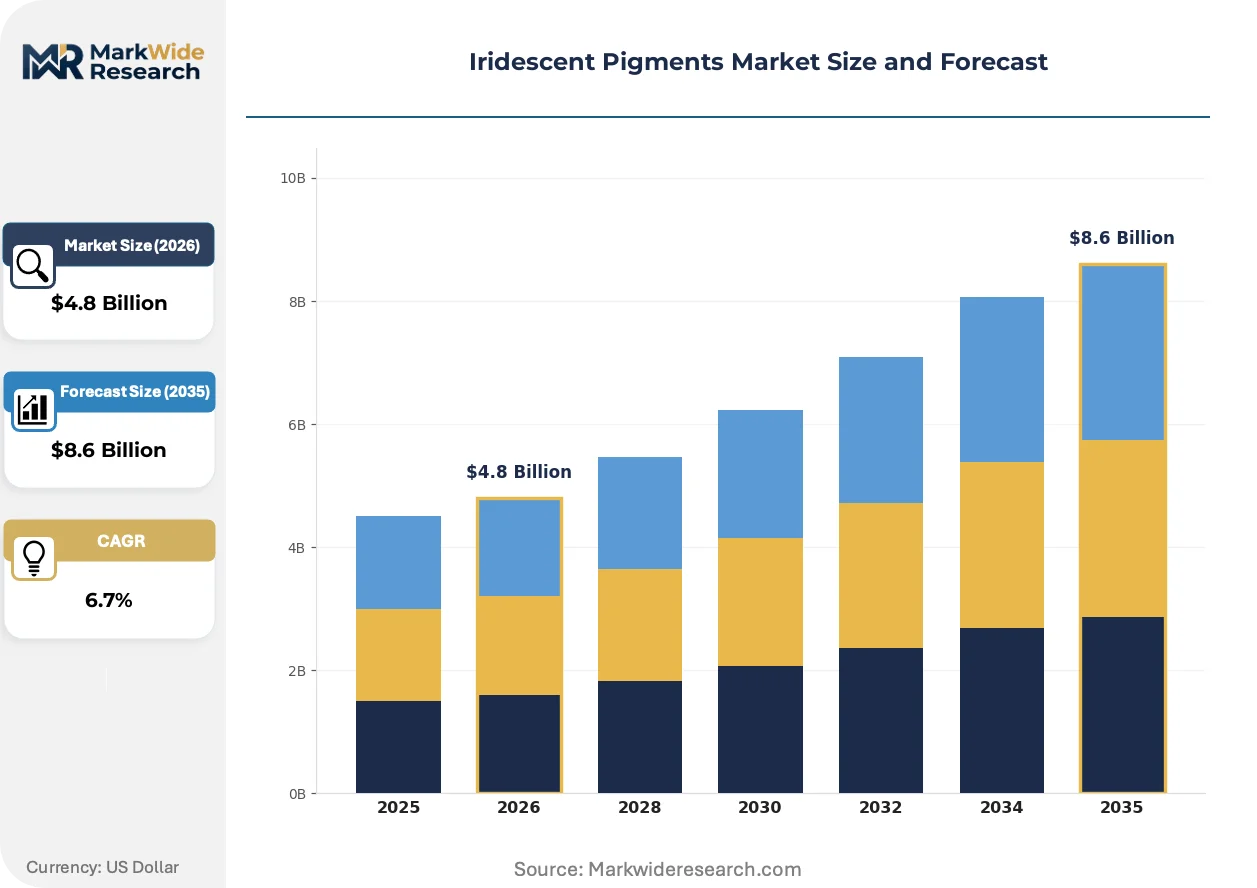
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
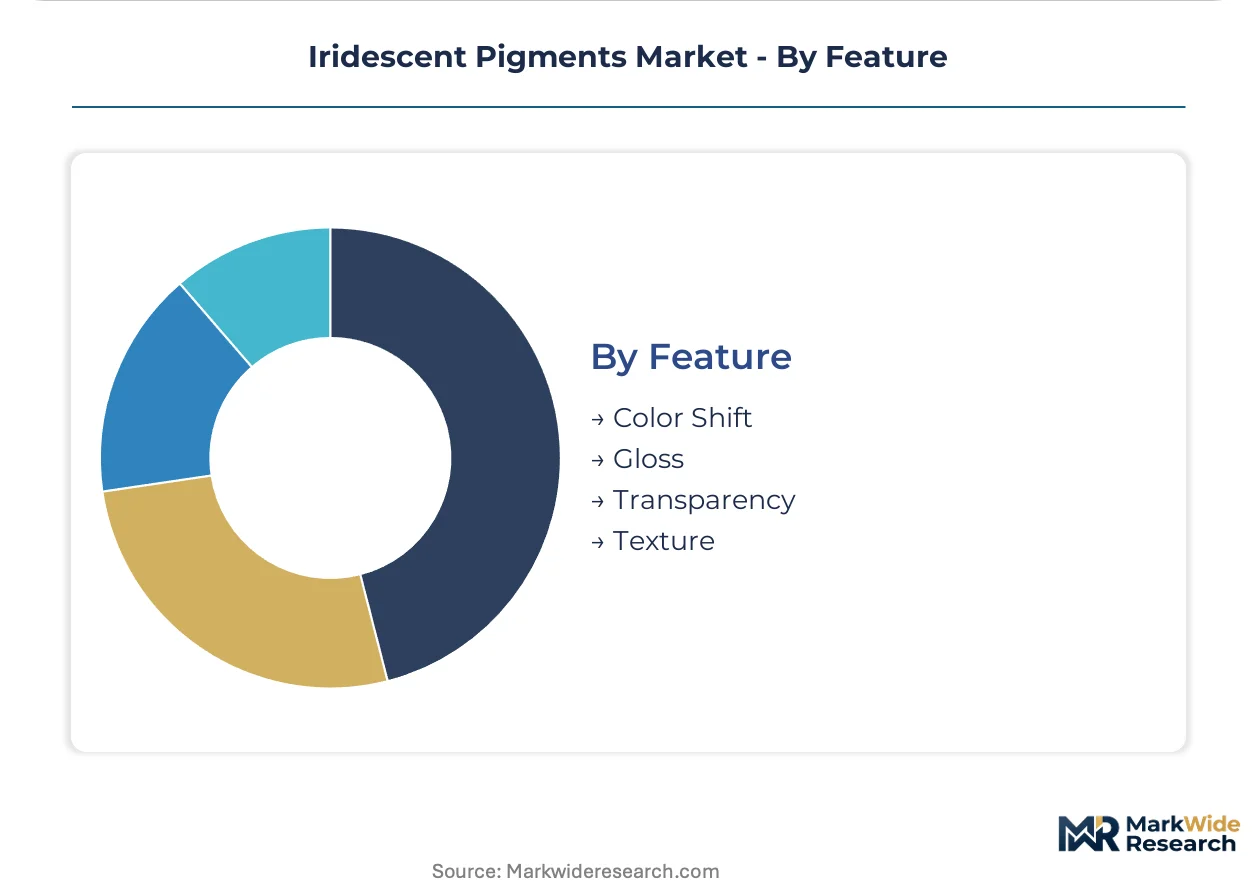
| Segmentation | Product Type: Flakes, Powders, Liquid, Granules Application: Coatings, Plastics, Inks, Cosmetics End User: Aerospace, Automotive, Consumer Goods, Packaging Feature: Color Shift, Gloss, Transparency, Texture |
| Companies Covered | BASF SE, AkzoNobel N.V., Merck KGaA, PPG Industries, Inc., Axalta Coating Systems Ltd., Nippon Paint Holdings Co., Ltd., Sherwin-Williams Company, Asian Paints Limited, Altana AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iridescent Pigments Market Shifts & Advancements
Synthetic substrate technologies and regulatory chemistry mandates are converging to redefine raw material sourcing and product architecture across all application tiers.
Multi-layer metal-oxide deposition onto synthetic silica flakes is collapsing the performance gap between natural mica and engineered substrates. Aerospace interior designers are specifying these materials for weight-critical cabin panels. The shift is compressing premium pricing tiers for conventional pearlescent grades.
RoHS heavy-metal thresholds are tightening enforcement across EU member states, compelling decorative coating formulators to validate supply chain certificates of analysis. Industrial maintenance contractors in Germany face audit pressure to document pigment provenance. The burden falls most heavily on spot-color matching services serving fragmented metal fabrication shops.
Automotive color stylists are bypassing traditional distributor networks to commission direct development agreements with pigment houses. Tier-one coating suppliers are consolidating approved vendor lists to three or fewer interference pigment sources. The pattern is most pronounced in Stuttgart and Munich, where OEM design studios maintain permanent technical liaison offices.
Iridescent Pigments Market Segmentation
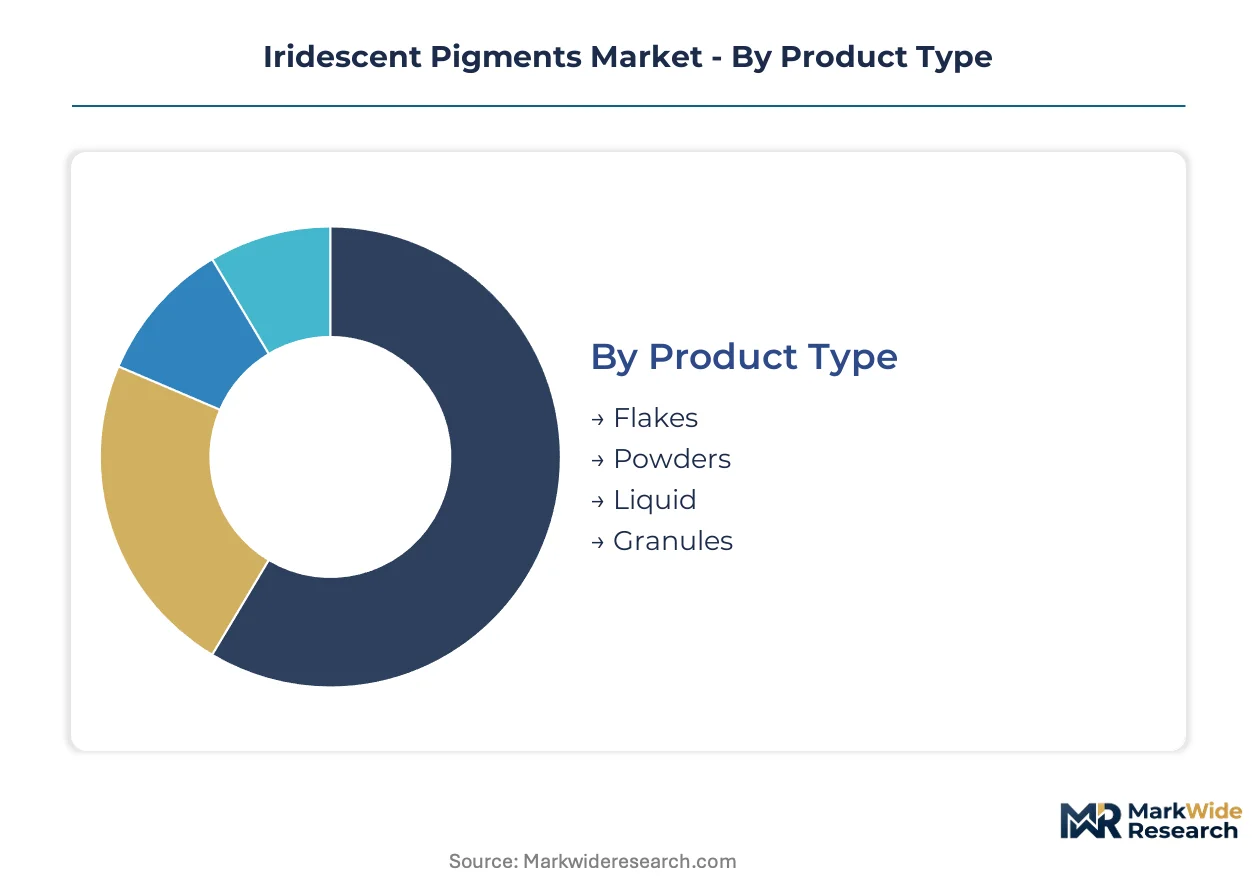
Iridescent pigment purchasing cycles vary dramatically by physical form and end-use specification. Automotive coating programs refresh color palettes every 18-24 months, while aerospace qualification timelines for interior cabin materials extend beyond five years. Understanding these velocity differentials informs inventory positioning and technical service resource allocation.
Product Type:
Flake formats command the longest qualification cycles due to optical interference calibration requirements, whereas liquid dispersions turn over fastest as inkjet packaging customers iterate seasonal designs.
- Flakes:Multi-layer metal-oxide-coated mica or synthetic silica substrates ranging 5-200 micrometers, engineered for angle-dependent color travel. Demand concentrates in Stuttgart and Munich automotive design studios where OEMs commission direct development agreements for exterior finishes, constrained by scarce thin-film physics formulation expertise.
- Liquid:Pumpable concentrates with controlled viscosity for drop-on-demand printheads, enabling customized short-run packaging for craft beverage and direct-to-consumer beauty brands. This segment is climbing the fastest as digital printing adoption accelerates in Southeast Asian contract packaging facilities.
- Powders:Free-flowing dry grades for high-volume powder coating operations in industrial maintenance applications.
- Granules:Dust-reduced agglomerated forms for automated dosing in thermoplastic compounding lines.
Flake formats dominate installed base across aerospace and automotive specification sheets. Liquid is where expansion concentrates as inkjet dispersion technology matures.
Application:
Coatings absorb the heaviest regulatory compliance burden through REACH and RoHS substance documentation, while cosmetics commands premium pricing with lighter certification overhead.
- Coatings:Automotive OEM color-matching programs compress formulation cycles and force pigment suppliers to co-locate technical service teams near assembly plants. Demand concentrates in Germany where BASF SE and Merck KGaA maintain specialized production facilities, restructuring traditional distributor-led supply models.
- Cosmetics:Prestige brands specify iridescent effects for limited-edition launches, expanding margin pools beyond industrial coatings. Domestic Indian prestige brands are accelerating adoption for festival-season packaging, outpacing industrial coating demand growth in that geography.
- Plastics:Masterbatch incorporation for consumer electronics housings and appliance panels requiring dimensional visual depth.
- Inks:Flexographic and gravure systems for decorative packaging with shorter run lengths than coatings.
Coatings retains the deepest specification lock-in through automotive approved vendor lists. Cosmetics represents the steepest expansion trajectory as luxury personal care brands differentiate through packaging aesthetics.
End User:
Automotive procurement operates through consolidated tier-one coating supplier relationships, while packaging fragments across thousands of short-run converters with spot-buying patterns.
- Automotive:Tier-one coating suppliers consolidate approved vendor lists to three or fewer interference pigment sources. Design studios in Stuttgart and Munich maintain permanent technical liaison offices, bypassing traditional distributor networks for direct pigment house commissions.
- Aerospace:Synthetic silica flake specifications for weight-critical cabin panels are gaining traction as multi-layer deposition technologies collapse performance gaps with natural mica grades.
- Consumer Goods:Electronics and appliance manufacturers specifying iridescent effects for product differentiation in saturated retail environments.
- Packaging:Craft beverage and direct-to-consumer beauty brands driving liquid dispersion adoption for customized short-run production.
Automotive dominates absolute volume through exterior finish programs. Packaging is where technology transfer from industrial to digital applications accelerates fastest.
Feature:
Color shift functionality commands the highest technical service intensity due to angular dependence calibration, while gloss specifications standardize more readily across customer bases.
- Color Shift:Angle-dependent interference effects requiring precise layer thickness control during metal-oxide deposition. Optical interference formulation expertise remains scarce, constraining technical service expansion for automotive direct accounts seeking custom color travel effects.
- Gloss:Specular reflection control for premium automotive and cosmetic applications where surface brilliance signals quality positioning.
- Transparency:See-through effects for layered packaging designs and automotive tinted clearcoats.
- Texture:Tactile dimensional finishes for luxury goods packaging and high-end interior surfaces.
Gloss dominates current specification volumes across established automotive programs. Color shift is where R&D investment concentrates as brands seek differentiated visual signatures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal procurement incentives are redirecting public sector coating specifications toward low-heavy-metal alternatives, while China's dual carbon goals enforced by MEE elevate energy costs for wet-processing operations. Germany and India concentrate specialized production and prestige cosmetics demand respectively.
Germany
Automotive OEM color-matching programs in Stuttgart and Munich compress formulation cycles and force pigment suppliers to co-locate technical service teams near assembly plants. REACH and RoHS compliance administered by ECHA tightens permissible heavy-metal content in decorative coatings. BASF SE and Merck KGaA maintain specialized production facilities for pearlescent and diffractive pigment technologies in Ludwigshafen and Darmstadt.
China
Commodity flake producers face margin compression as MEE-enforced dual carbon goals elevate power costs for aqueous precipitation operations. GB standards and SAMR oversight regulate industrial chemical discharge limits. Yangtze River Delta pigment compounders are adopting asset-light leasing arrangements for specialized milling equipment to fragment competitive entry barriers.
India
Domestic prestige cosmetics brands accelerate iridescent adoption for festival-season packaging, outpacing industrial coating demand growth. BIS certification requirements and DGFT export licensing govern specialty chemical trade. Maharashtra-based personal care manufacturers are expanding procurement of interference pigments for limited-edition launch aesthetics.
United States
EPA heavy-metal discharge limits shape manufacturing facility compliance strategies for wet-processing operations. Automotive coating suppliers consolidate approved vendor lists to three or fewer interference pigment sources. Michigan and Ohio assembly plant corridors host permanent technical liaison offices from major pigment houses.
Japan
METI industrial standards and JIS certification frameworks govern optical interference pigment specifications for consumer electronics housings. Kanto region coating formulators validate supply chain certificates of analysis under tightening RoHS-aligned thresholds. Tokyo-based masterbatch compounders incorporate iridescent effects for appliance panel differentiation.
Iridescent Pigments Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated substrate producers and specialized coating technology licensors. Three strategic archetypes dominate: captive mica processors with upstream mining control, synthetic silica substrate innovators, and automotive-direct technical service specialists. Competitive moves concentrate on co-location agreements with OEM design studios and operating lease structures for regional milling capacity.
Among Germany-based chemical conglomerates, BASF SE and Merck KGaA exemplify divergent scale strategies—one anchoring high-volume powder production through controlled precipitation chemistry, the other sustaining premium positioning via integrated mica supply chains. PPG Industries represents the automotive-direct archetype, competing through established channel relationships with OEMs for custom color-matching programs rather than substrate ownership.
| Leading Market Players |
|---|
| BASF SE |
| AkzoNobel N.V. |
| Merck KGaA |
| PPG Industries, Inc. |
| Axalta Coating Systems Ltd. |
| Nippon Paint Holdings Co., Ltd. |
| Sherwin-Williams Company |
| Asian Paints Limited |
| Altana AG |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta freight corridor carries synthetic mica substrates from Jiangsu processing hubs to German automotive coating facilities, with container rate volatility compressing margins for mid-tier flake compounders while amplifying price premiums for REACH-certified grades stocked in Rotterdam bonded warehouses.
Pricing Analysis
Certification level (REACH/RoHS-compliant versus legacy heavy-metal grades) creates the primary spread between premium and commodity tiers. Pricing stratifies across automotive-direct technical service bundles, standard industrial flake contracts, and spot-market powder lots. Cost compression in commodity mica-based grades is intensifying because Indian export licensing delays are forcing emergency procurement from higher-cost Madagascar sources. Tier-one automotive coating suppliers exhibit the lowest price sensitivity due to approved vendor list consolidation, while fragmented metal fabrication shops in Germany face acute margin pressure from audit documentation requirements.
Supply Chain Analysis
Toll coating specialists in the Yangtze River Delta and Ahmedabad chemical parks hold the majority of thin-film deposition capacity for mid-scale pigment processors. High-purity natural mica concentrates in India and Madagascar, while synthetic silica substrate production centers on China and Germany. The chain draws from metal-oxide precursors (titanium dioxide, iron oxide) and specialized milling media. Single-source vulnerability concentrates in Merck KGaA's captive mica mining operations. Distribution runs through distributor-led networks for industrial coatings, shifting to direct technical service teams for automotive OEM accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service attach rates for color-matching and formulation support are expanding faster than base pigment volumes as automotive OEMs compress development cycles and outsource optical interference expertise.
For Market Incumbents: Build formulation IP moats through captive thin-film physics talent pools co-located with Stuttgart and Munich design studios. Deepen backward integration into synthetic silica substrate production to offset natural mica supply volatility. Consolidate distributor relationships in Germany to defend against asset-light regional compounders leasing Yangtze River Delta milling capacity. For New Entrants and Emerging Players: Establish a beachhead in Indian prestige cosmetics packaging, where festival-season limited editions outpace industrial coating growth and certification burdens remain lighter than REACH jurisdictions. Target liquid dispersion formats for Southeast Asian inkjet contract packaging facilities adopting drop-on-demand technology. Lead with seasonal color trend forecasting services to differentiate from commodity flake suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors synthetic substrate innovators with multi-layer deposition capabilities collapsing performance gaps with natural mica. Long-term viability hinges on fluoropolymer-free grade pipelines as EPA and state-level PFAS restrictions tighten. The acquisition archetype combines thin-film physics competency with established automotive-direct relationships. Watch for REACH substance dossier completion rates as an inflection indicator for compliant supplier scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Silica Substrates | Merck KGaA's captive mica supply chain commands premium positioning that engineered substrates threaten to replicate. |
| Automotive-Direct Technical Service Co-location | PPG Industries and BASF SE maintain permanent liaison offices near Stuttgart assembly plants to compress formulation cycles. |
| Asset-Light Milling Equipment Leasing | Yangtze River Delta compounders fragment entry barriers by accessing specialized coating machinery through operating leases. |
| Fluoropolymer-Free Grade Development | EPA PFAS restrictions threaten treated iridescent grades, redirecting R&D budgets toward compliant surface chemistries. |
| Limited-Edition Cosmetics Packaging Partnerships | Maharashtra personal care manufacturers expand interference pigment procurement for festival-season aesthetic differentiation. |
Research Methodology
A standing panel of automotive coating procurement directors, thin-film R&D leads at pigment houses, REACH regulatory affairs specialists, and Indian personal care brand managers provided ongoing calibration against secondary validation. Primary interviews combined with customs trade data, ECHA substance registration databases, SEC chemical sector filings, and Yangtze River Delta industrial park output records. Bottom-up volume builds across flake, liquid, powder, and granule formats triangulated against top-down coatings, cosmetics, plastics, and inks application spending.
Scenario bracketing anchored projections across conservative, baseline, and accelerated regulatory enforcement paths. Segmentation dimensions modeled include physical form, application end-use, and automotive versus packaging buyer archetypes. CAGRs derived from fitted growth curves applied to qualified volume estimates, with cross-checks against OEM color palette refresh cycles and inkjet printhead adoption curves in Southeast Asian contract packaging.
Sensitivities concentrate around Indian mica export licensing volatility, PFAS restriction timelines across EPA and EU jurisdictions, and synthetic silica substrate yield rates. Cross-checking against automotive exterior finish specification volumes and prestige cosmetics launch frequency data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Global Architectural Paint Oxide Market
Dyes and Pigments
Asia Pacific Hair Colorants Market
Dyes and Pigments
Classic Organic Pigments Market
Dyes and Pigments
Brilliant Blue FCF Colors Market
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
Global Aluminum Anodizing Dyes Market
Dyes and Pigments
Synthetic Dyes Market
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
Special Effect Pigments Market
Dyes and Pigments
Pearlescent Pigments Market
Dyes and Pigments
Plastic Pigments Market
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Complex Inorganic Color Pigments Market
Dyes and Pigments
Inorganic Cosmetics Pigments Market
Dyes and Pigments
Oil-Dispersible Colors Market
Dyes and Pigments
Light Interference Pigments Market