
 Ellipsometer Market | 2026-2036
Ellipsometer Market Size, Share, and Industry Trends Forecast 2026-2036
Ellipsometer Market Analysis
Market Context
Equipment leasing and managed-service contracts for metrology tools is rewriting capital deployment patterns for mid-size fabs and research consortia. ULVAC leverages its vacuum-technology heritage to bundle ellipsometers with deposition systems, sustaining integrated workflow sales. HORIBA dominates spectroscopic instrument portfolios, extending optical characterization capabilities across semiconductor and materials science channels. J.A. Woollam specializes in research-grade ellipsometry, occupying the premium tier where academic laboratories and national institutes demand measurement flexibility.
Technical Foundation and Segment Structure
An ellipsometer measures the change in polarization state of light reflected from a sample surface, typically operating across ultraviolet to near-infrared wavelengths to determine film thickness, refractive index, and optical constants with sub-nanometer precision. Spectroscopic ellipsometry leads technology adoption in semiconductor manufacturing due to its broadband spectral acquisition speed, while ellipsometric imaging is the fastest-growing segment as flat-panel and advanced packaging inspection demands spatially resolved mapping. Research institutions anchor end-user demand for static and multiple-wavelength configurations, whereas manufacturing firms drive dynamic system procurement for inline process control where throughput dictates equipment selection.
Regulatory Environment and Strategic Outlook
ISO 17025 calibration standards and FDA quality system regulations shape metrology instrument validation requirements in pharmaceutical coating and medical device thin-film applications, while EU REACH and RoHS compliance redirects materials characterization priorities toward environmentally restricted substance detection. Semiconductor fabs in Germany face additional F-Gas Regulation constraints on deposition chemistries, elevating ellipsometry's role in verifying alternative dielectric stacks. Stakeholders must monitor how EU AI Act documentation requirements for automated measurement systems affect software-integrated ellipsometer deployment decisions.
Market Dynamics
Sub-7nm node characterization demands are compressing measurement cycles while EU REACH compliance redirects capital toward non-destructive optical metrology, fundamentally restructuring how fabs deploy metrology assets.
Growth Catalysts
- Semiconductor node scaling:Taiwan and South Korea foundries require angstrom-level thickness precision for gate oxide and high-k dielectric stacks, mandating spectroscopic ellipsometry deployment at multiple process steps.
- EU REACH substance restrictions:Hazardous substance limitations in thin-film deposition chemistries elevate ellipsometry's role in verifying compliant alternative dielectric materials without destructive testing.
- Advanced packaging inspection:Fan-out wafer-level packaging and 3D-IC architectures demand spatially resolved optical characterization, accelerating ellipsometric imaging system procurement.
Market Restraints
- High-purity optical component costs:UV-grade fused silica and precision polarizer assemblies face supply concentration from German and Japanese specialty glass manufacturers, creating input cost volatility.
- Calibration infrastructure scarcity:ISO 17025-accredited reference standards for traceable thickness measurement remain limited to national metrology institutes in Germany, Japan, and the United States.
- X-ray reflectometry substitution:Synchrotron and laboratory XRR systems capture ultra-thin film density profiling applications where ellipsometry faces sensitivity limitations below 0.5nm.
Strategic Opportunities
- India semiconductor ecosystem:The country's PLI scheme for fabs and display manufacturing creates greenfield metrology demand as domestic production capacity scales toward mature node logic and memory.
- Battery electrode coating metrology:Solid-state and thin-film lithium battery manufacturing requires precise cathode and electrolyte thickness control, opening new end-use verticals beyond traditional electronics.
- EU AI Act automated measurement:Documentation requirements for algorithmic process control systems favor ellipsometer vendors with embedded machine-learning thickness extraction and audit-ready data pipelines.
Industry Challenges
- Multiphysics modeling expertise:Anisotropic and graded-index film analysis requires rare combinations of optical physics, materials science, and computational skills that outpace university pipeline output.
- Legacy tool integration:200mm and legacy 300mm fabs operate mixed-vendor metrology suites where new ellipsometer software stacks must bridge incompatible data formats and SECS/GEM implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ellipsometer Market |
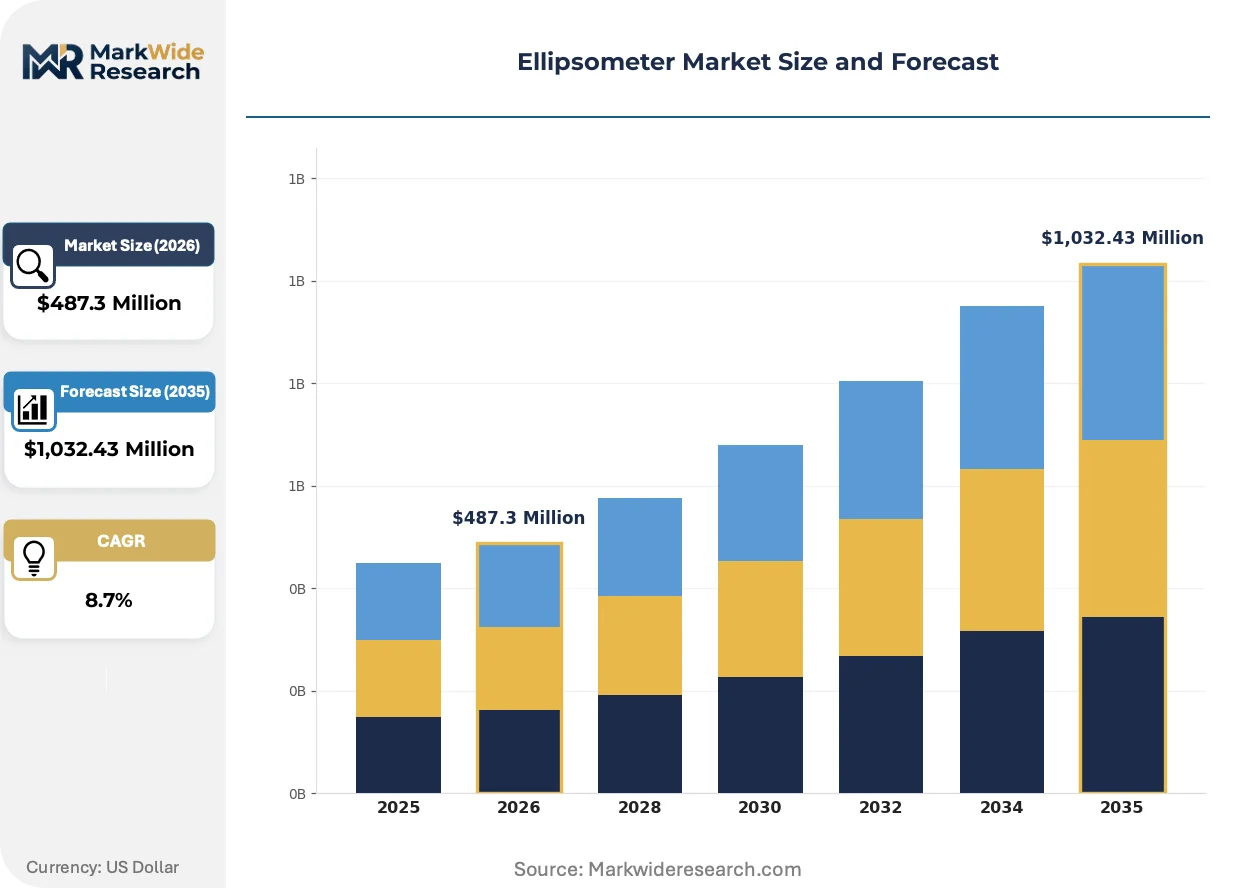
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Semiconductors, Solar Cells, Thin Films, Optical Coatings Technology: Phase Modulation, Spectroscopic, Time-Resolved, Ellipsometric Imaging End User: Research Institutions, Manufacturing Firms, Quality Control Labs, Academic Laboratories Product Type: Static, Dynamic, Confocal, Multiple Wavelength |
| Companies Covered | ULVAC, Semilab, HORIBA, Screen Holdings, KLA-Tencor, J.A. Woollam, SENTECH Instruments GmbH, Otsuka Electronics, Bruker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ellipsometer Market Emerging Trajectories
Real-time spectral acquisition and machine-learning inversion algorithms are compressing measurement cycles from minutes to seconds, while regulatory documentation mandates reshape software architecture priorities.
Mueller-matrix ellipsometry is rendering obsolete conventional single-angle spectroscopic systems for complex anisotropic films. Memory manufacturers in South Korea and Taiwan now specify full polarimetric capability for advanced 3D NAND stack characterization. The technology is rendering obsolete legacy configurations that cannot distinguish form birefringence from true optical anisotropy.
EU F-Gas Regulation constraints on fluorinated deposition chemistries are elevating ellipsometry verification requirements for alternative low-k dielectric qualification. German semiconductor fabs must document carbon footprint and material safety for every process change, embedding optical metrology deeper into environmental compliance workflows. Equipment vendors are responding with integrated thickness-refractive index databases that flag restricted substance content.
Managed-service contracts and performance-based leasing are displacing traditional capital purchase models among mid-size research consortia and specialty materials startups. European nanotechnology centers and North American battery pilot lines now specify uptime-guaranteed subscriptions with embedded calibration and algorithm updates. Taiwan displays this shift most acutely, where flexible OLED pilot facilities favor operational expenditure structures over multi-year depreciation schedules.
Ellipsometer Market Segmentation
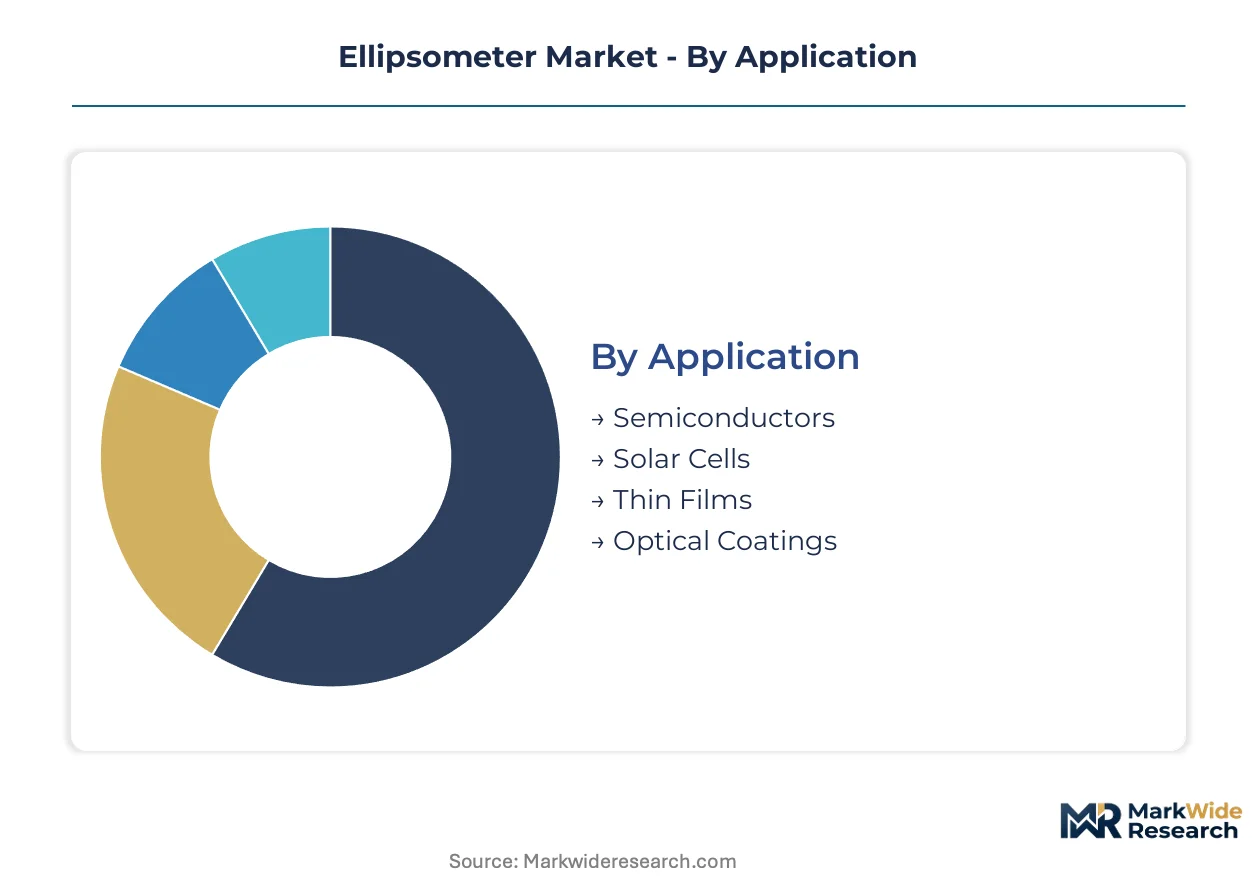
Ellipsometer procurement patterns diverge sharply between mature semiconductor fabs requiring inline throughput and emerging battery electrode coating lines prioritizing measurement flexibility. Technology selection, end-user sophistication, and application criticality create distinct commercial tiers that reshape vendor go-to-market strategies.
Application:
Mature process control dominates volume procurement, while emerging energy applications reshape specifications.
- Semiconductors:Gate oxide and high-k dielectric metrology at sub-7nm nodes demands angstrom-level precision across Taiwan and South Korea foundry clusters. Taiwan Semiconductor Manufacturing and Samsung Foundry deploy spectroscopic systems at multiple deposition steps to compress measurement cycles.
- Thin Films:EU REACH compliance on hazardous deposition chemistries elevates non-destructive optical verification for alternative dielectric qualification. German fabs under F-Gas Regulation constraints rely on ellipsometry to document carbon footprint and material safety for every process change.
- Solar Cells:Perovskite and tandem photovoltaic architectures require precise absorber layer thickness mapping during pilot production scaling.
- Optical Coatings:Anti-reflective and filter stack characterization for aerospace and medical device optics concentrates in specialty coating houses.
Semiconductors retain volume leadership; thin films holds the steepest expansion curve.
Technology:
Cost tier stratification separates research-grade flexibility from manufacturing throughput requirements.
- Spectroscopic:Broadband spectral acquisition across ultraviolet to near-infrared wavelengths enables sub-nanometer thickness determination with single-measurement speed. Memory manufacturers in South Korea and Taiwan specify full polarimetric capability for advanced 3D NAND stack characterization.
- Ellipsometric Imaging:Spatially resolved optical mapping addresses fan-out wafer-level packaging and 3D-IC architecture inspection demands. Flat-panel display pilot facilities in Taiwan favor this configuration for flexible OLED layer uniformity verification.
- Phase Modulation:High-sensitivity polarization modulation supports research environments requiring measurement of ultra-thin organic and biological films.
- Time-Resolved:Pump-probe configurations capture transient optical properties during pulsed laser deposition and rapid thermal processing studies.
Spectroscopic commands the premium pricing tier; ellipsometric imaging is climbing the fastest.
End User:
Customer type determines software integration depth and service contract structures.
- Manufacturing Firms:Inline process control deployments require SECS/GEM connectivity, automated recipe management, and uptime-guaranteed service subscriptions. Mid-size fabs increasingly specify performance-based leasing over capital purchase to preserve operational expenditure flexibility.
- Research Institutions:National metrology institutes and academic laboratories anchor demand for measurement flexibility, algorithm customization, and traceable calibration chains. These users prioritize Mueller-matrix capability and anisotropic film modeling over throughput metrics.
- Quality Control Labs:Pharmaceutical coating and medical device thin-film applications face ISO 17025 calibration standards and FDA quality system regulations that shape validation requirements.
- Academic Laboratories:Materials science and physics departments drive adoption of research-grade static and multiple-wavelength configurations for graduate training and exploratory studies.
Manufacturing firms generate the revenue base; quality control labs are expanding most quickly.
Product Type:
Volume scale separates high-throughput manufacturing configurations from specialized research instruments.
- Dynamic:Real-time spectral acquisition with machine-learning inversion algorithms compresses measurement cycles from minutes to seconds for inline process control. These systems dominate procurement at Taiwan and South Korea logic and memory fabs.
- Static:Fixed-angle configurations serve research environments where measurement repeatability and algorithm transparency outweigh speed requirements. Academic laboratories and national institutes favor these systems for fundamental optical constant determination.
- Multiple Wavelength:Discrete laser-line sources provide cost-effective thickness mapping for mature node semiconductor and solar cell production.
- Confocal:Combined ellipsometric and topographic profiling addresses advanced packaging and MEMS applications requiring simultaneous thickness and surface morphology data.
Dynamic systems retain volume leadership; confocal configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ellipsometer trade flows reflect concentrated production in East Asian foundry clusters and German precision optics, with import dependency structuring procurement patterns across emerging semiconductor ecosystems.
Taiwan
TSMC and United Microelectronics deploy spectroscopic systems across Hsinchu and Tainan Science Parks for sub-7nm gate oxide characterization. The National Science and Technology Council subsidizes domestic metrology infrastructure under the Chip Implementation Center program. Kaohsiung's emerging 2nm megafab anchors the fastest-growing procurement cluster for inline process control systems.
South Korea
Samsung Foundry and SK Hynix require Mueller-matrix capability for 3D NAND stack verification at Pyeongtaek and Icheon complexes. MFDS pharmaceutical coating regulations extend optical metrology demand into biologics manufacturing equipment. Seoul Capital Area fabs concentrate 80% of national ellipsometer deployment for logic and memory production.
Germany
Infineon and Bosch operate spectroscopic systems for automotive sensor dielectric qualification in Dresden and Reutlingen. EU F-Gas Regulation and REACH compliance mandate non-destructive verification of alternative low-k materials. Bavaria's semiconductor cluster around Munich drives premium-tier research-grade instrument demand from Fraunhofer institutes.
United States
Intel and GlobalFoundries scale metrology deployment for CHIPS Act-funded fabs in Arizona and New York. FDA quality system regulations shape pharmaceutical coating applications for medical device manufacturers. Greater Boston's battery startup ecosystem generates emerging demand for electrode thickness characterization systems.
India
Tata Electronics and ISMC Digital anchor greenfield fab construction in Gujarat and Karnataka under the PLI scheme for semiconductors. BIS certification requirements for imported metrology equipment create localization incentives for assembly partnerships. Tamil Nadu's display manufacturing corridor drives pilot-line procurement for flexible OLED inspection.
Ellipsometer Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying optical subassemblies and calibration standards. The vendor base stratifies across three tiers: vacuum-technology conglomerates bundling deposition-metrology workflows, spectroscopic instrument houses extending optical characterization portfolios, and research-grade specialists occupying premium niches. Competitive positioning hinges on SECS/GEM software integration depth and ISO 17025 traceability chains. Primary rivalry vectors include strategic partnerships with foundry equipment consortia and algorithm licensing for machine-learning thickness extraction.
Among Japanese vacuum-technology conglomerates, ULVAC exemplifies platform integration strategy. HORIBA occupies the spectroscopic instrument archetype with optical characterization heritage spanning semiconductor and materials science channels. J.A. Woollam represents the research-grade specialist tier where academic laboratories and national institutes prioritize measurement flexibility over throughput metrics.
| Leading Market Players |
|---|
| ULVAC |
| Semilab |
| HORIBA |
| Screen Holdings |
| KLA-Tencor |
| J.A. Woollam |
| SENTECH Instruments GmbH |
| Otsuka Electronics |
| Bruker |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on German and Japanese specialty glass manufacturers for UV-grade fused silica polarizer assemblies compresses pricing tier spreads while forcing fabs toward multi-year service contracts with embedded calibration guarantees.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on SECS/GEM software integration depth and ISO 17025 traceability certification tier. Cost compression in economy-tier static systems is intensifying because research consortia increasingly favor managed-service subscriptions over capital purchase. Memory manufacturers in South Korea and Taiwan exhibit lowest price sensitivity due to node-scaling imperatives, whereas Indian greenfield fabs under PLI scheme constraints show highest sensitivity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now structure supplier-financing relationships as optical subassembly vendors absorb working capital pressure from foundry equipment consortia. Supply concentrates in Germany, Japan, and the United States for precision polarizers, reference standards, and spectroscopic detectors. Raw material dependencies include UV-grade fused silica, calcite polarizer crystals, and InGaAs photodiode arrays. Tariff exposure on Japanese optical components threatens margin stability. Distribution runs through vacuum-technology conglomerates bundling deposition-metrology workflows and direct sales to national metrology institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Taiwan and South Korea foundry clusters, compressing vendor margins and favoring equipment vendors with captive calibration infrastructure and algorithm licensing depth.
For Market Incumbents: Entrench through backward integration into reference standard production and embedded machine-learning thickness extraction algorithms. X-ray reflectometry substitution for sub-0.5nm film characterization threatens spectroscopic system incumbency. Prioritize ISO 17025-accredited calibration chain investments to lock in foundry equipment consortium partnerships. For New Entrants and Emerging Players: Build out battery electrode coating metrology capabilities as solid-state lithium manufacturing scales beyond traditional electronics. India's PLI scheme for semiconductors and display manufacturing represents the most penetrable geography. Pursue performance-based leasing structures with uptime guarantees to bypass capital purchase barriers at mid-size research consortia. For Investors and Strategic Acquirers: EU AI Act documentation requirements for automated measurement systems reshape the acquisition landscape toward vendors with audit-ready data pipelines and embedded algorithm transparency. Long-term viability centers on software-integrated ellipsometer deployment decisions across the semiconductor fabrication ecosystem. Target research-grade specialists with Mueller-matrix capability and anisotropic film modeling expertise. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for alternative dielectric verification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Mueller-Matrix Capability Expansion | Full polarimetric systems capture 3D NAND stack characterization contracts from Samsung Foundry and SK Hynix. |
| Managed-Service Contract Rollout | Uptime-guaranteed subscriptions with embedded calibration displace capital purchases at Taiwan flexible OLED pilot facilities. |
| Backward Integration into Reference Standards | In-house production of ISO 17025-accredited calibration artifacts reduces dependency on German national metrology institutes. |
| Battery Electrode Coating Entry | Cathode and electrolyte thickness control systems address solid-state lithium manufacturing beyond traditional electronics. |
| SECS/GEM Software Stack Deepening | Automated recipe management and SECS/GEM connectivity secure inline process control procurement at TSMC and Intel. |
Methodological Framework
Desk research of trade customs data, SEC filings from metrology equipment vendors, and ISO 17025 accreditation registries preceded structured interviews with semiconductor fab metrology directors, vacuum-technology equipment procurement leads, and national institute calibration scientists. Primary fieldwork combined with secondary validation against ECHA REACH substance restriction databases and MFDS pharmaceutical coating regulations. Bottom-up segment sizing triangulated against top-down foundry capital expenditure disclosures.
Assumptions held semiconductor node scaling trajectories and EU regulatory enforcement intensity within observed patterns while varying India PLI scheme uptake rates and battery electrode coating metrology penetration. Segmentation modeling spanned technology tier, end-user sophistication, application criticality, and regional foundry cluster maturity. CAGRs derived from installation base growth rates and replacement cycle compression across the projection horizon. Forecast inputs included sub-7nm node characterization cycle times and ellipsometric imaging adoption curves for advanced packaging inspection.
The forecast holds incumbent behavior within observed patterns; aggressive moves by X-ray reflectometry vendors or synchrotron facility operators would shift outcomes. Macroeconomic deviation in East Asian foundry capital expenditure, regulatory expansion of EU AI Act documentation requirements, or breakthrough anisotropic film modeling algorithms would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Europe Scintillator Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
North America Photonic Sensors Market
Optical Components
Optical Fiber and Plastic Conduit Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Lithium Niobate Modulator Market
Optical Components
Optical Interconnect Market
Optical Components
Microchannel Plates Market
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
3-7mm Galvo Scanner Market
Optical Components
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market
Optical Components
Display Optical Film Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
LAMEA Lithium Niobate Modulator Market
Optical Components
Flip-Chip VCSEL Market
Optical Components
Passive Optical Component Market