
 Optical Image Stabilization (OIS) Actuators Market | 2026-2036
Optical Image Stabilization (OIS) Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Image Stabilization (OIS) Actuators Market Analytics
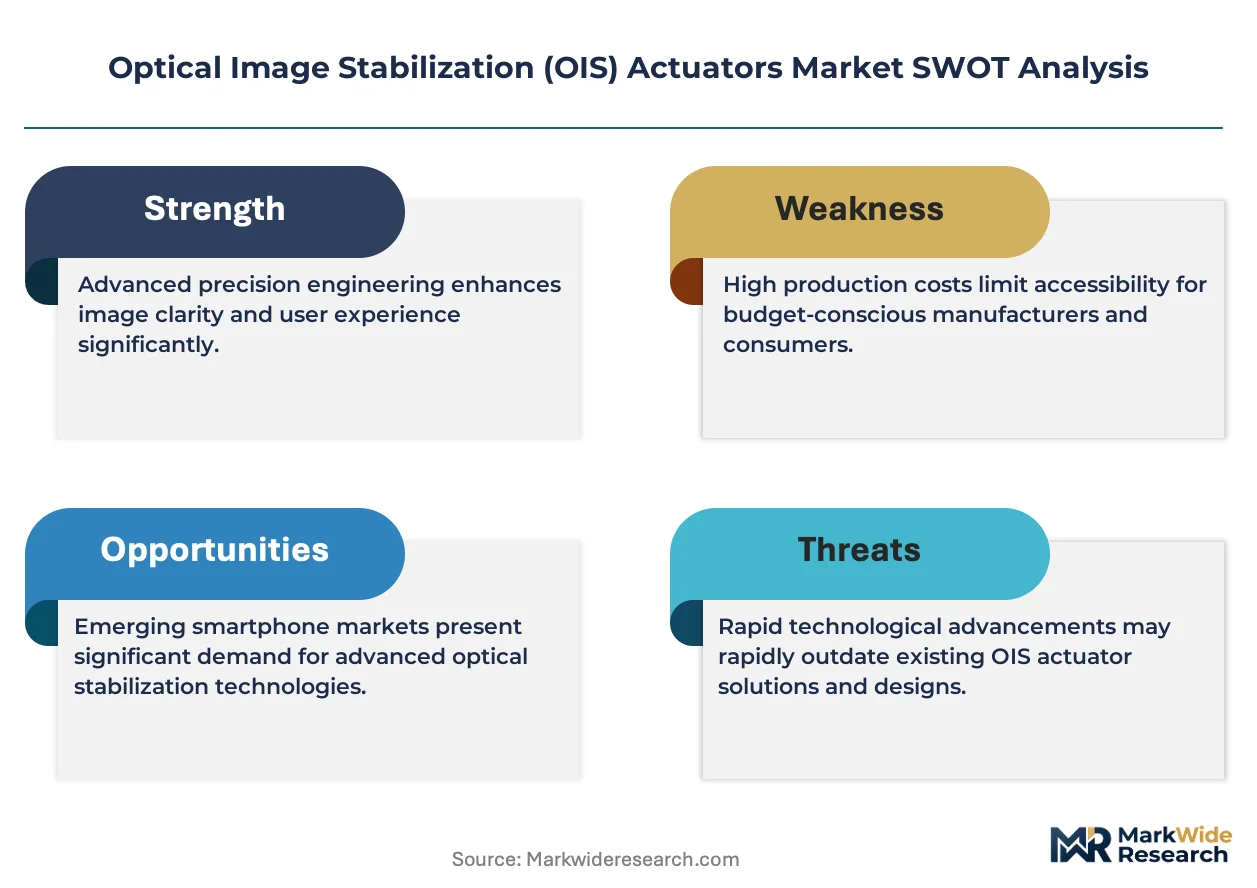
East Asian component manufacturing is consolidating around precision electromagnetic assembly for smartphone camera modules. Alps Alpine Co., Ltd. leverages its heritage in micro-electromechanical systems to dominate compact actuator designs for flagship devices. TDK Corporation anchors high-volume voice coil motor production through captive magnet supply chains in Japan and Malaysia. Samsung Electro-Mechanics Co., Ltd. competes aggressively by extending backward integration into rare-earth magnet processing and automated coil winding.
Optical Image Stabilization (OIS) Actuators are electromechanical transducers that physically shift lens elements or image sensors along multiple axes to compensate for involuntary hand motion, typically achieving correction amplitudes of 100-500 micrometers at response frequencies exceeding 100 Hz. Voice coil motors currently occupy the largest share of unit shipments due to their cost-efficiency in mass-market smartphones, while piezoelectric actuators differentiate premium camera systems through superior precision and lower power draw in medical endoscopy and drone gimbal applications. Hybrid stabilization systems, combining sensor-shift and lens-shift mechanisms, represent the fastest-growing technology segment as computational photography pipelines demand sub-pixel alignment accuracy.
FCC electromagnetic interference standards in the United States and CE marking requirements under the EU RoHS directive constrain actuator material selection and shielding designs, particularly for nickel-copper alloys and lead-free solder joints. Japan's METI enforces JIS standards on vibration durability that OEMs must satisfy for automotive advanced driver-assistance camera qualification. Stakeholders should monitor how China's GB standards on rare-earth export quotas reshape magnet cost structures and whether India's PLI scheme for electronics manufacturing attracts actuator assembly migration from incumbent East Asian hubs.
Market Dynamics
Multi-axis MEMS stabilization modules are compressing unit economics for smartphone camera suppliers while tightening FCC electromagnetic emission standards force shielding redesigns across North American-bound production lines.
Growth Catalysts
- Multi-lens smartphone arrays:Flagship device manufacturers in China, Japan, and South Korea now specify OIS actuators for periscope telephoto and ultrawide modules, expanding unit volumes per handset.
- EU RoHS lead-free mandates:CE marking requirements under the RoHS directive accelerate solder joint material transitions, creating upgrade cycles for automotive ADAS camera suppliers seeking European market access.
- Computational photography pipelines:Real-time image fusion algorithms demand sub-pixel alignment accuracy, pulling hybrid sensor-shift plus lens-shift architectures into mid-tier smartphone segments.
Market Restraints
- Rare-earth magnet cost volatility:China's GB standards on neodymium export quotas inject price uncertainty into voice coil motor bill-of-materials, compressing margins for non-integrated assemblers.
- Precision coil winding equipment scarcity:Automated winding machinery for sub-millimeter copper coils concentrates among Japanese and German capital goods suppliers, creating 12-18 month capacity lead times.
- Piezoelectric ceramic displacement limits:Medical endoscopy applications requiring stroke lengths beyond 300 micrometers face actuator size constraints that voice coil alternatives more readily satisfy.
Strategic Opportunities
- India PLI electronics manufacturing:India's production-linked incentive scheme for smartphone assembly attracts actuator module migration from Shenzhen and Seoul, diversifying geographic supply footprints.
- Drone gimbal stabilization:Commercial UAV operators specify piezoelectric actuators for low-power aerial cinematography, opening volume outside handset-dependent revenue streams.
- Automotive ADAS camera qualification:Japan's METI JIS vibration durability standards create certified supplier lists that qualified actuator vendors can leverage for long-term OEM contracts.
Industry Challenges
- MEMS process engineering talent scarcity:Foundries in East Asian manufacturing clusters compete for specialists capable of etching silicon spring structures with sub-micron tolerances.
- Multi-axis calibration complexity:Hybrid stabilization systems require simultaneous alignment of lens-shift and sensor-shift mechanisms, extending factory test cycle times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Image Stabilization (OIS) Actuators Market |
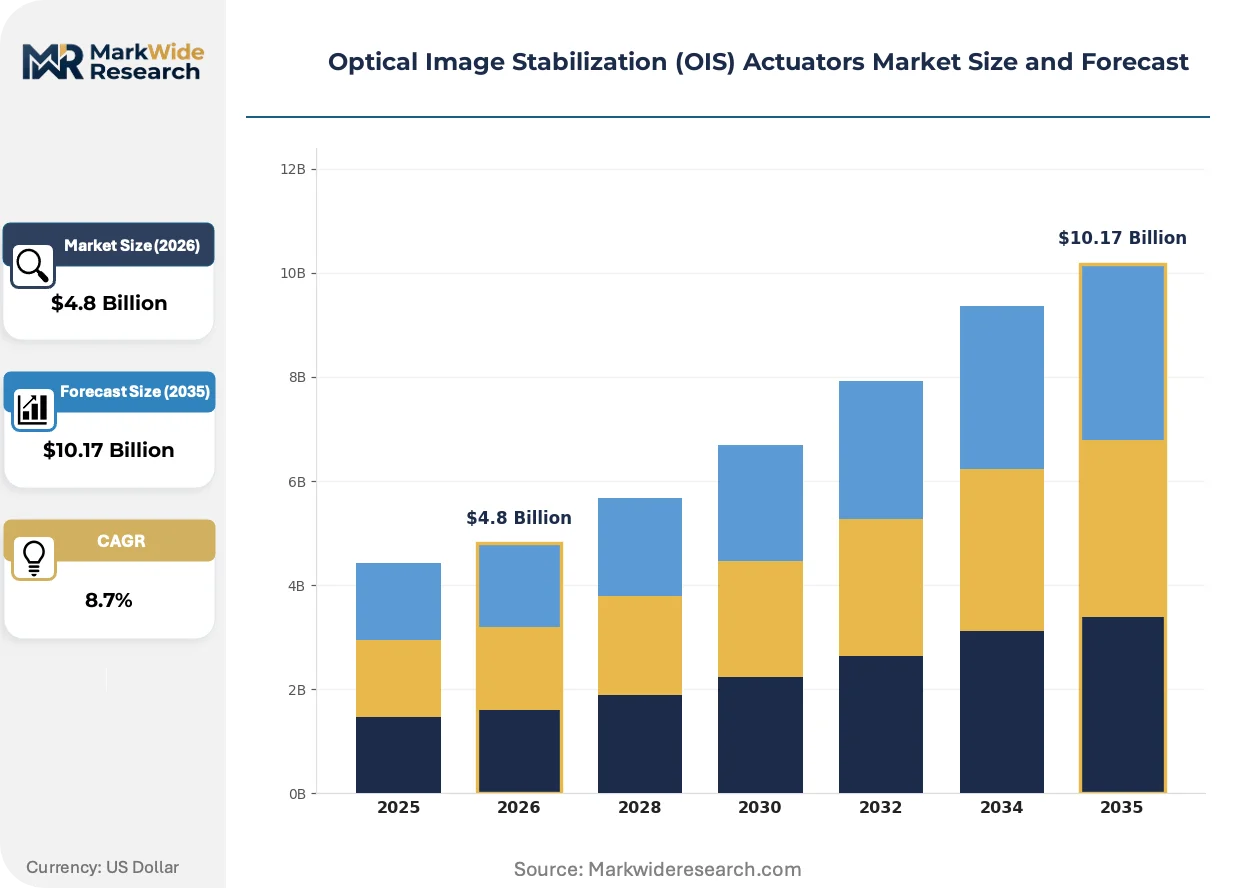
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MEMS Actuators, Voice Coil Motors, Piezoelectric Actuators, Electromagnetic Actuators Application: Smartphones, Digital Cameras, Drones, Wearable Devices End User: Consumer Electronics, Automotive, Aerospace, Medical Devices Technology: Active Stabilization, Passive Stabilization, Hybrid Systems, Software Integration |
| Companies Covered | Alps Alpine Co., Ltd., Largan Precision Co., Ltd., Sunny Optical Technology (Group) Co., Ltd., Sony Group Corporation, TDK Corporation, LG Innotek Co., Ltd., O-Film Tech Co., Ltd., STMicroelectronics N.V., Samsung Electro-Mechanics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Image Stabilization (OIS) Actuators Market Evolving Landscape
Computational photography requirements and tightening electromagnetic compatibility standards are reshaping actuator architecture roadmaps across consumer and industrial camera systems.
Sensor-shift stabilization is overtaking pure lens-shift architectures in premium smartphone segments. Apple and Samsung flagship engineering teams specify moving image sensors for superior correction amplitude across wide-angle modules. This shift is overtaking traditional voice coil motor dominance in devices above six hundred dollar price tiers, compressing lens-actuator supplier margins while expanding MEMS foundry utilization.
Japan's METI has tightened JIS C 60068-2-6 vibration testing protocols for automotive camera modules. Tier-1 suppliers must now demonstrate actuator survival through 500,000 cycle durability tests to qualify for advanced driver-assistance programs. Korean and Japanese actuator manufacturers are responding by migrating to nickel-iron alloy shielding laminates that satisfy both METI mechanical standards and FCC Part 15 electromagnetic emission limits.
Handset OEM procurement teams are consolidating supplier relationships from six-plus vendors to three preferred partners per camera module category. This concentration eliminates smaller voice coil motor assemblers unable to guarantee million-unit monthly volumes. Chinese smartphone brands headquartered in Shenzhen and Beijing are most aggressive in this rationalization, leveraging vertical manufacturing campus proximity to compress logistics costs.
Optical Image Stabilization (OIS) Actuators Market Segmentation
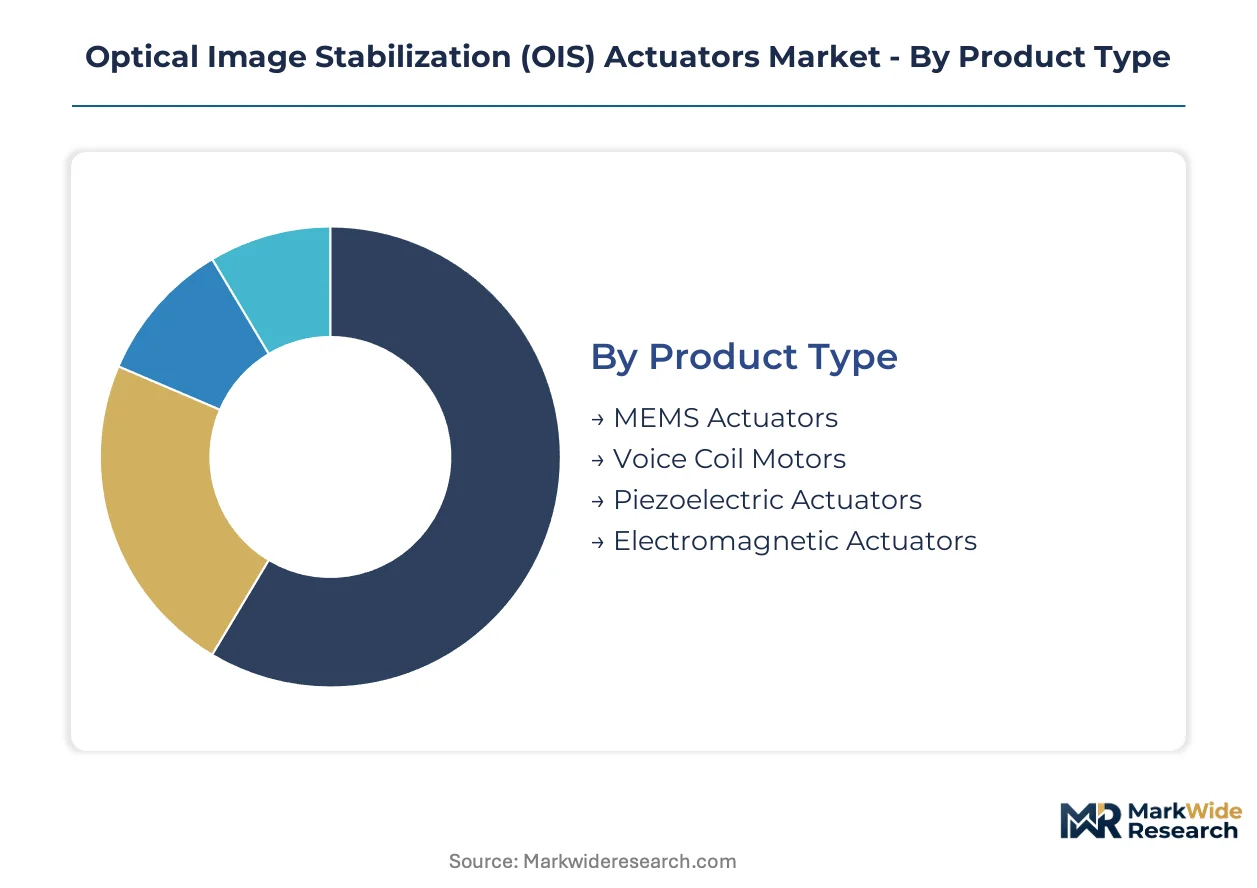
OIS actuator architectures diverge sharply across cost-performance thresholds. Product type selection determines shielding requirements, calibration protocols, and supply chain geography for camera module assemblers.
Product Type:
Customization intensity spans from off-the-shelf voice coil motors to application-specific MEMS designs requiring foundry co-development.
- MEMS Actuators:Silicon-etched spring structures achieve sub-micron positioning precision through electrostatic or electromagnetic forces. Samsung Electro-Mechanics and Alps Alpine dominate wafer-level packaging for flagship smartphones in Seoul and Tokyo manufacturing corridors.
- Voice Coil Motors:Copper coil assemblies suspended in permanent magnet fields deliver 100-500 micrometer stroke lengths at sub-dollar unit costs. Shenzhen-based camera module houses specify these for mid-tier handsets where FCC Part 15 emission compliance must coexist with aggressive bill-of-material targets.
- Piezoelectric Actuators:Ceramic stack elements convert electrical charge to mechanical displacement with minimal power draw. Medical endoscopy OEMs in Japan's precision manufacturing belt favor these for battery-constrained surgical instruments.
- Electromagnetic Actuators:Variable reluctance designs using nickel-iron laminates serve automotive ADAS cameras requiring METI JIS vibration durability certification.
Most installed capacity flows through Voice Coil Motors. Expansion is steepest in MEMS Actuators.
Application:
Volume concentration versus margin extraction varies dramatically across device categories, with handset scale economies clashing against aerospace unit premiums.
- Smartphones:Multi-lens arrays now specify OIS for periscope telephoto, ultrawide, and primary sensors simultaneously. Chinese OEM procurement teams in Beijing and Shenzhen consolidate supplier panels to three preferred partners per module category.
- Digital Cameras:Interchangeable-lens systems demand larger actuator stroke lengths for full-frame sensor stabilization. Japanese manufacturers anchor production in domestic precision machining clusters.
- Drones:Commercial UAV gimbals prioritize piezoelectric solutions for extended flight endurance. Low electromagnetic signatures prove critical for FCC-compliant aerial cinematography platforms.
- Wearable Devices:Miniaturized voice coil variants address space-constrained smartwatch camera modules. Korean component houses lead wafer-level chip-scale packaging for these form factors.
Smartphones absorb the dominant production share. Drone applications are climbing the fastest.
End User:
Certification burdens and qualification timelines create divergent competitive moats across customer verticals.
- Consumer Electronics:Handset and tablet manufacturers drive ninety-plus percent of unit volume. Annual model cycles compress actuator development timelines to six-month windows.
- Automotive:ADAS camera suppliers face Japan METI JIS C 60068-2-6 vibration testing mandates requiring 500,000-cycle durability demonstration. Nickel-iron alloy shielding laminates satisfy simultaneous FCC and METI requirements.
- Aerospace:Satellite imaging systems specify radiation-hardened electromagnetic actuators with decade-plus operational lifespans. Procurement runs through defense-qualified tier-1 contractors.
- Medical Devices:Endoscopy systems require sterilization-compatible piezoelectric stacks. FDA 510(k) pathways and EU MDR conformity assessment extend commercialization timelines.
Consumer Electronics channels the bulk of manufacturing throughput. Medical Devices show the steepest margin expansion.
Technology:
Hardware-software integration depth separates commodity suppliers from system-level solution providers.
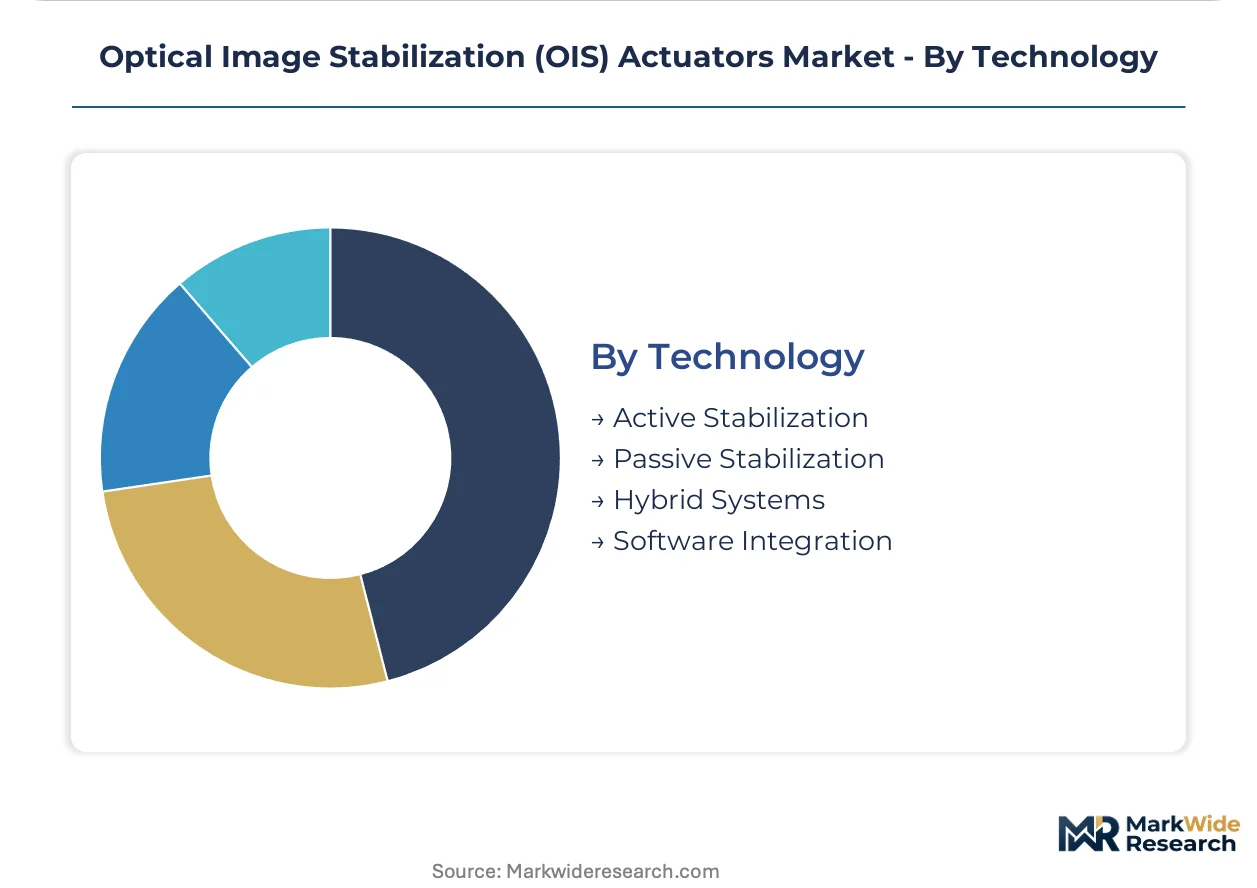
- Active Stabilization:Real-time gyroscope feedback drives closed-loop position correction at 100+ Hz response frequencies. Voice coil motors dominate this architecture in cost-sensitive applications.
- Passive Stabilization:Mechanical damping elements absorb vibration without power consumption. Limited to legacy digital camera systems and budget drone platforms.
- Hybrid Systems:Sensor-shift plus lens-shift mechanisms combine for sub-pixel alignment accuracy. Apple's computational photography pipeline and Samsung's flagship engineering teams specify these architectures.
- Software Integration:Predictive motion algorithms anticipate hand tremor patterns. MEMS foundries now co-develop actuator firmware with smartphone OEMs in Taiwan and Korea.
Active Stabilization commands the largest installed base. Hybrid Systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping actuator assembly footprints as FCC electromagnetic emission compliance costs in the United States diverge from China's GB standards enforcement. Manufacturers migrate module production toward jurisdictions with calibrated regulatory intensity.
China
Smartphone OEM procurement teams in Shenzhen and Beijing consolidate supplier panels to three preferred partners per camera module category. MIIT enforces GB standards on rare-earth export quotas that inject neodymium price uncertainty into voice coil motor bill-of-materials. Yangtze River Delta and Pearl River Delta manufacturing corridors host vertically integrated camera module houses serving domestic brands and Apple supply chains.
Japan
Precision machining clusters in Tokyo and Nagoya anchor full-frame digital camera actuator production for interchangeable-lens systems. METI enforces JIS C 60068-2-6 vibration testing protocols requiring 500,000-cycle durability demonstration for automotive ADAS camera qualification. Kanto and Kansai industrial belts concentrate MEMS foundry capacity for silicon-etched spring structures.
South Korea
Seoul Capital Area engineering teams specify sensor-shift stabilization architectures for flagship smartphone segments above six hundred dollar price tiers. MFDS aligns medical device actuator requirements with international electromagnetic compatibility standards. Busan-Ulsan manufacturing corridors process rare-earth magnets through captive supply chains for voice coil motor production.
United States
FCC Part 15 electromagnetic emission limits force nickel-iron alloy shielding redesigns across North American-bound production lines. Greater Boston and Pacific Northwest R&D clusters develop predictive motion algorithms for computational photography pipelines. Midwest industrial corridors test automotive camera modules against NHTSA durability benchmarks.
India
PLI scheme incentives for electronics manufacturing attract actuator module migration from incumbent East Asian hubs. BIS certification requirements for smartphone components extend qualification timelines for new market entrants. Maharashtra and Karnataka assembly corridors scale smartphone production capacity for domestic consumption and export markets.
Optical Image Stabilization (OIS) Actuators Market Competitive Landscape
East Asian producers anchor the high-volume tier; European and North American specialists hold positions in precision instrumentation and aerospace-qualified segments. The vendor base clusters around three strategic archetypes: vertically integrated conglomerates with captive magnet processing, MEMS foundry operators with wafer-level packaging capabilities, and precision optics houses with backward integration into coil winding. Capacity expansion and technology licensing dominate competitive moves as firms seek to secure million-unit monthly volume commitments.
Among Japan-based precision component fabricators, Alps Alpine Co., Ltd. and TDK Corporation exemplify the vertically integrated archetype with heritage in micro-electromechanical systems. Samsung Electro-Mechanics Co., Ltd. occupies a position representing Korean conglomerate diversification into rare-earth magnet processing and automated assembly. These three entities anchor distinct competitive vectors within the market structure, with Alps Alpine representing MEMS design specialization, TDK exemplifying magnet supply chain control, and Samsung Electro-Mechanics illustrating backward integration into materials processing.
| Leading Market Players |
|---|
| Alps Alpine Co., Ltd. |
| Largan Precision Co., Ltd. |
| Sunny Optical Technology (Group) Co., Ltd. |
| Sony Group Corporation |
| TDK Corporation |
| LG Innotek Co., Ltd. |
| O-Film Tech Co., Ltd. |
| STMicroelectronics N.V. |
| Samsung Electro-Mechanics Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Captive magnet processing in Japan and South Korea anchors supply positions while insulating integrated voice coil motor suppliers from China's GB standards volatility. This backward integration into rare-earth supply chains simultaneously secures input cost predictability and sustains pricing power against non-integrated Shenzhen assemblers serving mid-tier smartphone OEMs.
Pricing Analysis
Distributor margins for voice coil motors compress as Shenzhen-based camera module houses consolidate procurement panels to three preferred partners per category. Pricing stratifies across MEMS-based premium tiers, voice coil standard tiers, and piezoelectric specialty tiers. Cost compression in mid-tier voice coil segments intensifies because Chinese OEM procurement teams leverage campus proximity to extract logistics concessions. Automotive ADAS camera suppliers exhibit lowest price sensitivity due to METI JIS certification barriers.
Supply Chain Analysis
MEMS process engineering talent scarcity in Seoul, Tokyo, and Shenzhen manufacturing corridors constrains wafer-level packaging expansion for silicon-etched spring structures. Rare-earth magnet feedstock draws from Malaysia and Japan, while precision copper coil winding equipment sources from German and Japanese capital goods suppliers. Single-source vulnerability concentrates in automated winding machinery with 12-18 month capacity lead times. Distribution runs through vertically integrated camera module houses in Yangtze River Delta and Pearl River Delta corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily because computational photography pipelines perpetually demand sub-pixel alignment accuracy across multi-lens smartphone arrays.
For Market Incumbents: Hedge against rare-earth magnet cost volatility by deepening in-house production of neodymium processing in Busan-Ulsan corridors. Secure million-unit monthly volume commitments from Beijing and Shenzhen OEM procurement teams before Korean and Japanese competitors expand MEMS foundry capacity. For New Entrants and Emerging Players: Enter via India's PLI electronics manufacturing scheme to capture smartphone assembly migration from incumbent East Asian hubs. Drone gimbal piezoelectric applications present the most penetrable white-space target, with commercial UAV operators prioritizing low-power aerial cinematography specifications. For Investors and Strategic Acquirers: Roll-up economics work for MEMS foundry operators with wafer-level packaging capabilities because sensor-shift stabilization architectures are displacing pure lens-shift designs in premium smartphone segments. Watch for China's GB standards enforcement on rare-earth export quotas as the inflection indicator triggering margin compression for non-integrated assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Capacity Expansion | Seoul and Tokyo manufacturing corridors secure wafer-level packaging for sensor-shift architectures. |
| Rare-Earth Magnet Backward Integration | Busan-Ulsan captive supply chains insulate voice coil motor production from China's GB standards volatility. |
| Automotive ADAS Certification Investment | METI JIS vibration durability qualification opens long-term OEM contracts for nickel-iron alloy shielding designs. |
| India PLI Manufacturing Migration | Maharashtra and Karnataka assembly corridors diversify geographic supply footprints beyond Shenzhen and Seoul. |
| Computational Photography Firmware Co-Development | Taiwan and Korea MEMS foundries integrate predictive motion algorithms with smartphone OEM pipelines. |
Research Methodology
Direct dialogue with MEMS foundry engineers, smartphone OEM procurement directors, automotive Tier 1 camera module suppliers, and precision coil winding equipment manufacturers grounded qualitative insights. Secondary validation drew from FCC Part 15 filings, METI JIS standard documentation, MIIT GB standards publications, and SEC 10-K disclosures from listed component manufacturers. Bottom-up unit shipment estimates triangulated against top-down smartphone production forecasts across the analysis window.
Segmentation outputs spanned product type hierarchies, application categories from smartphones to medical endoscopy, end-user certification tiers, and technology architectures from active stabilization through hybrid systems. CAGRs were derived from installed base growth rates, replacement cycle compression, and premium tier penetration curves. Voice coil motor unit economics and MEMS foundry utilization rates served as industry-specific forecast inputs.
Inputs from smartphone OEM procurement panels and automotive Tier 1 qualification databases were available through the study window; gaps in piezoelectric ceramic displacement performance data introduce uncertainty bands for medical endoscopy segment sizing. Forecasts reflect assumptions on computational photography pipeline adoption and rare-earth magnet supply continuity. Material deviation in China's GB standards enforcement or FCC electromagnetic emission rulemaking warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
US Optical Sensors Market
Optical Components
Coherent Optical Equipment Market
Optical Components
Spectroradiometers Market
Optical Components
North America Tunable Laser Market
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Global Tunable Filter Market
Optical Components
Ellipsometer Market
Optical Components
Diode Laser Module Market
Optical Components
CW Fiber Amplifier Market
Optical Components
North America Lithium Niobate Modulator Market
Optical Components
Waveguide Phase Shifter Market
Optical Components
Global Wavelength Division Multiplexing (WDM) Equipment Market
Optical Components
VCSEL for Data Communication Market
Optical Components
Japan Lithium Niobate Modulator Market
Optical Components
Optical Time-Domain Reflectometer Market