
 Microchannel Plates Market | 2026-2036
Microchannel Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Microchannel Plates Market Foresight
Software-defined gain calibration is recalibrating what buyers procure alongside physical hardware. Hamamatsu Photonics K.K. leverages its vertically integrated photonics manufacturing to control quality across the full stack. PHOTONIS Technologies S.A.S. anchors European defense supply chains with specialized electron multiplication expertise. Incom, Inc. competes on custom plate geometries for scientific instrumentation.
Microchannel plates are glass substrates containing millions of parallel capillaries, each 10-100 micrometers in diameter, that multiply electrons through secondary emission for single-photon detection. Their primary purpose spans night vision image intensifiers, mass spectrometry detectors, and particle physics instrumentation where extreme sensitivity matters. Enhanced plates command margin premiums in medical imaging as hospitals seek higher resolution under diagnostic standards. Electron multiplication technology leads volume in defense and aerospace applications. Custom plates represent the fastest-growing category as research institutions specify novel geometries for particle detection experiments.
FDA diagnostic imaging standards, EU MDR device classification rules, and ISO 9001 quality management frameworks collectively shape product certification requirements and hospital procurement criteria. Japan's METI supports domestic manufacturing through industrial technology grants that sustain Hamamatsu's R&D pipeline. Stakeholders must monitor how evolving defense export controls and medical device traceability mandates reshape supplier qualification timelines.
Market Dynamics
Defense procurement cycles and diagnostic imaging standards are converging to reshape supplier qualification timelines across the microchannel plates supply base. Manufacturers must now satisfy simultaneous electron multiplication performance benchmarks and medical device traceability mandates to maintain dual-use market access.
Growth Catalysts
- Night Vision Modernization:Defense agencies in Germany, Japan, and the United States are accelerating image intensifier upgrades for ground and aerial platforms. Electron multiplication specifications now demand higher gain uniformity across temperature extremes.
- EU MDR Diagnostic Standards:Stricter resolution requirements for medical imaging devices are pushing European hospitals toward enhanced microchannel plates. Certification timelines have compressed procurement decision windows.
- Particle Physics Investment:Research institutions specify novel capillary geometries for single-photon detection experiments. Custom plate configurations command development partnerships with specialized manufacturers.
Market Restraints
- Lead Glass Supply Concentration:Specialized glass substrates containing lead oxide for secondary emission properties source from limited European and Japanese suppliers. Geopolitical friction threatens input security.
- FDA 510(k) Pathway Complexity:Medical device classification rules create extended validation periods for new plate designs. Diagnostic imaging manufacturers face dual compliance burdens with ISO 9001 quality frameworks.
- Solid-State Detector Substitution:Silicon photomultipliers and avalanche photodiodes are capturing segments of low-light detection where extreme gain is not required. Price-sensitive scientific instrumentation buyers are evaluating alternatives.
Strategic Opportunities
- Space-Based Sensing:Satellite manufacturers require radiation-hardened microchannel plates for ultraviolet and x-ray astronomy payloads. Orbital application specifications differ substantially from terrestrial defense standards.
- Japan METI Industrial Grants:Domestic manufacturing support programs sustain capital investment in advanced photonics fabrication. Foreign suppliers face qualification barriers without local partnership structures.
- Mass Spectrometry Miniaturization:Portable analytical instruments for environmental monitoring and food safety are shrinking detector footprints. Microchannel plate manufacturers can capture value through geometry optimization.
Industry Challenges
- Specialized Glass Drawing Expertise:Million-channel plate fabrication requires master craftsmen capable of maintaining 10-100 micrometer capillary uniformity across large formats. Talent pipelines for this precision work are constricting.
- Cleanroom Capacity Scaling:Secondary emission coating processes demand Class 1000 or better environments. Capital requirements for additional production lines strain mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microchannel Plates Market |
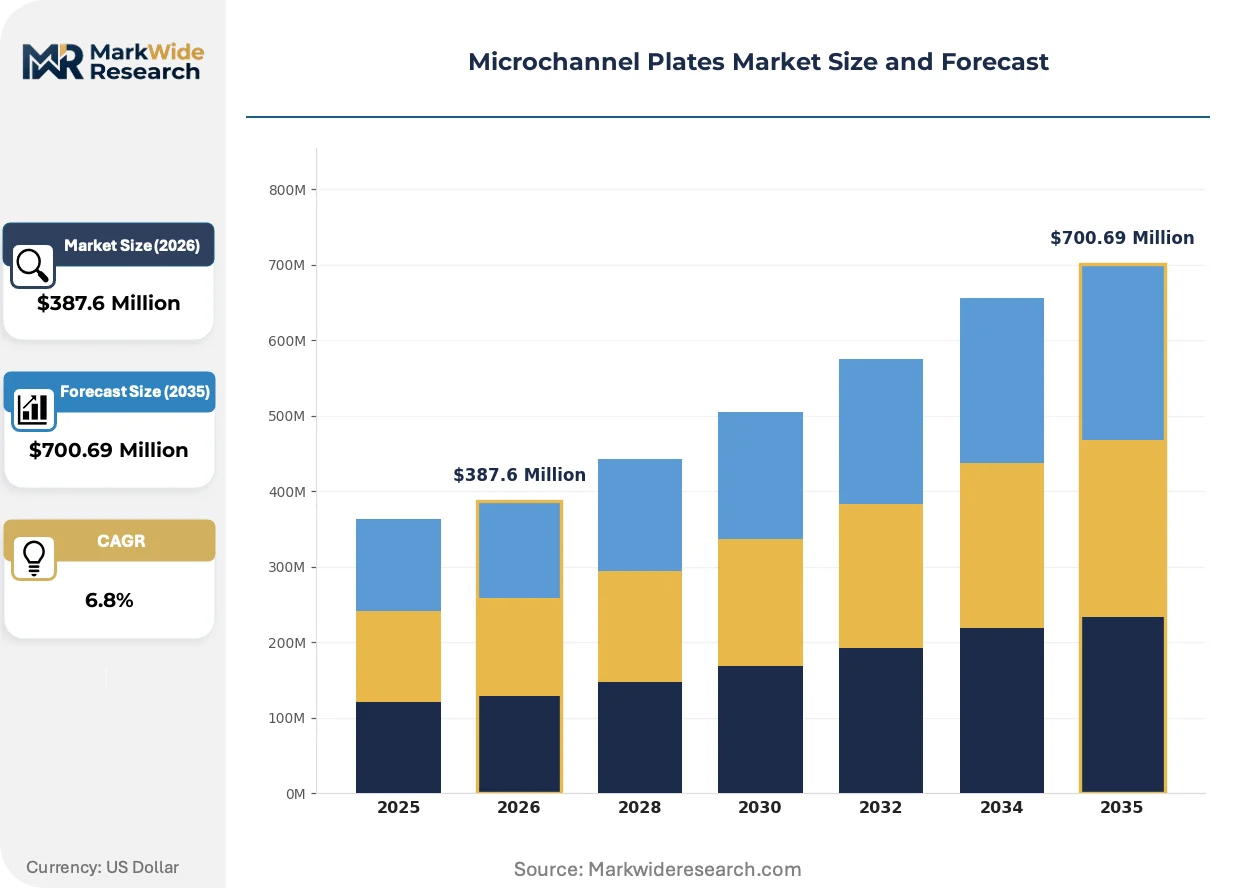
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Plates, Enhanced Plates, Custom Plates, Specialty Plates Technology: Electron Multiplication, Photon Detection, Charge Coupled Devices, Imaging Techniques Application: Medical Imaging, Scientific Research, Security Screening, Aerospace End User: Hospitals, Research Institutions, Defense Agencies, Space Organizations |
| Companies Covered | Hamamatsu Photonics K.K., PHOTONIS Technologies S.A.S., Incom, Inc., Photek, Tectra GmbH, Topag Lasertechnik GmbH, Baspik Ltd., Vigo System S.A., McPherson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microchannel Plates Market Shifts & Advancements
Software-defined calibration protocols are displacing hardware-fixed gain settings across detection system architectures. This shift is compressing traditional equipment replacement cycles while opening service revenue streams.
Atomic layer deposition of alternative electron multiplication materials is automating the transition away from traditional lead-glass substrates. Space instrumentation manufacturers at NASA and ESA are piloting these coatings for radiation-hardened missions. The technology is automating quality control by enabling real-time gain mapping during fabrication rather than post-production testing.
EU MDR device classification rules are tightening traceability requirements for diagnostic imaging components. Hospitals must now document supplier qualification across the full component chain. Enhanced microchannel plates with serialized manufacturing records are capturing preference in European procurement.
Defense agencies are unbundling image intensifier maintenance from original equipment manufacturer contracts. Third-party service providers with electron multiplication expertise are securing multi-year sustainment agreements. This pattern is most visible in United States Army and Marine Corps night vision fleet management programs.
Microchannel Plates Market Segmentation
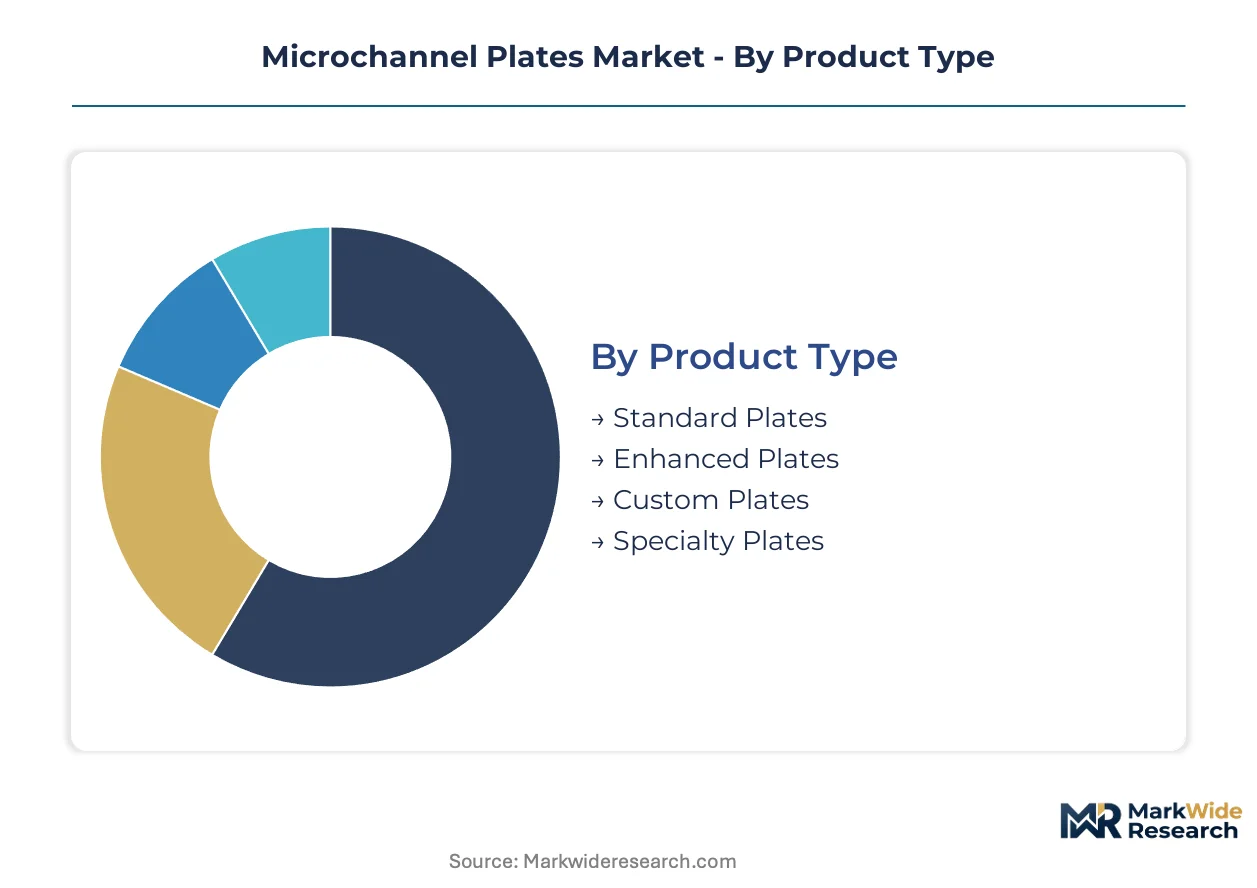
Microchannel plates fragment across four distinct dimensions that reshape procurement patterns and supplier economics. Product specifications, detection technologies, application requirements, and end-user compliance burdens each create separate qualification pathways for manufacturers.
Product Type:
Standard plates dominate unit volume in mature defense and industrial applications, while enhanced and custom configurations capture margin premiums in medical and scientific markets.
- Standard Plates:Fabricated from lead-glass substrates with uniform 10-100 micrometer capillary arrays, these plates satisfy baseline electron multiplication requirements for conventional night vision systems. Defense agencies in the United States and Germany procure these through multi-year fleet sustainment contracts where cost predictability outweighs performance optimization.
- Enhanced Plates:Secondary emission coatings and refined capillary geometries deliver higher gain uniformity across temperature extremes. European hospitals facing EU MDR diagnostic imaging standards are redirecting procurement toward these configurations to satisfy stricter resolution benchmarks without full custom development cycles.
- Custom Plates:Research institutions specify novel geometries for particle physics detection experiments. Development partnerships with specialized manufacturers command extended lead times but enable single-photon sensitivity in configurations unavailable off-the-shelf.
- Specialty Plates:Radiation-hardened variants serve space-based ultraviolet and x-ray astronomy missions at NASA and ESA.
Mature deployment sits with Standard Plates. Newer deployment is concentrated in Custom Plates.
Technology:
Electron multiplication anchors defense and aerospace procurement, while photon detection and solid-state alternatives reshape scientific instrumentation selection criteria.
- Electron Multiplication:Secondary emission cascades within capillary structures achieve gain factors exceeding 10^6 for single-photon detection. Night vision image intensifiers for ground and aerial platforms in Japan and the United States specify this technology exclusively.
- Photon Detection:Direct photon-to-electron conversion without intermediate phosphor stages reduces response latency. Particle physics experiments at CERN and Fermilab specify these configurations for time-resolved measurements.
- Charge Coupled Devices:Integration with microchannel plate outputs enables digital readout for medical imaging systems.
- Imaging Techniques:Software-defined gain calibration protocols are displacing hardware-fixed settings across detection architectures.
Volume concentration favors Electron Multiplication. Technology transition is accelerating in Imaging Techniques.
Application:
Medical imaging and scientific research command premium pricing through compliance and customization requirements, while security screening and aerospace operate on performance-to-cost optimization.
- Medical Imaging:Diagnostic equipment manufacturers integrate enhanced plates to satisfy FDA 510(k) and EU MDR resolution standards. Hospital procurement committees now require serialized manufacturing records for full component chain traceability.
- Scientific Research:Mass spectrometry and particle physics instrumentation demands novel capillary geometries with extreme gain uniformity. Research institutions specify development partnerships rather than catalog purchases.
- Security Screening:Portable analytical instruments for environmental monitoring and food safety are shrinking detector footprints.
- Aerospace:Satellite manufacturers require radiation-hardened plates for orbital ultraviolet and x-ray sensing payloads.
Compliance complexity peaks in Medical Imaging. Custom specification intensity is climbing fastest in Scientific Research.
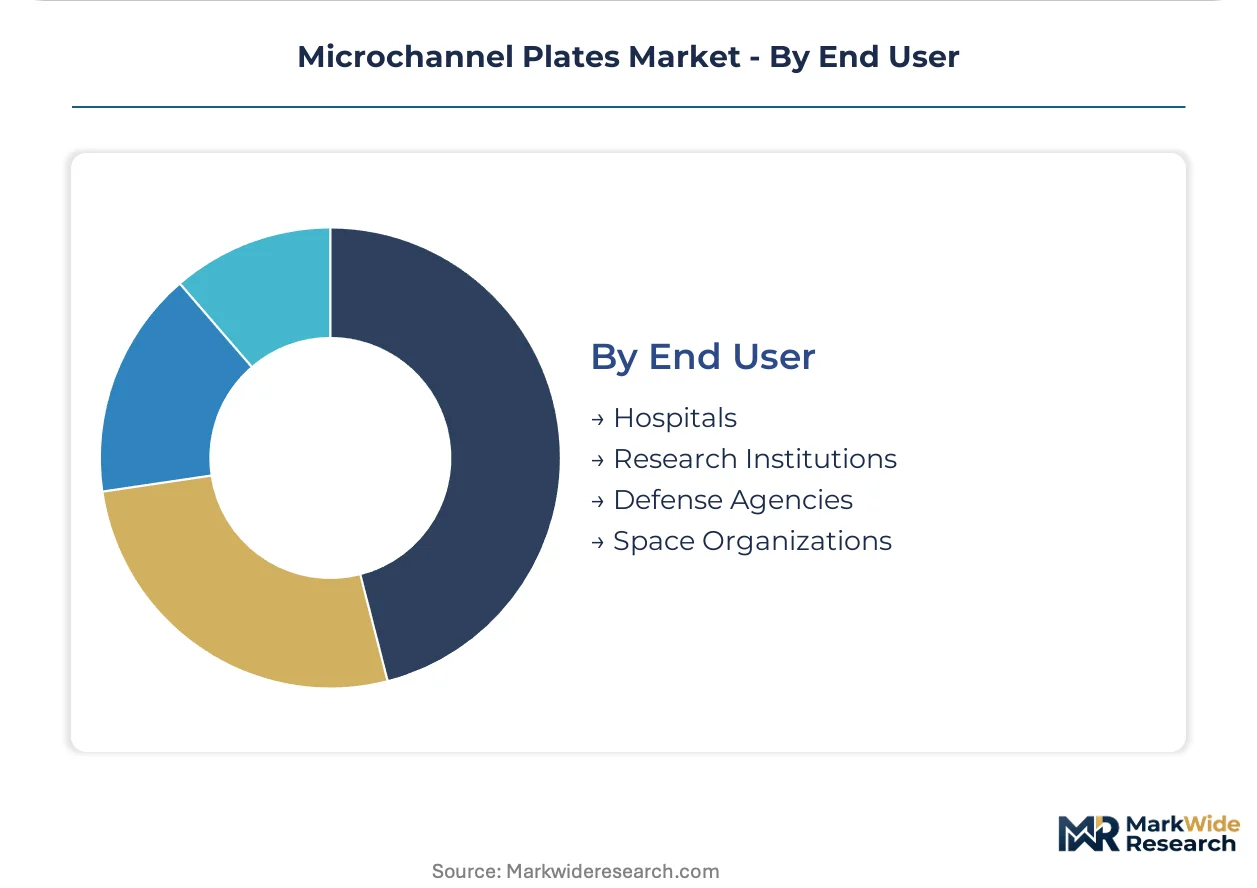
End User:
Defense agencies and hospitals operate on divergent procurement timelines—multi-year sustainment contracts versus compressed certification windows under evolving diagnostic standards.
- Hospitals:Diagnostic imaging departments face simultaneous FDA and EU MDR compliance burdens that compress supplier qualification timelines. Procurement committees prioritize enhanced plates with documented ISO 9001 quality management certification.
- Research Institutions:Particle physics laboratories and mass spectrometry facilities specify custom geometries through direct development partnerships. Funding cycles from national science agencies determine procurement timing.
- Defense Agencies:Night vision fleet modernization programs in the United States, Germany, and Japan generate sustained demand for standard and enhanced plates. Third-party service providers are unbundling maintenance from original equipment manufacturer contracts.
- Space Organizations:NASA and ESA mission specifications for radiation-hardened detectors differ substantially from terrestrial defense standards.
Procurement standardization is deepest with Defense Agencies. Specification evolution is most rapid among Hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan and Germany concentrate fabrication capacity for lead-glass substrates and precision capillary drawing. The United States consumes the largest share of finished plates through defense and medical imaging procurement. Demand fragmentation across these three centers shapes regional trade flows and supplier qualification requirements.
United States
Night vision fleet modernization programs at the Army and Marine Corps sustain volume demand for standard and enhanced plates. FDA 510(k) diagnostic imaging standards compress supplier qualification timelines for hospital procurement committees. Boston and Washington DC corridor hosts medical device manufacturers integrating serialized plates for traceability compliance.
Germany
EU MDR device classification rules redirect hospital procurement toward enhanced configurations with documented resolution benchmarks. The country's national pharmaceutical regulator enforces stricter component chain documentation than predecessor directives. Munich and Stuttgart industrial clusters concentrate precision glass drawing expertise for secondary emission substrates.
Japan
METI industrial technology grants sustain capital investment in advanced photonics fabrication for domestic manufacturers. JIS quality management frameworks align with ISO 9001 certification requirements for export market access. Hamamatsu and surrounding Shizuoka Prefecture anchor vertically integrated photonics manufacturing with captive substrate production.
United Kingdom
Particle physics research at CERN-adjacent facilities generates custom plate specifications for time-resolved detection experiments. The country's national pharmaceutical regulator maintains alignment with EU MDR standards post-transition. Oxford and Cambridge corridor hosts mass spectrometry instrumentation manufacturers shrinking detector footprints for portable analytical devices.
France
PHOTONIS Technologies anchors European defense supply chains with specialized electron multiplication expertise. ANSM medical device oversight requires enhanced traceability documentation for diagnostic imaging components. Paris-Saclay research cluster drives novel capillary geometry development for single-photon detection experiments.
Microchannel Plates Market Competitive Landscape
Top-tier vendors anchor defense and medical imaging procurement with vertically integrated fabrication, while mid-tier specialists capture custom development partnerships from research institutions. The vendor base concentrates around three strategic archetypes: photonics conglomerates with captive glass production, defense-focused electron multiplication specialists, and scientific instrumentation customizers. Capacity expansion and strategic partnerships dominate competitive moves as qualification barriers rise under dual-use regulatory frameworks.
Within the vertically integrated tier, Hamamatsu Photonics K.K. exemplifies full-stack photonics manufacturing with upstream control over substrate production. PHOTONIS Technologies S.A.S. occupies a position anchoring European defense supply chains through specialized electron multiplication expertise. Incom, Inc. sits within the scientific instrumentation specialist archetype, representing custom plate geometry capabilities for research institution partnerships. These three entities collectively illustrate how fabrication depth, regional defense alignment, and research customization capability partition competitive positioning across the supply base.
| Leading Market Players |
|---|
| Hamamatsu Photonics K.K. |
| PHOTONIS Technologies S.A.S. |
| Incom, Inc. |
| Photek |
| Tectra GmbH |
| Topag Lasertechnik GmbH |
| Baspik Ltd. |
| Vigo System S.A. |
| McPherson |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between enhanced plates for EU MDR hospital procurement and standard configurations for defense sustainment contracts manifests in pricing spreads and supply chain segmentation. Three-tier pricing stratification across premium, standard, and economy tiers tracks the lead-glass substrate purity and capillary drawing precision required for each application tier.
Pricing Analysis
Margin tightening in standard plates reflects solid-state detector substitution pressure from silicon photomultipliers in price-sensitive scientific instrumentation. Contract-based long-term offtake dominates defense procurement, while project-based pricing governs custom plate development partnerships. Price differentiation hinges on ISO 9001 certification grade and capillary geometry customization level. Research institutions exhibit lowest price sensitivity; portable analytical instrument manufacturers face acute cost compression.
Supply Chain Analysis
Qualification gating through FDA 510(k) and EU MDR traceability mandates concentrates supply relationships with certified manufacturers. Lead-glass substrate production centers on Japan, Germany, and the United States. Fabrication draws from specialized lead oxide suppliers and precision capillary drawing equipment. Single-source vulnerability looms in master craftsman talent for million-channel plate uniformity. Distribution runs through OEM integrators for defense and direct hospital procurement for medical imaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microchannel plate manufacturing is consolidating around dual-use qualification capabilities as FDA and EU MDR compliance costs force sub-scale competitors toward exit.
For Market Incumbents: Deepen backward integration into lead-glass substrate production to secure input quality and margin control against Japanese and German supply concentration. Expand Class 1000 cleanroom capacity in United States corridors to capture defense third-party service contracts unbundling from OEM maintenance agreements. Fortify against silicon photomultiplier substitution through electron multiplication performance benchmarking. For New Entrants and Emerging Players: Begin with mass spectrometry miniaturization segments where portable analytical instrument manufacturers seek geometry-optimized detectors without legacy qualification burdens. Target environmental monitoring and food safety applications with shrunken detector footprints. Pursue development partnership positioning rather than catalog competition against entrenched photonics conglomerates. For Investors and Strategic Acquirers: Re-rating potential sits with scientific instrumentation customizers given particle physics investment cycles and novel capillary geometry demand. Five-to-ten year viability favors manufacturers with captive glass production and serialized manufacturing records for EU MDR traceability. Monitor defense export control evolution as inflection signal for supplier qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lead-Glass Substrates | Captive supply of secondary emission materials insulates against Japanese and German input concentration. |
| Class 1000 Cleanroom Capacity Expansion | Secondary emission coating scale-up enables qualification for FDA 510(k) diagnostic imaging contracts. |
| Serialized Manufacturing Record Implementation | EU MDR traceability compliance captures preference in European hospital procurement committees. |
| Development Partnership Structuring | Direct research institution relationships command premium pricing for novel capillary geometries. |
| Third-Party Service Capability Buildout | Electron multiplication expertise secures multi-year sustainment agreements as defense agencies unbundle maintenance. |
Research Methodology
Multi-period observation of defense procurement cycle timing, FDA 510(k) submission volumes, and EU MDR certification trajectories anchored the trend analysis, supplemented by interviews with night vision program managers, hospital biomedical engineers, diagnostic equipment procurement leads, and particle physics laboratory directors. Secondary validation drew from FDA device classification databases, EMA MDR implementation guidance, METI industrial technology grant disclosures, and ISO 9001 certification registries. Bottom-up plate shipment estimates triangulated against top-down defense budget appropriations and medical imaging equipment production data.
Input-output matrices modeled electron multiplication performance specifications against end-use compliance requirements across product type, detection technology, application, and end-user dimensions. CAGRs derived from segment-level volume projections calibrated to defense modernization program announcements and hospital capital expenditure surveys. Forecast inputs included lead-glass substrate supply constraints, cleanroom capacity expansion pipelines, and solid-state detector substitution elasticity in scientific instrumentation.
Underlying measurement precision varies by segment; defense procurement volumes carry tighter precision than research institution custom development cycles. Forecasts reflect documented assumptions regarding regulatory timeline stability and input supply security. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Component Tester Market
Optical Components
Flexible Glass for Flexible Electronics Market
Optical Components
Fogless Mirror Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Optical Transceiver Market
Optical Components
Electronic Digital Magnifiers Market
Optical Components
Ellipsometer Market
Optical Components
US Optical Sensors Market
Optical Components
Planar Lightwave Circuit Splitter Market
Optical Components
3-7mm Galvo Scanner Market
Optical Components
Silicon Photonics Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Liquid Lenses Market
Optical Components
Photosensitive Glass Market
Optical Components
Asia Pacific Optical Sensors Market
Optical Components
US Lithium Niobate Modulator Market