
 South Korea Optical Detector Market | 2026-2036
South Korea Optical Detector Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Optical Detector Market Insights
MFDS medical device certification is reorganizing competitive access in South Korea's optical detector sector. Koh Young Technology leverages its machine vision specialization to sustain dominance in PCB inspection systems for domestic electronics fabs. Hamamatsu Photonics K.K. anchors premium photodiode supply through deep vertical integration across epitaxial growth and packaging stages. STMicroelectronics competes on silicon-based CMOS sensor scale, extending its foundry partnerships with Korean automotive Tier 1 suppliers.
Optical detectors are semiconductor devices that convert incident photons into measurable electrical signals through photovoltaic or photoconductive mechanisms, with spectral sensitivity spanning ultraviolet through infrared wavelengths depending on material bandgap engineering. Their primary commercial purpose centers on precision light measurement, imaging acquisition, and optical communication signal reception across industrial and consumer systems. CMOS image sensors lead volume production due to smartphone camera module demand, while InGaAs detectors command premium positioning in near-infrared spectroscopy for semiconductor wafer inspection. Quantum dot technology represents the fastest-expanding segment as Korean display makers integrate colloidal quantum dot photodetectors for next-generation sensing applications.
MFDS, Korea's national pharmaceutical and medical device regulator, enforces electromagnetic compatibility and biocompatibility standards that filter non-compliant optical sensor imports from European and Japanese suppliers. The Korea Agency for Technology and Standards mandates JIS-aligned calibration protocols for industrial automation deployments, creating compliance cost barriers for mid-tier entrants. Stakeholders must monitor how MFDS expands its software-as-medical-device framework to AI-enabled optical diagnostic instruments, as this reclassification would force additional clinical validation cycles for CMOS and CCD-based imaging modules.
Market Dynamics
MFDS certification expansion for AI-enabled diagnostic instruments is compressing product development timelines while forcing semiconductor fabs to requalify CMOS sensor supply chains for medical-grade reliability standards.
Growth Catalysts
- Semiconductor wafer inspection demand:Domestic memory and logic chip manufacturers in Gyeonggi Province are scaling near-infrared spectroscopy deployments for defect detection at sub-10nm nodes.
- MFDS software-as-medical-device framework:The regulator's expanding scope to AI-powered optical diagnostics creates mandatory upgrade cycles for imaging module manufacturers serving hospital networks.
- Quantum dot photodetector integration:Display makers in Seoul's precision electronics cluster are adopting colloidal quantum dot sensors for next-generation sensing applications in automotive and consumer panels.
Market Restraints
- Epitaxial wafer supply concentration:Premium photodiode production depends on captive supply of indium phosphide substrates from a concentrated base of Japanese and European vendors.
- JIS-aligned calibration mandates:Korea Agency for Technology and Standards protocols impose compliance cost barriers that filter mid-tier automation sensor imports from Southeast Asian suppliers.
- Silicon photomultiplier substitution:Solid-state alternatives to traditional photomultiplier tubes are compressing addressable market for vacuum tube-based detectors in medical imaging applications.
Strategic Opportunities
- Busan-Ulsan automotive sensor corridor:Hyundai Mobis and Kia's expanding ADAS programs create demand pull for CMOS image sensors in surround-view and LiDAR fusion systems.
- Photonics-foundry partnerships:Fabless quantum dot specialists can access Seoul National University's nanofabrication center for prototype-to-production scaling without captive fab investment.
- Green New Deal semiconductor incentives:National policy frameworks subsidize energy-efficient optical sensor production for solar inverters and smart grid monitoring equipment.
Industry Challenges
- Compound semiconductor process engineering:InGaAs detector fabrication requires specialized metal-organic chemical vapor deposition expertise concentrated in a narrow talent pool.
- Medical device validation timelines:MFDS clinical evidence requirements for AI-enabled optical diagnostics extend product launch cycles by 18-24 months versus industrial automation sensors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Optical Detector Market |
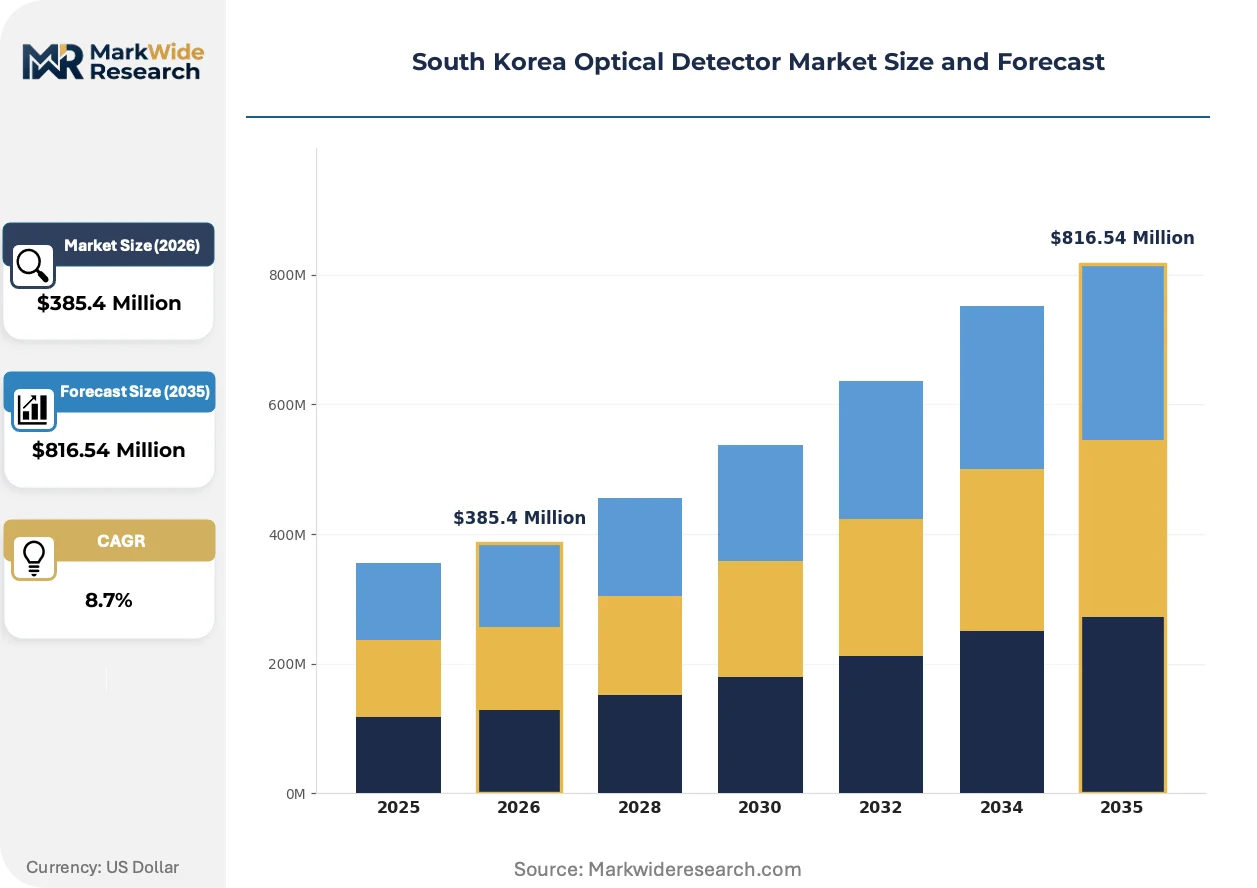
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
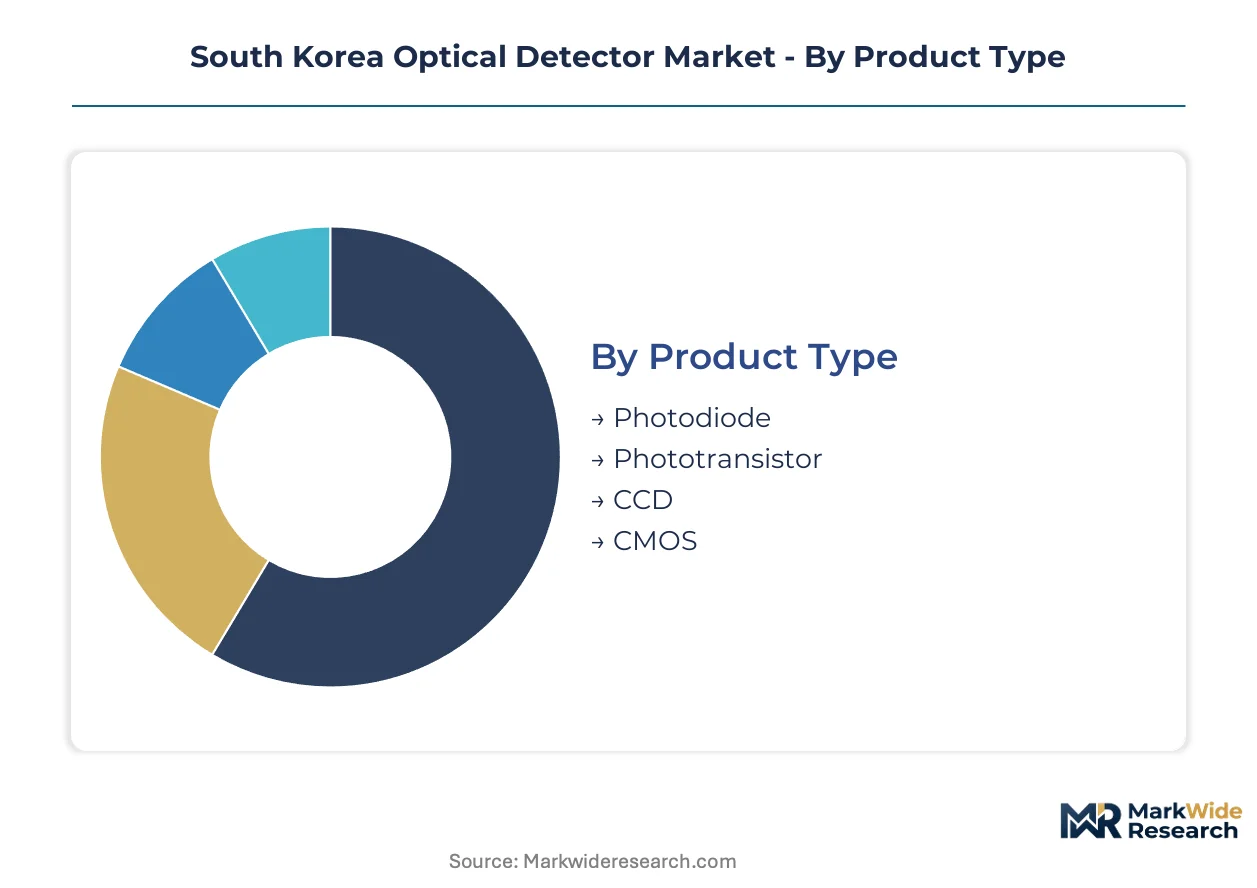
| Segmentation | Product Type: Photodiode, Phototransistor, CCD, CMOS Technology: Quantum Dot, Silicon-Based, Organic, InGaAs Application: Consumer Electronics, Industrial Automation, Medical Devices, Telecommunications End User: Healthcare, Automotive, Aerospace, Retail |
| Companies Covered | Omron Corporation, Texas Instruments, Koh Young Technology, Bosch Sensortec GmbH, TDK Corporation, Hamamatsu Photonics K.K., STMicroelectronics, Infineon Technologies AG, ams OSRAM AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Optical Detector Market Trends and Innovations
Photodetector architectures are diverging between commodity CMOS scale and specialized compound semiconductor precision, with Korean manufacturers navigating both paths simultaneously.
Colloidal quantum dot photodetector technology is fragmenting traditional silicon dominance in near-infrared sensing applications. Samsung Display and LG Display are integrating these solution-processed sensors into under-panel camera modules and ambient light detection systems. The technology is fragmenting established supply relationships by enabling non-traditional materials suppliers to enter the optical detector value chain.
MFDS electromagnetic compatibility testing requirements for medical device optical sensors are tightening ahead of anticipated AI-diagnostic reclassifications. Domestic PCB inspection equipment makers must now pre-validate CMOS modules against biocompatibility standards previously applied only to implantable devices. Seoul-based machine vision specialists are responding by embedding predictive failure analytics to demonstrate continuous compliance.
Hospital procurement committees are consolidating vendor relationships around full-stack imaging system suppliers rather than discrete sensor component vendors. Bundled service contracts covering installation, calibration, and software updates are displacing transactional component sales in tertiary care networks. This concentration is most visible in Seoul's five largest university hospital systems, which collectively account for disproportionate demand for high-end diagnostic optical detectors.
South Korea Optical Detector Market Segmentation
Optical detector segmentation in South Korea reflects the country's dual position as a domestic electronics manufacturing hub and export-oriented precision component supplier. Understanding how demand fragments across product architectures, material systems, and end-use certifications enables suppliers to align R&D investments with the most defensible revenue pools.
Product Type:
Photodiode and CMOS variants dominate domestic production volumes, while CCD retains niche positioning in specialized inspection equipment exports to Southeast Asian semiconductor fabs.
- Photodiode:These p-n junction devices convert light to current with nanosecond response times and minimal dark noise. Samsung Electro-Mechanics and domestic automotive Tier 1 suppliers in Busan drive demand for avalanche and PIN photodiodes in LiDAR and optical communication modules. MFDS biocompatibility requirements for medical-grade variants constrain import substitution opportunities.
- CMOS:Active-pixel sensor arrays integrate photodiodes with readout circuitry on single silicon dies, enabling high-speed imaging at low power. Seoul's smartphone camera module ecosystem—anchored by LG Innotek and Cowell Electronics—consumes the majority of domestic CMOS wafer starts, with surplus capacity directed to automotive surround-view systems.
- Phototransistor:Bipolar junction devices offering internal current gain for low-light applications without external amplification. Industrial automation sensor makers in Incheon's free economic zone specify these for presence detection in conveyor systems.
- CCD:Charge-coupled device architectures maintain residual demand in high-dynamic-range scientific imaging and legacy semiconductor wafer inspection tools. Domestic production has shifted toward refurbishment and module integration rather than front-end fabrication.
CMOS holds the largest share; momentum sits with photodiodes as automotive LiDAR penetration deepens.
Technology:
Silicon-based platforms command scale economics, while compound semiconductor alternatives capture premium pricing in spectroscopic applications where bandgap engineering determines spectral selectivity.
- Silicon-Based:Mature CMOS and bipolar processes leverage Korea's foundry infrastructure for cost-optimized visible and near-infrared detection. Domestic memory manufacturers in Icheon and Pyeongtaek specify silicon photodetectors for inline process monitoring where 900-1100nm sensitivity suffices.
- InGaAs:Indium gallium arsenide epitaxy enables short-wave infrared detection to 1700nm for semiconductor defect inspection and fiber optic test equipment. Epitaxial wafer supply dependence on Japanese vendors limits domestic value capture to packaging and module assembly stages.
- Quantum Dot:Colloidal nanocrystal films deposited via solution processing extend spectral tunability beyond traditional semiconductor constraints. Samsung Display and LG Display are integrating these sensors into under-panel camera architectures for bezel reduction.
- Organic:Polymer and small-molecule photodetectors offer mechanical flexibility and visible-light sensitivity at potentially lower thermal budget than crystalline alternatives. Research-stage deployments at KAIST and POSTECH spinouts target wearable health monitoring applications.
Silicon-based technology anchors volume production; quantum dot architectures are climbing the fastest as display makers redesign sensing integration.
Application:
Medical device and industrial automation applications impose the most stringent certification requirements, creating structural margin premiums over consumer electronics where price competition dominates procurement decisions.
- Consumer Electronics:Smartphone camera modules, ambient light sensors, and proximity detectors constitute the highest-volume demand pool. Domestic ODMs in Gumi and Gwangju source CMOS sensors for Samsung Electronics and Apple supply chains, with specifications converging toward 200-megapixel resolution and sub-pixel binning for low-light performance.
- Industrial Automation:Machine vision systems for PCB inspection, robotic guidance, and quality control require predictable quantum efficiency and MTBF ratings. Koh Young Technology's domestic market leadership in solder paste inspection drives specification standards for competing sensor vendors.
- Medical Devices:Diagnostic imaging, pulse oximetry, and endoscopic systems demand MFDS-certified electromagnetic compatibility and biocompatibility. Hospital procurement consolidation in Seoul's university hospital networks favors full-stack imaging suppliers over discrete component vendors.
- Telecommunications:Optical transceivers for 5G fronthaul and data center interconnects specify high-speed photodetectors with bandwidths exceeding 50 GHz. Domestic module assemblers in Suwon source InGaAs and silicon germanium variants for 400G/800G coherent systems.
Consumer electronics holds the largest share; medical devices present the steepest expansion trajectory as MFDS expands software-as-medical-device frameworks to AI-enabled diagnostics.
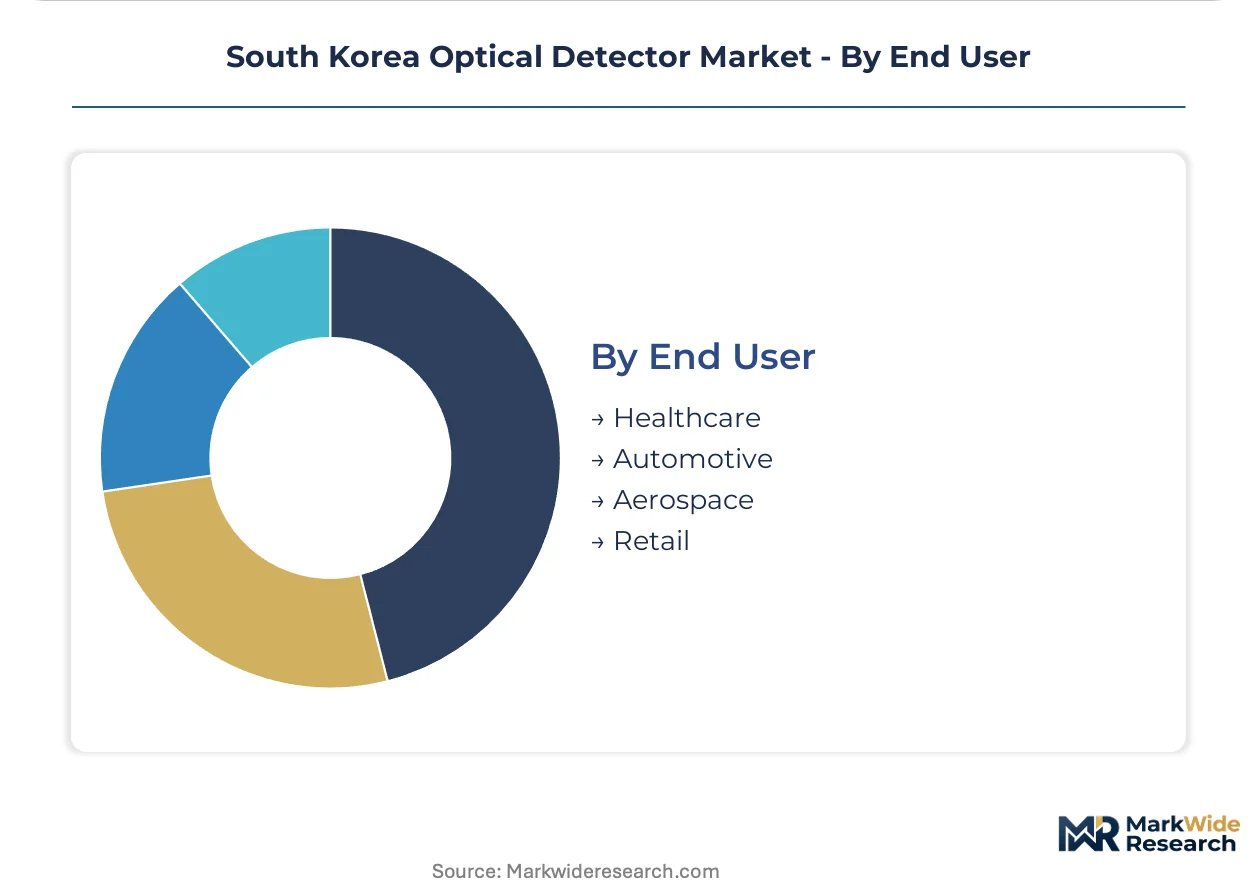
End User:
Healthcare and automotive end users are consolidating vendor relationships around full-stack system suppliers, while aerospace and retail maintain more fragmented procurement patterns.
- Healthcare:Tertiary care networks and diagnostic imaging centers drive demand for high-sensitivity, low-noise photodetectors in CT, PET, and optical coherence tomography systems. Bundled service contracts covering calibration and software updates are displacing transactional component sales.
- Automotive:Hyundai Mobis, Kia, and emerging EV specialists specify CMOS image sensors and LiDAR photodetectors for ADAS and autonomous driving programs. The Busan-Ulsan corridor is consolidating as the primary demand center for automotive-grade optical components.
- Aerospace:Satellite imaging and unmanned aerial vehicle payloads require radiation-hardened and thermally stabilized detector architectures. Domestic participation is limited to subsystem integration; focal plane arrays are imported from European and North American suppliers.
- Retail:Automated checkout systems, inventory tracking, and customer analytics deploy 2D and 3D optical sensing for barcode scanning and gesture recognition. Convenience store chains and duty-free operators in Seoul are piloting frictionless payment systems with embedded photodetector arrays.
Healthcare holds the largest share; automotive is gaining share fastest as ADAS penetration accelerates across domestic vehicle platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National semiconductor subsidies through the Green New Deal framework are redistributing optical detector demand across South Korea's manufacturing belts, with provincial governments competing to anchor photonics clusters through tax abatements and dedicated foundry access.
Seoul Capital Area
Display panel makers in Yongin and Paju drive colloidal quantum dot photodetector integration for under-panel camera modules. MFDS software-as-medical-device consultations concentrate in Seoul's regulatory advisory sector, compressing validation timelines for AI-enabled diagnostic imaging. Pangyo's technopolis hosts machine vision specialists serving PCB inspection demand from Gyeonggi semiconductor fabs.
Busan-Ulsan
Hyundai Mobis and Kia anchor ADAS photodetector procurement for surround-view and LiDAR fusion systems. Korea Agency for Technology and Standards calibration mandates for automotive-grade sensors filter non-compliant imports from Southeast Asian module assemblers. The Ulsan vehicle production complex is consolidating specification authority for CMOS image sensors across domestic EV platforms.
Daegu-Gyeongbuk
Industrial automation sensor makers source phototransistors for robotic guidance systems in textile and machinery manufacturing. Regional free economic zone status reduces tariff exposure on epitaxial wafer imports for InGaAs detector packaging. Daegu's machinery cluster is transitioning from legacy CCD-based inspection to CMOS machine vision architectures.
Daejeon-Sejong
KAIST and national research institutes spin out organic photodetector prototypes for wearable health monitoring applications. Sejong's administrative city status attracts medical device regulatory consulting firms supporting MFDS pre-submission pathways. Daejeon's photonics-foundry partnerships enable fabless quantum dot specialists to access nanofabrication without captive fab investment.
Gwangju-Honam
Solar inverter manufacturers specify energy-efficient optical sensors for smart grid monitoring under Green New Deal procurement preferences. Regional economic development agencies subsidize compound semiconductor workforce training to address MOCVD expertise scarcity. Gwangju's photonics valley is targeting module assembly stages to capture value from imported InP substrates.
South Korea Optical Detector Market Competitive Landscape
Player mix skews toward diversified electronics conglomerates with captive semiconductor divisions, creating tiered competition between integrated device manufacturers and specialized photonics houses. Market structure concentrates premium photodiode supply around Japanese and European vendors with epitaxial growth capabilities, while CMOS sensor segments face price pressure from Korean foundry scale. Three archetypes dominate: machine vision system integrators, compound semiconductor specialists, and silicon-scale commodity producers. Competitive moves center on photonics-foundry partnerships for quantum dot scaling and backward integration into epitaxial wafer supply.
Within the machine vision tier, Koh Young Technology exemplifies domestic PCB inspection specialization, while Hamamatsu Photonics K.K. anchors premium photodiode positioning through upstream control over crystal growth and packaging stages. STMicroelectronics occupies a scale-driven position leveraging foundry partnerships with Korean automotive Tier 1 suppliers for CMOS sensor volume.
| Leading Market Players |
|---|
| Omron Corporation |
| Texas Instruments |
| Koh Young Technology |
| Bosch Sensortec GmbH |
| TDK Corporation |
| Hamamatsu Photonics K.K. |
| STMicroelectronics |
| Infineon Technologies AG |
| ams OSRAM AG |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Japanese epitaxial wafer suppliers lock in InGaAs photodiode access while fixing input cost visibility for Korean module assemblers. These arrangements shield domestic packaging houses from spot-market indium phosphide volatility while embedding MFDS certification premiums into forward pricing schedules.
Pricing Analysis
Certification level (MFDS-grade versus industrial automation tier) creates the primary spread between commodity CMOS sensors and medical-grade photodiodes. Three-tier pricing structure across premium, standard, and economy levels stratifies by spectral precision and reliability ratings. Cost compression in consumer CMOS segments is intensifying because smartphone camera module specifications are converging toward undifferentiated resolution benchmarks. Industrial automation buyers exhibit highest price sensitivity due to JIS-aligned calibration mandates filtering mid-tier imports, while hospital procurement committees prioritize bundled service contracts over unit economics.
Supply Chain Analysis
Japan and Germany anchor epitaxial wafer production for InGaAs and avalanche photodiode substrates, while Taiwan and South Korea dominate silicon CMOS foundry capacity. Domestic packaging operations draw from imported indium phosphide wafers, silicon-on-insulator substrates, and specialized metal-organic chemical vapor deposition precursors. Single-source vulnerability concentrates in Japanese vendors controlling indium phosphide crystal growth. Distribution runs through Seoul-based component distributors serving Gyeonggi semiconductor fabs and Busan automotive Tier 1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MFDS software-as-medical-device reclassifications are fragmenting vendor relationships across AI-enabled diagnostic imaging, creating niche entry points for specialized photonics houses.
For Market Incumbents: Consolidate backward integration into epitaxial wafer supply through offtake agreements with Japanese substrate vendors. Expand MFDS pre-certification consulting capabilities to capture hospital procurement consolidation toward full-stack imaging suppliers. Hamamatsu's upstream control over crystal growth stages exemplifies the defensive moat quantum dot specialists must replicate. For New Entrants and Emerging Players: Anchor in Busan-Ulsan automotive sensor demand for LiDAR photodiodes and surround-view CMOS modules, where Hyundai Mobis procurement specifications remain less consolidated than Seoul hospital networks. Target Daejeon-Sejong photonics-foundry partnerships for prototype scaling without captive fab investment. Lead with JIS calibration compliance as a qualification wedge against Southeast Asian module assemblers. For Investors and Strategic Acquirers: Capital is best deployed toward fabless quantum dot specialists with Seoul National University nanofabrication access and existing display panel customer relationships. Long-term viability hinges on colloidal nanocrystal deposition expertise displacing traditional InGaAs in near-infrared sensing applications. Watch for MFDS AI-diagnostic framework finalization as the signal triggering medical-grade sensor valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Photonics-Foundry Partnership | Enables fabless quantum dot scaling via Seoul National University nanofabrication center access. |
| MFDS Pre-Certification Investment | Compresses AI-enabled diagnostic imaging validation timelines for CMOS module vendors. |
| Epitaxial Wafer Offtake Agreement | Secures indium phosphide substrate supply from Japanese vendors for InGaAs detector packaging. |
| Automotive Tier 1 Supplier Qualification | Unlocks Hyundai Mobis ADAS procurement specifications in Busan-Ulsan corridor. |
| Colloidal Quantum Dot Process Development | Positions Samsung Display and LG Display integration for under-panel camera architectures. |
Research Methodology
Desk research of MFDS regulatory filings, Korea Agency for Technology and Standards calibration protocols, and semiconductor trade flow databases preceded structured interviews with optical detector product managers, hospital biomedical engineers, automotive Tier 1 procurement leads, and machine vision system integrators. Primary fieldwork combined with secondary validation across customs records, foundry capacity disclosures, and display panel maker supply chain announcements. Bottom-up unit economics and top-down sectoral demand models were triangulated for convergence.
Variance decomposition across technology, application, and end-user dimensions shaped the analytical framework over the projection horizon. Modeled segmentation spans product architecture, material system, certification tier, and regional production cluster. CAGRs were derived from normalized baseline values and scenario-weighted growth assumptions. Forecast inputs incorporated Green New Deal subsidy allocation patterns and MFDS software-as-medical-device consultation timelines.
Material uncertainties — epitaxial wafer supply disruptions, MFDS AI-diagnostic reclassification timing, and quantum dot manufacturing yield scaling — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory consultation trajectories and display panel maker technology roadmaps. Recalibration cycles align with material shifts in national semiconductor incentive disbursements and medical device validation pathway announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Electro Optical System Market
Optical Components
Portable Lenses Market
Optical Components
Display Optical Film Market
Optical Components
Digital Optical Transmitter Market
Optical Components
Night Vision Tubes Market
Optical Components
100G Optical Transceivers Market
Optical Components
Ring Laser Gyroscope Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
Pancake Optical Module Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
Optical Dome Market
Optical Components
Italy Lithium Niobate Modulator Market
Optical Components
Mobile Optical Pluggable Market
Optical Components
Global Fiber Optic Gyroscope Market
Optical Components
Fogless Mirror Market
Optical Components
Optical Transmitter Market