
 Liquid Lenses Market | 2026-2036
Liquid Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Lenses Market Foresight
Software-defined focus calibration is decoupling hardware sales from recurring service revenue in the liquid lenses sector. Corning Incorporated leverages its glass-forming expertise to anchor supply of electrowetting substrates for medical and automotive tiers. Optotune specializes in tunable lens modules for machine vision and microscopy, sustaining R&D intensity above industry norms. Samsung Electronics dominates consumer electronics integration, controlling camera stack design for flagship smartphone lines.
Liquid lenses are optical elements that use electrowetting or liquid crystal principles to vary focal length without mechanical moving parts, typically achieving response times under 10 milliseconds through voltage-controlled interface curvature. Their primary commercial purpose is enabling compact, shock-resistant autofocus in space-constrained devices where traditional voice-coil motors fail. Electrowetting lenses lead product type revenue due to maturity in smartphone camera modules, while liquid crystal lenses represent the fastest-growing category for AR waveguide coupling. Among end users, medical devices command the strongest margin pool because diagnostic equipment demands ISO-certified biocompatibility that few suppliers satisfy.
FDA 510(k) pathways shape medical device market access by requiring liquid lens manufacturers to validate optical stability under sterilization cycles. REACH and RoHS frameworks in Europe restrict certain surfactants and electrode materials used in electrowetting assemblies, forcing reformulation of dielectric coatings. Stakeholders must monitor how IEC optical performance standards evolve for augmented reality headsets, as compliance timing will determine which technology suppliers capture design wins in next-generation wearable platforms.
Market Dynamics
Electrowetting substrate supply is concentrating among glass-forming specialists, tightening procurement leverage for medical device OEMs seeking ISO-certified biocompatibility.
Growth Catalysts
- Diagnostic Imaging Demand:Medical device manufacturers are expanding procurement of adaptive optics for ophthalmology and endoscopy systems, requiring liquid lens modules with sub-10 millisecond response times.
- REACH Material Reformulation:European electrowetting lens suppliers are reformulating dielectric coatings to comply with restricted surfactant lists, creating first-mover advantage for compliant producers.
- Smartphone Camera Stack Redesign:Flagship handset OEMs are eliminating voice-coil motors in favor of voltage-controlled focal length variation for shock resistance and module miniaturization.
Market Restraints
- Electrode Material Volatility:Indium tin oxide and transparent conductive oxide prices fluctuate with display panel demand cycles, compressing margin stability for lens assemblers.
- Sterilization Cycle Validation:FDA 510(k) pathways require optical stability demonstration across autoclave and gamma sterilization protocols, extending time-to-market for medical tier entrants.
- Mechanical Autofocus Substitution:Voice-coil motor manufacturers are improving miniaturization and power efficiency, retaining cost advantage in mid-tier consumer electronics.
Strategic Opportunities
- AR Waveguide Coupling:Liquid crystal lenses represent emerging insertion points for augmented reality headset manufacturers seeking compact pupil steering without mechanical actuators.
- German Precision Optics Cluster:Jena and Munich host concentrated R&D infrastructure for electrowetting substrate development, enabling co-location partnerships with automotive LiDAR developers.
- IEC Standard Anticipation:Early alignment with evolving optical performance standards for wearable platforms positions suppliers for design wins in next-generation headset releases.
Industry Challenges
- Biocompatibility Certification Talent:ISO 10993 testing expertise for liquid-contacting optical assemblies remains scarce, constraining medical tier expansion timelines.
- Cleanroom Capex Requirements:Electrowetting lens fabrication demands Class 1000 or better environments for dielectric deposition, elevating barrier to scale for mid-cap entrants.
- Legacy Camera Stack Integration:Smartphone OEMs face firmware and calibration complexity when replacing established voice-coil motor control loops with voltage-driven focus algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Lenses Market |
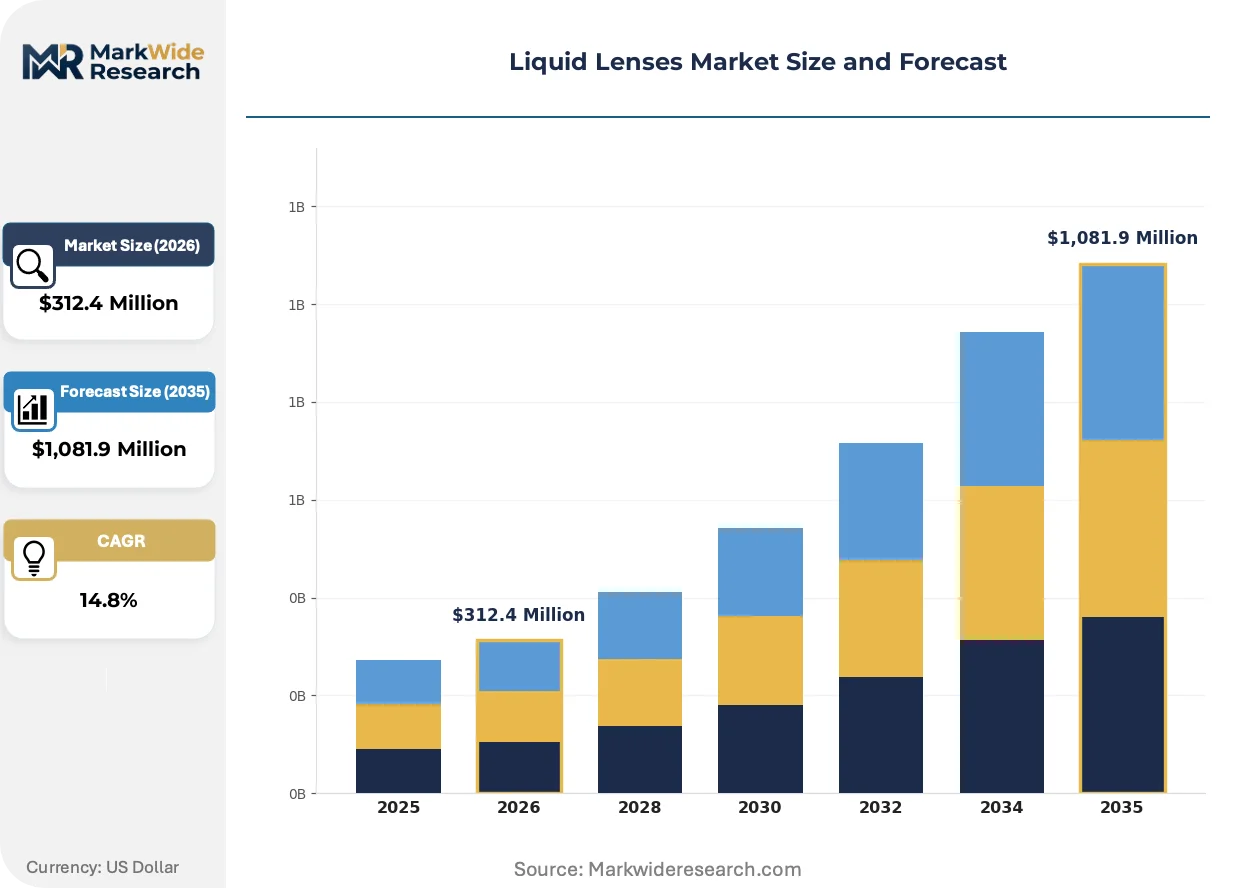
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,081.9 Million |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrowetting Lenses, Variable Focus Lenses, Adaptive Optics, Liquid Crystal Lenses End User: Consumer Electronics, Medical Devices, Automotive, Aerospace Technology: Electrowetting Technology, Liquid Crystal Technology, Optical Coatings, Nanotechnology Application: Camera Systems, Augmented Reality, Virtual Reality, Microscopy |
| Companies Covered | Corning Incorporated, Samsung Electronics, Varioptic, Cognex Corporation, Sony Corporation, Optotune, Huawei Technologies Co., Ltd., Opticon, Edmund Optics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Lenses Market Shifts & Advancements
Voltage-controlled optical interfaces are compressing mechanical complexity across imaging systems. Three developments are restructuring competitive position.
Electrowetting-on-dielectric architectures are electrifying focal length modulation by eliminating translation stages entirely. Medical endoscopy OEMs are adopting these modules for sterilizable instrument channels. The technology is compressing optical train length by sixty percent in diagnostic devices.
REACH and RoHS frameworks in Europe are restricting perfluorinated surfactants historically used in electrowetting electrolyte formulations. Lens manufacturers are substituting hydrocarbon-based alternatives with comparable interfacial tension properties. Medical device assemblers sourcing from European suppliers face reformulation validation timelines.
Software-defined focus calibration is decoupling hardware procurement from recurring service revenue. Machine vision integrators are purchasing lens modules with embedded tuning algorithms rather than discrete optical components. This pattern concentrates in German industrial automation deployments.
Liquid Lenses Market Segmentation
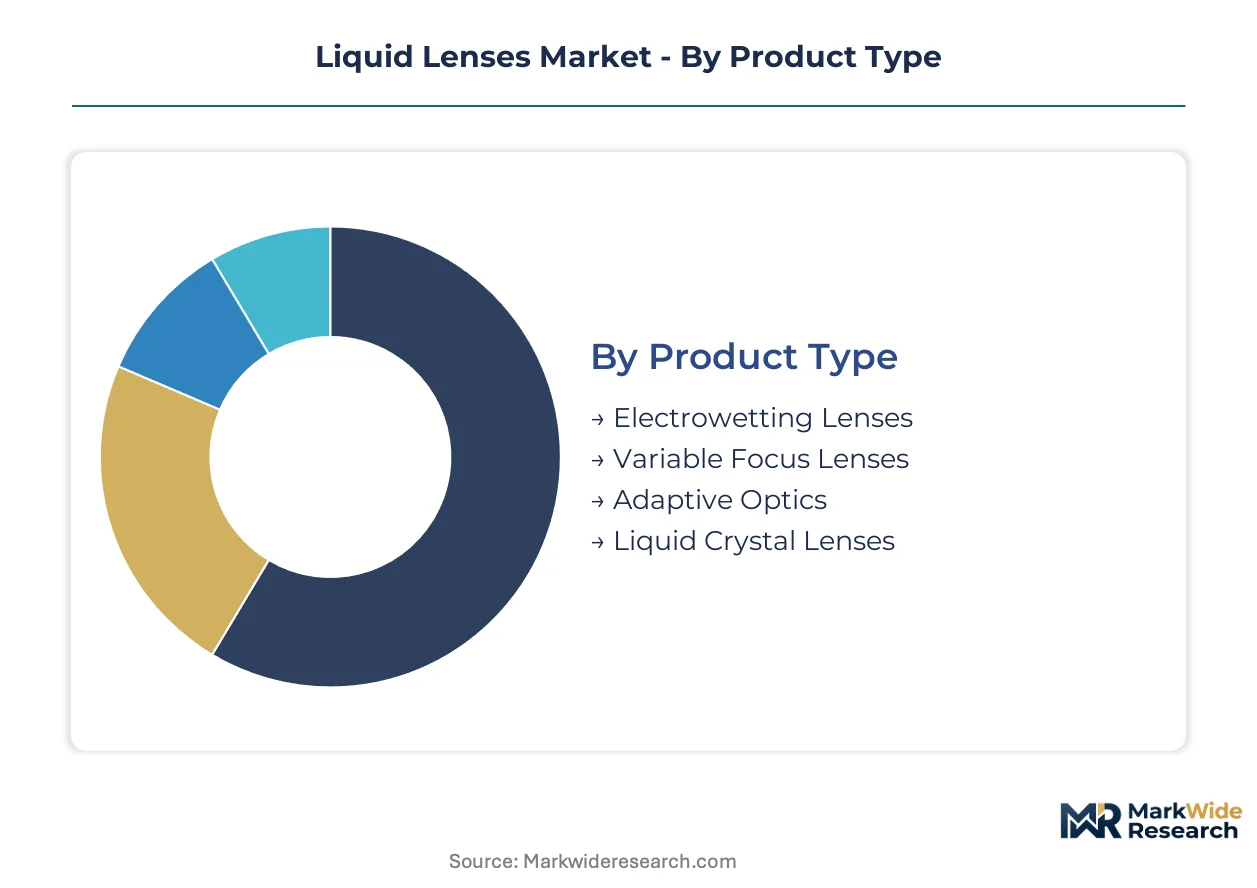
Liquid lens architectures vary sharply in response time, voltage requirements, and sterilization compatibility. Procurement patterns diverge across these boundaries, with medical device OEMs prioritizing biocompatibility certification while consumer electronics manufacturers optimize for module thickness.
Product Type:
Upgrade cycles in diagnostic imaging and smartphone camera stacks are pushing replacement demand toward electrowetting architectures with faster settling times and reduced hysteresis.
- Electrowetting Lenses:These devices modulate focal length through voltage-controlled curvature of a conductive liquid-liquid interface, typically achieving sub-10 millisecond response. German precision optics clusters in Jena and Munich concentrate manufacturing capacity for medical-grade variants that withstand autoclave sterilization.
- Liquid Crystal Lenses:Birefringence-based phase modulation enables polarization-sensitive focus control without mechanical translation. AR headset developers in California and Taiwan are integrating these for compact pupil steering in waveguide-based displays, where space constraints exclude voice-coil motors.
- Variable Focus Lenses:Pressure or thermal actuation of deformable membranes offers simpler drive electronics than electrowetting alternatives. Industrial machine vision deployments in Japanese automotive inspection lines favor these for cost-sensitive multi-camera arrays.
- Adaptive Optics:Wavefront correction systems incorporating deformable mirrors or liquid lenses for real-time aberration compensation. Ophthalmology diagnostic equipment in Swiss and French research hospitals represents the primary demand concentration.
Electrowetting lenses sit at the top of the volume ranking, with liquid crystal lenses climbing the fastest.
End User:
Margin structures diverge sharply across customer categories, with ISO 10993 certification requirements creating pricing power for qualified medical suppliers.
- Consumer Electronics:Smartphone camera stack integration demands sub-2mm module thickness and shock resistance exceeding 1,500G. Samsung Electronics and flagship handset OEMs in South Korea and China are eliminating voice-coil motors for electrowetting focal control.
- Medical Devices:Endoscopy and ophthalmology systems require optical stability across gamma and steam sterilization cycles. FDA 510(k) clearance pathways extend development timelines, compressing supplier margins for unprepared entrants.
- Automotive:LiDAR and surround-view camera systems prioritize temperature stability from -40°C to 85°C. German automotive tier-1 suppliers near Munich are co-lensing development with electrowetting substrate specialists.
- Aerospace:Satellite imaging and unmanned aerial vehicle payloads demand radiation-hardened optics with minimal moving parts. NASA and ESA procurement specifications favor liquid crystal variants for orbital deployment.
Consumer electronics commands the dominant share of unit shipments, though medical devices capture the highest average selling prices.
Technology:
Patent thickets around dielectric deposition and transparent electrode patterning are concentrating licensing leverage among established glass-forming specialists.
- Electrowetting Technology:Voltage-driven manipulation of liquid-liquid interfacial tension requires hydrophobic dielectric coatings with nanometer-scale uniformity. REACH compliance in Europe is forcing reformulation of perfluorinated surfactants historically used in electrolyte formulations.
- Liquid Crystal Technology:Electric field reorientation of nematic phases enables polarization-dependent phase modulation. Taiwanese display panel manufacturers are repurposing existing alignment layer deposition capacity for lens production.
- Optical Coatings:Anti-reflective and hydrophobic surface treatments reduce Fresnel losses and contamination susceptibility. Ion beam sputtering systems in Swiss and Japanese coating houses achieve sub-0.5% reflectance across visible wavelengths.
- Nanotechnology:Self-assembled monolayers and plasmonic nanostructures enable sub-wavelength feature control for advanced wavefront engineering. Research-stage applications concentrate in MIT and ETH Zurich laboratories.
Electrowetting technology anchors current production volumes, while liquid crystal approaches gain fastest in AR headset design-ins.
Application:
Calibration complexity varies by use case, with multi-element camera stacks requiring closed-loop firmware integration that favors incumbent voice-coil motor suppliers.
- Camera Systems:Smartphone, drone, and surveillance applications prioritize autofocus speed and power consumption. Chinese module assemblers are driving electrowetting adoption through stack redesigns eliminating mechanical translation stages.
- Augmented Reality:Waveguide-coupled pupil expansion demands compact varifocal elements with see-through optical paths. Meta and Apple hardware engineering teams are qualifying liquid crystal lenses for next-generation headset releases.
- Virtual Reality:Varifocal displays reducing vergence-accommodation conflict require millisecond-latency focus modulation. Sony and Pico Interactive are evaluating electrowetting modules for premium VR headset refresh cycles.
- Microscopy:High-NA objective integration and slide-scanning automation benefit from vibration-resistant focus control. Leica and Zeiss research microscope lines are incorporating tunable liquid lenses for z-stack acquisition.
Camera systems dominate current procurement volumes, with augmented reality applications showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of electrowetting substrates is migrating toward jurisdictions with established glass-forming infrastructure and streamlined medical device clearance pathways, creating compliance-cost arbitrage between European precision clusters and Asian contract manufacturing hubs.
Germany
Jena and Munich concentrate electrowetting substrate R&D for diagnostic imaging OEMs. ECHA REACH enforcement restricts perfluorinated surfactants in electrolyte formulations, forcing dielectric coating reformulation. The Bavarian precision optics corridor hosts co-development partnerships between substrate specialists and automotive LiDAR developers.
United States
FDA 510(k) pathways shape market access for sterilizable endoscopy modules. Optical stability validation across autoclave and gamma sterilization protocols extends development timelines for unprepared entrants. Boston and San Diego research hospitals drive adaptive optics procurement for ophthalmology diagnostic equipment.
China
Shenzhen and Dongguan module assemblers are eliminating voice-coil motors from smartphone camera stacks. NMPA medical device registration requirements are tightening for liquid-contacting optical assemblies. Yangtze River Delta manufacturing hubs are scaling electrowetting lens capacity for domestic handset OEMs.
South Korea
Seoul Capital Area flagship smartphone manufacturers are redesigning camera modules for shock-resistant focal control. MFDS biocompatibility certification for diagnostic tier products remains underdeveloped relative to FDA or CE pathways. Samsung Electronics anchors domestic demand through vertical control of camera stack specifications.
Switzerland
Swissmedic regulates diagnostic equipment incorporating liquid lenses for ophthalmology applications. ETH Zurich laboratories host research-stage nanotechnology development for advanced wavefront engineering. Swiss coating houses deploy ion beam sputtering systems achieving sub-0.5% reflectance across visible wavelengths.
Liquid Lenses Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with medical-grade certification requirements concentrating margin capture among ISO-qualified substrate suppliers while consumer electronics volume flows toward integrated module assemblers. The vendor base organizes around three archetypes: glass-forming multinationals with electrowetting dielectric expertise, tunable lens module specialists sustaining above-average R&D intensity, and consumer electronics OEMs controlling camera stack design through captive integration. Capacity expansion and strategic partnerships dominate competitive moves, with substrate suppliers co-locating near German automotive LiDAR developers and machine vision integrators embedding software-defined calibration algorithms.
Among glass-forming multinationals, Corning Incorporated anchors supply of electrowetting substrates through materials science expertise. Optotune occupies a position within the tunable lens specialist tier, representing concentrated R&D investment in machine vision and microscopy applications. Samsung Electronics exemplifies the integrated OEM archetype, controlling camera stack specifications for flagship smartphone lines. These three companies collectively illustrate how competitive positioning stratifies across substrate supply, component specialization, and end-product integration.
| Leading Market Players |
|---|
| Corning Incorporated |
| Samsung Electronics |
| Varioptic |
| Cognex Corporation |
| Sony Corporation |
| Optotune |
| Huawei Technologies Co., Ltd. |
| Opticon |
| Edmund Optics |
| Others |
Supply & Pricing Matrix
FDA 510(k) sterilization validation requirements for medical-grade liquid lenses are compressing supplier margins and forcing substrate specialists to absorb certification costs, which then flow through as premium pricing tiers for ISO 10993-compliant assemblies.
Pricing Analysis
Distributor margins for electrowetting lens modules compress at 15-20 points below direct OEM contracts due to firmware calibration complexity. Three-tier pricing structure across medical-certified, industrial-grade, and consumer tiers separates FDA-cleared substrates from REACH-compliant variants and unqualified imports. Pricing pressure stems from indium tin oxide electrode cost volatility tracking display panel demand cycles. Consumer electronics OEMs exhibit highest price sensitivity, while diagnostic equipment manufacturers accept 40-60 point premiums for biocompatibility certification.
Supply Chain Analysis
Freight costs for hydrophobic dielectric coatings and precision-ground glass substrates elevate landed costs by 8-12 points for non-European medical device assemblers sourcing from German precision optics clusters. Electrowetting lens fabrication concentrates in Germany, China, and Switzerland, with substrate supply anchored in Jena and Munich glass-forming infrastructure. Production rests on fluoropolymer dielectric deposition equipment and Class 1000 cleanroom capacity. Single-source vulnerability concentrates in transparent conductive oxide refining. Distribution runs through medical device OEM direct procurement for diagnostic tiers and module assembler consignment for consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement is shifting toward sterilization-validated, REACH-compliant substrates that command sustainable margin premiums over commodity alternatives.
For Market Incumbents: Anchor defensive positioning through captive dielectric coating capacity in Bavaria and ISO 10993 certification depth that emerging Asian entrants cannot replicate quickly. Threat substitution from liquid crystal architectures in AR headsets demands R&D hedging in waveguide-coupling designs. Backward integration into fluoropolymer formulation secures supply continuity against REACH surfactant restrictions. For New Entrants and Emerging Players: Machine vision integrators in German industrial automation corridors represent the most penetrable channel partnership for software-defined calibration modules. White-space targets include pressure-actuated variable focus lenses for Japanese automotive inspection lines and radiation-hardened liquid crystal variants for satellite imaging payloads. Go-to-market execution should emphasize embedded tuning algorithms that decouple hardware procurement from recurring service revenue. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap substrate specialists possessing both glass-forming expertise and medical-grade certification infrastructure. Five-to-ten year viability favors suppliers co-located with automotive LiDAR development clusters near Munich. The signal to watch is IEC optical performance standard finalization timing for AR headset design win allocation.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Dielectric Reformulation | First-mover producers capture medical device procurement from European OEMs facing restricted surfactant lists. |
| Software-Defined Calibration Licensing | Machine vision integrators in Germany embed recurring revenue streams alongside hardware module sales. |
| Co-Location Partnership with LiDAR Developers | Bavarian substrate specialists secure automotive tier-1 design wins through proximity to Munich engineering centers. |
| IEC Standard Anticipation Investment | Early alignment positions suppliers for AR headset platform integration at Meta and Apple hardware divisions. |
| ISO 10993 Certification Expansion | Biocompatibility depth creates pricing power in endoscopy and ophthalmology diagnostic equipment procurement. |
Research Methodology
Multiple input streams — structured interviews with biomedical engineers and GPO contracts managers, regulatory filing analysis, and precision optics trade data — were reconciled to construct demand and supply estimates. Primary fieldwork engaged hospital purchasing committees, medical device OEM procurement leads, and electrowetting substrate R&D directors across German precision optics clusters. Secondary validation drew from FDA 510(k) device clearances, ECHA REACH substance restrictions, SEC filings of glass-forming multinationals, and customs records of fluoropolymer dielectric imports. Bottom-up module shipment estimates and top-down diagnostic equipment production forecasts were triangulated against capital expenditure disclosures from cleanroom fabrication facilities.
Data-stream reconciliation across product architecture, end-use application, technology platform, and geographic production cluster enabled granular segmentation modeling. The analytical framework projected electrowetting versus liquid crystal adoption curves, medical certification tier penetration, and smartphone camera stack redesign timing across the analysis window. CAGRs were derived from shipment volume trajectories and average selling price evolution by certification grade. Forecast inputs incorporated sterilization cycle validation timelines, REACH compliance transition schedules, and AR headset release roadmaps from California and Taiwan hardware engineering teams.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IEC standard publication timing, indium tin oxide supply disruptions, and voice-coil motor efficiency improvements that could delay electrowetting adoption in mid-tier consumer electronics. Forecasts reflect documented assumptions about regulatory clearance pathways and technology substitution elasticities. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Global Wavelength Division Multiplexing (WDM) Equipment Market
Optical Components
Europe Optical Imaging Market
Optical Components
Europe Tunable Laser Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
Erbium Oxide Market
Optical Components
Electro-Optic Modulators Market
Optical Components
Silicon Photonics Market
Optical Components
Polarizer Film Market
Optical Components
Fiber Optic Collimating Lens Market
Optical Components
Mobile Optical Pluggable Market
Optical Components
Ellipsometer Market
Optical Components
Photointerrupter Market
Optical Components
Ring Panel Filters Market
Optical Components
Optical Film Market
Optical Components
Infrared Filter Market
Optical Components
ROADM WSS Component Market