
 Self-Balancing Mobility Market | 2026-2036
Self-Balancing Mobility Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Balancing Mobility Market Analytics
Electric motor control engineering talent is rotating toward Asia-Pacific manufacturing hubs, tightening design capacity in North America and Europe. Segway-Ninebot leverages its Shenzhen-based engineering base to sustain integrated firmware and hardware development. INMOTION anchors European distribution through certified service networks. Gotway competes in high-torque unicycle segments where specialized motor winding expertise creates defensible capability gaps.
Self-balancing mobility devices employ gyroscopic stabilization systems with brushless DC motors, lithium-ion battery packs, and microelectromechanical sensor arrays to maintain equilibrium across two or fewer wheels for personal transport and commercial fleet use. Electric scooters lead product type volume due to shared micromobility fleet procurement, while autonomous technology segments attract R&D investment for campus and warehouse navigation. Last-mile delivery applications within the application dimension are expanding fastest as logistics operators test riderless pod configurations for regulated urban zones.
FAA guidelines govern aerial drone interactions but NHTSA and EPA frameworks shape street-legal self-balancing vehicle classification, battery disposal, and motor efficiency standards in the United States. CE marking and EU AI Act provisions in Europe mandate cybersecurity and algorithmic transparency for app-enabled and autonomous variants. Stakeholders must monitor evolving municipal permitting regimes that determine where and how rental services deploy shared fleets.
Market Dynamics
Fleet operators in Shenzhen, Berlin, and Los Angeles are consolidating procurement around standardized battery-swappable platforms, compressing vendor diversity and elevating firmware-integrated hardware suppliers.
Growth Catalysts
- EU Green Deal emission mandates:Municipalities in Germany, France, and the Netherlands are banning combustion-engine vehicles from city centers, forcing logistics operators toward electric self-balancing pods for last-mile delivery.
- Lithium-silicon anode chemistry:Next-generation cell architectures are extending per-charge range by forty percent, eliminating range anxiety for commercial fleet managers deploying unbroken daily shifts.
- China:Shenzhen and Shanghai municipal governments are fast-tracking dedicated micromobility lanes and parking infrastructure, reducing accident liability exposure for rental service operators.
Market Restraints
- Cobalt and lithium carbonate price volatility:Battery pack input costs swing unpredictably, eroding margin visibility for hardware manufacturers locked into twelve-month fleet supply contracts.
- Brushless DC motor supply concentration:High-torque motor winding capacity clusters in Guangdong Province, creating single-source vulnerability for European and North American assemblers.
- CE marking cybersecurity annex:The EU AI Act's algorithmic transparency requirements are extending certification timelines by eight to fourteen months for app-connected models.
Strategic Opportunities
- India:Tier-two cities including Pune and Ahmedabad lack micromobility infrastructure, presenting first-mover advantages for rental services willing to pre-position charging networks.
- Autonomous campus navigation:Warehouse and university deployments are testing riderless pod configurations, opening software licensing revenue streams beyond hardware sales.
- US Inflation Reduction Act clean vehicle credits:Commercial fleet purchasers qualify for tax incentives when procuring domestically assembled electric mobility devices, reshaping sourcing geography.
Industry Challenges
- Embedded systems firmware engineering:Gyroscopic stabilization algorithm development requires specialized talent that rotates toward Asia-Pacific manufacturing hubs, hollowing North American and European design capacity.
- IP fragmentation across sensor fusion patents:Microelectromechanical array calibration methods are encumbered by overlapping university and corporate licensing claims, complicating product development.
- Reverse logistics for battery end-of-life:EPA hazardous waste rules and EU Battery Directive disposal mandates are imposing collection infrastructure costs that rental operators struggle to internalize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Balancing Mobility Market |
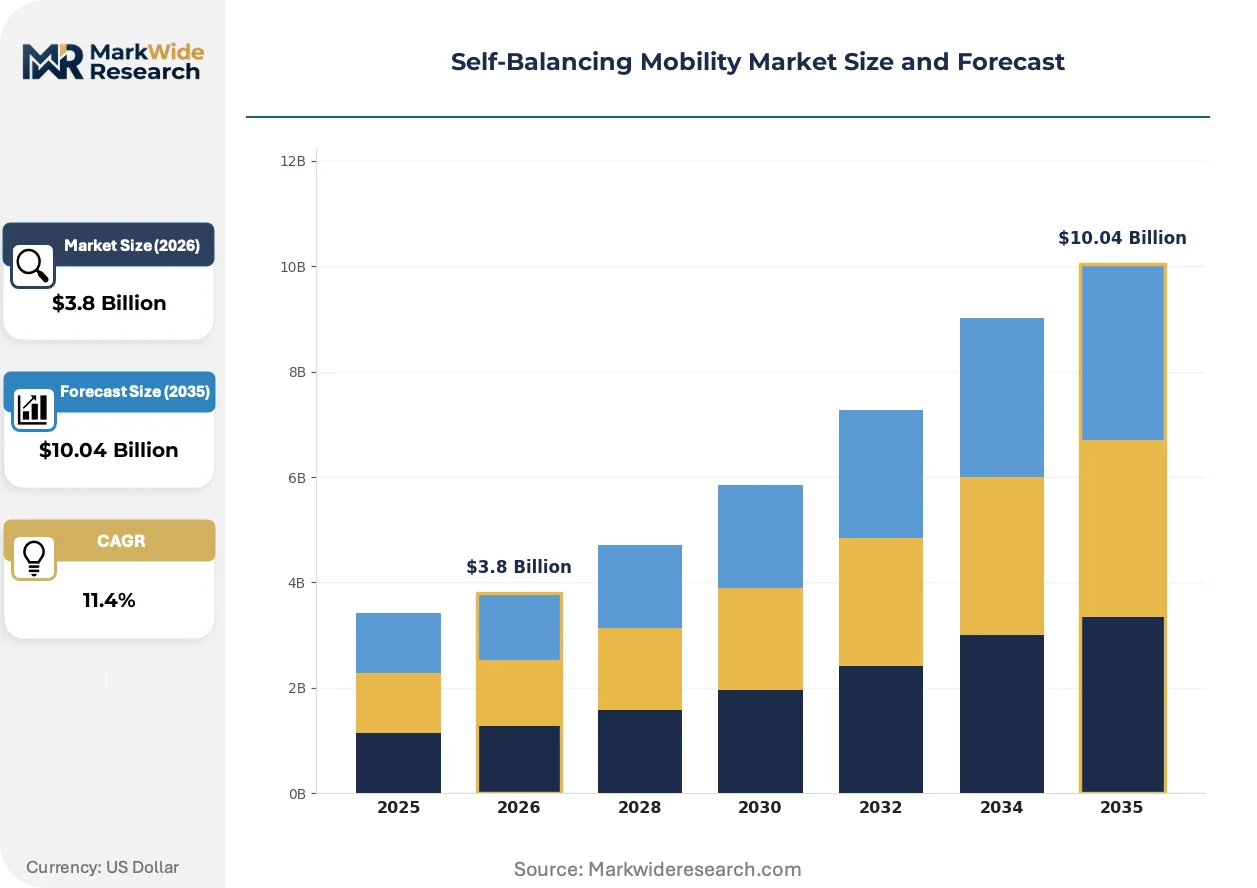
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Scooters, Hoverboards, Unicycles, Segways End User: Consumers, Businesses, Educational Institutions, Rental Services Technology: Gyroscopic, Sensor-Based, App-Enabled, Autonomous Application: Personal Transportation, Last-Mile Delivery, Recreation, Tourism |
| Companies Covered | Segway-Ninebot, Airwheel, INMOTION, IPS Electric Unicycle, Hoverzon, Swagtron, Gotway, Halo Rover, Monorover, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Balancing Mobility Market Evolving Landscape
Three forces are restructuring competitive advantage: firmware-hardware integration depth, regulatory compliance velocity, and fleet-scale operational data monetization. Each trend rewards capital commitment and punishes modular assembly strategies.
Solid-state battery cell architectures are decomposing the traditional lithium-ion pack supply chain. Campus logistics operators in California and Singapore are piloting ceramic-electrolyte configurations that eliminate thermal runaway risk. This chemistry shift is decomposing incumbent cell suppliers' volume advantages by enabling localized micro-factory deployment near fleet depots.
CE marking's cybersecurity annex under the EU AI Act is mandating firmware update transparency and breach notification protocols. Hardware vendors must now maintain European-registered security operations centers, adding fixed cost burdens. App-enabled scooter segments are absorbing compliance costs by bundling subscription services that amortize certification overhead across recurring revenue.
Corporate procurement departments are consolidating micromobility vendor relationships from fragmented local suppliers to single-source national contracts. Facility management teams at technology campuses and hospital networks are replacing ad-hoc purchases with multi-year fleet-as-a-service agreements. This concentration is most visible in Germany, where DAX-listed industrial groups are standardizing on two approved suppliers for all European sites.
Self-Balancing Mobility Market Segmentation
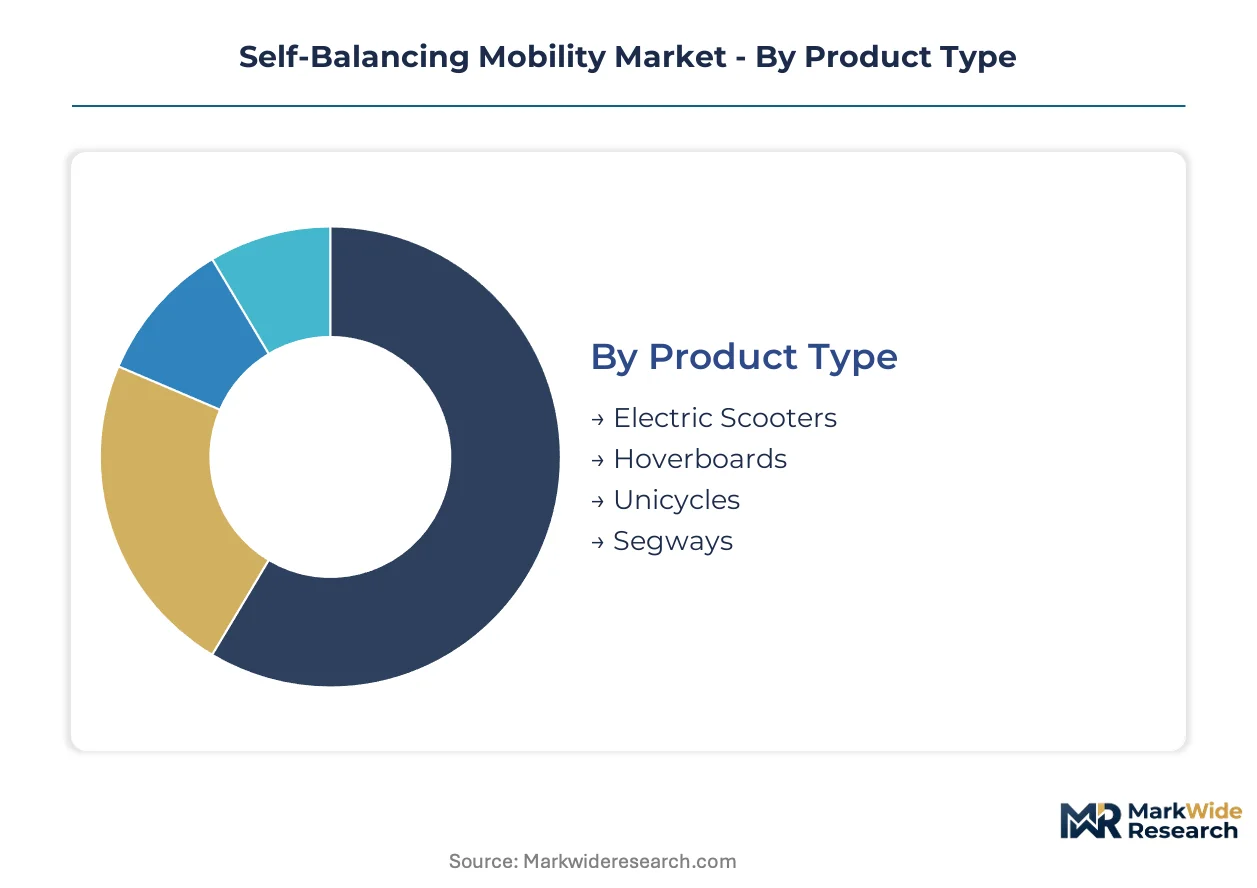
Segmentation in self-balancing mobility reveals divergent margin structures across consumer and commercial deployments. Fleet operators prioritize swappable battery platforms and firmware integration, while recreational buyers respond to design differentiation and price accessibility.
Product Type:
Electric scooters dominate domestic procurement in China and the United States, while hoverboard and unicycle exports concentrate through Shenzhen manufacturing corridors to European distributors.
- Electric Scooters:These devices integrate brushless DC motors with lithium-ion battery packs rated for 25-40 kilometer ranges per charge. Shared micromobility fleet operators in Los Angeles, Berlin, and Shanghai account for bulk procurement volumes, driven by municipal lane infrastructure investments and emissions zone restrictions.
- Hoverboards:Dual-wheel gyroscopic stabilization systems with pressure-sensitive foot pads characterize this segment. Consumer demand clusters in North American and European retail channels during holiday purchasing cycles, constrained by NHTSA and CE marking safety certification timelines that delay new model introductions.
- Unicycles:Single-wheel configurations with high-torque motor windings serve enthusiast riders and niche urban commuters.
- Segways:Two-wheeled platform designs with handlebar steering persist in campus security and guided tourism applications.
Electric scooters hold the largest share; momentum sits with unicycles as torque-density improvements expand their utility range.
End User:
Cost tier stratification separates capital-intensive fleet purchasers from discretionary consumer spending, with rental services occupying a hybrid position requiring operational scale.
- Consumers:Individual purchasers prioritize purchase price and portability specifications over fleet-grade durability. German and French buyers demonstrate willingness to pay premium pricing for CE-certified models with extended warranty coverage.
- Businesses:Corporate campus logistics and security operations demand ruggedized frames and centralized fleet management software. Warehouse operators in California test autonomous pod configurations for indoor material transport.
- Educational Institutions:University procurement departments favor multi-year service contracts with maintenance-inclusive pricing.
- Rental Services:Shared micromobility operators concentrate in urban centers with dedicated parking infrastructure.
Rental services command the highest unit volumes; businesses are expanding most quickly as logistics operators electrify last-mile operations.
Technology:
Application context determines technology selection, with autonomous systems requiring regulatory pre-approval while gyroscopic platforms deploy immediately.
- Gyroscopic:Mechanical stabilization using spinning rotors and angular momentum conservation maintains equilibrium without continuous power draw. Budget-conscious consumer segments in India and Southeast Asia favor these systems for their simplicity and repair accessibility.
- Sensor-Based:Microelectromechanical arrays detect pitch and roll angles for real-time motor adjustment. Industrial facility managers specify these configurations for reliability in temperature-variable environments.
- App-Enabled:Bluetooth-connected firmware allows ride tracking, remote locking, and over-the-air updates.
- Autonomous:Lidar and camera-based navigation enable riderless operation in mapped environments.
Gyroscopic systems retain the largest installed base; autonomous technology shows the steepest expansion trajectory as warehouse operators pilot pod deployments.
Application:
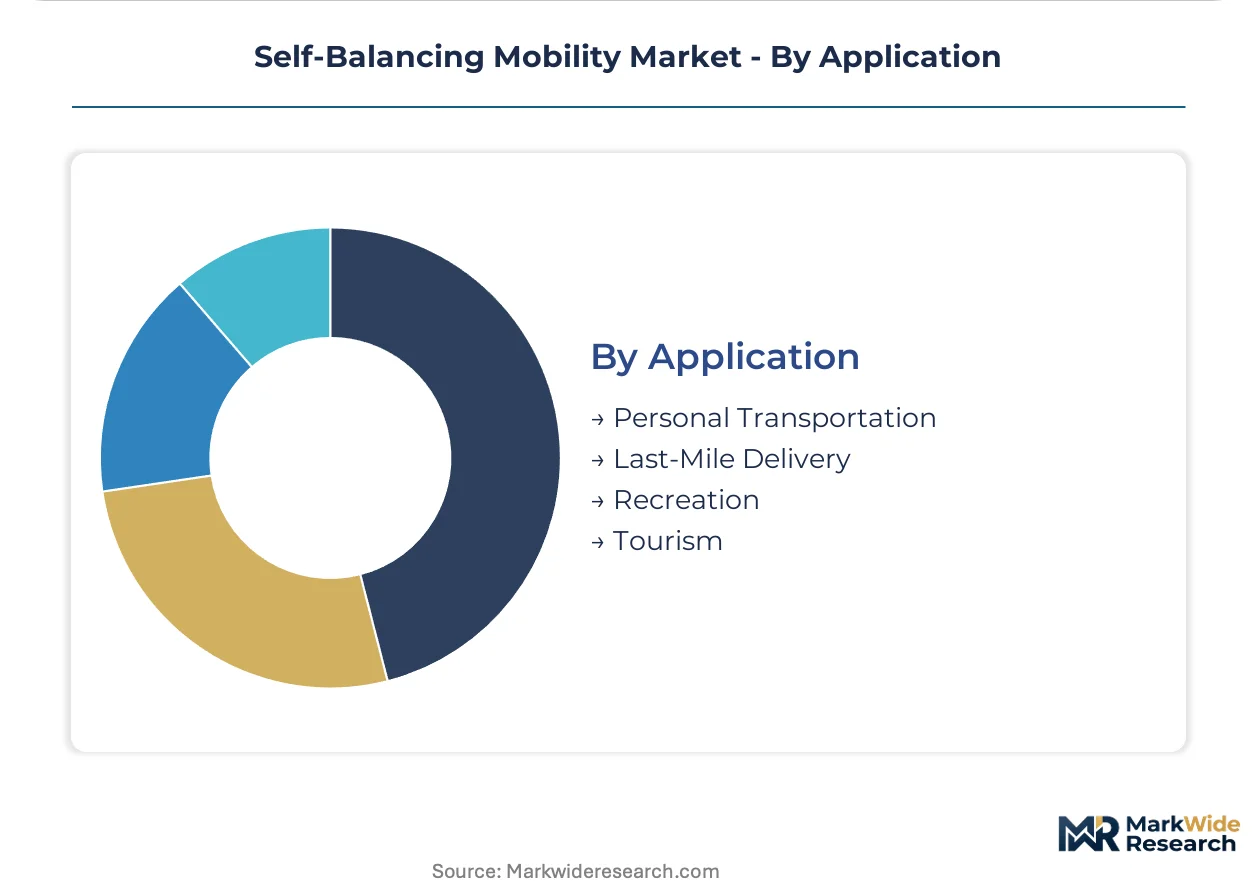
Volume concentration favors personal transportation, though margin profiles improve in commercial logistics where operational cost savings justify premium hardware pricing.
- Personal Transportation:Commuter and recreational riders in congested urban corridors substitute self-balancing devices for public transit connections. Chinese municipal governments in Shenzhen and Chengdu incentivize personal electric mobility through dedicated lane construction.
- Last-Mile Delivery:Logistics operators deploy electric cargo scooters and autonomous pods for final-stage parcel distribution. EU Green Deal emission mandates in Amsterdam and Paris force carrier fleet electrification, eliminating combustion-engine alternatives from city center operations.
- Recreation:Park and trail usage drives seasonal demand patterns in North American and Australian markets.
- Tourism:Guided tour operators in Barcelona, Rome, and Dubai maintain rental fleets for visitor sightseeing circuits.
Personal transportation maintains dominant volume; last-mile delivery gains share fastest as regulatory pressure compounds logistics electrification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA classification rules for street-legal self-balancing vehicles anchor the United States regulatory framework, while municipal permitting regimes in Shenzhen, Berlin, and Los Angeles determine fleet deployment viability. National regulators across five major economies are tightening emissions standards and battery disposal mandates.
United States
Commercial fleet purchasers qualify for Inflation Reduction Act clean vehicle credits when procuring domestically assembled electric mobility devices. NHTSA and EPA frameworks govern vehicle classification, battery disposal, and motor efficiency standards. Los Angeles operators consolidate procurement around standardized battery-swappable platforms.
China
Shenzhen and Shanghai municipal governments fast-track dedicated micromobility lanes and parking infrastructure. MIIT oversees national standards for lithium-ion battery packs and brushless DC motor specifications. Guangdong Province hosts concentrated high-torque motor winding capacity serving global assembler demand.
Germany
DAX-listed industrial groups standardize on approved suppliers for all European sites under multi-year fleet-as-a-service agreements. EU Green Deal emission mandates ban combustion-engine vehicles from city centers, forcing logistics electrification. Berlin fleet operators compress vendor diversity around firmware-integrated hardware suppliers.
France
Paris carriers face forced fleet electrification under EU Green Deal rules eliminating combustion-engine alternatives from city center operations. CE marking and EU AI Act provisions mandate cybersecurity and algorithmic transparency for app-enabled variants. Guided tour operators in Paris maintain rental fleets for visitor sightseeing circuits.
India
Tier-two cities including Pune and Ahmedabad lack micromobility infrastructure, presenting first-mover advantages for rental services willing to pre-position charging networks. BIS certification requirements shape product entry timelines. Budget-conscious consumer segments favor gyroscopic stabilization systems for repair accessibility.
Self-Balancing Mobility Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with firmware-hardware integration depth separating premium positioning from modular assembly strategies. Consolidation pressure compresses vendor diversity as fleet operators standardize procurement. Two strategic archetypes dominate: Asia-Pacific manufacturing-integrated developers with captive engineering bases, and European-certified distributors anchoring service networks. Competitive moves center on backward integration into motor winding capacity and geographic expansion through certified service partnerships.
Within the integrated manufacturing tier, Segway-Ninebot leverages its Shenzhen-based engineering base for sustained development, while INMOTION anchors European distribution positioning. Gotway occupies a specialist position in high-torque unicycle segments where technical capability creates defensible gaps.
| Leading Market Players |
|---|
| Segway-Ninebot |
| Airwheel |
| INMOTION |
| IPS Electric Unicycle |
| Hoverzon |
| Swagtron |
| Gotway |
| Halo Rover |
| Monorover |
| Others |
Value Network & Pricing Analysis
Twelve-month fleet supply contracts lock in battery pack pricing for rental operators while exposing manufacturers to cobalt and lithium carbonate volatility. This structure secures volume commitments from Shenzhen and Los Angeles fleet consolidators yet compresses margin visibility when raw material swings exceed hedging thresholds.
Pricing Analysis
Price spreads between CE-certified European models and unbranded Southeast Asian alternatives span three-to-one ratios. Three-tier pricing structure across premium, standard, and economy levels separates firmware-integrated hardware with over-the-air capability from basic gyroscopic units. Cost compression in the economy tier is intensifying because cobalt price volatility erodes assembler margins on fixed-contract deliveries. Rental services exhibit highest price sensitivity due to fleet-scale procurement leverage, while corporate campus buyers prioritize durability specifications over unit cost.
Supply Chain Analysis
Strategic stockpiling of lithium-silicon anode cells is displacing just-in-time preferences as fleet operators secure chemistry transitions ahead of solid-state disruption. High-torque motor winding capacity clusters in Guangdong Province, South Korea, and Japan, while lithium carbonate processing draws from Chile and Australia. Single-source vulnerability in Guangdong motor supply threatens European and North American assemblers during trade friction episodes. Distribution runs through certified service networks in Europe and direct OEM relationships in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from autonomous delivery pods and compact electric cargo bikes that threaten self-balancing devices in last-mile logistics.
For Market Incumbents: Consolidate procurement relationships with fleet operators around battery-swappable platform standardization to lock out modular competitors. Deepen backward integration into motor winding capacity within Guangdong Province to reduce single-source exposure. Prioritize firmware-hardware integration investments that create switching costs against emerging autonomous pod alternatives.
For New Entrants and Emerging Players: Anchor in tier-two Indian cities including Pune and Ahmedabad where charging infrastructure gaps deter established rental services. Target campus logistics operators testing riderless configurations with software licensing rather than hardware sales. Pursue BIS certification early to compress entry timelines against delayed competitors.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated manufacturers with captive engineering bases over modular assemblers. Long-term viability hinges on control over sensor fusion IP and firmware update infrastructure. Watch for EU AI Act certification timeline compression as an inflection signal for compliance-capable targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Segway-Ninebot and INMOTION consolidate fleet procurement through swappable cell architectures. |
| Backward Integration into Motor Winding | Gotway secures high-torque unicycle capability gaps through Guangdong manufacturing control. |
| EU AI Act Compliance Investment | Hardware vendors establish European security operations centers to meet CE marking cybersecurity annex. |
| Autonomous Campus Navigation Licensing | Software revenue streams emerge beyond hardware sales through riderless pod pilot programs. |
| India Charging Network Pre-positioning | First-mover rental services capture tier-two city markets ahead of infrastructure buildout. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Fleet procurement directors at Los Angeles and Berlin rental operators, Shenzhen manufacturing engineers, and European certified service network managers provided operational perspective. Secondary sources include NHTSA vehicle classification rulings, EU AI Act implementation guidance, MIIT battery standards documentation, and customs trade data for lithium-ion cell movements. Bottom-up fleet deployment counts triangulate against top-down manufacturer shipment estimates.
Sensitivity analysis around lithium carbonate price scenarios and EU certification timeline variations shapes the projection framework. Segmentation dimensions span product type, end user archetype, stabilization technology, and application context across the modeling period. CAGRs derive from volume-weighted average growth trajectories within each segment. Forecast inputs incorporate municipal lane infrastructure investment schedules and Inflation Reduction Act clean vehicle credit qualification thresholds.
Underlying assumptions cover sustained EU Green Deal enforcement and China micromobility lane expansion, with deviation risk concentrated in battery chemistry transition timing and trade policy friction. Revision becomes warranted when solid-state battery commercialization accelerates or when autonomous pod regulatory approval compresses self-balancing device addressable markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Intelligent Vehicle Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
Driverless Taxi Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Unmanned Traffic Management Market
Autonomous Vehicles
Automotive Autonomous Shuttle Market
Autonomous Vehicles
Driverless Cab Service Market
Autonomous Vehicles
Middle East and Africa Automated Guided Vehicles Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Global Autonomous Trucks Market
Autonomous Vehicles
France Autonomous Navigation Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Autonomous Vehicle Management Services Market