
 Middle East and Africa Electric Vehicle Thermal Management System Market | 2026-2036
Middle East and Africa Electric Vehicle Thermal Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Electric Vehicle Thermal Management System Market Foresight
Multi-zone refrigerant architectures with integrated heat pumps is rewriting thermal system design for electric vehicles operating in ambient temperatures exceeding 50°C. MAHLE GmbH leverages its Stuttgart-developed compressor platforms to anchor premium OEM contracts across the Gulf Cooperation Council states. Valeo competes through localized manufacturing partnerships that sustain cost advantages in North African assembly corridors. Robert Bosch GmbH extends its sensor-integrated control modules to dominate cabin-and-battery coordinated thermal loops.
An electric vehicle thermal management system comprises active and passive assemblies that regulate battery cell temperatures, power electronics heat rejection, and passenger cabin climate through liquid coolant circuits, refrigerant cycles, and phase change material buffers; these systems maintain lithium-ion cells within 15-35°C operational bands to prevent thermal runaway and preserve cycle life in high-ambient conditions. Active Systems occupy the dominant value share due to compressor-driven refrigeration complexity and replacement part premiums, while Phase Change Materials represent the fastest-growing technology segment as OEMs seek passive stabilization for parking-soak scenarios in sun-exposed Middle Eastern environments. Fleet Operations within the Use Case dimension concentrate margin pools where total-cost-of-ownership contracts bundle thermal hardware with predictive maintenance software.
South Africa's National Regulator for Compulsory Specifications enforces battery safety standards that shape product certification requirements for thermal containment systems, while Saudi Standards, Metrology and Quality Organization alignment with UN ECE R100 derivatives governs electric vehicle type approval across Gulf markets. The EU AI Act's extraterritorial influence on connected thermal diagnostics creates compliance complexity for Tier-1 Suppliers exporting into North African assembly plants serving European OEMs. Stakeholders must monitor which regulatory jurisdiction—Saudi, South African, or emerging Emirati federal rules—sets the de facto harmonization baseline for cross-border component trade.
Market Dynamics
Multi-zone refrigerant architectures with integrated heat pumps are compressing thermal system design cycles across Middle Eastern and African markets, forcing suppliers to reconfigure compressor platforms for ambient operating thresholds exceeding 50°C.
Growth Catalysts
- Saudi Arabia's Giga-Project Pipeline:NEOM and Red Sea developments are concentrating demand for high-performance battery cooling systems engineered for extreme desert thermal loads.
- South Africa's Carbon Tax Adjustments:Fleet operators are expanding electric bus procurement under stricter public transport emissions benchmarks that mandate thermal containment compliance.
- Phase Change Material Integration:OEMs are adopting passive stabilization buffers for parking-soak scenarios in sun-exposed Gulf Cooperation Council environments.
Market Restraints
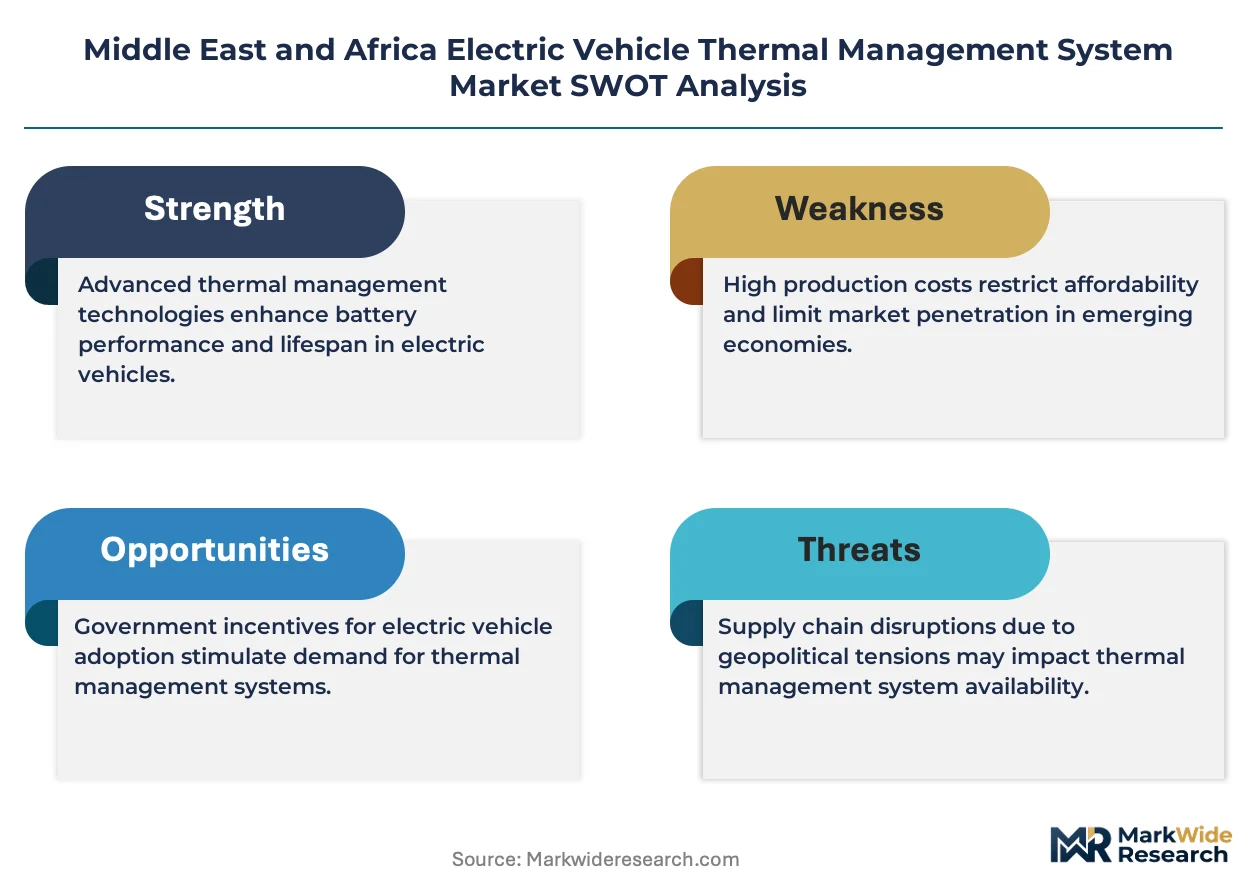
- Refrigerant Cost Volatility:Synthetic coolant prices fluctuate with European F-Gas Regulation quota allocations, squeezing margin on compressor-driven active systems.
- Supply Concentration Risk:Stuttgart-developed compressor platforms dominate premium OEM contracts, creating dependency on German engineering corridors for Gulf thermal hardware.
- Technical Limitation:Lithium-ion cell operational bands of 15-35°C narrow design tolerances for thermal runaway prevention in ambient conditions exceeding 50°C.
Strategic Opportunities
- Emirati Federal Rule Harmonization:Emerging UAE federal standards may establish de facto cross-border component trade baselines for North African assembly corridors.
- Connected Thermal Diagnostics:The EU AI Act's extraterritorial influence creates compliance complexity that local software-integrated hardware bundles can exploit.
- Heat Pump Convergence:Integration of cabin-and-battery coordinated thermal loops with sensor-integrated control modules opens predictive maintenance revenue streams.
Industry Challenges
- Certification Timeline Compression:Saudi Standards, Metrology and Quality Organization alignment with UN ECE R100 derivatives extends type approval cycles for thermal containment systems.
- Talent Scarcity in Predictive Thermal Modeling:Battery safety standards enforcement by South Africa's National Regulator for Compulsory Specifications demands specialized simulation expertise that regional labor pools lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Electric Vehicle Thermal Management System Market |
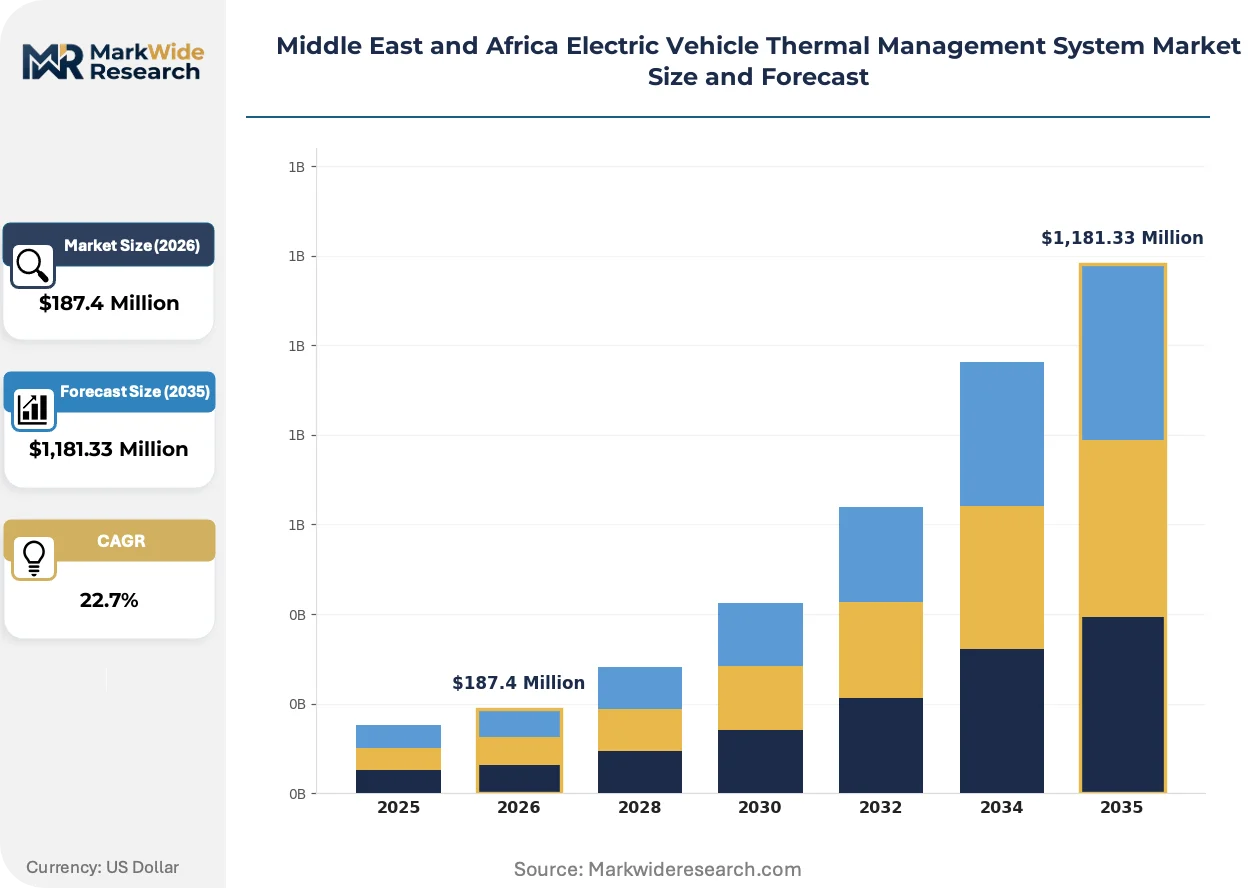
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Systems, Passive Systems, Thermal Battery Systems, Heat Exchangers Use Case: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Fleet Operations Technology: Refrigeration Cycle, Liquid Cooling, Air Cooling, Phase Change Materials End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Research Institutions |
| Companies Covered | MAHLE GmbH, Valeo, Modine Manufacturing Company, Continental AG, BorgWarner Inc., Denso Corporation, Robert Bosch GmbH, Gentherm, Hanon Systems, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Electric Vehicle Thermal Management System Market Shifts & Advancements
Thermal management architectures are fragmenting across active-passive hybrid designs as OEMs balance refrigeration complexity against parking-soak stabilization needs in extreme climates.
Refrigerant-based active cooling is migrating from single-zone compressor systems toward multi-circuit heat pump configurations. Saudi giga-project developers are specifying these platforms for desert construction fleets. The shift is compressing supplier development cycles and elevating Stuttgart-engineered compressor specifications as baseline requirements.
South Africa's National Regulator for Compulsory Specifications is tightening battery safety standards that reshape thermal containment certification. Industrial consequence includes mandatory thermal runaway propagation testing for all lithium-ion pack imports. North African assembly plants serving European OEMs face dual compliance burdens from EU AI Act diagnostic requirements and local containment rules.
Fleet procurement is consolidating around total-cost-of-ownership contracts that bundle thermal hardware with predictive maintenance software. Public transport operators in Johannesburg and Cape Town are displacing spot-component purchasing with lifecycle service agreements. This restructuring concentrates margin pools among suppliers offering integrated sensor-thermal-diagnostic platforms rather than discrete hardware vendors.
Middle East and Africa Electric Vehicle Thermal Management System Market Segmentation
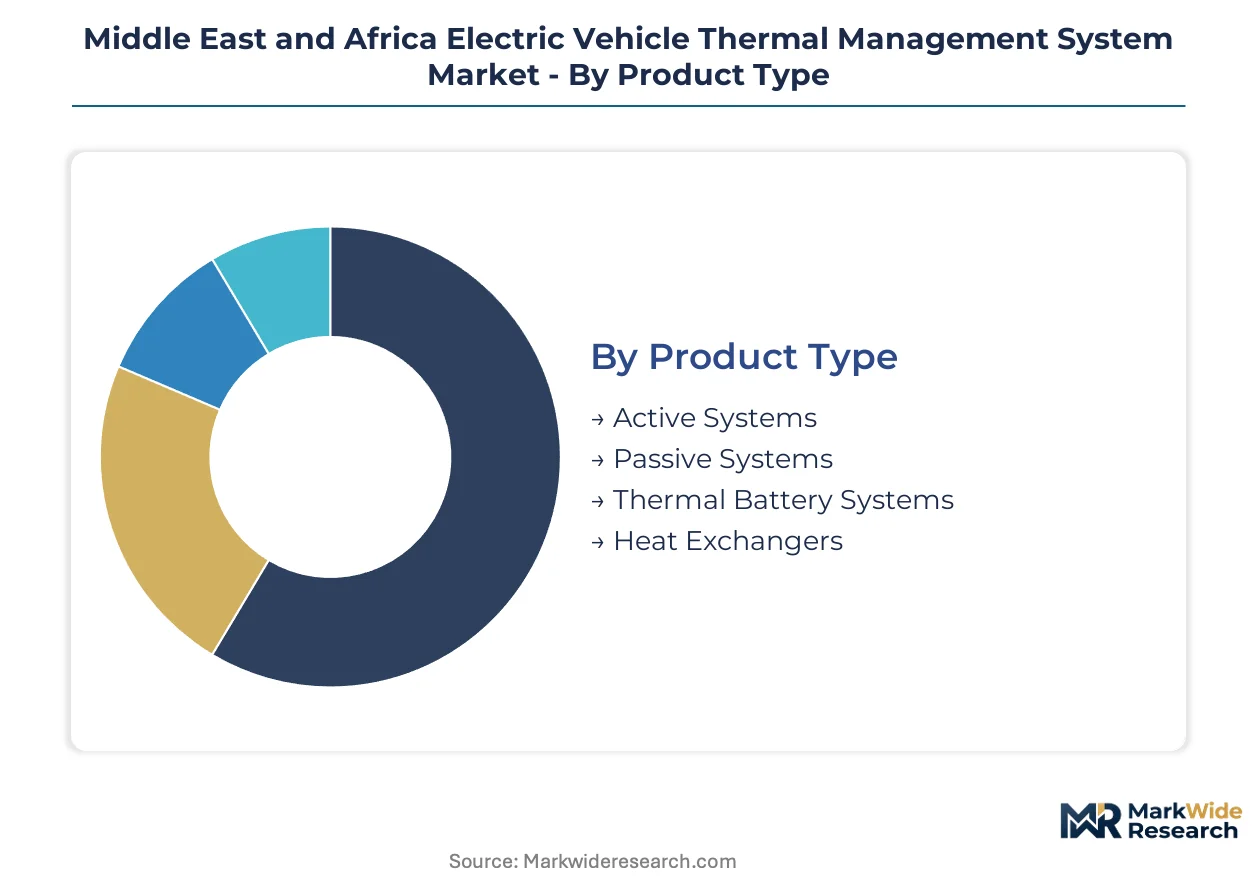
Thermal management architectures fragment across active-passive hybrids as OEMs balance refrigeration complexity against parking-soak stabilization in extreme climates. Segment boundaries blur where fleet contracts bundle hardware with predictive diagnostics, concentrating margin pools among integrated platform suppliers.
Product Type:
Active Systems turn inventory fastest through compressor-driven replacement cycles, while Passive Systems and Heat Exchangers rotate slower on vehicle-life durability.
- Active Systems:Compressor-driven refrigeration circuits with sensor-integrated control modules regulate battery and cabin temperatures through refrigerant cycles. Demand concentrates in Saudi giga-project construction fleets where NEOM and Red Sea developers specify high-performance cooling for desert thermal loads exceeding 50°C ambient.
- Phase Change Materials:Passive stabilization buffers absorb and release thermal energy during parking-soak scenarios without electrical draw. South African fleet operators expanding electric bus procurement under carbon tax adjustments specify these for sun-exposed depot parking.
- Passive Systems:Radiator-based and natural convection assemblies provide baseline heat rejection without powered circulation.
- Thermal Battery Systems:Integrated pack-level containment structures combine structural housing with active coolant distribution manifolds.
- Heat Exchangers:Plate-and-frame or tube-fin assemblies transfer thermal energy between coolant loops and ambient air or refrigerant circuits.
Active Systems dominate installed base through replacement part premiums. Phase Change Materials are where expansion concentrates for parking-soak thermal protection.
Use Case:
Passenger Vehicles and Two-Wheelers generate highest unit volumes, while Fleet Operations and Commercial Vehicles concentrate margin through total-cost-of-ownership contracting.
- Fleet Operations:Public transport and logistics operators procure thermal hardware bundled with predictive maintenance software under lifecycle service agreements. Johannesburg and Cape Town municipal operators displace spot-component purchasing with sensor-thermal-diagnostic platforms.
- Commercial Vehicles:Electric buses and delivery trucks require multi-zone refrigerant architectures with integrated heat pumps for sustained high-load operation. Saudi giga-project developers specify these for construction and logistics fleets operating in extreme desert climates.
- Passenger Vehicles:Private electric cars and SUVs deploy cabin-and-battery coordinated thermal loops through OEM integrated platforms.
- Two-Wheelers:Electric motorcycles and scooters utilize simplified air-cooled or basic liquid-cooled thermal management for compact battery packs.
Fleet Operations capture margin concentration through bundled service contracts. Passenger Vehicles remain the volume anchor across regional assembly corridors.
Technology:
Liquid Cooling and Air Cooling represent mature cost tiers, while Phase Change Materials and advanced Refrigeration Cycle configurations command technology premiums.
- Refrigeration Cycle:Vapor-compression systems using synthetic refrigerants deliver active cooling for battery packs and passenger cabins. Gulf Cooperation Council OEM contracts specify Stuttgart-engineered compressor platforms as baseline requirements for extreme ambient thresholds.
- Phase Change Materials:Paraffin or salt-hydrate compounds provide passive thermal buffering without energy consumption during vehicle shutdown. UAE federal rule harmonization efforts may establish certification baselines for these components across North African assembly plants.
- Liquid Cooling:Ethylene glycol or dielectric fluid circuits circulate through cold plates and jacketed battery modules.
- Air Cooling:Forced convection or natural airflow systems provide baseline thermal management for lower-power applications.
Refrigeration Cycle systems anchor premium OEM specifications. Phase Change Materials are climbing the fastest as passive stabilization demand intensifies.
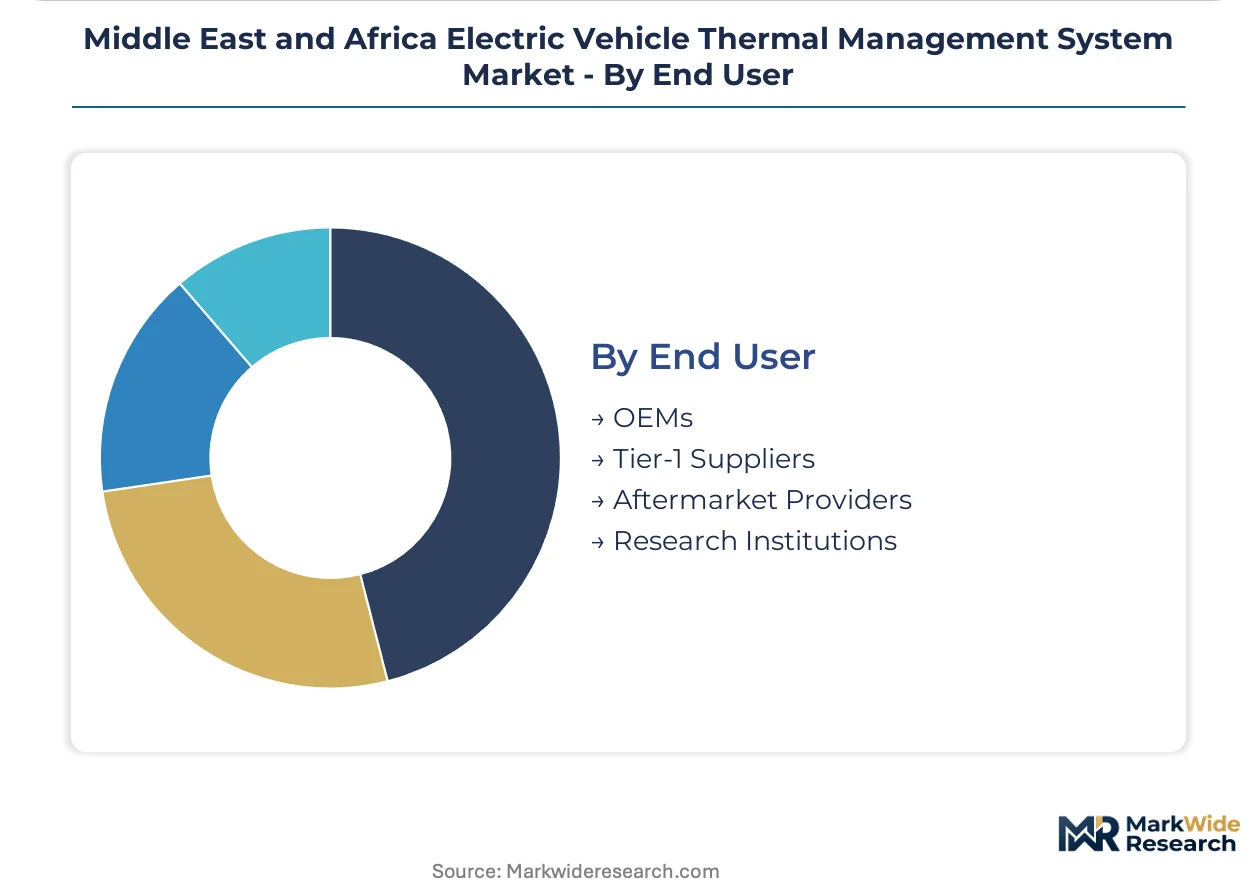
End User:
Tier-1 Suppliers and OEMs drive specification authority, while Aftermarket Providers and Research Institutions occupy adjacent value positions.
- Tier-1 Suppliers:Integrated thermal module manufacturers deliver compressor platforms, heat exchangers, and control systems to vehicle assemblers. EU AI Act extraterritorial compliance requirements on connected thermal diagnostics create complexity that localized software-integrated hardware bundles can exploit.
- OEMs:Vehicle manufacturers specify thermal system architectures and certify compliance with Saudi Standards, Metrology and Quality Organization UN ECE R100 derivatives.
- Aftermarket Providers:Independent service networks supply replacement components and retrofit thermal upgrades for existing electric vehicle fleets.
- Research Institutions:Universities and national laboratories develop advanced materials and simulation capabilities for next-generation thermal management.
Tier-1 Suppliers concentrate design-in authority. OEMs are where platform standardization decisions lock in multi-year procurement commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in thermal management hardware track assembly corridor investments rather than end-market consumption. Component sourcing concentrates in German engineering corridors for compressor platforms, while North African plants serve European OEM re-export demand. Regional regulatory divergence complicates cross-border certification timelines.
Saudi Arabia
NEOM and Red Sea giga-projects concentrate demand for high-performance battery cooling systems engineered to desert thermal loads exceeding 50°C ambient. Saudi Standards, Metrology and Quality Organization alignment with UN ECE R100 derivatives governs electric vehicle type approval for thermal containment systems. Riyadh and the Eastern Province anchor construction fleet procurement corridors where multi-zone refrigerant architectures dominate specifications.
United Arab Emirates
Dubai and Abu Dhabi municipal fleets are expanding electric bus procurement under federal emissions reduction mandates that elevate thermal hardware requirements. Emerging UAE federal standards may establish de facto harmonization baselines for cross-border component trade across Gulf Cooperation Council states. Jebel Ali industrial zones host assembly plants serving regional re-export markets for European OEM supply chains.
South Africa
Carbon tax adjustments and stricter public transport emissions benchmarks are accelerating electric bus fleet procurement by Johannesburg and Cape Town municipal operators. The National Regulator for Compulsory Specifications enforces battery safety standards that mandate thermal runaway propagation testing for lithium-ion pack imports. Gauteng and Western Cape provinces concentrate fleet operations where total-cost-of-ownership contracts bundle thermal hardware with predictive maintenance software.
Egypt
Public transport electrification programs in Cairo and Alexandria are generating procurement demand for thermal management systems in electric bus deployments. The country's national automotive regulator is developing type approval frameworks aligned with UN ECE regulatory derivatives for electric vehicle safety systems. Suez Canal Economic Zone industrial clusters are attracting component assembly investments serving North African and Levantine markets.
Morocco
Automotive export platforms in Tangier and Casablanca are integrating thermal system production for European OEM supply chains serving Mediterranean markets. Alignment with EU regulatory frameworks including the AI Act's extraterritorial diagnostic requirements creates compliance complexity for connected thermal hardware exports. Northern industrial corridors concentrate Tier-1 supplier manufacturing serving French and Spanish automotive assemblers.
Middle East and Africa Electric Vehicle Thermal Management System Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers anchored by German engineering houses, diversified automotive suppliers, and specialized thermal component fabricators. Stuttgart-developed compressor platforms dominate premium OEM specifications for extreme ambient thresholds, while localized manufacturing partnerships sustain cost positioning in North African assembly corridors. Strategic archetypes include integrated module suppliers delivering sensor-thermal-diagnostic bundles, refrigerant cycle specialists, and passive stabilization material providers. Competitive dynamics center on technology licensing arrangements and geographic expansion through joint ventures with regional automotive assemblers.
Among German-based engineering houses, MAHLE GmbH and Robert Bosch GmbH anchor the premium-tier specification vector for Gulf Cooperation Council OEM contracts. Valeo represents the diversified automotive supplier archetype competing through manufacturing partnerships that sustain cost advantages across North African corridors. These three companies exemplify the strategic positioning required to serve divergent regulatory and thermal load requirements across Middle Eastern and African markets.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Valeo |
| Modine Manufacturing Company |
| Continental AG |
| BorgWarner Inc. |
| Denso Corporation |
| Robert Bosch GmbH |
| Gentherm |
| Hanon Systems |
| Others |
Supply & Pricing Matrix
Jebel Ali freight corridors connecting German engineering centers to Gulf Cooperation Council assembly plants transmit compressor platform premiums into regional thermal hardware pricing, while South African carbon tax enforcement concentrates buyer leverage among municipal fleet operators seeking lifecycle cost compression.
Pricing Analysis
Current-generation multi-zone refrigerant architectures with integrated heat pumps command technology premiums against prior-generation single-circuit compressor systems, while next-generation solid-state thermal buffers remain pre-commercial. Three-tier pricing structure across premium Stuttgart-engineered platforms, mid-tier localized manufacturing partnerships, and economy passive stabilization materials dominates procurement. Price differentiation stems from UN ECE R100 certification grade and volume scale in fleet operations. Pricing pressure stems from European F-Gas Regulation quota volatility squeezing synthetic refrigerant margins. Fleet operators exhibit highest price sensitivity through total-cost-of-ownership contracting, while Saudi giga-project developers demonstrate lowest sensitivity for extreme-ambient performance specifications.
Supply Chain Analysis
Tariff exposure between Germany and Gulf Cooperation Council states dominates supply chain risk assessment for compressor platform imports. Geographic supply concentration centers on Germany for engineered compressor systems, Morocco and Tunisia for North African assembly corridor manufacturing, and South Korea for battery thermal interface materials. Raw material dependencies include synthetic refrigerants, aluminum cold plate extrusions, and paraffin-based phase change compounds. Single-source vulnerability persists for Stuttgart-developed compressor specifications anchoring premium OEM contracts. Distribution runs through Tier-1 supplier direct OEM relationships, with aftermarket channels serving replacement cycles in Johannesburg and Riyadh fleet depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation around lifecycle service agreements has shifted buyer power toward Johannesburg and Cape Town municipal operators, fragmenting spot-component vendor relationships into bundled platform selections.
For Market Incumbents: Entrench position through backward integration into phase change material production for parking-soak thermal buffering, and anchor capacity expansion in Jebel Ali industrial zones to capture UAE federal rule harmonization benefits. Refrigerant cost volatility from European F-Gas Regulation quotas threatens margin stability; certification investment in Saudi Standards, Metrology and Quality Organization alignment defends specification authority against emerging local competitors. For New Entrants and Emerging Players: Egyptian electric bus procurement under Cairo and Alexandria public transport electrification programs offers the most penetrable white-space target, with Suez Canal Economic Zone assembly investments creating localized manufacturing footholds. North African corridor serving European OEM re-export demand presents second-tier opportunity through EU AI Act compliance software bundles. Go-to-market angle should emphasize predictive thermal diagnostics integration for fleet operators displacing discrete hardware purchasing. For Investors and Strategic Acquirers: Sensor-integrated control module specialists with predictive maintenance software capabilities represent the priority acquisition archetype for platform consolidation plays. Long-term viability frames around heat pump convergence and connected thermal diagnostics revenue streams replacing pure hardware margins. Signal to watch is Emirati federal rule harmonization establishing cross-border certification baselines that would accelerate North African assembly corridor scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Platform Integration | Multi-zone refrigerant architectures compress development cycles for NEOM desert specifications. |
| Phase Change Material Manufacturing Scale-Up | Paraffin-buffer production capacity captures parking-soak demand in Gulf Cooperation Council depot environments. |
| Predictive Diagnostics Software Development | Sensor-thermal bundles exploit EU AI Act compliance complexity in North African export corridors. |
| Localized Assembly Joint Venture | Jebel Ali manufacturing partnerships sustain cost positioning against Stuttgart-engineered premium imports. |
| UN ECE R100 Certification Investment | Saudi Standards, Metrology and Quality Organization alignment accelerates type approval timelines for thermal containment systems. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement directors, fleet operations managers in Johannesburg and Cape Town, and thermal systems R&D leads converged on the working assumptions shaping this analysis. Primary interview intelligence combined with secondary validation from vehicle production databases, customs and trade flow records, IHS Markit registration data, and Saudi Standards, Metrology and Quality Organization regulatory filings. Bottom-up segment sizing triangulated against top-down market construction across product type, use case, technology, and end user dimensions.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across active and passive system architectures, fleet versus passenger vehicle use cases, refrigeration cycle and phase change material technologies, and Tier-1 supplier versus OEM end user categories. CAGRs derived from fitted growth curves reflecting technology adoption patterns and regulatory enforcement timelines. Industry-specific forecast inputs included Saudi giga-project procurement pipelines and South African carbon tax adjustment implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese compressor platform entrants or accelerated Emirati federal harmonization would shift outcomes. Material shifts in European F-Gas Regulation quota allocations or UN ECE R100 derivative adoption timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Electric Cars Market
Electric Vehicles
Luxembourg E-Bike Market
Electric Vehicles
France E-Bike Market
Electric Vehicles
Electric Delivery Vans Market
Electric Vehicles
E-Bike Battery Market
Electric Vehicles
Wireless Electric Vehicle Charging Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
New Energy Vehicle (NEV) Taxi Market
Electric Vehicles
Electric Vehicle Helmet Market
Electric Vehicles
Latin America E-Bike Market
Electric Vehicles
Russia Electric Cars Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
Electric Vehicle Liquid-Cooled Charging Connector Market
Electric Vehicles
Oman EV Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market