
 Africa Electric Scooter Market | 2026-2036
Africa Electric Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Electric Scooter Market Intelligence
Modular battery subscription programs are realigning how fleet buyers evaluate total cost of ownership across the Africa Electric Scooter Market. Yadea Technology Group Co., Ltd. leverages its integrated battery manufacturing to anchor pricing power in East African markets. Vmoto Limited specializes in sit-down configurations designed for commercial delivery routes. Honda Motor Co Ltd competes through its established dealer network presence in Southern Africa.
An electric scooter is a battery-powered two-wheeler with an electric motor rated typically between 250W and 4000W, using lithium-ion or lead-acid battery packs to achieve ranges of 40–100 km per charge, designed primarily for short-distance urban mobility and commercial last-mile logistics. Sit-down scooters command the deepest margin pools because commercial delivery services prioritize payload capacity and rider comfort over acquisition cost. Stand-up scooters dominate unit volume among commuters in dense African cities where parking scarcity favors compact form factors. Folding scooters remain a niche segment but attract tourist rental operators in coastal hubs like Cape Town and Mombasa.
South Africa's National Regulator for Compulsory Specifications enforces battery safety standards that filter out uncertified imports, while Kenya's Energy and Petroleum Regulatory Authority shapes demand through commercial EV tariff structures. Egypt's General Authority for Investment governs local assembly incentives that determine which manufacturers establish production rather than pure import channels. Stakeholders must track how each national regulator calibrates import duties against local content requirements.
Market Dynamics
Modular battery subscription models are compressing fleet total cost of ownership calculations across African commercial operators, forcing incumbent manufacturers to restructure pricing architectures around energy-as-a-service rather than hardware margins.
Growth Catalysts
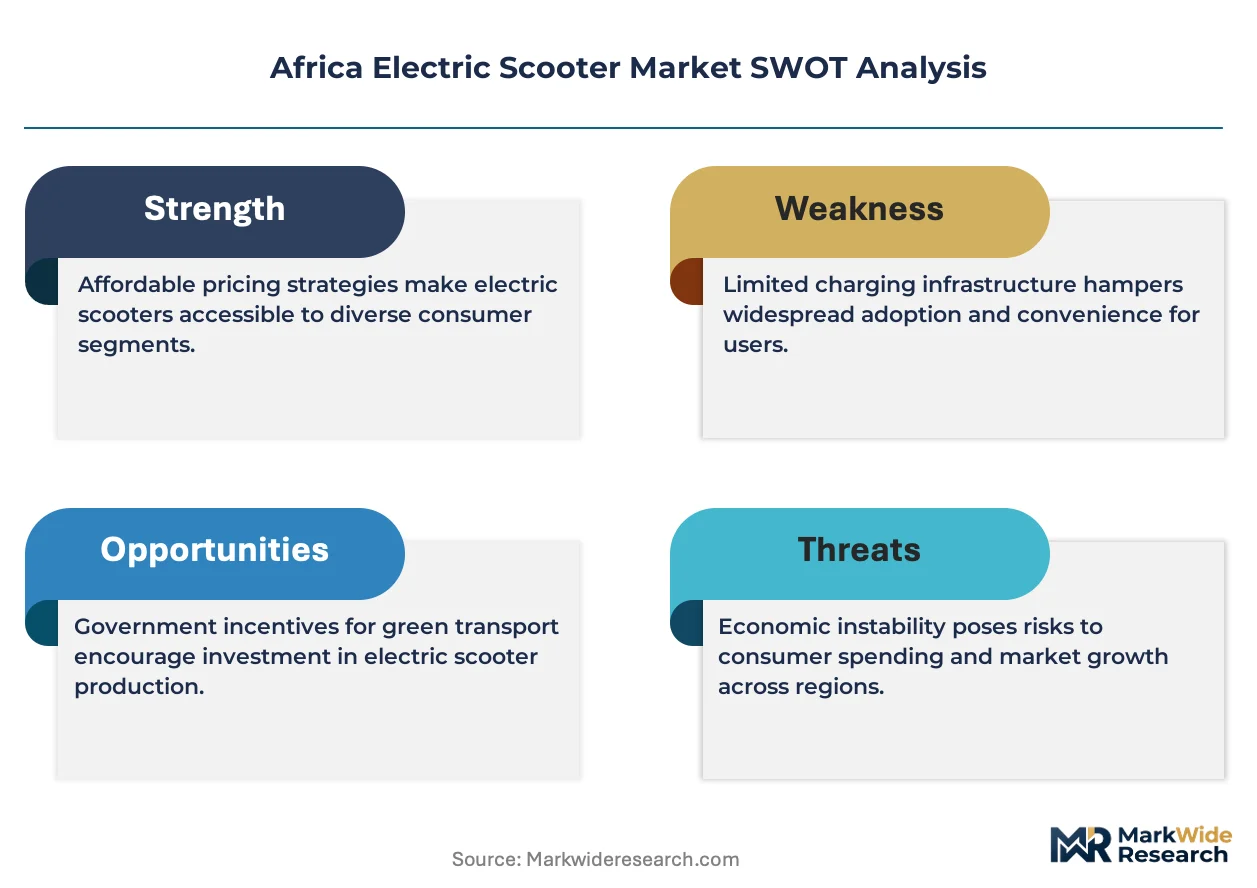
- Kenya's off-peak commercial EV tariffs:The Energy and Petroleum Regulatory Authority's approved rate structures slash charging costs for delivery fleets operating overnight, accelerating payback periods for electric two-wheeler conversions in Nairobi's logistics corridors.
- Last-mile delivery electrification:E-commerce fulfillment networks in Lagos and Nairobi are mandating zero-emission vehicle quotas, creating guaranteed demand pools that de-risk fleet procurement decisions for commercial buyers.
- Lithium-ion cost curves:Cell price declines are narrowing the upfront cost gap against petrol scooters, enabling pay-per-km battery leasing models that eliminate capital barriers for informal sector riders.
Market Restraints
- Import duty volatility:Egypt's General Authority for Investment calibrates local assembly incentives against pure import channels, creating policy uncertainty that freezes manufacturer localization commitments.
- Charging infrastructure gaps:Grid reliability constraints in secondary cities limit route expansion beyond Johannesburg, Cairo, and Nairobi metropolitan cores.
- Lead-acid battery persistence:Price-sensitive informal operators in peri-urban zones continue selecting heavier, shorter-life chemistries that undermine total cost of ownership advantages of lithium platforms.
Strategic Opportunities
- Rwanda's motorbike taxi electrification mandate:Kigali's phased combustion ban for commercial two-wheelers creates a captive replacement market with standardized vehicle specifications.
- Solar-integrated charging stations:Off-grid commercial charging hubs combining photovoltaic generation with battery storage address grid instability in Nigerian and Kenyan secondary cities.
- Tourism rental channel development:Coastal hospitality operators in Cape Town and Mombasa are piloting premium folding scooter fleets for visitor mobility, opening B2B2C revenue streams distinct from commuter sales.
Industry Challenges
- Technician certification gaps:High-voltage battery servicing skills remain concentrated in Johannesburg and Cairo, creating maintenance bottlenecks that strand assets in inland markets.
- Homologation timeline compression:South Africa's National Regulator for Compulsory Specifications enforces battery safety testing protocols that add six to nine months to product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Electric Scooter Market |
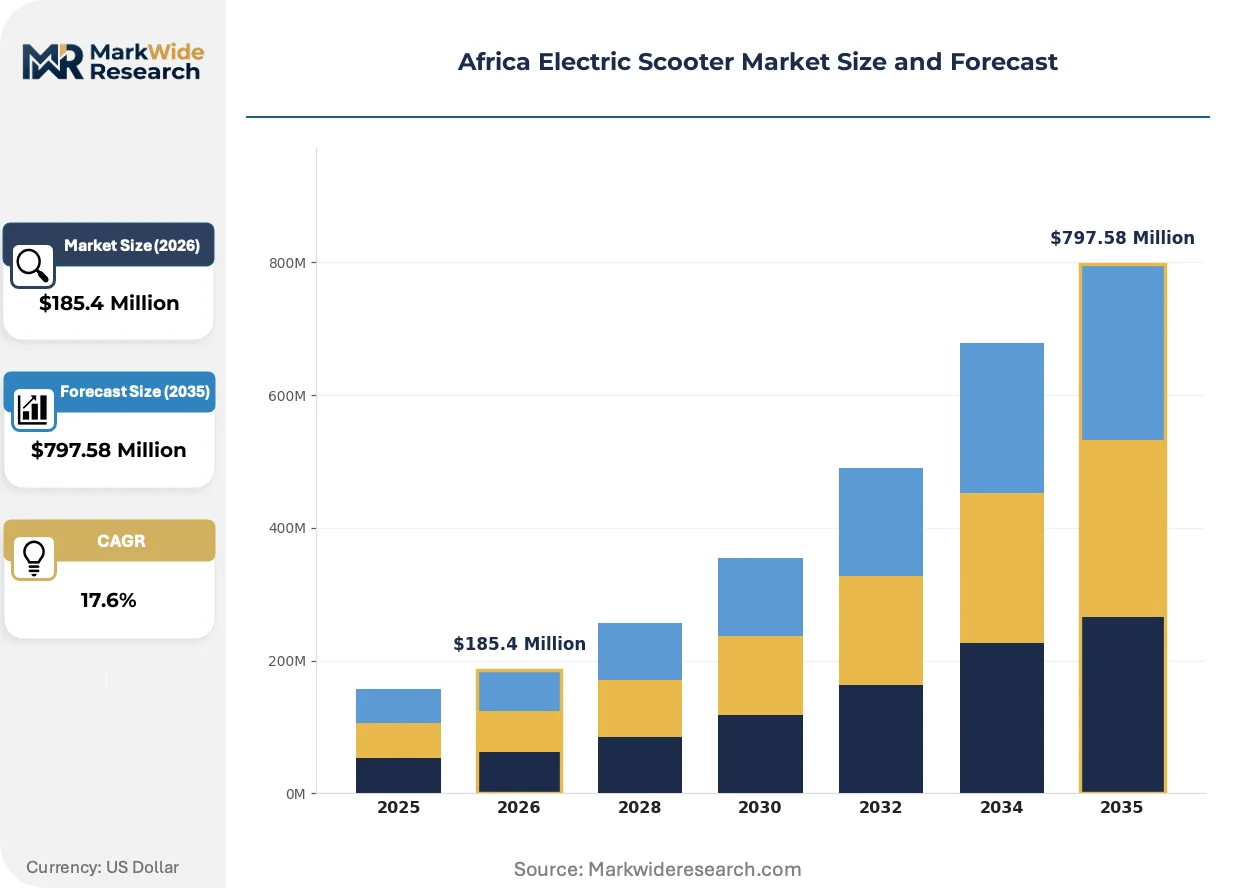
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $797.58 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Scooters, Sit-Down Scooters, Folding Scooters, Off-Road Scooters End User: Commuters, Delivery Services, Tourists, Urban Riders Speed Capacity: 15 km/h, 25 km/h, 40 km/h, 50 km/h Battery Type: Li-ion Batteries, Lead-Acid Batteries, Nickel-Metal Hydride, Others |
| Companies Covered | Ninebot Limited, Suzuki Motor Corporation, Honda Motor Co Ltd, Mahindra GenZe, Terra Motors Corporation, KTM AG, Yamaha Motor Company Limited, Vmoto Limited, Yadea Technology Group Co., Ltd., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Electric Scooter Market Strategic Shifts & Innovations
Swappable battery architectures are fragmenting competitive advantage away from vehicle manufacturing toward energy network control, with commercial fleet operators now evaluating scooter platforms primarily on interoperability with third-party charging infrastructure.
Silicon-anode lithium-ion chemistries are rewriting range expectations for commercial delivery applications. Lagos-based logistics fleets testing next-generation cells report forty percent capacity improvements without pack size increases. This density gain is compressing vehicle weight classes, enabling heavier payload configurations within existing license categories.
Ghana's Energy Commission is drafting two-wheeler import efficiency standards that will phase out sub-85 km range vehicles from Accra metropolitan registration. Manufacturers are pre-emptively redesigning entry-level models to exceed this threshold, diverting engineering resources from premium segments. The compliance push is accelerating local assembly partnerships to circumvent proposed import restrictions on fully-built units.
Commercial buyers are unbundling after-sales service from hardware procurement, negotiating direct maintenance contracts with third-party technicians rather than accepting manufacturer service bundles. This disintermediation is most visible among Nairobi delivery cooperatives, which now source spare parts through independent distributors and train in-house mechanics through vocational partnerships. The shift compresses manufacturer margin pools while fragmenting quality accountability across the vehicle lifecycle.
Africa Electric Scooter Market Segmentation
Commercial fleet operators in Lagos and Nairobi are reclassifying scooter procurement around total cost of ownership rather than sticker price, forcing segmentation logic to track how battery subscription models reshape category boundaries. Delivery cooperatives now evaluate sit-down platforms against stand-up alternatives based on interoperability with third-party charging networks, not manufacturer specifications alone.
Product Type:
Replacement cycles diverge sharply across form factors, with commercial delivery assets turning over every 18-24 months while commuter units persist for 4-6 years.
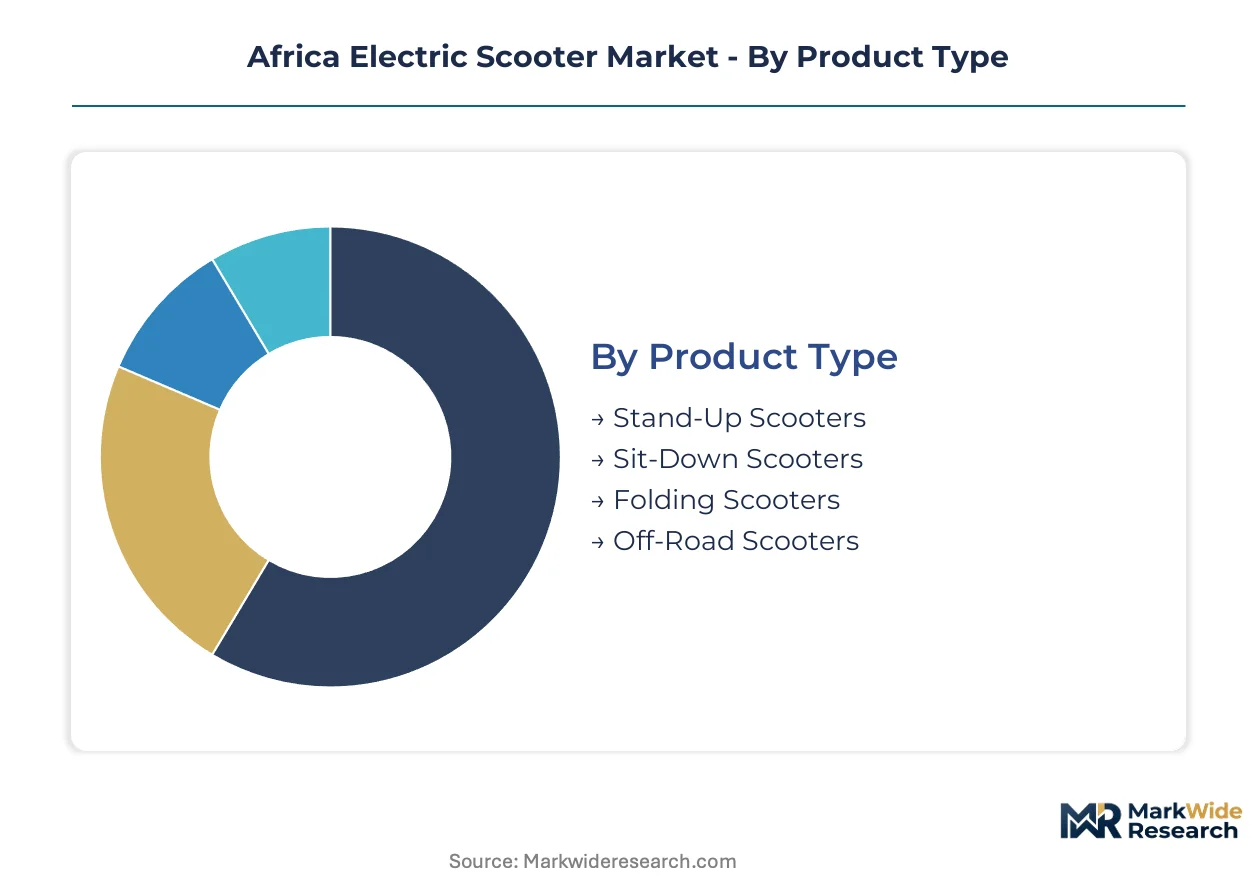
- Sit-Down Scooters:Configured with reinforced frames and extended deck platforms to accommodate 150-200 kg payloads for courier operations. Nairobi's logistics corridors concentrate demand for these units, driven by e-commerce fulfillment networks mandating zero-emission vehicle quotas that de-risk fleet procurement decisions.
- Stand-Up Scooters:Compact footprint designs dominate unit volume among commuters in dense African cities where parking scarcity favors minimal form factors. Lagos and Cairo metropolitan cores drive procurement, with informal sector riders prioritizing maneuverability through congested arterial roads over cargo capacity.
- Folding Scooters:Collapsible frame architectures attract tourist rental operators in Cape Town and Mombasa coastal hospitality markets.
- Off-Road Scooters:Knobby tire and suspension configurations serve peri-urban delivery routes with unpaved surface conditions.
Stand-Up Scooters sits at the top of the volume ranking, with Sit-Down Scooters climbing the fastest.
End User:
Customer economics separate sharply between wage-earning commuters and asset-owning delivery entrepreneurs, with the latter segment capturing disproportionate financing innovation.
- Delivery Services:Fleet-scale operators and independent couriers operating under platform aggregators like Gokada and MAX.ng. Kenya's Energy and Petroleum Regulatory Authority off-peak commercial EV tariffs slash charging costs for overnight operations, accelerating payback periods for electric two-wheeler conversions.
- Commuters:Salaried urban workers traversing 10-25 km daily distances on predictable routes. Johannesburg and Cairo concentrate this demand, with grid reliability in secondary cities limiting addressable market expansion beyond metropolitan cores.
- Tourists:Visitor mobility segments in coastal hospitality zones piloting premium rental fleets.
- Urban Riders:General-purpose personal transportation users spanning recreational and utilitarian trip purposes.
Commuters holds the widest installed base, while Delivery Services gains share fastest through fleet electrification mandates.
Speed Capacity:
License classification thresholds in South Africa and Kenya segment the market into 25 km/h pedestrian-class and 50 km/h motorcycle-class regulatory buckets with distinct compliance burdens.
- 25 km/h:Pedestrian-equivalent speed ratings avoiding motorcycle licensing requirements in most African jurisdictions. Nairobi and Lagos informal sector riders favor this threshold for regulatory simplicity, though route efficiency constraints push commercial operators toward higher-rated alternatives.
- 40 km/h:Intermediate velocity tier balancing urban traffic flow compatibility with reduced licensing friction.
- 50 km/h:Motorcycle-class performance enabling arterial road access and suburban route extension.
- 15 km/h:Restricted speed ratings for pedestrian zone access and tourist rental liability containment.
25 km/h dominates unit shipments by volume, with 50 km/h expanding most quickly as commercial fleets prioritize route coverage over licensing minimization.
Battery Type:
Cell chemistry selection determines residual value and financing accessibility, with lithium platforms enabling battery subscription models unavailable to lead-acid users.
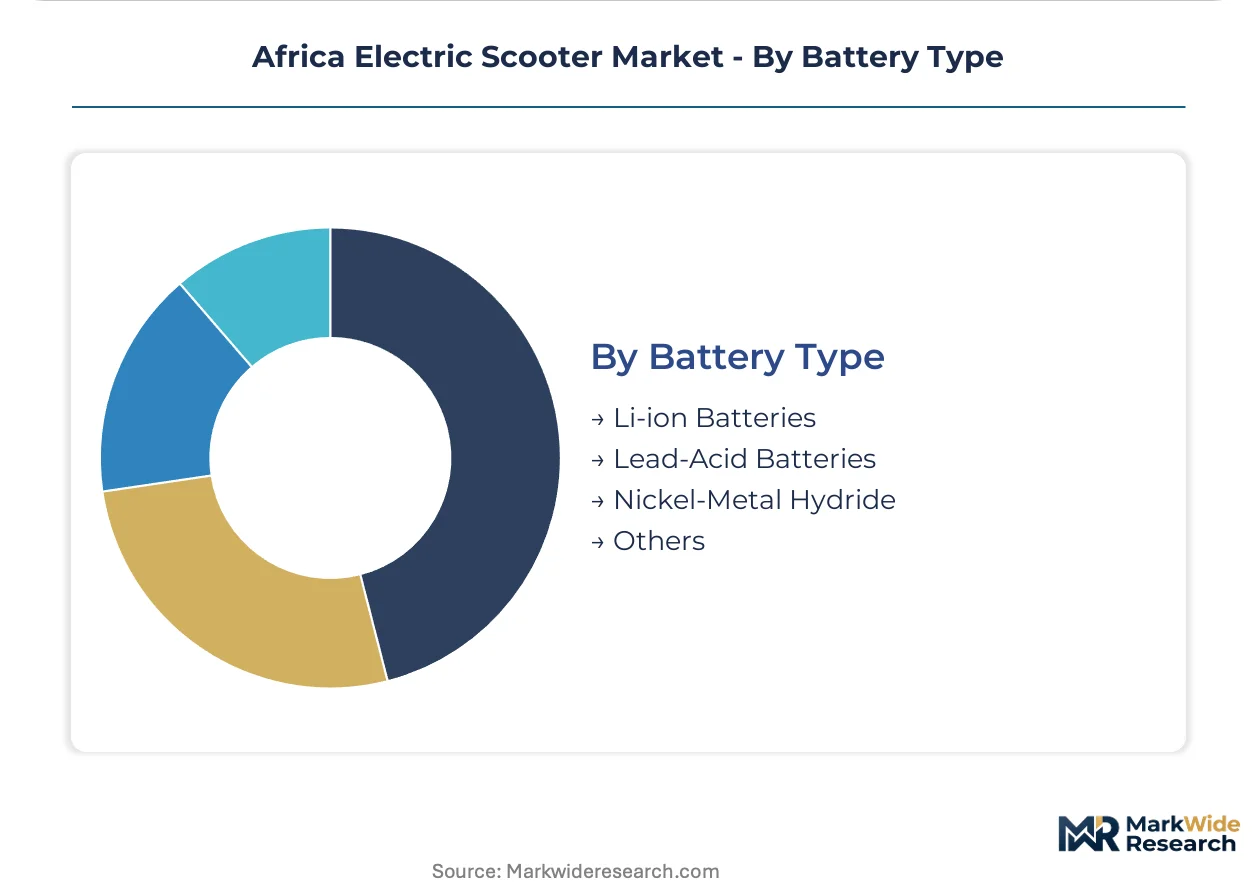
- Li-ion Batteries:Lithium-ion chemistries with silicon-anode variants delivering 40% capacity improvements without pack size increases. Ghana's Energy Commission draft efficiency standards will phase out sub-85 km range vehicles from Accra metropolitan registration, preemptively redirecting manufacturer engineering resources toward lithium platforms.
- Lead-Acid Batteries:Heavier, shorter-life chemistries persisting among price-sensitive informal operators in peri-urban zones. Nigerian and Kenyan secondary cities see continued selection of these units despite total cost of ownership disadvantages, constrained by upfront capital barriers.
- Nickel-Metal Hydride:Transitional chemistry occupying niche cost-performance positioning between lead-acid and lithium alternatives.
- Others:Emerging solid-state and sodium-ion architectures in pre-commercial testing phases.
Li-ion Batteries commands the revenue pool, with Lead-Acid Batteries retaining volume concentration in price-constrained segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric two-wheeler commercialization in Africa traces its operational roots to Nairobi's 2010s boda-boda electrification pilots, which established the fleet-conversion playbook now scaling across Lagos, Cairo, and Kigali logistics corridors.
South Africa
Gauteng province concentrates national demand through Johannesburg's courier networks and Pretoria's municipal procurement programs. The National Regulator for Compulsory Specifications enforces battery safety certification that filters uncertified imports from entry channels. Cape Town's coastal hospitality operators pilot premium folding scooter rental fleets for tourist mobility segments.
Kenya
Nairobi's logistics corridors drive fleet electrification through e-commerce fulfillment mandates and platform aggregator procurement quotas. The Energy and Petroleum Regulatory Authority's off-peak commercial EV tariffs slash overnight charging costs for delivery operators. Mombasa's coastal tourism market attracts folding scooter rental pilots distinct from commuter demand pools.
Egypt
Greater Cairo anchors national volume through dense urban mobility demand and last-mile delivery network expansion. The General Authority for Investment calibrates local assembly incentives against pure import channels, shaping manufacturer localization commitments. Alexandria's port infrastructure supports regional distribution hub development for North African markets.
Nigeria
Lagos metropolitan logistics networks mandate zero-emission vehicle quotas that de-risk fleet procurement decisions for commercial buyers. Grid reliability constraints in secondary cities limit route expansion beyond the Lagos-Ibadan corridor. Platform aggregators like Gokada and MAX.ng accelerate driver conversion through lease-to-own battery subscription programs.
Rwanda
Kigali's phased combustion ban for commercial two-wheelers creates a captive replacement market with standardized vehicle specifications. The national motorbike taxi electrification mandate eliminates regulatory uncertainty for fleet procurement planning. Secondary city deployment programs extend electrification targets to rural logistics corridors beyond the capital.
Africa Electric Scooter Market Key Industry Players
Premium-margin players sit above commodity-margin players across battery subscription integration depth, with sit-down commercial configurations commanding deeper margin pools than stand-up commuter alternatives. The vendor base stratifies between integrated battery manufacturers, vehicle-assemblers sourcing third-party cells, and energy-network operators unbundling hardware from energy service. Three archetypes dominate: integrated cell-to-vehicle manufacturers, fleet-focused platform specialists, and energy-as-a-service network operators. Competitive moves concentrate on strategic partnerships for charging infrastructure interoperability and geographic licensing agreements for battery swap network deployment.
Within the integrated manufacturing tier, Yadea Technology Group Co., Ltd. and Vmoto Limited exemplify contrasting geographic anchoring strategies. Yadea occupies a position tied to captive battery production scale, while Vmoto represents the fleet-specialist archetype with sit-down configuration focus. Honda Motor Co Ltd anchors the established dealer-network tier, leveraging Southern African distribution infrastructure built through decades of combustion two-wheeler presence.
| Leading Market Players |
|---|
| Ninebot Limited |
| Suzuki Motor Corporation |
| Honda Motor Co Ltd |
| Mahindra GenZe |
| Terra Motors Corporation |
| KTM AG |
| Yamaha Motor Company Limited |
| Vmoto Limited |
| Yadea Technology Group Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Lithium carbonate cell costs cascade through three distinct pricing tiers before reaching fleet operators in Lagos and Nairobi, with Chinese cathode material pricing volatility transmitting downstream into battery subscription rate structures across East African commercial markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the Africa Electric Scooter Market by certification grade and after-sales bundling intensity. South Africa's National Regulator for Compulsory Specifications battery safety certification commands premium positioning, while uncertified imports compete on sticker price alone. Cost compression in the economy tier is intensifying because Ghana's Energy Commission draft efficiency standards are forcing engineering redesigns. Delivery cooperatives in Nairobi exhibit the sharpest price sensitivity, whereas tourist rental operators in Cape Town prioritize reliability over acquisition cost.
Supply Chain Analysis
Battery refurbishment and end-of-life recovery flows are emerging as critical cost centers, with Nairobi-based third-party technicians now processing retired lithium packs for secondary stationary storage applications. Manufacturing concentration rests on China for cell production, Vietnam for frame assembly, and South Africa for localized kitting operations. Cathode active materials, battery management systems, and electric motor controllers constitute the core input dependencies. Single-source vulnerability in lithium hydroxide supply creates exposure to export licensing shifts. Distribution runs through Johannesburg-based import agents serving sub-regional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa Electric Scooter Market functions as a geographic-arbitrage play where Kenya's off-peak commercial EV tariffs create a fifteen to twenty percent operating cost differential against Nigerian grid-dependent operators.
For Market Incumbents: Anticipate margin compression from silicon-anode lithium-ion chemistry commoditization by securing backward integration into battery management system firmware development. Defensive positioning requires deepening charging infrastructure interoperability partnerships to lock in fleet operator switching costs. Yadea Technology Group Co., Ltd.'s captive cell production demonstrates how upstream control preserves pricing power against pure vehicle assemblers. For New Entrants and Emerging Players: The mid-tier price gap between premium sit-down configurations and economy stand-up alternatives offers white-space entry potential for modular platform specialists. Rwanda's motorbike taxi electrification mandate presents the most penetrable geography given standardized procurement specifications and captive replacement demand. A battery-as-a-service go-to-market angle eliminates capital barriers for informal sector rider conversion. For Investors and Strategic Acquirers: Consolidation pressure builds where technician certification gaps strand assets in inland markets, creating distressed acquisition opportunities for service-network consolidators. Long-term viability favors energy-network operators with swap station density over pure hardware manufacturers. Acquisition target archetypes include third-party maintenance platforms with vocational training partnerships. Monitor Ghana's Energy Commission final efficiency standard implementation as inflection indicator for lithium platform acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swap Network Deployment | Interoperability with third-party charging infrastructure determines fleet procurement decisions in Nairobi logistics corridors. |
| Solar-Integrated Charging Hub Development | Off-grid photovoltaic generation addresses grid instability constraints limiting route expansion in Nigerian secondary cities. |
| Local Assembly Partnership Formation | Egypt's General Authority for Investment incentives shape whether manufacturers establish production versus pure import channels. |
| Silicon-Anode Chemistry Transition | Forty percent capacity improvements without pack size increases compress vehicle weight classes for heavier payload configurations. |
| Technician Certification Program Investment | High-voltage battery servicing skills concentration in Johannesburg and Cairo creates maintenance bottlenecks strand assets inland. |
Research Approach
Multiple input streams — fleet operator procurement directors, energy regulatory authority officials, battery swap network operators, and aftermarket service technicians — were reconciled against secondary validation from customs trade records, national transport authority registration databases, and power utility tariff filings. Primary interviews captured operational economics across Lagos delivery cooperatives, Nairobi boda-boda associations, and Cape Town tourism rental operators. Bottom-up unit shipment estimates triangulated against top-down addressable market calculations.
Historical volume trajectories were cross-referenced against panel input from commercial fleet procurement committees to anchor projection parameters across the analysis window. Segmentation dimensions modeled include product type configuration, end-use application, speed capacity classification, and battery chemistry tier. CAGRs were derived from curve-fitting observed adoption patterns against regulatory mandate timelines. Forecast inputs incorporated Kenya's Energy and Petroleum Regulatory Authority tariff structure evolution and Rwanda's phased combustion ban implementation pace.
Caveats apply where import duty volatility or grid reliability deterioration could materially shift the outlook for commercial operator payback calculations. Practitioners should monitor lithium carbonate spot price movements and national regulator local content requirement announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
EV Platform Market
Electric Vehicles
Africa Electric Vehicle Market
Electric Vehicles
North America Automotive High Performance Electric Vehicle Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
Europe Electric Vehicle (EV) Fluids Market
Electric Vehicles
Hybrid E-Scooter Market
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
Electric Vehicle NVH Material Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
Europe Electric Vehicle Thermal Management System Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
Europe Electric Bus Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
France Electric Vehicle Market
Electric Vehicles
Electric Tuk-Tuks Market