
 Electric Vehicle Communication Controller Market | 2026-2036
Electric Vehicle Communication Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Communication Controller Market Intelligence
The direct-to-OEM supply channel for EV communication controllers is fragmenting as software-defined vehicle architectures become more prevalent. This fundamental shift creates openings for specialized software and hardware providers to engage directly with global car manufacturers. Vector Informatik GmbH leverages its deep expertise in automotive electronics and software tools to serve this evolving ecosystem. Meanwhile, Bosch Limited competes by offering highly integrated solutions that combine controller hardware with its extensive portfolio of vehicle systems.
An electric vehicle communication controller is a specialized electronic control unit that manages the complex data exchange between various EV components. It operates over protocols like Controller Area Network (CAN) and high-speed Automotive Ethernet to ensure real-time performance for critical functions. Within applications, charging management and battery management systems represent the largest and most technically demanding use cases for these controllers. Demand for powerful integrated modules is growing, although distributed controller architectures still dominate many legacy vehicle platforms.
Product design and market access are governed by a complex web of international standards and regional mandates. These include the US NHTSA's cybersecurity guidelines, the EU's Cyber Resilience Act, and China's mandatory GB standards for electric vehicles. Vendor success depends on developing flexible controller platforms that can be updated to comply with evolving communication and security protocols.
Market Dynamics
The shift towards software-defined vehicle architectures is the central force reshaping the market. This elevates the communication controller from a simple gateway to a central computing node, driving demand for more powerful and flexible hardware.
Growth Catalysts
- V2G Adoption:The rollout of Vehicle-to-Grid functionalities under ISO 15118 requires advanced controllers to manage bidirectional power flow and complex grid communication.
- Chinese GB Standards:Mandatory GB/T standards in China for EV charging impose specific communication requirements, creating a large domestic market for compliant controllers.
- Advanced BMS Integration:Complex battery management systems rely on high-speed controllers for real-time data aggregation and safety-critical actions in performance applications.
Market Restraints
- Protocol Fragmentation:Coexisting charging protocols across regions complicate controller design and increase validation costs for global vehicle platforms.
- Semiconductor Dependency:High reliance on few suppliers for automotive-grade microcontrollers creates significant supply chain vulnerabilities and pricing pressure.
- High R&D Overhead:Meeting cybersecurity mandates, like the EU's Cyber Resilience Act, requires substantial investment in specialized software development and updates.
Strategic Opportunities
- Wireless Charging Systems:Developing dedicated controllers for emerging wireless EV charging applications represents a new product category with minimal legacy competition.
- Integrated Security Modules:Converging communication and cybersecurity functions offers an opportunity to develop integrated hardware modules providing a single, certified solution to OEMs.
- IRA-Driven Domestic Sourcing:The US Inflation Reduction Act’s incentives for domestic content create an opportunity for controller manufacturers to establish production in North America.
Industry Challenges
- Automotive Software Talent:A scarcity of engineers with expertise in real-time automotive operating systems and cybersecurity protocols constrains product development.
- Legacy System Integration:Ensuring interoperability between new controllers and legacy ECU architectures within existing vehicle platforms presents a significant engineering challenge.
- Certification Bottlenecks:Long certification processes for standards like ISO 15118 can create significant delays in bringing products to market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Communication Controller Market |
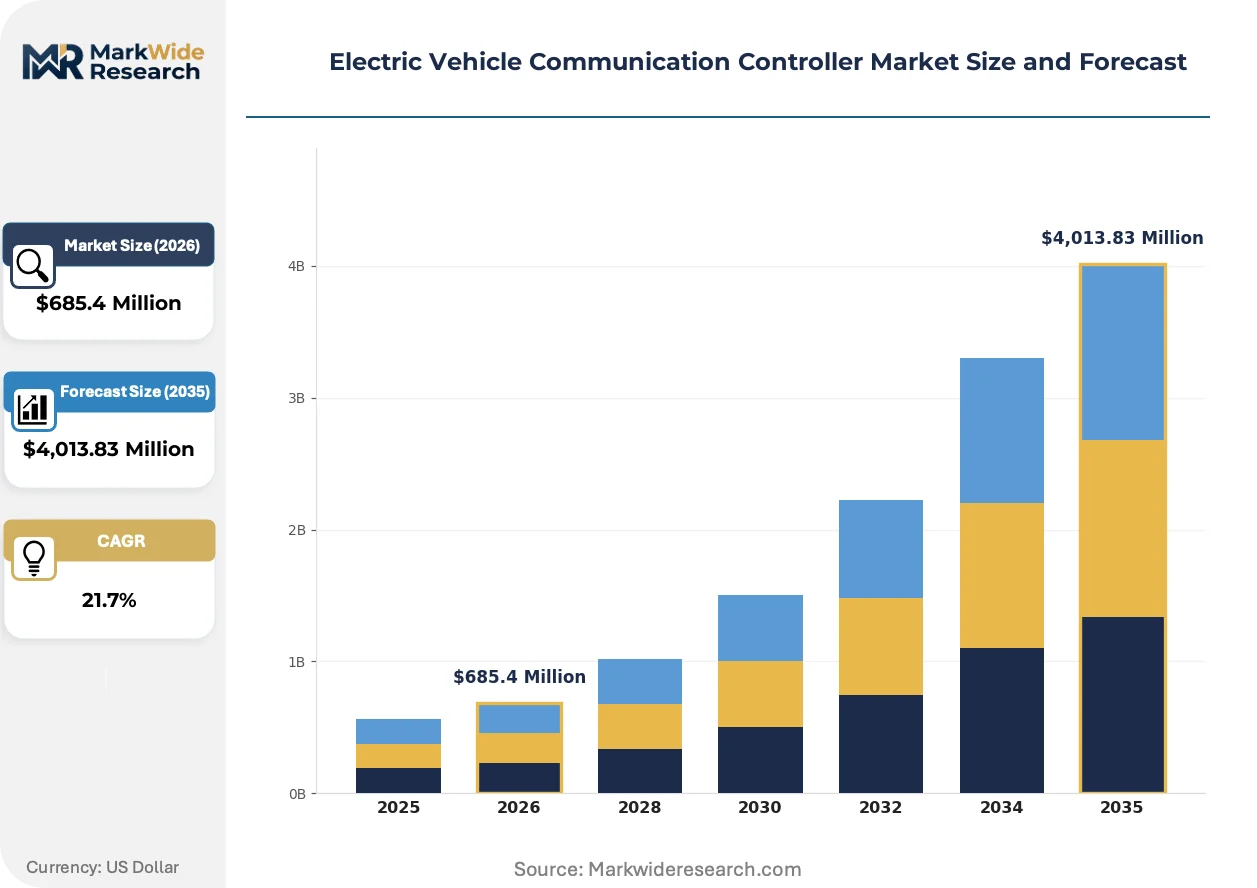
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $4,013.83 Million |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centralized Controller, Distributed Controller, Integrated Module, Custom Controller Communication Protocol: Controller Area Network, FlexRay, Ethernet, Bluetooth, UWB, Wi-Fi Application: Battery Management, Motor Control, Charging Management, Telematics, Infotainment, Safety Systems End User Type: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Service Providers |
| Companies Covered | Vector Informatik GmbH, Sensata Technologies, Inc., ABB, Mitsubishi Electric Corporation, Ficosa Internacional SA, LG Innotek, BYD Company Ltd., Bosch Limited, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Communication Controller Market Strategic Shifts & Innovations
The evolution of EV communication controllers is defined by a shift from hardware-centric gateways to software-defined computing nodes. This transition changes product design and the core value proposition for suppliers.
Automotive Ethernet provides high-bandwidth data transmission for modern EV architectures. Automakers are adopting it for vehicle backbone networks connecting domain controllers for ADAS, infotainment, and powertrain management. This technology is digitizing the vehicle's internal communication, replacing legacy CAN buses with a more powerful infrastructure.
New regulations like the EU's Cyber Resilience Act impose mandatory cybersecurity requirements for products with digital elements, including vehicle controllers. This forces manufacturers to implement secure-by-design principles and provide ongoing security updates. The charging management controller segment is most affected, needing to prove compliance for EU market access.
A significant shift in procurement sees automotive OEMs increasingly disaggregating hardware and software for vehicle electronics. This disrupts the traditional Tier-1 model, allowing specialized software vendors to supply operating systems directly to car manufacturers. This pattern is most visible in the competitive EV markets of China and Germany.
Electric Vehicle Communication Controller Market Segmentation
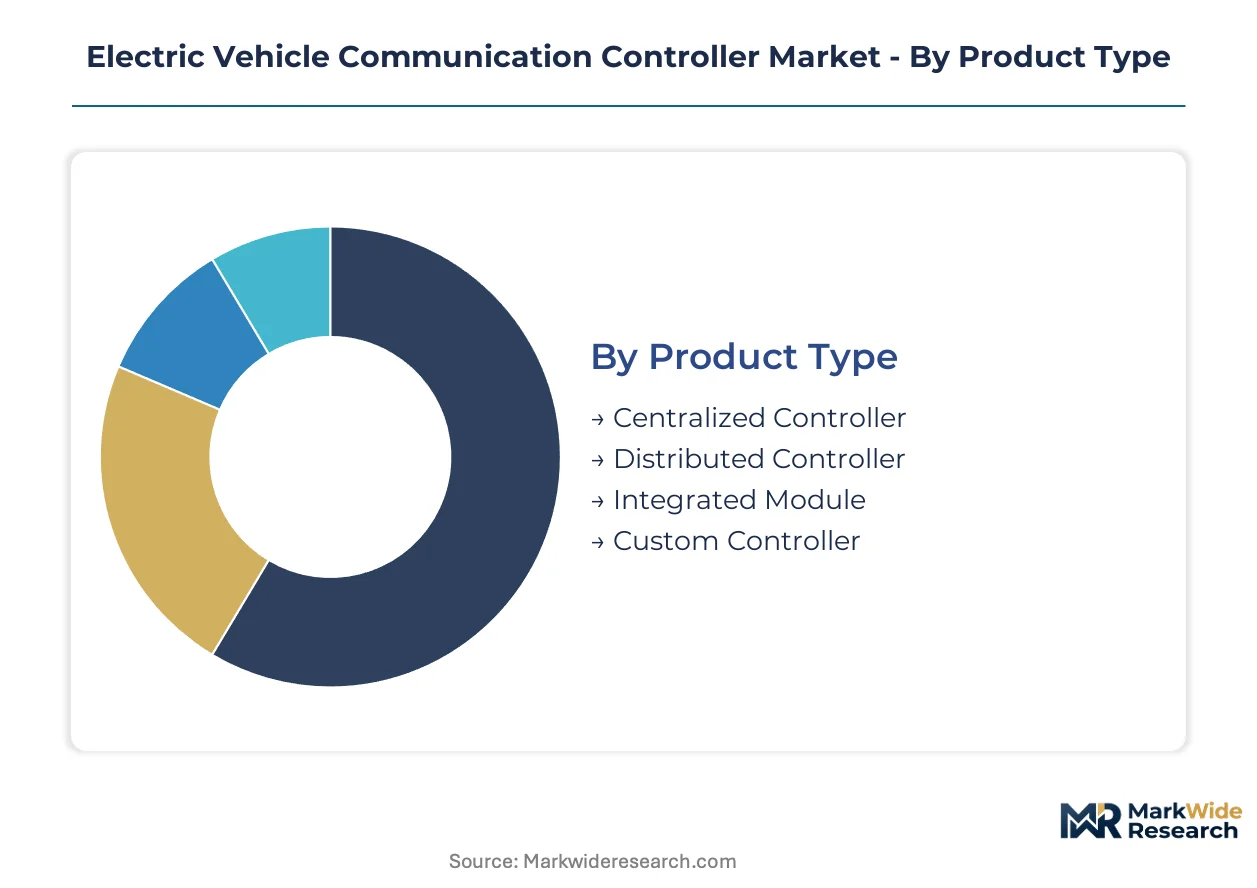
Understanding the market for electric vehicle communication controllers requires a detailed breakdown of its constituent parts. This segmentation reveals how different product types, communication protocols, applications, and end-user categories shape demand and technological development. Each segment plays a distinct role in the evolving EV ecosystem.
Product Type:
Product type segmentation delineates the physical architecture and deployment strategy of EV communication controllers.
- Integrated Module:These units combine multiple communication functions and often processing capabilities into a single, compact hardware package. Demand for integrated modules is growing due to the need for powerful, consolidated solutions in advanced battery management systems and charging applications.
- Distributed Controller:These controllers operate as individual electronic control units, managing specific vehicle functions and communicating across a network. Distributed architectures still dominate many legacy vehicle platforms, providing modularity and redundancy for critical operations.
- Centralized Controller:A single, high-performance unit manages communication for a broad range of vehicle systems, often serving as a domain controller. This approach simplifies wiring harnesses and enables more complex software-defined vehicle functions.
- Custom Controller:Tailored communication controllers address unique requirements for specialized EV platforms or niche applications, offering optimized performance and integration.
Distributed Controller holds installed capacity. Integrated Module is rotating up the share rankings.
Communication Protocol:
Communication protocols define how data moves across the vehicle's network infrastructure.
- Ethernet:Automotive Ethernet provides high-bandwidth data transmission, essential for modern EV architectures and vehicle backbone networks. This protocol supports real-time performance for ADAS, infotainment, and powertrain management.
- Controller Area Network:CAN remains a fundamental protocol for real-time performance in critical functions within electric vehicles, connecting various electronic control units. Legacy vehicle platforms heavily rely on CAN buses for robust and proven communication.
- FlexRay:This high-speed, fault-tolerant protocol offers deterministic communication, often used in safety-critical applications requiring guaranteed data delivery times. FlexRay provides enhanced reliability over traditional CAN networks.
- Bluetooth:Wireless Bluetooth communication enables short-range connectivity for in-vehicle systems, supporting features like smartphone integration and diagnostics.
- UWB:Ultra-Wideband technology provides precise location tracking and secure short-range data transfer, finding applications in digital key systems and advanced driver assistance.
- Wi-Fi:In-vehicle Wi-Fi connectivity facilitates over-the-air updates, infotainment streaming, and remote diagnostics, enhancing the user experience and vehicle serviceability.
Ethernet protocols are rapidly expanding their adoption in new vehicle platforms, while CAN remains foundational for many legacy systems.
Application:
Applications for EV communication controllers span critical operational and user-facing vehicle functions.
- Charging Management:These controllers manage the complex data exchange between the EV, charging station, and grid, especially for V2G functionalities under ISO 15118. Demand for compliant controllers is high due to evolving global standards, including China's GB standards.
- Battery Management:High-speed controllers are vital for real-time data aggregation and safety-critical actions within advanced battery management systems. These systems monitor cell health, temperature, and charge status for optimal performance and longevity.
- Motor Control:Communication controllers facilitate precise data exchange between the vehicle's central unit and the electric motor, ensuring efficient power delivery and regenerative braking.
- Telematics:Controllers in telematics systems enable remote vehicle diagnostics, emergency services, and connected car features, enhancing safety and convenience.
- Infotainment:These applications manage communication for in-car entertainment, navigation, and connectivity services, providing a rich user experience.
- Safety Systems:Communication controllers are integral to active and passive safety features, ensuring reliable data flow for airbags, ABS, and stability control systems.
Charging Management applications are undergoing significant technical evolution, driven by V2G requirements.
End User Type:
End user types differentiate the primary purchasers and integrators of communication controller solutions.
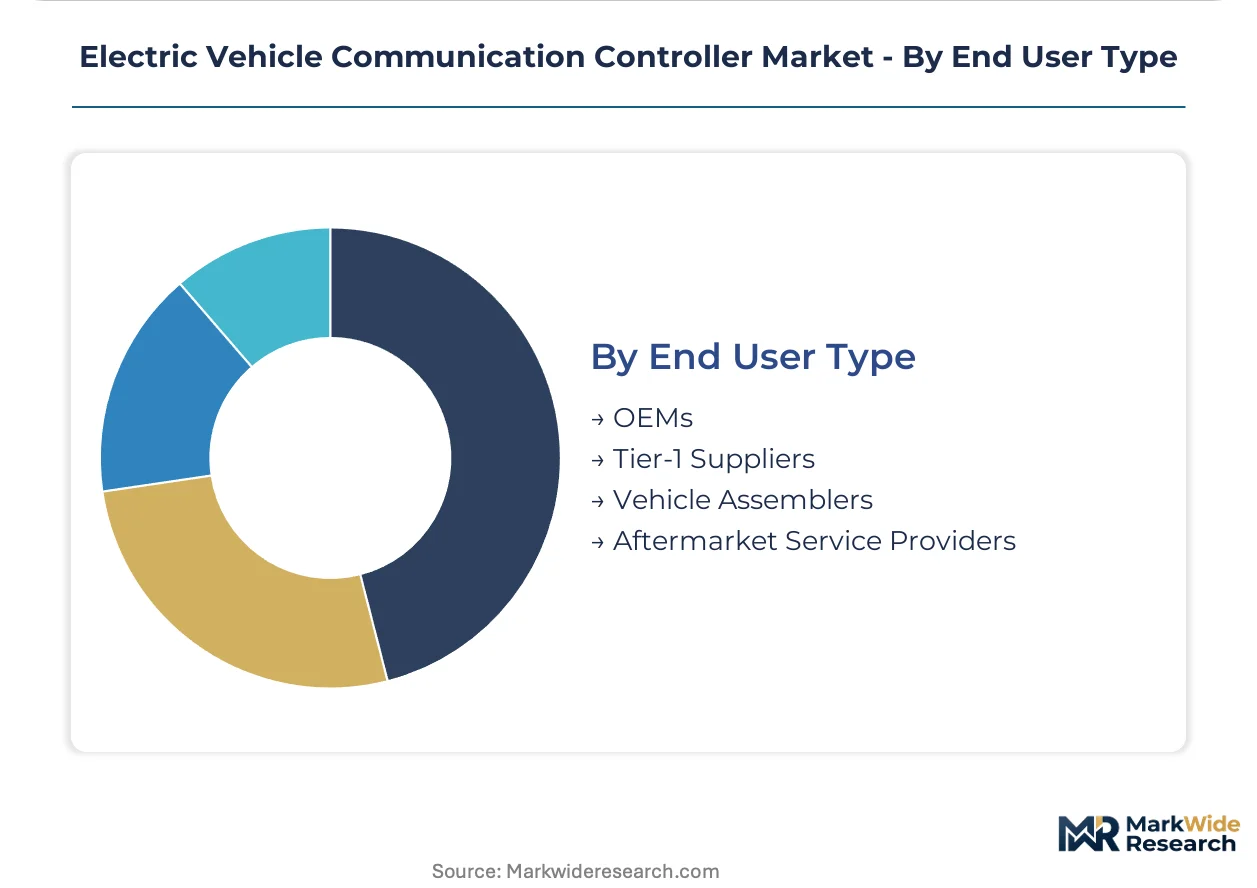
- OEMs:Automotive manufacturers directly integrate communication controllers into their vehicle designs, often seeking direct supply relationships for specialized software and hardware. The shift to software-defined architectures increases direct engagement.
- Tier-1 Suppliers:These large automotive component manufacturers develop and supply integrated systems that incorporate communication controllers to OEMs. They often provide highly integrated solutions combining controller hardware with other vehicle systems.
- Vehicle Assemblers:Companies focused on final vehicle assembly integrate components from various suppliers, ensuring seamless operation of communication controllers within the complete vehicle.
- Aftermarket Service Providers:These entities offer repair, maintenance, and upgrade services for electric vehicles, sometimes requiring replacement or updated communication controllers.
OEMs are increasingly seeking direct engagements, influencing procurement shifts across the value chain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB standards for electric vehicle charging significantly influence the global electric vehicle communication controller market, driving demand for compliant technologies. Key automotive manufacturing hubs across the globe are adapting their controller development to meet both regional mandates and the complex requirements of software-defined vehicle architectures. This regional dynamism shapes product design and market access strategies for controller manufacturers.
China
China's robust electric vehicle production and rapid adoption rates create substantial demand for communication controllers. Mandatory GB/T standards for EV charging impose specific communication requirements, fostering a large domestic market for compliant solutions. The Yangtze River Delta region, with its dense concentration of EV manufacturers, drives significant controller innovation for local and international brands.
Germany
Germany's advanced automotive manufacturing sector requires sophisticated communication controllers for its premium EV and software-defined vehicle platforms. The EU's Cyber Resilience Act imposes stringent cybersecurity requirements, necessitating secure-by-design principles in controller development. Bavaria's automotive hub continues to foster cutting-edge controller development and integration for leading European carmakers.
United States
Growing electric vehicle production and incentives from the US Inflation Reduction Act stimulate demand for communication controllers in the United States. NHTSA's cybersecurity guidelines for connected vehicles influence controller design, emphasizing robust security features. Michigan's automotive corridor supports numerous controller suppliers serving major original equipment manufacturers and emerging EV startups.
Japan
Japan's established automotive industry and focus on advanced battery technologies drive demand for high-performance communication controllers. The Ministry of Economy, Trade and Industry (METI) promotes EV infrastructure development, which includes advanced charging communication. The Nagoya region integrates sophisticated controllers into next-generation hybrid and electric vehicle systems for global markets.
South Korea
South Korea's rapid electric vehicle adoption rates and strong battery manufacturing base fuel demand for integrated communication controller modules. National policies support the expansion of smart charging infrastructure, requiring advanced controller functionalities. The Seoul Capital Area's dynamic technology ecosystem drives innovation in communication and power electronics for EV applications.
Electric Vehicle Communication Controller Market Key Industry Players
Specialized software providers and integrated hardware solution developers split the market for electric vehicle communication controllers. The market exhibits fragmentation among niche technology providers and consolidation among larger integrated system suppliers. Software-centric innovators, hardware-centric integrators, and custom solution providers represent key strategic archetypes. Strategic partnerships and technology licensing are prevalent as companies seek to expand their ecosystem reach and address diverse OEM needs.
Among the specialized software and tools providers, Vector Informatik GmbH exemplifies deep expertise in automotive electronics and software tools for evolving vehicle architectures. Meanwhile, Bosch Limited represents a major integrated solution provider, offering comprehensive controller hardware combined with its extensive portfolio of vehicle systems. Sensata Technologies, Inc. also occupies a position among suppliers focusing on sensor-integrated communication solutions for advanced automotive applications.
| Leading Market Players |
|---|
| Vector Informatik GmbH |
| Sensata Technologies, Inc. |
| ABB |
| Mitsubishi Electric Corporation |
| Ficosa Internacional SA |
| LG Innotek |
| BYD Company Ltd. |
| Bosch Limited |
| Schneider Electric |
| Others |
Cost & Logistics Intelligence
The Trans-Pacific shipping lanes' volatility directly influences the cost dynamics of EV communication controllers, impacting both component supply concentration and the final price differentiation for integrated modules. This reflects the globalized nature of automotive electronics manufacturing and the specialized components involved.
Pricing Analysis
Configured-to-order pricing for specialized EV communication controllers commands a premium over standard, off-the-shelf units. The dominant pricing model is project-based, reflecting complex OEM integration requirements. Price differentiation stems from certification levels, such as ISO 15118 compliance, and the degree of software customization. Pricing pressure stems from the increasing competition in the standard module segment, driven by Asian manufacturers. OEMs exhibit high price sensitivity for commodity components, while valuing performance and security for critical applications.
Supply Chain Analysis
Export controls on advanced semiconductor technologies from the United States limit the global flow of critical microcontrollers for EV communication controllers. Geographic supply concentration for these essential components lies primarily in Taiwan, South Korea, and China. Key raw material dependencies include rare earth elements for specialized sensors and high-grade silicon for processing units. Single-source vulnerability for automotive-grade microcontrollers presents a significant structural risk. Distribution runs through a direct-to-OEM model for highly customized solutions and Tier-1 integrators for standard modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric vehicle communication controller market represents a high-growth disruption, fundamentally reshaped by the transition to software-defined vehicle architectures. This shift elevates the controller's role from a simple gateway to a central computing node within the vehicle.
For Market Incumbents:Entrench existing OEM relationships by investing heavily in flexible controller platforms adaptable to evolving ISO 15118 and cybersecurity protocols. Incumbents face a threat from specialized software providers disaggregating hardware and software. Prioritize R&D in secure-by-design principles and develop robust over-the-air update capabilities to maintain compliance with regulations like the EU Cyber Resilience Act. Leverage deep automotive electronics expertise to offer highly integrated solutions, consolidating market share against fragmented competition.
For New Entrants and Emerging Players:Establish a beachhead in emerging wireless charging systems by developing dedicated communication controllers with minimal legacy competition. The charging management application segment, particularly for V2G functionalities, offers penetrable white space due to its rapid technical evolution. Target specialized software solutions for specific OEM needs, leveraging the shift towards software-defined vehicle architectures. A direct-to-OEM sales approach, emphasizing agility and specialized technical support, offers a viable go-to-market angle.
For Investors and Strategic Acquirers:Carve-out targets emerge from large automotive Tier-1 suppliers and diversified electronics conglomerates seeking to divest non-core communication controller divisions. The market exhibits long-term viability, driven by sustained EV growth and increasing complexity of in-vehicle communication. Focus on firms with strong intellectual property in cybersecurity or advanced communication protocols like Automotive Ethernet. A significant signal to watch is the accelerated adoption of centralized controller architectures by major automotive OEMs, indicating consolidation potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Software-Defined Controller Platforms | This enables flexible updates and compliance with evolving standards like ISO 15118 for global OEMs. |
| Invest in Cybersecurity Integration | Secure-by-design principles are crucial for meeting mandates such as the EU's Cyber Resilience Act. |
| Form Strategic Partnerships with Chipmakers | Securing long-term supply of automotive-grade microcontrollers mitigates supply chain vulnerabilities. |
| Expand Production in North America | The US Inflation Reduction Act incentives create domestic sourcing opportunities for controller manufacturers. |
| Target Wireless Charging Controller Development | This opens new product categories with minimal legacy competition in emerging EV charging applications. |
Research Approach
A standing panel of automotive engineers, Tier-1 procurement leads, EV software architects, and regulatory compliance specialists provided ongoing calibration for market sizing. This involved combining primary interviews with industry stakeholders and secondary validation from sources like NHTSA guidelines and GB standards. Publicly available financial reports and automotive production databases further informed the data collection process. Bottom-up and top-down triangulation ensured data consistency across all segments.
Scenario-bracketing defined the upper and lower bounds for market projections across the analysis window. The analytical framework modeled segmentation dimensions including product type, communication protocol, application, and end-user type, alongside regional EV production clusters. Compound annual growth rates were derived from historical trends and projected technological adoption curves. Key forecast inputs included projected EV sales volumes and the per-vehicle controller content.
Sensitivities concentrate around macroeconomic shifts, unforeseen regulatory changes, and semiconductor supply disruptions. Forecasts reflect assumptions documented through extensive primary and secondary research. Material shifts in global EV policy or core component availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
E-Bike Lithium-Ion Battery Market
Electric Vehicles
Electric Mobility Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
ASEAN Electric Bicycle Market
Electric Vehicles
India Electric Bus Market
Electric Vehicles
India Solar E-Bike Market
Electric Vehicles
China Electric Car Market
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market
Electric Vehicles
Vietnam Electric Vehicle Market
Electric Vehicles
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Golf Cart Battery Market
Electric Vehicles
Electric Bus Market
Electric Vehicles
Norway Electric Cars Market