
 Used EV Market | 2026-2036
Used EV Market Size, Share, and Industry Trends Forecast 2026-2036
Used EV Market Outlook
Modular battery leasing is restructuring how used EV buyers evaluate total ownership cost against upfront purchase price. Tesla dominates direct-to-consumer resale through its certified pre-owned program and over-the-air verification of battery state-of-health. CarMax Enterprise Services leverages standardized inspection protocols to sustain buyer trust across geographically dispersed inventory. BMW competes by extending manufacturer-backed warranties into secondary ownership cycles.
A used electric vehicle is a previously registered battery electric or plug-in hybrid automobile whose propulsion depends on rechargeable lithium-ion cells with capacities typically spanning 30 kWh to 80 kWh; these vehicles retain utility for urban commuting and fleet duty when cells maintain above 70% original capacity. The seller type dimension reveals that fleet sales channels concentrate the highest-volume transactions, while private sellers occupy the most price-sensitive tier of the market. Battery capacity segmentation shows that 60 kWh and 80 kWh configurations lead margin pools, as range adequacy remains the dominant buyer filter.
The EPA maintains fuel economy and emissions labeling requirements that affect used EV eligibility for state-level purchase incentives. NHTSA enforces safety recall transparency rules that shape marketplace disclosure obligations for dealers and auction platforms. The SEC monitors climate-risk disclosures from publicly traded fleet operators, indirectly pressuring vehicle procurement transparency. Stakeholders must monitor how regulatory shifts in battery certification standards will reshape which inventory qualifies for residual value financing.
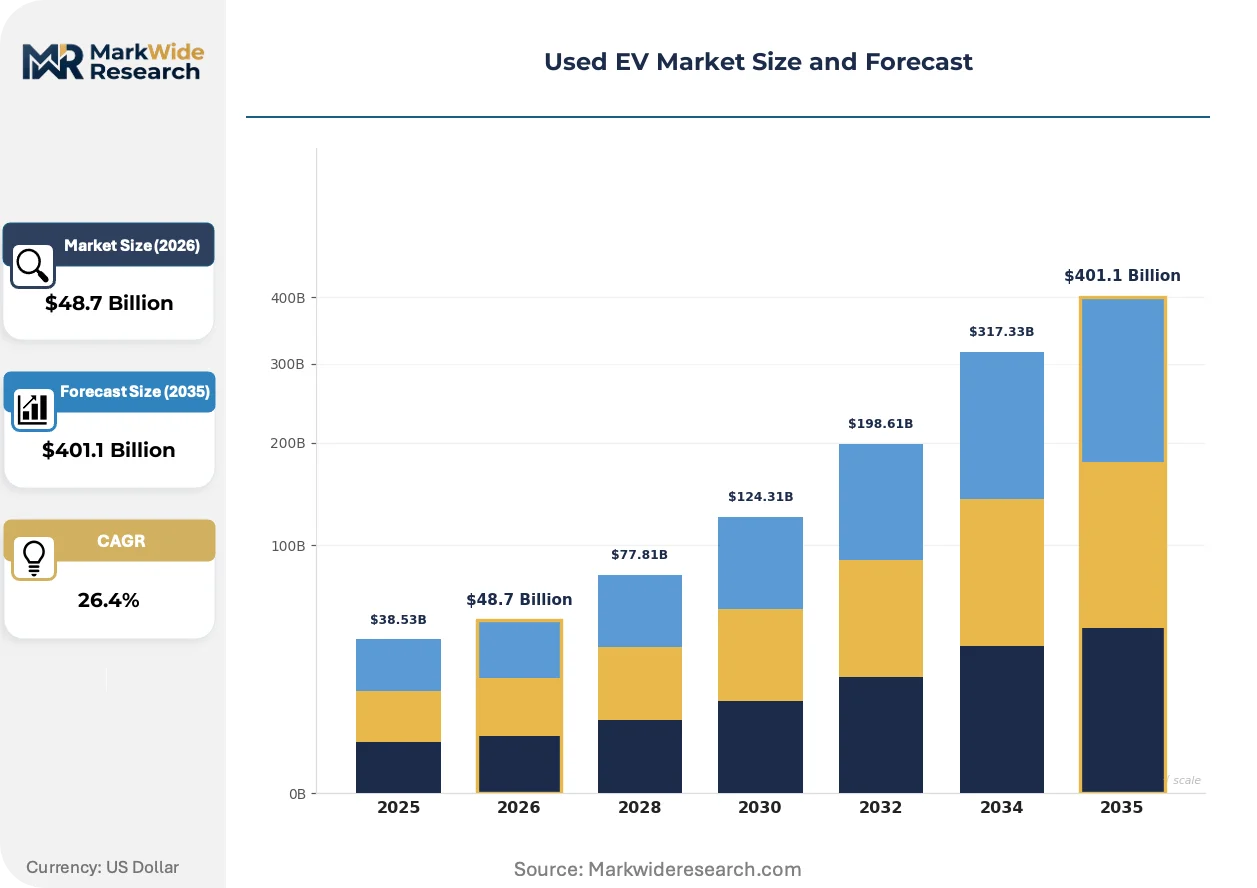
Market Dynamics
Battery health certification protocols are restructuring buyer confidence mechanisms across the secondary electric vehicle market, converting residual value uncertainty into a tradable asset class.
Growth Catalysts
- EPA State Incentive Alignment:Federal labeling requirements enable used EV qualification for state-level purchase subsidies, expanding addressable demand pools in California and New York.
- Fleet Operator Procurement:Corporate sustainability mandates from publicly traded logistics companies are accelerating bulk acquisitions of pre-owned electric sedans for urban delivery routes.
- Over-the-Air Verification:Remote battery state-of-health diagnostics reduce inspection friction and compress transaction timelines for geographically dispersed inventory.
Market Restraints
- Lithium Price Volatility:Raw material cost swings for cathode minerals compress refurbishment economics and squeeze independent dealer margins.
- Charging Infrastructure Asymmetry:Secondary market viability clusters in metropolitan corridors with density above 50 stations per 100,000 residents, excluding rural territories.
- Cell Degradation Uncertainty:Calendar aging effects below 70% original capacity create stranded asset risk for 30-40 kWh configurations with limited remaining utility.
Strategic Opportunities
- German Secondary Market Expansion:EU Green Deal vehicle scrappage incentives and manufacturer buyback programs concentrate high-quality inventory for cross-border arbitrage.
- Modular Battery Leasing:Separation of cell ownership from vehicle title reduces upfront capital barriers and unlocks subscription-based ownership models for price-sensitive segments.
- Standardized Auction Platforms:Digital wholesale marketplaces with embedded inspection data are displacing traditional physical auction lanes and compressing price discovery cycles.
Industry Challenges
- Diagnostic Technician Scarcity:Specialized training for high-voltage system assessment remains concentrated among OEM-authorized service networks, limiting independent dealer participation.
- Certification Timeline Compression:Battery health verification protocols require 4-6 hour inspection cycles that conflict with wholesale velocity requirements and inventory turnover targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used EV Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $401.1 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Hatchback, Sedan, SUV, Coupe Battery Capacity: 30 kWh, 40 kWh, 60 kWh, 80 kWh Age Category: Less than 1 Year, 1-3 Years, 3-5 Years, More than 5 Years Seller Type: Dealerships, Private Sellers, Auctions, Fleet Sales |
| Companies Covered | Tesla, Audi, Ford, Chevrolet, BMW, Nissan, Volkswagen, Hyundai, CarMax Enterprise Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used EV Market Strategic Shifts
Secondary market infrastructure is converging around data-driven trust mechanisms that displace physical inspection with algorithmic verification of asset condition.
Blockchain-based title and battery history registries are rewriting how provenance is established in transactions between unaffiliated parties. Fleet operators with centralized maintenance records are adopting these platforms first, using immutable service logs to command liquidity premiums in wholesale channels. The technology is compressing due diligence timelines from days to hours and enabling cross-border transactions without physical escrow.
The SEC's climate-risk disclosure rules for publicly traded fleet operators are mandating granular vehicle-level emissions tracking. This regulatory pressure is forcing procurement departments to document secondary market sourcing decisions with auditable chain-of-custody records. Large logistics firms are responding by integrating certified pre-owned EV acquisition into formal sustainability reporting frameworks.
Direct-to-consumer digital retail is displacing traditional dealer intermediation for vehicles under five years of age. Online platforms with integrated financing and home delivery are capturing urban buyers who prioritize convenience over test-drive access. This channel shift is most pronounced in the United States and Germany, where consumer protection frameworks for remote vehicle purchases have matured.
Used EV Market Segmentation
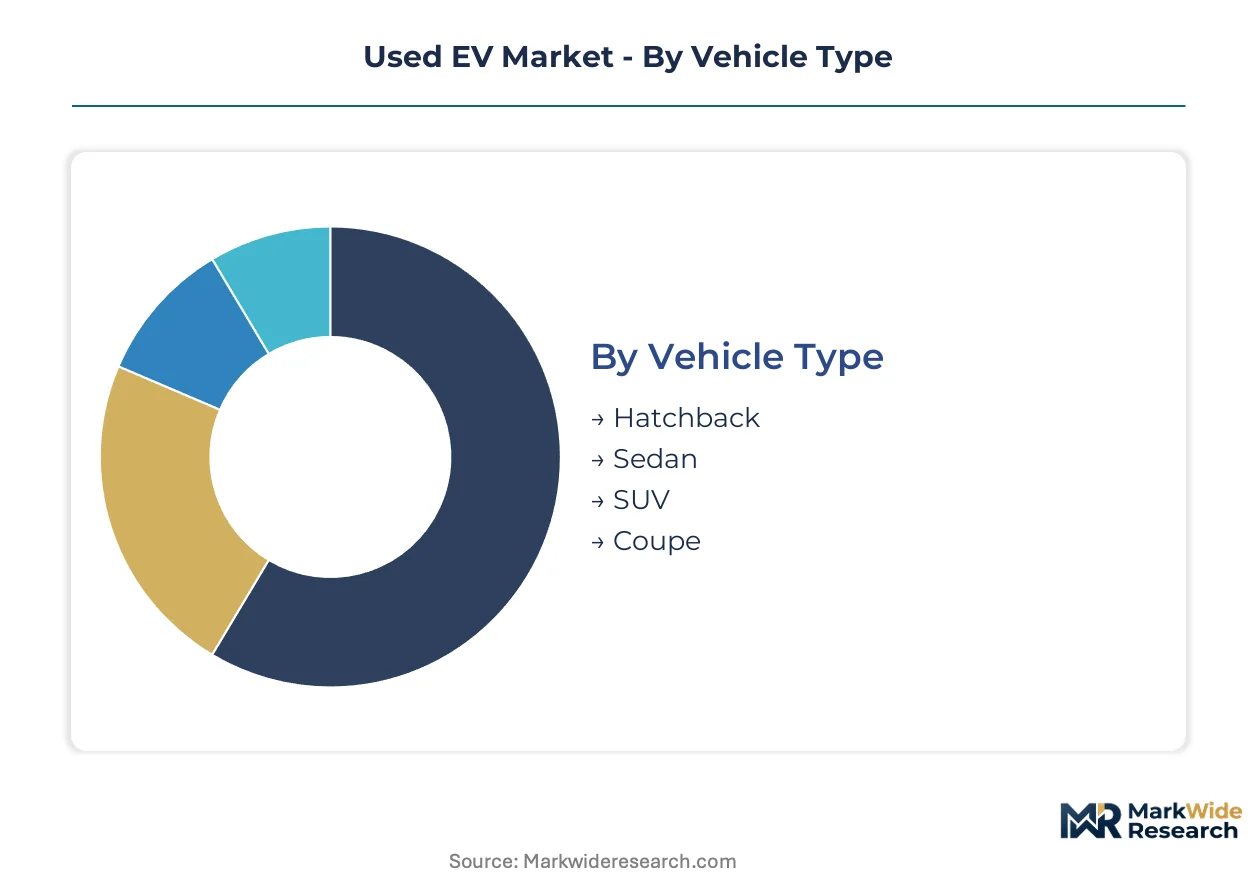
Segmentation in the used EV market determines financing eligibility, warranty coverage, and residual value guarantees. Battery capacity thresholds and seller type channels create distinct liquidity pools that shape procurement strategies for fleet operators and retail buyers.
Vehicle Type:
Upgrade cycles vary sharply by body style, with fleet operators cycling out sedans fastest while SUVs retain utility longer in secondary ownership.
- SUV:Higher ground clearance and cabin volume suit family buyers and last-mile delivery fleets. Demand clusters in United States metropolitan corridors where charging density supports larger battery configurations and range anxiety diminishes.
- Sedan:Lower center of gravity and aerodynamic efficiency maximize range per kWh. Corporate sustainability mandates from publicly traded logistics companies accelerate bulk acquisitions for urban delivery routes in Germany and China.
- Hatchback:Compact footprint dominates European urban cores with narrow street infrastructure.
- Coupe:Limited rear seating restricts fleet applicability to executive mobility services.
SUV sits at the top of the volume ranking, with Sedan climbing the fastest.
Battery Capacity:
Cost tier segmentation separates vehicles qualifying for residual value financing from those facing stranded asset risk below certification thresholds.
- 60 kWh:Balanced energy density supports 250-mile range adequacy for intercity commuting. EPA state incentive alignment enables qualification for purchase subsidies in California and New York, expanding addressable demand pools.
- 80 kWh:Premium configurations command liquidity premiums in wholesale channels. Over-the-air verification of battery state-of-health reduces inspection friction and compresses transaction timelines for geographically dispersed inventory.
- 40 kWh:Entry-level urban mobility segment with degradation risk accelerating replacement cycles.
- 30 kWh:Calendar aging effects below 70% original capacity create limited remaining utility and compressed resale horizons.
80 kWh leads margin capture, with 60 kWh expanding most quickly across fleet procurement channels.
Age Category:
Application-based segmentation distinguishes vehicles eligible for manufacturer-backed warranty extensions from those trading on price sensitivity alone.
- 1-3 Years:Near-new inventory with verified maintenance records commands liquidity premiums. Direct-to-consumer digital retail platforms capture urban buyers who prioritize convenience over test-drive access in United States and Germany.
- 3-5 Years:Depreciation curves stabilize as battery degradation patterns become measurable. Standardized auction platforms with embedded inspection data displace traditional physical auction lanes and compress price discovery cycles.
- Less than 1 Year:Off-lease volume concentrated among fleet operators with centralized maintenance records.
- More than 5 Years:Cell replacement economics dominate purchase decisions with refurbishment viability determining salvage value.
1-3 Years dominates transaction velocity, with 3-5 Years gaining share fastest as certified pre-owned programs mature.
Seller Type:
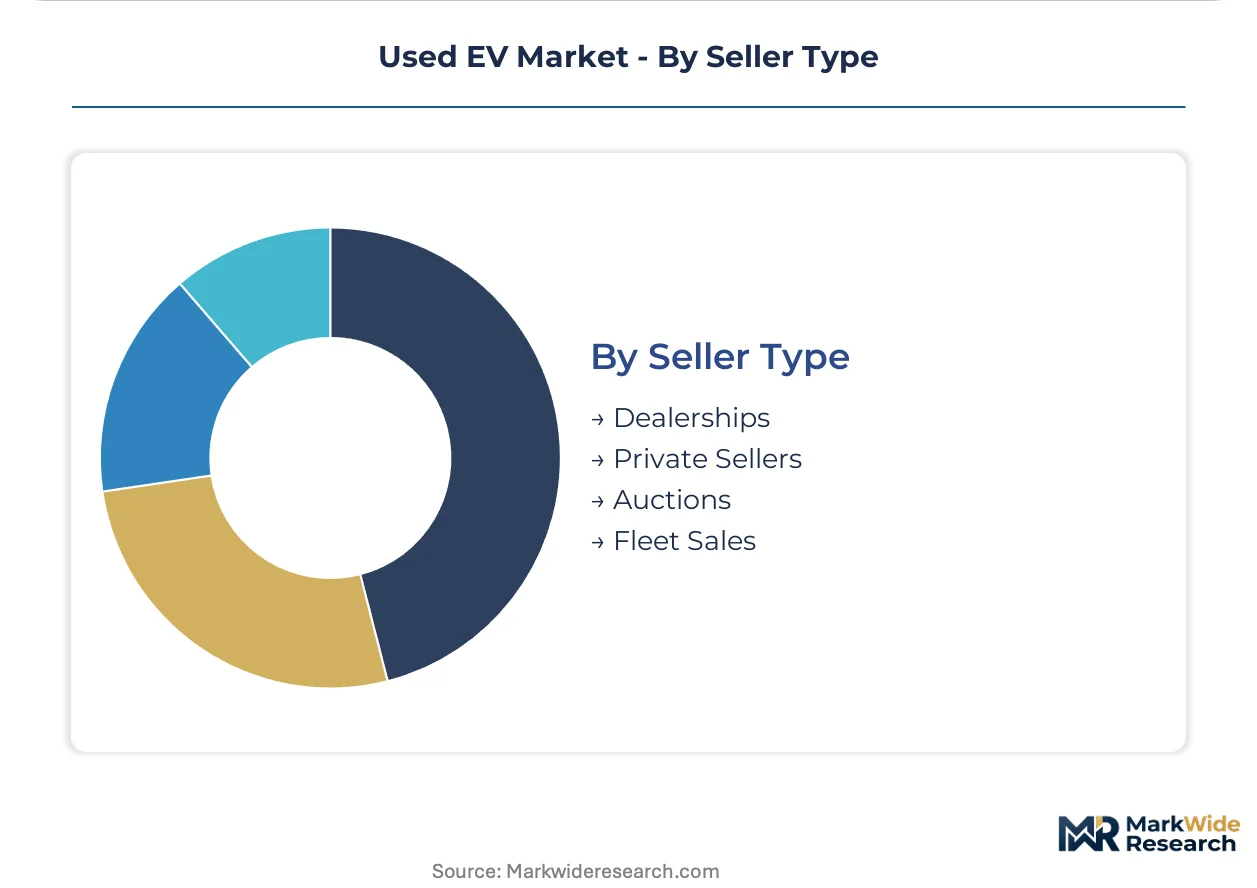
Customer-type segmentation reveals how transaction volume concentrates in institutional channels while price-sensitive buyers gravitate toward unaffiliated parties.
- Fleet Sales:Centralized maintenance records and immutable service logs enable blockchain-based provenance verification. Large logistics firms integrate certified pre-owned EV acquisition into formal sustainability reporting frameworks under SEC climate-risk disclosure rules.
- Dealerships:Standardized inspection protocols sustain buyer trust across geographically dispersed inventory. BMW extends manufacturer-backed warranties into secondary ownership cycles to compete with Tesla's certified pre-owned program.
- Auctions:Digital wholesale marketplaces compress due diligence timelines from days to hours for cross-border transactions.
- Private Sellers:Unverified battery history creates information asymmetry and price discounting pressure.
Fleet Sales anchors volume concentration, with Dealerships climbing fastest as certification protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The used EV market traces its commercial origins to California's early zero-emission vehicle mandates, which created the first concentrated secondary inventory pools during the mid-2010s as initial lease terms expired.
United States
Fleet operator bulk procurement and direct-to-consumer digital retail platforms concentrate transaction velocity in metropolitan corridors with charging density above 50 stations per 100,000 residents. EPA fuel economy labeling requirements enable used EV qualification for state-level purchase subsidies in California and New York. The Los Angeles-San Francisco corridor anchors wholesale liquidity, with standardized auction platforms displacing physical auction lanes.
Germany
EU Green Deal vehicle scrappage incentives and manufacturer buyback programs generate high-quality inventory for cross-border arbitrage into neighboring markets. KBA enforces safety recall transparency rules that shape marketplace disclosure obligations for dealers and auction platforms. The Munich-Stuttgart industrial belt concentrates certified pre-owned volume as BMW extends manufacturer-backed warranties into secondary ownership cycles.
China
Dual carbon goals and MIIT battery certification standards accelerate fleet turnover in urban delivery segments, releasing near-new inventory into secondary channels. SAMR monitors marketplace disclosure for battery health verification protocols. The Yangtze River Delta manufacturing cluster around Shanghai generates surplus lease returns that feed standardized auction platforms with embedded inspection data.
United Kingdom
Corporate sustainability mandates from publicly traded logistics companies drive bulk acquisitions for last-mile delivery electrification. CSRD climate-risk disclosure rules pressure procurement departments to document secondary market sourcing with auditable chain-of-custody records. London's ultra-low emission zone enforces demand concentration for 60-80 kWh configurations that maintain range adequacy under urban duty cycles.
Japan
METI battery recycling directives and JIS standards for high-voltage system assessment create certification infrastructure that supports residual value financing. PMDA-equivalent functional safety requirements for automotive systems shape inspection protocol development. The Kanto region around Tokyo concentrates fleet operator maintenance records that enable blockchain-based provenance verification in wholesale channels.
Used EV Market Competitive Environment
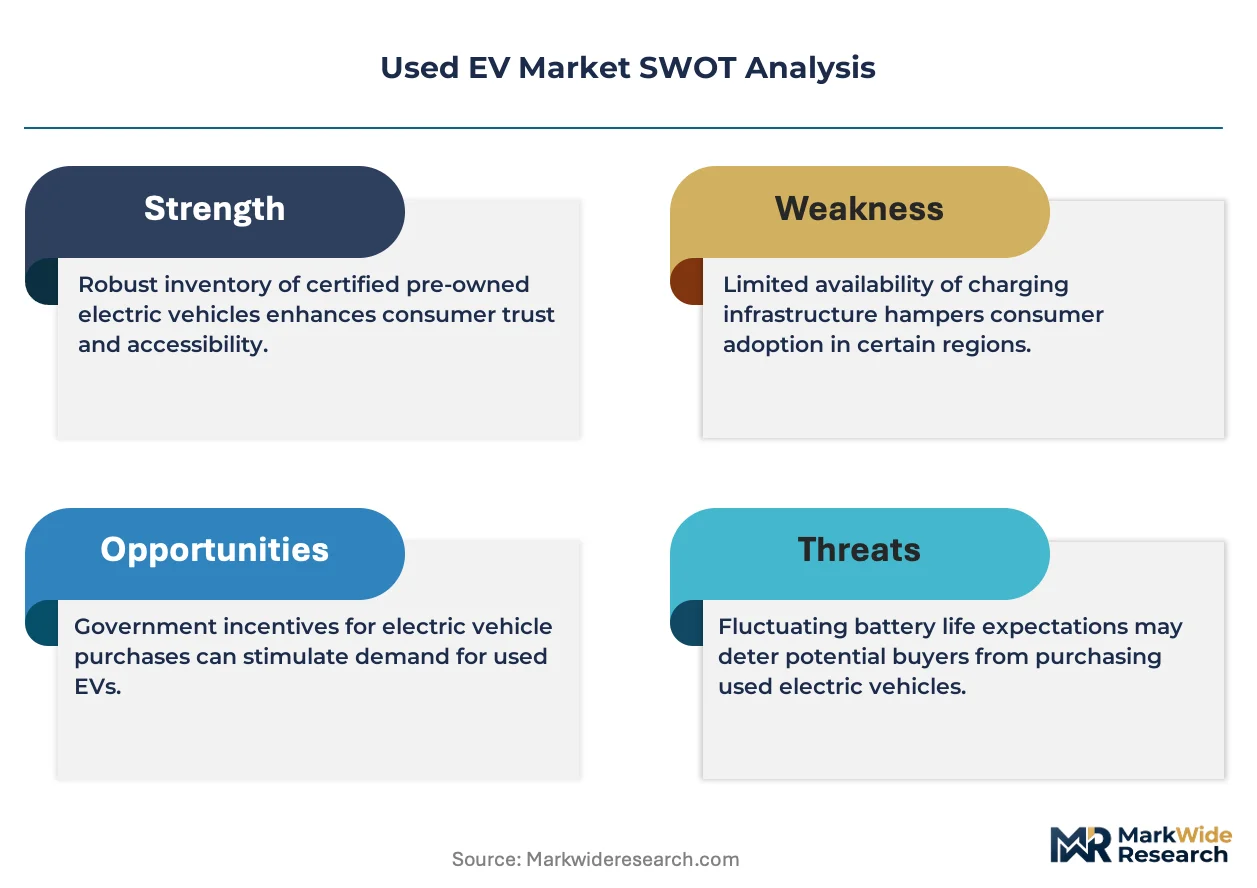
Premium-margin players sit above commodity-margin players across battery certification and warranty extension capabilities, with manufacturer-backed programs commanding liquidity premiums over independent dealer networks. The vendor base organizes into three strategic archetypes: OEM-certified programs with over-the-air verification, independent dealer networks with standardized inspection protocols, and digital wholesale marketplaces with embedded battery health data. Consolidation pressure concentrates among auction platforms and inspection service providers as transaction velocity requirements compress certification timelines. Dominant competitive moves include backward integration into battery diagnostics tooling and geographic expansion through cross-border inventory arbitrage.
Within the OEM-certified tier, Tesla and BMW exemplify divergent approaches to secondary market trust architecture, with the former leveraging direct-to-consumer resale infrastructure and the latter extending warranty coverage into subsequent ownership cycles. CarMax Enterprise Services anchors the independent dealer archetype, representing standardized inspection protocols that sustain buyer confidence across geographically dispersed inventory pools. These three companies occupy positions that illustrate how certification depth and channel control determine margin capture in an asset class converting residual value uncertainty into tradable liquidity.
| Leading Market Players |
|---|
| Tesla |
| Audi |
| Ford |
| Chevrolet |
| BMW |
| Nissan |
| Volkswagen |
| Hyundai |
| CarMax Enterprise Services |
| Others |
Value Chain & Pricing Dynamics
Fleet operator procurement concentration in North America and Germany anchors contract-based long-term offtake agreements that dominate transaction structures. These institutional buyers leverage bulk volume commitments to compress per-unit acquisition costs while securing battery health certification guarantees from OEM-certified programs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified inventory with over-the-air verification from independent dealer stock with standardized inspection protocols and unverified private sales. Certification grade and volume scale drive price differentiation, with 80 kWh configurations commanding liquidity premiums. Cost compression in the economy tier is intensifying because lithium price volatility squeezes refurbishment economics. Private sellers exhibit highest price sensitivity, while fleet operators prioritize total ownership cost over upfront capital outlay.
Supply Chain Analysis
Reverse-logistics flows for end-of-lease vehicles concentrate refurbishment capacity in the United States, Germany, and China where manufacturer buyback programs feed certified pre-owned channels. Battery cell supply draws from South Korean and Japanese cathode material processors, with lithium carbonate sourcing tethered to Chilean and Australian extraction operations. Single-source vulnerability in high-voltage diagnostic tooling creates bottlenecks for independent dealers. Distribution runs through digital wholesale marketplaces that compress price discovery cycles for geographically dispersed inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The used EV market represents a late-cycle quality story as battery health certification protocols redirect procurement budgets toward verified state-of-health inventory and away from price-discounted unverified stock.
For Market Incumbents: Anchor residual value financing capabilities through backward integration into battery diagnostics tooling and proprietary verification algorithms. OEM-certified programs must defend against digital wholesale marketplace encroachment by compressing certification timelines below four-hour inspection cycles. Capacity addition in German cross-border arbitrage corridors secures high-quality inventory access. For New Entrants and Emerging Players: Blockchain-based provenance verification technology offers a technology-first wedge into fleet sales channels where immutable service logs command liquidity premiums. Rural charging infrastructure gaps present the most penetrable white-space geography. A battery-health-data-as-a-service go-to-market angle unlocks subscription revenue from independent dealers lacking OEM-authorized diagnostic networks. For Investors and Strategic Acquirers: Fleet operators with centralized maintenance records are the most active acquirer in this space, using certified pre-owned EV procurement to satisfy SEC climate-risk disclosure requirements. Acquisition targets should demonstrate auditable chain-of-custody infrastructure and cross-border inventory arbitrage capabilities. Monitor EPA state incentive alignment shifts as the inflection indicator for demand pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Health Certification Standardization | Over-the-air verification protocols from Tesla reduce inspection friction across dispersed inventory pools. |
| Modular Battery Leasing Programs | Cell ownership separation from vehicle title unlocks subscription models for price-sensitive urban buyers. |
| Digital Wholesale Marketplace Expansion | Embedded inspection data displaces physical auction lanes in the Los Angeles-San Francisco corridor. |
| Cross-Border Inventory Arbitrage | EU Green Deal scrappage incentives concentrate German inventory for neighboring market penetration. |
| Blockchain Provenance Integration | Immutable service logs enable fleet operators to command liquidity premiums under SEC disclosure rules. |
Study Parameters
Bottom-up fleet procurement modeling reconciled against top-down auction platform transaction tracking forms the analytical core of this study. Primary interviews with fleet sustainability officers, OEM certified pre-owned program managers, independent dealer operations heads, and battery diagnostics tooling suppliers combined with secondary validation from EPA fuel economy labeling databases, NHTSA safety recall transparency filings, SEC climate-risk disclosure records, and vehicle registration data from IHS Markit. Top-down and bottom-up triangulation ensures segmentation integrity across battery capacity tiers and seller type channels.
Historical trendline analysis of lease return volumes and depreciation curve patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include vehicle type, battery capacity threshold, age category, and seller type channel, with regional regulatory cluster overlays for EPA state incentive alignment. CAGRs were derived from trend extrapolation adjusted for fleet operator procurement acceleration and certification protocol maturation. Forecast inputs incorporate lithium price volatility assumptions and charging infrastructure density thresholds.
The model holds under stable battery certification standards and sustained fleet electrification mandates; deviation in EPA regulatory shifts or lithium supply disruption would shift volume trajectories. Forecasts reflect documented assumptions about residual value financing availability and diagnostic technician training pipeline expansion. Practitioners should monitor NHTSA safety recall transparency enforcement and MIIT battery certification standard harmonization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Vehicle Solar Panel Market
Electric Vehicles
Australia Electric Vehicle Market
Electric Vehicles
Electric Vehicle NVH Material Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Mexico Solar E-Bike Market
Electric Vehicles
Global Electric Classic Car Market
Electric Vehicles
Middle East Wireless EV Charging Market
Electric Vehicles
Car Battery Chargers Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
48V Mild Hybrid Battery Pack Systems Market
Electric Vehicles
India Electric Vehicle Financing Market
Electric Vehicles
Indian E-Bike Rental Market
Electric Vehicles
Electric All-Terrain Vehicle (ATV) Market
Electric Vehicles
Asia Pacific Electric Commercial Vehicles Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market
Electric Vehicles
Vehicle-To-Grid (V2G) Market