
 Belgium E-Bike Market | 2026-2036
Belgium E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium E-Bike Market Outlook
Modular battery subscription and service bundling is broadening buyer choice beyond traditional hardware-only purchases. Cowboy leverages its direct-to-consumer platform to control pricing and customer relationships across Belgian cities. Accell België sustains multi-brand distribution strength through established dealer networks. Belgian Cycling Factory anchors premium domestic manufacturing with assembly operations serving northwest European markets.
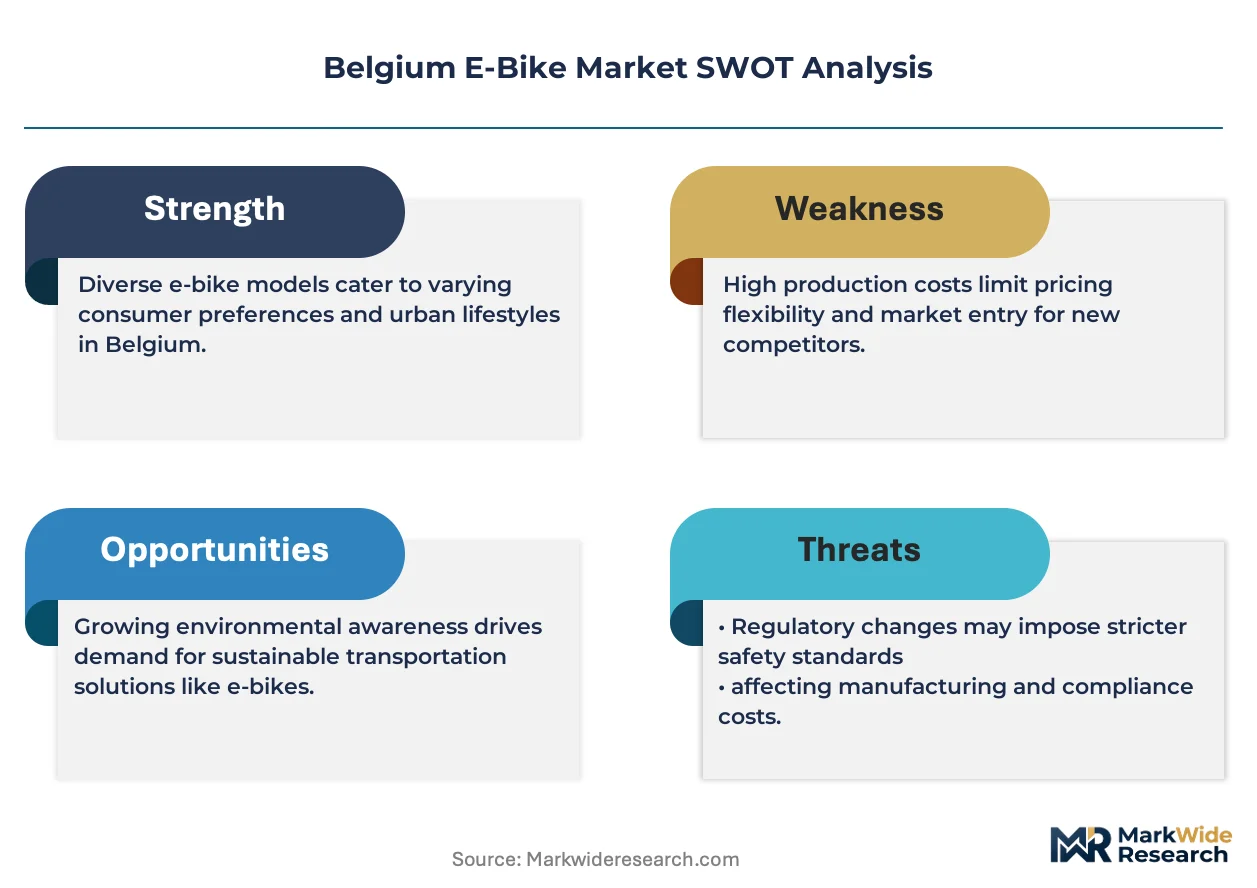
An e-bike integrates an electric motor, rechargeable battery pack, and pedal-assist or throttle-based propulsion system with conventional bicycle architecture, typically operating at 250W nominal power with torque sensors governing motor engagement. City/urban configurations dominate Belgian volume due to flat terrain and short commute distances, while cargo segments capture expanding margin pools from last-mile delivery fleet conversions. Lithium-ion battery chemistry leads technical deployment through energy density advantages, though end-of-life recycling obligations under extended producer responsibility frameworks are reshaping procurement criteria for fleet operators.
Belgium's federal mobility budget legislation and Flemish cycle highway investments shape demand structures, while EU Battery Regulation compliance requirements govern product standards for cross-border market access. The national road safety authority enforces type-approval standards harmonized with UNECE frameworks. Stakeholders must monitor evolving subsidy thresholds and infrastructure allocation decisions across regional governments to anticipate demand shifts.
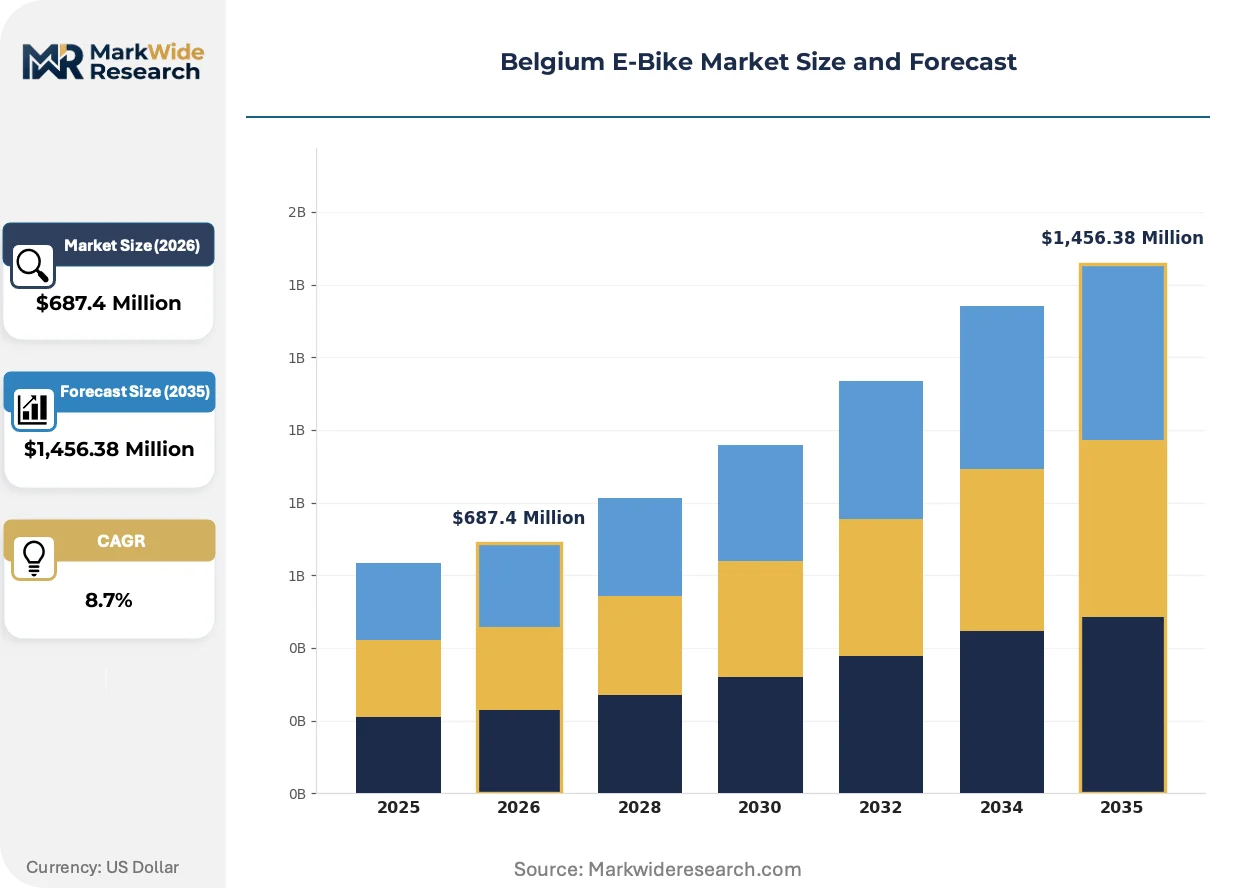
Market Dynamics
Federal mobility budget legislation and Flemish cycle highway investments are restructuring procurement patterns across Belgian corporate fleets, while EU Battery Regulation compliance deadlines compress product development cycles for domestic assemblers.
Growth Catalysts
- Flemish cycle highway infrastructure:Dense network investments in East Flanders and Antwerp provinces reduce commute friction for employer-subsidized fleet users. Corporate procurement teams prioritize routes with protected infrastructure.
- Federal cycle-to-work tax framework:Employer reimbursement ceilings and social contribution exemptions directly expand eligible employee pools. HR departments leverage these mechanisms for retention programming.
- Lithium-ion energy density improvements:Cell chemistry advances extend practical range thresholds for cargo configurations. Last-mile delivery operators convert diesel van allocations to electric cargo bike fleets.
Market Restraints
- Cell supply concentration:Cylindrical and prismatic lithium-ion cell sourcing clusters among East Asian producers. Belgian assemblers face extended lead times and currency exposure on battery pack imports.
- Extended producer responsibility obligations:EU Battery Regulation mandates end-of-life collection and recycling targets for traction batteries. Fleet operators must incorporate reverse logistics costs into total cost of ownership calculations.
- Substitution from electrified public transit:Municipal tram and bus network expansions in Brussels and Ghent compete for modal share on corridors under 10 kilometers. Commuters with transit passes exhibit reduced e-bike attachment rates.
Strategic Opportunities
- Walloon manufacturing footprint:Underdeveloped assembly capacity in Liège and Namur provinces offers greenfield site availability. Logistics positioning enables same-day distribution to Luxembourg and French border markets.
- Battery subscription unbundling:Modular service models separate hardware ownership from energy access. Direct-to-consumer platforms capture recurring revenue streams and reduce upfront price barriers for individual buyers.
- Corporate fleet electrification mandates:Brussels-Capital Region vehicle access restrictions and LEZ expansion timelines accelerate commercial procurement. Facility managers seek compliant alternatives to internal combustion vans.
Industry Challenges
- UNECE type-approval certification timelines:Harmonized technical requirements for speed pedelecs require documentation packages and testing protocols. Smaller assemblers lack dedicated homologation staff and externalize to specialized consultants.
- Diagnostic technician scarcity:Motor controller and battery management system troubleshooting demands electromechanical hybrid skills. Dealer networks struggle to recruit personnel with both bicycle mechanics and low-voltage electronics competencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium E-Bike Market |
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,456.38 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City/Urban, Mountain, Trekking, Cargo Battery Type: Lithium-Ion, Lead Acid, Nickel-Cadmium, Others Use Case: Commuting, Leisure, Delivery, Fitness End User: Individual Consumers, Fleet Operators, Rentals, Corporate Users |
| Companies Covered | Cowboy, Accell België, Belgian Cycling Factory, Veloci, Granville, Ellio, Oxford, Gazelle, Vita E-Bikes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium E-Bike Market Strategic Shifts
Digital integration of hardware ownership with energy-as-a-service models is fragmenting traditional purchase patterns, while regulatory pressure on battery lifecycle accountability forces redesign of procurement criteria and supplier relationships.
Smart battery management systems with cellular connectivity and predictive degradation algorithms are unifying hardware monitoring with subscription billing infrastructure. Fleet operators and direct-to-consumer platforms adopt these configurations to optimize swap logistics and minimize downtime. This convergence is compressing differentiation between premium and mid-tier hardware offerings as software-enabled service layers capture margin.
EU Battery Regulation delegated acts on carbon footprint declarations and recycled content thresholds are tightening supply chain documentation requirements. Belgian assemblers must secure cell supplier certificates of origin and establish recycling partnerships before product placement. Cargo bike configurations with larger battery packs face disproportionate compliance burden relative to urban commuter segments.
Employer-subsidized access models are displacing individual ownership in dense Flemish commuting corridors. HR platforms and mobility budget administrators intermediate fleet procurement, consolidating buyer power and standardizing service level expectations. This concentration is most visible in Antwerp and Ghent metropolitan zones where cycling modal share exceeds 25 percent.
Belgium E-Bike Market Segmentation
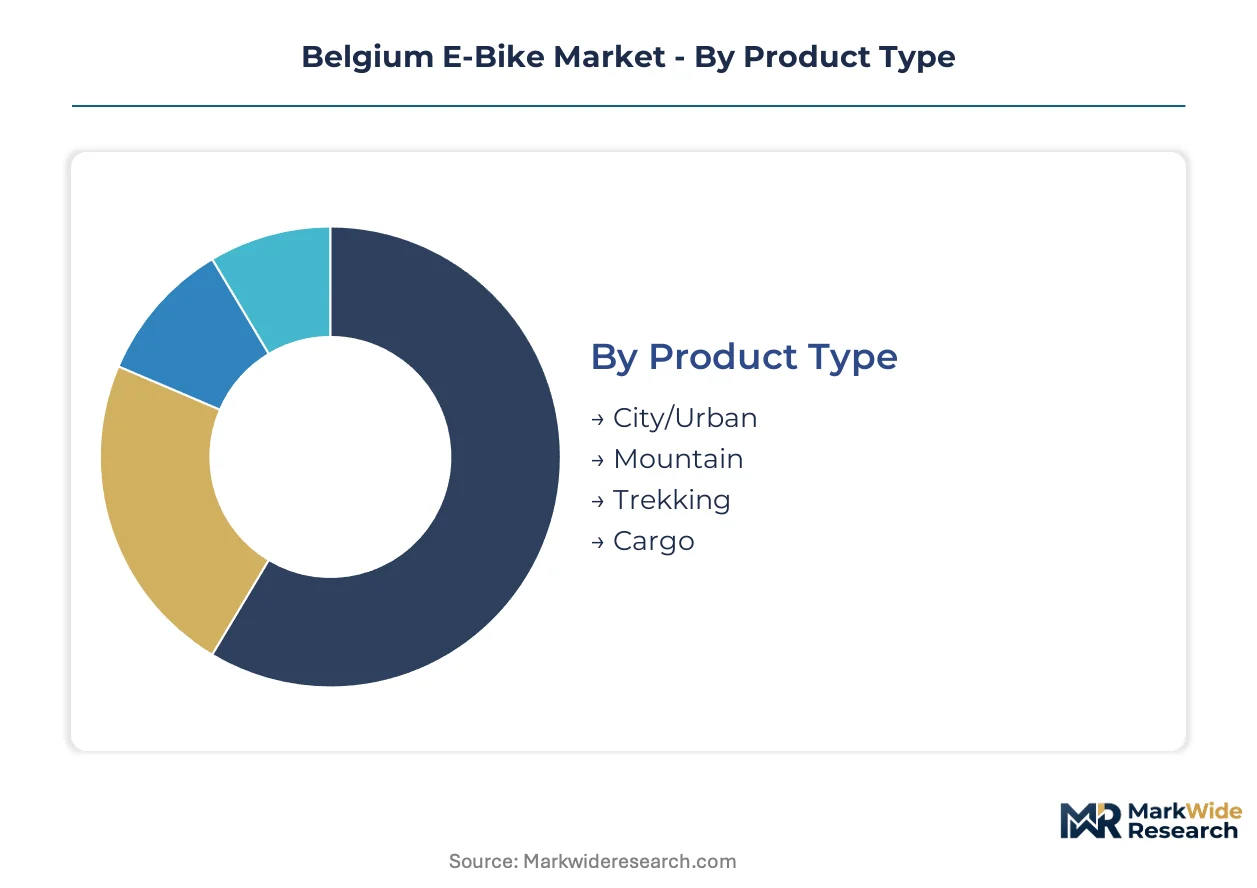
Belgian e-bike procurement patterns fragment across four distinct category axes. Each dimension captures different decision criteria: terrain suitability, energy infrastructure, trip purpose, and buyer organizational structure.
Product Type:
Frame geometry and motor positioning differentiate buyers by route topography and load requirements.
- City/Urban:Step-through frames with integrated hub motors dominate flat Flemish commuting corridors. Demand concentrates in Antwerp and Ghent metropolitan zones where employer subsidy programs and protected cycle highways reduce friction for daily trips under 15 kilometers.
- Cargo:Extended wheelbases accommodate dual-battery configurations for commercial payload capacity. Last-mile delivery operators in Brussels-Capital Region convert diesel van allocations to electric cargo fleets under Low Emission Zone compliance timelines.
- Mountain:Full-suspension frames with mid-drive torque sensors handle Ardennes terrain gradients. Recreational buyers in Wallonia's forest trail networks prioritize battery thermal management for sustained climbs.
- Trekking:Hybrid geometry balances rack mounting points with ergonomic positioning for multi-day routes. Touring cyclists along Flemish cycle node networks value integrated lighting and fender compatibility.
Volume sits with City/Urban configurations; growth tilts toward Cargo as commercial fleet electrification mandates tighten.
Battery Type:
Energy density and lifecycle accountability separate procurement strategies across fleet scale and ownership duration.
- Lithium-Ion:NMC and LFP cell chemistries deliver 500+ Wh capacity within frame-integrated enclosures. Belgian assemblers face EU Battery Regulation carbon footprint declaration requirements and extended producer responsibility obligations for end-of-life collection networks.
- Lead Acid:Sealed AGM configurations persist in price-sensitive rental fleet applications. Brussels bike-share operators specify these packs for theft-deterrence and lower replacement cost exposure in high-turnover deployments.
- Nickel-Cadmium:Memory-effect tolerance suits industrial utility applications with irregular charging patterns. Niche presence in institutional maintenance fleets with legacy charging infrastructure.
- Others:Solid-state prototypes and sodium-ion alternatives enter pilot programs through Flemish innovation subsidies. Research consortia test thermal stability in cargo configurations with larger pack volumes.
Lithium-Ion dominates installed base; alternative chemistries gain trial share fastest in subscription-model deployments where battery ownership unbundles from hardware.
Use Case:
Journey frequency and distance thresholds determine motor power specification and service bundling preferences.
- Commuting:Daily round-trip reliability demands drive belt or enclosed chain systems for reduced maintenance. Corporate mobility budget administrators standardize on 250W nominal power to comply with federal cycle-to-work reimbursement ceilings.
- Delivery:Stop-start route optimization requires rapid torque response and regenerative braking integration. Courier platforms in Leuven and Mechelen specify dual-battery hot-swap configurations to minimize downtime during peak windows.
- Leisure:Weekend trip flexibility prioritizes range reserve and smartphone navigation integration. Individual buyers in coastal provinces value step-through accessibility for multi-generational household sharing.
- Fitness:Variable assist levels preserve rider exertion control for training regimens. Cycling clubs in Limburg province specify torque sensor granularity for group ride pacing compatibility.
Commuting captures transaction volume; Delivery exhibits steepest expansion trajectory as logistics electrification deadlines approach.
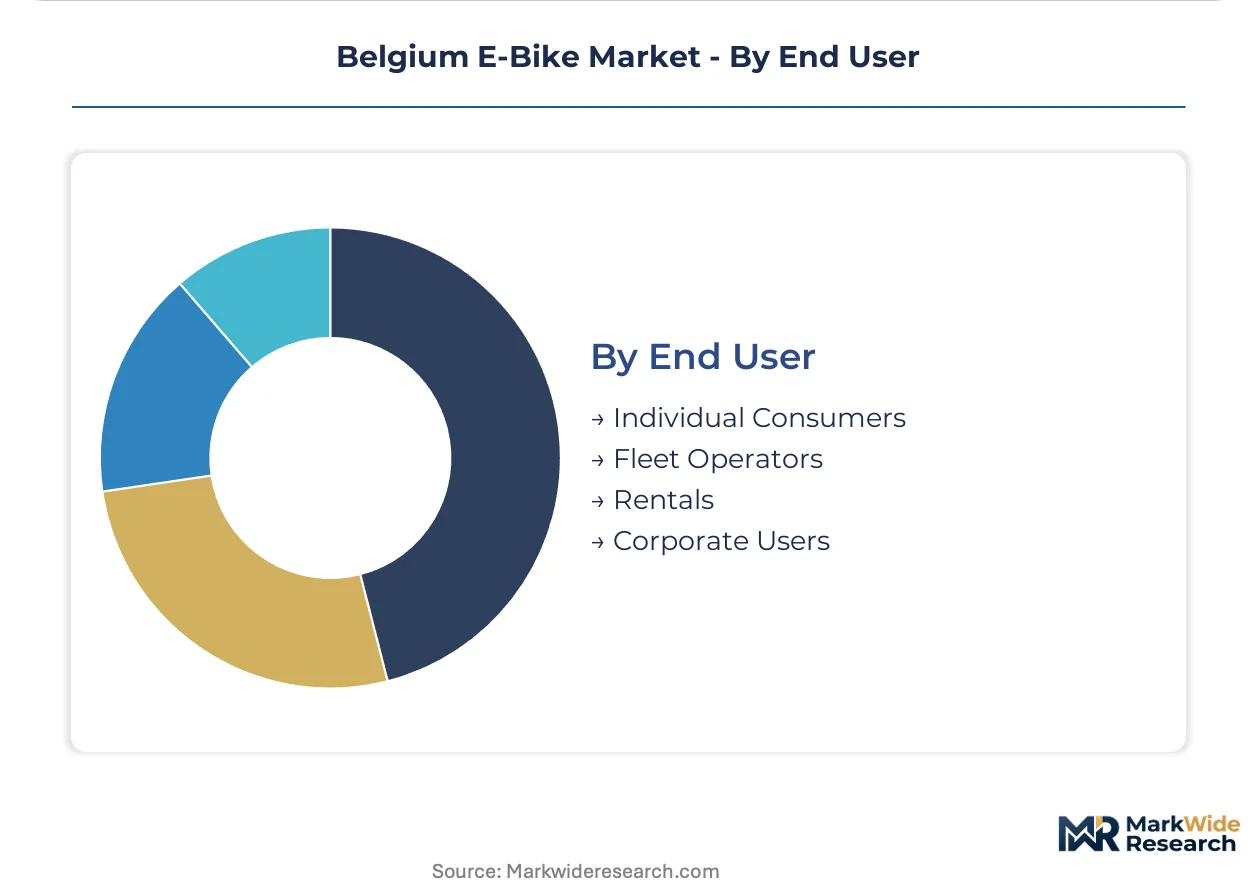
End User:
Procurement scale and decision centralization create distinct channel and service expectations.
- Fleet Operators:Standardized specifications with centralized maintenance contracts reduce total cost of ownership. Last-mile logistics coordinators negotiate volume pricing and swap-station network access.
- Corporate Users:HR departments intermediate employee access through mobility budget platforms. Procurement teams prioritize route infrastructure quality and theft insurance bundling for retention programming.
- Individual Consumers:Direct-to-consumer platforms and dealer networks compete on test-ride availability and financing terms. Flemish buyers concentrate in urban corridors with protected infrastructure; Wallonia shows lower penetration.
- Rentals:Municipal and private bike-share schemes demand vandal-resistant hardware with cellular tracking. Brussels-Capital Region operators face station density requirements under regional mobility plans.
Individual Consumers hold installed base majority; Fleet Operators are climbing the fastest as commercial vehicle restrictions expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Flemish cycle-to-work tax incentive zone concentrates employer-subsidized procurement in northern provinces. Federal mobility budget legislation and regional infrastructure investments create divergent uptake patterns across Belgium's three linguistic regions.
Flanders
Antwerp and Ghent metropolitan corridors generate dense fleet demand through employer subsidy aggregation. The Flemish government maintains cycle highway investments linking East Flanders with Brussels-Capital commuter sheds. Cowboy and Accell België distribution networks prioritize Antwerp- and Leuven-based dealer partnerships for corporate account servicing.
Wallonia
Liège and Namur provinces exhibit underdeveloped assembly capacity relative to Flanders. The Walloon Region's industrial reconversion programs target greenfield e-bike manufacturing sites near French and Luxembourg border logistics nodes. Belgian Cycling Factory maintains no Walloon production footprint, creating import dependency for southern retail channels.
Brussels-Capital Region
Low Emission Zone expansion and vehicle access restrictions accelerate commercial fleet electrification timelines. The Brussels regional government mandates bike-share station density requirements under mobility master plans. Last-mile delivery operators convert diesel van allocations to electric cargo configurations ahead of compliance deadlines.
Netherlands (Cross-Border Influence)
Dutch cycling infrastructure standards and procurement practices spill across the Flemish border through integrated logistics corridors. Randstad-based fleet operators extend service contracts into Belgian Limburg and Antwerp provinces. EU Battery Regulation harmonization eliminates technical barriers for Dutch assemblers serving Belgian corporate accounts.
Belgium E-Bike Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across hardware manufacturing and direct-to-consumer distribution channels. Market structure exhibits tiered concentration: established multi-brand distributors with dealer network scale, domestic assemblers with regional manufacturing footprints, and venture-backed direct-to-consumer platforms with pricing control. Strategic archetypes include vertically integrated manufacturers, subscription-model service bundlers, and fleet-focused B2B intermediaries. Competitive moves center on battery subscription unbundling and corporate procurement platform consolidation.
Among Belgian-based specialists, Cowboy exemplifies the direct-to-consumer archetype with urban-focused hardware and controlled pricing across metropolitan markets. Accell België occupies the multi-brand distributor position with established dealer network relationships serving fleet and individual segments. Belgian Cycling Factory anchors domestic manufacturing capacity with assembly operations targeting northwest European export markets.
| Leading Market Players |
|---|
| Cowboy |
| Accell België |
| Belgian Cycling Factory |
| Veloci |
| Granville |
| Ellio |
| Oxford |
| Gazelle |
| Vita E-Bikes |
| Others |
Value Chain & Pricing Dynamics
Federal cycle-to-work reimbursement ceilings compress hardware budgets for corporate procurement teams, forcing assemblers to unbundle battery ownership and absorb currency exposure on East Asian cell imports. This demand-side constraint reshapes supplier relationships and margin distribution across Belgian distribution channels.
Pricing Analysis
Premium pricing for 4-6 week lead-time battery packs runs 15-20 percent above spot inventory cleared through distributor networks. Three-tier pricing structure across premium direct-to-consumer platforms, standard dealer networks, and economy rental fleet specifications reflects after-sales service bundling and warranty duration. Cost compression in mid-tier urban commuter configurations is intensifying because cylindrical cell sourcing clusters in South Korea and Japan. Individual consumers exhibit highest price sensitivity; fleet operators prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
EU Battery Regulation carbon footprint declarations and recycled content mandates are reshaping sourcing protocols for Belgian assemblers. Cell supply draws from South Korea, Japan, and China; motor controllers and torque sensors originate from Taiwan and Germany. Single-source vulnerability concentrates in NMC cathode active material flows. Distribution runs through Antwerp- and Leuven-centered dealer networks serving Flemish corporate accounts, with direct-to-consumer platforms bypassing traditional retail markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lithium-ion cell supply bottlenecks prop hardware pricing, creating margin protection for assemblers with secured supplier relationships and forward inventory positions.
For Market Incumbents: Cement dealer network exclusivity in Antwerp and Ghent corridors to lock out subscription-model entrants. Secure multi-year cell supply agreements with South Korean producers before EU Battery Regulation recycled content thresholds tighten. Vertical integration into domestic battery pack assembly mitigates currency exposure and lead time volatility from East Asian imports. For New Entrants and Emerging Players: Launch via battery subscription unbundling to reduce upfront price barriers for Wallonia's underpenetrated individual consumer segment. Target Liège and Namur provinces for greenfield assembly sites enabling same-day distribution to Luxembourg and French border markets. White space sits with corporate fleet electrification mandates in Brussels-Capital Region where Low Emission Zone compliance deadlines accelerate procurement. For Investors and Strategic Acquirers: Re-rating potential sits with domestic assemblers possessing secured cell supply and EU Battery Regulation compliance infrastructure given regulatory barrier elevation. Long-term viability favors vertically integrated specialists with captive battery management system development and recycling partnership networks. Signal to watch: Flemish government cycle highway allocation decisions indicating demand trajectory inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Subscription Unbundling | Direct-to-consumer platforms capture recurring revenue while reducing upfront price barriers for individual buyers. |
| Corporate Fleet Electrification Partnership | HR mobility budget administrators consolidate procurement volume and standardize service level expectations across Flemish employers. |
| Domestic Assembly Footprint Expansion | Walloon greenfield sites near French and Luxembourg logistics nodes reduce import dependency for southern retail channels. |
| EU Battery Regulation Compliance Investment | Carbon footprint documentation and recycling partnership networks secure market access before delegated acts tighten. |
| Dealer Network Control Consolidation | Exclusive servicing agreements in Antwerp and Ghent corridors lock out emerging subscription-model competitors. |
Study Parameters
Independent corroboration across OEM procurement directors, dealer network operators, and mobility budget platform administrators underwrites the qualitative findings. Primary fieldwork engaged fleet managers at last-mile logistics operators, HR benefits coordinators, and aftermarket service technicians. Secondary validation drew from EU Battery Regulation delegated acts, Flemish government infrastructure allocation disclosures, and UNECE type-approval documentation. Bottom-up shipment data triangulates against top-down mobility budget expenditure flows.
Rate-of-change decomposition separates volume growth from mix shift and pricing evolution across the analysis window. Segmentation dimensions model product type, battery chemistry, use case, and end user organizational structure. CAGRs derive from logistic curve fitting to employer subsidy program expansion trajectories and fleet conversion timelines. Forecast inputs incorporate Flemish cycle highway completion schedules and Brussels-Capital Region Low Emission Zone phase-in dates.
Subsidy threshold adjustments, cell supply disruption events, and public transit network expansion are the dominant revision risks. Forecasts reflect documented assumptions on employer participation rates and infrastructure completion timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
Singapore Electric Vehicle Market
Electric Vehicles
South America Electric Bus Market
Electric Vehicles
US Electric Vehicle Market
Electric Vehicles
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
Global Electric Cars Market
Electric Vehicles
Automotive Battery Packs Market
Electric Vehicles
Battery-Only Electric Bus Market
Electric Vehicles
E-Bike Lithium-Ion Battery Market
Electric Vehicles
Embedded System for Electric Vehicle Market
Electric Vehicles
EV Thermal Management System Market