
 Folding E-Scooter Market | 2026-2036
Folding E-Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Folding E-Scooter Market Foresight
The folding e-scooter category is repositioning around a widening gap between premium connected models and basic commuter units. Segway-Ninebot leverages its patent portfolio to dominate the smart connectivity tier, while Xiaomi Corporation anchors volume production through manufacturing scale across multiple price bands. Unagi Scooters differentiates through design-forward lightweight frames that command higher margins in North American urban markets.
A folding e-scooter is a collapsible personal electric vehicle with a hinged stem and deck mechanism, typically incorporating brushless hub motors rated between 250W and 500W and lithium-ion battery packs with energy densities enabling 15-40 mile ranges per charge. The device serves last-mile transit and daily commuting applications where portability and multimodal integration outweigh conventional bicycle utility. Lightweight frame configurations lead unit shipments due to carry-friendly weights under 30 pounds, while smart connectivity technology captures disproportionate margin pools through subscription-enabled firmware and theft-recovery services. Heavy-duty frame variants remain a smaller but defensible niche serving delivery personnel who prioritize load capacity over fold compactness.
The EU Green Deal and F-Gas Regulation shape battery chemistry transitions and end-of-life recycling obligations for manufacturers selling into European markets. The US Consumer Product Safety Commission and FAA maintain distinct frameworks governing maximum battery watt-hour limits for air travel and minimum safety certifications for retail distribution. Stakeholders must monitor how diverging national micromobility ordinances around sidewalk riding permissions and parking infrastructure will channel demand toward specific motor power and weight classes.
Market Dynamics
EU Green Deal subsidy restructuring is bifurcating demand between premium connected units qualifying for micromobility incentives and basic models excluded from rebate programs.
Growth Catalysts
- EU Green Deal micromobility subsidies:Member states including Germany, France, and the Netherlands redirect transport infrastructure budgets toward personal electric vehicle incentives, expanding addressable demand for folding e-scooters in urban commuter segments.
- Lithium-ion energy density improvements:Battery pack gravimetric density advances extend single-charge range thresholds from 15 miles toward 40 miles, reducing range anxiety among last-mile transit users.
- Brushless hub motor efficiency gains:250W to 500W motor configurations achieve higher torque-to-weight ratios, enabling lighter frame designs under 30 pounds that satisfy carry-friendly portability requirements.
Market Restraints
- Lithium carbonate price volatility:Raw material input cost swings compress margin structures for battery pack manufacturers serving the mid-tier segment.
- Cell supply concentration in East Asian production:Cylindrical and prismatic cell manufacturing clusters create single-source dependency risks for European and North American assembly operations.
- FAA watt-hour limits for air travel:Maximum 100Wh battery restrictions constrain product design for travel-oriented folding e-scooter variants targeting business commuter segments.
Strategic Opportunities
- Subscription-enabled firmware services:Theft-recovery and over-the-air performance tuning create recurring revenue streams atop hardware margins in North American urban markets.
- Delivery personnel load-capacity segments:Heavy-duty frame variants with reinforced decks address underpenetrated commercial last-mile logistics applications.
- F-Gas Regulation battery chemistry transitions:EU end-of-life recycling obligations accelerate demand for solid-state and sodium-ion alternatives with simplified material recovery profiles.
Industry Challenges
- CE marking certification timelines:Machinery Directive and EMC compliance testing create 4-6 month product launch delays for new entrants.
- IP fragmentation across hinge mechanisms:Patent thickets around folding stem and deck articulation designs generate licensing complexity for independent manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Folding E-Scooter Market |
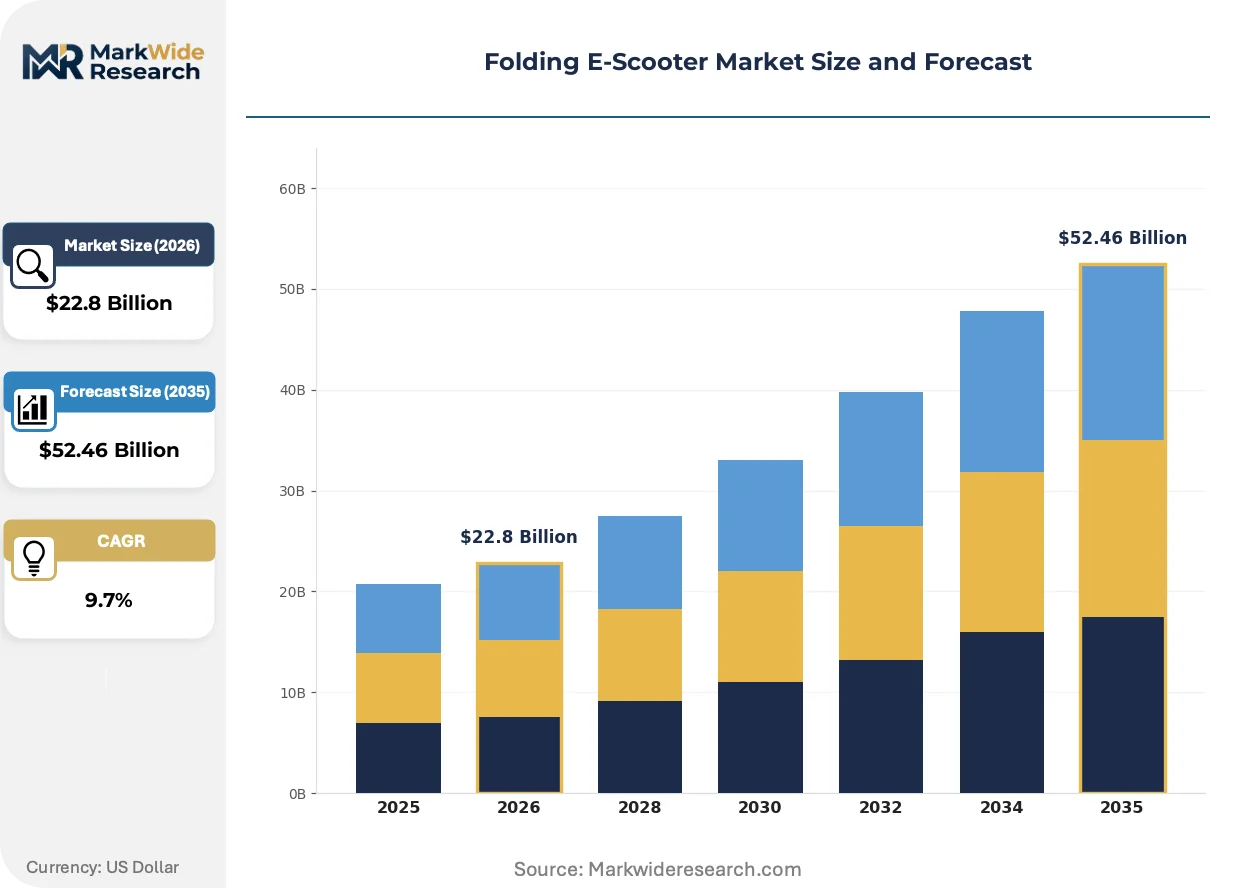
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $52.46 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lightweight Frame, Heavy-Duty Frame, Compact Design, Reinforced Deck Technology: Brushless Motor, Lithium-Ion Battery, Regenerative Braking, Smart Connectivity Application: Last Mile Transit, Commuting, Leisure Riding, Campus Transport End User: Urban Commuters, Delivery Personnel, Students, Recreational Riders |
| Companies Covered | Xiaomi Corporation, Segway-Ninebot, NIU Technologies, Razor USA, GoTrax, Unagi Scooters, Kaabo, Turboant, Glion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Folding E-Scooter Market Shifts & Advancements
Three distinct vectors are restructuring competitive advantage: embedded connectivity architectures, regulatory chemistry mandates, and service-layer monetization.
Solid-state battery prototypes are integrating into premium tier development pipelines. Early adopters in German and Dutch urban commuter segments test pre-production units with 50% faster charge rates. This chemistry transition is integrating thermal management simplification that reduces enclosure weight and assembly complexity.
EU F-Gas Regulation and parallel battery passport requirements mandate granular material traceability from cell production through end-of-life recovery. Manufacturers serving European markets must redesign supply chain documentation systems to satisfy extended producer responsibility frameworks. The premium connected segment faces the steepest compliance cost absorption.
Urban fleet operators now unbundle hardware purchases from maintenance and insurance subscriptions. Direct-to-consumer channels lose share to micromobility-as-a-service platforms in Paris, Berlin, and Amsterdam. This procurement restructuring concentrates volume with platforms capable of integrating municipal parking compliance APIs.
Folding E-Scooter Market Segmentation
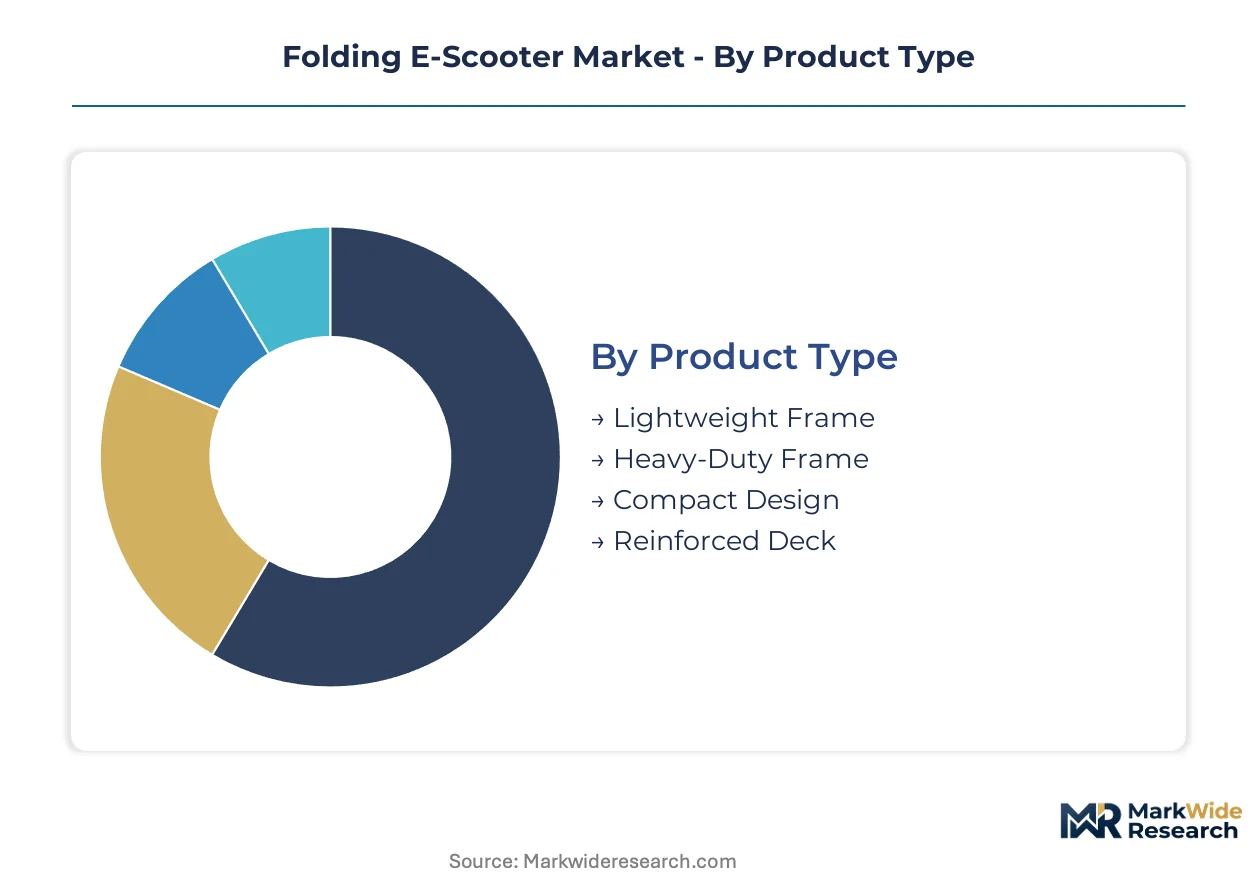
Folding e-scooter segmentation reveals divergent design priorities between carry-optimized portability and load-bearing durability. Buyers trade weight against range, motor torque against fold compactness, and upfront hardware cost against subscription-enabled service layers.
Product Type:
Frame selection hinges on whether the buyer prioritizes multimodal carry convenience or structural load capacity.
- Lightweight Frame:Aluminum alloy and carbon fiber constructions keep unit weight under 30 pounds for stair carry and transit integration. Demand clusters in German and Dutch urban cores where EU Green Deal subsidies favor qualifying micromobility purchases.
- Heavy-Duty Frame:Reinforced steel tubing supports 220-pound-plus payloads with reinforced hinge mechanisms. Delivery personnel in Paris and Berlin drive procurement for commercial last-mile logistics where deck durability outweighs fold compactness.
- Compact Design:Minimalist frame geometry reduces folded footprint to airline cabin dimensions. Business travelers navigating FAA 100Wh battery limits select this tier for multimodal business trips.
- Reinforced Deck:Extended platform surfaces accommodate standing stability for larger riders or small cargo loads. Campus transport operators in French university towns specify this variant for shared fleet durability.
Volume sits with Lightweight Frame configurations; growth tilts toward Heavy-Duty Frame variants as commercial logistics adoption accelerates.
Technology:
Technology stack selection determines margin capture through hardware differentiation versus recurring software revenue.
- Brushless Motor:Hub-mounted direct-drive systems rated 250W to 500W deliver torque-to-weight ratios enabling sub-30-pound frame targets. EU Machinery Directive CE marking requirements extend certification timelines for new motor suppliers entering German and French markets.
- Lithium-Ion Battery:Cylindrical and prismatic cell packs with 15-40 mile range thresholds dominate energy storage. Lithium carbonate price volatility compresses margin structures for mid-tier battery pack assemblers serving European markets.
- Regenerative Braking:Kinetic energy recovery systems extend effective range 8-12% in stop-start urban traffic. Dutch and Belgian commuters on flat terrain gain marginal benefit compared to hill-climbing applications.
- Smart Connectivity:Embedded GPS, theft-recovery firmware, and over-the-air performance tuning enable subscription monetization. North American urban markets show willingness to pay recurring fees atop hardware purchases.
Revenue concentrates with Smart Connectivity tiers; unit shipments expand most quickly in Brushless Motor configurations as efficiency gains enable lighter frame designs.
Application:
Use case segmentation separates daily dependency riders from occasional recreational purchasers with distinct durability and service expectations.
- Last Mile Transit:Multimodal integration with rail and bus networks requires sub-30-pound carry weight and sub-10-second fold mechanisms. Paris, Berlin, and Amsterdam infrastructure investment channels demand toward parking-compliant models.
- Commuting:Daily round-trip reliability above 20 miles per charge with weather-sealed electronics. German KBA type-approval requirements for road-legal operation filter non-compliant imports from volume segments.
- Leisure Riding:Weekend recreational use prioritizes acceleration response and hill-climbing torque over fold compactness. Recreational Riders in Southern European markets favor this application tier.
- Campus Transport:Shared fleet deployment on university grounds with centralized charging infrastructure. French and Dutch higher education procurement favors ruggedized variants with simplified maintenance access.
Procurement volume clusters in Last Mile Transit; Commuting applications show steepest expansion trajectory as EU Green Deal subsidies restructure personal mobility incentives.
End User:
User type determines whether purchase decisions emphasize upfront acquisition cost or total cost of ownership across service life.
- Urban Commuters:Daily multimodal travelers in German, French, and Dutch metropolitan areas. EU Green Deal micromobility subsidies reduce effective purchase price for qualifying connected models.
- Delivery Personnel:Commercial last-mile logistics operators prioritizing deck load capacity and battery swap compatibility over fold speed. Heavy-Duty Frame variants with reinforced hinges serve this segment.
- Students:Price-sensitive campus residents selecting entry-tier models for short-distance mobility. Campus Transport fleet subscriptions increasingly displace individual ownership in university towns.
- Recreational Riders:Occasional weekend users with lower annual mileage and reduced durability requirements. Leisure Riding applications in Southern European markets attract this user base.
Urban Commuters anchor unit volume; Delivery Personnel represent the fastest-growing end-user category as commercial logistics electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangtze River Delta manufacturing corridor supplies brushless hub motors and lithium-ion battery packs to assembly plants across three continents. Shenzhen's electronics ecosystem produces smart connectivity modules that enable theft-recovery firmware and over-the-air performance tuning. These Chinese industrial clusters anchor upstream component flows while final assembly and brand distribution concentrate in Germany, the Netherlands, and the United States.
Germany
Berlin and Munich urban commuters drive premium connected model adoption through KBA type-approval requirements that filter non-compliant imports. EU Green Deal micromobility subsidies reduce effective purchase prices for qualifying smart connectivity tiers. Stuttgart's automotive supplier ecosystem repurposes brushless motor engineering talent toward lightweight frame designs under 30 pounds.
Netherlands
Amsterdam and Rotterdam infrastructure investment channels demand toward parking-compliant models with sub-10-second fold mechanisms. Dutch flat terrain reduces regenerative braking benefit compared to hill-climbing applications, shifting specification priorities toward weight minimization. Eindhoven's high-tech systems sector supplies embedded GPS and theft-recovery firmware for subscription-enabled service layers.
France
Paris delivery personnel procurement accelerates heavy-duty frame variants with reinforced decks for commercial last-mile logistics. ANSM and CNIL oversight shapes data governance for connected fleet operators managing municipal parking compliance APIs. Lyon and Toulouse university towns specify ruggedized campus transport variants with simplified maintenance access for shared fleet deployment.
United States
New York and San Francisco urban commuters navigate FAA 100Wh battery limits for air travel-oriented compact designs. CPSC safety certification frameworks govern minimum thresholds for retail distribution across mass-market channels. Los Angeles micromobility-as-a-service platforms concentrate procurement volume with operators capable of integrating insurance and maintenance subscriptions.
China
Shenzhen and Dongguan manufacturing clusters produce cylindrical and prismatic cells that create single-source dependency risks for European and North American assembly operations. MIIT standards and dual carbon goals accelerate domestic demand for solid-state battery prototypes with 50% faster charge rates. Zhejiang and Jiangsu provinces host final assembly operations serving export markets through Ningbo and Shanghai port corridors.
Folding E-Scooter Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered structure where manufacturing scale, patent portfolios, and service-layer monetization separate sustainable positions from commodity pressure. The vendor base fragments across three strategic archetypes: vertically integrated electronics conglomerates controlling upstream cell supply, design-forward specialists commanding premium margins through lightweight engineering, and value-optimized assemblers competing on unit economics in mass-market channels. Dominant competitive moves include M&A to secure hinge mechanism IP and strategic partnerships with micromobility-as-a-service platforms for fleet procurement concentration.
Within the patent-protected connectivity tier, Segway-Ninebot exemplifies intellectual property leverage through its smart firmware ecosystem. Xiaomi Corporation occupies a position as a scale-driven assembler spanning multiple price bands through manufacturing volume. Unagi Scooters represents the design-forward archetype with lightweight frame specialization for North American urban markets. These three anchors illustrate how competitive positioning stratifies across hardware commodification, software subscription capture, and aesthetic differentiation vectors.
| Leading Market Players |
|---|
| Xiaomi Corporation |
| Segway-Ninebot |
| NIU Technologies |
| Razor USA |
| GoTrax |
| Unagi Scooters |
| Kaabo |
| Turboant |
| Glion |
| Others |
Supply & Pricing Matrix
Premium smart connectivity tiers and basic commuter units diverge sharply in both pricing architecture and supply chain configuration, with EU Green Deal subsidy eligibility filtering procurement toward connected models whose firmware-enabled service layers command recurring revenue atop hardware margins. Lithium-ion battery pack costs concentrate pricing pressure in mid-tier segments where raw material volatility compresses assembler margins without the offset of subscription monetization.
Pricing Analysis
Value-based pricing anchored to theft-recovery uptime and firmware-enabled performance tuning separates premium connected tiers from commodity hardware. Pricing stratifies across premium, standard, and economy tiers based on smart connectivity certification levels and geographic delivery infrastructure. Cost compression in mid-tier battery packs is intensifying because lithium carbonate volatility erodes assembler margins. Students and recreational riders exhibit highest price sensitivity, while urban commuters in subsidized EU markets show lowest sensitivity due to rebate-adjusted effective pricing.
Supply Chain Analysis
Dual-sourcing requirements for cylindrical and prismatic cells are mandating multi-supplier qualification programs among European and North American assemblers seeking to reduce dependency risks. Cell production concentrates in China, South Korea, and Japan, while brushless hub motor manufacturing clusters in Zhejiang and Jiangsu provinces. Raw material dependencies span lithium carbonate, nickel sulfate, and rare-earth magnets for motor assemblies. Single-source vulnerability in East Asian cell supply creates structural risk. Distribution runs through direct-to-consumer channels and micromobility-as-a-service platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The folding e-scooter market sits in a technology-transition phase as solid-state battery chemistry displaces conventional lithium-ion architectures across premium development pipelines.
For Market Incumbents: Anchor market position through captive supply of solid-state cell prototypes and CE marking certification investment ahead of EU F-Gas Regulation enforcement. Threat from emerging design-forward specialists with lightweight carbon fiber engineering demands defensive patent licensing around hinge mechanisms. Vertical integration into theft-recovery firmware development preserves subscription revenue streams. For New Entrants and Emerging Players: Begin with heavy-duty frame variants for Paris and Berlin delivery personnel, the most penetrable commercial segment underserved by incumbent carry-optimized designs. Campus transport fleet subscriptions in French university towns offer second white-space target. Go-to-market angle should emphasize battery swap compatibility and simplified maintenance access. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by automotive supplier ecosystems repurposing motor engineering talent toward micromobility applications. Long-term viability favors targets with solid-state battery partnerships and municipal parking compliance API integration. Signal to watch is ANSM and CNIL data governance enforcement tightening compliance costs for connected fleet operators.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Battery Integration | 50% faster charge rates enable premium tier differentiation in German commuter segments. |
| CE Marking Certification Investment | Machinery Directive compliance filters non-compliant imports from German and French volume channels. |
| Subscription Firmware Development | Theft-recovery services create recurring revenue streams in North American urban markets. |
| Micromobility-as-a-Service Partnership | Paris, Berlin, and Amsterdam fleet procurement concentrates volume with platform-integrated suppliers. |
| Heavy-Duty Frame Capacity Expansion | Reinforced deck variants address underpenetrated commercial logistics in Paris delivery corridors. |
Research Methodology
Multi-period observation of EU Green Deal subsidy disbursement patterns, lithium carbonate price indices, and micromobility infrastructure investment flows anchored the trend analysis, supplemented by interviews with product development leads at tier-1 assemblers, procurement officers at micromobility-as-a-service platforms, regulatory affairs specialists navigating CE marking pathways, and fleet operations managers at university transport departments. Secondary validation drew from EU transport subsidy databases, MIIT standards filings, FAA battery guidance documents, and customs trade records. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segment-weighting approaches applied differential growth assumptions across lightweight frame, heavy-duty frame, and compact design product categories, with technology tiers modeled separately for brushless motor efficiency classes and smart connectivity penetration rates. Application segmentation distinguished last-mile transit, commuting, leisure riding, and campus transport use cases with distinct replacement cycles and durability requirements. CAGRs derived from regression analysis of historical adoption curves adjusted for subsidy phase-in schedules and battery chemistry transition timelines. Forecast inputs incorporated KBA type-approval timelines and F-Gas Regulation compliance cost absorption rates.
Underlying measurement precision varies by segment; premium connected tiers with disclosed subscription revenue carry tighter precision than gray-market basic units. Forecasts reflect assumptions around EU subsidy continuity, lithium supply expansion, and solid-state battery commercialization timelines. Deviation in CE marking enforcement stringency or FAA battery limit revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
Electric Vehicle Liquid Cold Plates Market
Electric Vehicles
Electric Vehicle Air Conditioning Market
Electric Vehicles
EV Condenser Market
Electric Vehicles
Electric Delivery Vans Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
EV Platform Market
Electric Vehicles
Electric Bicycle Market
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
Solar E-Bike Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
Electric Van Market
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
Light Electric Vehicle Market
Electric Vehicles
Special Purpose Electric Vehicle Market