
 Electric Shuttle Market | 2026-2036
Electric Shuttle Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Shuttle Market Analytics
Subscription-based fleet management software is realigning what shuttle operators purchase, shifting capital expenditure toward per-mile service contracts. BYD Company Ltd. leverages its integrated battery manufacturing to control unit economics across airport and campus deployments. Yutong Bus Co., Ltd. anchors its position through high-volume production lines purpose-built for electric shuttle platforms. Proterra Inc. specializes in proprietary drivetrain architectures that differentiate its vehicles in medium-duty transit segments.
An electric shuttle is a battery-electric vehicle designed for fixed-route or on-demand passenger transport, typically operating at speeds below 50 mph with ranges from 80 to 300 miles depending on battery configuration and duty cycle. These vehicles employ lithium-ion phosphate or nickel-manganese-cobalt cell chemistries assembled into modular packs that enable rapid swap or conductive charging protocols. Passenger shuttles dominate current fleet procurement volumes, while autonomous shuttles represent the fastest-expanding segment as lidar and V2X infrastructure matures. Public transport authorities constitute the deepest margin pool due to multi-year procurement frameworks and total-cost-of-ownership contracting models.
The EPA tailpipe emission standards and NHTSA fuel economy regulations are accelerating diesel shuttle phase-outs across United States transit networks. California Air Resources Board zero-emission bus mandates are creating de facto national product specifications that manufacturers must satisfy for market access. FAA ground support equipment electrification directives at major airports are expanding the addressable fleet base. Stakeholders must monitor how battery passport traceability requirements and domestic content thresholds reshape supplier qualification criteria.
Market Dynamics
Zero-emission mandates from airport authorities and municipal transit agencies are compressing procurement cycles for diesel shuttle replacements, forcing manufacturers to reconfigure production lines around battery-electric architectures before charging infrastructure matures.
Growth Catalysts
- California Air Resources Board zero-emission bus mandates:These regulations create de facto national specifications that manufacturers must satisfy for fleet access, accelerating product standardization across North American deployments.
- Last-mile connectivity demand:Municipal transit agencies in Texas and Florida are expanding electric shuttle networks to bridge gaps between rail stations and residential zones.
- Solid-state battery prototyping:Energy density improvements in next-generation cell chemistries are extending operational range without increasing pack weight or vehicle footprint.
Market Restraints
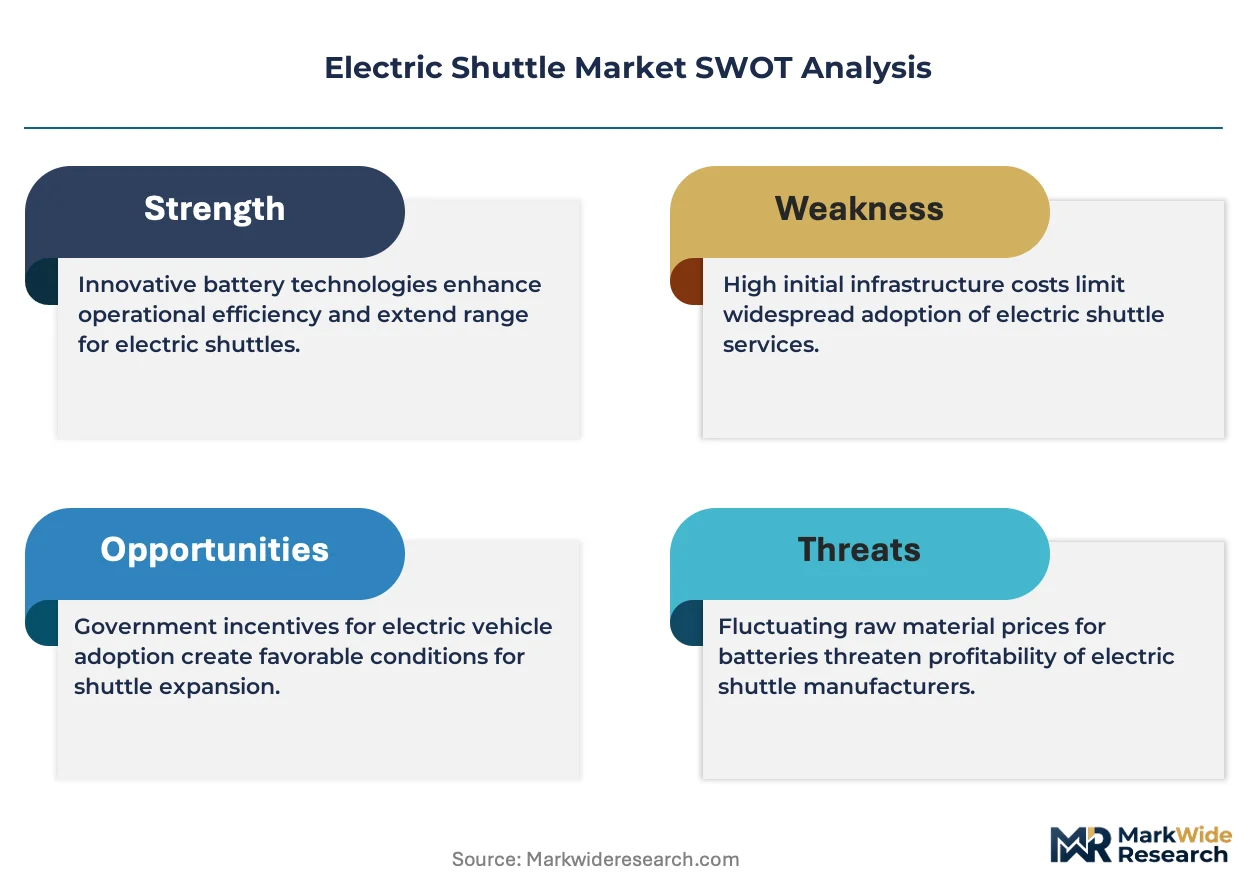
- Lithium carbonate price volatility:Raw material input swings compress margin predictability for battery pack assemblers and vehicle integrators alike.
- Charging infrastructure concentration:Depot charging hardware suppliers cluster in East Asian manufacturing hubs, creating single-source vulnerability for North American fleet operators.
- Thermal management limitations:Extreme climate operation degrades lithium-ion phosphate performance, restricting deployment latitude without active conditioning systems.
Strategic Opportunities
- Autonomous shuttle corridors:Dedicated right-of-way deployments in planned communities and corporate campuses bypass mixed-traffic regulatory complexity.
- FAA ground support equipment electrification directives:Airport authority procurement frameworks expand the addressable fleet base for airside passenger transport vehicles.
- V2X infrastructure convergence:Integration of vehicle-to-everything communication with traffic signal prioritization enables headway compression on fixed routes.
Industry Challenges
- High-voltage technician certification gaps:Fleet maintenance departments lack personnel qualified for battery pack diagnostics and module replacement protocols.
- Multi-year procurement framework alignment:Public transit authority bidding cycles misalign with battery technology refresh rates, creating specification obsolescence risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Shuttle Market |
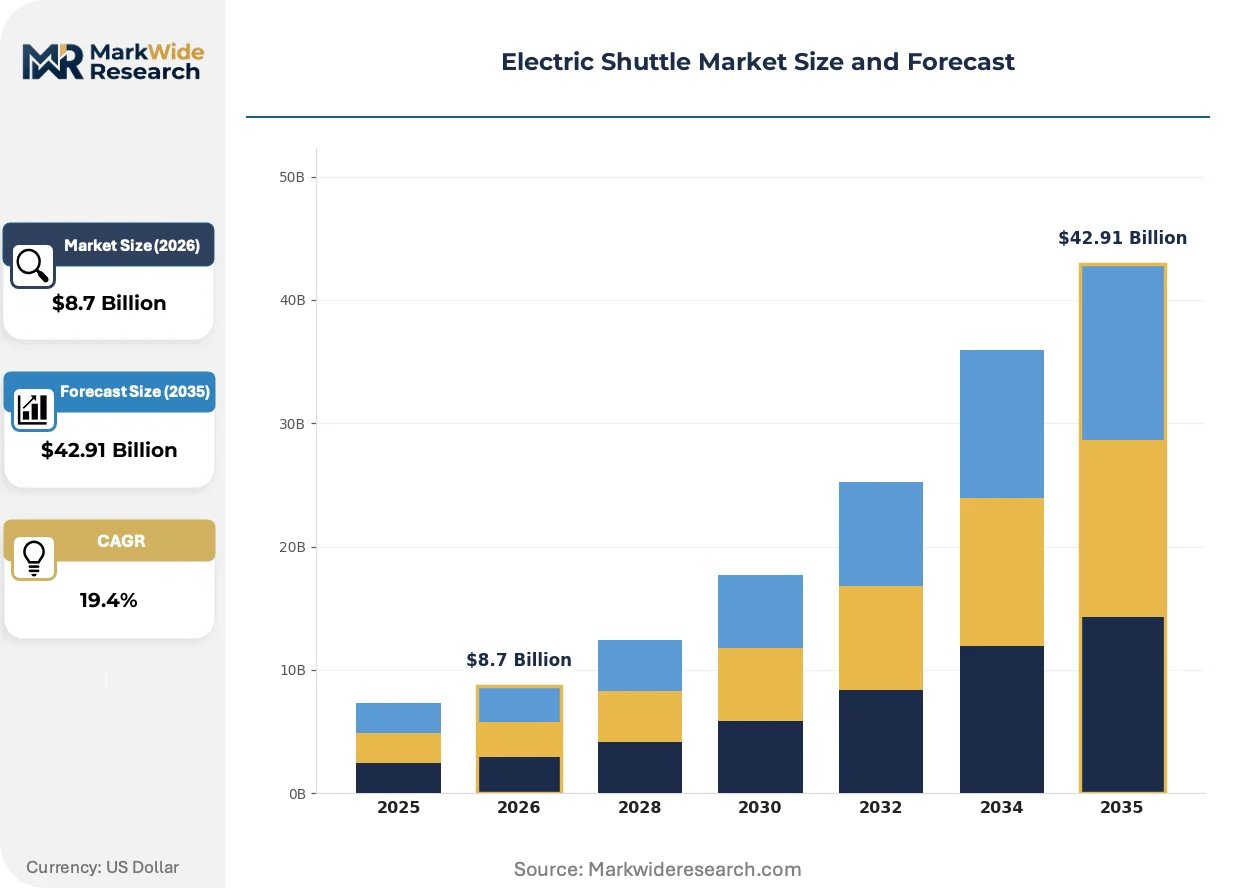
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Shuttles, Cargo Shuttles, Autonomous Shuttles, Electric Buses End User: Public Transport Authorities, Corporate Mobility Services, Educational Institutions, Hospitality Services Range: Short-Range, Medium-Range, Long-Range, Ultra-Long-Range Charging Infrastructure: Fast Charging Stations, Wireless Charging, Regular Charging Stations, Battery Swapping |
| Companies Covered | BYD Company Ltd., Yutong Bus Co., Ltd., CRRC Corporation Limited, NFI Group, Volvo Group, Proterra Inc., VDL Groep, Blue Bird Corporation, GreenPower Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Shuttle Market Evolving Landscape
Shuttle electrification is accelerating faster than charging infrastructure deployment, creating interim operational models that rely on opportunity charging and battery swap systems rather than overnight depot replenishment.
Silicon-carbide power electronics are electrifying drivetrain efficiency in medium-duty shuttle platforms. Airport ground transportation fleets are adopting these inverter technologies to extend range without expanding battery mass. The shift is electrifying competitive differentiation around energy consumption per passenger-mile rather than upfront vehicle cost.
EPA tailpipe emission standards are tightening compliance windows for diesel shuttle phase-outs across United States transit networks. Fleet operators must accelerate replacement schedules or face operating restriction penalties. California's regulatory stringency is propagating eastward as other states adopt identical zero-emission certification thresholds.
Subscription-based fleet management software is restructuring how shuttle operators acquire vehicle capability. Municipal transit agencies now favor per-mile service contracts that transfer battery degradation risk to manufacturers. This preference is most visible in California procurement frameworks where total-cost-of-owne
Electric Shuttle Market Segmentation
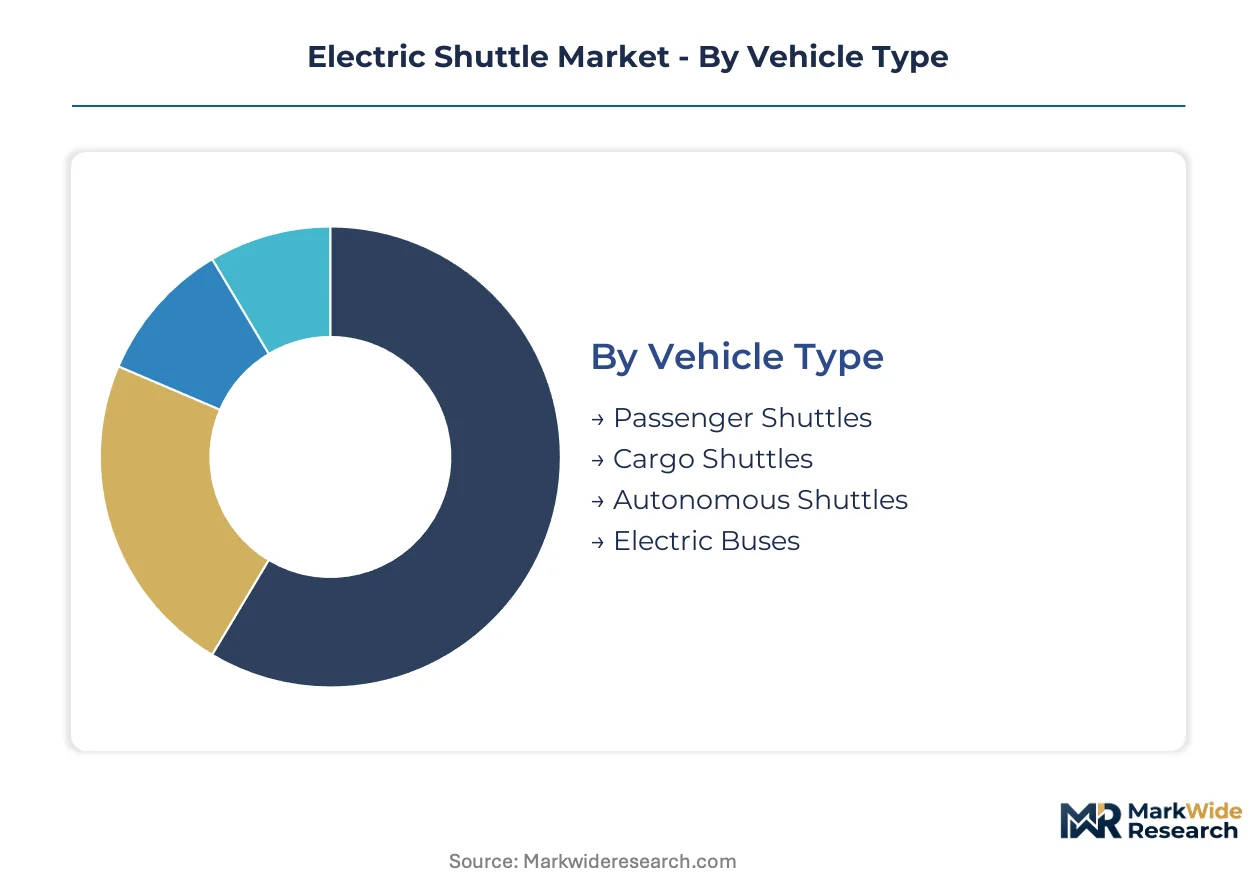
Electric shuttle procurement patterns diverge sharply across duty cycles and infrastructure availability, forcing manufacturers to maintain parallel product architectures. Fleet operators select vehicle configurations based on route density, passenger volume, and depot charging constraints rather than upfront acquisition cost alone.
Vehicle Type:
Fleet procurement decisions pivot on passenger capacity requirements and automation readiness rather than platform commonality.
- Passenger Shuttles:Fixed-route vehicles with 12-40 seat configurations dominate municipal transit and airport ground transportation procurement. California transit agencies specify these for last-mile rail connections under zero-emission mandates, with lithium-ion phosphate packs optimized for high-cycle depot charging.
- Autonomous Shuttles:Low-speed pod vehicles operating on dedicated right-of-way corridors bypass mixed-traffic regulatory barriers. Corporate campuses in Texas and planned communities in Florida deploy these for circulator services where V2X infrastructure enables signal prioritization.
- Cargo Shuttles:Flatbed and enclosed freight variants serve airport logistics and urban delivery consolidation points.
- Electric Buses:Higher-capacity platforms overlap with transit bus segments but retain shuttle-class duty cycles and charging protocols.
Volume sits with Passenger Shuttles; growth tilts toward Autonomous Shuttles.
End User:
Contracting structures determine margin capture, with multi-year service agreements concentrating value in public sector frameworks.
- Public Transport Authorities:Municipal agencies in California, Texas, and Florida drive fleet-scale procurement through total-cost-of-ownership contracts that transfer battery degradation risk to manufacturers. EPA tailpipe standards and CARB zero-emission bus mandates compress replacement timelines for diesel shuttle retirements.
- Corporate Mobility Services:Technology and financial services campuses deploy private shuttle networks for employee transportation, favoring subscription-based fleet management software over capital purchase.
- Educational Institutions:University transit systems prioritize student safety and route flexibility over capacity optimization.
- Hospitality Services:Resort and hotel operators select premium-configuration shuttles for guest experience differentiation.
Procurement volume clusters with Public Transport Authorities; margin expansion favors Corporate Mobility Services.
Range:
Battery pack sizing decisions trade capital cost against route flexibility and charging infrastructure investment.
- Medium-Range:150-250 mile configurations balance battery mass with operational coverage for suburban transit loops and airport hotel circuits. Texas municipal agencies specify these for rail feeder services where midday opportunity charging extends effective duty cycles.
- Long-Range:250-300 mile packs enable single-shift operation without interim charging, critical for rural transit authorities and inter-campus connectors where depot infrastructure remains underdeveloped.
- Short-Range:Sub-150 mile variants serve dense urban cores with ubiquitous charging access.
- Ultra-Long-Range:300+ mile configurations address specialized airport airside and remote facility access routes.
Medium-Range configurations anchor current fleet procurement; Long-Range demand accelerates as charging infrastructure lags route expansion.
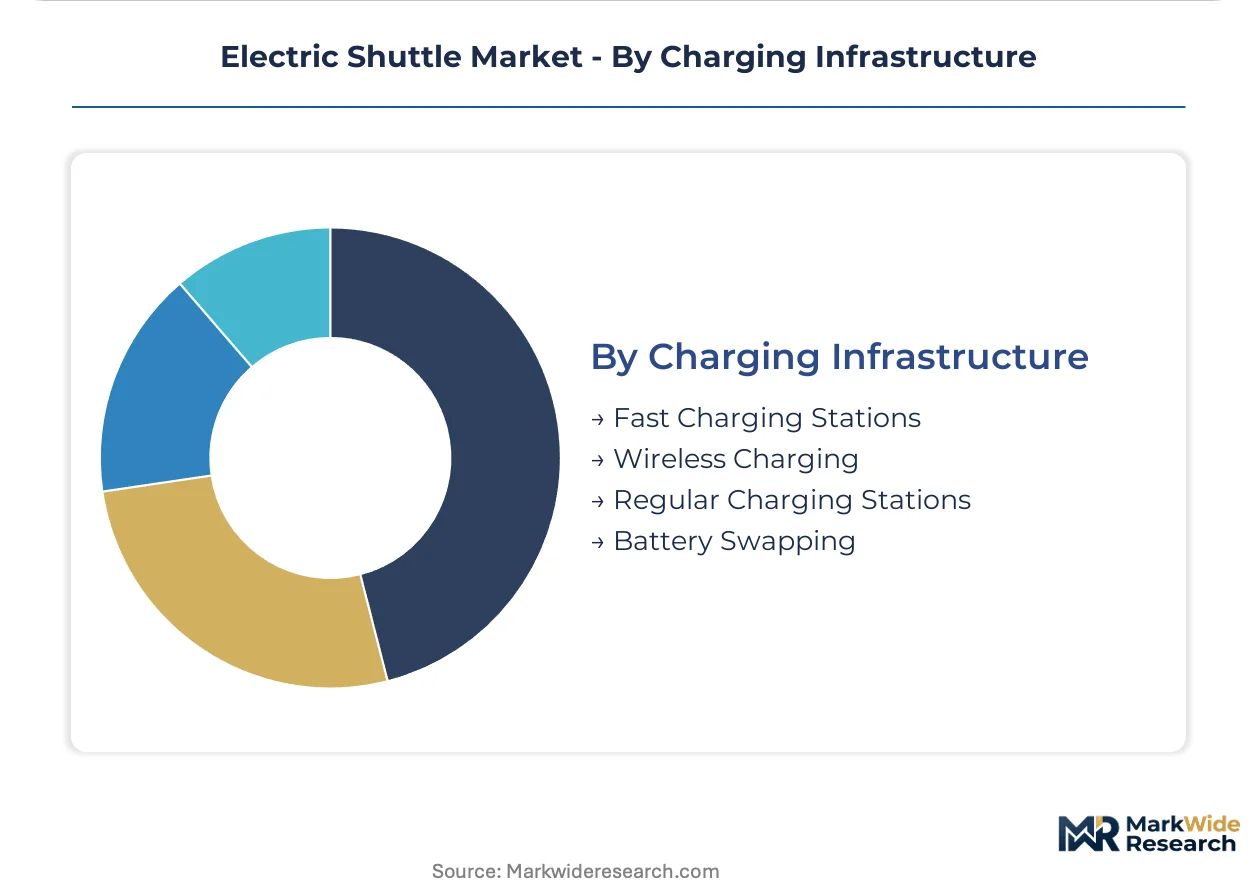
Charging Infrastructure:
Hardware selection constrains vehicle design and operational scheduling more than any other technical parameter.
- Fast Charging Stations:150-350 kW conductive systems enable 30-minute replenishment during driver breaks, compressing fleet asset utilization. Florida transit agencies deploy these at route termini to extend effective range without expanding battery mass.
- Battery Swapping:Automated pack exchange systems eliminate dwell time entirely, requiring standardized module architectures across fleet operators. Chinese manufacturing clusters dominate swap station hardware supply, creating procurement concentration risk for North American operators.
- Regular Charging Stations:Overnight depot AC charging remains baseline for predictable fixed-route operations.
- Wireless Charging:Inductive pad systems at bus stops enable continuous opportunity charging without driver intervention.
Fast Charging Stations capture procurement volume; Battery Swapping gains traction where route density justifies infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Chinese industrial zones while fleet deployment concentrates in North American and European transit authorities with aggressive electrification mandates. This production-consumption divide shapes trade flows and supplier qualification requirements across the value chain.
United States
California transit agencies drive fleet-scale procurement through total-cost-of-ownership contracts that transfer battery degradation risk to manufacturers. EPA tailpipe emission standards and FAA ground support equipment directives compress diesel shuttle replacement timelines at major airports. Texas municipal agencies in Dallas and Houston expand medium-range electric shuttle networks for last-mile rail connectivity.
China
Integrated battery manufacturers control unit economics across domestic and export shuttle deployments through captive cell supply. MIIT new energy vehicle mandates and dual carbon goals accelerate domestic fleet electrification in Beijing and Shanghai. Zhengzhou and Shenzhen anchor high-volume production lines purpose-built for electric shuttle platforms serving global markets.
Germany
Automotive engineering heritage translates into precision manufacturing of electric drivetrain components for medium-duty shuttle segments. KBA type-approval standards and EU Green Deal zero-emission vehicle mandates align procurement specifications across municipal transit authorities. Bavaria and Baden-Württemberg concentrate R&D facilities developing silicon-carbide power electronics for next-generation shuttle platforms.
Japan
Advanced materials suppliers develop solid-state battery prototypes to extend operational range without increasing pack weight. METI carbon neutrality roadmaps and JIS standards for electric commercial vehicles create regulatory certainty for fleet operators. Kanto region manufacturing clusters around Tokyo and Nagoya specialize in thermal management systems for extreme climate operation.
India
Rapid urbanization and air quality mandates in Delhi-NCR and Maharashtra accelerate electric shuttle deployment for public transit and corporate mobility. PLI scheme incentives for advanced chemistry cell manufacturing attract domestic battery assembly investment. Karnataka and Tamil Nadu industrial corridors emerge as assembly hubs for airport and campus shuttle variants.
Electric Shuttle Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the electric shuttle value chain, with integrated battery manufacturers holding structural advantages in unit economics. The vendor base stratifies into three tiers: full-stack producers controlling cell-to-vehicle integration, chassis specialists sourcing battery packs from third-party suppliers, and autonomous software layers licensing perception stacks to hardware partners. Consolidation pressure intensifies as public transit procurement frameworks favor multi-year service contracts requiring balance sheet depth. Dominant competitive moves include backward integration into battery cell manufacturing and strategic partnerships with charging infrastructure providers.
Within the integrated manufacturing tier, BYD Company Ltd. and Yutong Bus Co., Ltd. exemplify capital-heavy structures with captive battery supply chains. Proterra Inc. occupies a specialist position in proprietary drivetrain architectures for medium-duty transit applications. These three anchors represent divergent strategic postures: full vertical integration, high-volume platform standardization, and technology differentiation through power electronics specialization.
| Leading Market Players |
|---|
| BYD Company Ltd. |
| Yutong Bus Co., Ltd. |
| CRRC Corporation Limited |
| NFI Group |
| Volvo Group |
| Proterra Inc. |
| VDL Groep |
| Blue Bird Corporation |
| GreenPower Motor Company |
| Others |
Value Network & Pricing Analysis
Sovereign-backed battery manufacturers from China anchor upstream supply positions, compressing margin capture for Western vehicle integrators while enforcing pricing discipline through captive lithium carbonate sourcing and state-subsidized cell production.
Pricing Analysis
Margin tightening in mid-range passenger shuttles reflects lithium carbonate price volatility and CARB compliance certification costs. Three-tier pricing structure across premium, standard, and economy levels segments buyers by fleet scale and after-sales service bundling. Cost-down pressure on standard-tier configurations accelerates because municipal transit agencies shift toward per-mile service contracts that transfer battery degradation risk. Public transport authorities exhibit highest price sensitivity; corporate campus operators accept premium pricing for autonomous-ready platforms.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from California and Texas transit authorities, while dealer networks serve fragmented campus and hospitality segments. Cell manufacturing concentrates in China, South Korea, and Japan; pack assembly clusters in Zhengzhou and Shenzhen for export markets. Supply chains draw from Chilean lithium, Indonesian nickel, and synthetic graphite from Heilongjiang province. Single-source vulnerability in fast-charging hardware from East Asian suppliers exposes North American fleet operators to logistics chokepoint risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electric Shuttle Market operates as a cost-of-compliance arena where EPA tailpipe standards and CARB zero-emission mandates erect regulatory moats that favor incumbent producers with certified platform architectures and balance sheet depth for multi-year service contracting.
For Market Incumbents: Acquire high-voltage technician training networks to close maintenance capability gaps that constrain fleet operator adoption. Defensive consolidation should prioritize battery swap station operators in Texas and Florida corridors, and deepen in-house production of silicon-carbide inverters to differentiate drivetrain efficiency against emerging drivetrain specialists.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in autonomous shuttle software layers offers white-space entry for asset-light perception stack developers. Target corporate campus circulator contracts in planned communities where V2X infrastructure enables signal prioritization without mixed-traffic regulatory complexity. Position through subscription-based fleet management partnerships rather than capital-heavy vehicle manufacturing.
For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed battery pack assemblers with stranded lithium-ion phosphate capacity in East Asian manufacturing hubs. Long-term viability hinges on solid-state chemistry transitions and domestic content qualification for US federal procurement. Watch FAA ground support equipment electrification directive implementation timelines as fleet replacement inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Captive lithium carbonate sourcing from Chilean offtake contracts secures cell cost predictability for California fleet deployments. |
| Charging Infrastructure Partnership | Fast-charging hardware co-development with Florida transit agencies extends route range without expanding battery mass. |
| Software-Defined Vehicle Investment | Over-the-air update capability enables autonomous feature activation post-delivery, deferring regulatory certification costs. |
| Platform Standardization | Modular pack architectures compatible with battery swap systems reduce fleet downtime for Texas municipal operators. |
| Geographic Manufacturing Footprint | Assembly presence in Karnataka industrial corridors qualifies for Indian PLI scheme incentives and airport procurement frameworks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fleet procurement managers at California transit agencies, airport ground transportation directors, battery pack engineering leads, charging infrastructure deployment specialists, and CARB certification consultants. EPA enforcement databases, FAA ground support equipment directives, MIIT new energy vehicle production statistics, and UN Comtrade lithium carbonate flow records provided demand-side validation. Bottom-up vehicle deployment tallies triangulated against top-down market sizing from transit authority capital expenditure disclosures.
Granularity-level modeling distinguished passenger shuttle, autonomous shuttle, and cargo shuttle configurations; segmented by range tier, charging infrastructure type, and end-user contracting structure across the analysis window. CAGRs derived from logistic diffusion curves fitted to zero-emission mandate compliance timelines and battery cost experience curves. Forecast inputs incorporated lithium carbonate price scenario bands and charging infrastructure deployment lag assumptions.
Inputs from CARB certification databases and FAA airport electrification reports were available through the study window; gaps in solid-state battery commercialization timelines introduce uncertainty bands around long-range vehicle adoption trajectories. Forecasts reflect documented assumptions regarding mandate enforcement stringency and cell chemistry transition rates. Periodic stress-testing of base assumptions against actual fleet procurement award data is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Global Solar Powered Car Market
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
Electric Vehicle Traction Inverter System Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
Europe Automotive Battery Thermal Management System Market
Electric Vehicles
Electric Vehicle Electronic Expansion Valve (EXV) Market
Electric Vehicles
Canada Solar E-Bike Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
Electric Vehicle (EV) Range Extender Market
Electric Vehicles
Netherlands Solar E-Bike Market
Electric Vehicles
E-SUV Market
Electric Vehicles
Car Battery Chargers Market
Electric Vehicles
Electric Vehicle Battery Enclosure Market
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
Global EV Relay Market