
 China Electric Car Market | 2026-2036
China Electric Car Market Size, Share, and Industry Trends Forecast 2026-2036
China Electric Car Market Analysis
Market Context
The China electric car market is pivoting on a widening split between premium intelligent EVs with advanced driver-assistance systems and commodity battery electric vehicles priced for mass penetration. BYD leverages its in-house blade battery production and semiconductor fabrication to sustain cost leadership across affordable and mid-range tiers. Tesla anchors the premium segment through its Shanghai Gigafactory's manufacturing scale and over-the-air software differentiation. NIO competes on battery-swap infrastructure and user community ecosystems, occupying a service-led niche distinct from hardware-centric rivals.
Technical Definition and Segment Structure
China electric cars are road vehicles propelled by one or more electric motors drawing energy from rechargeable battery packs, typically lithium-ion chemistries with energy densities exceeding 150 watt-hours per kilogram, designed for passenger transport and light commercial duty. Battery Electric Vehicle deployment leads volume, while Plug-in Hybrid Electric Vehicle retains structural importance in charging-infrastructure-constrained inland provinces where range anxiety persists. Solid-state Batteries represent the fastest-growing technology segment, though Lithium-ion Batteries dominate current manufacturing capacity and margin pools. Commercial Fleets constitute the most concentrated demand expansion vector as logistics operators electrify delivery and urban transport assets.
Regulatory Framework
MIIT administers China's New Energy Vehicle mandate credits and GB standards governing battery safety, electromagnetic compatibility, and charging interfaces, while SAMR enforces market access certification and consumer protection protocols. NMPA oversees automotive component quality frameworks that shape supplier qualification and product liability exposure. Stakeholders must monitor evolving dual carbon implementation timelines and credit-trading mechanics that will determine manufacturing quota allocations and technology investment priorities.
Market Dynamics
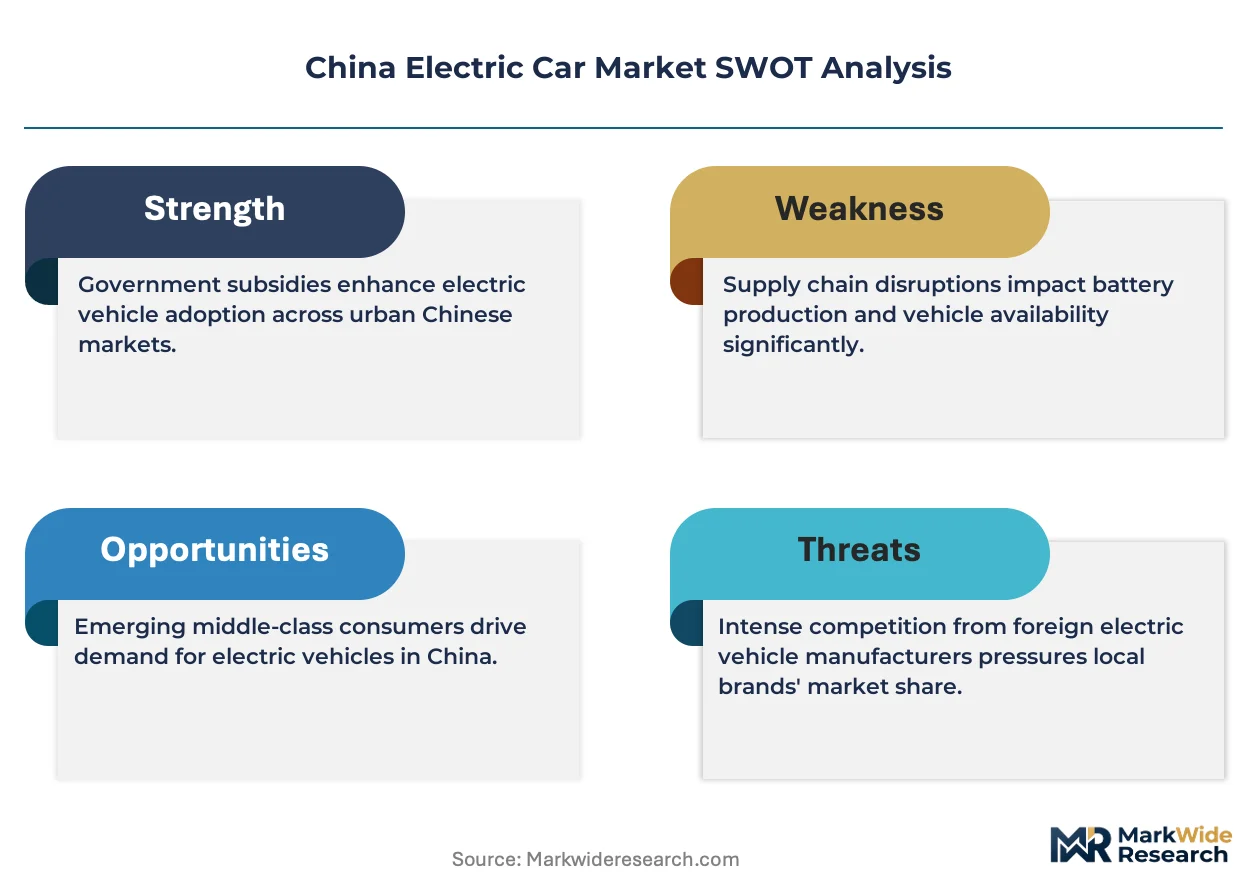
China's electric car market pivots on MIIT's tightening NEV credit thresholds, which force manufacturers to accelerate zero-emission production or purchase credits from rivals, compressing margin structures across mid-tier producers.
Growth Catalysts
- NEV Mandate Credits:MIIT's credit-trading mechanism penalizes ICE-heavy portfolios while rewarding BEV and PHEV output, directing capital toward battery capacity expansion.
- Commercial Fleet Electrification:Logistics operators in the Yangtze River Delta are replacing diesel delivery vans with electric light trucks as total cost of ownership advantages materialize.
- Blade Battery Diffusion:Lithium iron phosphate cell-to-pack architectures are cutting battery costs while improving thermal stability, accelerating mass-market penetration.
Market Restraints
- Lithium Carbonate Volatility:Cathode material input costs swing with spot-market lithium prices, squeezing cell manufacturer margins and forcing pricing recalibration.
- Inland Charging Infrastructure Gaps:Central and western provinces lack high-speed charging density, constraining BEV adoption outside coastal clusters.
- Dual Carbon Compliance Timelines:MEE emission reduction mandates require accelerated factory retooling, straining capital allocation for smaller assemblers.
Strategic Opportunities
- Battery-Swap Infrastructure:NIO's swap-station network demonstrates a service-layer differentiation model that reduces buyer range anxiety without larger battery packs.
- Software-Defined Vehicle Revenue:Over-the-air feature subscriptions and autonomous driving packages create recurring revenue streams decoupled from hardware sales cycles.
- Export Manufacturing Base:Shanghai Gigafactory and BYD's overseas plants position Chinese EV makers to supply Southeast Asian and European demand.
Industry Challenges
- Semiconductor Talent Scarcity:In-house chip design for power electronics and autonomous systems requires analog and automotive-grade silicon expertise that remains concentrated in Taiwan and South Korea.
- GB Standard Certification Lag:New battery safety and electromagnetic compatibility protocols from MIIT extend homologation timelines, delaying model launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Electric Car Market |
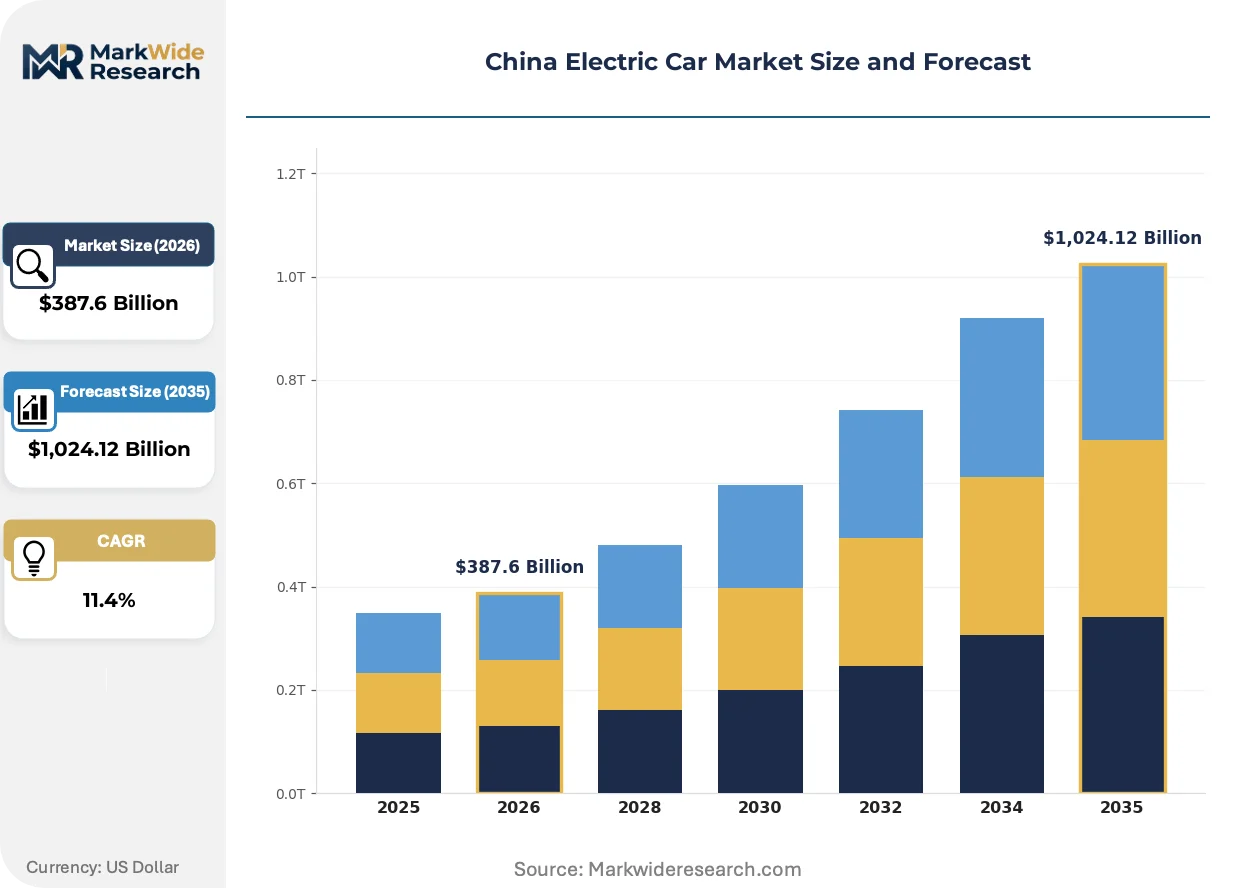
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric Vehicle, Plug-in Hybrid Electric Vehicle, Fuel Cell Electric Vehicle, Others Technology: Lithium-ion Batteries, Solid-state Batteries, Ultracapacitors, Hydrogen Fuel Cells End User: Individual Consumers, Commercial Fleets, Government Agencies, Ride-sharing Services Price Tier: Affordable, Mid-range, Premium, Luxury |
| Companies Covered | BYD, Tesla, NIO, Li Auto, XPeng, AITO, Geely, Great Wall Motor, Changan Automobile, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Electric Car Market Emerging Trajectories
Intelligent cockpit systems and autonomous driving hardware are converging to redefine vehicle differentiation, shifting competition from powertrain specifications to software execution and data infrastructure.
Solid-state electrolyte architectures are rewriting the safety-performance tradeoff in battery design. Cell manufacturers are piloting sulfide and oxide ceramic separators that eliminate thermal runaway risks while enabling higher nickel cathode loading. Premium EV assemblers are targeting these cells for flagship sedan launches, compressing the timeline for lithium-ion obsolescence in the luxury tier.
MIIT's GB/T charging interface harmonization mandates are consolidating connector standards across domestic and imported brands. The industrial consequence is reduced adapter complexity for charging network operators, who can now deploy single-hardware stalls serving all compliant vehicles. Commercial fleet operators benefit most, as depot charging infrastructure requires fewer cable variants and maintenance protocols.
Fleet procurement departments are consolidating supplier relationships around total cost of ownership guarantees rather than sticker price. Leasing companies and logistics operators are negotiating battery health warranties and residual value floors as standard contract terms. This behavior is most visible in Zhejiang and Jiangsu provinces, where municipal delivery electrification quotas accelerate fleet turnover cycles.
China Electric Car Market Segmentation
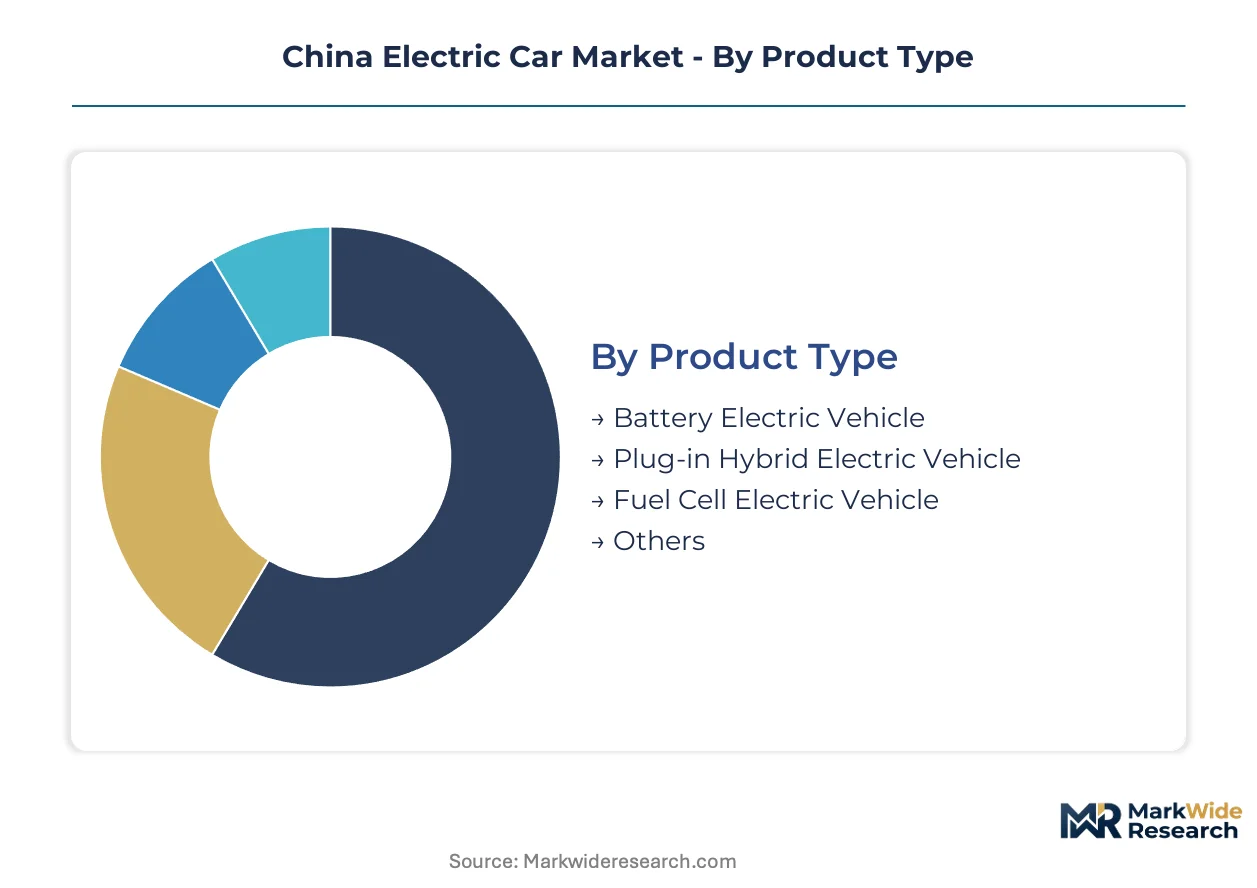
Segmentation in China's electric car market reveals how MIIT's NEV credit mechanics and regional infrastructure disparities create divergent growth vectors across powertrain architectures and buyer categories. Understanding these splits illuminates where battery technology investments concentrate and which customer segments absorb production volume.
Product Type:
Standardization dominates at the mass-market level where MIIT's credit-trading system rewards volume BEV output, while customization persists in range-extended formats for inland provinces with charging gaps.
- Battery Electric Vehicle:Pure-electric architectures with lithium-ion or solid-state packs exceeding 150 watt-hours per kilogram dominate coastal manufacturing. Demand concentrates in Shanghai and the Yangtze River Delta where high-speed charging density eliminates range constraints for individual consumers and commercial fleets.
- Plug-in Hybrid Electric Vehicle:Dual-powertrain systems combining electric motors with range-extending combustion engines retain structural importance in central and western provinces. Sichuan and Shaanxi fleet operators prefer PHEV delivery vans where charging infrastructure remains sparse and total cost of ownership calculations favor fuel flexibility.
- Fuel Cell Electric Vehicle:Hydrogen proton-exchange membrane systems power heavy-duty commercial applications in Beijing-Tianjin-Hebei industrial corridors.
- Others:Extended-range EVs and niche battery-swap architectures serve specialized logistics and premium mobility segments.
Leading the category by volume: Battery Electric Vehicle. Growing fastest: Fuel Cell Electric Vehicle.
Technology:
Cost tier stratification separates mature lithium-ion manufacturing from next-generation solid-state pilot lines, with margin pools concentrating at opposite ends of the investment spectrum.
- Lithium-ion Batteries:Nickel-manganese-cobalt and lithium iron phosphate chemistries constitute the incumbent manufacturing base. BYD's blade battery cell-to-pack architecture and CATL's cell formats anchor current capacity expansion in Fujian and Guangdong provinces.
- Solid-state Batteries:Sulfide and oxide ceramic electrolyte architectures eliminate thermal runaway risks while enabling higher energy density. Qingtao Energy Development and WeLion New Energy pilot production lines target premium sedan launches from Beijing and Shanghai assemblers.
- Ultracapacitors:Carbon-based electrochemical double-layer systems provide burst power for hybrid drivetrains and regenerative braking optimization.
- Hydrogen Fuel Cells:Proton-exchange membrane stacks convert hydrogen to electricity for long-haul trucking and bus fleets in northern industrial zones.
Commanding manufacturing scale: Lithium-ion Batteries. Steepest expansion trajectory: Solid-state Batteries.
End User:
Application-driven divergence splits passenger transport optimization from asset-utilization logic, with procurement patterns varying sharply between individual ownership and fleet-managed depreciation cycles.
- Individual Consumers:Private buyers in Jiangsu and Zhejiang provinces prioritize intelligent cockpit systems and autonomous driving hardware. NIO's battery-swap subscriptions and Tesla's over-the-air feature packages attract tech-forward households in Shanghai's Pudong and Hangzhou districts.
- Commercial Fleets:Logistics operators and delivery platforms in the Pearl River Delta negotiate total cost of ownership guarantees and battery health warranties. SF Express and Meituan electrify last-mile van fleets under municipal decarbonization quotas in Shenzhen and Guangzhou.
- Government Agencies:State-owned enterprises and municipal procurement departments specify domestic brand requirements for official vehicle fleets.
- Ride-sharing Services:Didi Chuxing and regional platforms optimize for charging speed and depreciation-resistant durability in high-mileage urban deployments.
Absorbing production volume: Individual Consumers. Gaining share fastest: Commercial Fleets.
Price Tier:
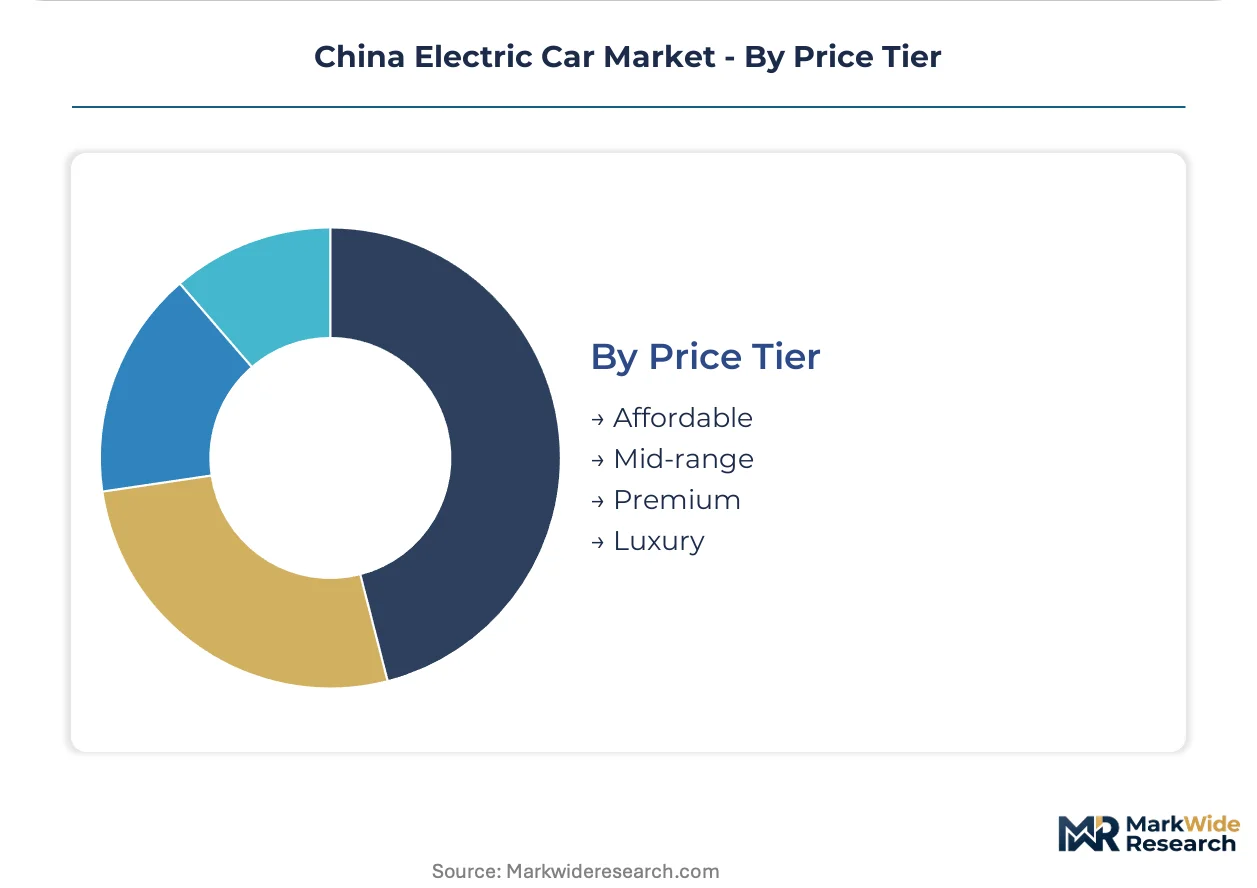
Customer type and margin structure map directly onto four pricing strata, with volume concentration at the affordable end and technology differentiation commanding premium positioning.
- Affordable:Sub-100,000 RMB vehicles with lithium iron phosphate batteries and stripped intelligent features target rural and small-city buyers. BYD's Seagull and Wuling's Mini EV dominate county-level dealerships in Henan and Shandong provinces.
- Mid-range:100,000-250,000 RMB crossovers and sedans balance battery capacity with driver-assistance features. XPeng and Leapmotor compete for family buyers in Chengdu and Wuhan metropolitan areas.
- Premium:250,000-500,000 RMB intelligent EVs with advanced autonomous hardware and luxury interior specifications.
- Luxury:Above-500,000 RMB flagship sedans and SUVs with solid-state battery pilots and concierge service ecosystems.
Capturing unit volume: Affordable. Expanding most quickly: Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the Yangtze River Delta cluster where high-speed charging density and MIIT's NEV mandate credits concentrate manufacturing investment and fleet procurement.
Beijing-Tianjin-Hebei
State-owned enterprise procurement and municipal fleet electrification quotas drive demand in this northern corridor. MEE's dual carbon compliance timelines force accelerated factory retooling across Hebei province. Beijing's battery-swap infrastructure pilots serve taxi and ride-sharing operators under municipal decarbonization mandates.
Guangdong Province
Pearl River Delta logistics operators electrify last-mile delivery fleets as total cost of ownership advantages materialize. SAMR enforces GB standard certification for battery safety and electromagnetic compatibility. Shenzhen's charging network density supports commercial van deployment for SF Express and Meituan under municipal quotas.
Sichuan-Chongqing
Inland charging infrastructure gaps sustain plug-in hybrid demand among fleet operators prioritizing fuel flexibility. MIIT's credit-trading mechanism still rewards zero-emission production despite geographic constraints. Chengdu's metropolitan buyers balance battery capacity with driver-assistance features in the mid-range tier.
Zhejiang Province
Intelligent cockpit systems and autonomous driving hardware attract tech-forward households in Hangzhou districts. NMPA oversees automotive component quality frameworks shaping supplier qualification. Ningbo's port logistics and manufacturing base export lithium iron phosphate cells to Southeast Asian assembly plants.
China Electric Car Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across China's electric car market. The structure consolidates around vertically integrated battery manufacturers and software-centric assemblers. Three archetypes dominate: integrated cell-to-vehicle producers, premium intelligent EV specialists, and mass-market commodity players. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure cathode material supply and charging network access.
Within the integrated producer tier, BYD exemplifies backward integration into blade battery manufacturing and semiconductor fabrication. Tesla anchors the premium segment through Shanghai Gigafactory manufacturing scale. NIO occupies a service-led position distinct from hardware-centric rivals. These three represent divergent strategic paths: captive supply chain control, manufacturing scale with software differentiation, and infrastructure-based user ecosystems.
| Leading Market Players |
|---|
| BYD |
| Tesla |
| NIO |
| Li Auto |
| XPeng |
| AITO |
| Geely |
| Great Wall Motor |
| Changan Automobile |
| Others |
Supply Flow & Price Mechanics
Commercial fleet operators in the Yangtze River Delta anchor volume procurement through total cost of ownership contracts, compressing sticker-price premiums and forcing assemblers toward battery-swap subscriptions and residual-value guarantees as the dominant pricing architecture.
Pricing Analysis
Value-based pricing tied to vehicle uptime and battery health guarantees anchors fleet procurement contracts in Zhejiang and Jiangsu provinces. Three-tier pricing structure across premium intelligent EVs, mid-range family vehicles, and affordable commodity models separates NIO's service-bundled subscriptions from BYD's hardware-centric transactions. Cost compression in the affordable tier intensifies as lithium iron phosphate cell prices fall and MIIT credit trading rewards volume BEV output. Fleet procurement departments exhibit the highest price sensitivity, while individual consumers in Shanghai's premium segment absorb software-subscription premiums with lower elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale cathode material demand from CATL and BYD, while aftermarket distributors serve replacement battery and charging component markets. Manufacturing concentration centers on China's Fujian and Guangdong provinces for lithium-ion cell production, with South Korea and Japan supplying high-nickel cathode precursors and separator membranes. The supply chain draws from Australian spodumene and Chilean brine for lithium carbonate, Indonesian nickel laterite, and DRC cobalt hydroxide. Single-source vulnerability in semiconductor-grade silicon for power electronics and autonomous driving chips creates structural risk, as analog and automotive-grade silicon expertise remains concentrated in Taiwan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT's tightening NEV credit thresholds are accelerating a consolidation play, forcing mid-tier assemblers without captive battery supply or software differentiation toward exit or acquisition.
For Market Incumbents: Deploy blade battery cell-to-pack architectures and in-house IGBT fabrication to defend against margin compression from lithium carbonate volatility and emerging solid-state entrants. Secure long-term cathode material offtake agreements with Indonesian nickel and Chilean lithium suppliers. Deepen backward integration into semiconductor design to reduce dependency on Taiwan and South Korean analog chip foundries. For New Entrants and Emerging Players: The 100,000-250,000 RMB mid-range gap between BYD's cost leadership and Tesla's premium positioning offers white-space opportunity in intelligent cockpit systems for Chengdu and Wuhan metropolitan buyers. Target Sichuan-Chongqing fleet operators with PHEV delivery vans where charging infrastructure gaps sustain fuel-flexibility demand. Pursue battery-swap infrastructure partnerships with municipal governments as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors solid-state battery specialists with sulfide electrolyte pilot lines and premium OEM qualification timelines. Long-term viability hinges on technology transition rather than manufacturing scale, positioning Qingtao Energy Development and WeLion New Energy archetypes for acquisition premiums. Monitor MIIT's GB standard certification timelines for battery safety protocols as the inflection indicator for production-readiness valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL's cell supply contracts with Shanghai Gigafactory anchor Tesla's manufacturing scale and cost position. |
| Software-Defined Vehicle Investment | XPeng's autonomous driving R&D creates recurring revenue streams through over-the-air feature subscriptions. |
| Charging Infrastructure Partnership | NIO's swap-station network with municipal governments in Beijing reduces buyer range anxiety without larger battery packs. |
| Geographic Manufacturing Footprint | BYD's Thailand and Hungary plants position Chinese EV makers to supply Southeast Asian and European demand. |
| Platform Standardization | Geely's SEA architecture sharing across Zeekr, Volvo, and Polestar reduces development costs and accelerates model launches. |
Methodological Framework
Multi-period observation of MIIT NEV credit trading volumes, battery cell production capacity, and vehicle registration data anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, charging network operators, and fleet procurement managers. Secondary validation drew from MIIT production bulletins, SAMR market access certifications, customs export records, and IHS Markit vehicle registration databases. Bottom-up assembly of segment volumes and top-down macroeconomic anchoring were triangulated to ensure consistency.
Segment-weighting across propulsion architecture, battery technology tier, end-user category, and regional production cluster shaped the analytical framework. CAGRs were derived from fitted growth curves calibrated to historical penetration rates and policy-mandated adoption floors. Forecast inputs included MIIT credit threshold trajectories, lithium carbonate spot-price elasticity models, and charging infrastructure deployment schedules by provincial grid operators.
Inputs from MIIT production databases and provincial vehicle registration systems were available through the study window; gaps in solid-state battery pilot-line yield data and autonomous driving chip foundry utilization introduce uncertainty bands around technology-transition timelines. Practitioners should monitor MIIT's GB standard certification announcements and dual carbon compliance timeline revisions for early signals of regulatory inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
E-Bike Battery Market
Electric Vehicles
Electric Vehicle Helmet Market
Electric Vehicles
Asia-Pacific Solar E-Bike Market
Electric Vehicles
France Electric Bus Battery Pack Market
Electric Vehicles
Worldwide EV Range Extender Market
Electric Vehicles
North America Electric Vehicle Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Asia Pacific Electric Scooter Market
Electric Vehicles
Middle-East and Africa E-Bike Market
Electric Vehicles
United Kingdom E-Bike Market
Electric Vehicles
India Hybrid Electric Vehicle Battery Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market
Electric Vehicles
Asia-Pacific Electric Vehicle (EV) Fluids Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
US Electric Commercial Vehicle Battery Pack Market