
 Asia Pacific Electric Scooter Market | 2026-2036
Asia Pacific Electric Scooter Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Electric Scooter Market Analytics
GB/T 34657 certification for electric vehicle conductive charging is rotating the competitive landscape toward manufacturers with in-house testing labs and government-backed homologation partnerships. Yadea Technology Group Co., Ltd. leverages its vertically integrated battery cell production to control cost structures across mass-market sit-down models. NIU Technologies differentiates through IoT-enabled fleet management systems that sustain recurring software revenue alongside hardware sales. Gogoro Inc. anchors its position through proprietary battery swap infrastructure that locks in urban commuter demand across Taiwanese and expanding Southeast Asian networks.
Asia Pacific electric scooters are battery-powered two-wheel personal mobility devices with hub-mounted or mid-drive electric motors, typically operating at 48V to 72V with lithium-ion or lead-acid energy storage, designed for urban transit and commercial fleet applications. The product mix tilts heavily toward sit-down scooters where margin pools concentrate due to higher unit values and fleet procurement volumes, while stand-up variants face commoditization pressure from unbranded Shenzhen-area assemblers. Lithium-ion chemistry leads the battery type split as lead-acid faces phase-out pressure under China's dual carbon goals and India's PLI scheme for advanced cell manufacturing, though nickel-metal hydride retains niche presence in cost-sensitive Indonesian and Philippine markets.
China's MIIT enforces GB/T motor power limits and SAMR oversees product quality inspections that determine market access eligibility, while India's CEA and state transport authorities coordinate FAME II subsidy disbursement tied to domestic value-add requirements. Japan's METI sets JIS standards for battery safety that constrain import eligibility for non-compliant manufacturers. Stakeholders must monitor how Indonesia's forthcoming battery recycling mandates and Vietnam's proposed domestic assembly quotas reshape supplier qualification criteria and capital deployment timelines across the region.
Market Dynamics
GB/T charging standardization across China's MIIT framework is concentrating supplier qualification power with domestic testing consortiums, forcing foreign manufacturers into joint-venture homologation partnerships to access the region's dominant production base.
Growth Catalysts
- FAME II subsidy architecture:India's domestic value-add requirements are pulling battery pack assembly from Shenzhen to Chennai and Bengaluru industrial corridors.
- Last-mile fleet electrification:Jakarta-Bandung megacity logistics operators are replacing gasoline two-wheeler fleets with sit-down electric scooters for parcel and food delivery density.
- Lithium-ion chemistry transition:China's dual carbon goals are accelerating lead-acid phase-out timelines across municipal procurement specifications.
Market Restraints
- Raw material concentration:Cathode precursor processing capacity clusters in Hunan and Fujian provinces, creating single-geography supply vulnerability for non-Chinese assemblers.
- Homologation cost escalation:Japan's METI JIS battery safety certification requires in-country testing that adds twelve-to-eighteen month market entry delays for new entrants.
- Lead-acid residual demand:Nickel-metal hydride retains cost-sensitive positioning in Indonesian and Philippine provincial markets where upfront price sensitivity overrides total cost of ownership calculus.
Strategic Opportunities
- Vietnam urban corridor penetration:Ho Chi Minh City and Hanoi municipal authorities are expanding dedicated two-wheeler EV lane infrastructure without equivalent gasoline vehicle access.
- Battery swap infrastructure:Proprietary swap station networks are locking in commuter demand through subscription-based energy access models that decouple vehicle from battery ownership.
- Indonesian recycling mandates:Forthcoming regulations on end-of-life battery recovery are creating first-mover advantage for manufacturers with pre-positioned reverse logistics partnerships.
Industry Challenges
- GB/T 34657 certification timelines:Conductive charging compliance testing backlog at MIIT-accredited laboratories is stretching product launch schedules for non-vertically integrated suppliers.
- Power electronics talent scarcity:Hub motor controller firmware engineering expertise concentrates in Suzhou and Shenzhen, forcing regional expansion candidates into compensation wars or acquisition strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Electric Scooter Market |
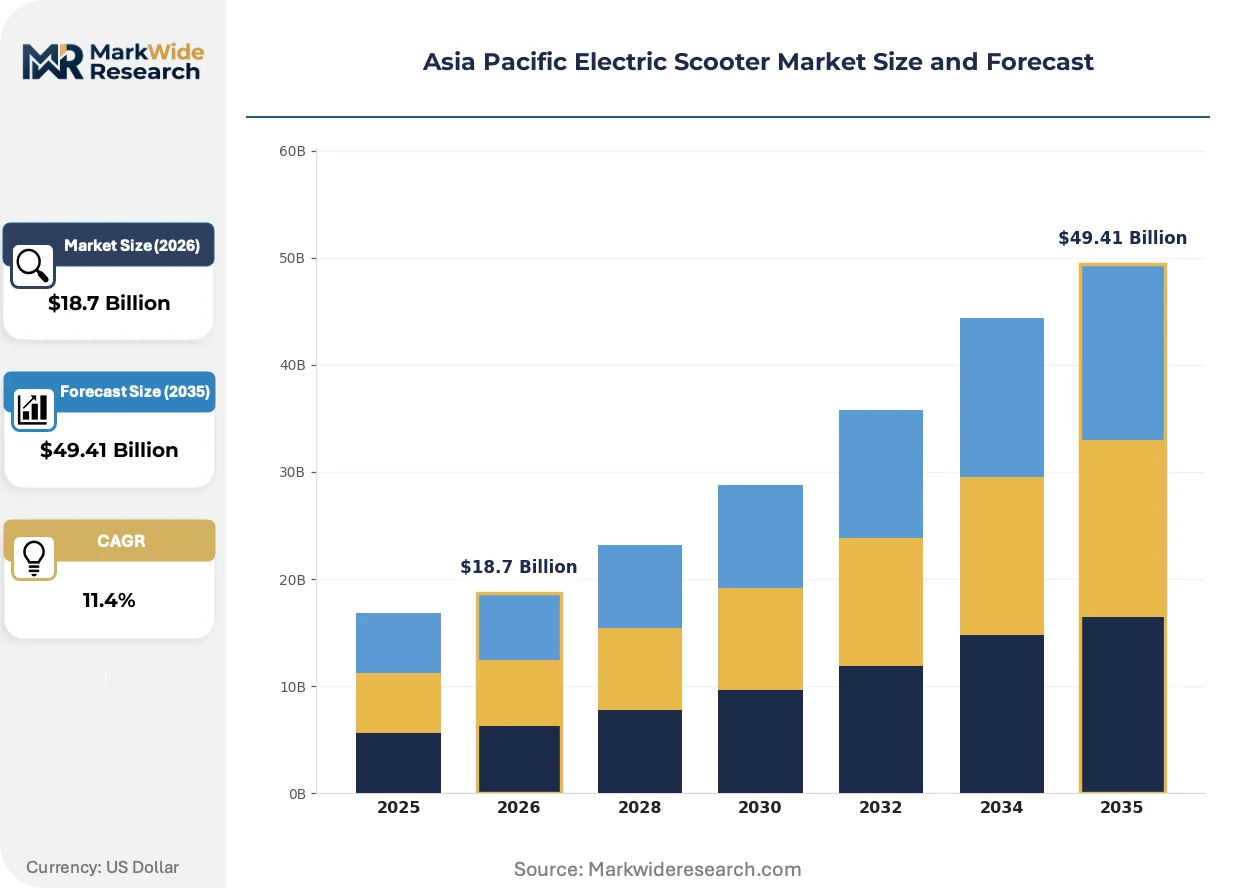
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Scooters, Sit-Down Scooters, Folding Scooters, Off-Road Scooters Battery Type: Lithium-Ion, Lead Acid, Nickel-Metal Hydride, Others End User: Commuters, Tourists, Delivery Services, Recreational Users Charging Mode: Standard Charging, Fast Charging, Solar Charging, Inductive Charging |
| Companies Covered | Yadea Technology Group Co., Ltd., NIU Technologies, Gogoro Inc., Ather Energy Pvt. Ltd., Ola Electric Mobility Pvt. Ltd., Hero MotoCorp Ltd., TVS Motor Company, Yamaha Motor Co. Ltd., Honda Motor Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Electric Scooter Market Evolving Landscape
Silicon carbide power electronics are penetrating motor controller designs, enabling thermal efficiency gains that reshape vehicle architecture trade-offs between range, weight, and cooling system complexity across Southeast Asian humidity conditions.
Silicon carbide MOSFETs are replacing silicon IGBTs in 72V hub motor controllers, cutting switching losses by roughly one-third at equivalent power output. Fleet operators in Vietnam's urban corridors are specifying SiC-based platforms for reduced thermal management overhead and extended motor life. This semiconductor transition is decomposing the traditional cost-performance trade-off that constrained high-voltage mass-market penetration.
China's MIIT is tightening GB/T motor power limits and expanding SAMR quality inspection scope to cover battery thermal runaway propagation testing. The regulatory expansion is forcing component suppliers to redesign cell-to-pack architectures and thermal barrier materials. Southeast Asian import authorities are mirroring these standards, compressing market access for non-compliant manufacturers.
Subscription-based battery access is displacing outright purchase in Taiwanese and expanding Southeast Asian urban markets, separating energy provision from vehicle ownership. Fleet managers and individual commuters are adopting swap-station memberships that eliminate charging downtime and battery degradation risk. This consumption-pattern shift concentrates in metropolitan zones with station density above one per square kilometer.
Asia Pacific Electric Scooter Market Segmentation
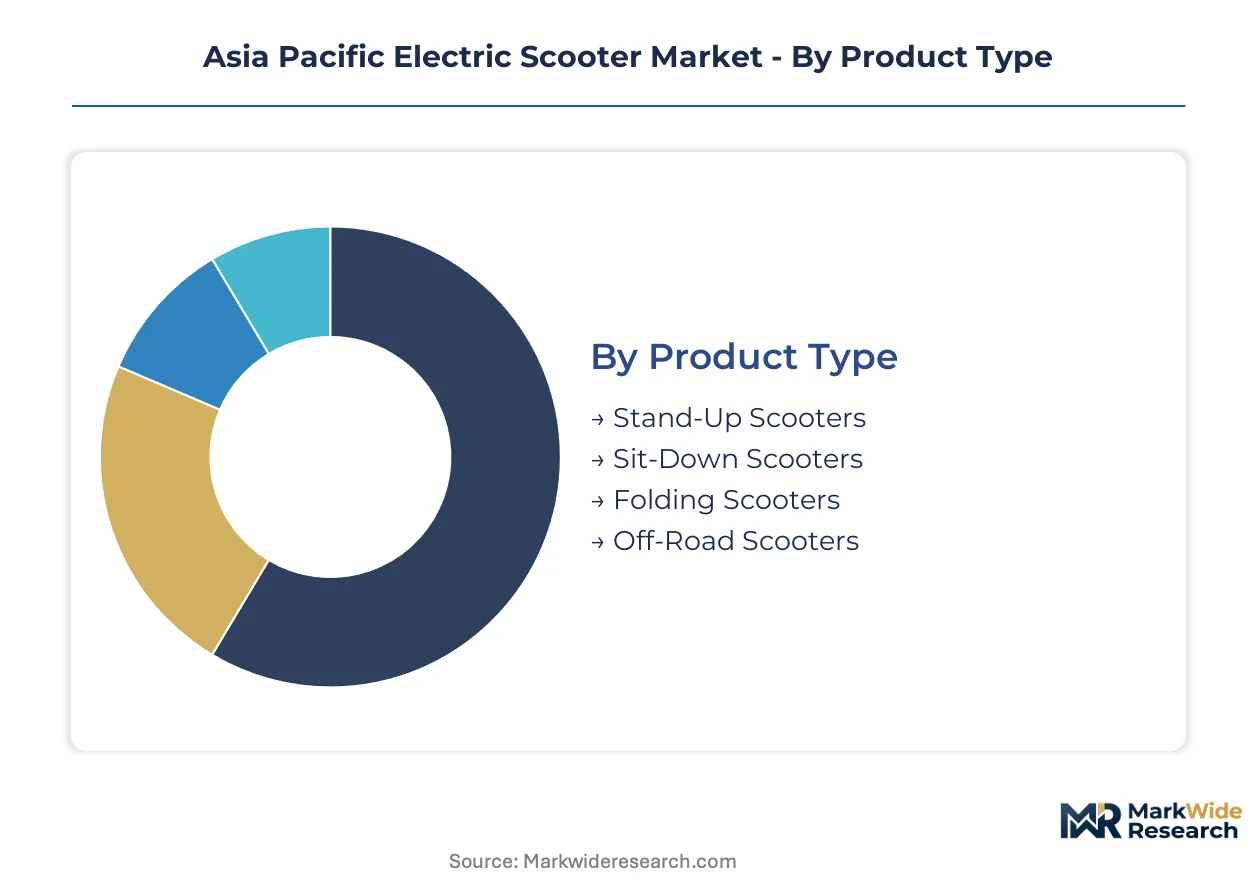
Segmentation in the Asia Pacific electric scooter market reveals how regulatory frameworks and infrastructure maturity create divergent growth corridors across product architectures, battery chemistries, and charging modalities. Understanding these divisions exposes where subsidy eligibility, homologation requirements, and fleet procurement specifications concentrate commercial opportunity.
Product Type:
China's MIIT motor power limits and SAMR quality inspections apply differentially across form factors, with sit-down models facing stricter certification burdens that advantage established domestic manufacturers.
- Stand-Up Scooters:Compact hub-motor designs operating at 36V to 48V dominate first-mile urban transit and shared micromobility deployments. India's FAME II subsidy thresholds exclude many imported stand-up variants, channeling procurement toward domestically assembled units in Chennai and Bengaluru corridors.
- Sit-Down Scooters:Higher-voltage platforms with 60V to 72V lithium-ion packs command fleet procurement volumes from Jakarta-Bandung logistics operators replacing gasoline two-wheelers. GB/T 34657 charging certification requirements concentrate supplier qualification with vertically integrated manufacturers possessing in-house testing capabilities.
- Folding Scooters:Collapsible frame designs targeting multimodal commuters face weight restrictions under Japan's METI transport safety guidelines that constrain import eligibility.
- Off-Road Scooters:Suspension-equipped variants with enhanced ground clearance serve recreational demand in Australian and New Zealand trail networks where terrain regulations differ from urban compliance frameworks.
Established volume favors sit-down scooters; emerging adoption favors folding scooters.
Battery Type:
Cost tier stratification separates premium lithium-ion platforms from residual lead-acid demand, with chemistry selection determining subsidy access and fleet total cost of ownership calculations.
- Lithium-Ion:NMC and LFP cell architectures deliver energy densities above 180 Wh/kg, enabling range extension for Vietnam's Ho Chi Minh City-Hanoi corridor fleets. China's dual carbon goals and India's PLI scheme for advanced cell manufacturing accelerate phase-out pressure on competing chemistries.
- Lead Acid:Flooded and AGM variants retain 20-30% cost advantages at the pack level, sustaining presence in Indonesian and Philippine provincial markets where upfront price sensitivity overrides lifecycle economics. Municipal procurement specifications in tier-three Chinese cities still permit lead-acid for specific fleet categories.
- Nickel-Metal Hydride:Intermediate energy density chemistry occupies niche positioning in cost-sensitive Southeast Asian segments awaiting lithium-ion price parity.
- Others:Emerging sodium-ion and solid-state prototypes occupy pre-commercial testing phases with limited regional deployment.
Procurement momentum clusters with lithium-ion; residual fleet replacement sustains lead-acid.
End User:
Application-driven specification divergence separates consumer commuter requirements from commercial fleet duty cycles, with each segment imposing distinct motor power, charging speed, and durability thresholds.
- Commuters:Daily urban transit users prioritize weight reduction and parking convenience, driving demand for 48V folding and compact sit-down models across Taiwanese and Vietnamese metropolitan zones.
- Tourists:Short-term rental demand concentrates in Bangkok, Bali, and Phuket hospitality corridors where operators specify enhanced weatherproofing and simplified user interfaces.
- Delivery Services:Food and parcel fleet operators in Indonesia's megacity zones specify 72V platforms with swappable battery architectures, eliminating charging downtime through Gogoro-style station networks.
- Recreational Users:Weekend riders in Australian and Japanese markets demand higher-performance motor controllers and suspension systems with limited price elasticity.
Commercial fleet specifications are tightening fastest; consumer commuter volumes remain largest.
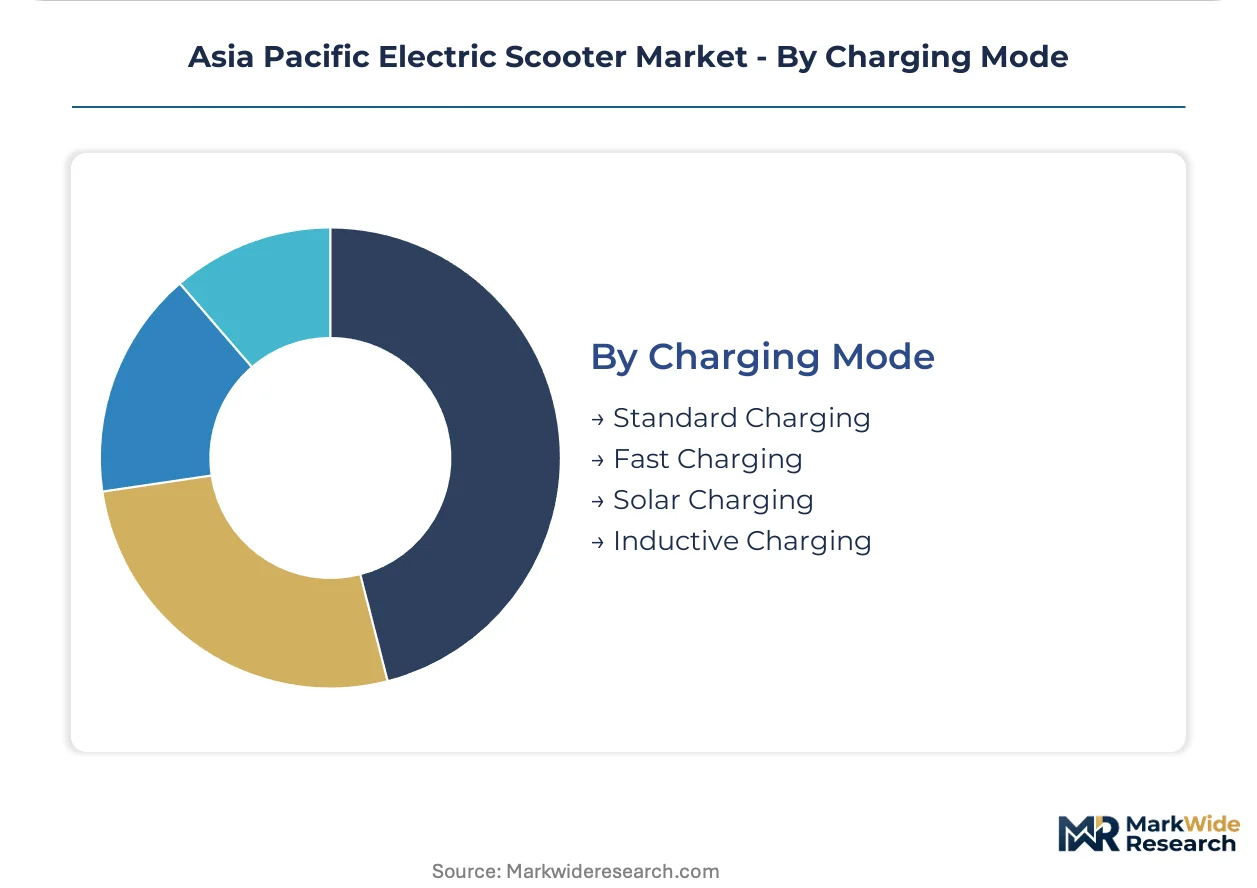
Charging Mode:
Infrastructure availability and grid reliability constraints across Southeast Asian urban corridors create divergent adoption patterns between conductive and wireless charging modalities.
- Standard Charging:Level 1 AC charging via GB/T 34657 connectors dominates residential and workplace installations where dwell times exceed six hours, aligning with overnight fleet depot operations.
- Fast Charging:DC rapid infrastructure above 3kW enables opportunity charging for delivery fleets, though Vietnam and Indonesia grid stability limitations constrain deployment density.
- Solar Charging:Off-grid photovoltaic integration serves rural Indonesian and Philippine markets with unreliable grid access, pairing with lead-acid storage for cost containment.
- Inductive Charging:Wireless pad systems remain pilot-phase in Singapore and Japanese smart city demonstrations, awaiting standardization alignment with GB/T frameworks.
Conductive standard charging anchors current deployment; battery swap subscriptions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's FAME II subsidy architecture and China's GB/T charging standards are reshaping procurement patterns across the region, pulling battery assembly toward Chennai and Bengaluru while concentrating supplier qualification with domestic testing consortiums.
China
MIIT motor power limits and SAMR quality inspections determine market access eligibility for manufacturers targeting domestic and export volumes. GB/T 34657 certification requirements concentrate supplier qualification with vertically integrated producers possessing in-house testing labs. The Yangtze River Delta and Pearl River Delta industrial clusters host cathode precursor processing capacity that creates supply vulnerability for non-Chinese assemblers.
India
FAME II domestic value-add requirements are redirecting battery pack assembly from Shenzhen to Chennai and Bengaluru industrial corridors. CEA coordination with state transport authorities ties subsidy disbursement to local manufacturing thresholds. Maharashtra and Karnataka sub-regions concentrate fleet procurement volumes as delivery operators replace gasoline two-wheelers with electric platforms.
Vietnam
Ho Chi Minh City and Hanoi municipal authorities are expanding dedicated two-wheeler EV lane infrastructure without equivalent gasoline vehicle access. Provincial transport departments align procurement specifications with emerging GB/T safety standards. Urban corridor fleet operators specify 72V platforms with swappable battery architectures to eliminate charging downtime.
Indonesia
Jakarta-Bandung megacity logistics operators are converting last-mile delivery fleets from gasoline two-wheelers to electric scooters for parcel and food delivery density. Forthcoming battery recycling mandates are reshaping supplier qualification criteria and capital deployment timelines. Nickel-metal hydride retains cost-sensitive positioning in provincial markets outside the core megacity zone.
Japan
METI JIS battery safety certification constrains import eligibility for non-compliant manufacturers through in-country testing requirements. Regulatory compliance adds twelve-to-eighteen month market entry delays for new entrants. Kanto and Kansai metropolitan zones concentrate commuter demand for IoT-enabled fleet management systems.
Asia Pacific Electric Scooter Market Competitive Landscape
Player mix skews toward vertically integrated battery producers and IoT-enabled platform specialists competing against traditional two-wheeler manufacturers pivoting from internal combustion. The competitive structure tiers across premium subscription-based energy access providers, mass-market hardware-focused assemblers, and fleet-management software integrators. Strategic moves concentrate on backward integration into cell production and proprietary charging infrastructure deployment.
Among China-based fabricators, Yadea Technology Group Co., Ltd. and NIU Technologies occupy positions representing contrasting archetypes of scale-driven manufacturing versus connected-platform specialization. Gogoro Inc. anchors the battery swap infrastructure tier. These three exemplify how competitive positioning diverges between captive battery production, recurring software revenue models, and subscription-based energy access networks.
| Leading Market Players |
|---|
| Yadea Technology Group Co., Ltd. |
| NIU Technologies |
| Gogoro Inc. |
| Ather Energy Pvt. Ltd. |
| Ola Electric Mobility Pvt. Ltd. |
| Hero MotoCorp Ltd. |
| TVS Motor Company |
| Yamaha Motor Co. Ltd. |
| Honda Motor Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Cathode precursor processing capacity utilization in Hunan and Fujian provinces anchors cost floors for lithium-ion pack assembly, concentrating supplier bargaining power with vertically integrated cell manufacturers while compressing margins for non-captive assemblers across Vietnam and Indonesia procurement markets.
Pricing Analysis
GB/T 34657 certification tier creates the primary spread between premium and mass-market positioning, separating manufacturers with in-house MIIT-accredited testing capabilities from joint-venture-dependent entrants. Three-tier pricing structure across premium, standard, and economy levels reflects battery chemistry grade, motor controller sophistication, and swap-station network access bundling. Cost compression in economy-tier lead-acid variants is intensifying because Indonesian provincial buyers prioritize upfront acquisition cost over total cost of ownership. Fleet procurement managers in Jakarta-Bandung corridors show least price sensitivity due to fuel savings amortization, while individual commuters in Philippine secondary cities exhibit highest elasticity.
Supply Chain Analysis
Strait of Malacca transit chokepoint underwrites logistics vulnerability for cathode active materials flowing from Chinese coastal processors to Southeast Asian assembly plants. Manufacturing gravity centers on China, Vietnam, and India, with cell production anchored in Yangtze River Delta and Pearl River Delta clusters while pack assembly migrates toward Chennai and Ho Chi Minh City industrial zones. Hub motor controller firmware engineering expertise draws from Suzhou and Shenzhen talent pools, creating single-geography dependency for power electronics design. Distribution runs through OEM-direct fleet contracts and regional two-wheeler dealer networks serving replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across battery chemistry, charging modality, and fleet-versus-consumer demand creates specialist niche opportunities as procurement specifications diverge under divergent regulatory regimes.
For Market Incumbents: Consolidate backward integration into cell production to defend margin position against Shenzhen-area commoditization pressure, while locking fleet customers through proprietary swap-station subscription models that raise switching costs. Priority investments center on MIIT homologation partnerships and Vietnam urban corridor charging infrastructure density. For New Entrants and Emerging Players: GB/T certification fast-track through joint-venture testing consortiums opens procurement access to China's dominant production base. White-space concentration sits in Indonesian provincial markets where nickel-metal hydride cost positioning meets relaxed municipal specifications, and in Philippine delivery fleet retrofits where financing innovation can offset upfront battery premiums. Go-to-market leverage rests on solar-charging integration for off-grid rural deployments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among battery-swap network operators with subscription-based energy access models, offering superior cash flow predictability versus transactional hardware sales. Long-term viability favors manufacturers with captive lithium-ion cell supply and pre-positioned Indonesian recycling logistics. Inflection signal to monitor is Vietnam municipal lane infrastructure buildout velocity relative to gasoline two-wheeler registration declines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Production | Captive lithium-ion supply secures GB/T certification timelines and insulates margin from cathode precursor volatility. |
| Battery Swap Infrastructure Deployment | Proprietary station networks lock commuter demand through subscription energy models across Taiwanese and Vietnamese metros. |
| MIIT Homologation Partnership | Domestic testing consortium access compresses product launch schedules for non-vertically integrated suppliers. |
| Fleet Management Software Integration | IoT-enabled platforms generate recurring revenue alongside hardware sales through telematics and predictive maintenance. |
| Indonesian Recycling Logistics Pre-positioning | First-mover reverse partnerships capture advantage under forthcoming end-of-life battery recovery mandates. |
Research Methodology
Operator-level perspectives from fleet procurement managers, OEM platform engineers, battery swap network operators, and MIIT regulatory affairs specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through MIIT GB/T filing databases, India CEA FAME II disbursement records, and Vietnam transport authority infrastructure procurement disclosures. Bottom-up unit economics modeling triangulated against top-down regional demand aggregation.
Sensitivity analysis across subsidy phase-out trajectories, lithium carbonate price bands, and swap-station density thresholds shaped the analytical framework. Segmentation dimensions spanned product architecture, battery chemistry, end-use application, charging modality, and country-level regulatory cluster. CAGRs derived from installed base turnover rates and fleet electrification penetration curves, with cross-reference to motor power limit enforcement intensity and domestic value-add threshold adjustments.
Underlying assumptions cover FAME II continuity, GB/T standard adoption timelines, and Indonesia recycling mandate implementation, with deviation risk concentrated in raw material export restriction escalation and grid stability constraints across Southeast Asian urban corridors. Revision becomes warranted when cathode precursor processing capacity utilization crosses thresholds that trigger supply rationing to non-integrated assemblers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
ASEAN Electric Bicycle Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
Embedded System for Electric Vehicle Market
Electric Vehicles
Electric Vehicle Skateboard Platform Market
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
Right Hand Drive Electric Vehicle Market
Electric Vehicles
Global Electric Scooters Market
Electric Vehicles
Driveline Electric Vehicle Market
Electric Vehicles
Scooter Market