
 Light Olefins Market | 2026-2036
Light Olefins Market Size, Share, and Industry Trends Forecast 2026-2036
Light Olefins Market Outlook
Multi-source feedstock procurement is realigning how integrated producers secure ethylene and propylene supply. DowDuPont leverages its Gulf Coast steam cracking network to sustain cost-advantaged polyethylene output. Saudi Arabian Oil Co. anchors massive derivative capacity at Jubail Industrial City. Exxon Mobil Corporation competes through proprietary metallocene catalyst technology that differentiates its polymer grades.
Light olefins are unsaturated hydrocarbons containing one double bond, primarily produced through steam cracking of naphtha, ethane, or propane at temperatures exceeding 800°C to yield ethylene, propylene, and butylene fractions. These molecules serve as foundational monomers for polyethylene, polypropylene, and synthetic rubber manufacturing across industrial economies. Ethylene dominates product type value generation due to its conversion into high-density polyethylene for rigid packaging applications. Propylene trails as the fastest-expanding olefin segment, driven by polypropylene demand in automotive lightweighting and flexible food packaging. Steam cracking retains technology leadership despite emerging gas-to-liquids investments, as established crackers benefit from sunk capital and optimized heat integration.
The US EPA enforces emissions thresholds for cracking furnaces under the Clean Air Act, while the EU F-Gas Regulation constrains fluorinated refrigerant use in olefin separation processes. China's MEE implements dual carbon targets that restrict new coal-to-olefin projects and favor ethane-based configurations. India's BIS mandates polymer grade specifications for food-contact applications, shaping import quality requirements. Stakeholders must monitor feedstock cost spreads between ethane and naphtha to optimize cracking economics and capital allocation.
Market Dynamics
Feedstock arbitrage between ethane and naphtha is compressing margin structures for integrated steam crackers, forcing capital redeployment toward lighter configurations as China's MEE enforces dual carbon compliance on new project approvals.
Growth Catalysts
- E-commerce logistics packaging:Polyethylene demand from Asia-Pacific fulfillment centers is pulling ethylene consumption into high-volume, just-in-time supply contracts that favor coastal crackers with direct port access.
- REACH chemical safety protocols:EU registration requirements for polymer additives are accelerating substitution toward metallocene-catalyzed grades with cleaner compositional profiles.
- Propane dehydrogenation:PDH units in the Middle East are unlocking on-purpose propylene supply independent of naphtha cracking economics, diversifying derivative feed sources for polypropylene compounders.
Market Restraints
- Ethane price volatility:US Gulf Coast ethane differentials swing with natural gas liquid fractionation capacity, exposing export-oriented crackers to margin compression when Henry Hub benchmarks spike.
- Concentrated catalyst supply:Metallocene single-site catalyst production concentrates among three specialized chemical firms, creating procurement bottlenecks for differentiated polyethylene grades.
- F-Gas Regulation constraints:EU limits on fluorinated refrigerants are raising capital costs for olefin separation train retrofits, extending payback periods for capacity expansions.
Strategic Opportunities
- India's PLI scheme for chemicals:Production-linked incentives for petrochemical manufacturing are drawing greenfield cracker investments toward Gujarat's Dahej Petroleum Chemical and Petrochemical Investment Region.
- Bio-based ethylene routes:Ethanol-to-ethylene dehydration is gaining traction among European brand owners seeking mass-balance certified packaging feedstocks for consumer goods.
- Automotive lightweighting mandates:Polypropylene compounds replacing metal underhood components are opening specification windows for high-crystallinity grades in electric vehicle platforms.
Industry Challenges
- Cracker furnace engineering talent:Specialized expertise in radiant coil design and coking mitigation is retiring faster than apprenticeship programs replenish the workforce, threatening reliability metrics.
- ISO 17025 laboratory accreditation:Polymer grade certification timelines for food-contact applications are extending due to backlog at testing facilities, delaying customer qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Olefins Market |
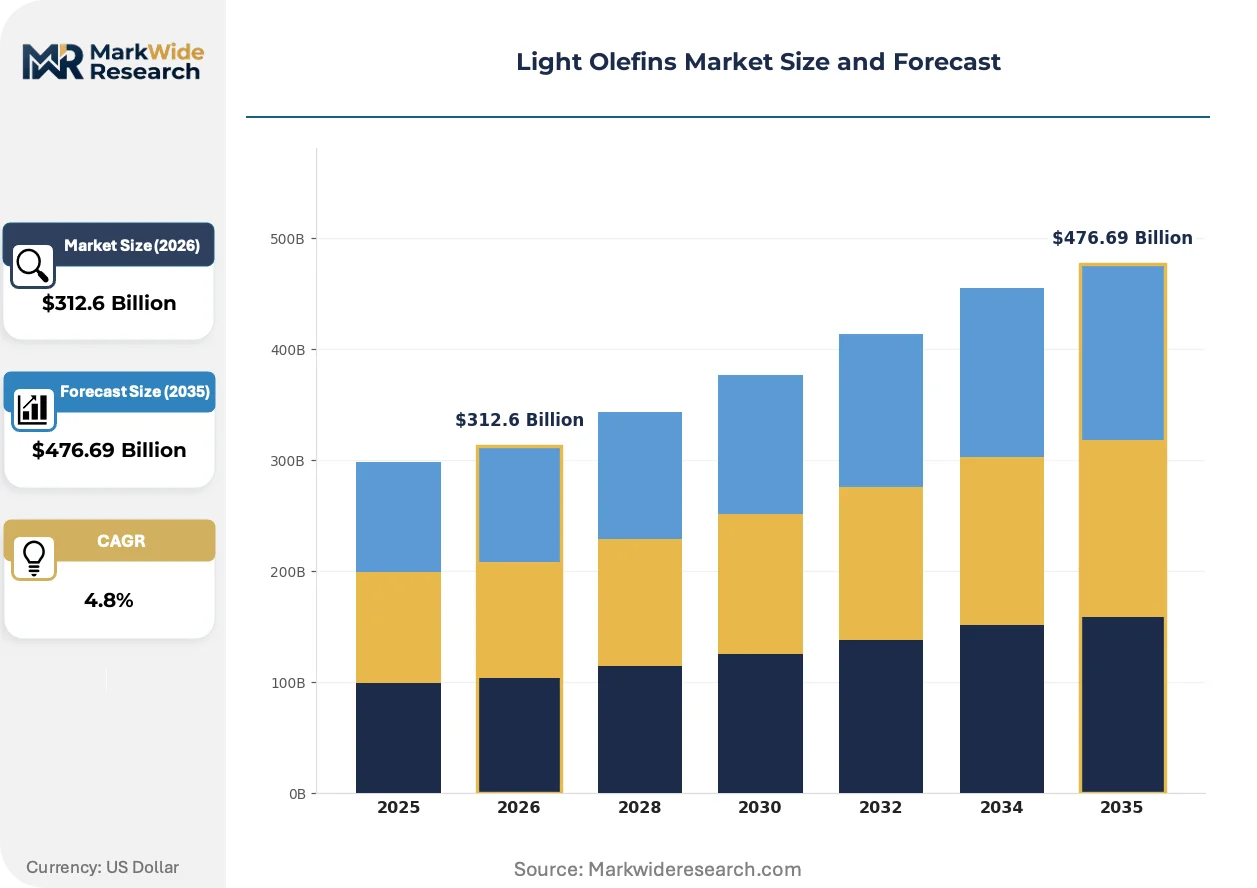
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $476.69 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene, Propylene, Butylene, Isobutylene Application: Plastics, Chemicals, Automotive, Textiles Technology: Catalytic Cracking, Steam Cracking, Gas-to-Liquids, Fluid Catalytic Cracking End User: Petrochemical Industry, Packaging, Construction, Consumer Goods |
| Companies Covered | DowDuPont, PetroChina, Royal Dutch Shell, Saudi Arabian Oil Co., China Petro & Chemical Corp, Reliance Industries Limited, Exxon Mobil Corporation, LyondellBasell, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Olefins Market Strategic Shifts
Electrification of process heat and feedstock flexibility investments are rewriting the technology frontier for olefin production, while regulatory carbon accounting forces disclosure of Scope 3 emissions across derivative supply chains.
Electrified cracking furnaces are electrifying the conventional steam cracking heat supply by replacing fuel-fired burners with resistive or inductive heating elements. European integrated producers are piloting these units to eliminate Scope 1 emissions from ethylene production. This technology is electrifying project finance structures as lenders apply green bond eligibility criteria to petrochemical capex.
China's MEE dual carbon implementation rules are tightening approval thresholds for coal-to-olefin projects while fast-tracking ethane-based configurations with lower carbon intensity benchmarks. Provincial environmental bureaus are rejecting methanol-to-olefin proposals in Inner Mongolia and Shanxi. Steam cracker operators are responding by locking long-term ethane supply contracts with US exporters.
Polymer procurement is consolidating under integrated converters seeking direct offtake agreements with crackers, bypassing traditional distributor intermediaries. Flexible packaging compounders in eastern China are negotiating toll manufacturing arrangements that guarantee resin supply through demand cycles. This pattern is most visible in Zhejiang and Jiangsu provinces where e-commerce fulfillment density supports dedicated polyethylene supply lines.
Light Olefins Market Segmentation
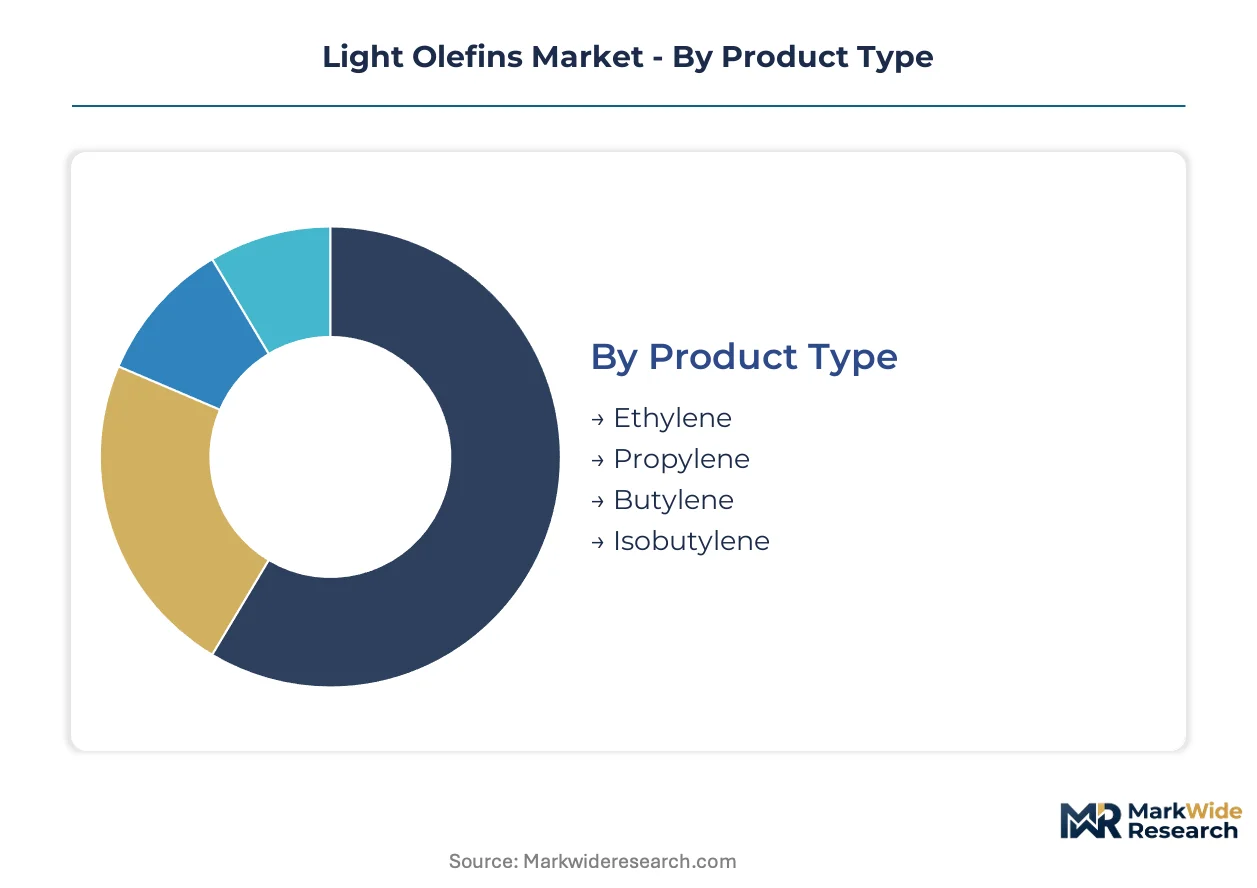
Segmentation in light olefins reveals how capital deployment, feedstock access, and derivative demand concentrate value capture across distinct production and consumption clusters. Understanding these divisions helps stakeholders align capacity investments with specific margin structures and regulatory constraints.
Product Type:
Capital intensity varies sharply across olefin molecules, with ethylene requiring the largest steam cracker complexes while butylene derivatives demand specialized alkylation and MTBE units.
- Ethylene:The foundational olefin produced through high-temperature steam cracking of naphtha or ethane, yielding polymer-grade purity specifications for polyethylene manufacturing. Demand concentrates in China's Zhejiang and Jiangsu provinces where integrated refinery-olefin complexes serve e-commerce packaging fulfillment networks. The EPA enforces emissions thresholds for cracking furnaces under the Clean Air Act, elevating compliance costs for US Gulf Coast producers.
- Propylene:Extracted as a co-product from naphtha crackers or produced on-purpose via propane dehydrogenation units in the Middle East. Automotive lightweighting specifications in Germany and Japan are pulling high-crystallinity polypropylene compounds into electric vehicle underhood applications. China's MEE dual carbon targets favor PDH configurations over coal-to-olefin routes.
- Butylene:Four-carbon olefin stream separated from cracked gas fractions, primarily directed toward synthetic rubber and alkylate gasoline blending components.
- Isobutylene:Branched C4 olefin serving methyl tert-butyl ether production and butyl rubber manufacturing for tire inner liners.
Ethylene absorbs the bulk of installed capacity; propylene is expanding most quickly.
Application:
Application segmentation tracks how olefin molecules flow into distinct value chains with varying price elasticity and specification requirements.
- Plastics:Polyethylene and polypropylene conversion dominates olefin offtake, with flexible food packaging specifications tightening under EU REACH chemical safety protocols for polymer additives.
- Chemicals:Ethylene oxide, propylene oxide, and acrylonitrile production consumes olefins for industrial intermediates, with India's BIS mandating polymer grade specifications for food-contact applications that shape import quality requirements.
- Automotive:Polypropylene compounds replacing metal components in electric vehicle platforms are opening specification windows for high-crystallinity grades. Germany's KBA type-approval processes influence material selection for underhood thermal management systems.
- Textiles:Acrylonitrile fiber production for apparel and industrial applications draws propylene supply, with mass-balance certification gaining traction among European brand owners.
Plastics commands the largest volume share; automotive applications are climbing the fastest as lightweighting mandates intensify.
Technology:
Technology segmentation reflects diverging capital structures and carbon intensity profiles across production routes.
- Steam Cracking:Established thermal cracking of hydrocarbon feedstocks at temperatures exceeding 800°C retains technology leadership due to sunk capital and optimized heat integration across integrated refining complexes.
- Catalytic Cracking:Fluidized bed processes converting heavier feedstocks into lighter olefins, prevalent in refineries with residue upgrading requirements.
- Gas-to-Liquids:Fischer-Tropsch synthesis routes converting natural gas to liquid fuels with olefin co-production, concentrated in Qatar and South Africa where stranded gas resources anchor economics.
- Fluid Catalytic Cracking:Petroleum refinery process yielding propylene-rich streams as a byproduct of gasoline production, with FCC propylene supply sensitive to transportation fuel demand cycles.
Steam cracking holds the dominant installed base; gas-to-liquids is gaining share fastest in regions with stranded natural gas resources.
End User:
End user segmentation maps how olefin derivatives flow through distinct procurement channels with varying contract structures and specification rigor.
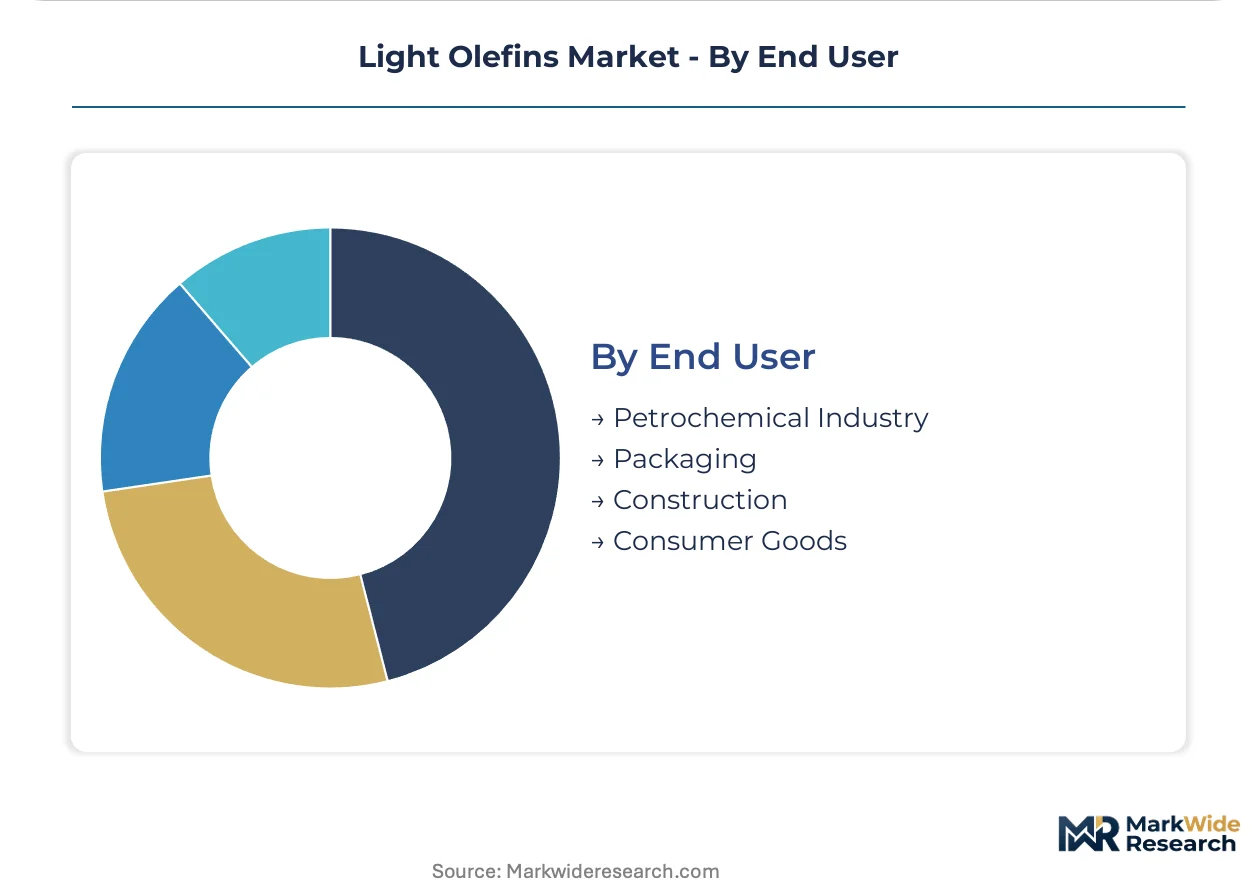
- Petrochemical Industry:Integrated producers consuming captive olefin supply for downstream derivative manufacturing, with DowDuPont leveraging Gulf Coast steam cracking networks for cost-advantaged polyethylene output.
- Packaging:Flexible and rigid packaging converters negotiating direct offtake agreements with crackers, bypassing traditional distributor intermediaries in China's eastern coastal provinces where e-commerce fulfillment density supports dedicated supply lines.
- Construction:Polyethylene pipe and geomembrane applications drawing medium-density grades, with India's PLI scheme for chemicals drawing greenfield investments toward Gujarat's Dahej Petroleum Chemical and Petrochemical Investment Region.
- Consumer Goods:Brand owners sourcing mass-balance certified packaging feedstocks, with ethanol-to-ethylene dehydration gaining traction among European converters seeking bio-based ethylene routes.
Petrochemical industry internal consumption absorbs the largest share; packaging is expanding most quickly as direct procurement consolidates under integrated converters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethane supply from the US Gulf Coast and naphtha from Middle Eastern refineries anchor regional production economics. Integrated crackers in coastal zones leverage port access for feedstock flexibility. Regulatory carbon intensity benchmarks are redirecting capital toward lighter feedstock configurations.
United States
Shale-derived ethane abundance sustains cost-advantaged steam cracking economics along the Texas-Louisiana corridor. The EPA enforces emissions thresholds for cracking furnaces under the Clean Air Act, elevating compliance investments for Gulf Coast operators. DowDuPont leverages its regional cracking network from facilities anchored in Freeport and Texas City.
China
E-commerce logistics packaging pulls polyethylene demand into Zhejiang and Jiangsu provinces where fulfillment density concentrates. The MEE implements dual carbon targets that restrict new coal-to-olefin projects and favor ethane-based configurations. Ningbo and Zhoushan host integrated refinery-olefin complexes serving direct port access for just-in-time supply contracts.
Germany
Automotive lightweighting specifications drive high-crystallinity polypropylene compounds into electric vehicle underhood applications. The EU F-Gas Regulation constrains fluorinated refrigerant use in olefin separation processes, raising retrofit capital costs. BASF and LyondellBasell operate crackers in Ludwigshafen and Wesseling within the Rhine-Ruhr chemical cluster.
Saudi Arabia
Stranded gas resources anchor gas-to-liquids economics with olefin co-production at world-scale. The SFDA regulates chemical product standards for regional export markets. Jubail Industrial City concentrates massive derivative capacity where Saudi Arabian Oil Co. anchors downstream polymer manufacturing.
India
Production-linked incentives for petrochemical manufacturing draw greenfield cracker investments toward import substitution. The BIS mandates polymer grade specifications for food-contact applications, shaping resin quality requirements. Gujarat's Dahej Petroleum Chemical and Petrochemical Investment Region hosts Reliance Industries Limited's expanding olefin derivative complex.
Light Olefins Market Competitive Environment
Global majors compete with regional champions across feedstock access and derivative integration depth. The vendor base concentrates around integrated energy-chemical conglomerates with captive feedstock supply and specialized catalyst technology licensors. Three archetypes dominate: Gulf Coast ethane-advantaged operators, Middle East gas-based producers, and Asia-Pacific naphtha crackers with downstream polymer integration. Capacity expansion and strategic feedstock partnerships constitute the primary competitive vectors as margin compression forces asset optimization.
Within the integrated energy-chemical tier, DowDuPont and Saudi Arabian Oil Co. exemplify scale-driven positioning through captive feedstock and downstream derivative control. Exxon Mobil Corporation occupies a technology-differentiated position anchored by proprietary catalyst systems. These three entities represent distinct competitive models: US Gulf Coast ethane economics, Middle East gas-resource leverage, and metallocene-based product differentiation.
| Leading Market Players |
|---|
| DowDuPont |
| PetroChina |
| Royal Dutch Shell |
| Saudi Arabian Oil Co. |
| China Petro & Chemical Corp |
| Reliance Industries Limited |
| Exxon Mobil Corporation |
| LyondellBasell |
| Honeywell International Inc. |
| Others |
Value Chain & Pricing Dynamics
Specialized cracker furnace engineering talent concentration in the US Gulf Coast and Rhine-Ruhr chemical corridor creates labor-cost differentials that widen pricing-tier spreads between premium metallocene-catalyzed grades and standard Ziegler-Natta polyethylene. These regional workforce disparities translate directly into margin structures, as crackers in higher-cost labor markets bundle technical service and quality certification into contract premiums.
Pricing Analysis
Technical service bundling separates premium contract structures from spot-market transactions, with metallocene-grade polyethylene commanding inclusion of laboratory accreditation support and food-contact compliance documentation. Price differentiation rests on catalyst technology tier and polymer grade certification level under FDA and EU REACH protocols. Cost compression in standard-grade polyethylene intensifies as naphtha-ethane feedstock spreads compress. Small-scale flexible packaging converters exhibit highest price sensitivity, while automotive Tier 1 suppliers under German KBA approval processes demonstrate lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Workforce availability constraints in eastern China's Zhejiang and Jiangsu provinces are tightening operational flexibility at integrated refinery-olefin complexes serving e-commerce fulfillment networks. Supply concentrates in China, the United States, and Saudi Arabia, with raw material dependencies on naphtha, ethane, and propane feedstocks. Single-source vulnerability to US Gulf Coast ethane export terminal capacity creates structural risk. Distribution runs through direct offtake agreements between coastal crackers and integrated packaging converters, bypassing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The light olefins sector sits in a technology-transition phase as electrified cracking furnaces displace conventional fuel-fired burners to eliminate Scope 1 emissions from ethylene production.
For Market Incumbents: Acquire specialized catalyst technology licenses to secure differentiation in metallocene-grade polyethylene as proprietary single-site catalyst supply concentrates among three specialized chemical firms. Lock long-term ethane supply contracts with US exporters before China's MEE dual carbon implementation rules accelerate demand for lower-carbon feedstock configurations. Prioritize backward integration into cracker furnace engineering talent pipelines as specialized expertise in radiant coil design retires faster than apprenticeship programs replenish capacity. For New Entrants and Emerging Players: Launch via toll manufacturing arrangements with coastal crackers in Gujarat's Dahej Petroleum Chemical and Petrochemical Investment Region, leveraging India's PLI scheme for chemicals to bypass capital-intensive greenfield construction. Target bio-based ethylene routes through ethanol-to-ethylene dehydration for European brand owners seeking mass-balance certified packaging feedstocks. White-space opportunity concentrates in automotive lightweighting polypropylene compounds for electric vehicle underhood applications where specification windows are widening. For Investors and Strategic Acquirers: Re-rating potential sits with PDH-focused propylene producers given China's MEE rejection of methanol-to-olefin proposals in Inner Mongolia and Shanxi. Long-term viability favors operators with feedstock flexibility across ethane, naphtha, and propane configurations. Acquisition target archetype: integrated crackers with direct port access and downstream polymer compounding assets. Signal to watch: provincial environmental bureau approval velocity for electrified furnace pilot projects.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethane Supply | Long-term contracts with US Gulf Coast fractionators anchor cost-advantaged cracking economics against naphtha volatility. |
| Electrified Furnace Pilot Deployment | European integrated producers at Ludwigshafen and Wesseling eliminate Scope 1 emissions to qualify for green bond financing. |
| Metallocene Catalyst Licensing | Proprietary single-site technology from Exxon Mobil Corporation differentiates polymer grades for food-contact applications. |
| PDH Capacity Expansion | Middle East operators unlock on-purpose propylene supply independent of naphtha cracking economics for polypropylene compounders. |
| Direct Offtake Agreement Consolidation | Flexible packaging converters in Zhejiang and Jiangsu bypass distributors to secure dedicated polyethylene supply lines. |
Study Parameters
Document review covered SEC 10-K filings from integrated energy-chemical conglomerates, customs and trade data from major olefin importing jurisdictions, and ACC and Cefic industry reports, complemented by interviews with plant managers at steam cracking facilities, procurement leads at downstream polyethylene converters, and technical R&D directors at catalyst technology licensors. Bottom-up capacity modeling triangulated against top-down demand aggregation from derivative consumption patterns across plastics, automotive, and packaging end-uses.
Cross-referencing historical feedstock cost spreads against expert panel assessments of cracker margin sustainability shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application end-use, technology route, and regional production hub configuration. CAGRs derived from capacity utilization trends, feedstock price elasticity coefficients, and regulatory carbon intensity benchmark trajectories. Industry-specific forecast inputs incorporated MEE dual carbon approval thresholds and EU F-Gas Regulation retrofit capital cost assumptions.
The model assumes a particular technology adoption path for electrified cracking furnaces; alternative pathways for resistive versus inductive heating elements would alter the outlook for Scope 1 emissions elimination timelines. Forecasts reflect assumptions regarding ethane export terminal expansion pace, naphtha-ethane price correlation stability, and provincial environmental bureau enforcement consistency in China. Material deviation in these triggers warrants pause and re-evaluation of capacity deployment and feedstock configuration strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Oman Pyrolysis Gasoline Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market
Petrochemicals
Pentaerythritol Market
Petrochemicals
Propylene Market
Petrochemicals
Basic Petrochemical Market
Petrochemicals
Anthracene Oil Market
Petrochemicals
Olefin Derivatives Market
Petrochemicals
Alkylate Isooctane Market
Petrochemicals
Global Perfluorocarbons Market
Petrochemicals
Malaysia Chemical and Petrochemical Market
Petrochemicals
Chemical and Petroleum Containers Market
Petrochemicals
Global Polypropylene Market
Petrochemicals
Alkylate Market
Petrochemicals
Global Butadiene Market
Petrochemicals
Petrochemical Feedstock Market
Petrochemicals
Aliphatic Hydrocarbon Market