
 Malaysia Chemical and Petrochemical Market | 2026-2036
Malaysia Chemical and Petrochemical Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Chemical and Petrochemical Market Foresight
Electronics manufacturing is restructuring Malaysia's chemical offtake patterns as semiconductor packaging and printed circuit board producers expand resin and solvent purchases. PETRONAS Chemicals Group Berhad anchors integrated olefin production across Kertih and Gebeng. Lotte Chemical Titan Holding Berhad dominates polyolefin output with substantial capacity at Pasir Gudang. BASF Petronas Chemicals leverages its specialty chemicals JV to serve automotive coatings demand from Selangor-based OEM plants.
Chemical and petrochemical operations encompass the conversion of crude oil, natural gas, and feedstock derivatives into intermediates such as ethylene, propylene, benzene, and toluene through steam cracking and catalytic reforming at temperatures exceeding 800°C, subsequently processed into polymers, solvents, and resins for industrial manufacturing. Oils and solvents sustain the largest volume throughput due to lubricant blending and coating formulations serving regional export markets. Polymers represent the fastest-expanding margin pool as engineered plastics displace metals in automotive lightweighting and electronics miniaturization across ASEAN manufacturing hubs.
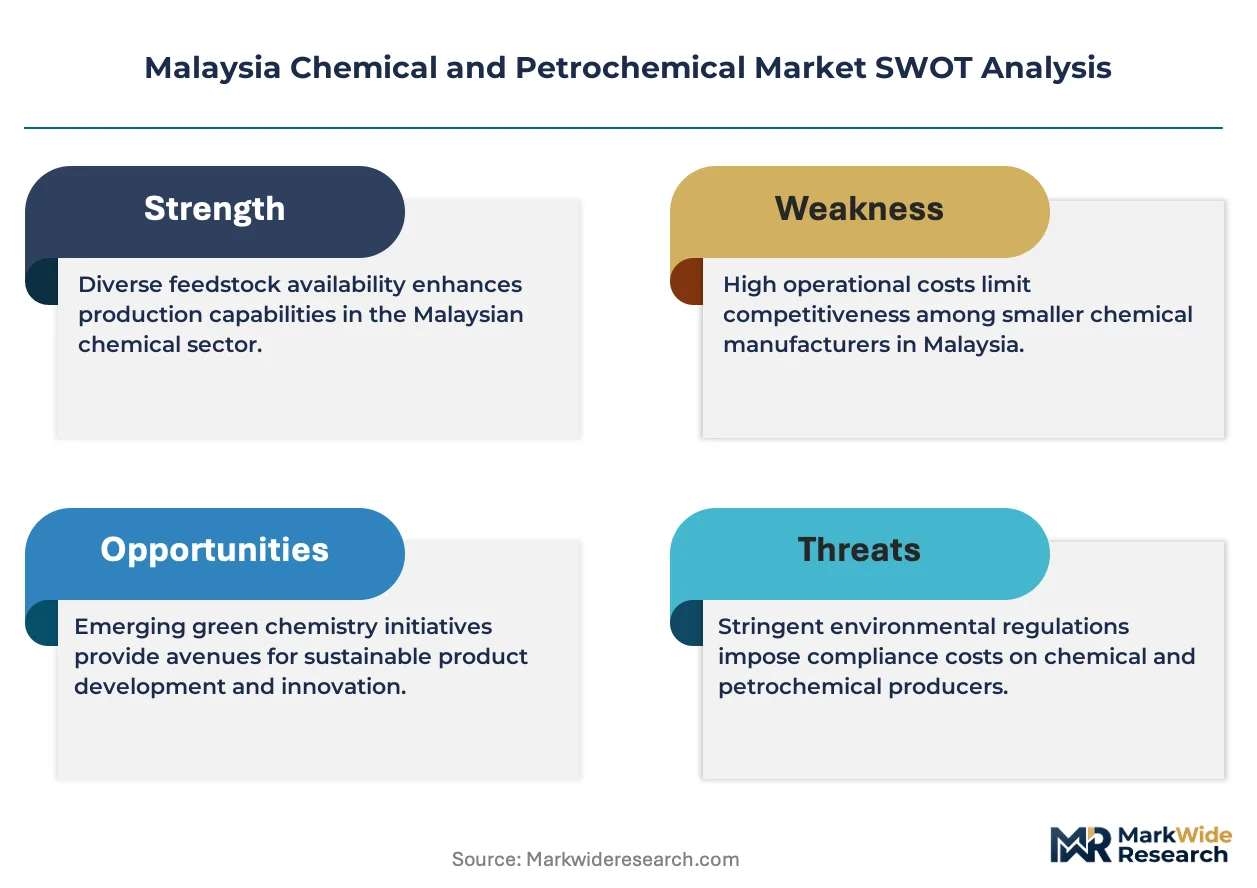
BIS certification requirements and the Department of Environment's Environmental Quality Act govern hazardous chemical handling standards and effluent discharge limits for Malaysian petrochemical facilities. The Environmental Quality (Scheduled Wastes) Regulations impose cradle-to-grave tracking obligations that elevate compliance costs for smaller compounders. Stakeholders must monitor feedstock cost volatility linked to LNG pricing dynamics and assess captive supply integration options before committing to greenfield specialty chemical investments.
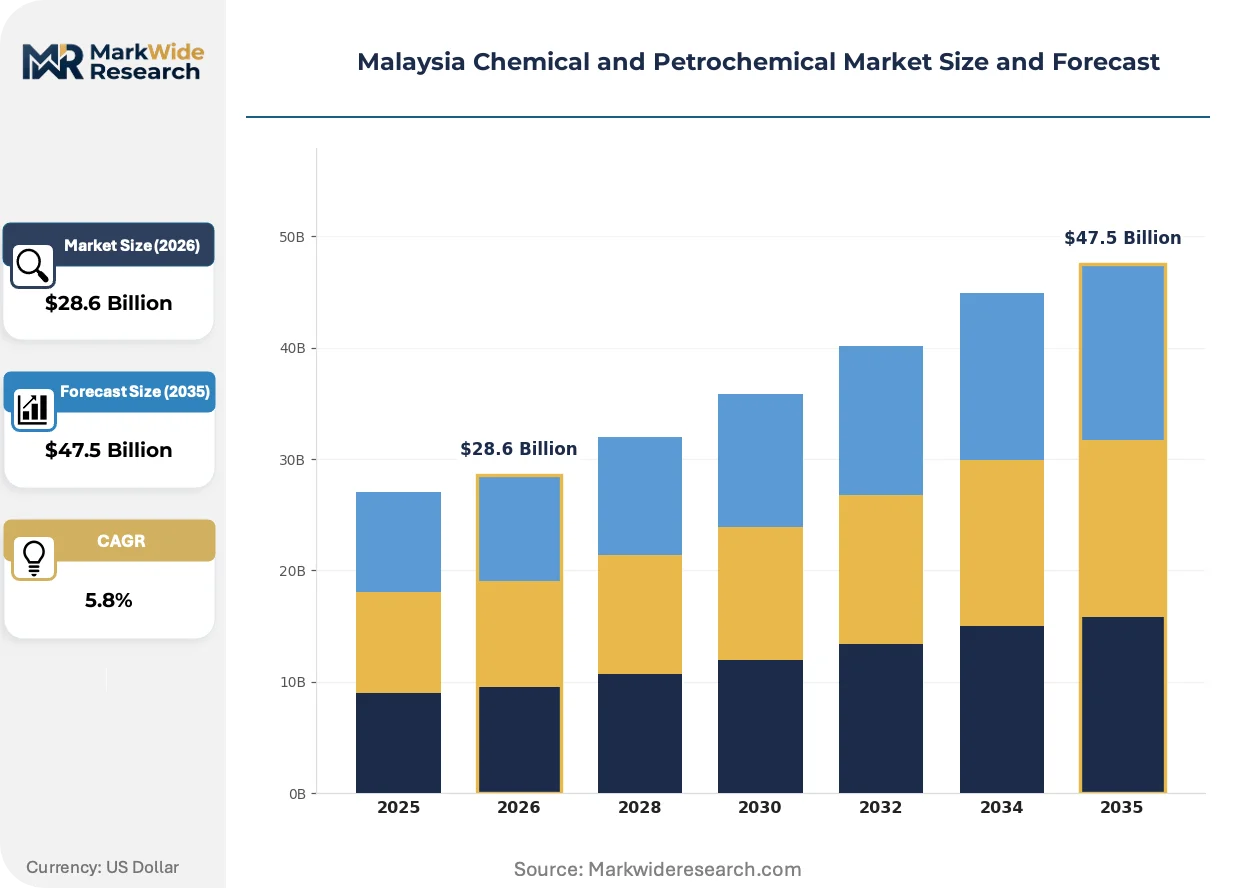
Market Dynamics
PETRONAS's RAPID complex expansion and the Malaysian Investment Development Authority's petrochemical incentives are concentrating downstream specialty chemical capacity in Johor, locking in feedstock integration advantages that reshape competitive entry economics across Peninsular Malaysia.
Growth Catalysts
- Electronics manufacturing expansion:Semiconductor packaging and printed circuit board producers across Peninsular Malaysia are expanding resin and solvent offtake, creating dedicated chemical demand corridors anchored by Selangor-based OEM plants.
- PETRONAS Chemicals Group integration:Integrated olefin production across Kertih and Gebeng provides captive feedstock supply that lowers input cost volatility for downstream polymer operations.
- Environmental Quality Act enforcement:The Department of Environment's hazardous chemical handling standards are accelerating facility upgrades that favor capital-rich integrated producers over smaller compounders.
Market Restraints
- LNG feedstock cost volatility:Steam cracking operations remain exposed to natural gas pricing dynamics that compress margins during energy price spikes.
- Johor supply concentration:The Pengerang Integrated Complex anchors concentrated downstream capacity, creating geographic vulnerability to localized disruptions.
- Scheduled Wastes tracking burden:The Environmental Quality (Scheduled Wastes) Regulations impose cradle-to-grave compliance obligations that elevate fixed costs disproportionately for smaller compounders.
Strategic Opportunities
- Automotive lightweighting applications:Engineered plastics are displacing metals in ASEAN automotive manufacturing, opening margin pools in high-performance polymer grades.
- BIS certification alignment:Harmonization with India's Bureau of Indian Standards creates export pathway advantages for Malaysian producers targeting South Asian markets.
- Electronics miniaturization demand:Specialty solvents and ultra-pure resins for advanced semiconductor packaging represent underpenetrated product categories with premium pricing potential.
Industry Challenges
- Process safety engineering talent scarcity:Steam cracking and catalytic reforming operations require specialized expertise at temperatures exceeding 800°C that outpaces local technical training pipeline output.
- Greenfield capex intensity:Specialty chemical investments require captive supply integration assessments before commitment, extending pre-construction timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Chemical and Petrochemical Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Resins, Solvents, Polymers End Use Industry: Construction, Automotive, Electronics, Textiles Application: Coatings, Adhesives, Plastics, Chemicals Trade Type: Export, Import, Local Supply, Procurement |
| Companies Covered | BASF Petronas Chemicals, Eastman Chemical, PETRONAS Chemicals Group Berhad, Mitsui Chemicals, Idemitsu Petrochemical, Lotte Chemical Titan Holding Berhad, BP Petronas, DSM Malaysia, Petronas Chemicals Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Chemical and Petrochemical Market Shifts & Advancements
Process intensification and digital twin deployment are compressing plant optimization cycles across Malaysian petrochemical complexes, while regulatory alignment pressures and buyer consolidation are restructuring traditional supply relationships.
Advanced process control systems are converging with real-time sensor networks to enable predictive maintenance across steam cracking units. PETRONAS Chemicals Group and integrated operators at Gebeng are deploying these systems to minimize unplanned outages. This convergence is compressing the competitive gap between flagship complexes and mid-scale facilities by democratizing operational excellence.
The Environmental Quality (Scheduled Wastes) Regulations are tightening cradle-to-grave tracking mandates for hazardous chemical handling. Malaysian compounders must now implement digital waste manifest systems that interface directly with Department of Environment audit protocols. Smaller facilities in Penang and Selangor face disproportionate compliance cost escalation relative to integrated Johor complexes with in-house environmental management infrastructure.
Consolidated procurement by electronics OEMs is displacing fragmented distributor relationships across solvent and resin categories. Selangor-based semiconductor packaging houses are negotiating direct supply agreements with integrated petrochemical producers, bypassing traditional chemical distributors. This pattern is most visible in the Klang Valley corridor where buyer concentration has compressed switching cycles to quarterly price renegotiations.
Malaysia Chemical and Petrochemical Market Segmentation
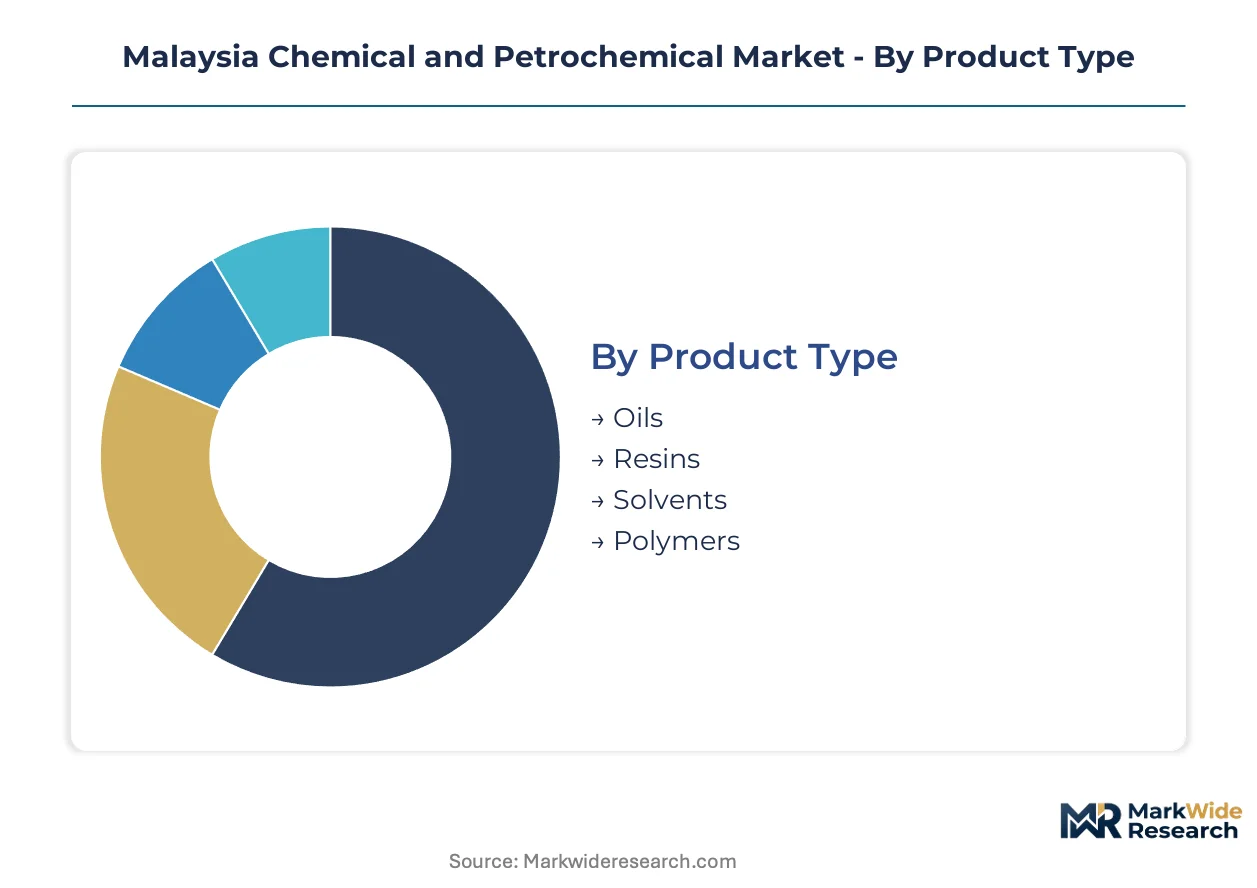
Malaysia's chemical and petrochemical market segments reveal divergent margin structures. Volume-heavy commodity streams compete against specialty grades commanding premium pricing. Understanding these splits guides capital allocation across the value chain.
Product Type:
Oils and solvents dominate tonnage throughput while polymers capture expanding margin pools through specialty grades.
- Oils:Lubricant base stocks and process oils refined from crude fractions serve regional blending operations. Demand concentrates in Klang Valley lubricant plants serving ASEAN export markets, with feedstock integration at PETRONAS refineries lowering cost volatility.
- Polymers:Polyethylene, polypropylene, and engineered thermoplastics produced via steam cracking at Gebeng and Pasir Gudang complexes. Electronics miniaturization across Penang and Selangor packaging facilities drives specialty polymer offtake with premium pricing.
- Resins:Epoxy, phenolic, and polyurethane intermediates for coatings and composites.
- Solvents:Aromatic and aliphatic hydrocarbons for industrial cleaning and formulation.
Today's leader: Oils. Tomorrow's challenger: Polymers.
End Use Industry:
Application concentration varies sharply between infrastructure-heavy sectors and precision manufacturing verticals.
- Electronics:Semiconductor packaging and printed circuit board production consumes ultra-pure solvents and specialty resins. Selangor-based OEM plants anchor demand corridors with direct procurement from integrated producers, displacing traditional distributor channels.
- Automotive:OEM coating formulations and under-the-hood plastics from Selangor assembly plants. BASF Petronas Chemicals supplies automotive coatings demand through its specialty chemicals JV, with lightweighting trends expanding engineered polymer specifications.
- Construction:Adhesives, sealants, and waterproofing membranes for infrastructure projects.
- Textiles:Dye intermediates and finishing chemicals for garment manufacturing.
Electronics commands premium pricing. Automotive offers volume scale.
Application:
Functional requirements separate commodity formulation inputs from performance-critical materials.
- Plastics:Injection molding and extrusion grades for consumer goods and industrial components. Johor's Pengerang Integrated Complex feeds downstream compounding operations with captive olefin supply, locking in integration economics.
- Coatings:Automotive OEM and industrial protective finishes requiring precise viscosity and durability specifications. Department of Environment hazardous handling standards elevate compliance costs for smaller paint manufacturers.
- Adhesives:Structural bonding and assembly applications across manufacturing sectors.
- Chemicals:Intermediate compounds for further downstream processing.
Plastics anchor volume throughput. Coatings extract margin through technical service.
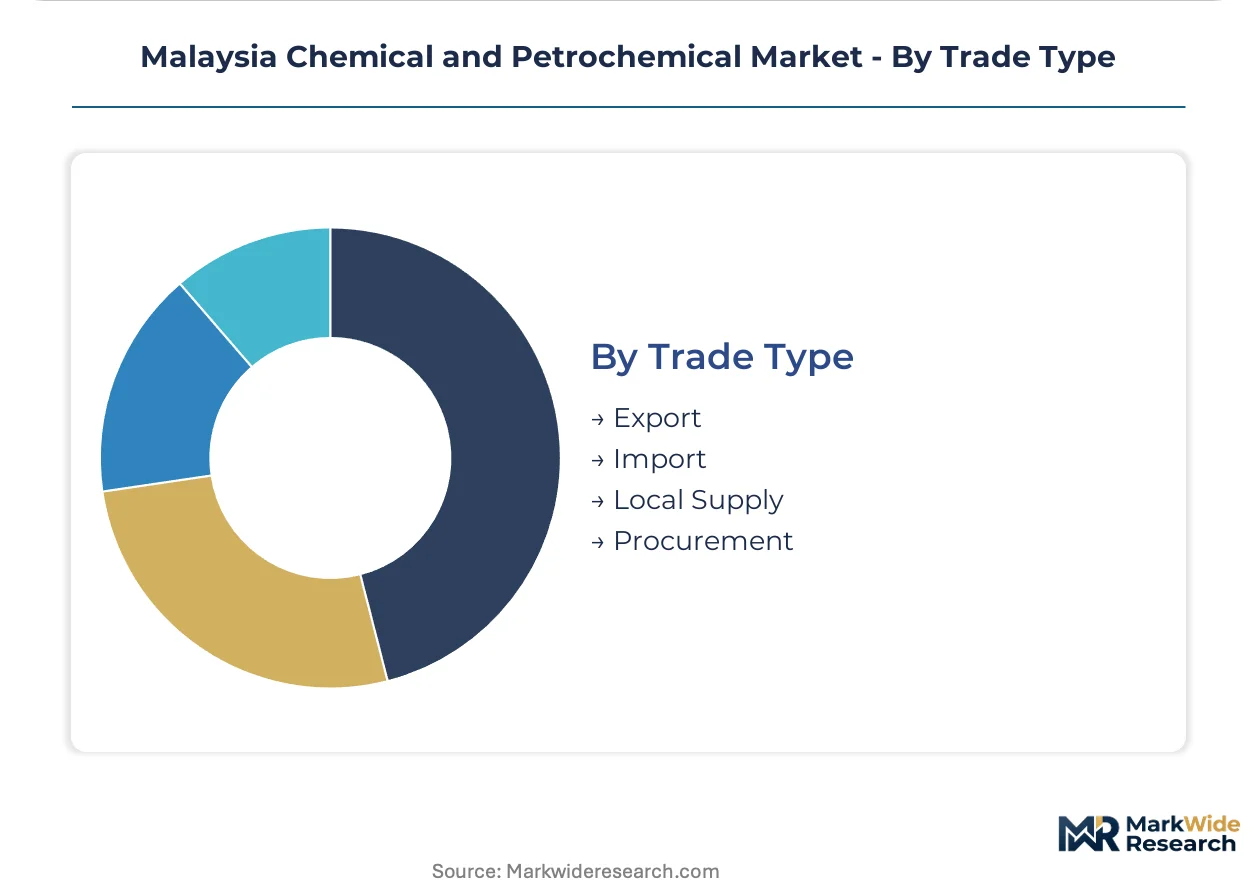
Trade Type:
Supply chain configuration determines competitive positioning between integrated producers and trading intermediaries.
- Local Supply:Captive production from PETRONAS Chemicals Group and Lotte Chemical Titan serving domestic manufacturers. Kertih and Gebeng complexes provide pipeline-connected feedstock security unmatched by import-dependent competitors.
- Export:Regional shipments to ASEAN and South Asian markets leveraging BIS certification alignment. Malaysian producers target Indian Bureau of Indian Standards compliance for cross-border advantage.
- Import:Specialty grades and feedstock supplements for non-integrated processors.
- Procurement:Direct purchasing agreements between electronics OEMs and petrochemical producers.
Local supply defends margin. Export expands addressable market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting specialty chemical investments toward jurisdictions with streamlined environmental permitting and feedstock integration advantages. Malaysia's Department of Environment enforcement patterns create compliance cost differentials that favor integrated producers over smaller compounders.
Peninsular Malaysia
Electronics manufacturing corridors in Selangor and Penang drive solvent and resin offtake for semiconductor packaging operations. The Environmental Quality Act imposes cradle-to-grave tracking obligations that elevate fixed costs for non-integrated processors. The Klang Valley lubricant blending cluster serves ASEAN export markets with pipeline-connected feedstock security from PETRONAS refineries.
Johor
The Pengerang Integrated Complex anchors concentrated downstream specialty chemical capacity with captive olefin supply from RAPID complex expansion. Malaysian Investment Development Authority petrochemical incentives accelerate capacity commitments by integrated producers. Pasir Gudang polyolefin operations feed compounding facilities serving automotive lightweighting demand from regional OEM plants.
Sarawak
Natural gas feedstock abundance supports methanol and ammonia production for regional fertilizer and industrial chemical markets. The state's national petroleum corporation joint ventures leverage LNG pricing advantages for export-oriented commodity chemical output. Bintulu's liquefied natural gas facilities provide cost-competitive feedstock integration unmatched by import-dependent Peninsular competitors.
Sabah
Petroleum refining and basic chemical processing concentrate at Labuan's duty-free industrial zone with streamlined customs procedures for re-export markets. The federal territory's offshore financial center status complements chemical trading and procurement operations. Sipitang oil and gas installations feed regional demand for fuel additives and process chemicals.
Malaysia Chemical and Petrochemical Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated olefin producers commanding feedstock-integrated positions in commodity polymers while specialty chemical joint ventures capture premium pricing in automotive and electronics applications. The market structure concentrates around three strategic archetypes: national oil company chemical divisions with captive feedstock, Asian conglomerate petrochemical subsidiaries with scale advantages, and European-Japanese specialty chemical joint ventures with technical service capabilities. Dominant competitive moves include backward integration into olefin production and strategic partnerships with electronics OEMs for direct procurement relationships.
Among integrated national champions, PETRONAS Chemicals Group Berhad and Lotte Chemical Titan Holding Berhad exemplify the feedstock-integrated archetype with pipeline-connected operations across Kertih, Gebeng, and Pasir Gudang. BASF Petronas Chemicals occupies the specialty joint venture tier, leveraging European technical capabilities with Malaysian feedstock access for automotive coatings and engineered polymer applications. These three entities represent distinct competitive positioning vectors that smaller compounders struggle to replicate without captive supply integration.
| Leading Market Players |
|---|
| BASF Petronas Chemicals |
| Eastman Chemical |
| PETRONAS Chemicals Group Berhad |
| Mitsui Chemicals |
| Idemitsu Petrochemical |
| Lotte Chemical Titan Holding Berhad |
| BP Petronas |
| DSM Malaysia |
| Petronas Chemicals Group |
| Others |
Supply & Pricing Matrix
Captive olefin integration at PETRONAS Chemicals Group and Lotte Chemical Titan facilities anchors supply security and pricing power across Peninsular Malaysia's downstream polymer operations. This feedstock control insulates integrated producers from LNG volatility that compresses margins at import-dependent compounders.
Pricing Analysis
Distributor margins have collapsed under direct-to-OEM procurement pressure from Selangor-based electronics manufacturers. Contract-based long-term offtake agreements dominate volume transactions, with price differentiation driven by certification grade and volume scale. Cost compression in standard-grade polymers is intensifying because Chinese import competition has eroded regional pricing floors. Electronics OEMs exhibit the lowest price sensitivity due to specification-critical applications, while construction-sector buyers remain highly elastic.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from semiconductor packaging houses, bypassing traditional chemical distributors entirely. Geographic supply concentrates in Malaysia, Singapore, and Thailand, with raw material dependencies on natural gas feedstock, naphtha imports, and catalyst supplies. Single-source vulnerability runs through the Pengerang Integrated Complex, where localized disruption would cascade across downstream specialty chemical output. Distribution runs through pipeline-connected complexes for integrated producers and bonded warehouse networks for non-integrated processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's chemical and petrochemical market reads as a late-cycle quality story, with electronics miniaturization demand shifting procurement toward ultra-pure specialty grades that command sustained premium pricing.
For Market Incumbents: Acquire specialty solvent production capabilities to defend against direct-procurement erosion from Selangor-based OEMs. Deepen backward integration into catalyst manufacturing to reduce import dependency. Prioritize BIS certification investment to capture Indian export corridor growth. For New Entrants and Emerging Players: Enter via niche engineered polymer compounding for automotive lightweighting applications in Johor's supplier park corridor. Target Penang's semiconductor packaging cluster with ultra-pure resin formulations. Pursue toll manufacturing partnerships with established distributors to bypass captive feedstock disadvantages. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale compounders with environmental compliance infrastructure because Department of Environment tracking mandates have created fixed-cost barriers that favor scaled operators. Long-term viability centers on specialty grade migration rather than commodity volume exposure. Watch electronics OEM consolidation patterns as the inflection signal for distributor displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive olefin supply from RAPID complex expansion locks in feedstock cost advantages for downstream polymer operations. |
| Green Manufacturing Transition | Digital waste manifest systems align with Environmental Quality Act cradle-to-grave tracking mandates. |
| Long-term Supply Agreement | Direct procurement contracts with Selangor semiconductor packaging houses displace traditional distributor relationships. |
| Joint Venture | European-Asian specialty chemical partnerships replicate BASF Petronas Chemicals' technical service model. |
| Capacity Expansion | Pengerang Integrated Complex additions concentrate downstream specialty chemical output with pipeline-connected feedstock security. |
Research Methodology
Multiple input streams — primary interviews with plant managers and procurement leads at downstream OEMs, secondary validation through customs/trade data and SEC filings, and technical R&D director surveys — were reconciled through bottom-up and top-down triangulation. Stakeholder perspectives from distribution channel partners provided demand-side corroboration. ACC and Cefic industry reports supplied regional benchmark context.
Data-stream reconciliation across the projection horizon applied grade tier, end-use industry, and regional production hub segmentation dimensions. CAGRs were derived from modeled volume trajectories and value-per-ton assumptions. Forecast inputs incorporated LNG pricing correlation coefficients and electronics production index sensitivity factors.
Inputs from plant-level operational disclosures and trade association datasets were available through the study window; gaps in real-time inventory positioning data introduce uncertainty bands around quarterly demand fluctuation estimates. Forecasts reflect base-case assumptions regarding RAPID complex expansion timelines and electronics manufacturing relocation patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Pentane Market
Petrochemicals
Bioisobutene Market
Petrochemicals
Global Methyl Tertiary Butyl Ether Market
Petrochemicals
Global Butadiene Market
Petrochemicals
Light Olefins Market
Petrochemicals
Propane Market
Petrochemicals
Alkylate Market
Petrochemicals
Fossil Fuel-Based Plastics Market
Petrochemicals
Anthracene Oil Market
Petrochemicals
Global Perfluorocarbons Market
Petrochemicals
Alkylate Isooctane Market
Petrochemicals
Petrochemical Feedstock Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market
Petrochemicals
Pentaerythritol Market
Petrochemicals
Bio Butadiene Market
Petrochemicals
Basic Petrochemical Market