
 Global Naphthenic Base Oil Market | 2026-2036
Global Naphthenic Base Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Naphthenic Base Oil Market Foresight
Subscription-based oil condition monitoring is expanding as a service-component layer that changes what refiners sell to industrial buyers. Chevron Corporation leverages its integrated lubricant testing platforms to anchor long-term supply contracts with power utilities. Nynas AB specializes in transformer-grade naphthenic oils and dominates the European electrical insulation segment through direct technical service agreements.
Naphthenic base oil consists of cycloparaffin-rich crude fractions refined through selective solvent extraction and hydrofinishing to achieve low pour points and excellent solvency. Heavy Naphthenic grades lead volume demand due to their dominance in transformer oil formulations where oxidation stability governs asset life. Metalworking Fluids represents the fastest-growing end-user category as precision manufacturing expands in Asia-Pacific markets. API Group I classification remains the largest grade segment though margin pools are shifting toward specialized Non-API products for electrical applications.
REACH in Europe and API licensing protocols in North America shape product formulation standards and cross-border market access for naphthenic base oil suppliers. EPA oversight of used oil recycling and China's GB standards for transformer fluids are tightening purity and environmental compliance thresholds. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with diverging certification requirements.
Market Dynamics
Power utilities in China, India, and Indonesia are retiring transformer fleets installed during the 1980s rural electrification wave, creating a replacement cycle that concentrates naphthenic base oil procurement around electrical insulation specifications rather than traditional lubricant performance metrics.
Growth Catalysts
- REACH substance restrictions:ECHA's tightening limits on polycyclic aromatics in mineral oils are disqualifying paraffinic alternatives from European transformer applications, redirecting specification authority toward naphthenic producers with hydrofinishing capabilities.
- Metalworking precision manufacturing:Automotive component machining in Thailand and Vietnam requires soluble oil formulations with the low pour points and high solvency that heavy naphthenic grades deliver for aluminum and titanium alloy cutting.
- Grid hardening mandates:India's Central Electricity Authority has issued revised transformer oil standards under CEA Technical Standards that mandate oxidation stability testing, accelerating qualification of specialized naphthenic suppliers.
Market Restraints
- Crude slate concentration:Viable naphthenic feedstock derives from a narrow band of Venezuelan, Egyptian, and Indonesian crudes, exposing refiners to geopolitical supply disruptions and freight cost volatility.
- API Group II/III substitution:Hydrocracker investments by Middle Eastern refiners are expanding paraffinic base oil output with viscosity index improvers that approximate naphthenic solvency at lower sulfur content.
- REACH registration burdens:ECHA's Substance Information Exchange Forums impose data-sharing costs and hazard communication obligations that disproportionately burden smaller naphthenic blenders without dedicated regulatory affairs teams.
Strategic Opportunities
- Indonesia's archipelago electrification:PLN's 35,000 MW capacity expansion program requires tropical-grade transformer oils with ultra-low pour points that naphthenic chemistry achieves without pour point depressant additives.
- Re-refining integration:Used transformer oil collection networks in Germany and France can anchor closed-loop supply contracts with utilities seeking Scope 3 emissions reductions under CSRD disclosure requirements.
- Non-API electrical grades:Formulations optimized for supergrid HVDC converter stations command specification premiums outside standard API licensing protocols, creating margin pools insulated from commodity Group I pricing.
Industry Challenges
- Hydrofinishing catalyst expertise:Achieving sub-10 ppm sulfur in transformer-grade naphthenic oils requires proprietary noble metal catalyst systems and reactor operating knowledge concentrated among a handful of European engineering contractors.
- Dual certification timelines:Simultaneous pursuit of IEC 60296 electrical standards and ASTM D3487 utility specifications stretches product development cycles and delays market entry for reformulated grades.
- Feedstock assay variability:Naphthenic crude sourcing from multiple origins creates batch-to-batch aromatic ring distribution shifts that complicate consistent pour point and dielectric loss factor performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Naphthenic Base Oil Market |
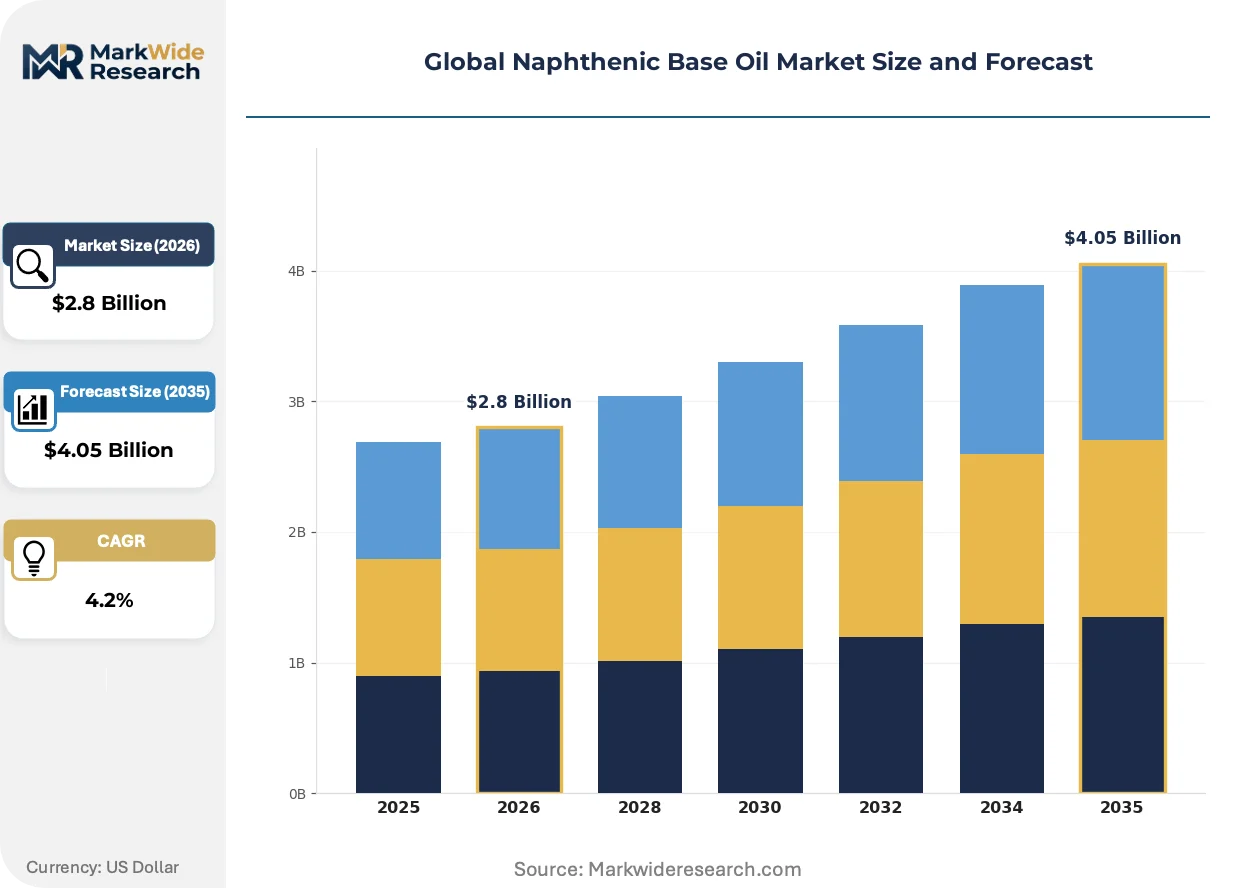
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.05 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy Naphthenic, Light Naphthenic, Medium Naphthenic, Super Heavy Naphthenic End User: Automotive Lubricants, Industrial Oils, Metalworking Fluids, Greases Grade: API Group I, API Group II, API Group III, Non-API Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Chevron Corporation, TotalEnergies SE, Nynas AB, PetroChina Company Limited, Exxon Mobil Corporation, Ergon, Inc., Royal Dutch Shell PLC, Apar Industries Limited, Calumet Specialty Products Partners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Naphthenic Base Oil Market Shifts & Advancements
Digital oil condition monitoring is compressing replacement intervals and shifting supplier relationships from transactional volume sales toward performance-guaranteed service contracts anchored by real-time analytics platforms.
Gas-to-liquid base oil technology is integrating Fischer-Tropsch wax hydroisomerization with selective aromatic extraction to synthesize naphthenic-equivalent structures from natural gas feedstocks. Shell's Pearl GTL facility in Qatar and Sasol's Lake Charles complex are piloting these hybrid process trains for electrical insulation applications. This synthetic route is integrating carbon intensity tracking into utility procurement scoring, enabling premium positioning for certified low-carbon transformer fluids.
EPA's revised Used Oil Management Standards under 40 CFR 279 are tightening tracking and recycling requirements for transformer fluids containing PCBs above 50 ppm thresholds. Refiners must now maintain chain-of-custody documentation from collection through re-refining, increasing compliance overhead but creating barriers against informal reprocessors. North American utilities are responding by consolidating supplier lists around vertically integrated re-refiners with certified destruction capabilities.
Condition-based maintenance contracts are displacing calendar-based transformer oil replacement across Japanese and South Korean power utilities. Yokogawa Electric and Mitsubishi Electric are deploying dissolved gas analysis sensors that trigger fluid processing decisions based on fault gas accumulation rates rather than elapsed service time. This behavioral shift concentrates purchasing authority within centralized procurement teams that negotiate multi-year technical service agreements rather than spot volume purchases.
Global Naphthenic Base Oil Market Segmentation
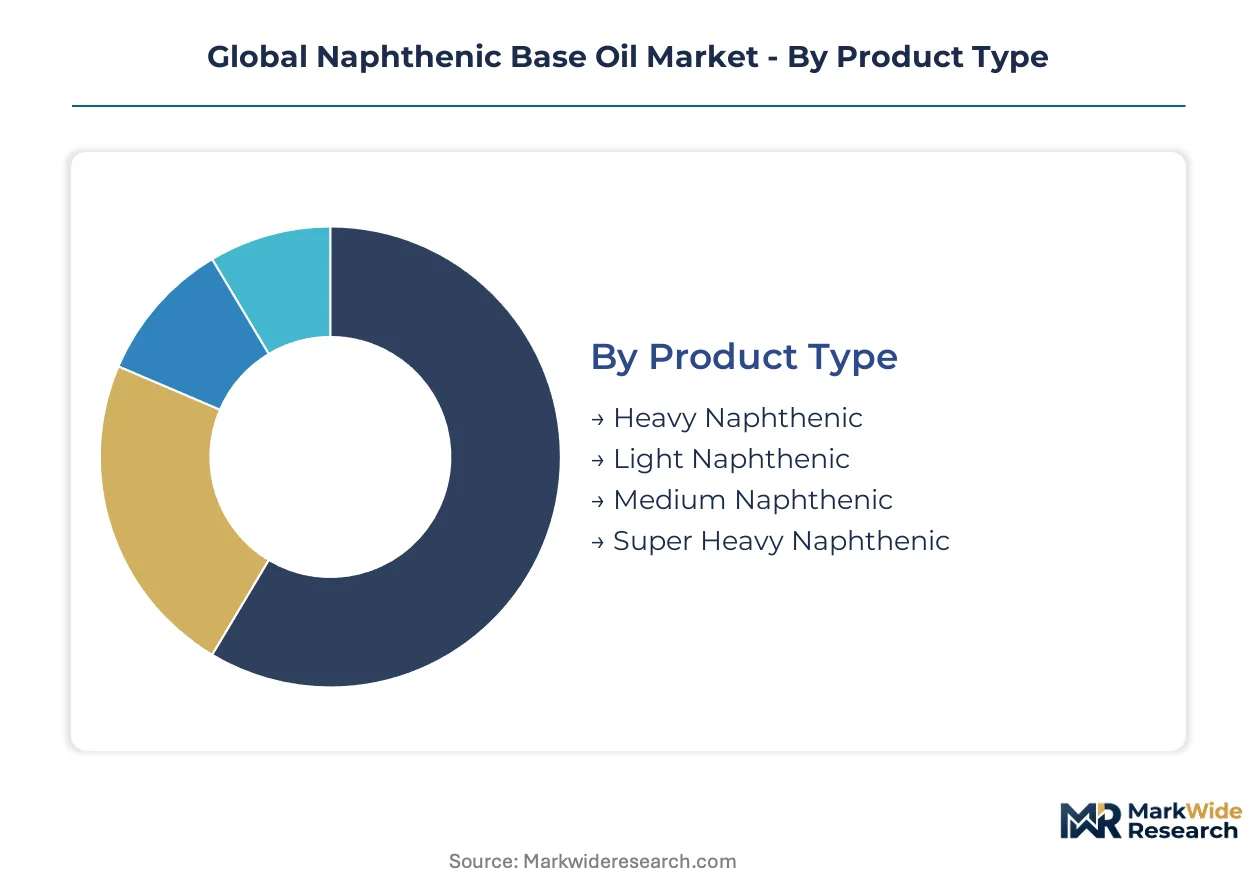
Naphthenic base oil procurement operates through specification-driven qualification systems where product certification determines market access more than price competition. Each segment carries distinct regulatory burdens that reshape supplier portfolios and margin structures across electrical insulation, metalworking, and lubricant applications.
Product Type:
API licensing protocols, IEC 60296 electrical standards, and transformer OEM approvals create tiered certification barriers that Heavy and Super Heavy grades must clear for utility contracts, while Light and Medium grades navigate less stringent industrial lubricant specifications.
- Heavy Naphthenic:Cycloparaffin-rich fractions with viscosity ranges of 40-100 cSt at 40°C dominate transformer oil formulations. Demand concentrates in China's State Grid infrastructure upgrades where oxidation stability testing under CEA Technical Standards governs supplier selection. Pour points below -40°C without additive packages justify specification premiums.
- Light Naphthenic:Lower viscosity grades (8-20 cSt) serve metalworking fluid diluents and refrigeration compressor lubricants. Precision machining clusters in Thailand's Eastern Economic Corridor and Vietnam's Binh Duong province require the high solvency and rapid heat dissipation these grades deliver for aluminum alloy cutting operations.
- Medium Naphthenic:Intermediate viscosity positioning suits hydraulic fluid formulations and industrial gear oils. REACH registration requirements in Europe and GB standard compliance in China fragment supplier qualification pathways.
- Super Heavy Naphthenic:Ultra-high viscosity bases (>150 cSt) anchor cable impregnation compounds and specialty grease thickeners. Limited hydrofinishing capacity constrains qualified supply to a narrow refiner set.
Heavy Naphthenic sits at the top of the volume ranking, with Metalworking Fluids climbing the fastest among end-use applications driving Light grade consumption.
End User:
Customer procurement sophistication varies sharply across segments, with power utilities demanding multi-year technical service agreements while automotive lubricant blenders prioritize spot pricing and freight optimization.
- Metalworking Fluids:Soluble oil formulations for precision manufacturing require low pour points and high solvency that Heavy Naphthenic grades deliver. Thailand's automotive component machining sector and Vietnam's aerospace parts suppliers anchor demand concentration.
- Industrial Oils:Hydraulic fluids, compressor lubricants, and refrigeration oils specify naphthenic bases for thermal stability. Indonesia's manufacturing expansion and India's industrial automation drive specification diversity.
- Automotive Lubricants:Engine oil and transmission fluid applications face substitution pressure from API Group II/III paraffinic bases with viscosity index improvers. Passenger vehicle OEM approvals in China and India determine accessible volume pools.
- Greases:Lithium and calcium soap thickeners utilize Super Heavy grades for structural stability. Mining equipment maintenance in Australia and construction machinery in Brazil concentrate procurement.
Industrial Oils commands the largest revenue share, with Metalworking Fluids expanding most quickly as precision manufacturing relocates to Southeast Asia.
Grade:
Margin structures diverge sharply between commodity API-licensed products and specialized Non-API electrical grades where specification premiums offset smaller production runs.
- API Group I:Conventional solvent-refined bases with sulfur content above 0.03% and viscosity index below 120 dominate volume production. Price competition from paraffinic substitutes compresses margins in automotive and industrial lubricant applications.
- Non-API:Transformer-grade formulations optimized for IEC 60296 and ASTM D3487 electrical standards command specification premiums outside commodity pricing. HVDC converter station applications in China and Germany require ultra-low sulfur and controlled aromatic content that only specialized hydrofinishing achieves.
- API Group II:Hydrocracked bases with improved viscosity index and lower sulfur content approximate naphthenic solvency through additive packages. Middle Eastern refinery expansions increase competitive pressure.
- API Group III:Severely hydrocracked bases with viscosity index above 120 compete directly in high-performance lubricant segments. Synthetic-equivalent positioning under API definitions limits naphthenic penetration.
API Group I retains volume leadership, with Non-API grades gaining share fastest as electrical infrastructure investment accelerates.
Distribution Channel:
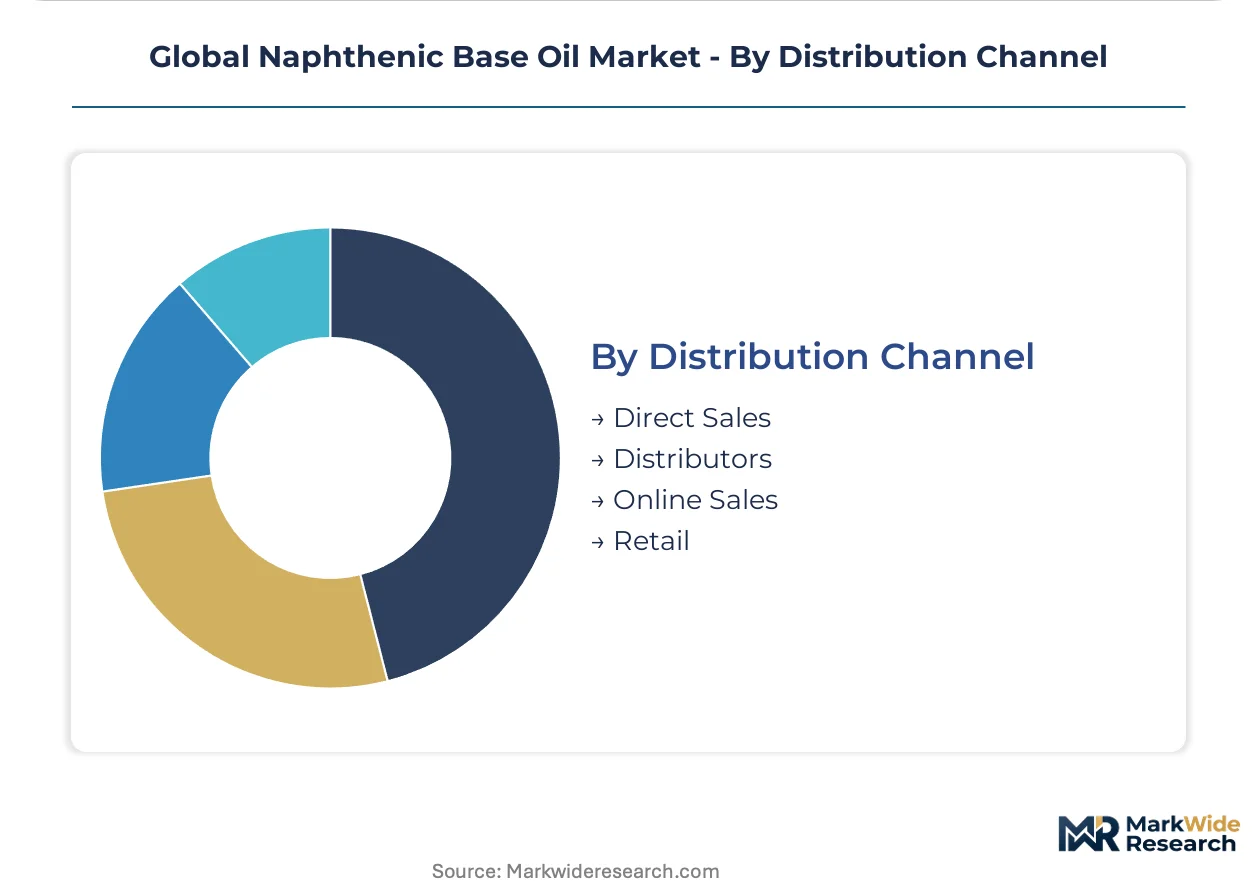
Channel selection reflects order scale and technical service intensity, with direct sales dominating utility contracts while distributors fragment industrial lubricant supply.
- Direct Sales:Long-term supply agreements with power utilities, transformer OEMs, and national oil companies anchor volume concentration. Technical service integration including oil condition monitoring and dissolved gas analysis locks in supplier relationships.
- Distributors:Regional blending facilities and industrial lubricant compounders access smaller batch sizes with customized additive packages. Fragmented metalworking fluid formulators in Southeast Asia rely on distributor networks for inventory management.
- Online Sales:Emerging procurement channel for standardized industrial lubricant grades with transparent pricing. Limited penetration in transformer oil segments due to certification documentation requirements.
- Retail:Automotive aftermarket lubricants and small-volume industrial maintenance products. Marginal channel share constrained by naphthenic base oil's industrial end-use concentration.
Direct Sales captures the largest transaction value, with Distributors expanding quickest as regional metalworking clusters multiply across Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refiners are relocating hydrofinishing capacity toward jurisdictions with streamlined chemical registration protocols, exploiting cost-of-compliance gaps between REACH-intensive Europe and emerging Asian regulatory frameworks. This arbitrage is redrawing supply maps as transformer-grade production concentrates where certification timelines compress.
China
State Grid's rural electrification retrofits and HVDC supergrid expansion drive Heavy Naphthenic procurement for oxidation-stable transformer oils. GB standards for transformer fluids under SAMR oversight mandate dielectric testing that favors domestic hydrofinishing investments. Yangtze River Delta refineries near Shanghai are expanding specialty electrical-grade output to serve eastern province utilities.
United States
EPA's Used Oil Management Standards under 40 CFR 279 are consolidating utility supplier lists around re-refiners with certified PCB destruction capabilities. Gulf Coast petrochemical complexes leverage integrated hydrocracker capacity to produce Group I-equivalent naphthenic bases for domestic transformer fleets. Texas and Louisiana refiners anchor North American electrical insulation supply through direct utility contracting.
India
CEA Technical Standards revisions mandate oxidation stability testing for transformer oils, accelerating supplier qualification timelines for specialized naphthenic producers. PLI scheme incentives for power infrastructure are amplifying procurement volumes from State Electricity Boards. Gujarat and Maharashtra industrial corridors concentrate metalworking fluid demand from precision automotive component machining clusters.
Germany
ECHA's polycyclic aromatic restrictions under REACH are disqualifying paraffinic alternatives from transformer applications, reinforcing specification authority for hydrofinished naphthenic suppliers. CSRD disclosure requirements are pushing utilities toward closed-loop re-refining contracts with Scope 3 tracking. Ruhr Valley chemical complexes maintain European electrical insulation leadership through IEC 60296 certification dominance.
Indonesia
PLN's 35,000 MW archipelago electrification program requires tropical-grade transformer oils with ultra-low pour points achievable through native naphthenic chemistry. The country's national energy regulator is aligning local content requirements with specialty base oil import substitution goals. Java-Bali grid interconnection projects concentrate procurement authority in Jakarta-based technical evaluation committees.
Global Naphthenic Base Oil Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated majors dominating electrical-grade certification and regional blenders capturing metalworking fluid volumes. Market structure tilts toward oligopoly in transformer oils where IEC and ASTM dual certification creates entry barriers, while industrial lubricant supply fragments across distributor networks. Two archetypes anchor competitive positioning: vertically integrated refiners with captive hydrofinishing capacity, and formulation specialists leveraging technical service agreements to lock in utility contracts. Capacity expansion in Middle Eastern Group II/III production and backward integration into used oil re-refining represent the dominant competitive vectors reshaping supplier portfolios.
Among integrated majors, Chevron Corporation and Exxon Mobil Corporation exemplify the certification-heavy archetype through direct utility anchoring, while Nynas AB occupies a specialized position within European electrical insulation supply. These three entities represent contrasting geographic and structural approaches to the transformer-grade segment, with US-based multinationals leveraging scale and Swedish-incorporated specialists emphasizing technical service intensity.
| Leading Market Players |
|---|
| Chevron Corporation |
| TotalEnergies SE |
| Nynas AB |
| PetroChina Company Limited |
| Exxon Mobil Corporation |
| Ergon, Inc. |
| Royal Dutch Shell PLC |
| Apar Industries Limited |
| Calumet Specialty Products Partners |
| Others |
Supply & Pricing Matrix
Crude slate concentration in Venezuelan, Egyptian, and Indonesian feedstocks cascades through refinery gate pricing into three distinct procurement tiers for transformer-grade, industrial lubricant, and metalworking fluid buyers. Freight differentials on heavy sour barrels from these origins compress margins for European hydrofinishing operations while amplifying pricing power for integrated Gulf Coast producers with captive dock access.
Pricing Analysis
Distributor margin layering separates spot-volume metalworking fluid transactions from long-term utility contracts with embedded technical service fees. Three-tier pricing structure across premium transformer-grade, standard industrial lubricant, and economy metalworking diluent levels reflects IEC 60296 certification intensity and sulfur content thresholds. Cost compression in the commodity Group I tier intensifies because Middle Eastern Group II/III expansions approximate naphthenic solvency at lower sulfur baselines. Power utilities demonstrate the lowest price sensitivity due to asset-life guarantees, while automotive lubricant blenders exhibit acute spot-price responsiveness.
Supply Chain Analysis
Freight cost volatility on long-haul naphthenic crude movements from Venezuela and Indonesia amplifies working capital requirements for European and Asian refiners without integrated shipping fleets. Geographic supply concentration centers on the United States Gulf Coast, Germany's Ruhr Valley, and China's Yangtze River Delta where hydrofinishing capacity clusters. Raw material dependencies rest on cycloparaffin-rich crude assays, noble metal catalyst systems, and specialized solvent extraction units. Single-source vulnerability from Venezuelan crude sanctions exposure threatens consistent heavy naphthenic feedstock availability. Distribution runs through direct sales channels for electrical insulation grades and fragmented distributor networks for industrial lubricant volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in naphthenic base oil hinges on specification premium capture in transformer-grade segments as utilities prioritize oxidation stability over unit cost, while hydrofinishing scale economies compress per-barrel processing overhead.
For Market Incumbents: Deploy captive hydrofinishing capacity expansion in jurisdictions with streamlined chemical registration protocols to defend against REACH-registered European specialists. Anchor long-term utility contracts through integrated oil condition monitoring platforms that embed switching costs. Counter API Group II/III substitution threats by emphasizing pour point performance without additive packages in tropical transformer applications. For New Entrants and Emerging Players: Regional metalworking fluid formulators in Vietnam's Binh Duong province and Thailand's Eastern Economic Corridor represent the most penetrable channel partner type for light naphthenic grade distribution. Target precision machining clusters requiring soluble oil formulations with documented heat dissipation performance. Pursue toll-processing arrangements with established hydrofinishing operators to bypass capital-intensive reactor investments. For Investors and Strategic Acquirers: Consolidation pressure builds where dual IEC 60296 and ASTM D3487 certification timelines stretch product development cycles beyond smaller blenders' capital endurance. Long-term viability favors vertically integrated refiners with captive feedstock sourcing and re-refining capabilities that capture Scope 3 disclosure premiums from European utilities. Acquisition target archetypes include specialized transformer-grade producers with established utility technical service agreements. Monitor ECHA substance restriction proposals as inflection indicators for paraffinic disqualification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Used Oil Re-refining | Captures closed-loop utility contracts under CSRD Scope 3 tracking requirements in Germany. |
| Hydrofinishing Capacity Expansion | Positions Yangtze River Delta refiners to serve State Grid's GB-standard transformer oil procurement. |
| Long-term Technical Service Agreement | Locks in Japanese utility procurement authority shifting from calendar-based to condition-based maintenance. |
| Joint Venture with Regional Distributor | Accelerates penetration of Vietnam's precision machining clusters requiring light grade soluble oils. |
| Green Manufacturing Transition | Enables premium positioning for certified low-carbon transformer fluids in German HVDC converter stations. |
Research Methodology
Direct dialogue with refinery operations managers, power utility procurement directors, transformer OEM technical specification leads, and metalworking fluid formulators grounded qualitative assessment in operational realities. Secondary validation drew from customs trade data on naphthenic crude and base oil movements, IEC and ASTM standard documentation, SEC filings from integrated petroleum majors, and CEA Technical Standards revisions. Bottom-up volume modeling across grade tiers and end-use segments triangulated against top-down macroeconomic drivers of electrical infrastructure investment and precision manufacturing relocation.
Top-down macroeconomic indicators of grid hardening mandates and rural electrification programs anchored the analytical lens, while bottom-up segment modeling across API Group I, Non-API electrical, and specialty industrial grades populated volume and value outputs across the projection horizon. Segmentation dimensions included viscosity grade tier, end-use application intensity, certification protocol cluster, and regional regulatory framework. CAGRs emerged from fitted growth curves on historical procurement patterns and infrastructure investment pipelines. Industry-specific forecast inputs incorporated transformer fleet replacement cycles and metalworking precision manufacturing capacity additions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Venezuelan crude supply disruptions, ECHA polycyclic aromatic restriction tightening, and Middle Eastern Group II/III capacity commissioning timelines. Forecasts reflect documented assumptions on feedstock assay stability and utility procurement behavior shifts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Europe Carbon Black Market
Bulk Chemicals
Potassium Hydrogen Sulfite Market
Bulk Chemicals
Nonprotein Nitrogen Market
Bulk Chemicals
Asia-Pacific Lithium Chloride Market
Bulk Chemicals
Sodium Hydrogen Sulphite Market
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
Propionic Acid Market
Bulk Chemicals
Benzyl Chloroformate Market
Bulk Chemicals
United States Iodine Market
Bulk Chemicals
Sodium Bisulfite Market
Bulk Chemicals
Needle Coke Market
Bulk Chemicals
Triammonium Citrate Market
Bulk Chemicals
Monoethylene Glycol (MEG) Market
Bulk Chemicals
Europe Lipids Market
Bulk Chemicals
Global Lithium Derivatives Market
Bulk Chemicals
Asia-Pacific Formic Acid Market