

Bio Butadiene Market Size, Share, and Industry Trends Forecast 2026-2036
Bio Butadiene Market Insights
The capital-intensity divergence between integrated petrochemical giants and specialty biotech entrants is collapsing as fermentation-based production reaches commercial scale. SABIC leverages its existing crackers and logistics infrastructure to trial bio-butadiene co-feeding at European sites. Braskem anchors its position through backward integration into sugarcane-derived feedstocks at Brazilian operations. Evonik Industries differentiates via catalyst technology for selective dehydration of bio-ethanol to butadiene.
Bio butadiene denotes a C4 hydrocarbon produced from renewable biomass feedstocks rather than naphtha cracking, typically achieving minimum bio-based carbon content of 70% under ASTM D6866 testing protocols and serving as a drop-in monomer for synthetic rubber and polymer resin manufacturing. Fermentation pathways currently lead commercial deployment while catalytic conversion from bio-ethanol captures growing investment due to higher throughput yields. Tire manufacturing dominates application demand, though polymer resins for automotive interiors represent the fastest-expanding margin pool as OEMs enforce recycled and renewable content quotas.
The EU Green Deal and REACH framework restrict fossil-derived monomer content in tires sold within Europe, while EPA renewable fuel standards in the United States create compliance credit value for bio-based chemical pathways. BIS certification requirements in India mandate disclosure of bio-based content percentages for imported elastomer compounds. Stakeholders must monitor feedstock cost volatility against crude oil benchmarks and secure offtake agreements with tire manufacturers before committing to greenfield fermentation capacity.
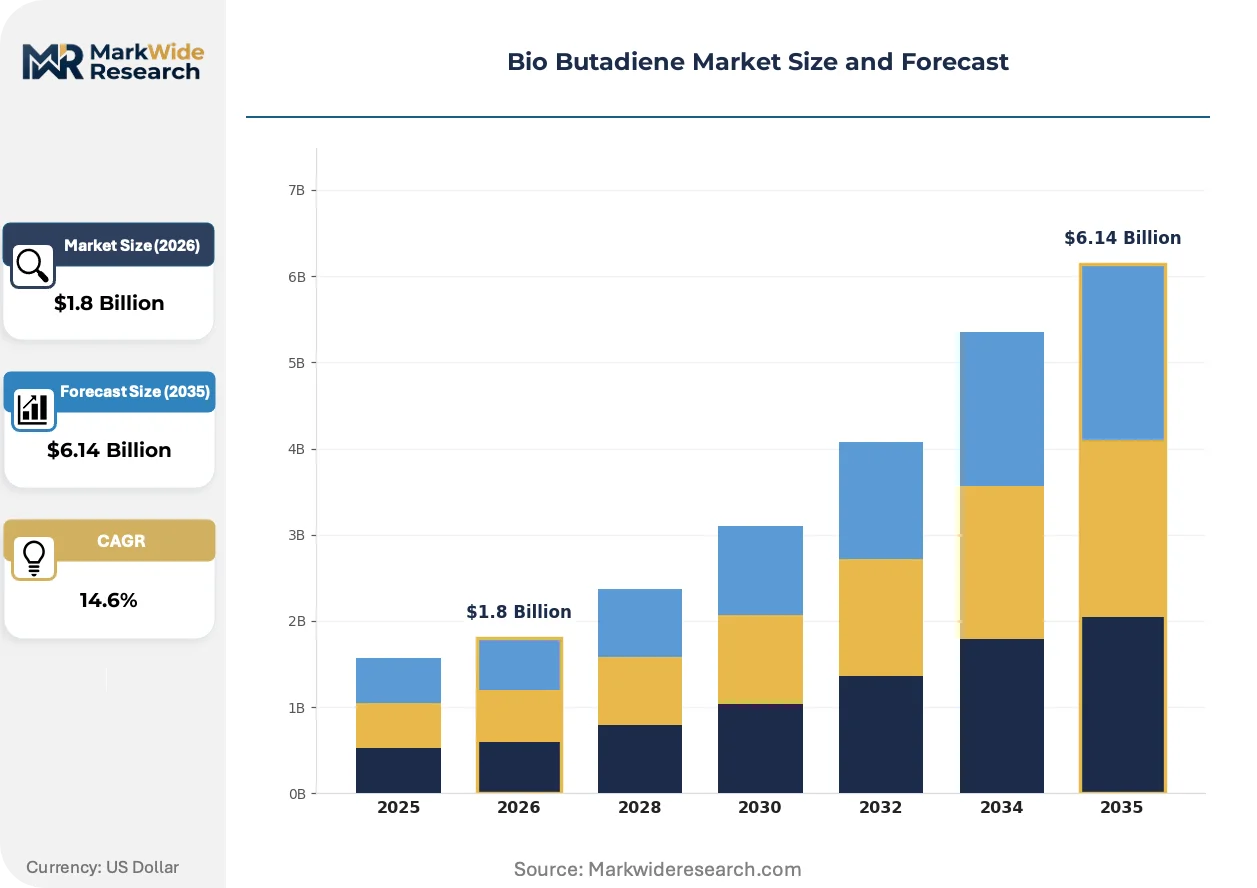
Market Dynamics
Fermentation-derived butadiene pathways are collapsing the historical cost gap with naphtha cracking, forcing integrated petrochemical operators to reconfigure capital allocation toward bio-based feedstocks or risk stranded asset exposure in European tire supply chains.
Growth Catalysts
- EU Green Deal mandates:REACH compliance requirements redirect petrochemical investments toward renewable monomer pathways, tightening fossil-derived content restrictions in automotive elastomers sold across Germany, France, and the Netherlands.
- Tire manufacturer procurement:Sustainability mandates from automotive OEMs accelerate offtake agreements for bio-based feedstocks, concentrating demand in German industrial clusters where BASF and Lanxess anchor polymer development.
- Bio-ethanol catalytic conversion:Selective dehydration catalysts achieve higher throughput yields than fermentation alternatives, attracting capital from specialty chemical producers seeking backward integration into sugarcane-derived feedstocks.
Market Restraints
- Feedstock cost volatility:Brazilian sugarcane prices swing against crude oil benchmarks, compressing margin predictability for fermentation operators dependent on agricultural commodity cycles.
- Technical yield limitations:Bio-based butadiene production currently achieves 70% minimum carbon content under ASTM D6866, constraining premium pricing power against fossil-derived drop-in alternatives in cost-sensitive polymer applications.
- Substitution threat:Isoprene and synthetic polyisoprene rubber formulations displace butadiene in select tire tread compounds, particularly in Asian markets where natural rubber availability reduces bio-butadiene substitution economics.
Strategic Opportunities
- Automotive interior polymer resins:OEM recycled and renewable content quotas create the fastest-expanding margin pool, outpacing tire manufacturing in volume growth potential for fermentation-derived butadiene.
- Indian BIS certification pathways:Mandatory disclosure of bio-based content percentages for imported elastomer compounds creates first-mover advantage for producers achieving ASTM D6866 verification ahead of domestic capacity buildout.
- Co-feeding infrastructure:Existing European crackers trial bio-butadiene integration without greenfield construction, leveraging established logistics networks to reduce capital intensity versus standalone fermentation facilities.
Industry Challenges
- ASTM D6866 certification timelines:Carbon-14 testing protocols require 3-6 month validation cycles, delaying offtake contract execution and locking working capital in pre-commercial inventory.
- Fermentation scale-up complexity:Microbial strain optimization and bioreactor contamination control demand specialized biochemical engineering talent scarce in traditional petrochemical labor pools.
- Legacy system integration:Drop-in monomer specifications must match naphtha-derived butadiene purity standards exactly, requiring costly downstream distillation retrofits at rubber processing facilities.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio Butadiene Market Trends and Innovations
Multiple technology pathways for renewable butadiene production are fragmenting the historical naphtha-cracking monopoly, while regulatory frameworks in Europe and Asia harden bio-content requirements across automotive supply chains.
Catalytic dehydration of bio-ethanol to butadiene is fragmenting the production technology landscape previously dominated by direct fermentation routes. Specialty chemical producers in Germany and the Netherlands adopt this pathway to achieve higher volumetric productivity per reactor volume. The resulting technology bifurcation is fragmenting equipment supplier relationships and splitting capital flows between bioreactor builders and heterogeneous catalyst developers.
REACH authorization procedures and the EU Green Deal's carbon border adjustment mechanism tighten fossil-derived monomer restrictions in tires and automotive components sold within Europe. Industrial consequence includes mandatory supply chain disclosure requirements and third-party verification of bio-based carbon content. Tire manufacturers with European production footprints respond by accelerating direct offtake negotiations with fermentation operators, bypassing traditional petrochemical distributors.
Automotive OEM procurement departments now mandate renewable content quotas in supplier contracts rather than accepting voluntary sustainability certifications. Tier-1 rubber compounders face contract renegotiation pressure to document ASTM D6866-compliant feedstock percentages. This behavioral shift concentrates most visibly in German automotive clusters, where BMW and Mercedes-Benz enforce cascading bio-content requirements through multi-tier supply contracts.
Bio Butadiene Market Segmentation
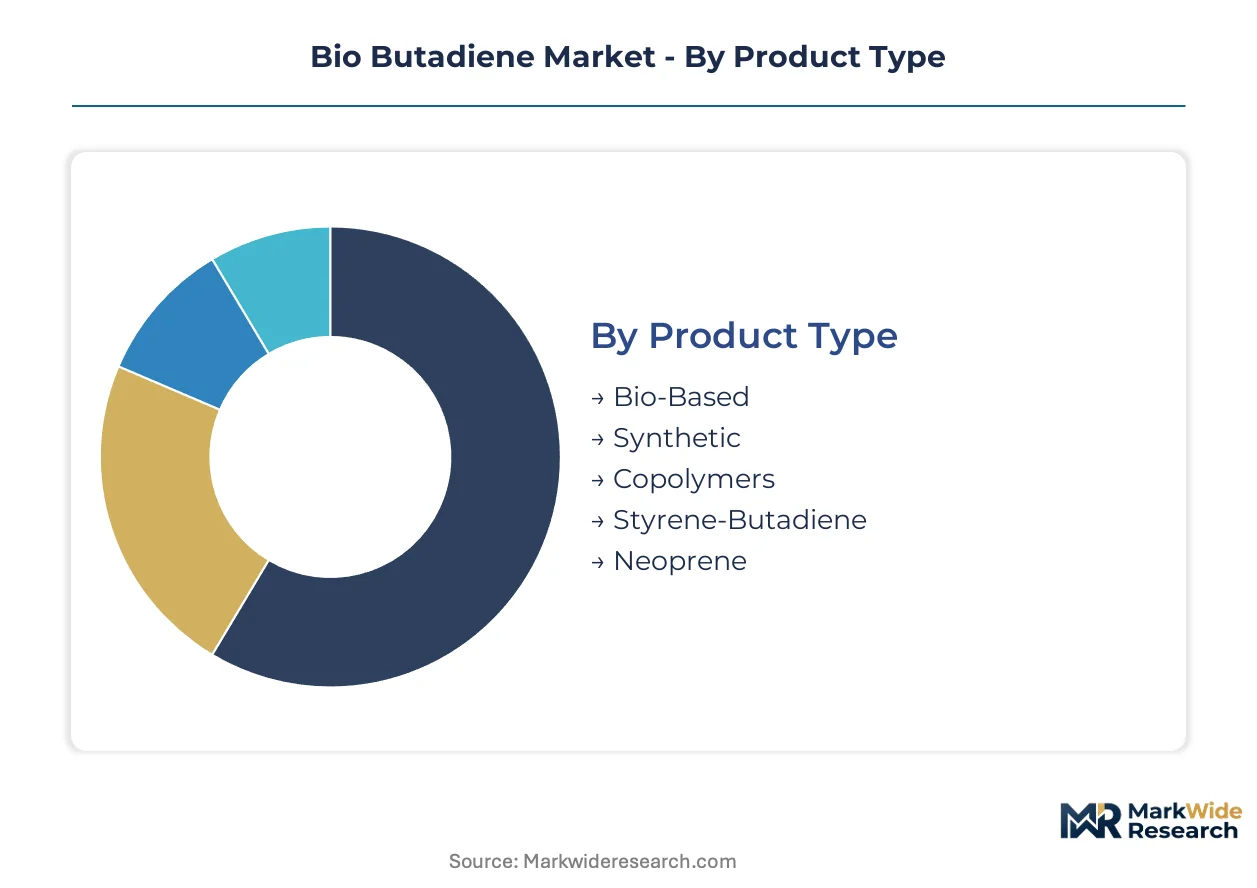
Segmentation in bio butadiene reveals how production pathways and customer specifications fragment procurement channels. Tire manufacturers source through direct offtake agreements with fermentation operators, while chemical distributors handle smaller volume polymer resin accounts.
Product Type:
Channel mix varies sharply across product categories, with bio-based grades flowing through certified supply chains requiring ASTM D6866 documentation while synthetic and copolymer grades leverage existing petrochemical distribution networks.
- Bio-Based:Minimum 70% bio-based carbon content under ASTM D6866 testing protocols qualifies material for EU Green Deal compliance credits. Demand concentrates in German tire manufacturing clusters where REACH mandates enforce renewable content quotas in automotive elastomers.
- Synthetic:Naphtha-derived butadiene serving cost-sensitive applications with established purity specifications. Volume leadership persists in Asian markets where natural rubber availability reduces bio-butadiene substitution economics.
- Copolymers:Styrene-butadiene and acrylonitrile-butadiene variants blending renewable and fossil feedstocks.
- Styrene-Butadiene:Drop-in rubber compounds for tire tread formulations requiring precise molecular weight distribution.
- Neoprene:Chloroprene-based elastomers for industrial hose and gasket applications.
By volume, Synthetic leads. By growth pace, Bio-Based is expanding most quickly.
Technology:
Cost tier differentiation separates capital-intensive fermentation installations from retrofit-friendly catalytic conversion units, with enzymatic and thermochemical pathways occupying niche positions based on feedstock availability.
- Fermentation:Microbial strain optimization converts sugars to butadiene through engineered metabolic pathways. Commercial deployment centers on Brazilian sugarcane processing sites where Braskem anchors backward integration into agricultural feedstocks.
- Catalytic Conversion:Selective dehydration of bio-ethanol over heterogeneous catalysts achieves higher volumetric productivity per reactor volume. German and Dutch specialty chemical producers favor this route for integration with existing petrochemical infrastructure.
- Enzymatic Synthesis:Cell-free biocatalytic systems under development for precision polymerization control.
- Gasification:Thermochemical conversion of lignocellulosic biomass to syngas intermediates.
- Pyrolysis:Thermal decomposition of waste rubber and biomass to recover C4 hydrocarbon fractions.
Fermentation captures the largest installed base. Catalytic Conversion is gaining share fastest as established chemical producers seek lower-capital entry points.
Application:
Application mix determines margin structure, with tire manufacturing representing high-volume baseline demand while polymer resins for automotive interiors command premium pricing under OEM renewable content mandates.
- Tire Manufacturing:Dominant demand segment consuming fermentation-derived butadiene for styrene-butadiene rubber tread compounds. Procurement concentrates at German production sites serving BMW and Mercedes-Benz supply chains under cascading bio-content contract requirements.
- Polymer Resins:ABS and high-impact polystyrene formulations for automotive interior components. This segment climbs the fastest as OEM recycled and renewable content quotas outpace tire manufacturing in volume growth potential.
- Adhesives:Pressure-sensitive and structural bonding formulations requiring specific viscosity grades.
- Elastomers:Industrial rubber goods including hoses, belts, and seals.
- Coatings:Protective and decorative finishes utilizing butadiene-derived latex binders.
Tire Manufacturing leads by volume. Polymer Resins show the steepest expansion trajectory driven by automotive interior specifications.
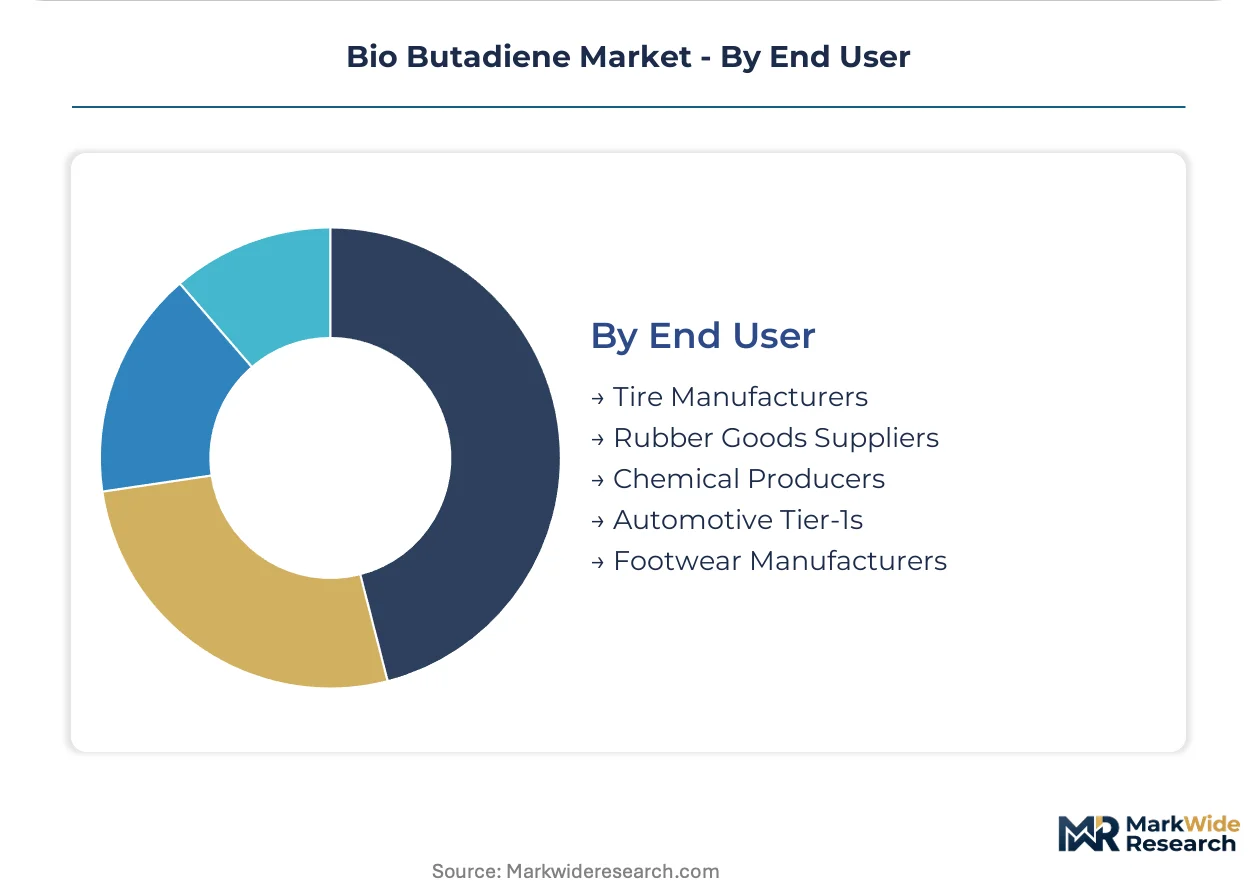
End User:
Customer type shapes contract structure, with tire manufacturers negotiating multi-year offtake agreements while footwear and smaller rubber goods suppliers purchase through spot market and distributor channels.
- Tire Manufacturers:Direct procurement from fermentation operators bypassing traditional petrochemical distributors. Sustainability mandates from automotive OEMs accelerate offtake negotiations, with demand clustering in German industrial zones where BASF and Lanxess anchor polymer development.
- Automotive Tier-1s:Rubber compounders facing contract renegotiation pressure to document ASTM D6866-compliant feedstock percentages. These suppliers represent the fastest-growing customer segment as OEM procurement departments mandate renewable content quotas rather than accepting voluntary certifications.
- Rubber Goods Suppliers:Industrial and consumer product manufacturers with fragmented demand patterns.
- Chemical Producers:Intermediate processors blending butadiene into downstream polymer formulations.
- Footwear Manufacturers:Niche demand for neoprene and synthetic rubber sole compounds.
Tire Manufacturers dominate volume. Automotive Tier-1s are expanding procurement fastest under OEM compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil exhibit the highest price elasticity, tethering procurement decisions to sugarcane commodity cycles, while German automotive OEMs demonstrate inelastic demand under binding EU Green Deal mandates that override cost considerations.
Germany
Automotive OEMs enforce cascading bio-content requirements through multi-tier supply contracts, creating inelastic demand for ASTM D6866-verified feedstocks. REACH authorization procedures and the EU Green Deal's carbon border adjustment mechanism tighten fossil-derived monomer restrictions. The industrial cluster around Ludwigshafen and Cologne anchors polymer development where BASF and Lanxess coordinate fermentation-derived butadiene procurement.
United States
EPA renewable fuel standards generate compliance credit value for bio-based chemical pathways, incentivizing domestic fermentation capacity investments. Tire manufacturers face sustainability mandates from Detroit-based automotive OEMs accelerating offtake negotiations. The Gulf Coast petrochemical corridor trials bio-butadiene co-feeding at existing crackers, leveraging established logistics infrastructure without greenfield construction.
Brazil
Backward integration into sugarcane-derived feedstocks anchors Braskem's position, though agricultural commodity price volatility compresses margin predictability. National biofuel policy frameworks support renewable chemical pathways through tax incentives. The São Paulo state industrial belt concentrates fermentation infrastructure where sugarcane processing proximity reduces feedstock transportation costs.
India
BIS certification requirements mandate disclosure of bio-based content percentages for imported elastomer compounds, creating compliance barriers for uncertified suppliers. Central government PLI scheme incentives target domestic specialty chemical manufacturing capacity buildout. The Gujarat industrial corridor attracts first-mover fermentation operators seeking ASTM D6866 verification ahead of domestic supply maturation.
Netherlands
Specialty chemical producers favor catalytic dehydration pathways for integration with existing petrochemical infrastructure, achieving higher volumetric productivity per reactor volume. ECHA regulatory alignment with REACH frameworks enforces supply chain disclosure requirements for automotive components. The Rotterdam-Antwerp chemical cluster hosts heterogeneous catalyst development operations serving German tire manufacturing demand.
Bio Butadiene Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive positioning across the bio butadiene value chain. Integrated petrochemical giants leverage existing crackers and logistics networks to trial bio-butadiene co-feeding, while specialty biotech entrants pursue standalone fermentation facilities requiring greenfield capital deployment. Two strategic archetypes dominate: backward-integrated agricultural processors controlling sugarcane feedstock supply, and catalyst technology specialists commanding selective dehydration process yields. Competitive moves concentrate on strategic partnerships with tire manufacturers for multi-year offtake agreements, and geographic expansion into jurisdictions with binding bio-content mandates.
Within the integrated petrochemical tier, SABIC and Braskem occupy positions exemplifying divergent feedstock strategies—SABIC representing Middle Eastern petrochemical scale advantages, Braskem embodying Brazilian agricultural integration. Among European specialty chemical producers, Evonik Industries anchors catalyst technology development for bio-ethanol conversion pathways. These three companies represent the dominant competitive archetypes: fossil infrastructure leverage, agricultural backward integration, and process technology specialization.
| Leading Market Players |
|---|
| SABIC |
| Michelin |
| Zeon Corporation |
| Trinseo |
| Braskem |
| Versalis |
| Lummus Technology |
| Evonik Industries |
| Synthos |
| Others |
Pricing and Supply Chain Analysis
Ninety-day ASTM D6866 certification cycles lock working capital in pre-commercial inventory, amplifying pricing power for verified suppliers while compressing margins for fermentation operators awaiting carbon-14 validation. This lead-time bottleneck concentrates procurement leverage among German tire manufacturers with multi-year offtake mandates under REACH compliance.
Pricing Analysis
After-sales revenue from technical service contracts and catalyst regeneration drives lifetime value for bio-butadiene producers. Contract-based long-term offtake agreements dominate, with price differentiation anchored in ASTM D6866 certification tier and volume scale commitments. Cost compression in fermentation-derived grades is intensifying because Brazilian sugarcane price volatility feeds directly into feedstock cost structures. Tire manufacturers demonstrate lowest price sensitivity due to binding EU Green Deal mandates, while polymer resin compounders in Asian markets exhibit highest elasticity.
Supply Chain Analysis
Port congestion at Rotterdam and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for catalyst and bioreactor equipment imports. Supply concentrates in Germany, Brazil, and the Netherlands, with production anchored in Ludwigshafen industrial clusters, São Paulo state sugarcane processing belts, and Rotterdam-Antwerp chemical corridors. Raw material dependencies center on Brazilian sugarcane feedstocks, heterogeneous catalyst metals, and engineered microbial strains. Single-source vulnerability in Brazilian agricultural supply creates structural exposure. Distribution runs through direct offtake agreements with tire manufacturers, bypassing traditional petrochemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
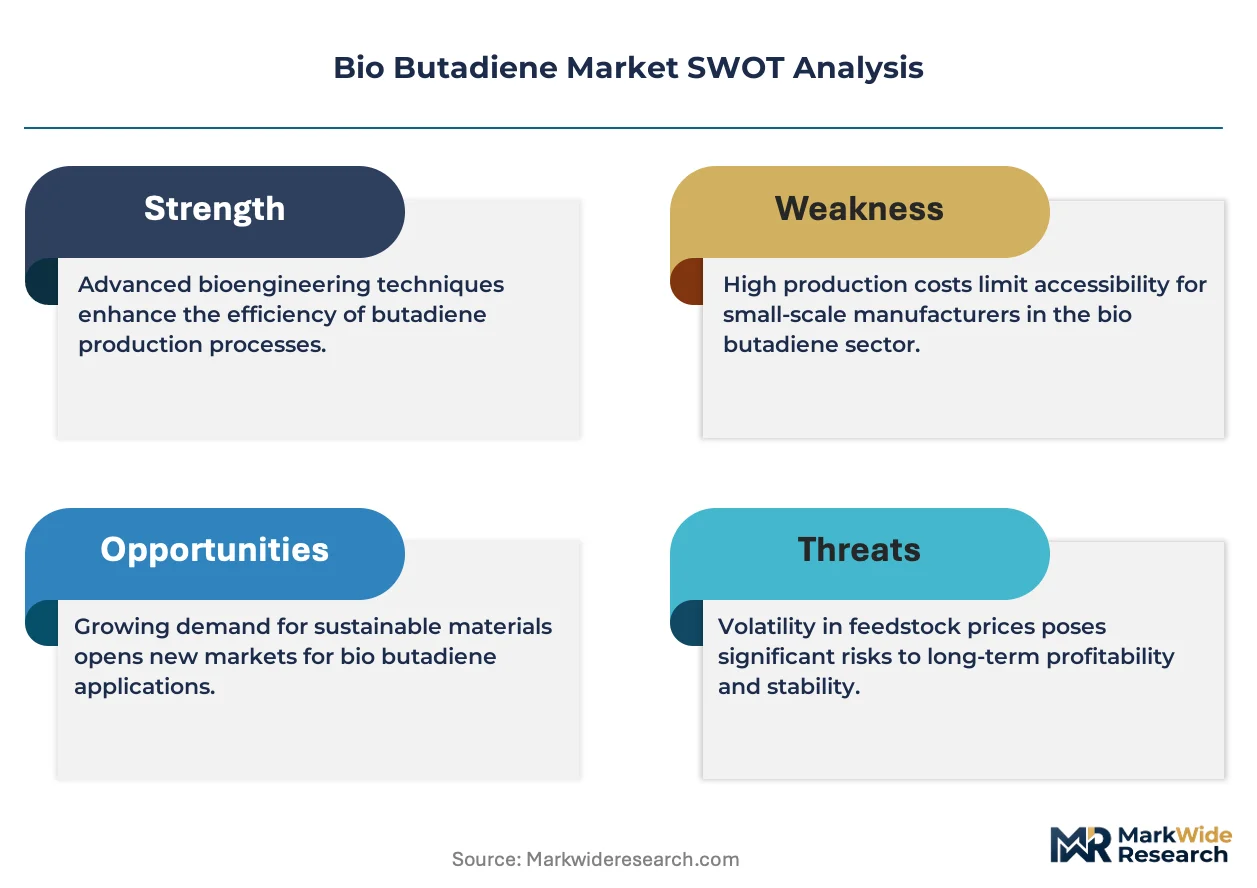
Bio-butadiene represents a high-growth disruption as fermentation pathways collapse the cost gap with naphtha cracking, with EU Green Deal mandates forcing automotive supply chain reconfiguration toward renewable monomer verification.
For Market Incumbents: Secure multi-year offtake agreements with German automotive OEMs before domestic Indian capacity achieves BIS certification scale. Anchor backward integration into sugarcane processing to defend margin position against feedstock volatility. Prioritize catalyst R&D investment in selective dehydration technology to offset microbial strain optimization delays. For New Entrants and Emerging Players: ASTM D6866 fast-track certification creates first-mover advantage in Indian elastomer import markets ahead of domestic supply maturation. Target polymer resin applications for automotive interiors as the most penetrable segment under OEM renewable content quotas. Pursue joint development agreements with Tier-1 rubber compounders lacking in-house fermentation expertise. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across catalytic conversion sub-segments as established petrochemical infrastructure enables co-feeding without greenfield construction. Five-to-ten year viability favors acquisition targets with verified ASTM D6866 compliance and locked Brazilian feedstock supply. Monitor EU carbon border adjustment mechanism implementation timelines as inflection signal for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Direct offtake with BMW or Mercedes-Benz secures volume under cascading bio-content mandates. |
| Backward Integration | Captive sugarcane processing in São Paulo state reduces feedstock cost volatility exposure. |
| Green Manufacturing Transition | Fermentation pathway conversion unlocks EU Green Deal compliance credits for tire supply chains. |
| Joint Venture | Catalyst technology partnerships with Dutch specialty chemical producers accelerate bio-ethanol dehydration scale-up. |
| Capacity Expansion | Gujarat industrial corridor positioning captures Indian BIS certification demand ahead of domestic competition. |
Research Methodology
Cross-validation between primary interviews with tire manufacturer procurement directors, fermentation plant managers, and automotive Tier-1 compounders anchors the qualitative findings against secondary validation from ECHA regulatory filings, Brazilian customs trade data, and SEC 10-K disclosures. Bottom-up capacity buildout tracking triangulates against top-down OEM renewable content mandate analysis.
Sensitivity analysis across feedstock cost scenarios and certification timeline variations shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include production technology pathway, application end-use, and regional regulatory cluster. CAGRs derive from installed capacity ramp rates and offtake contract execution velocity. Industry-specific forecast inputs incorporate sugarcane commodity price bands and REACH authorization procedure timelines.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated Indian domestic capacity buildout would require recalibration. Forecasts reflect documented assumptions regarding microbial strain yield improvements and catalyst selectivity advances. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.