
 Alkylate Isooctane Market | 2026-2036
Alkylate Isooctane Market Size, Share, and Industry Trends Forecast 2026-2036
Alkylate Isooctane Market Analysis
The gap between premium alkylate grades and commodity blending stock is broadening as refiners face divergent pathway economics. ExxonMobil leverages integrated alkylation capacity across its Gulf Coast system to capture margin from specialized fuel pools. Shell anchors its position through hydrocracker-alkylate coproduction networks in Rotterdam and Singapore. Valero Energy competes by sustaining merchant supply relationships with independent gasoline blenders on the US Atlantic Coast.
Alkylate isooctane denotes a highly branched C8 hydrocarbon produced through sulfuric or hydrofluoric acid alkylation of isobutene with isobutane, yielding a product with research octane numbers typically exceeding 95 and near-zero sulfur content. Premium alkylate commands structural margin over regular grades due to its suitability for reformulated gasoline meeting stringent aromatics limits. Aviation fuel applications represent the fastest-expanding demand segment as regional airports phase out leaded avgas. Chemical feedstock offtake matures amid competition from shale-derived light naphtha alternatives.
EPA Tier 3 gasoline sulfur regulations and California Air Resources Board LCFS carbon intensity scoring reshape product specifications and refinery investment decisions across North American markets. EU F-Gas Regulation and REACH chemical safety protocols constrain European alkylation unit operations and catalyst handling practices. Stakeholders must monitor evolving carbon border adjustment mechanisms and low-carbon fuel standard expansions to anticipate which production methods and product grades will retain access to premium pricing corridors.
Market Dynamics
EPA Tier 3 sulfur standards and California LCFS carbon intensity scoring are compressing the viable product slate for gasoline blenders, forcing capital reallocation toward alkylation units capable of producing sub-10 ppm sulfur alkylate with verified low-carbon pathways.
Growth Catalysts
- Aviation Fuel Mandates:FAA pressure to eliminate leaded avgas is redirecting regional airport fuel procurement toward high-octane alkylate alternatives. General aviation operators in the United States are phasing in unleaded formulations faster than regulatory deadlines require.
- EPA Tier 3 Compliance:The regulation's 10 ppm gasoline sulfur cap eliminates conventional blending components, elevating alkylate's share in reformulated gasoline pools. Refiners lacking alkylation capacity face stranded asset risk in premium fuel markets.
- Shale-Derived Isobutane Abundance:Permian Basin NGL fractionation expansion has collapsed domestic isobutane feedstock costs. Gulf Coast alkylation units capture structurally lower variable costs versus European and Asian competitors dependent on imported feedstock.
Market Restraints
- HF Acid Regulatory Burden:Hydrofluoric acid alkylation faces OSHA Process Safety Management and EPA Risk Management Plan constraints that elevate compliance costs and unit siting restrictions. Refiners in densely populated coastal zones confront de facto moratoriums on new HF capacity.
- Shale Naphtha Substitution:Light naphtha from US tight oil production competes directly with alkylate in chemical feedstock applications. Petrochemical buyers in Texas and Louisiana are switching cracking feedslates toward lighter, cheaper alternatives.
- Merchant Supply Concentration:Independent gasoline blenders on the US Atlantic Coast depend on a narrow set of Gulf Coast refiners for alkylate rail and barge supply. Disruption at key origin points cascades rapidly through downstream blending operations.
Strategic Opportunities
- Carbon-Intensity Certification:California LCFS credit generation creates premium pricing for alkylate produced via low-carbon electricity or carbon capture integration. Refiners with verified CI scores below the baseline capture incremental margin in West Coast fuel pools.
- SAF Coproduction Integration:Sustainable aviation fuel pre-treatment units can share hydrogen and fractionation infrastructure with alkylation complexes. Engineering studies at Gulf Coast refineries are evaluating combined alkylate-SAF production trains.
- Marine Fuel Reformulation:IMO 2020 low-sulfur residual fuel standards and emerging EU FuelEU Maritime rules are opening marine gasoline niche applications for high-purity alkylate. Port fuel suppliers in Rotterdam and Singapore are testing alkylate-gasoil blends for coastal vessels.
Industry Challenges
- Alkylation Unit Relicensing:Sulfuric acid alkylation catalyst handling permits require renewal under EPA New Source Review every 10-15 years. Refiners face procedural delays and contested public comment periods that freeze expansion timelines.
- Specialized Welding and Inspection Talent:HF alkylation unit maintenance demands ASME-certified welders with acid service experience. The contracting pool for this skill set has contracted as veteran technicians retire without sufficient apprentice pipeline replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkylate Isooctane Market |
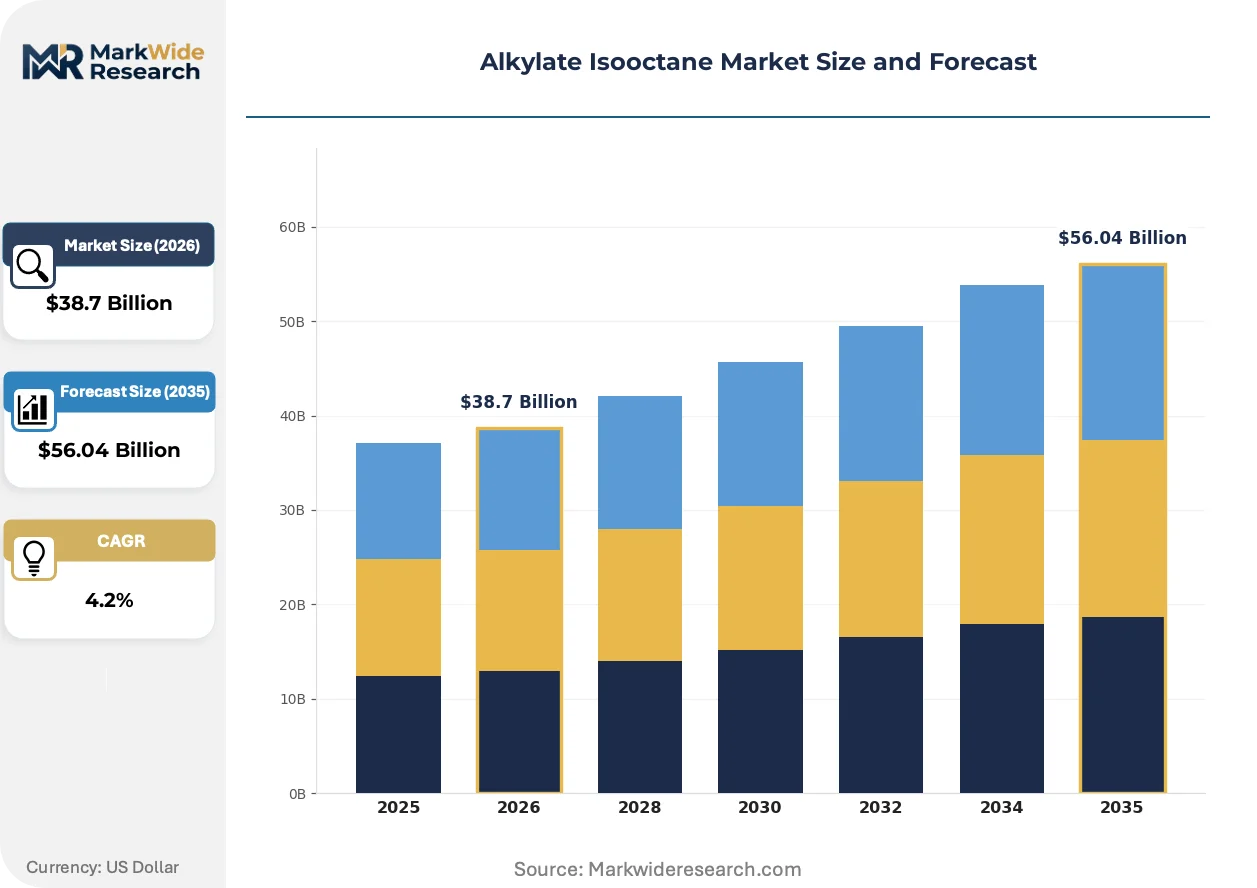
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Alkylate, Premium Alkylate, Speciality Alkylate, Blended Alkylate Production Method: Fluid Catalytic Cracking, Hydrocracking, Alkylation, Reforming Application: Aviation Fuel, Automotive Fuel, Industrial Solvent, Chemical Feedstock Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Outlets |
| Companies Covered | ExxonMobil, Shell, BP, Chevron, TotalEnergies, Phillips 66, Valero Energy, LyondellBasell, Borealis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkylate Isooctane Market Emerging Trajectories
Solid-acid alkylation catalysts and ionic liquid processes are disrupting the half-century dominance of liquid acid technologies, while regulatory carbon accounting is embedding itself into product specifications and procurement criteria.
Ionic liquid alkylation is converging with conventional sulfuric acid unit revamps as refiners seek to eliminate hazardous acid inventory without sacrificing octane yield. European refiners in Rotterdam and Antwerp are piloting chloroaluminate ionic liquid systems that operate at ambient temperature with simplified product separation. This convergence is compressing the capital cost gap between greenfield solid-acid installations and legacy acid unit retrofits, accelerating technology turnover in mature refining corridors.
EU F-Gas Regulation and REACH chemical safety protocols are constraining hydrofluoric acid catalyst handling and transportation across European alkylation operations. The industrial consequence is accelerated unit shutdown planning and feedstock redirection toward sulfuric acid or solid-acid alternatives. German and Dutch refiners are most affected, with several facilities announcing HF alkylation phase-out timelines ahead of regulatory minimums to preempt liability exposure.
Certification-driven procurement is reshaping how gasoline blenders evaluate alkylate suppliers, with carbon intensity scores and renewable content verification displacing traditional octane-plus-price metrics. Large retail fuel marketers in California and Oregon are unbundling fuel sourcing from logistics contracts, creating direct supplier relationships with specific refiners. This pattern is most visible in the US West Coast, where LCFS credit stacking and quarterly CI reporting requirements favor transparent, long-term offtake agreements over spot market transactions.
Alkylate Isooctane Market Segmentation
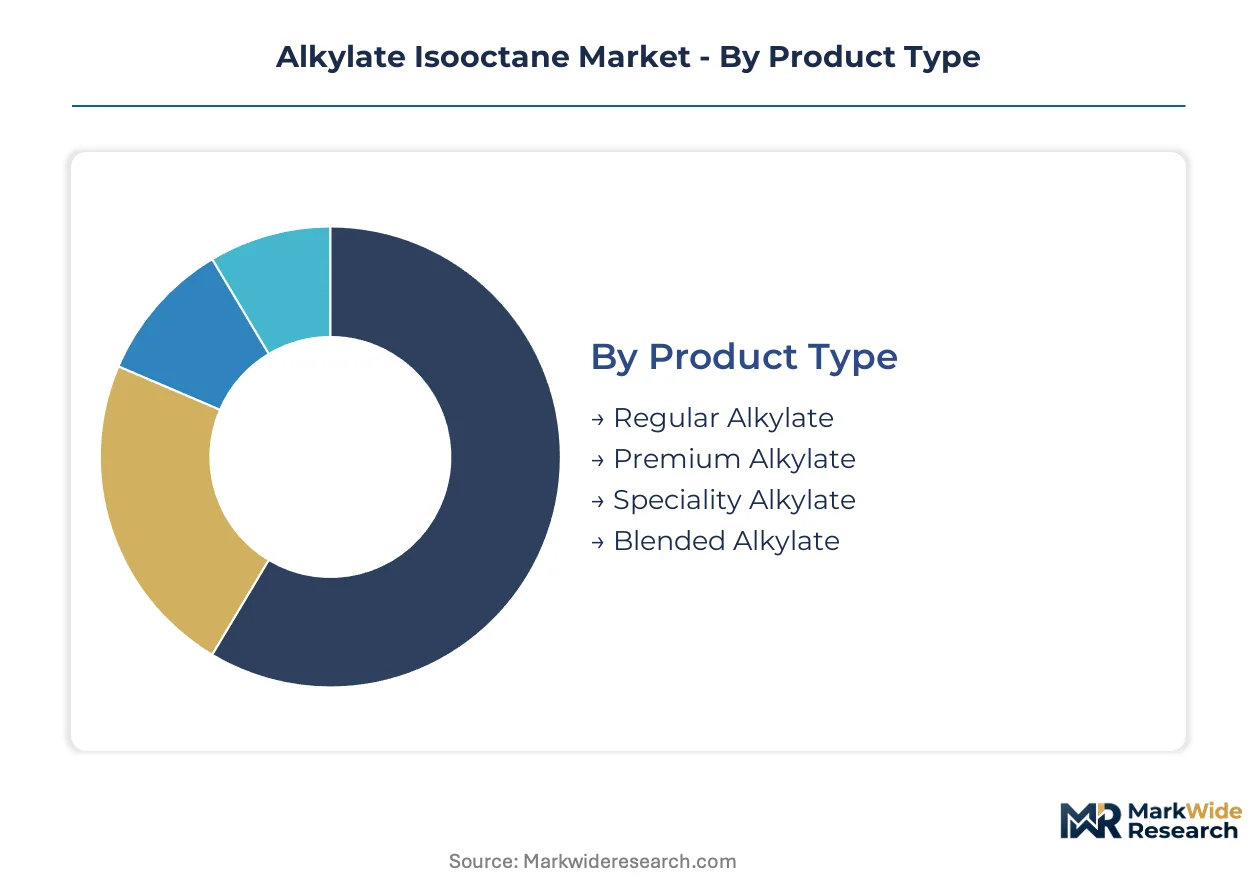
Product grade differentiation determines margin capture in alkylate isooctane, as refiners balance specification flexibility against capital intensity. Each segmentation axis reveals distinct competitive dynamics across fuel blending, chemical conversion, and specialty applications.
Product Type:
Customization intensity spans from commodity blending stock to certified low-carbon grades, with specification breadth directly correlating to pricing power.
- Regular Alkylate:Standard C8 isoparaffinic stream with research octane numbers of 92-95, produced through conventional sulfuric acid alkylation. Demand concentrates in Gulf Coast reformulated gasoline pools where EPA Tier 3 sulfur compliance elevates baseline alkylate inclusion rates. Refiners lacking carbon intensity certification compete primarily on delivered cost to Atlantic Coast blenders.
- Premium Alkylate:Ultra-low sulfur grade exceeding 97 RON with verified sub-5 ppm sulfur content and California LCFS carbon intensity scores below baseline. Demand concentrates in West Coast premium gasoline formulations where retail fuel marketers unbundle sourcing from logistics contracts. CI certification creates structural margin separation from regular grades.
- Speciality Alkylate:Aviation-grade material meeting ASTM D910 unleaded avgas specifications with enhanced volatility control for high-altitude engine performance.
- Blended Alkylate:Pre-mixed formulations combining alkylate with oxygenates or bio-components for downstream blender operational simplification.
Most installed capacity flows through Regular Alkylate. Expansion is steepest in Premium Alkylate.
Production Method:
Technology selection reflects feedstock access, byproduct handling constraints, and regional regulatory tolerance for hazardous catalyst inventory.
- Alkylation:Acid-catalyzed union of isobutene with isobutane yielding the highest-octane C8 stream available for gasoline blending. Gulf Coast refiners exploit Permian Basin isobutane abundance to sustain structurally lower variable costs than European or Asian competitors dependent on imported feedstock.
- Hydrocracking:Heavy feedstock conversion producing alkylate-range material as secondary output alongside middle distillates. Demand concentrates in integrated refineries seeking diesel-gasoline production flexibility rather than dedicated octane supply.
- Fluid Catalytic Cracking:Residual upgrading process yielding light olefins and naphtha-range material requiring further processing for alkylate equivalence.
- Reforming:Catalytic rearrangement of naphtha streams producing high-octane aromatics and isoparaffins with distinct composition from true alkylate.
Acid alkylation dominates dedicated octane production. Hydrocracking-alkylate coproduction is gaining share in European integrated sites.
Application:
End-use diversification exposes producers to distinct regulatory timelines and substitution risks across transportation and industrial demand pools.
- Automotive Fuel:Reformulated gasoline blending representing the foundational demand anchor for alkylate isooctane volume. EPA Tier 3 sulfur standards and state-level low-carbon fuel specifications are compressing the viable product slate, forcing capital reallocation toward sub-10 ppm sulfur alkylate with verified low-carbon pathways.
- Aviation Fuel:Unleaded avgas replacement for piston-engine aircraft as FAA pressure eliminates tetraethyl lead from general aviation. Regional airports in the United States are phasing in unleaded formulations faster than regulatory deadlines require, redirecting fuel procurement toward high-octane alkylate alternatives.
- Chemical Feedstock:Cracking feed for olefin production facing displacement from shale-derived light naphtha alternatives.
- Industrial Solvent:Precision cleaning and extraction applications leveraging alkylate's near-zero aromatics and controlled evaporation profile.
Automotive Fuel retains volume concentration. Aviation Fuel is climbing the fastest as regulatory phase-out accelerates.
Distribution Channel:
Channel structure reflects buyer scale, specification complexity, and geographic concentration of downstream blending capacity.
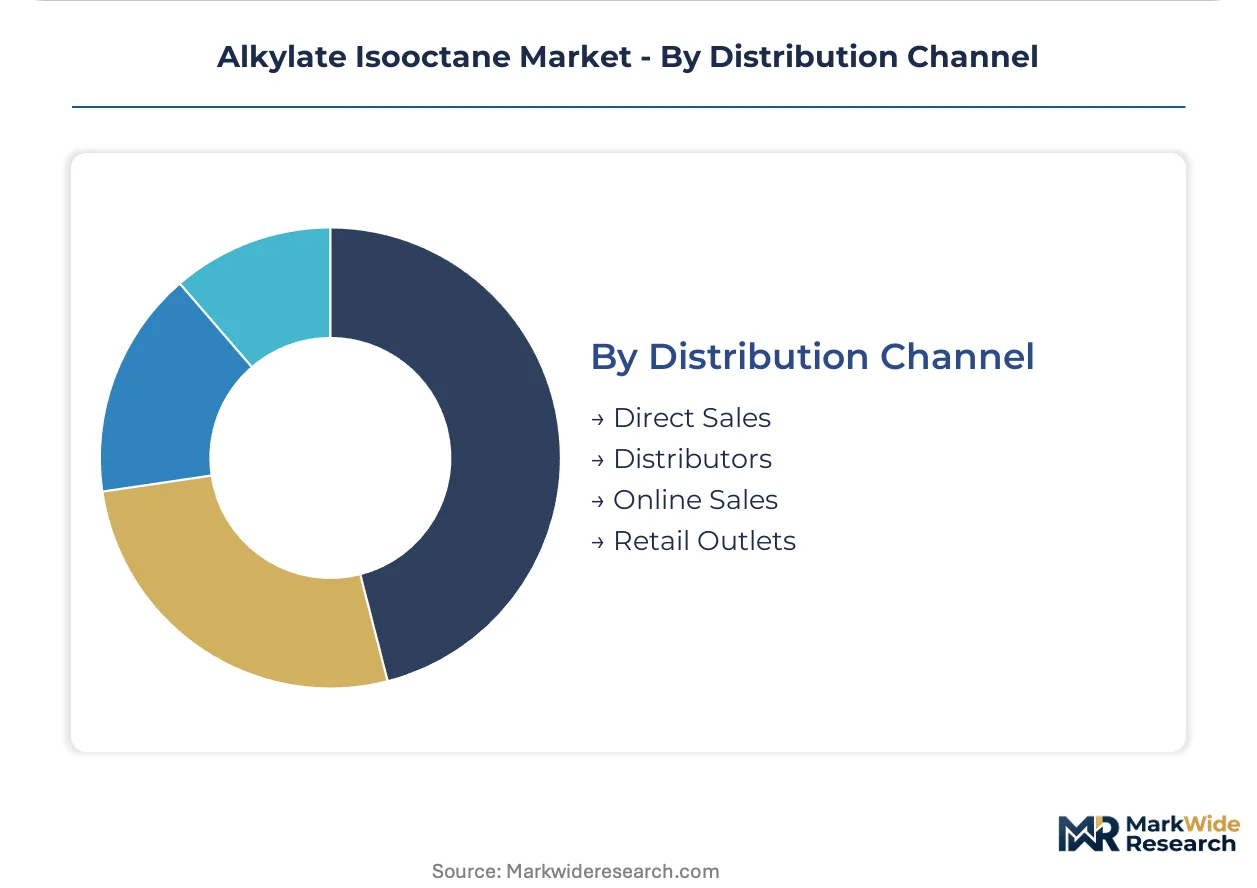
- Direct Sales:Long-term offtake agreements between integrated refiners and large retail fuel marketers, particularly prevalent in California and Oregon where LCFS credit stacking demands transparent CI verification. Large buyers unbundle fuel sourcing from logistics contracts to capture margin from specific production pathways.
- Distributors:Merchant supply intermediaries aggregating rail and barge volumes from Gulf Coast refiners for independent Atlantic Coast blenders. Concentration risk emerges as disruption at key origin points cascades rapidly through downstream blending operations.
- Online Sales:Digital procurement platforms for spot market transactions and specification documentation exchange.
- Retail Outlets:Branded fuel stations with captive supply relationships to specific refiner product slates.
Direct Sales commands premium grade volume. Distributor-mediated supply is expanding most quickly among independent blenders seeking supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized welding technicians with acid-service certification cluster along the US Gulf Coast, anchoring the industry's geographic footprint. Their concentration enables maintenance-intensive alkylation operations that competitors elsewhere struggle to replicate. This workforce distribution shapes where capacity expands and where it retires.
United States
Permian Basin isobutane abundance sustains structurally lower feedstock costs for Gulf Coast refiners. EPA Tier 3 sulfur standards and California LCFS carbon intensity scoring compress viable product slates, elevating alkylate's share in reformulated gasoline pools. Houston-Beaumont-Port Arthur refining corridor hosts the densest concentration of merchant alkylate supply capacity serving Atlantic Coast blenders.
Germany
REACH chemical safety protocols and EU F-Gas Regulation constrain hydrofluoric acid catalyst handling, accelerating phase-out timelines ahead of regulatory minimums. German refiners redirect feedstock toward sulfuric acid or solid-acid alternatives to preempt liability exposure. Industrial clusters in North Rhine-Westphalia and the Hamburg region face the steepest compliance-driven restructuring.
Netherlands
Rotterdam refining complex anchors European hydrocracker-alkylate coproduction networks serving premium fuel pools. EU carbon border adjustment mechanisms and emerging low-carbon fuel standards reshape procurement criteria for export-oriented gasoline blenders. Pilot installations of chloroaluminate ionic liquid systems are compressing capital cost gaps between greenfield solid-acid and legacy acid unit retrofits.
Singapore
Jurong Island refining hub integrates hydrocracker-alkylate coproduction with marine fuel reformulation for IMO 2020 low-sulfur residual standards. Port fuel suppliers test alkylate-gasoil blends for coastal vessels under emerging EU FuelEU Maritime rules. Feedstock dependence on imported isobutane elevates variable costs versus US Gulf Coast competitors with domestic shale-derived supply.
Japan
METI energy security frameworks prioritize domestic refining capacity retention despite feedstock import dependence. Japanese refiners evaluate solid-acid alkylation retrofits to eliminate hazardous acid inventory while sustaining octane yield. Chubu-Nagoya industrial corridor maintains specialized alkylation units serving captive automotive fuel demand from domestic manufacturers.
Alkylate Isooctane Market Vendor Landscape
Top-tier vendors anchor integrated refining systems, while merchant suppliers compete on logistics reliability and specification flexibility. The vendor base stratifies across three tiers: multinational majors with captive alkylation capacity, regional refiners with specialized product slates, and merchant traders aggregating rail and barge volumes. Two strategic archetypes dominate: integrated producers leveraging feedstock-cost advantages and specification-certified suppliers capturing California LCFS premiums. Competitive moves concentrate on capacity expansion at low-carbon intensity sites and strategic partnerships with independent blenders seeking supply security.
Among US-based integrated majors, ExxonMobil, Valero Energy, and Phillips 66 exemplify contrasting strategic positions. ExxonMobil occupies the archetype of system-wide alkylation integration across Gulf Coast refining networks. Valero Energy represents merchant supply relationships with independent Atlantic Coast blenders. Phillips 66 sits within the tier of refiners balancing automotive fuel blending against aviation fuel certification requirements. Each anchors a distinct competitive vector without overlapping strategic territory.
| Leading Market Players |
|---|
| ExxonMobil |
| Shell |
| BP |
| Chevron |
| TotalEnergies |
| Phillips 66 |
| Valero Energy |
| LyondellBasell |
| Borealis |
| Others |
Supply Flow & Price Mechanics
Permian Basin isobutane feedstock costs cascade through Gulf Coast alkylation units into three distinct pricing tiers downstream, with carbon-intensity certification separating premium grades from commodity blending stock as California LCFS rules tighten procurement criteria.
Pricing Analysis
Bundled logistics-plus-product contracts dominate Gulf Coast-to-Atlantic Coast supply, while unbundled direct sourcing spreads among West Coast retail fuel marketers seeking transparent CI verification for LCFS credit stacking. Price differentiation hinges on California LCFS carbon intensity scores below baseline and EPA Tier 3 sub-10 ppm sulfur certification, with premium grades commanding structural margin separation. Cost compression in regular alkylate intensifies as shale naphtha substitutes erode chemical feedstock offtake. Independent Atlantic Coast blenders exhibit highest price sensitivity due to narrow merchant supply alternatives, while certified low-carbon buyers show inelastic demand for premium grades.
Supply Chain Analysis
Single-source vulnerability sits with the Houston-Beaumont-Port Arthur refining corridor, where disruption at key origin points cascades rapidly through downstream Atlantic Coast blending operations. Supply concentrates in the United States, Netherlands, and Singapore, with feedstock anchored in domestic Permian Basin isobutane for Gulf Coast producers versus imported volumes for European and Asian competitors. Raw material dependencies span isobutane, isobutene, and sulfuric or hydrofluoric acid catalysts. Tariff exposure on catalyst imports and acid handling permits elevates operational risk. Distribution runs through long-term offtake agreements for premium grades and rail-barge merchant networks for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in low-carbon certification tiers as Permian feedstock abundance compresses variable costs for integrated Gulf Coast producers, while regulatory phase-out timelines for leaded aviation fuel open premium pricing corridors for certified grades.
For Market Incumbents: To counter solid-acid technology disruption and ionic liquid retrofit competition, incumbents should deepen backward integration into Permian Basin NGL fractionation to lock in structural feedstock cost advantages. Second, secure ASME-certified welding apprentice pipelines to preempt maintenance talent scarcity that threatens HF alkylation unit reliability. For New Entrants and Emerging Players: The price-point gap between premium alkylate with California LCFS certification and regular Gulf Coast blending stock offers entry space for entrants with low-carbon electricity access or carbon capture integration. Target aviation fuel certification as the most penetrable segment, with FAA-mandated unleaded avgas phase-out accelerating faster than regulatory deadlines. Pursue direct offtake relationships with regional airport fuel suppliers rather than competing for saturated automotive fuel blending slots. For Investors and Strategic Acquirers: Consolidation pressure builds where merchant supply concentration meets stranded asset risk for refiners lacking alkylation capacity under EPA Tier 3 compliance timelines. Long-term viability favors integrated producers with verified low-carbon pathways and captive feedstock access. Acquisition targets include sulfuric acid alkylation units in regulatory jurisdictions permitting expansion, or solid-acid technology licensors with proven retrofit economics. Watch California LCFS carbon intensity benchmark revisions as the inflection signal for premium grade margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | California LCFS credit generation secures premium pricing in West Coast fuel pools. |
| SAF Coproduction Partnership | Shared hydrogen infrastructure with alkylation units reduces capital intensity for dual-output refineries. |
| Aviation Fuel Certification | ASTM D910 compliance opens FAA-mandated unleaded avgas replacement demand. |
| Ionic Liquid Retrofit | Chloroaluminate systems eliminate hazardous acid inventory while preserving octane yield. |
| Permian Feedstock Integration | Direct isobutane sourcing from Basin fractionation collapses variable cost versus import-dependent competitors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with refinery operations managers, gasoline blender procurement leads, aviation fuel suppliers, and alkylation unit maintenance contractors with secondary validation from EIA refinery capacity data, EPA compliance filings, and California Air Resources Board LCFS program reports. Bottom-up capacity and production estimates triangulated against top-down demand projections from automotive and aviation fuel consumption trends.
Segment-weighting across the projection horizon applied product type, production method, application, and distribution channel dimensions, with CAGRs derived from rolling average growth rate analysis adjusted for regulatory inflection points. Forecast inputs incorporated EPA Tier 3 sulfur standard implementation timelines, FAA unleaded avgas phase-out schedules, and Permian Basin NGL production trajectories.
The model assumes a particular technology adoption path; alternative pathways for solid-acid alkylation catalysts would alter the outlook if ionic liquid retrofits achieve faster cost parity than projected. Forecasts reflect assumptions about carbon intensity scoring stability and feedstock cost differentials. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Bioisobutene Market
Petrochemicals
Bio Butadiene Market
Petrochemicals
Synthetic and Biobased Butadiene Market
Petrochemicals
Propylene Carbonate Market
Petrochemicals
Global Butadiene Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market
Petrochemicals
Chemical and Petroleum Containers Market
Petrochemicals
Propane Market
Petrochemicals
Alkylate Market
Petrochemicals
Anthracene Oil Market
Petrochemicals
Global Methyl Tertiary Butyl Ether Market
Petrochemicals
Military Propellants Market
Petrochemicals
Basic Petrochemical Market
Petrochemicals
Fossil Fuel-Based Plastics Market
Petrochemicals
Tert Butyl Hydroperoxide Market
Petrochemicals
Propylene Market