
 Chemical and Petroleum Containers Market | 2026-2036
Chemical and Petroleum Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical and Petroleum Containers Market Outlook
Modular intermediate bulk container systems is recalibrating procurement patterns among chemical distributors who now lease rather than own fleet assets. Mauser Packaging Solutions leverages its closed-loop pooling network across North American manufacturing corridors. Greif anchors its position through steel drum refurbishment capabilities that extend container life cycles. Schütz competes via composite IBC designs that reduce tare weight for hazardous liquid transport.
Chemical and petroleum containers are engineered receptacles manufactured from steel, plastic, aluminum, or composite materials to store, transport, and dispense corrosive, flammable, or reactive substances, typically featuring UN-certified constructions with pressure ratings, gasket seals, and venting mechanisms to prevent leakage or combustion. Drums retain dominance in lubricant and solvent distribution due to standardized handling equipment and established recycling infrastructure, while intermediate bulk containers capture expanding share in bulk chemical logistics where cube utilization and forklift compatibility reduce per-liter shipping costs. Plastic containers lead in agricultural chemical packaging where UV resistance and chemical inertness outperform metal alternatives, though steel maintains structural preference for high-temperature petroleum derivatives and solvent recovery operations.
EPA hazardous waste container regulations and DOT 49 CFR shipping requirements mandate specific wall thicknesses, closure systems, and labeling protocols that directly shape product development budgets and certification timelines for domestic manufacturers. ECHA REACH compliance in Europe and China's GB standards for dangerous goods packaging create parallel compliance architectures that exporters must simultaneously satisfy. Stakeholders should monitor evolving state-level extended producer responsibility frameworks and their potential to transform container ownership models toward service-based revenue structures.
Market Dynamics
Reusable intermediate bulk container pooling networks are compressing capital deployment cycles for chemical distributors, converting fixed asset ownership into variable operating expenses while tightening traceability requirements under hazardous materials tracking mandates.
Growth Catalysts
- EU REACH chemical safety mandates:Specialty chemical producers in Germany are expanding reusable IBC programs to satisfy ECHA documentation and lifecycle tracking requirements for hazardous substance handling.
- India's petrochemical corridor expansion:Domestic refining capacity growth near Gujarat is concentrating demand for corrosion-resistant storage systems serving downstream polymer and solvent operations.
- Composite material substitution:Lightweight fiber-reinforced polymer designs are displacing steel in solvent transport applications where tare weight reduction directly lowers freight costs per liter.
Market Restraints
- Steel price volatility:Drum manufacturers face margin compression when hot-rolled coil costs spike, forcing pass-through delays that erode contract profitability.
- Refurbishment infrastructure concentration:Closed-loop reconditioning capacity clusters in the US Gulf Coast and Rotterdam-Antwerp corridor, creating logistics dead zones for inland chemical producers.
- Cross-border certification friction:Exporters must simultaneously satisfy EPA hazardous waste container regulations, ECHA REACH compliance, and China's GB standards for dangerous goods packaging, multiplying testing budgets.
Strategic Opportunities
- Extended producer responsibility frameworks:California and New York state-level EPR legislation is creating service-based revenue structures where container-as-a-service models capture recurring revenue streams.
- Agricultural chemical UV resistance demand:Plastic container specifications for pesticide and fertilizer distribution in Brazil and Australia favor high-density polyethylene formulations over metal alternatives.
- Digital tracking convergence:RFID-enabled IBC systems combined with blockchain provenance records are opening premium pricing tiers for pharmaceutical and food-grade chemical logistics.
Industry Challenges
- UN certification timeline compression:New composite designs require 12-18 month approval cycles through DOT and RID/ADR testing protocols, delaying product launches.
- Legacy ERP integration friction:Pooling network operators struggle to synchronize container tracking data with customer inventory management systems, creating reconciliation bottlenecks.
- Specialized welding technician scarcity:Steel drum reconditioning facilities face hiring gaps for certified pressure vessel repair skills required by OSHA process safety standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical and Petroleum Containers Market |
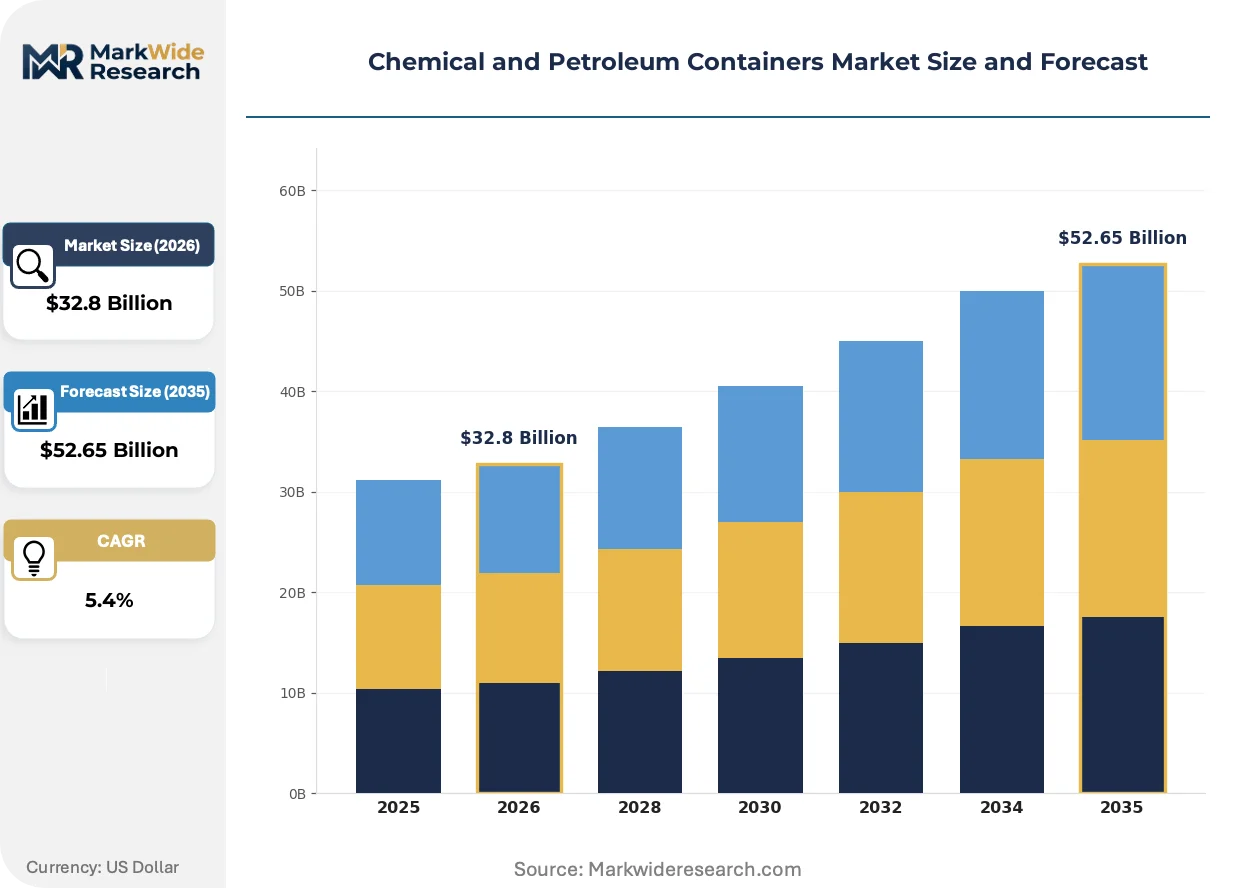
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Drums, Tanks, Intermediate Bulk Containers, Bottles Material: Plastic, Steel, Aluminum, Composite End Use Industry: Chemicals, Oil & Gas, Agriculture, Pharmaceuticals Packaging Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Hazardous |
| Companies Covered | Berry Global, Amcor, Greif, Mauser Packaging Solutions, Schütz, Consolidated Container Company, Berlin Packaging, Alpha Packaging, Drug Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical and Petroleum Containers Market Strategic Shifts
Material science breakthroughs and regulatory digitization are converging to transform container lifecycle economics, with particular momentum in lightweight composite adoption and sensor-enabled asset tracking.
Multi-layer co-extruded polymer barrier technology is integrating oxygen and moisture ingress resistance into intermediate bulk container designs. Agricultural chemical distributors in Brazil and Australia are adopting these specifications at accelerated rates to satisfy extended shelf-life requirements for formulated pesticides. This material evolution is integrating premium pricing tiers into commodity container categories previously dominated by single-layer HDPE.
ECHA's SCIP database obligations under the EU Waste Framework Directive are mandating granular substance-of-concern disclosure across container supply chains. Chemical distributors serving European manufacturing must now trace SVHC content through every coating, gasket, and liner component. Small and mid-sized drum suppliers without dedicated compliance teams are outsourcing documentation to third-party platforms, fragmenting competitive positioning around data infrastructure rather than manufacturing scale.
Leasing arrangements for reusable IBC fleets are displacing outright purchase in North American specialty chemical distribution. Third-party pooling operators now manage container rotation, cleaning certification, and damage liability for regional solvent and lubricant distributors. This financial restructuring is most visible in the US Great Lakes manufacturing corridor, where chemical distributors report 30-40% lower working capital requirements compared to owned-fleet models.
Chemical and Petroleum Containers Market Segmentation
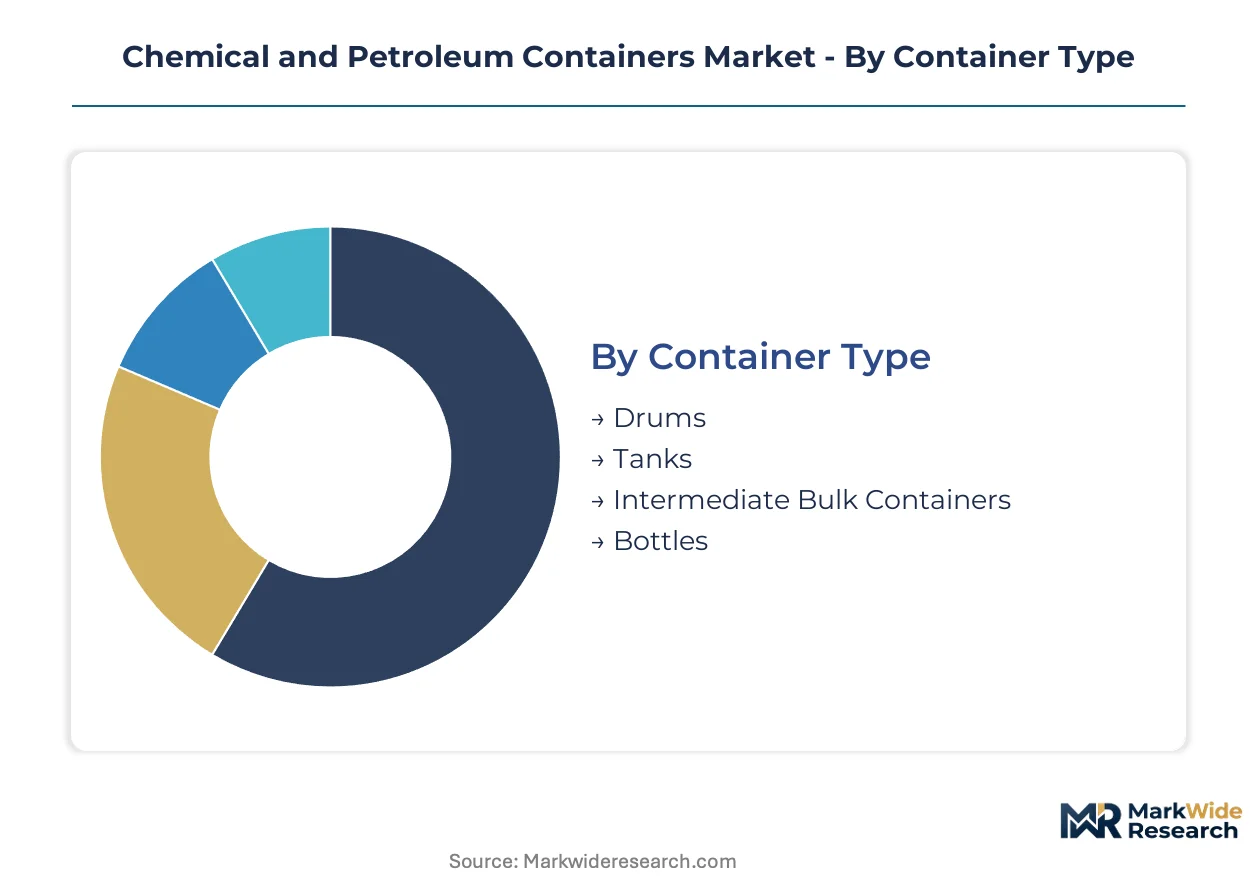
Container specifications diverge sharply across chemical handling applications, with material selection and certification grade determining regulatory compliance pathways and total cost of ownership. Procurement teams segment purchasing decisions by transport mode, substance hazard class, and reuse frequency rather than unit price alone.
Container Type:
Manufacturing capacity clusters around drum and IBC production lines, with tank fabrication requiring specialized pressure vessel certification that limits supplier bases.
- Drums:Steel and fiber constructions dominate lubricant distribution networks where standardized 55-gallon dimensions interface with existing filling lines and drum handling equipment. Demand concentrates in US Gulf Coast solvent recovery operations where DOT 49 CFR specifications mandate specific wall thicknesses for flammable liquid transport.
- Intermediate Bulk Containers:Composite and stainless steel designs with UN-certified stacking frames capture bulk chemical logistics where cube utilization and forklift compatibility reduce per-liter shipping costs. Specialty chemical producers in Germany are expanding reusable IBC programs under ECHA chemical safety mandates that require lifecycle documentation.
- Tanks:Stationary and transportable pressure vessels serve high-volume petroleum derivatives and corrosive acid storage with ASME and ADR certification requirements.
- Bottles:Small-format HDPE and fluoropolymer containers address laboratory reagents and specialty additive distribution.
Today's leader: Drums. Tomorrow's challenger: Intermediate Bulk Containers.
Material:
Raw material sourcing geography shapes cost structures, with steel coil availability tied to integrated mill locations and polymer grades dependent on petrochemical feedstock corridors.
- Steel:Hot-rolled and cold-rolled carbon steel constructions retain structural preference for high-temperature petroleum derivatives and solvent recovery operations where drum integrity under thermal stress is non-negotiable. Drum manufacturers face margin compression when coil costs spike, forcing pass-through delays that erode contract profitability.
- Plastic:High-density polyethylene and fluoropolymer formulations lead in agricultural chemical packaging where UV resistance and chemical inertness outperform metal alternatives for pesticide and fertilizer distribution in Brazil and Australia.
- Aluminum:Lightweight corrosion-resistant alloys serve specialty solvent and cosmetic chemical transport where tare weight reduction justifies material premium.
- Composite:Fiber-reinforced polymer designs are displacing steel in solvent transport applications where tare weight reduction directly lowers freight costs per liter.
Steel commands volume leadership. Composite materials are climbing the fastest on substitution economics.
End Use Industry:
Customer concentration patterns vary by sector, with oil and gas procurement consolidating through major integrated operators while agricultural distribution fragments across regional cooperatives.
- Chemicals:Specialty and commodity chemical producers drive demand for multi-trip IBC pooling systems and UN-certified drum fleets with traceability documentation.
- Oil & Gas:Downstream refining and lubricant blending operations require corrosion-resistant storage systems serving polymer and solvent operations, with India's petrochemical corridor near Gujarat concentrating demand as domestic refining capacity expands.
- Agriculture:Formulated pesticide and fertilizer distributors specify UV-stabilized HDPE containers with extended shelf-life barrier properties.
- Pharmaceuticals:cGMP-compliant container systems with extractables testing and sterile filling compatibility command premium positioning.
Chemical sector procurement sets specification standards. Pharmaceutical grade requirements are gaining share fastest on regulatory stringency.
Packaging Grade:
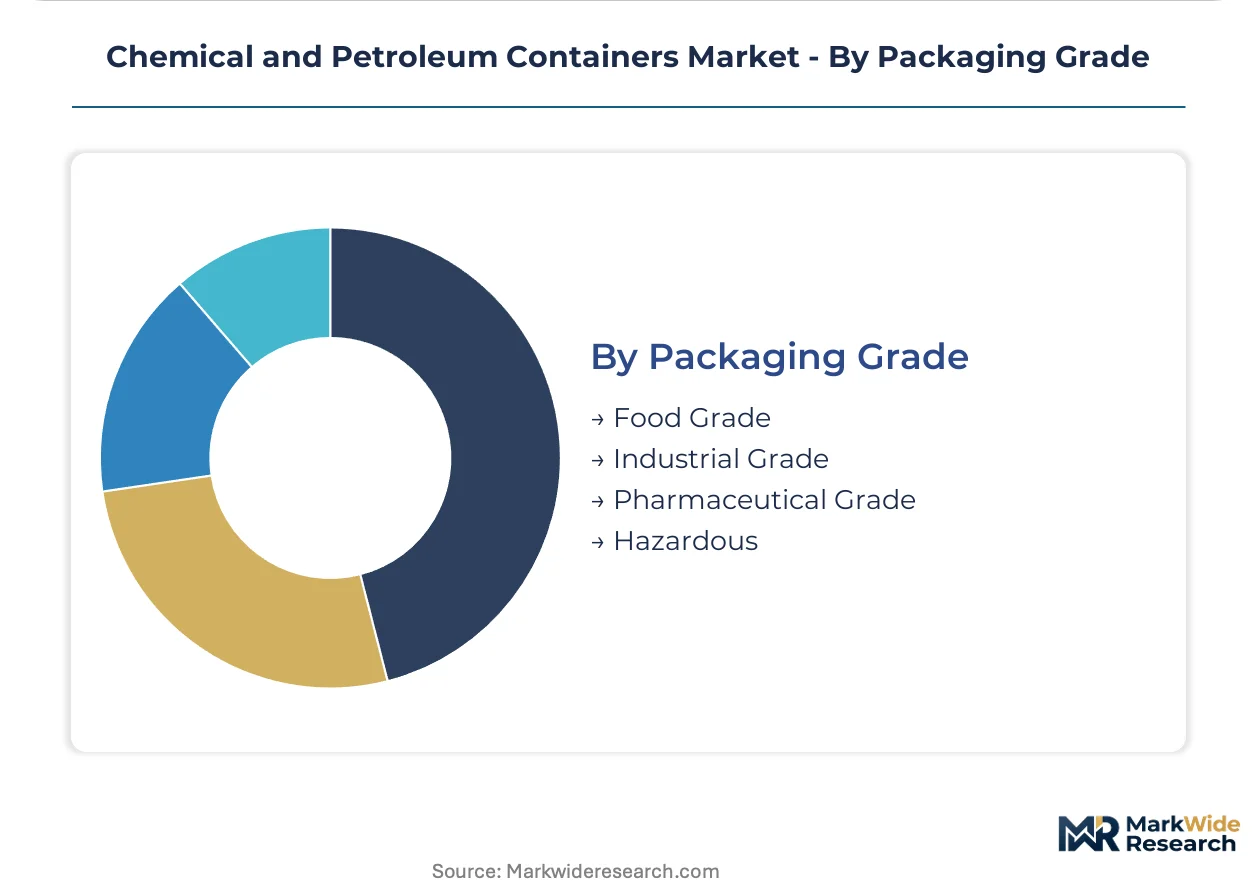
Certification tier determines testing protocols and documentation burdens, with hazardous grade requiring the most extensive UN performance testing and pharmaceutical grade demanding extractables validation.
- Hazardous:UN-certified constructions with pressure ratings, gasket seals, and venting mechanisms prevent leakage or combustion for corrosive, flammable, and reactive substances across DOT, RID, and ADR transport regulations.
- Industrial Grade:Standard duty containers serve non-regulated chemicals and general manufacturing inputs with lower certification overhead.
- Food Grade:FDA and EFSA compliant materials with migration testing address edible oil and food additive containment.
- Pharmaceutical Grade:USP Class VI and EP 3.1.9 compliant materials with dedicated manufacturing lines serve active pharmaceutical ingredient and excipient handling.
Hazardous grade dominates shipment value. Pharmaceutical grade shows steepest expansion trajectory on biologics logistics growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The chemical and petroleum containers industry traces its modern scale to German industrialization in the late 19th century, when BASF and Bayer pioneered standardized steel drum logistics for coal-tar derivatives. Today's geographic footprint reflects this heritage while incorporating new production corridors in Asia and North America.
United States
Downstream refining and lubricant blending operations drive drum demand along the Gulf Coast, where solvent recovery facilities cluster under EPA hazardous waste container regulations. The US DOT 49 CFR framework mandates specific wall thicknesses and closure systems that shape domestic manufacturing specifications. Houston and Baton Rouge anchor concentrated reconditioning infrastructure serving regional chemical distributors.
Germany
Specialty chemical producers in the Rhine-Ruhr and Ludwigshafen corridors are expanding reusable IBC programs to satisfy ECHA REACH documentation requirements. The country's ECHA SCIP database obligations under the EU Waste Framework Directive force granular substance-of-concern disclosure across container supply chains. BASF's headquarters region sets specification standards adopted across European chemical distribution networks.
India
Domestic refining capacity expansion near Gujarat's petrochemical corridor is concentrating demand for corrosion-resistant storage systems serving downstream polymer operations. The country's BIS standards for dangerous goods packaging create parallel compliance architectures for exporters. Reliance Industries' Jamnagar complex anchors regional procurement patterns for intermediate bulk containers.
China
State-owned refinery expansion along the Yangtze River Delta and Bohai Rim is driving tank fabrication demand under GB standards for dangerous goods packaging. The Ministry of Ecology and Environment's dual carbon goals are pressuring steel drum manufacturers toward lighter composite alternatives. Shanghai and Ningbo port clusters handle the bulk of Asia-Pacific container re-export traffic.
Brazil
Agricultural chemical distributors in São Paulo and Mato Grosso specify UV-stabilized HDPE containers for pesticide distribution under ANVISA agrochemical packaging guidelines. The country's national pharmaceutical regulator maintains strict extractables testing protocols for pharmaceutical-grade containers. Campinas and São José dos Campos host concentrated plastic container manufacturing serving Latin American markets.
Chemical and Petroleum Containers Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification grade and service integration dimensions. The vendor base organizes into three tiers: integrated pooling network operators, specialized material fabricators, and regional reconditioning specialists. Structural consolidation is accelerating through closed-loop asset ownership models and cross-border certification capability acquisitions. Geographic expansion and strategic partnerships represent the dominant competitive moves as players seek to bridge logistics dead zones.
Within the integrated pooling tier, Mauser Packaging Solutions and Greif exemplify asset-light service architectures that convert distributor capital deployment from fixed to variable cost structures. Schütz occupies a position among composite material specialists leveraging fiber-reinforced designs for tare weight reduction. These three anchors illustrate divergent strategic bets on material substitution versus fleet management optimization.
| Leading Market Players |
|---|
| Berry Global |
| Amcor |
| Greif |
| Mauser Packaging Solutions |
| Schütz |
| Consolidated Container Company |
| Berlin Packaging |
| Alpha Packaging |
| Drug Plastics |
| Others |
Value Chain & Pricing Dynamics
Hot-rolled coil price indices cascade through chemical container manufacturing into three distinct procurement tiers. Steel-dependent drum producers pass material volatility to contract customers with 60-90 day lags, while composite IBC specialists anchor pricing on polymer feedstock corridors near Gulf Coast petrochemical complexes.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates UN-certified hazardous-grade containers from industrial-grade alternatives. Price differentiation hinges on certification grade and volume scale, with pharmaceutical-grade extractables testing commanding material premiums over standard hazardous-grade constructions. Cost compression in standard-grade steel drums is intensifying because hot-rolled coil volatility erodes fixed-contract margins. Regional solvent distributors show highest price sensitivity, while pharmaceutical logistics buyers prioritize traceability documentation over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from chemical distributors mandate multi-supplier qualification across steel drum, composite IBC, and reconditioning service categories. Manufacturing capacity concentrates in the United States, Germany, and China, with raw material sourcing drawing from integrated steel mills in each region. Feedstock dependencies span hot-rolled carbon steel, high-density polyethylene resin, and fiber-reinforced polymer composites. Single-source vulnerability looms where ASME-certified pressure vessel fabrication clusters along the US Gulf Coast. Distribution runs through third-party pooling operators who manage container rotation, cleaning certification, and damage liability for regional chemical networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
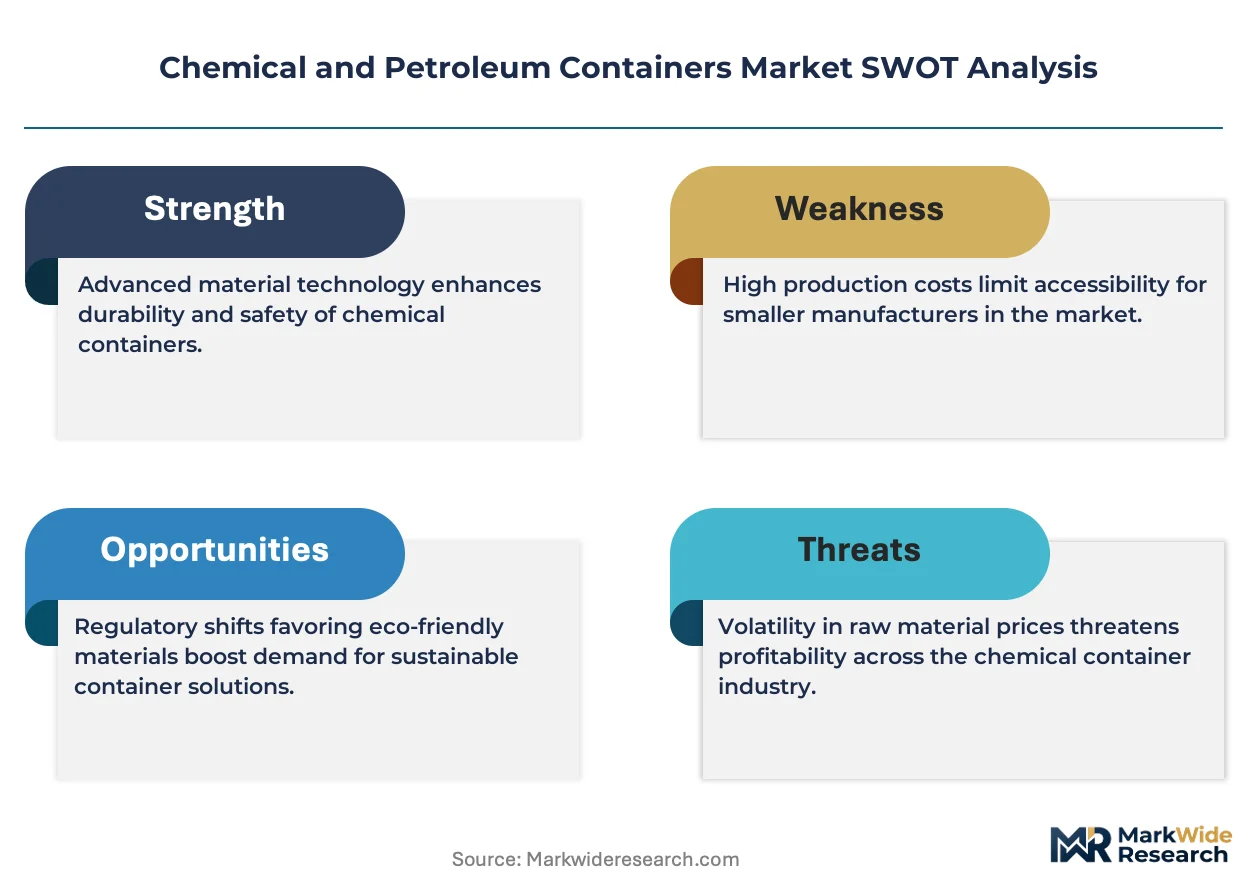
Chemical container procurement arbitrages the compliance cost differential between ECHA REACH documentation in Europe and EPA hazardous waste regulations in the United States. German specialty chemical producers face steeper lifecycle tracking burdens than Gulf Coast solvent distributors, compressing European margins faster.
For Market Incumbents: Lock in reconditioning infrastructure acquisitions along logistics corridors where pooling network density creates customer switching costs. Composite material substitution threatens steel drum incumbents in solvent transport applications; backward integration into fiber-reinforced polymer fabrication secures tare-weight advantages. Capacity addition near Gujarat's petrochemical corridor captures India's refining expansion demand before regional competitors establish service footholds.
For New Entrants and Emerging Players: Third-party logistics providers represent the most accessible channel partner type for container-as-a-service market entry. White-space targets include RFID-enabled IBC tracking for pharmaceutical-grade logistics and UV-stabilized HDPE formulations for Brazilian agricultural chemical distribution. The most penetrable segment is mid-sized specialty chemical distributors in the US Great Lakes corridor seeking working capital relief through leased-fleet conversion.
For Investors and Strategic Acquirers: Asymmetric upside sits with composite material specialists who combine fiber-reinforced designs with digital tracking infrastructure. Long-term viability over the coming decade favors operators who control closed-loop reconditioning assets rather than pure manufacturing plays. Acquisition target archetype: regional pooling networks with established customer relationships in underserved inland corridors. Watch for inflection when California or New York extended producer responsibility legislation triggers fleet-ownership model conversion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive HDPE supply secures UV-stabilized formulations for Brazilian agricultural chemical demand. |
| RFID-Enabled Asset Tracking Deployment | Blockchain-linked IBC provenance opens premium tiers for pharmaceutical logistics under FDA scrutiny. |
| Reconditioning Capacity Expansion | Gulf Coast cluster additions close logistics dead zones for inland solvent recovery operations. |
| Joint Venture with Pooling Network Operator | Mauser-style closed-loop partnerships convert distributor capital deployment from fixed to variable costs. |
| Composite IBC Manufacturing Scale-Up | Fiber-reinforced designs displace steel in solvent transport where freight cost per liter determines procurement. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged plant managers at drum manufacturing facilities, procurement leads at downstream specialty chemical distributors, reconditioning facility operators, and technical R&D directors at composite material suppliers. Secondary validation drew from customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings from listed packaging companies, and DOT hazardous materials incident databases. Bottom-up capacity estimates from individual manufacturing sites triangulated against top-down demand modeling from end-use industry consumption patterns.
Comparable-period anchoring linked the projection horizon to historical reference windows spanning pre-pandemic baseline, supply disruption volatility, and normalization phases. The analytical framework modeled segmentation across packaging format, material type, certification grade tier, end-use industry vertical, and regional production hub. CAGRs derived from fitted growth curves applied to each segment, with cross-segment consistency checks against macro chemical production indices. Industry-specific forecast inputs included UN certification approval timelines and ECHA SCIP database compliance cost trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel price volatility, composite material substitution rates, and state-level extended producer responsibility adoption timing. Deviation in hot-rolled coil cost trajectories or UN certification timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Global Perfluorocarbons Market
Petrochemicals
Oman Pyrolysis Gasoline Market
Petrochemicals
Olefin Derivatives Market
Petrochemicals
Propylene Carbonate Market
Petrochemicals
Petrochemicals Market
Petrochemicals
Propylene Market
Petrochemicals
Synthetic and Biobased Butadiene Market
Petrochemicals
Propane Market
Petrochemicals
Malaysia Chemical and Petrochemical Market
Petrochemicals
Anthracene Oil Market
Petrochemicals
Global Polypropylene Market
Petrochemicals
Pentaerythritol Market
Petrochemicals
Tert Butyl Hydroperoxide Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market
Petrochemicals
Military Propellants Market
Petrochemicals
Pentane Market