
 Mexico Adhesives Market | 2026-2036
Mexico Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Adhesives Market Foresight
ISO 9001 and IATF 16949 qualification cycles for automotive adhesive supply is unwinding the competitive field, raising barriers for uncertified domestic blenders. Henkel AG & Co. KGaA leverages its captive polyurethane technology to dominate OEM specification lists across Mexican assembly plants. 3M sustains channel control through direct distributor relationships with major construction retailers in Mexico City and Monterrey. H.B. Fuller Company anchors its position with localized production serving woodworking exporters in Querétaro.
Adhesives are non-metallic substances formulated from synthetic polymers, resins, and curing agents that develop structural or semi-structural bonds through chemical crosslinking, mechanical interlocking, or diffusion mechanisms, typically achieving lap shear strengths between 1 and 35 MPa depending on chemistry and substrate preparation. These materials serve primarily to replace or supplement mechanical fasteners in manufacturing assemblies, reducing weight, distributing stress, and enabling dissimilar material joining across metal, composite, and polymer interfaces. Polyurethane formulations lead volume in Mexico due to their flexibility and moisture-cure versatility across construction and automotive applications, while epoxy systems command premium positioning in aerospace and industrial composite bonding where elevated temperature resistance justifies higher formulation costs. Acrylic adhesives represent the fastest-growing chemistry segment, displacing solvent cements in signage and transportation assembly as Mexican manufacturers adopt UV-curable and two-part structural acrylic platforms for faster throughput.
SEMARNAT enforces NOM-085-ECOL-2011 limits on volatile organic compound emissions from adhesive manufacturing and application, compelling reformulation investments toward water-based and hot-melt platforms. PROFECO monitors product labeling and performance claims for consumer-grade adhesives sold through retail channels, while NOM-004-SE-2021 standards govern industrial chemical hazard communication. The Secretariat of Economy's alignment with USMCA rules of origin affects tariff treatment for imported resin feedstocks, influencing domestic blending economics. Stakeholders must monitor pending updates to Mexico's General Law for Climate Change implementing regulations, as carbon accounting requirements could reshape supply chain sourcing for petrochemical-derived adhesive intermediates.
Market Dynamics
Automotive OEMs in Guanajuato and Nuevo León are consolidating adhesive specifications around IATF 16949-qualified suppliers, compressing the vendor base and elevating technical barriers for uncertified domestic blenders serving specification-grade bonding applications.
Growth Catalysts
- SEMARNAT VOC limits:NOM-085-ECOL-2011 enforcement is accelerating water-based and hot-melt platform investments across Mexican adhesive manufacturing facilities.
- Aerospace cluster expansion:Querétaro's aerostructures hub is driving specification-grade epoxy procurement for composite bonding in commercial aircraft assemblies.
- Lightweight vehicle bonding:Multi-material joining requirements in Bajío automotive plants are displacing mechanical fasteners with structural polyurethane and acrylic platforms.
Market Restraints
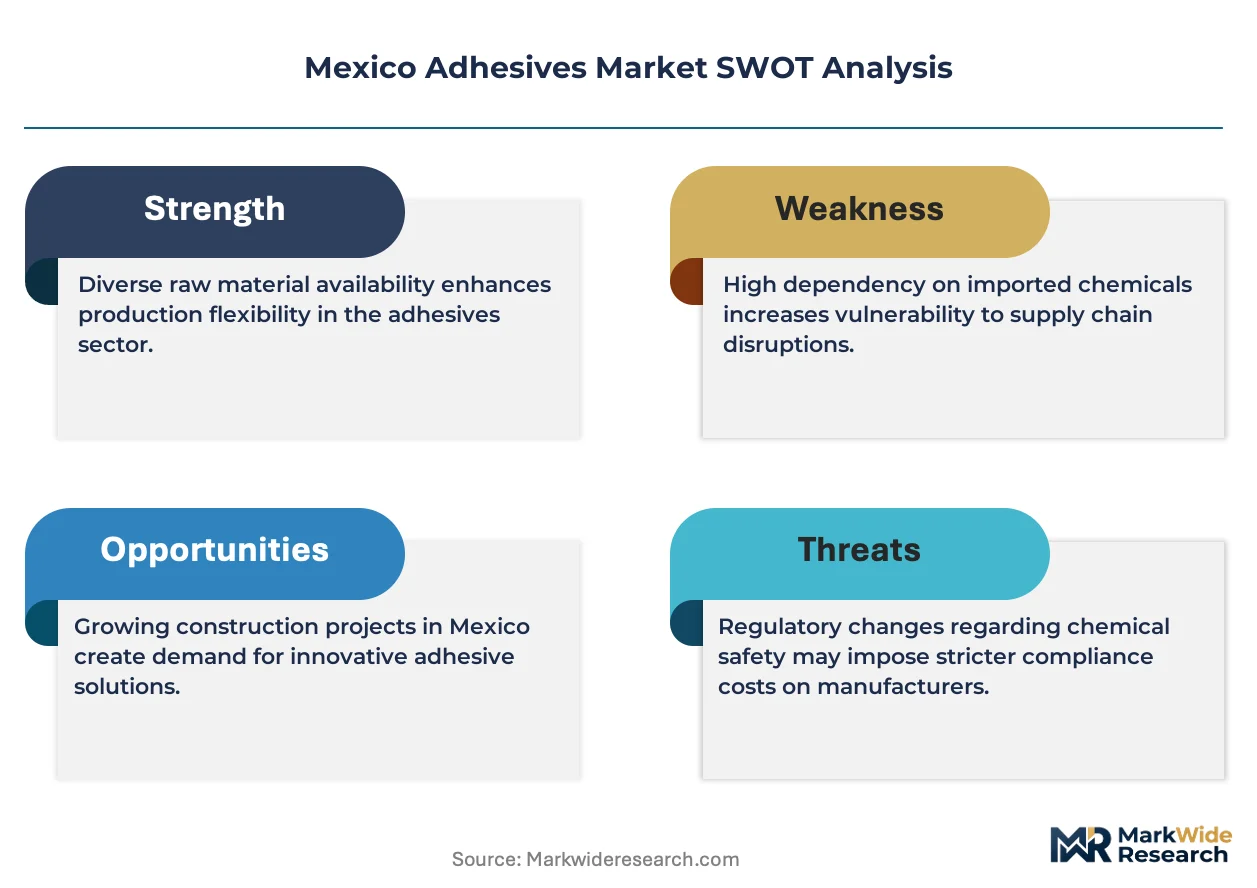
- Petrochemical feedstock volatility:Imported resin intermediates face USMCA rules-of-origin tariff uncertainty, squeezing blending margins for domestic formulators.
- ISO 9001 certification bottlenecks:Extended audit timelines at SEMARNAT-recognized bodies delay market entry for new adhesive suppliers targeting OEM qualification lists.
- Mechanical fastener persistence:Cold-stamped joining retains cost advantage in heavy-truck chassis assembly, limiting adhesive penetration in commercial vehicle manufacturing.
Strategic Opportunities
- Yucatán manufacturing corridor:Nearshoring momentum in Mérida industrial parks creates greenfield demand for construction and packaging adhesives outside saturated central regions.
- UV-curable acrylic convergence:Signage and transportation assembly sectors are adopting dual-cure platforms combining UV initiation with moisture secondary cure for throughput gains.
- PROFECO labeling alignment:Compliance investments for consumer-grade adhesive retail channels open shelf-space expansion in Mexico City and Monterrey home improvement chains.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for moisture-cure polyurethane systems concentrates among retiring technical staff at legacy Guadalajara blending operations.
- Clean-room retrofit capex:Aerospace specification compliance requires ISO 14644-1 Class 8 production environments that mid-cap domestic producers cannot finance without external capital.
- Legacy solvent inventory:Existing stocks of toluene-based contact cements complicate SEMARNAT transition timelines for woodworking exporters in Querétaro.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Adhesives Market |
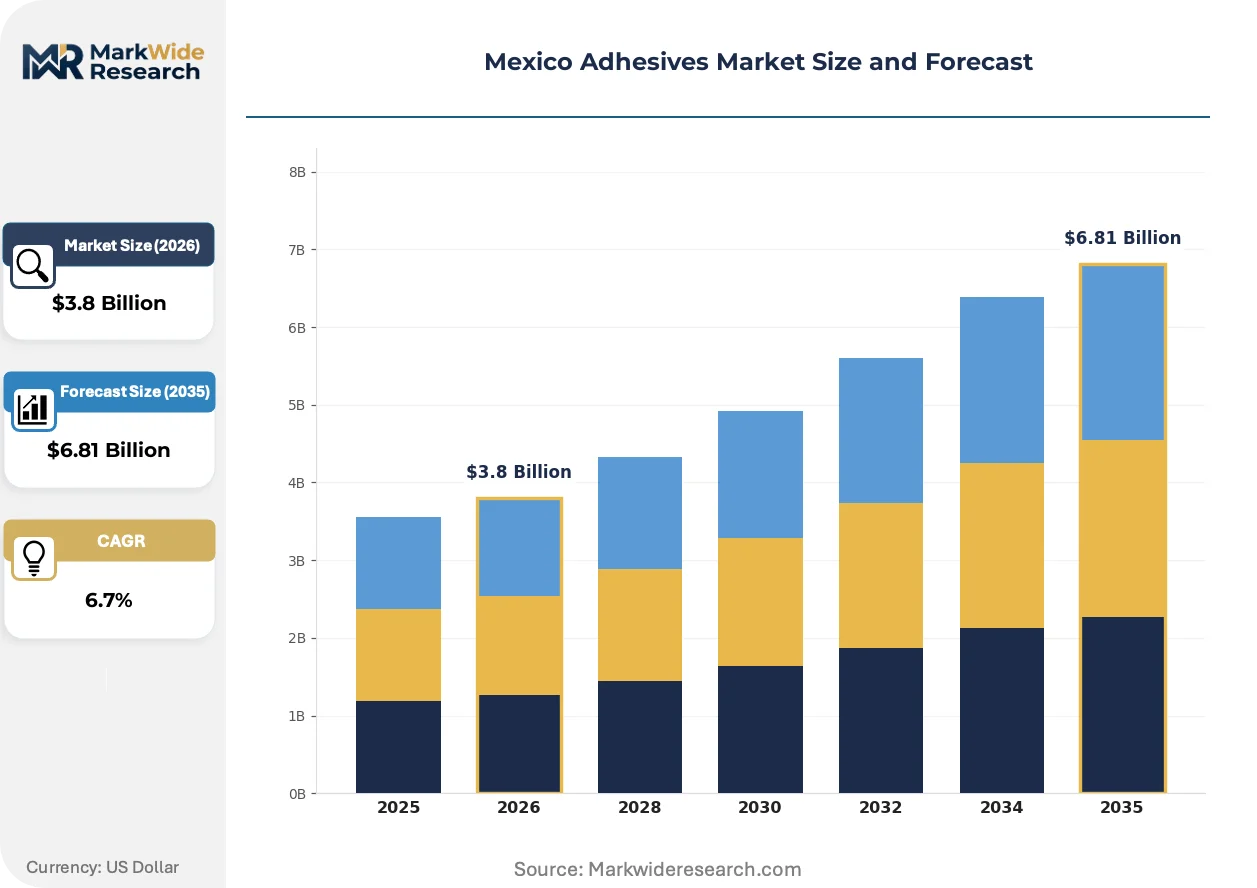
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Silicone Application: Construction, Automotive, Woodworking, Packaging End User: Manufacturers, Contractors, Retailers, Distributors Form: Liquid, Paste, Powder, Tape |
| Companies Covered | 3M, Henkel AG & Co. KGaA, Sika AG, Arkema Group, H.B. Fuller Company, Dow, Illinois Tool Works Inc., Saint-Gobain, Jowat SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Adhesives Market Shifts & Advancements
Adhesive chemistry platforms are pivoting toward faster-cure, lower-VOC formulations as Mexican industrial buyers prioritize throughput and regulatory compliance over legacy solvent-based bonding systems.
Two-part structural acrylic systems are supplanting solvent cements in transportation assembly and signage fabrication. Tier-two automotive suppliers in Puebla are adopting these platforms for mixed-substrate bonding. The shift is compressing fixture times from hours to minutes while eliminating VOC exposure compliance costs.
SEMARNAT's pending updates to NOM-085-ECOL-2011 implementation guidelines are tightening residual solvent thresholds in adhesive manufacturing. Domestic blenders are reformulating hot-melt polyurethanes to preempt enforcement actions. Construction-grade adhesive producers in Estado de México face the steepest reformulation investments.
Buyer concentration among Bajío automotive OEMs is consolidating procurement decisions around qualified supplier lists. Tier-one suppliers are bypassing distributor networks for direct mill agreements with certified adhesive formulators. The pattern is most pronounced in Guanajuato assembly plant supply chains.
Mexico Adhesives Market Segmentation
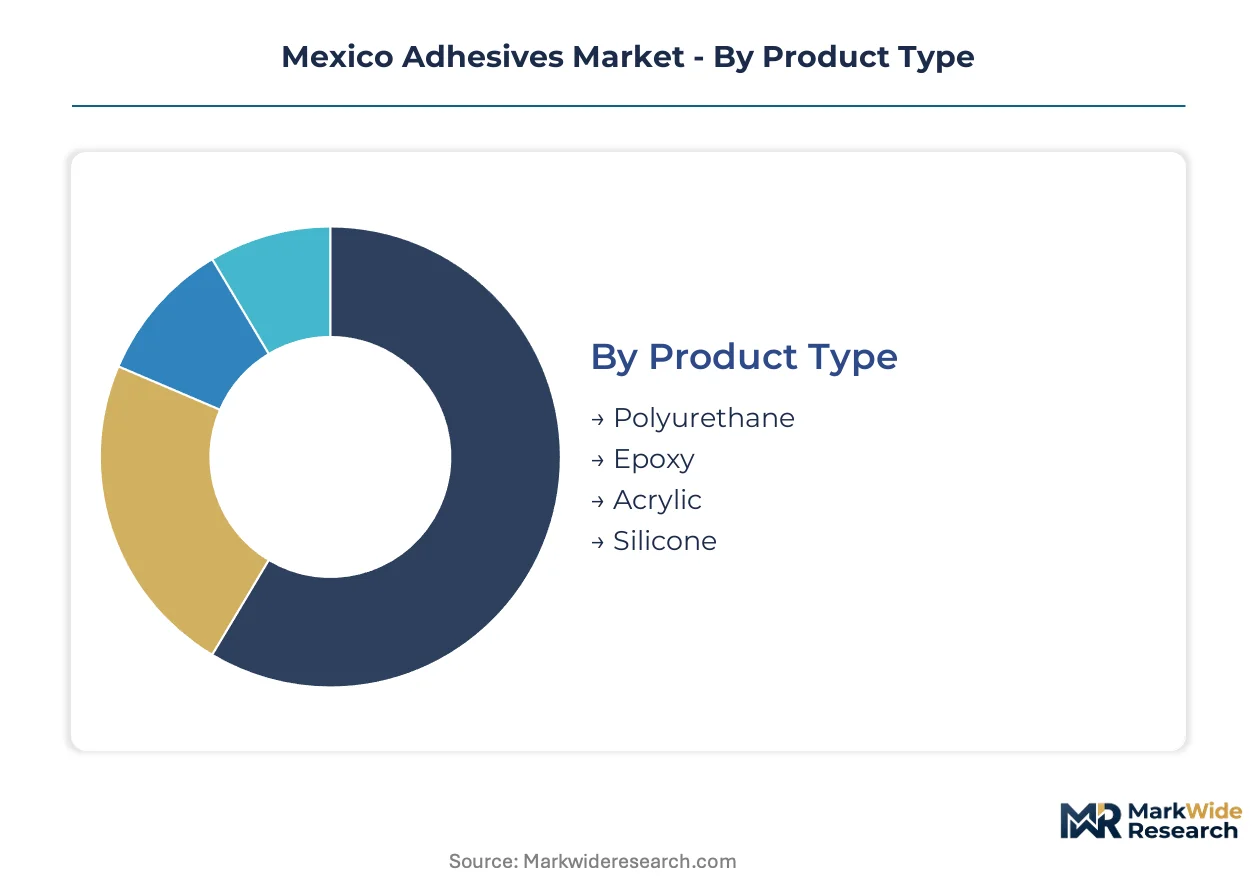
Segmentation in the Mexico adhesives market reveals distinct margin architectures across chemistry platforms and procurement channels. Understanding where specification-grade demand concentrates versus commodity volume enables targeted resource allocation for formulators and distributors.
Product Type:
Polyurethane and epoxy formulations capture the deepest margin pools due to OEM qualification requirements and aerospace specification barriers.
- Polyurethane:Moisture-cure systems dominate construction sealing and automotive panel bonding across Guanajuato assembly plants. Bajío automotive OEMs specify these formulations for multi-material substrates where flexibility and impact resistance justify premium positioning.
- Epoxy:Two-part thermoset systems serve Querétaro aerostructures fabrication and industrial composite repair. Elevated temperature resistance and lap shear performance above 25 MPa command specification-grade procurement from IATF 16949-qualified suppliers.
- Acrylic:UV-curable and two-part structural platforms displace solvent cements in Puebla transportation assembly and Monterrey signage fabrication.
- Silicone:High-temperature sealants concentrate in HVAC ductwork and electrical encapsulation across Estado de México industrial zones.
Polyurethane holds installed capacity across Guadalajara blending operations. Acrylic is rotating up the share rankings as SEMARNAT enforcement accelerates VOC-compliant platform adoption.
Application:
Automotive and construction applications split the market by procurement modality — direct mill agreements versus distributor-mediated retail channels.
- Construction:Water-based acrylics and hot-melt polyurethanes bond flooring, insulation, and facade systems across Mexico City and Monterrey commercial projects. PROFECO labeling compliance creates shelf-space differentiation in home improvement retail.
- Automotive:Structural adhesives replace spot welding and mechanical fasteners in Guanajuato and Nuevo León lightweight vehicle programs. OEM qualification lists compress vendor bases to IATF 16949-certified formulators with captive polyurethane technology.
- Woodworking:Hot-melt and PVA formulations serve Querétaro furniture exporters facing SEMARNAT solvent inventory transition deadlines.
- Packaging:Water-based acrylics and hot-melt EVA systems seal corrugated and flexible substrates in Yucatán nearshoring corridors.
Construction commands volume throughput. Automotive is climbing the fastest on value-per-kilogram metrics driven by specification-grade procurement.
End User:
Manufacturer procurement patterns diverge sharply from retail channel economics, with distributors caught in margin compression between consolidated OEM buying and fragmented contractor demand.
- Manufacturers:Tier-one automotive and aerospace OEMs in Bajío corridors negotiate direct mill agreements with qualified adhesive formulators. Volume commitments and technical service requirements exclude uncertified domestic blenders from specification lists.
- Contractors:Small and mid-scale construction operators in Estado de México and Jalisco purchase through regional distributors where price transparency limits brand loyalty.
- Retailers:Mexico City and Monterrey home improvement chains stock consumer-grade cyanoacrylates and epoxies under PROFECO-monitored labeling standards.
- Distributors:Industrial chemical distributors maintain inventory positions across multiple chemistry platforms to serve fragmented contractor and secondary manufacturing demand.
Manufacturers anchor specification-grade revenue. Distributors are gaining logistical importance as Yucatán corridor expansion stretches supply chain reach.
Form:
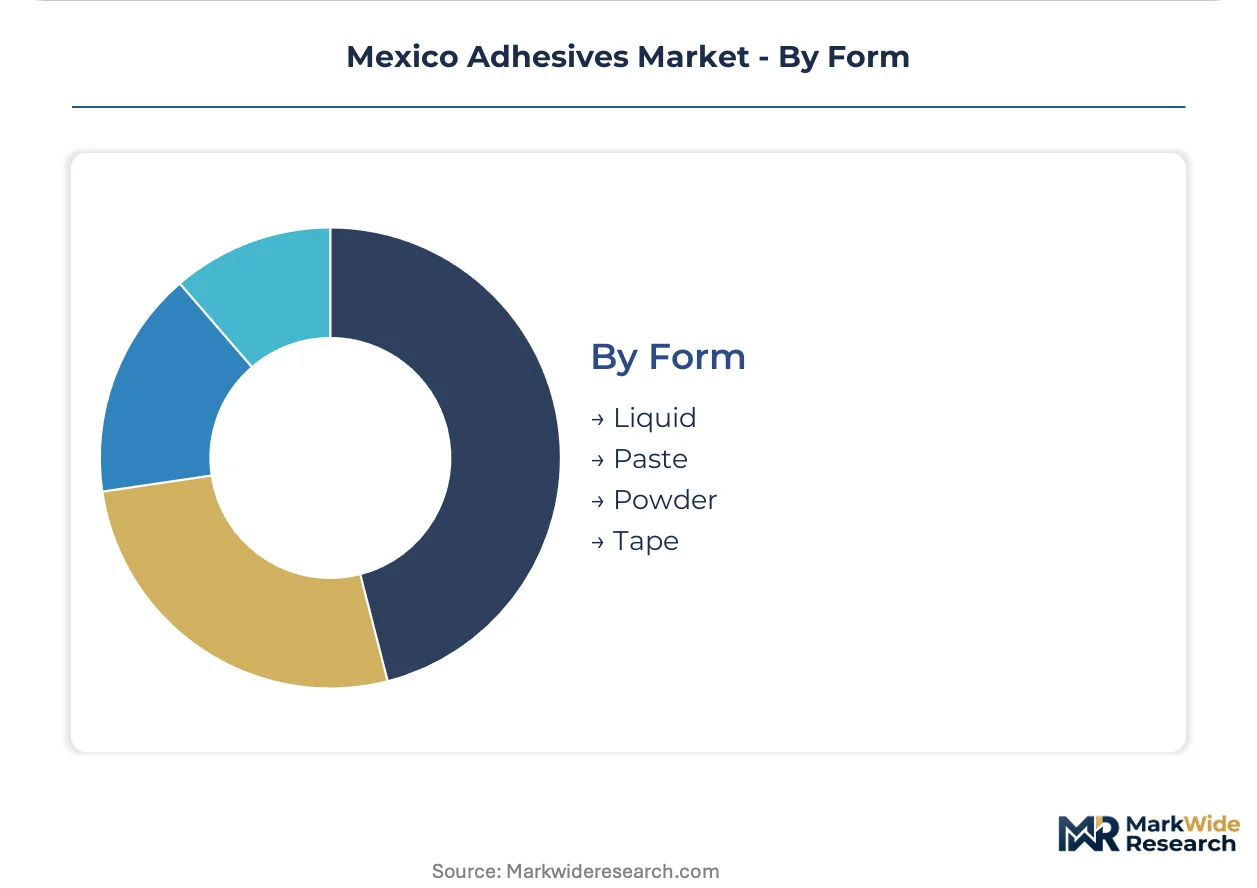
Liquid and paste formulations retain manufacturing concentration in legacy Guadalajara blending assets, while tape and powder formats import processing technology.
- Liquid:Solvent-based and water-borne systems in drum and tote packaging serve high-volume automotive and construction applications. SEMARNAT reformulation timelines concentrate investment in water-based platform conversions.
- Paste:Thixotropic epoxies and polyurethanes fill gap-bonding and vertical surface applications in aerospace assembly and industrial maintenance.
- Powder:Hot-melt adhesive powders support textile lamination and woodworking edge-banding in specialized Querétaro operations.
- Tape:Pressure-sensitive acrylic and silicone tapes serve electrical insulation and temporary assembly fixturing across electronics contract manufacturers in Baja California.
Liquid maintains production scale. Tape is expanding most quickly as electronics assembly and automotive trim attachment adopt pressure-sensitive platforms for labor efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEMARNAT's enforcement of NOM-085-ECOL-2011 VOC limits is redirecting capital toward water-based and hot-melt production assets across Mexican industrial corridors. State-level economic development incentives in Nuevo León and Guanajuato are accelerating adhesive demand from automotive OEM expansion. The analysis examines five sub-regions where specification-grade procurement concentrates.
Nuevo León
Automotive assembly plants in Apodaca and Escobedo are displacing mechanical fasteners with structural polyurethane bonding for lightweight vehicle programs. The state's Secretariat of Economy coordinates with federal SEMARNAT officials on accelerated environmental permitting for reformulated adhesive facilities. Monterrey anchors distributor networks serving construction-grade demand across northern Mexico.
Guanajuato
Bajío automotive OEMs specify IATF 16949-qualified adhesive suppliers for multi-material chassis and panel bonding applications. PROFECO monitors product labeling compliance for consumer-grade adhesives retailed through León and Irapuato home improvement channels. Silao assembly plants drive direct mill agreements with captive polyurethane technology holders.
Querétaro
Aerospace aerostructures fabrication demands specification-grade epoxy systems with elevated temperature resistance above 25 MPa lap shear. The state's environmental agency enforces SEMARNAT-aligned VOC thresholds for adhesive manufacturing within the Querétaro Industrial Park. Woodworking exporters face solvent inventory transition deadlines under pending NOM-085-ECOL-2011 updates.
Jalisco
Legacy Guadalajara blending operations concentrate formulation expertise for moisture-cure polyurethane systems among retiring technical staff. The state Secretariat of Environment and Territorial Development implements SEMARNAT-mandated emission monitoring for solvent-based adhesive production. Tlaquepaque furniture manufacturers are converting hot-melt platforms for export compliance.
Yucatán
Mérida industrial parks attract nearshoring investment creating greenfield demand for construction and packaging adhesives outside saturated central regions. State economic promotion agencies coordinate with federal customs authorities on USMCA rules-of-origin documentation for imported resin feedstocks. Progreso port logistics support Yucatán corridor supply chain reach to southeastern US markets.
Mexico Adhesives Market Competitive Landscape
Player mix skews toward multinational chemical conglomerates with captive polymer technology and established IATF 16949 qualification status. Three structural tiers have crystallized: specification-grade formulators serving OEM direct procurement, construction-focused distributors controlling retail shelf space, and mid-cap domestic blenders supplying woodworking and packaging segments. M&A activity concentrates on acquiring SEMARNAT-compliant production assets, while greenfield investment targets Yucatán corridor capacity for nearshoring demand.
Within the multinational specification-grade tier, Henkel AG & Co. KGaA and 3M exemplify divergent channel strategies—Henkel leveraging captive polyurethane technology for OEM qualification lists, 3M sustaining distributor relationships with major construction retailers. H.B. Fuller Company occupies a position among mid-cap specialists with localized production serving regional export clusters. These three anchors represent how certification requirements and geographic proximity to Bajío automotive plants determine competitive positioning.
| Leading Market Players |
|---|
| 3M |
| Henkel AG & Co. KGaA |
| Sika AG |
| Arkema Group |
| H.B. Fuller Company |
| Dow |
| Illinois Tool Works Inc. |
| Saint-Gobain |
| Jowat SE |
| Others |
Supply & Pricing Matrix
IATF 16949 certification gates simultaneously determine supplier qualification status and price positioning across Mexican adhesive procurement. OEM specification lists compress vendor bases to certified formulators commanding premium positioning, while uncertified domestic blenders compete on price in commodity woodworking and packaging segments.
Pricing Analysis
Certification level creates the primary spread between specification-grade and commodity tiers in Mexican adhesive markets. Three-tier pricing structure separates IATF 16949-qualified automotive supply from ISO 9001 industrial grades and unlabeled retail products. Pricing pressure stems from USMCA rules-of-origin uncertainty on imported resin feedstocks squeezing domestic blender margins. Tier-one automotive OEMs exhibit lowest price sensitivity due to bonding performance liability exposure, while small construction contractors drive hard volume negotiations through distributor channels.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive adhesive procurement from Guanajuato assembly plants, while strategic stockpiling persists among construction distributors buffering SEMARNAT reformulation transitions. Supply concentrates in Germany, the United States, and Japan for specialty resin intermediates and curing agent technologies. Raw material dependencies center on MDI prepolymers, epoxy resins, and acrylic monomers subject to petrochemical price volatility. Single-source vulnerability concentrates in moisture-cure polyurethane formulation expertise held by retiring technical staff at legacy Guadalajara operations. Distribution runs through direct mill agreements for OEM supply and regional chemical distributors serving fragmented contractor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise for specification-grade bonding applications is thinning faster than replacement pipelines can replenish, creating durable competitive moats for qualified incumbents and acquisition premiums for scarce technical assets.
For Market Incumbents: Secure captive polyurethane technology positions through targeted recruitment of retiring formulation chemists from legacy Guadalajara blending operations. Expand ISO 14644-1 Class 8 clean-room capacity in Querétaro to preempt aerospace specification demand before mid-cap domestic competitors access external capital. SEMARNAT enforcement timelines threaten margin compression for solvent-based inventory holders; accelerate water-based platform conversions to defend positioning. For New Entrants and Emerging Players: IATF 16949 fast-track programs through SEMARNAT-recognized bodies open qualification pathways for Yucatán corridor automotive suppliers underserved by incumbent distribution networks. Target packaging adhesive demand in Mérida industrial parks where nearshoring momentum outpaces local production capacity. Lead with UV-curable acrylic platforms for signage fabrication in Monterrey, bypassing entrenched solvent-cement relationships through throughput advantages. For Investors and Strategic Acquirers: Pending NOM-085-ECOL-2011 implementation guideline updates reshape the acquisition landscape toward SEMARNAT-compliant production assets with water-based and hot-melt platform conversions already executed. Long-term viability favors targets with demonstrated OEM qualification relationships and captive polymer technology rather than commodity blending operations. Monitor IATF 16949 certification completion rates at mid-cap domestic formulators as inflection indicator for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Intermediates | USMCA rules-of-origin compliance secures tariff-advantaged feedstock supply for Guanajuato automotive adhesive production. |
| Clean-Room Manufacturing Scale-Up | ISO 14644-1 Class 8 capacity expansion in Querétaro captures specification-grade epoxy demand from aerostructures fabrication. |
| Water-Based Platform Conversion | SEMARNAT-aligned reformulation investments preempt enforcement action and open PROFECO-compliant retail shelf space. |
| Yucatán Corridor Distribution Buildout | Mérida industrial park proximity reduces logistics costs for packaging adhesive supply to nearshoring manufacturing operations. |
| Formulation Chemist Acquisition | Retiring technical staff recruitment from legacy Guadalajara operations transfers scarce moisture-cure polyurethane expertise. |
Research Methodology
Cross-validation between primary interviews with adhesive plant managers, automotive Tier 1 procurement leads, distribution channel partners, and technical R&D directors anchors the qualitative findings. Secondary validation draws from customs and trade data, SEC 10-K filings of multinational chemical conglomerates, SEMARNAT regulatory filings, and automotive production databases. Bottom-up segment sizing triangulates against top-down market value estimates across chemistry platforms and application verticals.
Sensitivity analysis on petrochemical feedstock cost assumptions and USMCA tariff treatment scenarios frames the projection horizon. The analytical framework segments by chemistry type, application end-use, procurement channel, and regional production cluster throughout the forecast period. CAGRs derive from fitted growth curves applied to segment-level volume and value baselines. Industry-specific forecast inputs include IATF 16949 certification penetration rates and SEMARNAT compliance transition timelines for solvent-based inventory.
The analysis sits within stated boundaries; outcomes outside sustained nearshoring momentum, stable USMCA trade treatment, or predictable SEMARNAT enforcement pacing would require recalibration. Forecasts reflect documented assumptions regarding automotive OEM expansion in Bajío corridors and aerospace cluster development in Querétaro. Revision becomes warranted when petrochemical feedstock volatility or regulatory implementation delays cross thresholds that alter domestic blending economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Epoxy Curing Agents Market
Adhesives & Sealants
Ocular Adhesives and Sealants Market
Adhesives & Sealants
Bio-Based Adhesive and Sealant Market
Adhesives & Sealants
Asia-Pacific Hot-Melt Adhesives Market
Adhesives & Sealants
South America Acrylic Adhesives Market
Adhesives & Sealants
Global Emulsion Adhesives Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
Latin America Adhesives and Sealants Market
Adhesives & Sealants
Corrosion Protection Tapes Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
US Tile Adhesive Market
Adhesives & Sealants
Chemical Anchors Market
Adhesives & Sealants
Wood Adhesives Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Packaging Adhesives Market