
 Bio Based Paraxylene Market | 2026-2036
Bio Based Paraxylene Market Size, Share, and Industry Trends Forecast 2026-2036
Bio Based Paraxylene Market Analysis
Packaging demand from beverage and food-grade PET producers is realigning procurement priorities across the value chain. Toray Industries leverages its integrated fiber-to-resin platform to anchor supply relationships with Asian polyester makers. BASF competes through catalytic conversion R&D intensity at its Ludwigshafen complex. Origin Materials specializes in woody biomass feedstock processing, occupying a distinct technology tier against petrochemical incumbents.
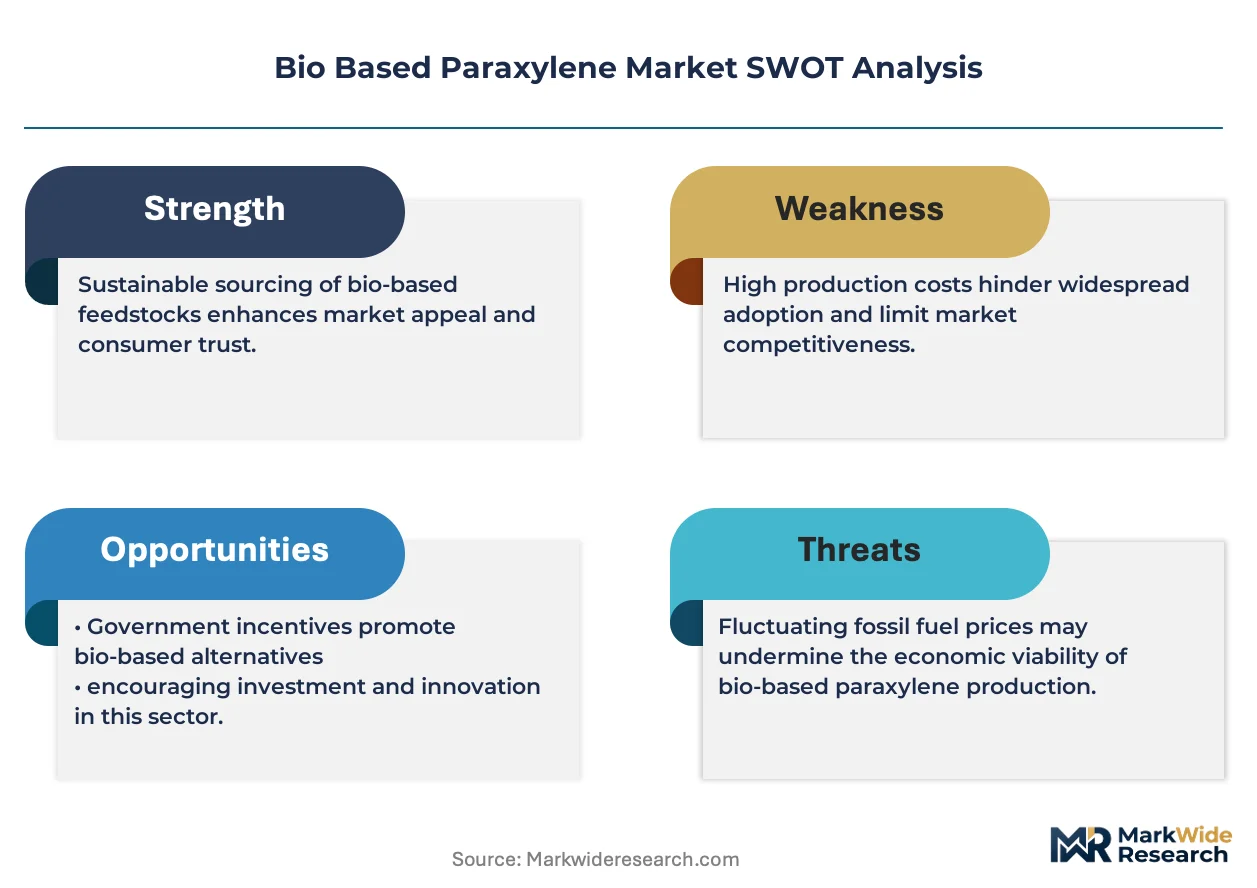
Bio based paraxylene denotes para-xylene manufactured from renewable feedstocks rather than naphtha cracking, typically achieving polymer-grade purity above 99.7 weight percent for terephthalic acid synthesis. The molecule serves as the principal building block for polyethylene terephthalate resin used in bottles, films, and synthetic fibers. Among technology routes, catalytic conversion from sugars and lignocellulosic streams currently leads commercial scale-up, while fermentation pathways attract venture capital for their selectivity advantages. On the application side, packaging commands the deepest margin pools due to brand-owner sustainability commitments, though automotive interior textiles represent the fastest-growing demand segment as OEMs phase in recycled content mandates.
EPA renewable fuel standards and EU REACH aromatic substance classifications jointly shape product certification requirements and market access conditions for bio based paraxylene producers. The EU Green Deal's packaging waste directive accelerates brand-owner switching from fossil-derived PET, while FDA food-contact approvals govern US beverage bottle adoption timelines. Stakeholders must monitor feedstock cost parity against naphtha-based paraxylene and the pace of ASTM D6866 biogenic carbon certification uptake across major polyester consuming regions.
Market Dynamics
EU REACH aromatic substance classifications are forcing polyester producers to requalify supply chains around biogenic carbon certification, compressing the window for fossil-based paraxylene conversion.
Growth Catalysts
- EU Green Deal packaging mandates:Brand-owners face binding recycled content thresholds for PET bottles by 2030, redirecting procurement toward ASTM D6866-certified feedstocks.
- Automotive interior mandates:OEMs in Germany now specify bio-derived polyester for seat fabrics and headliners, pulling volume through the Rhine chemical corridor.
- Catalytic conversion scale-up:Sugar-to-paraxylene pathways achieve polymer-grade purity above 99.7 weight percent, matching naphtha-cracking specifications for terephthalic acid synthesis.
Market Restraints
- Feedstock cost volatility:Woody biomass and agricultural residue prices fluctuate with harvest cycles and competing biofuel offtake, squeezing margin stability against naphtha-based benchmarks.
- Supply concentration risk:Catalytic conversion capacity clusters at pilot-scale facilities in Germany and the Netherlands, creating single-source dependencies for European converters.
- Fermentation pathway limitations:Microbial selectivity for para-xylene remains below commercial thresholds, trapping venture-backed projects in pre-scale validation.
Strategic Opportunities
- Underpenetrated US beverage packaging:FDA food-contact approval timelines lag EU certification by 18-24 months, creating first-mover windows for biogenic PET in carbonated soft drinks.
- Japan automotive textiles:METI carbon neutrality roadmaps for vehicle manufacturing are accelerating OEM sourcing of bio-derived interior materials.
- Technology convergence:Lignocellulosic preprocessing advances from pulp and paper industries are crossing into paraxylene feedstock preparation, lowering capital barriers for new entrants.
Industry Challenges
- ASTM D6866 certification bottlenecks:Testing laboratory capacity constraints extend biogenic carbon verification timelines, delaying contract executions with brand-owners.
- Legacy PET converter requalification:Existing terephthalic acid plants require catalyst system modifications to handle bio-based paraxylene impurity profiles, demanding extended shutdown windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio Based Paraxylene Market |
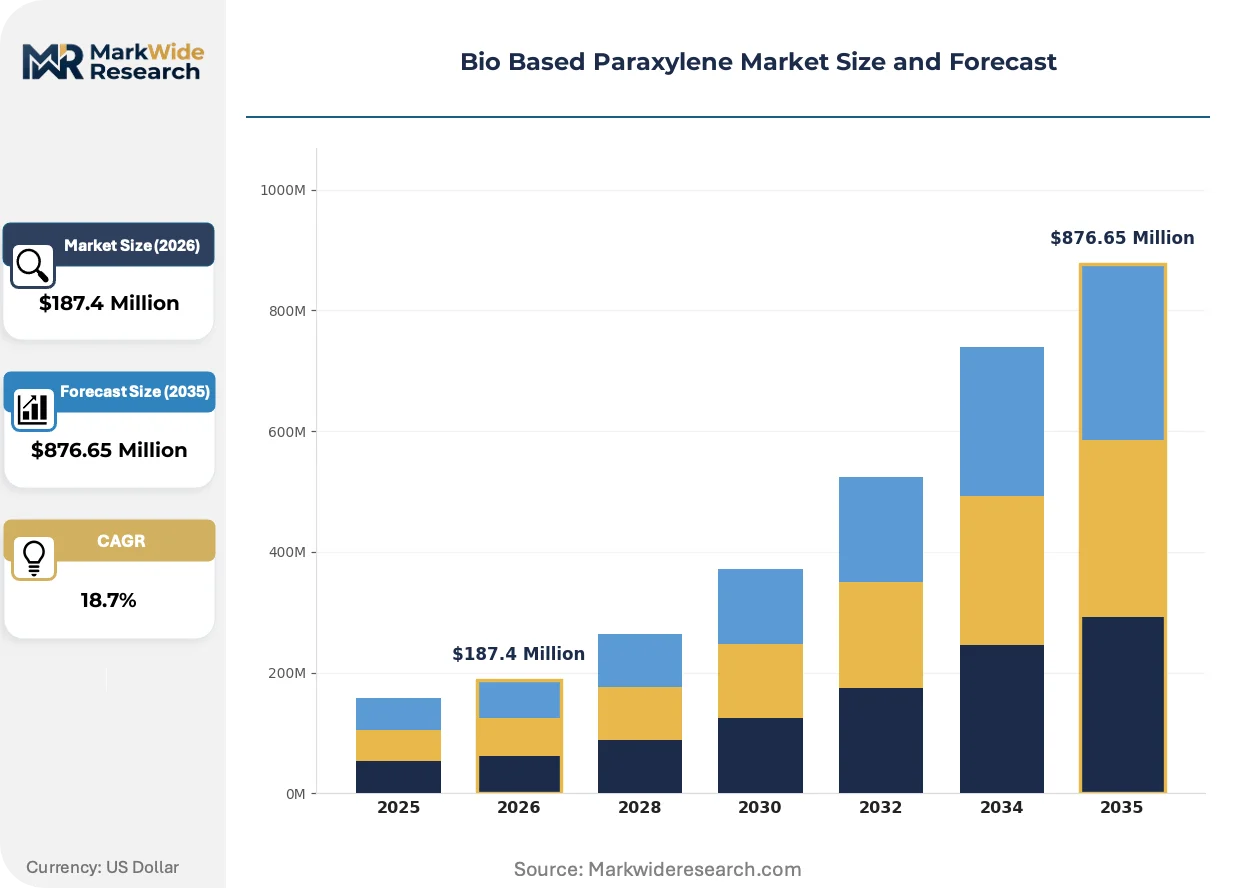
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purified Paraxylene, Para-Xylene, Dimethyl Terephthalate, Terephthalic Acid Application: Textiles, Packaging, Automotive, Coatings End User: Manufacturers, Retailers, Distributors, Exporters Technology: Chemical Recycling, Biological Processing, Catalytic Conversion, Fermentation |
| Companies Covered | Avantium, Anellotech, BASF, Toray Industries, Braskem, Origin Materials, Virent, Renmatix, Lanzatech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio Based Paraxylene Market Emerging Trajectories
Technology maturation and regulatory sequencing are compressing the commercialization timeline for bio-based aromatic chemicals, with certification infrastructure now pacing market access rather than process chemistry.
Catalytic pyrolysis of lignocellulosic sugars is expanding into commercial-scale paraxylene production through fixed-bed reactor configurations optimized for C8 aromatic selectivity. Packaging converters in Germany and the Netherlands are commissioning dedicated offtake agreements for certified bio-PET resin. This platform is expanding into automotive supply chains as OEMs integrate sustainability metrics into tier-one supplier scorecards.
EU REACH substance classification updates are redefining fossil-based aromatic chemicals as substances of very high concern for certain textile applications. The regulatory consequence is a phased restriction on naphtha-derived paraxylene in consumer-facing polyester products. German textile producers are responding by accelerating backward integration into bio-based feedstock sourcing.
Brand-owner sustainability scorecards now weight biogenic carbon content above recycled content for premium packaging tiers. Direct contracting between beverage companies and bio-paraxylene producers is displacing merchant market purchases through traditional polyester resin distributors. This pattern is most visible in Northern Europe, where deposit-return systems and extended producer responsibility schemes align financial incentives across the value chain.
Bio Based Paraxylene Market Segmentation
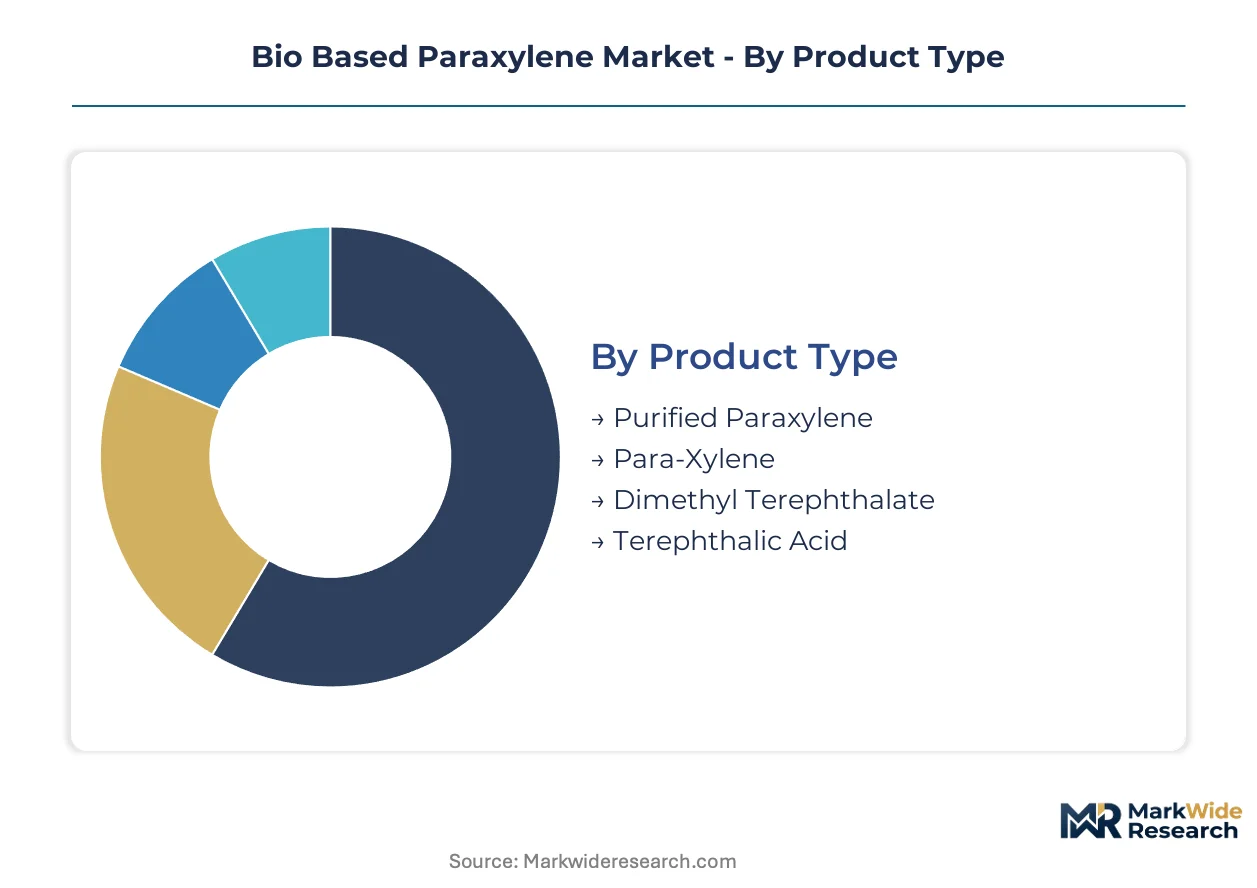
Bio based paraxylene segmentation reveals how certification requirements fragment procurement strategies across the value chain. Product purity grades, application specifications, and technology readiness levels each impose distinct regulatory burdens that shape supplier selection and contract structures.
Product Type:
FDA food-contact approvals and EU REACH substance classifications create divergent certification timelines across product grades, with polymer-grade materials facing the most stringent biogenic carbon verification requirements.
- Purified Paraxylene:Achieves polymer-grade purity above 99.7 weight percent through catalytic conversion of lignocellulosic sugars. Beverage packaging converters in Germany and the Netherlands prioritize this grade for PET bottle resin, driven by EU Green Deal packaging mandates requiring ASTM D6866 certification.
- Terephthalic Acid:Synthesized directly from bio-paraxylene oxidation, this intermediate bypasses traditional naphtha-cracking routes. Automotive OEMs in Germany specify this grade for interior textile applications, pulling volume through Rhine corridor chemical complexes as recycled content mandates tighten.
- Para-Xylene:Technical-grade material suitable for non-food industrial applications.
- Dimethyl Terephthalate:Esterification intermediate used in specialty polyester formulations.
Leading the category by volume: Purified Paraxylene. Growing fastest: Terephthalic Acid.
Application:
Margin structures diverge sharply across end-uses, with brand-owner sustainability premiums concentrated in consumer-facing segments while industrial applications compete on cost parity with fossil-derived alternatives.
- Packaging:Food-grade PET bottles command the deepest margin pools as Coca-Cola, PepsiCo, and Danone execute direct offtake agreements with bio-paraxylene producers. EU deposit-return systems and extended producer responsibility schemes align financial incentives across Northern European value chains, accelerating procurement shifts.
- Automotive:Interior textiles represent the steepest expansion trajectory as BMW, Mercedes-Benz, and Volkswagen integrate biogenic polyester into seat fabrics and headliners. German tier-one suppliers now face sustainability scorecard requirements that weight bio-derived content above recycled alternatives.
- Textiles:Polyester fiber applications for apparel and home furnishings.
- Coatings:Industrial polyester resin formulations for protective and decorative applications.
Highest margin capture: Packaging. Steepest volume acceleration: Automotive.
End User:
Procurement sophistication varies dramatically across buyer types, with integrated manufacturers leveraging backward control while merchant distributors struggle to aggregate fragmented converter demand.
- Manufacturers:Integrated polyester producers like Toray Industries and Indorama Ventures execute long-term supply contracts directly with bio-paraxylene technology developers. These stakeholders control catalyst system specifications and impurity tolerance thresholds that determine commercial acceptance of bio-derived feedstocks.
- Distributors:Merchant resin traders face compressed margins as brand-owners disintermediate traditional supply chains through direct producer contracting, particularly visible in Northern European beverage packaging.
- Retailers:Private-label apparel and housewares brands with sustainability commitments.
- Exporters:Trading houses managing cross-border arbitrage of certified bio-PET resin.
Deepest contract sophistication: Manufacturers. Most vulnerable to disintermediation: Distributors.
Technology:
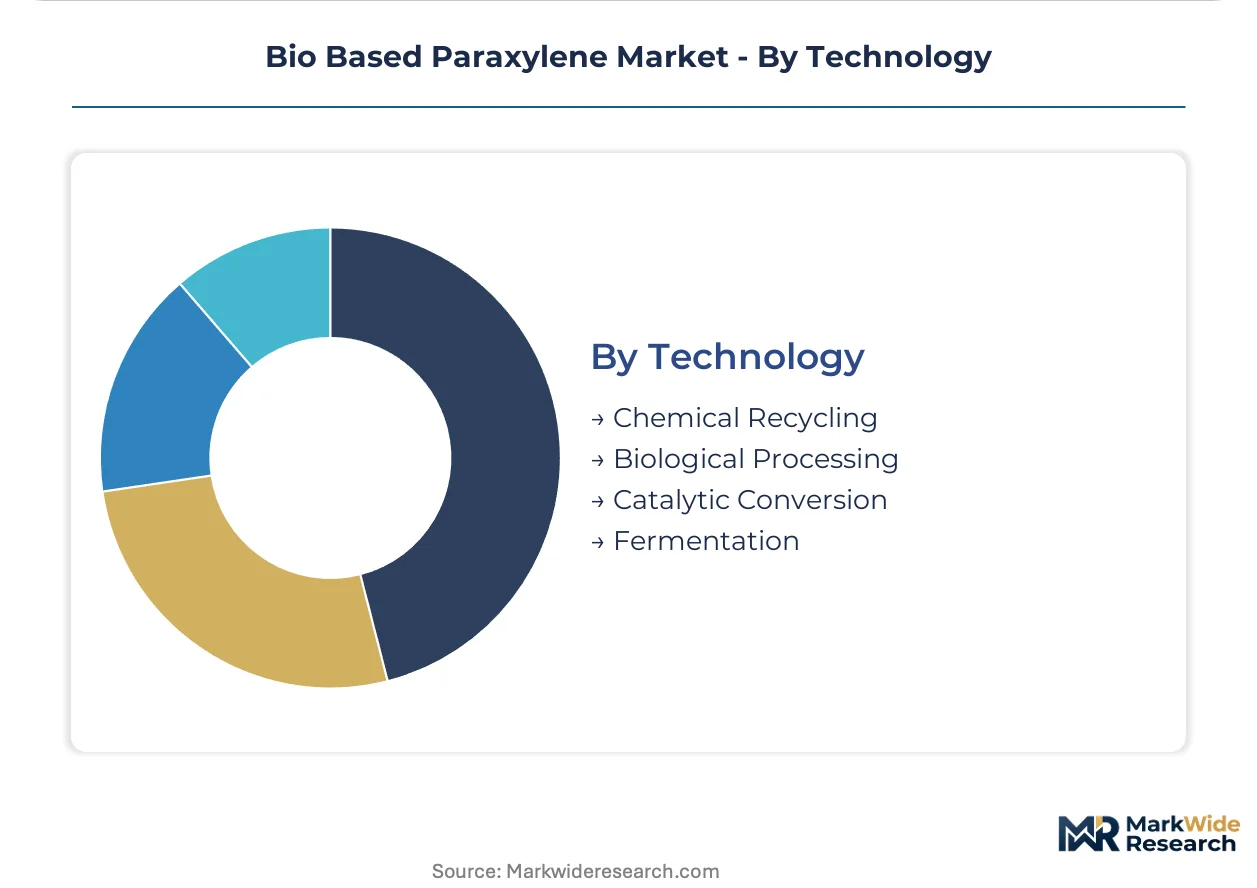
Capital intensity and yield profiles separate commercially scaled pathways from venture-stage alternatives, with catalytic conversion achieving polymer-grade specifications while fermentation remains trapped in pilot validation.
- Catalytic Conversion:Fixed-bed reactor configurations optimized for C8 aromatic selectivity dominate commercial scale-up. BASF's Ludwigshafen complex and Origin Materials' Sacramento facility deploy sugar-to-paraxylene pathways that match naphtha-cracking purity specifications, enabling drop-in replacement at existing terephthalic acid plants.
- Fermentation:Microbial selectivity for para-xylene remains below commercial thresholds despite venture capital backing. Pre-scale validation projects in the Netherlands and California face extended timelines as metabolic engineering advances lag catalytic chemistry maturation.
- Chemical Recycling:Pyrolysis-based recovery of paraxylene from waste PET streams.
- Biological Processing:Enzymatic pretreatment of woody biomass for downstream conversion.
Commercial readiness leader: Catalytic Conversion. Longest development runway: Fermentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine chemical corridor's special economic zones concentrate European bio-based paraxylene capacity through tax-advantaged processing sites. German automotive OEMs and Dutch packaging converters anchor demand clusters along this corridor.
Germany
Automotive interior mandates from BMW, Mercedes-Benz, and Volkswagen pull bio-derived polyester through Rhine corridor chemical complexes. EU REACH substance classifications restrict fossil-based aromatic chemicals in consumer-facing textiles. BASF's Ludwigshafen complex anchors catalytic conversion scale-up for polymer-grade paraxylene production.
Netherlands
Packaging converters commission dedicated offtake agreements for certified bio-PET resin ahead of EU Green Deal packaging mandates. ECHA enforcement of aromatic substance classifications accelerates brand-owner procurement shifts. Rotterdam-Antwerp port infrastructure clusters feedstock import and resin export logistics for Northern European beverage markets.
United States
FDA food-contact approval timelines lag EU certification by 18-24 months, creating first-mover windows for biogenic PET in carbonated soft drinks. EPA renewable fuel standards shape biogenic carbon verification requirements for domestic producers. Origin Materials' Sacramento facility represents the leading catalytic conversion scale-up outside European chemical corridors.
Japan
METI carbon neutrality roadmaps for vehicle manufacturing accelerate OEM sourcing of bio-derived interior materials. Toray Industries leverages its integrated fiber-to-resin platform to anchor supply relationships with domestic polyester makers. Nagoya and Osaka industrial zones concentrate textile processing capacity for automotive tier-one suppliers.
China
Dual carbon goals and national plastic restriction policies redirect state-owned chemical enterprises toward bio-based feedstock trials. NMPA food-contact regulations govern import approval timelines for foreign bio-PET resin. Yangtze River Delta chemical parks host pilot fermentation projects for para-xylene microbial selectivity advancement.
Bio Based Paraxylene Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical incumbents controlling catalytic conversion scale-up while venture-backed biotech ventures pursue fermentation pathway validation. Market structure concentrates around three strategic archetypes: diversified chemical conglomerates with existing aromatic infrastructure, dedicated bio-based technology developers with captive feedstock processing, and pulp-and-paper industry crossovers leveraging lignocellulosic preprocessing capabilities. Capacity expansion and strategic partnerships dominate competitive moves, with producers securing long-term offtake agreements ahead of ASTM D6866 certification completion.
Among diversified chemical conglomerates, BASF and Toray Industries exemplify scale-driven archetypes with integrated fiber-to-resin platforms. BASF occupies a position within the catalytic conversion tier through its Ludwigshafen complex operations. Toray Industries anchors supply relationships with Asian polyester makers. Origin Materials represents the dedicated bio-based technology developer archetype, sitting within the woody biomass feedstock processing tier against petrochemical incumbents.
| Leading Market Players |
|---|
| Avantium |
| Anellotech |
| BASF |
| Toray Industries |
| Braskem |
| Origin Materials |
| Virent |
| Renmatix |
| Lanzatech |
| Others |
Supply Flow & Price Mechanics
EU REACH aromatic substance classifications are compressing procurement timelines for ASTM D6866-certified feedstocks, forcing converters to accept premium pricing for guaranteed biogenic carbon verification while suppliers struggle to expand catalytic conversion capacity fast enough to meet contracted volumes.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as German automotive OEMs and Dutch packaging converters compete for limited polymer-grade paraxylene output. Three-tier pricing structure across premium certified, standard merchant, and economy spot tiers reflects ASTM D6866 verification status and volume commitment length. Pricing pressure stems from woody biomass cost volatility against naphtha benchmarks, squeezing margin stability for catalytic conversion operators. Merchant distributors show highest price sensitivity as brand-owners disintermediate traditional supply chains through direct producer contracting.
Supply Chain Analysis
Freight costs from Rotterdam-Antwerp port infrastructure to Rhine corridor chemical complexes add meaningful delivered cost premiums for bio-PET resin. Supply concentrates in Germany, the Netherlands, and the United States where catalytic conversion capacity clusters at pilot and demonstration scale. Feedstock dependencies on woody biomass, agricultural residues, and lignocellulosic sugars from pulp and paper industry crossovers create harvest-cycle price exposure. Single-source vulnerability runs through BASF's Ludwigshafen complex and Origin Materials' Sacramento facility for polymer-grade output. Distribution runs through direct long-term offtake agreements displacing traditional merchant resin channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EU REACH substance classifications erect barrier-to-entry moats around ASTM D6866-certified producers, marginalizing fossil-based paraxylene incumbents unable to requalify supply chains.
For Market Incumbents: Deepen backward integration into woody biomass preprocessing to secure feedstock cost parity against naphtha volatility. Lock in multi-year offtake agreements with German automotive OEMs before fermentation pathways achieve commercial scale. The threat of venture-backed biotech ventures achieving microbial selectivity breakthroughs demands accelerated catalytic conversion capacity expansion at existing Rhine corridor facilities. For New Entrants and Emerging Players: EU Green Deal packaging mandates in the Netherlands and Germany open a window for dedicated bio-PET resin production serving Coca-Cola, PepsiCo, and Danone direct procurement programs. Target underpenetrated US beverage packaging where FDA food-contact approval timelines lag EU certification. A go-to-market angle anchored in ASTM D6866 certification completion ahead of contract execution distinguishes viable entrants from pilot-stage competitors. For Investors and Strategic Acquirers: The window for entry favors pulp-and-paper industry crossovers with captive lignocellulosic preprocessing infrastructure and existing relationships with woody biomass suppliers. Long-term viability hinges on technology convergence between catalytic conversion scale-up and fermentation pathway maturation. The signal to watch is METI carbon neutrality roadmap implementation accelerating Japanese automotive OEM sourcing commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Processing | Origin Materials and pulp industry crossovers lower biomass cost exposure through captive supply chains. |
| Long-term Supply Agreement | Toray Industries anchors Asian polyester maker relationships through integrated fiber-to-resin platform commitments. |
| Capacity Expansion | BASF's Ludwigshafen complex scale-up addresses polymer-grade paraxylene bottlenecks for Rhine corridor converters. |
| Green Certification Program | ASTM D6866 biogenic carbon verification enables EU Green Deal packaging mandate compliance for brand-owners. |
| Joint Venture | Dutch packaging converters partner with catalytic conversion developers to secure dedicated bio-PET resin offtake. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with catalytic conversion plant managers, polyester procurement leads at automotive OEMs, beverage packaging converters, distribution channel partners, and ECHA regulatory affairs specialists combined with secondary validation from EU REACH substance classification databases, SEC 10-K filings, and Cefic chemical industry reports. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates across the analysis window.
Data-stream reconciliation merged production capacity disclosures, import-export flows, and end-use consumption patterns into a unified analytical framework. Segmentation dimensions modeled include product purity grade, application specification, technology readiness level, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from weighted average growth trajectories across these dimensions, with specific inputs from EU Green Deal packaging waste directive implementation timelines and METI carbon neutrality roadmap milestones.
The model assumes a particular technology adoption path; alternative pathways for fermentation-based para-xylene production would alter the outlook if microbial selectivity achieves commercial thresholds faster than projected. Forecasts reflect assumptions about ASTM D6866 certification laboratory capacity expansion and ECHA enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ethylene Dichloride Market
Bulk Chemicals
Europe Carbon Black Market
Bulk Chemicals
Asia-Pacific Solid Sulfur Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
Heavy Alkyl Benzenes Market
Bulk Chemicals
Ferric Sulphate and Polyferric Sulphate Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Copper Sulphate Market
Bulk Chemicals
Ammonium Dichromate Market
Bulk Chemicals
Mexico Calcium Carbonate Market
Bulk Chemicals
Battery Grade Lithium Chloride Market
Bulk Chemicals
Cresylic Acid Market
Bulk Chemicals
Global Linear Alkyl Benzene Market
Bulk Chemicals
Sheet Molding and Bulk Molding Compounds Market
Bulk Chemicals
Triammonium Citrate Market