
 UV-Based Nanoimprint Lithography (UV-NIL) System Market | 2026-2036
UV-Based Nanoimprint Lithography (UV-NIL) System Market Size, Share, and Industry Trends Forecast 2026-2036
UV-Based Nanoimprint Lithography (UV-NIL) System Market Insights
Photonics end-use is decoupling from traditional microelectronics dominance as AR waveguide and optical interconnect applications scale. EV Group leverages its Austrian headquarters to sustain European research institute relationships. Canon Inc. anchors Asian display panel supply chains with roll-to-roll UV-NIL platforms. SUSS MicroTec differentiates through hybrid stamp architectures serving both semiconductor and biomedical lithography needs.
UV-Based Nanoimprint Lithography (UV-NIL) Systems employ photocurable resins and transparent quartz molds to replicate nanoscale features through ultraviolet exposure at sub-200nm wavelengths, achieving sub-10nm resolution for semiconductor, photonic, and biological patterning applications. Hard stamp configurations lead current revenue pools due to dimensional stability in high-volume semiconductor manufacturing, while roll-to-roll technology captures the fastest growth trajectory as display fabricators adopt continuous processing for flexible substrate patterning. Maskless imprint systems occupy premium margin tiers in R&D environments where photomask costs would otherwise dominate prototyping economics.
FDA device manufacturing guidelines and ISO 10993 biocompatibility standards constrain biomedical UV-NIL system configurations, particularly for diagnostic sensor production. EPA hazardous air pollutant regulations and REACH substance restrictions jointly reshape photoresin formulation requirements across North American and European install bases. Semiconductor manufacturers must monitor evolving EU AI Act supply chain transparency mandates that could extend to lithography equipment provenance documentation.
Market Dynamics
Semiconductor manufacturers are compressing patterning cycles below 10nm resolution thresholds, forcing UV-NIL equipment vendors to align curing chemistry with solvent-free regulatory mandates while maintaining throughput parity with electron-beam alternatives.
Growth Catalysts
- Sub-10nm Logic Node Migration:Foundries in Taiwan and South Korea are qualifying UV-NIL for advanced memory stacking and logic gate patterning where optical lithography hits diffraction limits.
- REACH Solvent Restrictions:European ECHA enforcement is eliminating traditional thermal imprint chemistries, redirecting capital toward photocurable resin platforms that eliminate volatile organic compound emissions.
- AR Waveguide Fabrication:Photonics manufacturers are adopting roll-to-roll UV-NIL for nanostructured optical element replication at wafer-scale dimensions.
Market Restraints
- Quartz Master Stamp Cost Concentration:Single-crystal quartz substrate supply concentrates among Japanese and German specialty glass manufacturers, creating input cost volatility for high-volume semiconductor deployments.
- Photoresin Formulation Lock-In:Proprietary oligomer chemistry from dominant material suppliers creates switching friction and limits second-source qualification timelines.
- Electron-Beam Direct Write Substitution:Maskless e-beam systems are capturing R&D prototyping volumes where photomask amortization would otherwise favor UV-NIL economics.
Strategic Opportunities
- Biomedical Sensor Patterning:FDA 21 CFR Part 820 quality system requirements for diagnostic device manufacturing are creating certified UV-NIL system demand for microfluidic chip production.
- Flexible Display Backplane Integration:South Korean panel manufacturers are piloting continuous roll-to-roll imprinting for OLED thin-film transistor patterning on polyimide substrates.
- EU AI Act Supply Chain Transparency:Emerging provenance documentation mandates for high-risk AI hardware components could extend to lithography equipment traceability systems.
Industry Challenges
- Multi-Physics Simulation Talent Scarcity:UV-NIL process optimization requires simultaneous fluence modeling, resin rheology, and stamp deformation analysis that crosses traditional mechanical-optical-chemical engineering boundaries.
- ISO 10993 Biocompatibility Certification Timelines:Medical device manufacturers face 18-24 month validation cycles for imprinted diagnostic surfaces that must demonstrate cytotoxicity and sensitization compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV-Based Nanoimprint Lithography (UV-NIL) System Market |
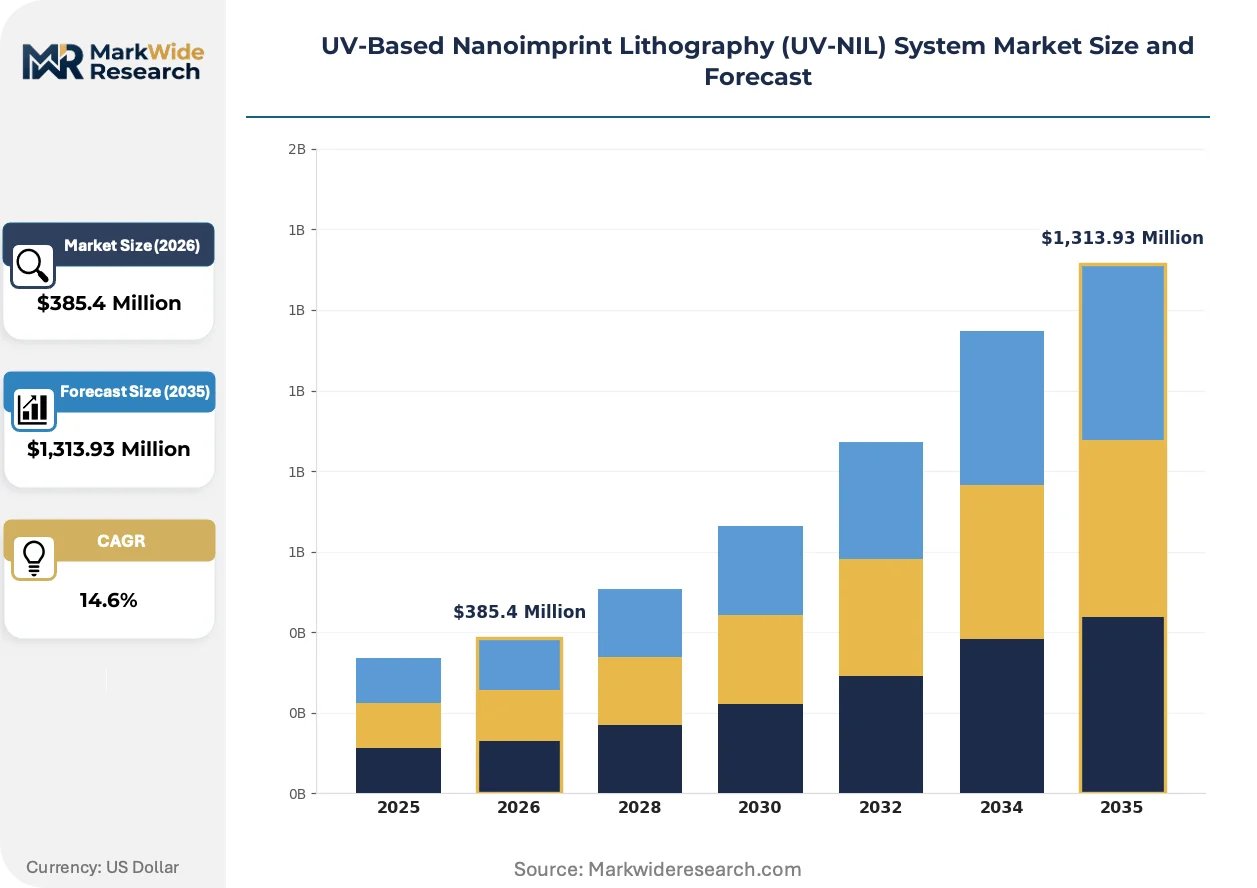
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,313.93 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Maskless Imprint, Hard Stamp, Soft Stamp, Hybrid Technology: UV-Curing, Thermal Imprinting, Standard NIL, Roll-to-Roll End User: Semiconductor Manufacturers, Display Fabricators, Photonics, Biomedical Companies Application: Microelectronics, Optoelectronics, Data Storage, Sensors |
| Companies Covered | EV Group, Canon Inc., SUSS MicroTec, Nanonex Corp., Obducat AB, NIL Technology, AMO GmbH, Stensborg A/S, Morphotonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV-Based Nanoimprint Lithography (UV-NIL) System Market Trends and Innovations
Photocurable resin chemistry is converging with precision mechanical engineering to enable patterning applications beyond traditional semiconductor confines, reshaping equipment architecture and service delivery models simultaneously.
Hybrid stamp architectures combining rigid quartz backing with flexible surface layers are electrifying biomedical lithography applications. Diagnostic sensor manufacturers are adopting these configurations for microfluidic channel replication at sub-micron precision. The technology is compressing prototyping-to-production transition timelines from months to weeks for point-of-care device developers.
REACH substance restrictions and EPA hazardous air pollutant regulations are jointly eliminating thermal imprint process chemistries from European and North American install bases. Equipment vendors are reconfiguring curing subsystems to accommodate 100% solids photocurable formulations. Biomedical and display panel segments are most affected, with fabs accelerating resin qualification programs to maintain production licenses.
Service unbundling is fragmenting traditional equipment procurement models. Semiconductor foundries are separating hardware acquisition from process recipe development, engaging specialized engineering firms for application-specific resin-stamp-fluence optimization. Taiwan and South Korea display the most advanced procurement sophistication, with tier-one manufacturers negotiating outcome-based performance guarantees separate from capital equipment contracts.
UV-Based Nanoimprint Lithography (UV-NIL) System Market Segmentation
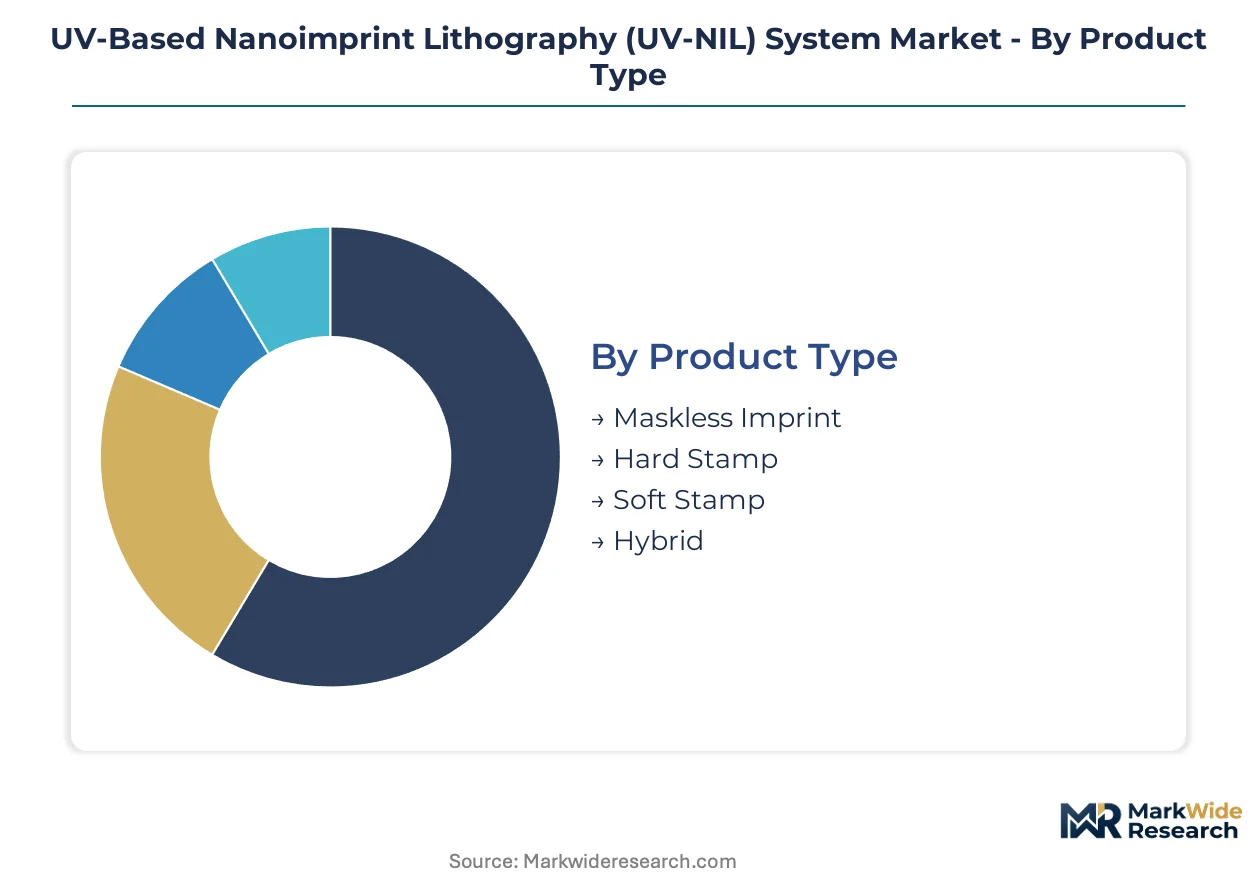
UV-NIL system segmentation reveals divergent equipment architectures optimized for semiconductor volume manufacturing versus emerging photonics and biomedical applications. Each dimension—product configuration, curing technology, end-user requirements, and application specificity—creates distinct procurement criteria and margin structures.
Product Type:
Hard stamp configurations command premium pricing through dimensional stability, while maskless systems target R&D environments where photomask economics would dominate prototyping cycles.
- Hard Stamp:Single-crystal quartz masters bonded to rigid substrates deliver sub-10nm replication fidelity for logic node patterning. Taiwan foundries and South Korean memory manufacturers concentrate procurement here, driven by thermal cycling durability requirements in high-volume semiconductor fabrication.
- Maskless Imprint:Direct-write patterning eliminates master stamp fabrication for low-volume prototyping and custom photonic structures. Research institutes in Austria and Germany favor this configuration where photomask amortization would otherwise dominate economics for experimental designs.
- Soft Stamp:Elastomeric materials enable conformal contact over substrate topography for non-planar surface patterning.
- Hybrid:Rigid backing layers combined with flexible surface films compress biomedical prototyping timelines for diagnostic sensor production.
Today's leader: Hard Stamp. Tomorrow's challenger: Hybrid.
Technology:
Roll-to-roll processing is gaining share fastest in display manufacturing, while UV-curing dominates semiconductor installations through regulatory alignment with solvent-free mandates.
- Roll-to-Roll:Continuous web processing enables wafer-scale optical element replication on flexible polyimide substrates. South Korean OLED panel manufacturers pilot this technology for thin-film transistor backplane patterning, driven by substrate handling efficiency in mass production environments.
- UV-Curing:Photocurable resin platforms at sub-200nm wavelengths achieve sub-10nm resolution without thermal cycling. REACH solvent restrictions across European install bases redirect capital toward these 100% solids formulations that eliminate volatile organic compound emissions.
- Thermal Imprinting:Heat-activated polymer flow remains constrained by EPA hazardous air pollutant regulations in North American facilities.
- Standard NIL:Conventional contact imprinting serves legacy semiconductor process nodes and research applications.
Roll-to-Roll climbs the fastest in display fabrication; UV-Curing holds semiconductor dominance through regulatory compliance.
End User:
Semiconductor manufacturers anchor equipment revenue through advanced logic node migration, while biomedical companies generate premium margins through extended certification requirements.
- Semiconductor Manufacturers:Foundries in Taiwan's Hsinchu Science Park and South Korea's Giheung complex qualify UV-NIL for memory stacking and gate patterning where optical lithography encounters diffraction limits. Sub-10nm resolution requirements drive capital deployment despite electron-beam substitution threats in R&D volumes.
- Biomedical Companies:FDA 21 CFR Part 820 quality system compliance and ISO 10993 biocompatibility validation create 18-24 month certification timelines for diagnostic sensor production. This extended qualification cycle sustains premium pricing for certified system configurations.
- Display Fabricators:Continuous processing adoption for flexible substrate patterning concentrates procurement in East Asian manufacturing clusters.
- Photonics:AR waveguide and optical interconnect applications are decoupling from traditional microelectronics equipment specifications.
Semiconductor Manufacturers currently absorb the majority of system shipments; Biomedical Companies command the steepest price premiums per installation.
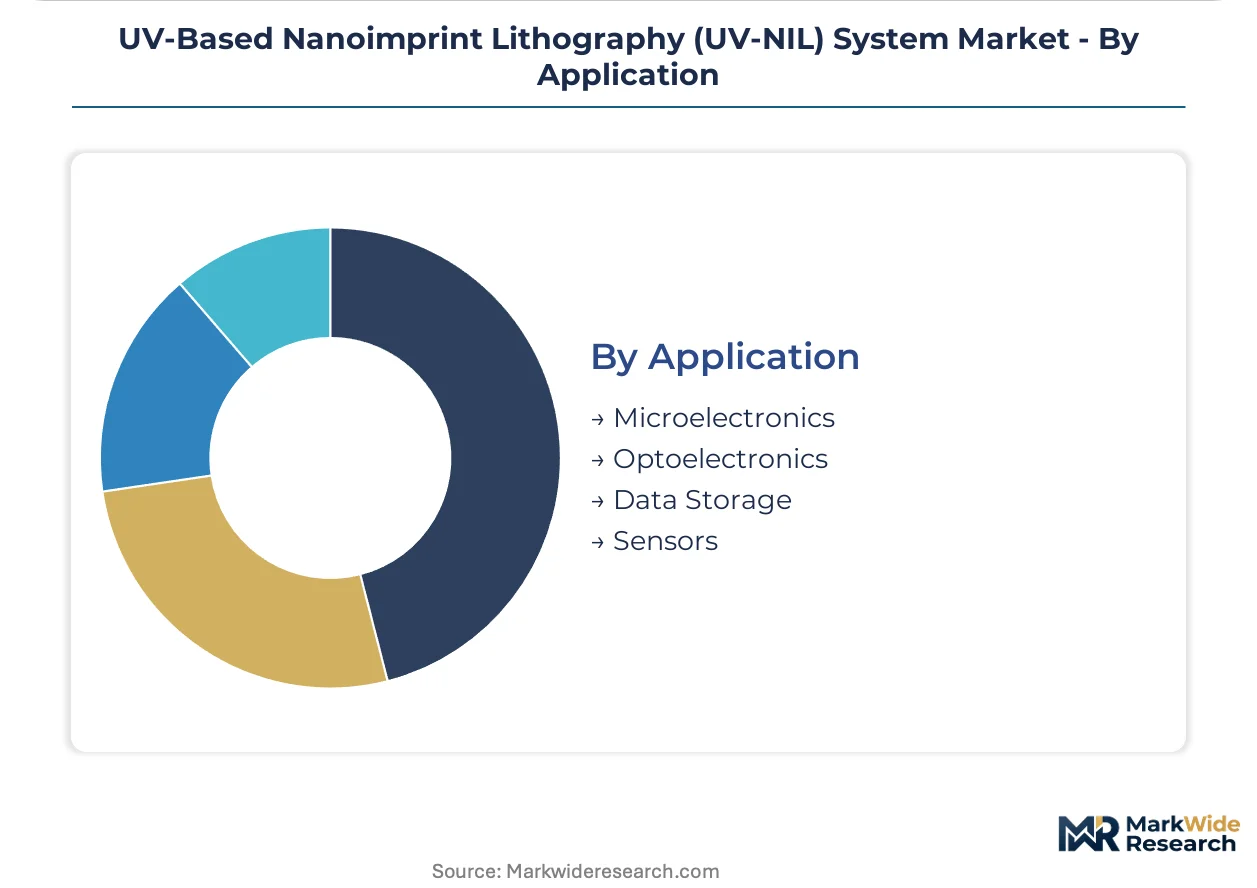
Application:
Microelectronics applications concentrate volume demand, while sensor patterning creates diversification opportunities across regulatory-constrained medical device manufacturing.
- Microelectronics:Logic and memory device fabrication at sub-10nm nodes requires hard stamp UV-NIL systems with quartz master durability for thermal cycling endurance. Taiwan and South Korean foundries dominate this application segment through advanced node migration timelines.
- Sensors:Microfluidic diagnostic chip production combines biomedical lithography requirements with semiconductor-derived precision. FDA device manufacturing guidelines and ISO 10993 standards constrain equipment configurations for point-of-care device developers.
- Optoelectronics:Nanostructured optical element replication serves AR waveguide and optical interconnect scaling.
- Data Storage:Bit-patterned media and advanced recording head fabrication maintain steady equipment demand.
Microelectronics sustains current revenue concentration; Sensors expand the addressable market through regulatory-certified biomedical pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redistributing UV-NIL equipment procurement toward jurisdictions with streamlined chemical compliance frameworks, compressing deployment timelines for fabs facing REACH and EPA solvent restrictions.
Taiwan
Foundries in Hsinchu Science Park are qualifying hard stamp UV-NIL systems for sub-10nm logic node migration where optical lithography encounters diffraction limits. The island's EPA-equivalent environmental regulator enforces volatile organic compound emission caps that favor photocurable resin platforms over thermal imprint chemistries. TSMC and UMC procurement teams concentrate equipment trials in Taichung's Central Taiwan Science Park, accelerating resin-stamp-fluence optimization cycles.
South Korea
Samsung Electronics and SK Hynix are deploying UV-NIL for advanced memory stacking applications, driven by 3D NAND layer multiplication requirements. MFDS chemical substance notifications and Ministry of Environment hazardous material permits constrain resin formulation imports, creating localization pressure on oligomer suppliers. Giheung semiconductor complex hosts the densest concentration of pilot roll-to-roll systems for OLED thin-film transistor backplane patterning on polyimide substrates.
United States
Intel and GlobalFoundries are evaluating maskless UV-NIL configurations for R&D prototyping volumes where photomask amortization economics favor direct-write alternatives. EPA hazardous air pollutant regulations under the Clean Air Act are eliminating thermal imprint process chemistries from domestic install bases, redirecting capital toward 100% solids photocurable formulations. Albany Nanotech Complex in New York and the University of Texas at Austin's Texas Nanofab serve as primary qualification sites for FDA 21 CFR Part 820 compliant biomedical lithography systems.
Germany
Fraunhofer Institute networks and AMO GmbH anchor European research institute demand for maskless imprint systems in experimental photonic structure development. ECHA REACH substance restrictions and the EU Green Deal's chemical sustainability targets are jointly reshaping photoresin formulation requirements, eliminating solvent-based thermal processes from Bavarian and Saxon manufacturing clusters. Dresden's Silicon Saxony consortium coordinates cross-border qualification programs with Austrian and Czech partners for hybrid stamp architectures serving biomedical sensor applications.
Japan
Tokyo Electron and Shin-Etsu Chemical supply chain relationships concentrate quartz master stamp substrate production among domestic specialty glass manufacturers, creating input cost leverage for semiconductor equipment vendors. METI's Green Transformation initiative and carbon neutrality targets for 2050 are accelerating fab transitions to low-energy UV-curing processes. Tsukuba and Kansai Science City research parks host the highest density of ISO 10993 biocompatibility validation programs for diagnostic sensor lithography.
UV-Based Nanoimprint Lithography (UV-NIL) System Market Competitive Landscape
Technology licensing dominates the current landscape as equipment vendors seek to overcome photoresin formulation lock-in and quartz master stamp supply concentration. The vendor base stratifies across three tiers: integrated lithography platform providers with captive resin partnerships, specialized imprint equipment pure-plays, and roll-to-roll system architects serving display manufacturing. Strategic archetypes include semiconductor-focused hard stamp specialists, biomedical hybrid stamp innovators, and continuous processing roll-to-roll developers. M&A activity and geographic expansion into East Asian manufacturing clusters represent the dominant competitive vectors.
Within the integrated platform tier, EV Group exemplifies European research institute relationship anchoring through its Austrian headquarters structure. Canon Inc. occupies a position reflecting Asian display panel supply chain penetration with roll-to-roll platform specialization. SUSS MicroTec sits within the hybrid architecture segment, representing dual-use equipment configurations that bridge semiconductor and biomedical lithography requirements.
| Leading Market Players |
|---|
| EV Group |
| Canon Inc. |
| SUSS MicroTec |
| Nanonex Corp. |
| Obducat AB |
| NIL Technology |
| AMO GmbH |
| Stensborg A/S |
| Morphotonics |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap equipment specialists in Germany and Austria anchor quartz master stamp production, translating captive technical know-how into pricing discipline that resists commoditization despite Asian volume competition. Their long-tenured relationships with Fraunhofer research networks and AMO GmbH create switching costs that sustain premium positioning for hybrid stamp architectures serving biomedical certification requirements.
Pricing Analysis
Distributor margin absorption varies sharply across equipment tiers, with semiconductor hard stamp systems commanding direct-to-OEM pricing that eliminates intermediary layers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated biomedical configurations from R&D maskless systems and legacy thermal imprint platforms. Price differentiation hinges on ISO 10993 biocompatibility certification grade and after-sales service bundling that extends resin-stamp optimization support. Cost compression in standard-tier semiconductor equipment is intensifying because South Korean and Taiwanese foundries negotiate outcome-based performance guarantees separate from capital contracts. Display fabricators exhibit highest price sensitivity due to roll-to-roll platform commoditization, while biomedical companies show least sensitivity given 18-24 month validation cycle lock-in.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers and German oligomer specialists, creating formulation dependencies that equipment vendors cannot easily second-source. Quartz master stamp substrate production concentrates in Japan, Germany, and select Austrian glassworks, with single-crystal ingot supply tethered to Shin-Etsu Chemical and Heraeus Holdings relationships. Photocurable resin chemistry, precision mechanical components, and transparent mold blanks constitute the critical input trinity. Single-source vulnerability in quartz substrate qualification timelines threatens high-volume semiconductor deployments where thermal cycling durability requirements preclude rapid supplier switching. Distribution runs through direct OEM sales teams for tier-one foundries, with specialized engineering firms unbundling process recipe development from hardware procurement in Taiwan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in UV-NIL equipment favor vendors mastering resin-stamp-fluence optimization as a service layer, with premium-tier shift toward certified biomedical configurations outpacing semiconductor commoditization pressures.
For Market Incumbents: Cement quartz master stamp supply control through backward integration into Japanese and German specialty glass manufacturers, or through exclusive long-term offtake agreements that lock in thermal cycling-grade substrate access. Deepen captive resin partnerships to counter formulation lock-in threats from oligomer suppliers, particularly for 100% solids photocurable platforms required by REACH and EPA mandates. Electron-beam direct write substitution in R&D prototyping volumes demands defensive certification investment in maskless system performance guarantees. For New Entrants and Emerging Players: Roll-to-roll continuous processing platforms for flexible OLED backplane patterning offer the most penetrable white-space target, as South Korean panel manufacturers pilot production-scale deployment without incumbent equipment lock-in. Biomedical sensor lithography presents secondary entry path through hybrid stamp architectures that compress FDA 21 CFR Part 820 validation timelines. Go-to-market angle should emphasize outcome-based process recipe development contracts separate from capital equipment sales, mirroring procurement sophistication emerging in Taiwan and South Korea. For Investors and Strategic Acquirers: Valuations sit cheapest among European research institute equipment pure-plays with undermonetized biomedical certification capabilities. Long-term viability over the coming decade hinges on regulatory compliance breadth spanning REACH, EPA, and emerging EU AI Act supply chain transparency mandates. Acquisition target archetype: hybrid stamp specialists with existing ISO 10993 validation programs and Fraunhofer/AMO relationship anchors. Signal to watch: ECHA enforcement intensity on solvent-based thermal imprint chemistries accelerating photocurable platform transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Resin Formulation Partnership | Captive oligomer supply secures REACH-compliant 100% solids platforms for European install bases. |
| Biomedical Certification Investment | FDA 21 CFR Part 820 compliance opens diagnostic sensor lithography premium pricing tiers. |
| Roll-to-Roll Platform Development | Continuous processing capability penetrates South Korean OLED thin-film transistor backplane demand. |
| Quartz Substrate Integration | Backward integration into Shin-Etsu or Heraeus supply chains mitigates master stamp cost volatility. |
| Service Unbundling Launch | Process recipe optimization contracts separate from hardware sales capture procurement sophistication in Taiwan. |
Research Methodology
Direct dialogue with semiconductor foundry procurement directors, biomedical device quality system managers, photonics R&D leads, and specialty chemical formulation engineers grounded qualitative intelligence, cross-referenced against SEC 10-K equipment disclosures, ECHA REACH substance registration databases, FDA 510(k) device filings, and Japan METI industrial statistics. Bottom-up and top-down triangulation validated segment-level assumptions through independent estimation paths.
Bottom-up modeling aggregated equipment shipment volumes by product configuration, curing technology, and end-user segment, while top-down analysis calibrated aggregate market scale against foundry capex disclosure patterns and display panel manufacturer equipment procurement trends. Segmentation dimensions spanned stamp architecture type, resin curing mechanism, application specificity across microelectronics and biomedical pathways, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating foundry node migration timelines and REACH chemical restriction phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA enforcement intensity on solvent restrictions, quartz substrate supply disruption events, and electron-beam direct write technology cost curves. Forecasts reflect documented assumptions regarding resin qualification timelines and stamp durability parameters. A small set of triggers—EU AI Act lithography equipment provenance mandates, MFDS chemical notification expansions, and METI carbon neutrality acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
Solar Module Production Equipment Market
Semiconductor Equipment
Asia-Pacific Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
I-Line Lithography Market
Semiconductor Equipment
Vacuum Spin Coaters Market
Semiconductor Equipment
Semiconductor Assembly Equipment Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market
Semiconductor Equipment
Electron Beam Lithography Machine Market
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Molecular Beam Epitaxy System Market
Semiconductor Equipment
Remote Plasma Source Market
Semiconductor Equipment
Global Semiconductor Etch Equipment Market
Semiconductor Equipment
Global Photoresist Market