
 Industrial Vacuum Evaporation Systems Market | 2026-2036
Industrial Vacuum Evaporation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Vacuum Evaporation Systems Market Outlook
German equipment fabricators is pivoting toward modular vacuum evaporation skids for pharmaceutical wastewater streams. GEA Group leverages its centrifuge-to-evaporator integration to anchor large-scale solvent recovery contracts across European chemical parks. Alfa Laval competes through plate evaporator specialization, sustaining margin pools in food processing concentration applications. SPX Flow controls niche positions in high-vacuum thin film systems for temperature-sensitive pharmaceutical actives.
Industrial vacuum evaporation systems operate by reducing boiling points through sub-atmospheric pressure, typically achieving evaporation temperatures between 35°C and 85°C depending on vacuum depth and heat transfer configuration. These systems separate solvents, concentrate solutions, or recover valuable materials from industrial process streams across wastewater treatment, chemical synthesis, and surface coating operations. Continuous systems dominate throughput-intensive installations where steady-state operation minimizes energy consumption per unit volume, while batch systems retain strong positions in multi-product pharmaceutical facilities requiring frequent changeover and validated cleaning protocols. Robotic systems represent the fastest-expanding category as semiconductor and electronics manufacturers automate wafer coating processes demanding precise vacuum control and minimal human intervention.
EPA effluent guidelines under the Clean Water Act shape equipment specifications for US-based chemical and pharmaceutical discharge points, while REACH registration requirements in Europe restrict solvent compositions that evaporation systems must process. ISO 14001 environmental management frameworks and EU Green Deal decarbonization targets are forcing upgrades from atmospheric to vacuum-based recovery technologies to cut thermal energy intensity. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as these compounds resist conventional evaporation and demand specialized vacuum distillation or hybrid separation approaches.
Market Dynamics
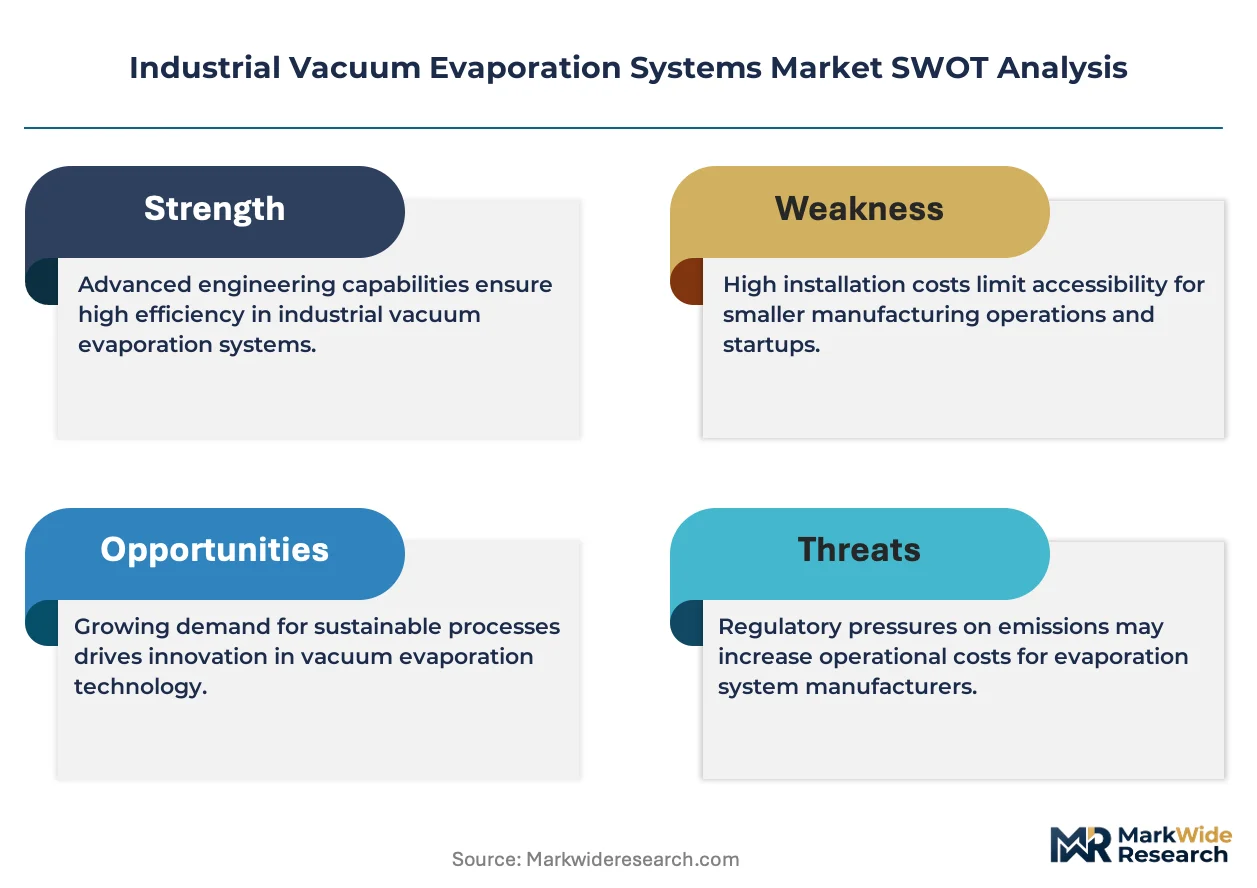
Modular vacuum evaporation skids are displacing conventional fixed installations across pharmaceutical wastewater treatment, driven by REACH compliance deadlines forcing rapid capacity expansion without civil construction timelines.
Growth Catalysts
- REACH effluent standards:European chemical manufacturers must upgrade solvent recovery infrastructure to meet tightening discharge limits, accelerating replacement cycles for atmospheric evaporators.
- Semiconductor wafer coating automation:Electronics manufacturers deploy robotic vacuum evaporation systems for precision thin-film deposition, demanding sub-atmospheric pressure control.
- ISO 14001 adoption:Food processing concentration facilities in Germany's chemical corridor prioritize energy-efficient plate evaporators to satisfy environmental management certification requirements.
Market Restraints
- Stainless steel price volatility:Vacuum chamber fabrication depends on nickel-alloy feedstock, exposing equipment fabricators to commodity swings.
- Specialized vacuum pump supply concentration:German and Japanese precision pump manufacturers control critical sub-system supply, creating bottleneck risk.
- Per- and polyfluoroalkyl substance processing limitations:Conventional evaporation fails on fluorinated compounds, forcing costly hybrid separation investments.
Strategic Opportunities
- India's pharmaceutical manufacturing expansion:CDSCO regulatory harmonization with ICH standards drives demand for validated batch evaporation systems in API production.
- EU Green Deal thermal efficiency mandates:Decarbonization targets subsidize vacuum-based solvent recovery retrofits, displacing atmospheric thermal processes.
- Thin-film evaporator-pharmaceutical centrifuge integration:Combined mechanical-thermal separation packages capture high-value active ingredient recovery contracts.
Industry Challenges
- ASME pressure vessel certification timelines:Vacuum system fabrication requires stamped code compliance, extending delivery schedules for custom designs.
- Legacy DCS integration complexity:Brownfield chemical plants struggle to interface new vacuum skids with existing distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Vacuum Evaporation Systems Market |
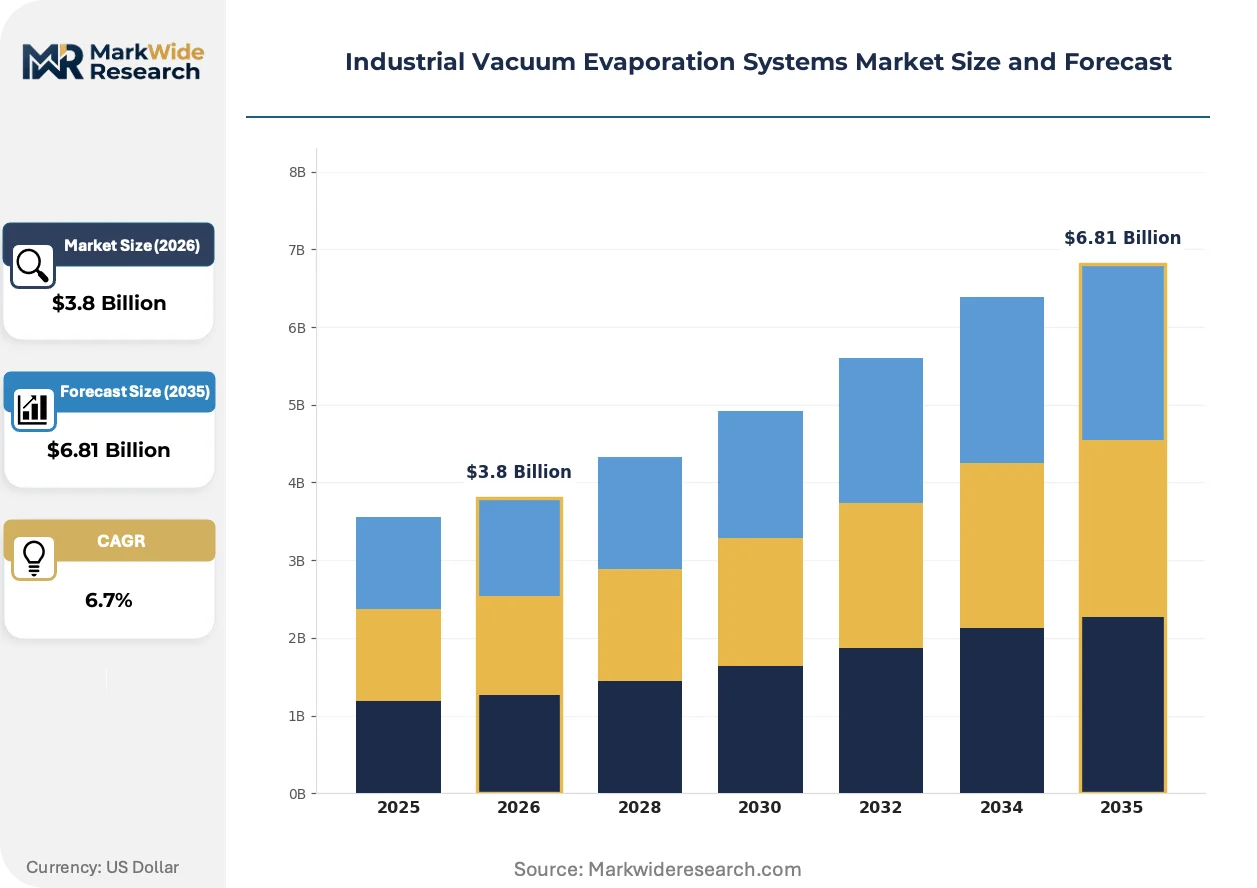
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Systems, Continuous Systems, Robotic Systems, Customized Solutions End User: Aerospace, Pharmaceuticals, Electronics, Food Processing Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Thin Film Deposition, Molecular Layer Deposition Application: Coating, Material Production, Surface Treatment, Solvent Recovery |
| Companies Covered | GEA Group, Veolia Water Technologies, Alfa Laval, SPX Flow, PRAB, Condorchem Envitech, BÜCHI Labortechnik AG, Sanshin Mfg. Co. Ltd., Eco-Techno SRL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Vacuum Evaporation Systems Market Strategic Shifts
Heat pump-assisted vacuum evaporation is compressing energy intensity benchmarks across wastewater treatment applications, while regulatory pressure on solvent emissions accelerates closed-loop recovery architectures.
Mechanical vapor recompression evaporators is overtaking multi-effect thermal systems in pharmaceutical wastewater concentration. These units recycle latent heat through compressor work rather than steam injection. Major API manufacturers in Germany and Switzerland deploy MVR systems for solvent recovery, cutting thermal energy input by half. Steam boiler infrastructure is shrinking as a result.
EPA effluent guidelines under the Clean Water Act are tightening permissible solvent discharge limits for US chemical manufacturing points. Pharmaceutical facilities must install vacuum-based recovery ahead of permit renewal cycles. Thin-film evaporator specifications dominate new installations where temperature-sensitive actives require sub-50°C processing.
Equipment-as-a-service contracts are displacing capital purchase models among mid-scale chemical processors. Leasing arrangements bundle maintenance and solvent recovery validation, transferring operational risk to fabricators. This shift concentrates most visibly in the Netherlands and Belgium, where chemical park operators prefer opex-aligned financing for multi-tenant wastewater infrastructure.
Industrial Vacuum Evaporation Systems Market Segmentation
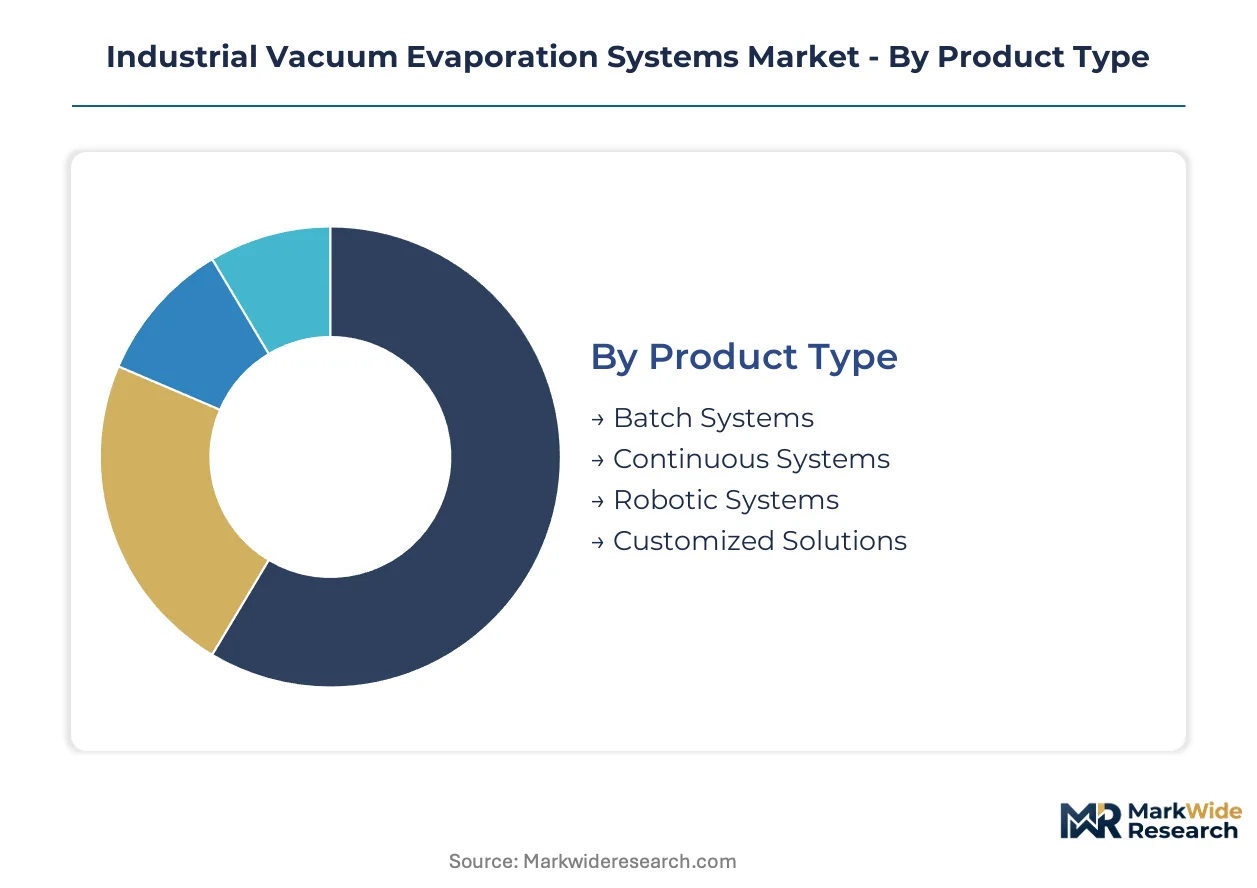
Equipment selection in vacuum evaporation hinges on thermal sensitivity of process streams, batch validation requirements, and automation depth for precision coating. Buyers prioritize energy recovery architecture and regulatory compliance pathways when specifying system configurations across pharmaceutical and electronics manufacturing.
Product Type:
Procurement patterns diverge sharply between throughput-maximizing chemical processors and validation-bound pharmaceutical facilities with frequent product changeover cycles.
- Continuous Systems:Steady-state thermal separation architectures minimize energy consumption per unit volume in high-throughput chemical synthesis and food concentration operations. Demand concentrates in Germany's Ludwigshafen chemical corridor where GEA Group anchors large-scale solvent recovery contracts through centrifuge-to-evaporator integration packages.
- Batch Systems:Intermittent processing configurations accommodate validated cleaning protocols and multi-product flexibility essential for active pharmaceutical ingredient manufacturing. CDSCO regulatory harmonization with ICH standards in India drives demand for these systems among contract API manufacturers expanding wastewater treatment capacity.
- Robotic Systems:Automated vacuum control platforms serve semiconductor wafer coating processes demanding precise pressure modulation and minimal human intervention.
- Customized Solutions:Engineered-to-order configurations address specialized feedstock compositions and hybrid separation requirements for per- and polyfluoroalkyl substance processing.
Volume sits with Continuous Systems in chemical processing corridors; growth tilts toward Robotic Systems as electronics manufacturers automate thin-film deposition workflows.
End User:
Margin pools vary by sector based on regulatory stringency, solvent recovery value, and equipment qualification complexity.
- Pharmaceuticals:Temperature-sensitive active ingredient processing demands sub-50°C thin-film evaporator specifications and ASME pressure vessel certification. REACH effluent standards and EPA Clean Water Act guidelines force replacement cycles for atmospheric evaporators across European and US manufacturing sites.
- Electronics:Precision coating applications for semiconductor wafers require sub-atmospheric pressure control and robotic handling systems. Equipment-as-a-service contracts concentrate in Netherlands and Belgium chemical parks where multi-tenant infrastructure operators prefer opex-aligned financing.
- Food Processing:Energy-efficient plate evaporator configurations dominate concentration applications as ISO 14001 certification requirements tighten thermal intensity benchmarks.
- Aerospace:Specialized surface treatment and coating operations utilize high-vacuum thin film systems for protective layer deposition on critical components.
Revenue concentrates in Pharmaceuticals due to validation premiums; Electronics is climbing the fastest on semiconductor fabrication expansion.
Technology:
Technology selection determines deposition uniformity, material purity thresholds, and compatibility with substrate thermal budgets.
- Physical Vapor Deposition:Solid-source material evaporation under vacuum produces high-purity thin films for electronics and aerospace coating applications. Demand concentrates in semiconductor manufacturing clusters where robotic vacuum evaporation systems automate wafer processing.
- Chemical Vapor Deposition:Gas-phase precursor reactions enable conformal coating deposition for complex geometries in electronics packaging and aerospace component protection.
- Thin Film Deposition:Controlled layer formation at reduced pressures serves temperature-sensitive pharmaceutical actives and precision electronics manufacturing.
- Molecular Layer Deposition:Sequential self-limiting surface reactions achieve angstrom-level thickness control for advanced semiconductor and optical coating applications.
Deployment breadth favors Physical Vapor Deposition; Molecular Layer Deposition is gaining share fastest on nanoscale precision requirements.
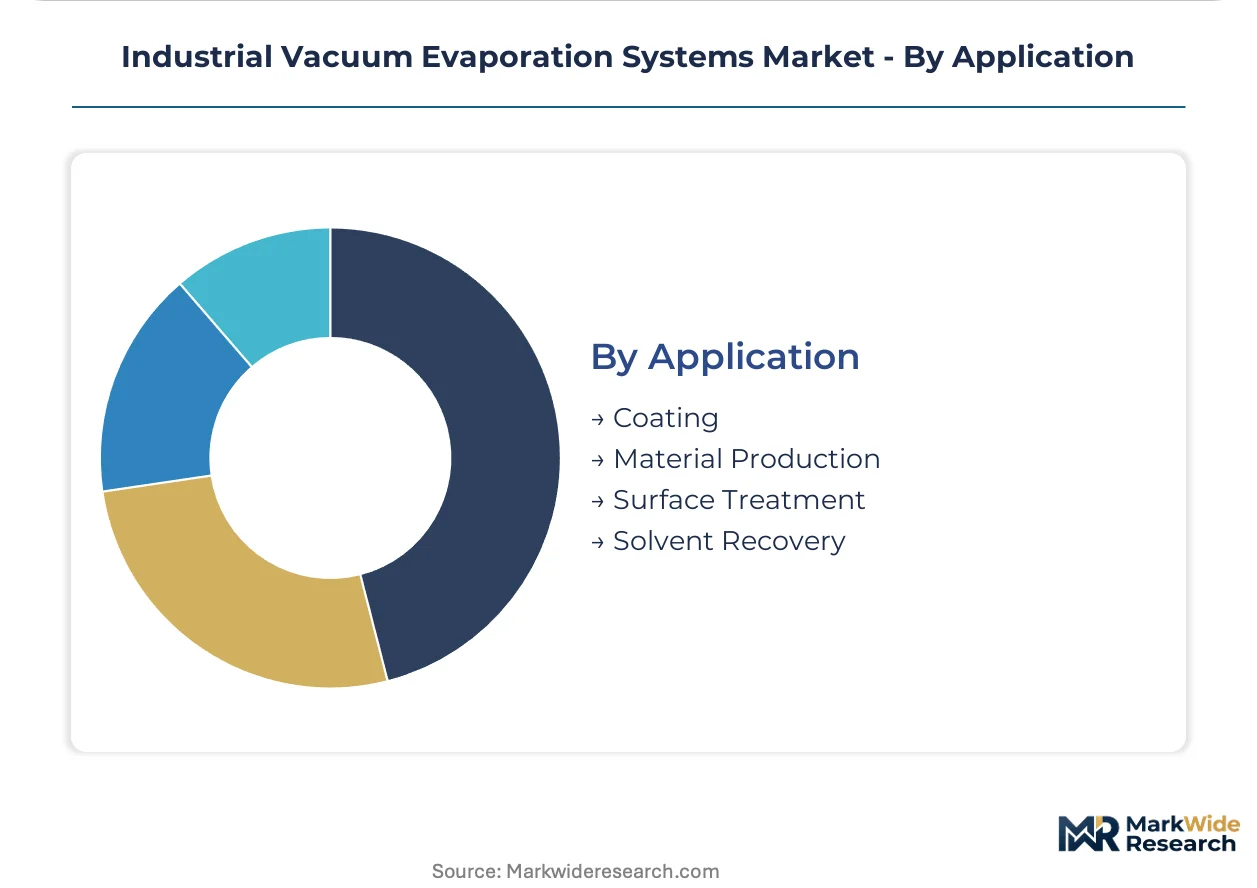
Application:
Application focus shapes vacuum depth requirements, heat transfer configuration, and recovery system architecture.
- Solvent Recovery:Closed-loop vacuum-based separation systems capture valuable organic solvents from pharmaceutical and chemical process streams. EU Green Deal thermal efficiency mandates subsidize retrofits displacing atmospheric thermal processes across German and Swiss API manufacturing sites.
- Coating:Thin-film deposition for electronics, aerospace, and optical components demands precise pressure control and automated substrate handling.
- Material Production:Vacuum evaporation concentrates solutions and isolates pure materials for specialty chemical and food ingredient manufacturing.
- Surface Treatment:Protective and functional layer deposition enhances component durability and performance in aerospace and industrial applications.
Capital allocation prioritizes Solvent Recovery on regulatory compliance deadlines; Coating applications show steepest expansion trajectory from semiconductor automation investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel feedstock from German mills and Japanese specialty alloy producers anchors equipment fabrication clusters. Vacuum pump sub-system supply concentrates around precision engineering corridors in southern Germany and the Kansai region of Japan.
United States
Pharmaceutical wastewater treatment upgrades dominate demand as EPA effluent guidelines under the Clean Water Act tighten discharge limits. The IRA subsidizes energy-efficient solvent recovery retrofits across chemical manufacturing sites. New Jersey and Pennsylvania chemical corridors anchor large-scale vacuum evaporation installations serving API producers.
Germany
REACH compliance deadlines force rapid capacity expansion without civil construction timelines. The EU Green Deal thermal efficiency mandates subsidize vacuum-based retrofits displacing atmospheric thermal processes. The Ludwigshafen chemical corridor concentrates demand for modular skids integrated with centrifuge separation packages.
Switzerland
High-value active ingredient recovery drives thin-film evaporator specifications requiring sub-50°C processing. Swissmedic validation requirements enforce ASME pressure vessel certification for pharmaceutical installations. Basel and Zurich anchor API manufacturing clusters deploying mechanical vapor recompression systems.
India
CDSCO regulatory harmonization with ICH standards accelerates validated batch system procurement. The PLI scheme for pharmaceuticals subsidizes wastewater infrastructure expansion among contract manufacturers. Maharashtra and Gujarat pharmaceutical clusters drive demand for multi-product flexible configurations.
Japan
Semiconductor wafer coating automation requires robotic vacuum evaporation systems with precise pressure modulation. METI industrial decarbonization targets push adoption of heat pump-assisted configurations. The Kyushu and Chubu regions concentrate electronics manufacturing investments in closed-loop recovery architectures.
Industrial Vacuum Evaporation Systems Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue modular skid configurations and equipment-as-a-service financing models. The vendor base clusters around three archetypes: diversified process equipment conglomerates with centrifuge-to-evaporator integration capabilities, plate evaporator specialists serving food concentration applications, and precision thin-film system fabricators for temperature-sensitive pharmaceutical actives. Consolidation pressure intensifies as REACH compliance deadlines compress procurement cycles. Strategic moves center on geographic expansion into India's pharmaceutical corridor and technology licensing partnerships for mechanical vapor recompression architectures.
Among diversified European conglomerates, GEA Group and Alfa Laval occupy positions spanning multiple end-use verticals through distinct technical specializations. GEA Group exemplifies the integrated separation systems archetype, while Alfa Laval represents plate heat transfer expertise. SPX Flow sits within the precision thin-film tier serving temperature-constrained pharmaceutical applications. These three anchors demonstrate how fabricators differentiate through thermal configuration specialization rather than geographic coverage alone.
| Leading Market Players |
|---|
| GEA Group |
| Veolia Water Technologies |
| Alfa Laval |
| SPX Flow |
| PRAB |
| Condorchem Envitech |
| BÜCHI Labortechnik AG |
| Sanshin Mfg. Co. Ltd. |
| Eco-Techno SRL |
| Others |
Value Chain & Pricing Dynamics
Mechanical vapor recompression adoption is compressing energy intensity benchmarks while simultaneously concentrating procurement leverage among German and Swiss API manufacturers with steam boiler infrastructure to decommission. This technology shift rewards fabricators with captive heat pump compressor supply chains while penalizing atmospheric evaporator specialists exposed to nickel-alloy feedstock volatility.
Pricing Analysis
Equipment-as-a-service bundling separates maintenance-inclusive contracts from unbundled capital purchases across Netherlands and Belgium chemical parks. Three-tier pricing structure across premium certified, standard validated, and economy non-ASME tiers reflects ASME pressure vessel certification premiums and REACH compliance validation depth. Pricing pressure stems from stainless steel commodity swings pressuring vacuum chamber fabrication costs. Mid-scale chemical processors in multi-tenant infrastructure show highest price sensitivity; pharmaceutical API manufacturers with Swissmedic validation requirements demonstrate lowest.
Supply Chain Analysis
Freight cost exposure runs through oversized vacuum chamber shipments from German fabrication clusters to Indian pharmaceutical corridors. Supply concentration rests in German stainless steel mills, Japanese precision vacuum pump manufacturers in the Kansai region, and Swiss mechanical vapor recompression compressor specialists. Nickel-alloy feedstock dependency and single-source vulnerability from German-Japanese pump sub-system concentration create structural bottlenecks. Distribution feeds through regional equipment fabricators with centrifuge-to-evaporator integration capabilities serving Ludwigshafen chemical park operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH effluent standards and EPA Clean Water Act guidelines have transformed solvent recovery infrastructure into a cost-of-compliance barrier, erecting validation moats that protect incumbent fabricators with ASME certification capabilities while filtering out atmospheric evaporator generalists.
For Market Incumbents: Lock in centrifuge-to-evaporator integration packages across European chemical parks before modular skid entrants capture REACH-driven replacement cycles. Prioritize backward integration into heat pump compressor supply chains to defend margin pools against energy efficiency commoditization. Anchor long-term service contracts with Swiss and German API manufacturers facing Swissmedic validation renewal deadlines. For New Entrants and Emerging Players: Begin with equipment-as-a-service financing models targeting Netherlands and Belgium multi-tenant chemical park operators seeking opex-aligned wastewater infrastructure. India's CDSCO-harmonized contract API manufacturing corridor offers the most penetrable geography for validated batch system entry. Pursue technology licensing partnerships with mechanical vapor recompression specialists to bypass ASME certification timeline disadvantages. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified process equipment conglomerates seeking centrifuge-to-evaporator integration capabilities. Long-term viability favors fabricators with pharmaceutical validation credentials and heat pump-assisted technology portfolios over atmospheric evaporator legacy positions. Monitor EPA effluent guideline enforcement intensity as the inflection signal for US pharmaceutical wastewater retrofit acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Vapor Recompression Technology Licensing | Swiss and German API manufacturers cut thermal energy input by half through compressor-based latent heat recycling. |
| Modular Skid Configuration Expansion | REACH compliance deadlines in Ludwigshafen chemical corridor reward rapid deployment without civil construction timelines. |
| Equipment-as-a-Service Model Launch | Netherlands and Belgium chemical park operators transfer operational risk to fabricators through opex-aligned leasing. |
| ASME Pressure Vessel Certification Investment | Swissmedic validation requirements enforce stamped code compliance for pharmaceutical active ingredient recovery systems. |
| Heat Pump Compressor Backward Integration | German fabricators secure captive supply of energy efficiency sub-systems amid Japanese pump manufacturer bottleneck risk. |
Study Parameters
Independent corroboration across equipment fabricator technical directors, pharmaceutical plant engineers, and chemical park procurement managers underwrites the qualitative findings. Primary fieldwork with maintenance directors at German API manufacturing sites, aftermarket service heads at centrifuge-to-evaporator integrators, and OEM procurement teams in the Ludwigshafen corridor combined with secondary validation from SEC 10-K filings, Cefic chemical industry reports, and customs trade data. Bottom-up installation tracking and top-down market sizing triangulate volume estimates across continuous, batch, and robotic system configurations.
Rate-of-change decomposition across product type, end user vertical, technology architecture, and application focus anchors the analytical framework over the projection horizon. Segmentation modeling incorporates thermal sensitivity thresholds, validation protocol complexity, and automation depth as industry-specific forecast inputs. CAGRs derive from installed base evolution, replacement cycle compression from regulatory deadlines, and penetration rate assumptions for heat pump-assisted configurations displacing multi-effect thermal systems.
Underlying measurement precision varies by segment; continuous systems in established chemical processing corridors carry tighter precision than emerging robotic system deployments in semiconductor manufacturing. Forecasts reflect assumptions about REACH enforcement intensity, EPA guideline implementation pacing, and stainless steel commodity trajectory. Stakeholders should weight assumptions against their own operating context and regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Special Purpose Machines Market
Industrial Equipment
Laser Cleaning Market
Industrial Equipment
Parts and Equipment Market
Industrial Equipment
Europe Fusion Splicer Market
Industrial Equipment
Precision Machine Market
Industrial Equipment
Digital Tachometer Market
Industrial Equipment
United States Ball Bearing Market
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Laser Marking Equipment Market
Industrial Equipment
Slewing Bearing Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
Industrial Refrigeration Systems Market
Industrial Equipment
Bellows Vacuum Suction Cup Market
Industrial Equipment
Camera Tripods Market
Industrial Equipment
Servo Drive Market
Industrial Equipment
Ceramic Roller Bearings Market