
 FOUP Cleaning System Market | 2026-2036
FOUP Cleaning System Market Size, Share, and Industry Trends Forecast 2026-2036
FOUP Cleaning System Market Foresight
Polymer chemistry is shifting from legacy polycarbonate FOUP shells toward advanced cyclic olefin polymer formulations that reduce ionic outgassing during high-temperature plasma cleans. Tokyo Electron Limited leverages its etch equipment installed base to bundle FOUP cleaning modules with chamber maintenance contracts. Brooks Automation sustains aftermarket revenue through proprietary sensor networks that predict particulate buildup. SEMES Co., Ltd. anchors Korean foundry supply chains with localized wet bench manufacturing.
A FOUP cleaning system removes organic residues, metallic contaminants, and airborne particles from front opening unified pods used to transport 300mm silicon wafers between semiconductor process tools, typically employing deionized water megasonics, diluted chemistry sprays, or supercritical fluid phases operating at pressures above 7.4 MPa to preserve wafer surface integrity. Ultrasonic cleaners dominate installed base economics due to mature transducer reliability and lower capital outlay, while supercritical fluid technology captures margin pools in EUV lithography support applications where sub-0.1 ppb metallic contamination thresholds apply. Wet cleaning retains volume leadership across foundry and memory fabs, though dry cleaning and plasma cleaning segments accelerate fastest as chemical consumption regulations tighten in East Asian manufacturing jurisdictions.
ISO 14644-1 cleanroom classification protocols, Japan's METI semiconductor supply chain resilience directives, and South Korea's K-Battery and K-Semiconductor Acts collectively elevate contamination control standards and localize equipment procurement preferences. The EPA's National Emission Standards for Hazardous Air Pollutants also constrain solvent-based chemistries deployed in US-based wafer fabs, redirecting capital toward closed-loop aqueous and CO2-based systems. Stakeholders must monitor which cleaning modality achieves process-of-record status at next-generation gate-all-around transistor fabs before committing to multi-year capacity expansion cycles.
Market Dynamics
Sub-3nm process ramps at logic foundries in Taiwan and South Korea are compressing particulate contamination thresholds below 0.1 ppb metallic levels, forcing wholesale replacement of solvent-based wet benches with closed-loop ultrasonic and supercritical CO2 systems that preserve wafer surface integrity during high-temperature plasma cleans.
Growth Catalysts
- ISO 14644-1 cleanroom classification tightening:Semiconductor fabs in Hsinchu and Pyeongtaek must upgrade FOUP cleaning infrastructure to meet revised particulate limits for 300mm wafer transport, triggering capital deployment across automated cleaning lines.
- Japan's METI semiconductor supply chain resilience directives:Domestic equipment procurement mandates are accelerating localized manufacturing of closed-loop aqueous cleaning systems to reduce import dependency for critical contamination control hardware.
- Supercritical CO2 technology maturation:Gate-all-around transistor architectures require non-aqueous cleaning chemistries that eliminate watermarks on EUV-patterned wafers, expanding addressable market for high-pressure fluid systems above 7.4 MPa operating thresholds.
Market Restraints
- Fluoropolymer and high-purity stainless steel input cost volatility:Supercritical CO2 system fabricators face margin compression from specialty alloy price swings tied to energy-intensive refining capacity concentrated in Germany and Japan.
- Transducer supply concentration:Piezoelectric ceramic components for ultrasonic cleaning modules source predominantly from Chinese and Japanese material suppliers, creating single-point vulnerability for wet bench OEMs.
- EPA National Emission Standards for Hazardous Air Pollutants:US-based wafer fabs face accelerated depreciation of solvent-based chemistries, stranding capital in legacy wet bench installations before full payback periods.
Strategic Opportunities
- India's PLI scheme for semiconductor manufacturing:Greenfield fab investments in Gujarat and Karnataka create first-mover advantage for FOUP cleaning system vendors establishing localized service networks before production ramps.
- Cyclic olefin polymer FOUP shell convergence:Advanced polymer formulations reducing ionic outgassing during plasma cleans enable equipment vendors to bundle cleaning modules with material upgrade contracts.
- Aftermarket sensor network monetization:Predictive particulate buildup monitoring creates recurring revenue streams through proprietary IoT platforms that lock in long-term maintenance relationships with foundry customers.
Industry Challenges
- Cleanroom technician certification bottlenecks:ISO 14644-1 auditor scarcity extends commissioning timelines for new FOUP cleaning installations, delaying revenue recognition for equipment vendors.
- Legacy wet bench integration complexity:Retrofitting closed-loop aqueous systems into existing solvent-based infrastructure requires custom plumbing and control architecture, inflating project engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FOUP Cleaning System Market |
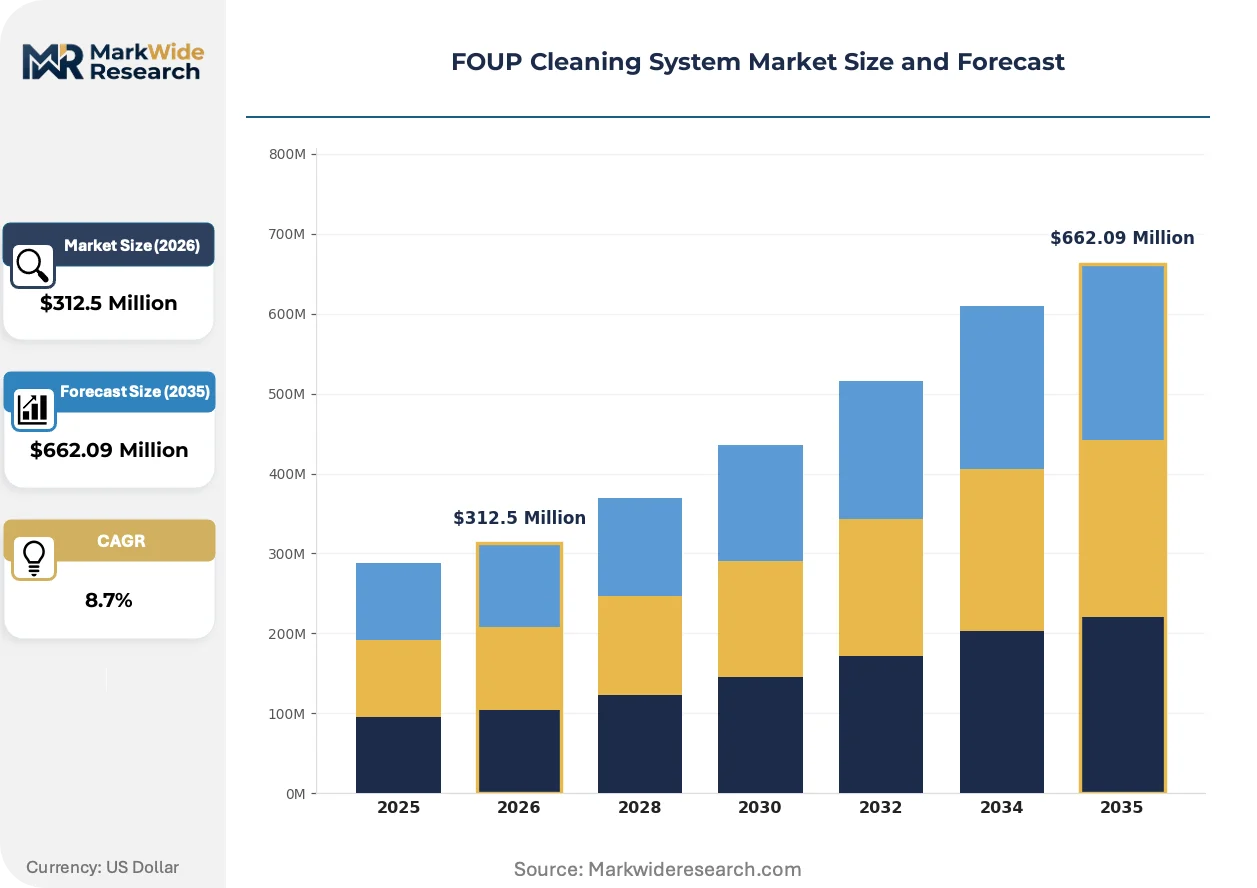
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Cleaners, Spray Cleaners, Heated Cleaners, Vacuum Cleaners, Automated Handling Systems Technology: Dry Cleaning, Wet Cleaning, Plasma Cleaning, Chemical Vapor, Supercritical Fluid Application: Semiconductor Fabrication, MEMS Manufacturing, Wafer Processing, Photolithography Support, Thin Film Deposition End User: Chipmakers, Foundries, Equipment Vendors, Research Institutes, Contract Manufacturers |
| Companies Covered | Tokyo Electron Limited, Brooks Automation, SEMES Co., Ltd., Merck KGaA, Hugle Electronics, Modutek Corporation, Shibaura Mechatronics Corporation, DEVICEENG Co., Ltd., Entegris, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FOUP Cleaning System Market Shifts & Advancements
Semiconductor contamination control is bifurcating between mature ultrasonic economics and emerging supercritical fluid architectures, with regulatory chemistry constraints and EUV lithography yield requirements determining technology selection across foundry capital cycles.
Supercritical CO2 cleaning is rewriting wafer surface preparation protocols by eliminating watermarks and metallic residues through dense-phase fluid extraction at pressures exceeding 7.4 MPa. Leading-edge logic foundries in Taiwan and South Korea are adopting these systems for EUV mask blank and reticle pod cleaning, compressing the addressable market for traditional aqueous chemistries in sub-5nm process nodes.
South Korea's K-Semiconductor Act mandates domestic equipment procurement preferences that redirect capital toward localized wet bench manufacturing. Korean foundry operators must now source contamination control hardware from approved domestic vendors, reshaping competitive positioning for Japanese and American equipment suppliers who previously dominated the aftermarket.
Foundry procurement departments are unbundling FOUP cleaning equipment from bundled chamber maintenance contracts, forcing equipment vendors to compete on standalone system pricing rather than integrated service agreements. This behavioral shift is most visible in the Hsinchu Science Park corridor, where Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation have established separate RFP processes for capital equipment and consumable service tiers.
FOUP Cleaning System Market Segmentation
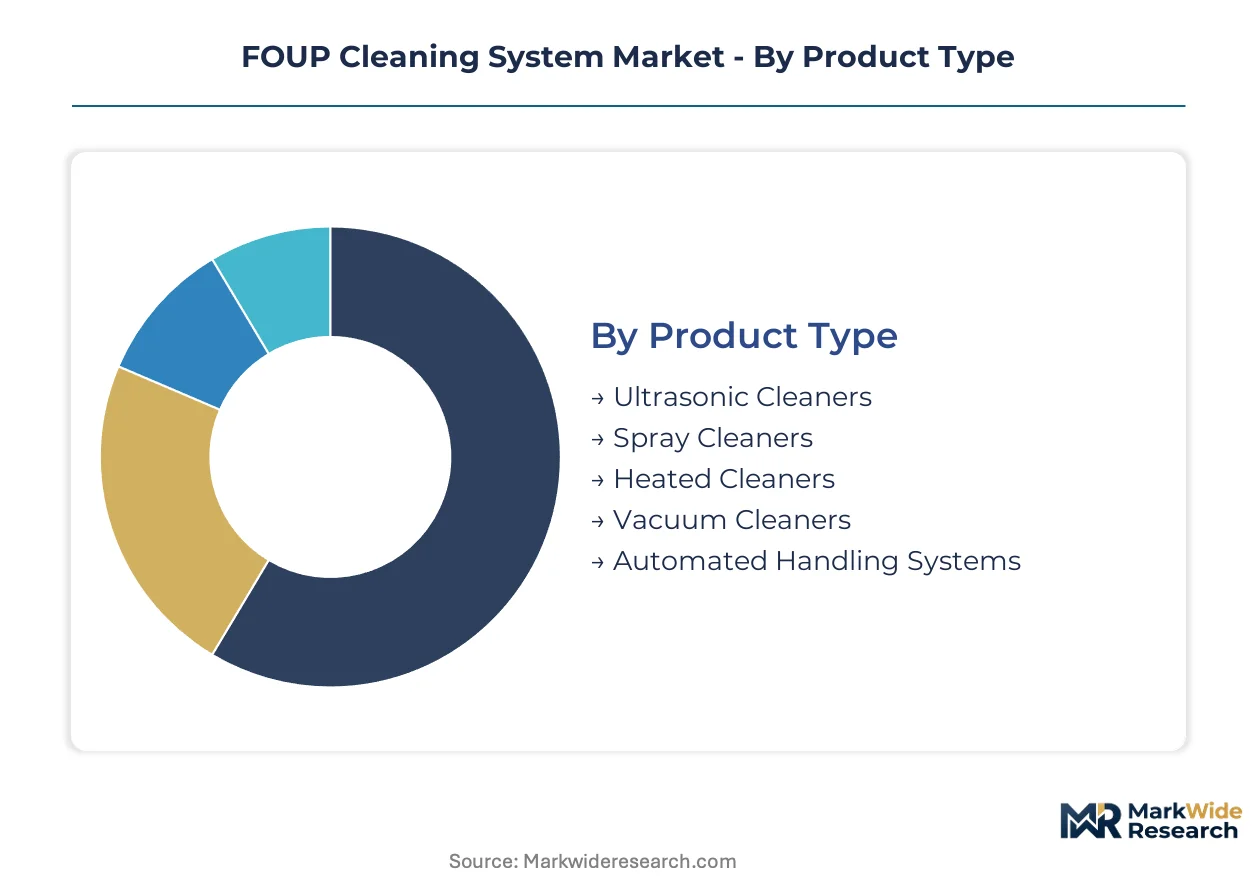
FOUP cleaning system procurement varies sharply by fab process node and contamination tolerance. Buyers prioritize different performance thresholds across logic foundries, memory fabs, and research environments, fragmenting vendor pricing power.
Product Type:
Capital intensity and throughput requirements separate buyers in this category.
- Ultrasonic Cleaners:Piezoelectric transducers operating at 40-130 kHz frequencies remove sub-micron particles through cavitation without mechanical abrasion. Mature installed base economics dominate foundry procurement in Hsinchu and Pyeongtaek, though transducer supply concentration in Japanese and Chinese ceramic suppliers creates procurement risk.
- Automated Handling Systems:Robotic FOUP transfer mechanisms integrate with AMHS rail networks to eliminate human-borne contamination during cassette loading. Logic foundries scaling sub-3nm production mandate these configurations for ISO 14644-1 Class 3 compliance, compressing commissioning timelines where cleanroom technician certification bottlenecks persist.
- Spray Cleaners:Pressurized deionized water or dilute chemistry nozzles target surface residues on polymer FOUP shells.
- Heated Cleaners:Elevated temperature aqueous baths accelerate organic decomposition for high-volume memory fab operations.
- Vacuum Cleaners:Low-pressure particle extraction systems serve retrofit applications in legacy 200mm facilities.
Volume sits with ultrasonic cleaners; growth tilts toward automated handling systems.
Technology:
Regulatory chemistry constraints and EUV lithography yield requirements determine technology selection.
- Wet Cleaning:Aqueous chemistries with megasonic or spray delivery retain volume leadership across foundry and memory fabs. Closed-loop water recycling systems address tightening EPA National Emission Standards for Hazardous Air Pollutants constraints in US-based installations, though watermark formation limits adoption at sub-5nm nodes.
- Supercritical Fluid:Dense-phase CO2 extraction at pressures exceeding 7.4 MPa eliminates metallic residues and watermarks from EUV-patterned wafers. Gate-all-around transistor architectures in Taiwan and South Korea drive adoption where sub-0.1 ppb contamination thresholds apply, despite fluoropolymer and high-purity stainless steel input cost volatility.
- Dry Cleaning:Non-aqueous particle removal via pressurized gas or cryogenic aerosol serves water-sensitive process steps.
- Plasma Cleaning:Low-temperature glow discharge removes organic films through reactive ion etching.
- Chemical Vapor:Vapor-phase solvent delivery enables precision residue stripping in research institute environments.
Installed base concentrates in wet cleaning; steepest expansion trajectory belongs to supercritical fluid.
Application:
Process criticality and wafer value at risk shape procurement specifications.
- Semiconductor Fabrication:Front-end wafer processing demands the most stringent particulate control, with FOUP cleaning integrated into automated transport loops between etch, deposition, and metrology tools. Taiwan Semiconductor Manufacturing Company and Samsung Electronics specifications drive industry-wide contamination thresholds.
- Photolithography Support:EUV mask blank and reticle pod cleaning requires non-aqueous chemistries to prevent watermark defects on optical surfaces. Sub-3nm logic ramps in South Korea's Pyeongtaek cluster accelerate capital deployment for supercritical CO2 configurations in this application.
- MEMS Manufacturing:Microelectromechanical device fabrication tolerates higher particle counts but requires specialized handling for fragile suspended structures.
- Wafer Processing:General-purpose 300mm wafer preparation spans memory and logic production with moderate cleanliness requirements.
- Thin Film Deposition:Pre-deposition surface preparation emphasizes metallic contamination removal for gate oxide integrity.
Revenue concentrates in semiconductor fabrication; photolithography support climbs the fastest.
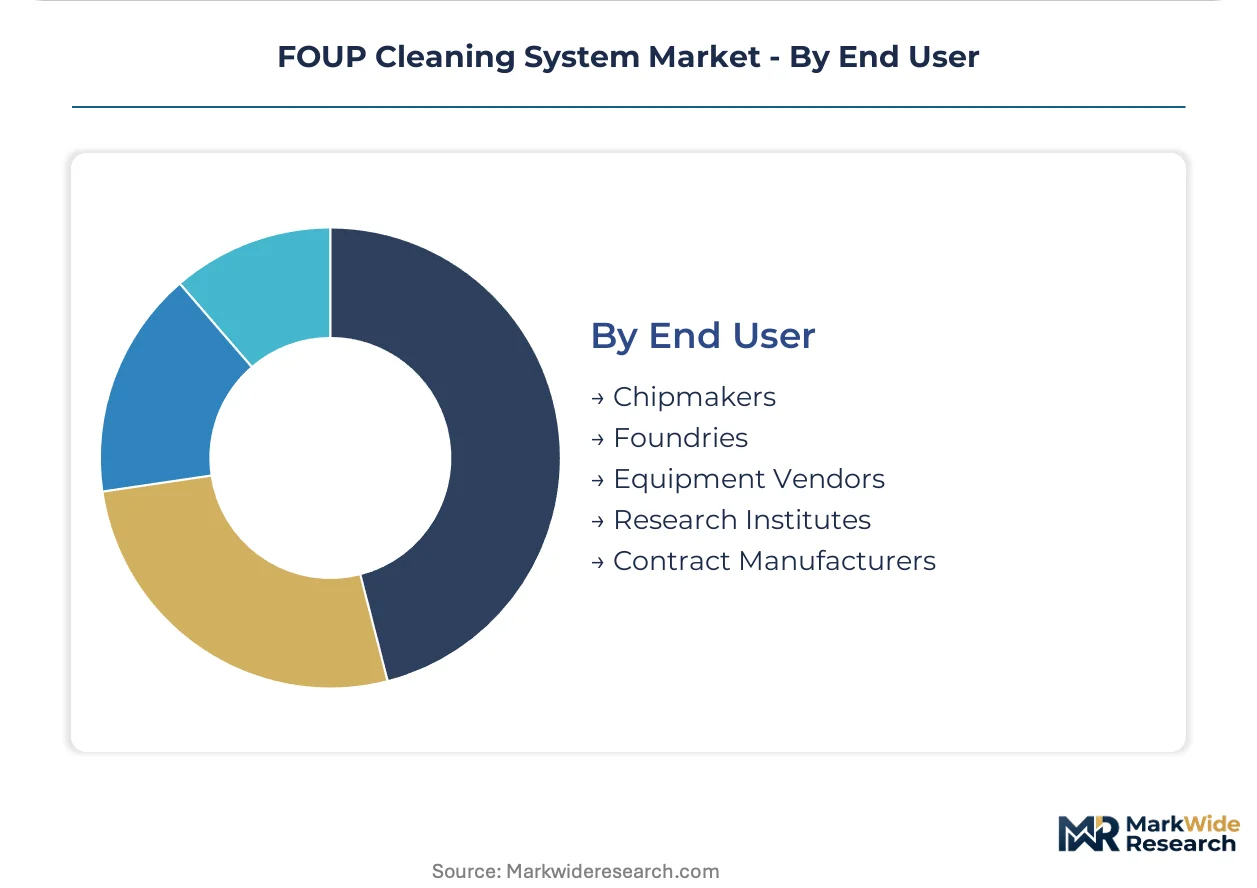
End User:
Procurement authority and maintenance integration preferences segment this category.
- Foundries:Pure-play and integrated foundries operate the largest installed bases, with unbundling of equipment and service contracts reshaping vendor relationships. Taiwan's Hsinchu Science Park corridor and South Korea's Pyeongtaek cluster represent concentrated demand where separate RFP processes for capital equipment and consumable tiers now prevail.
- Chipmakers:Integrated device manufacturers with captive fabs prioritize equipment reliability over standalone pricing, sustaining bundled maintenance agreements.
- Equipment Vendors:OEMs sourcing cleaning modules for integration into larger toolsets.
- Research Institutes:Academic and government laboratories with flexible throughput requirements.
- Contract Manufacturers:Outsourced assembly and test providers with cost-optimized specifications.
Procurement volume clusters with foundries; research institutes gain share fastest as government semiconductor initiatives expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in East Asian semiconductor manufacturing corridors where sub-3nm process ramps require automated FOUP cleaning infrastructure. Taiwan, South Korea, and Japan anchor procurement volume through foundry expansion cycles and domestic equipment mandates.
Taiwan
Advanced logic foundries in Hsinchu Science Park drive automated FOUP cleaning capacity additions to support 300mm wafer output scaling. Taiwan's National Development Council semiconductor initiatives prioritize contamination control equipment localization. The Hsinchu-Taichung corridor hosts concentrated demand where Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation operate separate RFP processes for capital equipment tiers.
South Korea
Samsung Electronics and SK Hynix memory expansions in Pyeongtaek trigger wet bench and supercritical CO2 system procurement for EUV lithography support. South Korea's K-Semiconductor Act mandates domestic equipment sourcing preferences that redirect capital toward approved local vendors. The Pyeongtaek semiconductor cluster represents the fastest-growing installation base for closed-loop aqueous cleaning configurations.
Japan
Tokyo Electron and Shin-Etsu Chemical supply chain integration sustains demand for precision cleaning modules in Nagoya and Kumamoto fab corridors. Japan's METI semiconductor supply chain resilience directives accelerate localized manufacturing of contamination control hardware to reduce import dependency. The Kyushu region hosts concentrated equipment fabrication where domestic wet bench OEMs serve captive foundry demand.
United States
Intel and Micron Technology fab investments in Arizona and New York generate procurement for EPA-compliant closed-loop systems replacing solvent-based wet benches. The EPA's National Emission Standards for Hazardous Air Pollutants constrain chemistry choices in US-based installations, redirecting capital toward aqueous and supercritical CO2 alternatives. The Phoenix metropolitan area anchors southwestern demand where TSMC's Arizona facility drives localized service network requirements.
China
SMIC and Hua Hong Semiconductor capacity expansions in Shanghai and Wuxi sustain wet cleaning equipment demand despite export control restrictions on advanced nodes. China's MIIT domestic equipment procurement guidelines prioritize localized contamination control hardware for mature-node foundries. The Yangtze River Delta cluster concentrates manufacturing where indigenous wet bench vendors compete for state-backed fab projects.
FOUP Cleaning System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated equipment vendors capturing premium positions in automated handling configurations while regional fabricators compete on wet bench economics. The market structure tilts toward consolidation in supercritical CO2 technology where fluoropolymer fabrication capabilities concentrate among Japanese and German suppliers, while ultrasonic cleaning remains fragmented across Asian contract manufacturers. Three archetypes dominate: full-stack semiconductor equipment vendors bundling cleaning modules with chamber maintenance, dedicated contamination control specialists with proprietary sensor networks, and regional wet bench fabricators serving price-sensitive memory fab procurement. Competitive moves center on backward integration into piezoelectric ceramic supply and geographic expansion through localized manufacturing mandates in South Korea and Japan.
Within the full-stack equipment vendor tier, Tokyo Electron Limited and Brooks Automation exemplify archetypes leveraging installed base relationships to bundle FOUP cleaning modules with service contracts. SEMES Co., Ltd. occupies a position as the anchor Korean vendor benefiting from K-Semiconductor Act localization requirements, representing how domestic procurement mandates reshape competitive positioning for foreign suppliers previously dominant in aftermarket segments.
| Leading Market Players |
|---|
| Tokyo Electron Limited |
| Brooks Automation |
| SEMES Co., Ltd. |
| Merck KGaA |
| Hugle Electronics |
| Modutek Corporation |
| Shibaura Mechatronics Corporation |
| DEVICEENG Co., Ltd. |
| Entegris, Inc. |
| Others |
Supply & Pricing Matrix
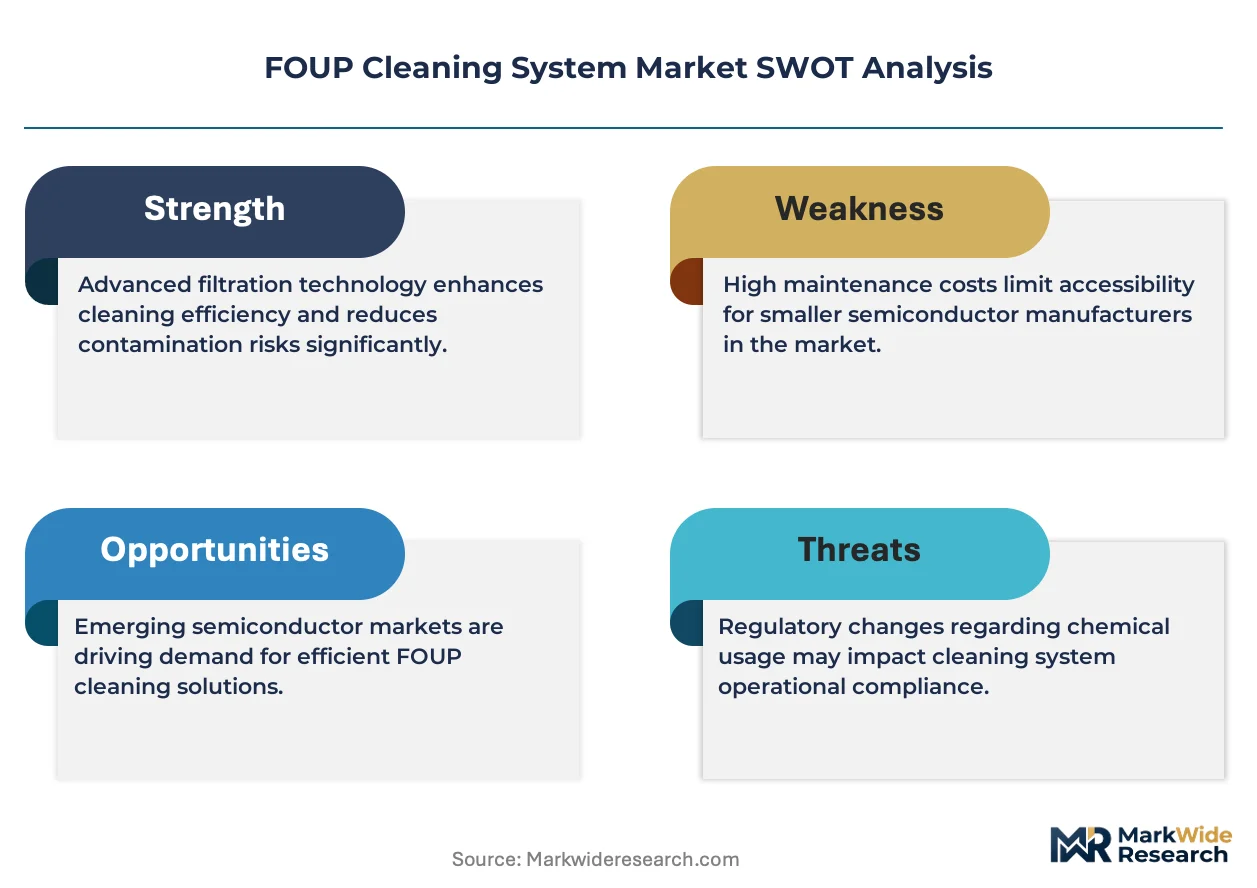
Family-owned Japanese ceramic suppliers and sovereign-backed Korean equipment fabricators anchor supply behavior, translating concentrated piezoelectric transducer production into disciplined pricing tiers that resist commoditization despite memory fab procurement pressure.
Pricing Analysis
High-volume ultrasonic cleaner deployments capture unit economics leadership while supercritical CO2 configurations command margin premiums through EUV lithography certification requirements. Price differentiation rests on ISO 14644-1 compliance tier and after-sales sensor network bundling. Cost compression in standard wet bench tiers is intensifying because Chinese contract manufacturers are scaling indigenous production. Memory fabs in Pyeongtaek exhibit highest price sensitivity; EUV-enabled logic foundries in Hsinchu show lowest.
Supply Chain Analysis
Freight costs for fluoropolymer pressure vessels and high-purity stainless steel chambers concentrate procurement risk on transpacific lanes serving Taiwanese and Korean installation sites. Manufacturing draws from Japan, Germany, and South Korea for specialty alloys; piezoelectric ceramics source predominantly from Chinese and Japanese material suppliers. Single-source vulnerability in transducer supply creates chokepoint exposure. Distribution runs through foundry-direct contracts with localized service depot requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into piezoelectric ceramic supply and captive sensor network deployment constitutes the dominant vertical-integration race, with equipment vendors pursuing upstream material control to defend margin pools against contract manufacturer encroachment.
For Market Incumbents: Deploy proprietary IoT sensor networks to lock in long-term maintenance relationships before SEMES Co. and domestic Korean vendors capture Pyeongtaek service contracts. Deepen backward integration into Japanese piezoelectric ceramic supply to offset Chinese material supplier concentration risk. Secure ISO 14644-1 Class 3 certification ahead of sub-3nm logic ramp timelines. For New Entrants and Emerging Players: Begin with India's Gujarat and Karnataka greenfield corridors where PLI scheme fab investments lack established service networks. Target photolithography support applications for supercritical CO2 systems where EUV mask blank cleaning specifications create certification barriers for incumbents. Pursue foundry-direct sales bypassing bundled chamber maintenance incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor Korean wet bench specialists with K-Semiconductor Act approval status and established Pyeongtaek relationships. Long-term viability hinges on gate-all-around transistor process-of-record adoption at leading logic foundries. Monitor which cleaning modality achieves EUV lithography yield thresholds as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piezoelectric Ceramics | Captive transducer supply reduces Japanese and Chinese supplier dependency for ultrasonic module OEMs. |
| Sensor Network Platform Launch | Proprietary IoT particulate monitoring creates recurring revenue lock-in with Hsinchu and Pyeongtaek foundries. |
| Supercritical CO2 Certification Investment | EUV lithography compliance opens sub-0.1 ppb contamination threshold applications at Samsung and TSMC. |
| Localized Manufacturing in South Korea | K-Semiconductor Act domestic sourcing mandates redirect procurement toward approved Korean wet bench vendors. |
| India Service Network Establishment | First-mover positioning in Gujarat and Karnataka captures PLI scheme fab ramp maintenance contracts. |
Research Methodology
Document review covered SEC semiconductor equipment filings, METI supply chain resilience directives, and Korean K-Semiconductor Act procurement guidelines, complemented by interviews with foundry contamination control engineers, wet bench OEM product managers, cleanroom certification auditors, and piezoelectric ceramic procurement leads. Secondary validation drew from ISO 14644-1 classification protocols, EPA National Emission Standards enforcement records, and foundry capital expenditure disclosures. Bottom-up installation base modeling and top-down equipment spending forecasts were triangulated.
Historical capital deployment patterns were cross-referenced against panel input from equipment vendor sales directors and foundry procurement officers across the projection horizon. Segmentation dimensions modeled include cleaning modality, automation level, process node compatibility, and regional regulatory framework. CAGRs were derived from capacity expansion timelines and technology substitution curves. Forecast inputs incorporated EUV lithography ramp schedules and gate-all-around transistor yield requirements.
Underlying measurement precision varies by segment; supercritical CO2 technology forecasts carry tighter precision than ultrasonic cleaner projections given concentrated vendor base visibility. Forecasts reflect assumptions about sub-3nm process adoption rates and domestic equipment procurement mandate enforcement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Slide Processing System Market
Semiconductor Equipment
SMT Reflow Soldering Equipment Market
Semiconductor Equipment
Global Battery Manufacturing Equipment Market
Semiconductor Equipment
Laser Annealing System Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Semiconductor Assembly Equipment Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Global Wafer Processing and Assembly Equipment Market
Semiconductor Equipment
Wafer CMP Machine Market
Semiconductor Equipment
Electron Beam Lithography Machine Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market
Semiconductor Equipment
Lithographic Photomasks Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Global Semiconductor Etch Equipment Market
Semiconductor Equipment
Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Global Laser Dicing Systems Market