
 Dicing Equipment Market | 2026-2036
Dicing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Dicing Equipment Market Outlook
The EU Green Deal is hardening carbon accounting and material disclosure rules for capital equipment sold into European fabs. DISCO Corporation leverages its blade dicing heritage to sustain leadership in high-volume memory die singulation. Panasonic Corporation anchors its position through integrated motion control and spindle systems developed in-house. Plasma-Therm LLC specializes in dry etch dicing solutions that compete on kerf width reduction for gallium nitride devices.
Dicing equipment comprises precision machines that separate semiconductor wafers, substrates, or electronic components into individual dies using mechanical blades, lasers, plasma etching, or water jet streams, typically achieving kerf widths below 30 micrometers for advanced nodes. Saw dicers dominate volume shipments for silicon wafer processing where mechanical blade technology offers proven cost economics at mature nodes. Laser dicers represent the fastest-expanding product category as silicon carbide and gallium nitride substrates drive demand for thermal-stress-free singulation. Plasma dicers occupy a premium niche in MEMS applications where contamination-free, debris-less cutting preserves delicate suspended structures.
The EPA regulates coolant discharge and occupational exposure limits for abrasive slurry systems used in mechanical dicing facilities across the United States. The EU F-Gas Regulation and RoHS directives constrain refrigerant choices and hazardous substance content in equipment shipped to European semiconductor fabs. Japan's METI enforces energy efficiency standards that shape R&D priorities for spindle motor and motion platform designs. Stakeholders must monitor how evolving dual-use export controls and clean energy mandates reshape equipment qualification timelines and geographic sourcing strategies.
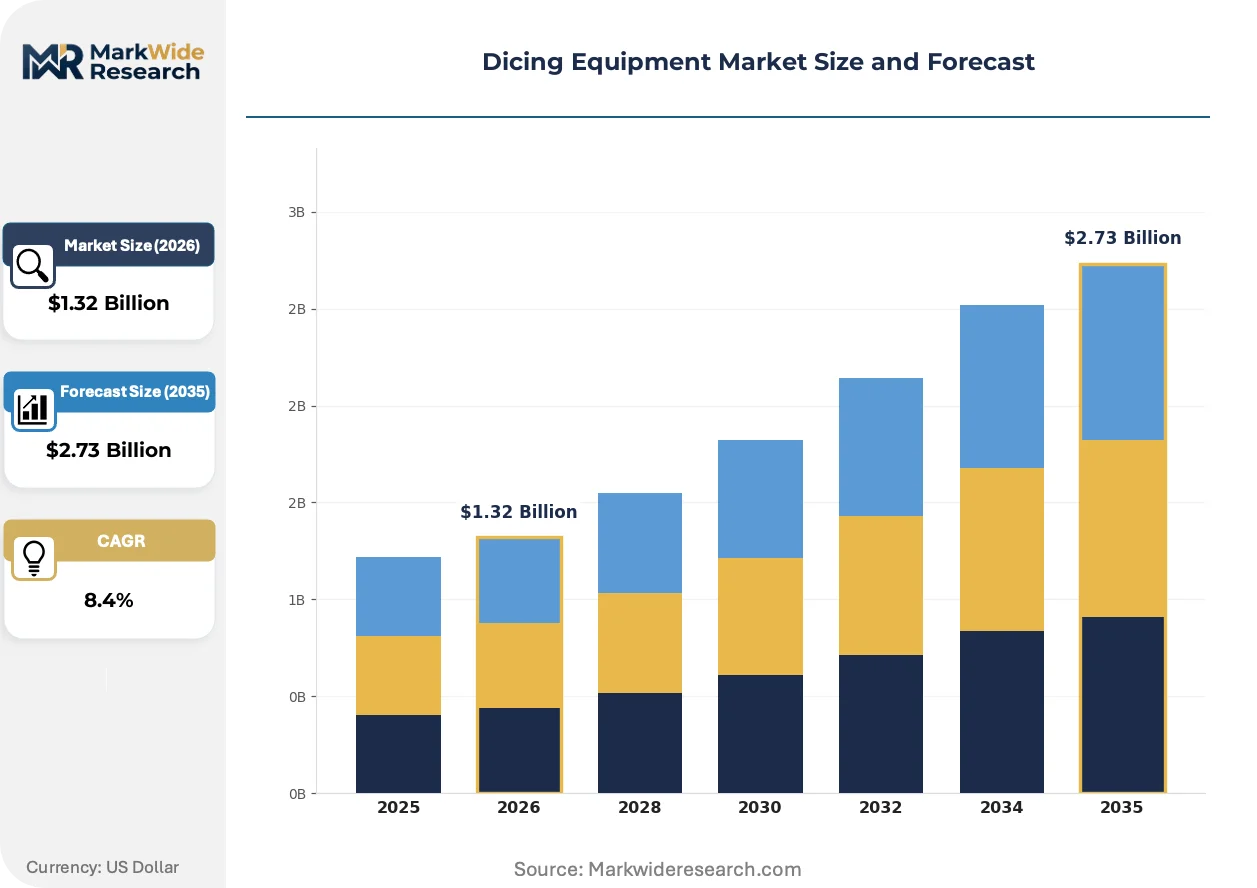
Market Dynamics
Advanced packaging roadmaps are compressing die singulation tolerances below 15 micrometers, forcing equipment vendors to integrate real-time metrology and AI-driven process control directly into dicing platforms.
Growth Catalysts
- Silicon carbide substrate expansion:Power semiconductor fabs in South Korea and Taiwan are scaling 200mm SiC wafer production, requiring thermal-stress-free laser dicing that mechanical blades cannot deliver.
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is accelerating equipment redesigns for spindle cooling systems, creating replacement demand for compliant motion platforms.
- Advanced packaging integration:Chiplet architectures and 3D stacking at TSMC and Samsung Foundry are multiplying dicing steps per wafer, expanding tool utilization rates.
Market Restraints
- Precision spindle supply concentration:Japanese and German specialized motor suppliers control 80% of ultra-high-speed spindle output above 60,000 RPM, creating single-source vulnerability.
- Plasma dicing cost structure:Per-wafer processing costs for dry etch singulation remain 4-7x mechanical blade economics, limiting adoption outside MEMS and GaN RF devices.
- Dual-use export control expansion:US Bureau of Industry and Security licensing delays for sub-7nm-capable equipment are extending qualification timelines for Chinese fabs by 6-12 months.
Strategic Opportunities
- India semiconductor manufacturing:Micron's Gujarat assembly and test facility and Tata Electronics' fab investments are creating first-mover equipment installation demand for dicing tools.
- EU Green Deal carbon accounting:Scope 3 disclosure mandates for capital equipment are favoring vendors with lifecycle-certified low-carbon spindle and coolant systems.
- Laser-plasma hybrid platforms:Converging ultrafast laser ablation with downstream plasma cleaning is opening kerf-width performance gaps unattainable by standalone methods.
Industry Challenges
- Multi-physics simulation expertise:Integrating thermal, mechanical, and plasma process models requires scarce computational materials engineering talent concentrated in Germany and Japan.
- Legacy blade dicer retrofit complexity:Upgrading installed mechanical systems for thinner wafer handling demands platform redesigns that cannibalize existing service revenue streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dicing Equipment Market |
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.73 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saw Dicers, Laser Dicers, Plasma Dicers, Water Jet Dicers End User: Semiconductor Manufacturers, Electronics Firms, Research Institutions, OEMs Technology: Mechanical Dicing, Laser Technology, Plasma Technology, Water Jet Technology Application: Flat Panel Displays, Solar Cells, Integrated Circuits, MEMS |
| Companies Covered | Plasma-Therm LLC, Panasonic Corporation, DISCO Corporation, 3D-Micromac, Synova SA, Tokyo Seimitsu Co., Ltd., Kulicke & Soffa Industries, Inc., SUSS MicroTec, Advanced Dicing Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dicing Equipment Market Strategic Shifts
Process integration is collapsing discrete dicing, cleaning, and inspection steps into unified platforms, compressing factory footprint requirements and redefining equipment value propositions around throughput-per-square-meter.
Ultrafast picosecond laser systems are converging with adaptive optics for real-time beam steering. Automotive power module manufacturers in Germany and Japan are adopting these platforms for SiC MOSFET singulation. The technology is converging with inline ellipsometry to enable closed-loop depth control, eliminating post-dice thickness verification steps.
Japan's METI energy efficiency standards for industrial equipment are tightening motor power density requirements. Equipment vendors must redesign spindle and motion systems to meet 2027 targets. Dicing platforms destined for Japanese fabs face accelerated R&D cycles to maintain qualification eligibility.
Consolidated procurement through foundry-level master service agreements is displacing individual fab equipment purchasing. Memory manufacturers in South Korea now negotiate enterprise-wide dicing tool contracts spanning multiple sites. This concentration is visible most acutely in HBM packaging lines where tool standardization reduces process variation.
Dicing Equipment Market Segmentation
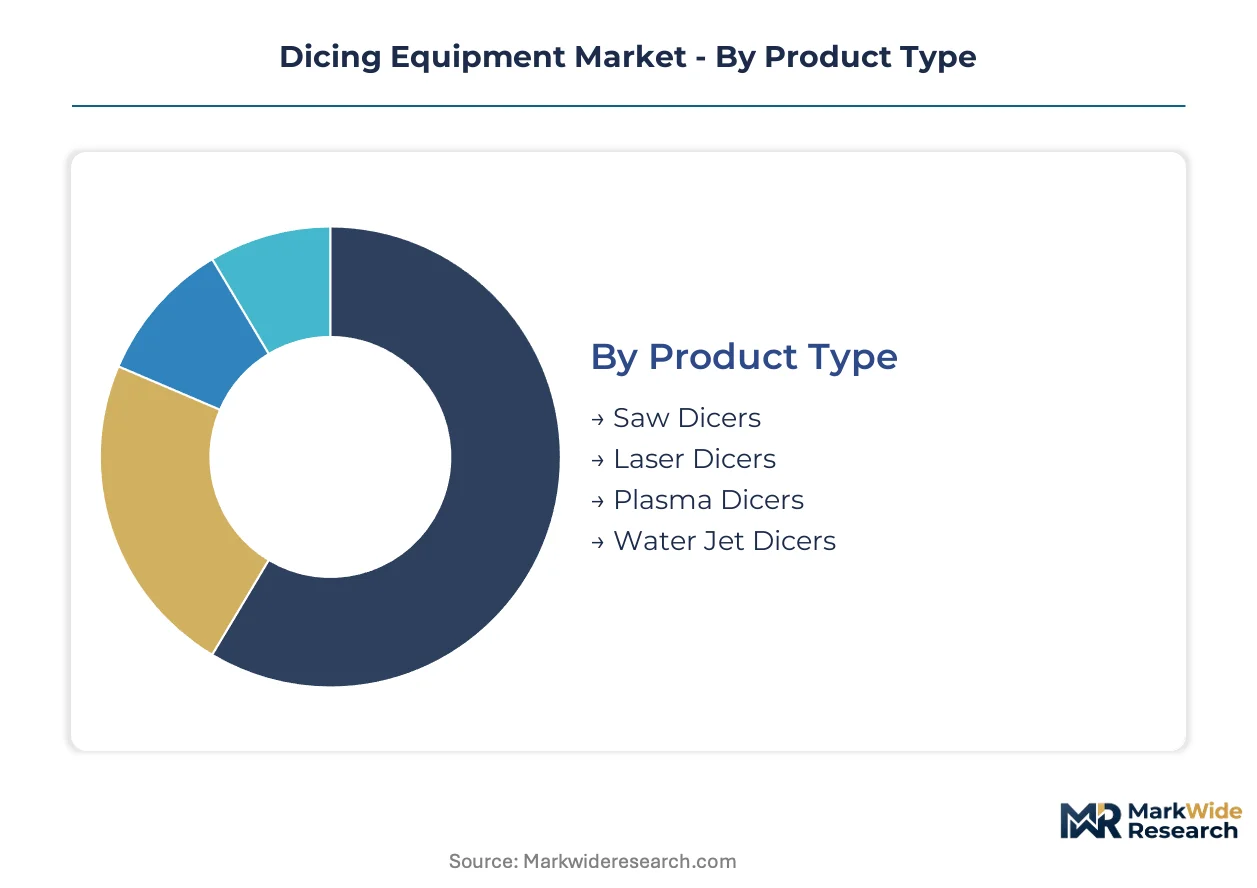
Dicing equipment segmentation reveals how process requirements fragment across substrate materials and die geometries. Equipment vendors configure platforms around thermal budgets, kerf width tolerances, and contamination sensitivity rather than pursuing universal tool designs.
Product Type:
Supply concentration in high-speed spindles and precision motion systems shapes competitive positioning across dicing modalities.
- Saw Dicers:Mechanical blade systems achieve kerf widths down to 15 micrometers using diamond-impregnated wheels rotating above 60,000 RPM. Silicon wafer fabs in Taiwan and South Korea deploy these systems for memory die singulation where mature node economics favor proven mechanical processing.
- Laser Dicers:Ultrafast picosecond and femtosecond systems ablate material without thermal diffusion zones, enabling singulation of brittle silicon carbide substrates. Power semiconductor manufacturers in Germany and Japan are standardizing these platforms for automotive MOSFET production where mechanical blade chipping destroys device yield.
- Plasma Dicers:Dry etch singulation eliminates debris generation through chemical removal rather than physical fracture. MEMS foundries leverage these systems where suspended cantilever structures cannot survive mechanical or thermal stress.
- Water Jet Dicers:Abrasive slurry jet cutting addresses thick ceramic substrates and compound semiconductor wafers where blade loading causes cracking. Solar cell manufacturers utilize these systems for silicon wafer squaring before cell fabrication.
Saw dicers absorb the bulk of installed capacity; laser dicers are expanding most quickly.
End User:
Procurement authority concentrates at the foundry level, compressing vendor negotiation leverage and standardizing tool configurations across multiple fab sites.
- Semiconductor Manufacturers:Integrated device foundries and memory houses operate the highest tool utilization rates, with dicing steps multiplying under chiplet packaging roadmaps. TSMC and Samsung Foundry negotiate enterprise-wide equipment contracts spanning HBM and advanced logic lines.
- Electronics Firms:Module assemblers and subsystem manufacturers purchase dicing capacity for printed circuit board singulation and component trimming. These users prioritize throughput-per-square-meter over kerf width minimization.
- Research Institutions:University cleanrooms and national laboratories acquire flexible platforms supporting multiple substrate types. METI and NSF grant funding shapes equipment specifications for exploratory packaging research.
- OEMs:Captive semiconductor operations at automotive and industrial conglomerates maintain internal dicing capacity for proprietary power module designs. Bosch and Denso operate in-house SiC singulation lines to protect process intellectual property.
Semiconductor manufacturers absorb the bulk of installed capacity; OEMs are expanding most quickly.
Technology:
Cost tier differentiation separates capital-intensive plasma systems from blade platforms with lower per-wafer economics.
- Mechanical Dicing:Diamond blade abrasion dominates silicon wafer processing where decades of process development have optimized coolant chemistry and feed rate algorithms. EPA regulations on slurry discharge constrain facility siting decisions in the United States.
- Laser Technology:Solid-state and fiber laser architectures compete on beam quality and pulse duration. Adaptive optics integration enables real-time kerf steering for non-linear cutting paths required by fan-out wafer-level packaging.
- Plasma Technology:Inductively coupled plasma etch systems achieve sub-10 micrometer kerf widths with vertical sidewall profiles. Per-wafer processing costs remain elevated, restricting deployment to GaN RF devices and MEMS where yield sensitivity justifies premium economics.
- Water Jet Technology:High-pressure abrasive jet systems cut thick substrates without heat-affected zones. Solar ingot squaring and ceramic substrate processing represent primary demand concentrations.
Mechanical dicing absorbs the bulk of installed capacity; laser technology is expanding most quickly.
Application:
Volume concentration in integrated circuit singulation masks faster growth in emerging substrate categories.
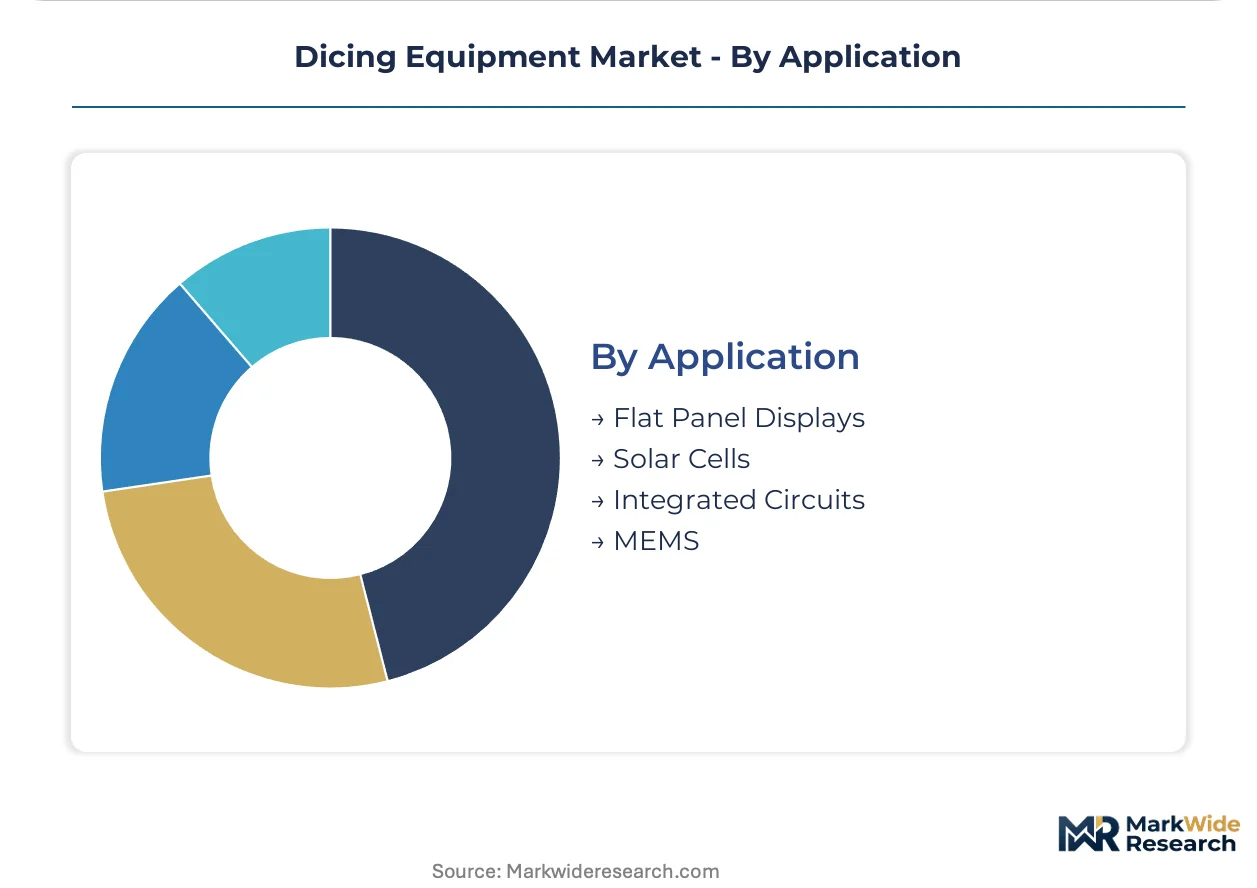
- Flat Panel Displays:Large-area substrate dicing requires extended travel motion platforms and specialized vacuum chuck designs. Korean display panel manufacturers drive demand for Gen 10.5+ mother glass singulation equipment.
- Solar Cells:Silicon wafer squaring and cell isolation utilize abrasive water jet and diamond wire systems. India's PLI scheme for solar manufacturing is stimulating equipment orders for domestic cell and module production.
- Integrated Circuits:Logic and memory die singulation represents the largest equipment installed base. Advanced packaging roadmaps at TSMC and Intel Foundry are compressing tolerances and multiplying dicing steps per finished wafer.
- MEMS:Micro-electromechanical systems demand contamination-free singulation preserving delicate suspended structures. Bosch and STMicroelectronics operate dedicated plasma dicing lines for accelerometer and gyroscope production.
Integrated circuits absorb the bulk of installed capacity; MEMS is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors the world's densest concentration of dicing equipment demand, with TSMC and United Microelectronics Corporation operating singulation lines for advanced logic and memory packaging.
South Korea
Samsung Electronics and SK Hynix drive laser dicing procurement for HBM3E and advanced DRAM packaging. The Ministry of Trade, Industry and Energy administers K-Chips Act tax credits for domestic equipment sourcing. Pyeongtaek and Yongin semiconductor clusters host the highest tool utilization rates for 200mm SiC wafer singulation.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor upstream material supply for blade dicing consumables. METI enforces 2027 energy efficiency standards that compress spindle motor R&D cycles. Kyoto-Osaka corridor equipment vendors redesign motion platforms to maintain qualification eligibility for domestic fabs.
United States
Intel Foundry and Texas Instruments expand dicing capacity for automotive power modules and defense-qualified components. The EPA regulates coolant discharge from abrasive slurry systems under Clean Water Act permits. Arizona's Phoenix metro corridor attracts equipment installations for CHIPS Act-funded fabs.
Germany
Bosch and Infineon operate captive SiC singulation lines for EV traction inverter production. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants in spindle cooling systems. Dresden's Silicon Saxony cluster concentrates plasma dicing deployment for GaN RF device manufacturing.
Dicing Equipment Market Competitive Environment
The competitive structure tilts toward precision spindle and motion control specialists. Japanese and German motor suppliers control 80% of ultra-high-speed spindle output above 60,000 RPM, creating single-source vulnerability for equipment assemblers. Three archetypes dominate: integrated platform vendors with in-house spindle production, modular subsystem suppliers licensing motion technology, and application-specific specialists converging laser and plasma modalities. Equipment vendors pursue M&A to secure spindle supply chains and form strategic partnerships with foundries for co-development roadmaps.
Among Japanese precision equipment specialists, DISCO Corporation, Panasonic Corporation, and Tokyo Seimitsu Co., Ltd. occupy positions defined by heritage in blade dicing, integrated motion systems, and metrology platforms respectively. DISCO exemplifies the integrated archetype through vertical control over diamond wheel consumables. Panasonic represents the subsystem-integrated model with captive spindle and motion platform development. Tokyo Seimitsu sits within the precision measurement tier, supplying inspection modules that converge with dicing platforms for closed-loop process control.
| Leading Market Players |
|---|
| Plasma-Therm LLC |
| Panasonic Corporation |
| DISCO Corporation |
| 3D-Micromac |
| Synova SA |
| Tokyo Seimitsu Co., Ltd. |
| Kulicke & Soffa Industries, Inc. |
| SUSS MicroTec |
| Advanced Dicing Technologies |
| Others |
Value Chain & Pricing Dynamics
Performance-grade bifurcation between sub-10-micrometer plasma systems and commodity blade platforms manifests in divergent pricing architectures and supply chain sourcing strategies. Premium laser-plasma hybrids command value-based contracts tied to die yield outcomes, while mechanical dicer procurement tracks spindle motor availability from Japanese and German captive suppliers.
Pricing Analysis
Yield-guarantee contracts anchor value-based pricing for laser dicing platforms serving silicon carbide power device manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates plasma systems with real-time metrology from blade platforms with fixed feed rates from entry-level refurbished units. Cost compression in mechanical dicing intensifies because South Korean memory houses consolidate procurement through enterprise-wide master service agreements. Foundry-level buyers exhibit lowest price sensitivity for kerf-width-critical applications, while electronics module assemblers prioritize throughput-per-square-meter over precision specifications.
Supply Chain Analysis
Ultra-high-speed spindle supply rests on Japanese and German specialty motor producers controlling output above 60,000 RPM. Diamond-impregnated blade consumables draw from Tokyo Electron and Shin-Etsu Chemical upstream material networks. Ceramic bearing assemblies and precision ball screws source from Switzerland and Japan. Single-source vulnerability in spindle motors creates qualification timeline risk for equipment assemblers seeking second-source approval. Distribution runs through foundry-level direct contracts displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision spindle capacity constraints prop pricing power for integrated platform vendors. Japanese and German motor suppliers throttle expansion, extending lead times for equipment qualification.
For Market Incumbents: Anchor market position through backward integration into spindle motor production or exclusive supply agreements with Nakanishi or Fischer Precise. Secure carbon-accounting certification for coolant and motion systems ahead of EU Green Deal Scope 3 disclosure mandates. Defend against modular subsystem suppliers by embedding AI-driven process control as standard platform features. For New Entrants and Emerging Players: Capture installation demand at India's emerging Gujarat and Dholera semiconductor clusters where first-mover equipment relationships form. Target MEMS foundry plasma dicing segments where per-wafer economics matter less than contamination-free processing. Pursue co-development partnerships with automotive power module manufacturers seeking captive SiC singulation capability. For Investors and Strategic Acquirers: Re-rating potential sits with laser-plasma hybrid specialists given convergence of ultrafast laser ablation with downstream plasma cleaning. Long-term viability favors vendors with in-house adaptive optics and real-time beam steering intellectual property. Watch qualification timeline extensions at Chinese fabs under expanded dual-use export controls as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Spindle Motor Backward Integration | Captive supply of 60,000+ RPM motors insulates DISCO and Panasonic from Japanese supplier concentration risk. |
| Laser-Plasma Hybrid Platform Launch | Converged ultrafast laser with plasma cleaning opens kerf-width performance gaps for GaN RF device manufacturers. |
| EU Green Deal Certification Investment | Lifecycle-certified low-carbon spindle systems qualify vendors for Scope 3 disclosure mandates at European fabs. |
| India Semiconductor Cluster Partnership | Early equipment installation at Micron Gujarat and Tata Electronics fabs establishes replacement part revenue streams. |
| Real-Time Metrology Integration | Inline ellipsometry for closed-loop depth control eliminates post-dice thickness verification at TSMC HBM lines. |
Study Parameters
Multi-period observation of equipment installation announcements, foundry capex disclosures, and spindle motor supplier order backlogs anchored the trend analysis, supplemented by interviews with precision equipment product managers, semiconductor fab process engineers, and aftermarket service directors. Primary fieldwork combined with secondary validation against SEMI equipment market data, METI industrial production statistics, and EPA enforcement actions on coolant discharge. Bottom-up triangulation across vendor shipment records and top-down reconciliation with foundry-level procurement databases established volume estimates.
Input-output matrices modeled equipment demand across product type, substrate material, and end-user application dimensions over the projection horizon. Segmentation analysis incorporated technology modality, kerf-width specification tier, and regional regulatory cluster. CAGRs derived from equipment replacement cycles, node migration timelines, and packaging step multiplication factors under chiplet roadmaps. Forecast inputs included SiC substrate capacity expansion announcements and EU F-Gas Regulation compliance deadlines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to dual-use export control expansion and clean energy mandate acceleration. Assumptions reflect current qualification timelines, spindle supplier capacity plans, and foundry procurement consolidation patterns. Export licensing delays, refrigerant phase-down schedules, and automotive power module demand volatility warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
Ion Beam Etching System Market
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market
Semiconductor Equipment
Multi-Touch Equipment Market
Semiconductor Equipment
Acid Filling and Leveling Machine Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Semiconductor Wafer Process Control Equipment Market
Semiconductor Equipment
Global Semiconductor Machinery Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Global Equipment Front End Module (EFEM) Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Cathode Stripping Machines Market
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
Epitaxy Equipment Market
Semiconductor Equipment
Global Semiconductor Photolithography Market