
 Middle-East and Africa Wind Power Market | 2026-2036
Middle-East and Africa Wind Power Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Wind Power Market Foresight
IEC 61400-1 certification for wind turbine design is rotating the competitive field in the Middle-East and Africa Wind Power Market, filtering out suppliers lacking validated load-case documentation for desert and coastal conditions. Siemens Gamesa Renewable Energy leverages its blade-testing facilities in the region to sustain qualification timelines that outpace rivals. Vestas Wind Systems A/S anchors its position through localized nacelle assembly partnerships that reduce import dependency. GE Renewable Energy competes on grid-forming inverter integration, a capability that differentiates its offering where weak transmission networks prevail.
Middle-East and Africa wind power encompasses the mechanical-to-electrical conversion infrastructure—turbines with rotor diameters exceeding 150 meters, doubly-fed induction generators, and pitch-control systems—deployed to harness kinetic atmospheric energy for grid-connected generation. The primary purpose is bulk electricity supply to national grids and industrial offtakers seeking cost hedging against volatile fuel imports. Horizontal axis technology dominates installed capacity due to mature supply chains and higher aerodynamic efficiency at utility scale, while offshore systems remain nascent pending seabed lease frameworks in the Red Sea and Mediterranean. Government Projects command disproportionate capital allocation because sovereign-backed procurement de-risks long-dated power purchase agreements for developers.
Saudi Arabia's National Renewable Energy Program and South Africa's REIPPPP framework shape auction design, tariff ceilings, and local-content thresholds that determine developer returns. Egypt's New and Renewable Energy Authority and Morocco's MASEN enforce grid-code compliance and environmental impact standards that extend project development timelines. Stakeholders must monitor how currency convertibility guarantees and offtaker creditworthiness evolve across jurisdictions where macroeconomic volatility threatens project finance structures.
Market Dynamics
Utility-scale procurement auctions under Saudi Arabia's National Renewable Energy Program are compressing developer margins while accelerating project pipeline maturation across the Middle-East and Africa.
Growth Catalysts
- REIPPPP auction rounds:South Africa's renewable energy procurement framework de-risks long-dated power purchase agreements for independent power producers.
- Egypt's Gulf of Suez zone:Grid interconnections with Saudi Arabia and superior wind resource quality concentrate developer capital allocation.
- Grid-forming inverter integration:Weak transmission networks in rural Morocco and Jordan create pull for advanced power electronics that stabilize voltage frequency.
Market Restraints
- Currency convertibility volatility:Egyptian pound and Nigerian naira depreciation threaten dollar-denominated debt service for project finance structures.
- Blade resin supply concentration:Epoxy and carbon fiber precursor manufacturing clusters in China expose turbine OEMs to shipping cost spikes and tariff uncertainty.
- Desert sand erosion:Abrasive particulate loading degrades leading-edge aerodynamics faster than IEC 61400-1 design assumptions anticipate.
Strategic Opportunities
- Red Sea offshore leasing:Seabed framework development in Egyptian and Saudi waters opens capacity factors exceeding 45% for floating foundation pilots.
- Green hydrogen offtake:NEOM and Ain Sokhna industrial zones create anchor demand for curtailed wind generation at sub-transmission voltage.
- Local-content thresholds:Morocco's MASEN nacelle assembly mandates force technology transfer that builds indigenous O&M capability.
Industry Challenges
- Grid-code compliance timelines:Egypt's New and Renewable Energy Authority extends permitting by 8-14 months for frequency ride-through testing.
- Specialized technician scarcity:Blade repair and high-voltage termination skills concentrate in South Africa and Turkey, leaving Saudi and UAE projects dependent on expatriate labor.
- Spare parts inventory fragmentation:Pitch bearing and yaw drive lead times from European suppliers mismatch EPC construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Wind Power Market |
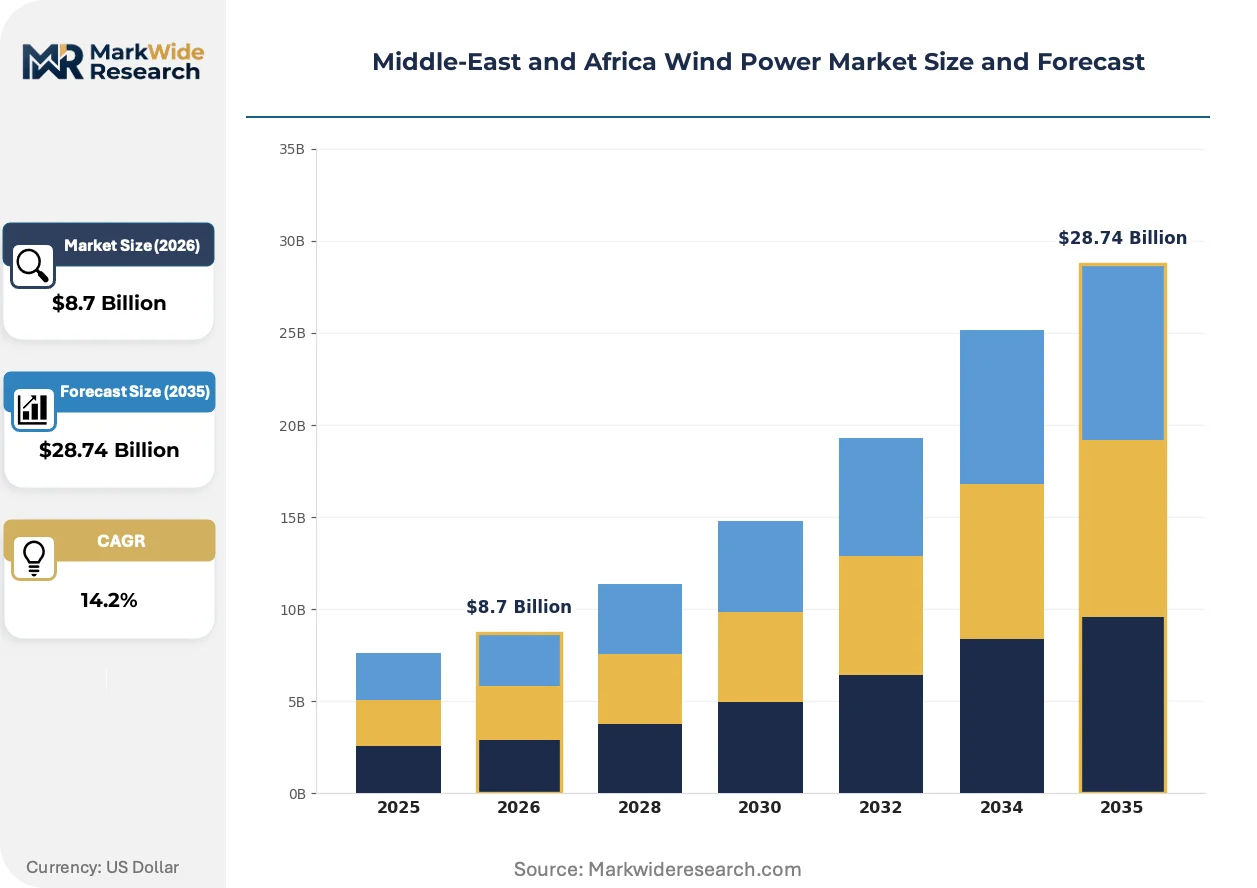
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbines, Generators, Control Systems, Accessories Technology: Horizontal Axis, Vertical Axis, Offshore, Onshore Capacity: Small, Medium, Large, Ultra-large End User: Utilities, Industrial Users, Government Projects, Commercial Installations |
| Companies Covered | Siemens Gamesa Renewable Energy, Vestas Wind Systems A/S, GE Renewable Energy, Goldwind, Envision Energy, Nordex, ACWA Power, Masdar, Enercon, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Wind Power Market Shifts & Advancements
Technology trajectories in the Middle-East and Africa wind power market center on turbine scaling, auction mechanism refinement, and procurement model evolution that reward operational flexibility over pure capacity addition.
Segmented blade designs using bolted root connections are fragmenting the transport logistics constraint that previously limited rotor diameters to 140 meters for desert-accessible sites. EPC contractors in Egypt and Saudi Arabia now specify 170-meter rotors for Gulf of Suez projects. The technology is fragmenting the historical trade-off between energy yield and site accessibility that favored smaller machines in infrastructure-constrained markets.
Saudi Arabia's National Renewable Energy Program introduced dynamic tariff ceilings that adjust for local-content achievement and grid-stabilization capability. The mechanism rewards developers who integrate synchronous condensers or battery storage alongside wind capacity. Moroccan and Jordanian regulators are studying similar auction designs to improve network resilience.
Industrial offtakers in phosphate mining and desalination are unbundling power purchase agreements from asset ownership, preferring tolling structures where developers retain merchant exposure and offtakers pay variable energy charges. The model concentrates credit risk with developers while freeing industrial balance sheets from long-term liabilities. Egypt's aluminum smelters and South Africa's platinum miners are piloting these structures.
Middle-East and Africa Wind Power Market Segmentation
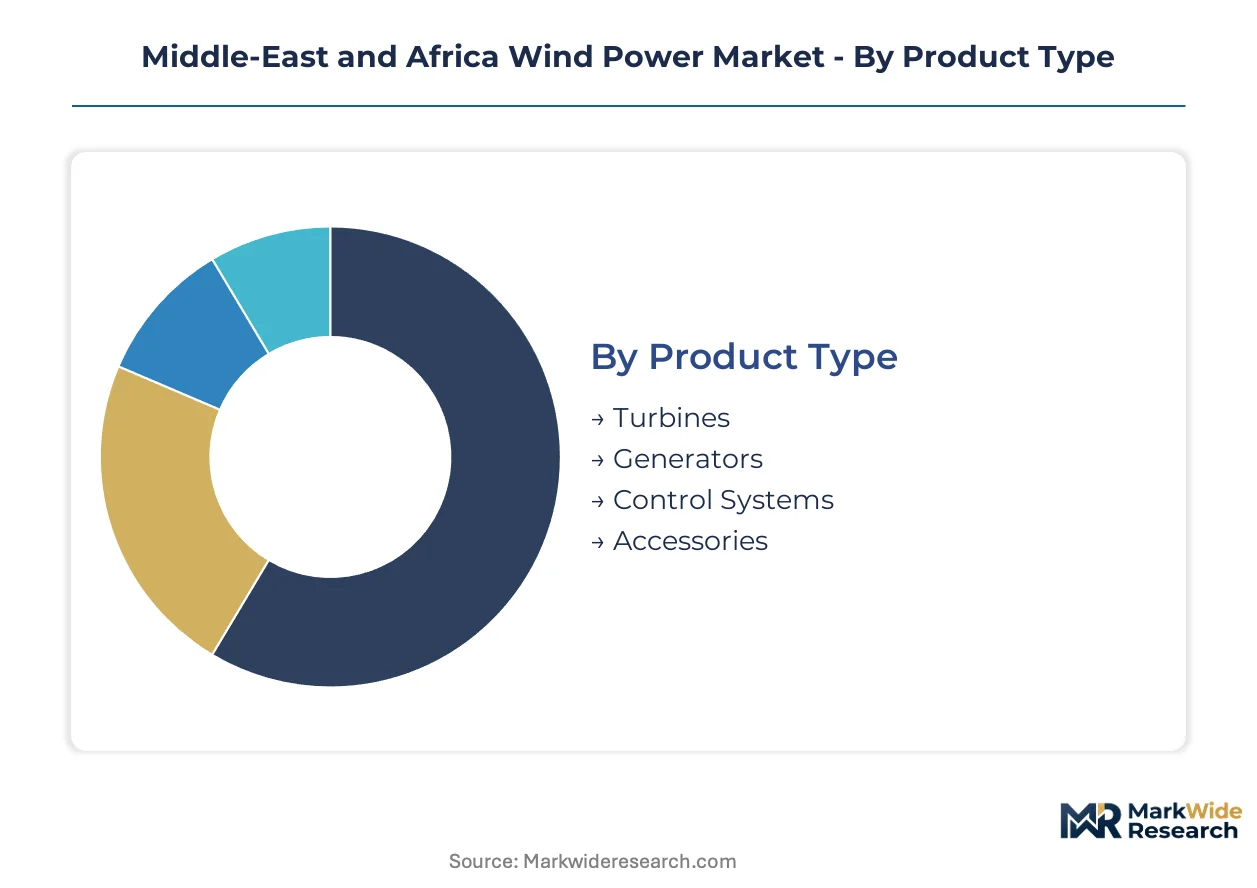
Wind power segmentation in the Middle-East and Africa reveals how technology choices and procurement models align with grid infrastructure constraints and sovereign energy diversification mandates. Distinct equipment categories and deployment scales face varying degrees of competition from solar PV and natural gas peaking plants.
Product Type:
Substitute pressure from solar PV modules is most acute for Accessories and Control Systems, where battery inverters and power electronics overlap functionally with wind-specific components.
- Turbines:Rotor assemblies exceeding 150 meters in diameter with doubly-fed induction generators dominate utility-scale procurement in Egypt's Gulf of Suez zone. Saudi Arabia's National Renewable Energy Program specifications favor turbines with sand-resistant blade coatings and extended temperature operating ranges.
- Generators:Synchronous and asynchronous generator sets rated above 3 MW anchor project economics in Morocco's wind corridors. Grid-forming capabilities differentiate premium offerings where weak transmission networks in rural Jordan require voltage frequency stabilization.
- Control Systems:Pitch and yaw automation hardware with IEC 61400-1 compliant load-case algorithms commands premium positioning.
- Accessories:Transformers, switchgear, and foundation hardware complete installation packages.
Turbines retain volume leadership; Control Systems holds the steepest expansion curve.
Technology:
Cost tier stratification separates mature onshore deployments from nascent offshore pilots requiring floating foundation engineering.
- Horizontal Axis:Upwind rotor configurations with three blades capture over 95% of installed capacity across South Africa's REIPPPP rounds and Egypt's New and Renewable Energy Authority concessions. Aerodynamic efficiency advantages and established supply chains reinforce dominance despite higher transport logistics costs for 170-meter rotors.
- Vertical Axis:Darrieus and Savonius designs serve distributed micro-generation in remote Moroccan agricultural zones and UAE commercial installations where noise restrictions and omni-directional wind capture outweigh efficiency penalties.
- Offshore:Floating foundation pilots in Red Sea waters await seabed lease framework finalization.
- Onshore:Ground-mounted installations across Saudi Arabia's central plateau and Jordan's Tafila corridor constitute the deployable base.
Onshore dominates current procurement; Offshore represents the steepest expansion trajectory pending regulatory clarity.
Capacity:
Application scale determines financing structure complexity, with utility-scale projects accessing sovereign-backed power purchase agreements unavailable to smaller installations.
- Small:Systems below 100 kW serve rural electrification in Nigeria's northern states and Kenya's pastoral regions where grid extension remains uneconomical. Diesel generator displacement drives demand despite higher per-kW capital costs.
- Medium:100 kW to 1 MW installations anchor commercial and industrial offtake in South African mining operations and Egyptian desalination plants.
- Large:1 MW to 3 MW machines constitute the procurement sweet spot for Jordanian and Moroccan utility tenders.
- Ultra-large:Turbines exceeding 3 MW with rotor diameters above 150 meters concentrate in Saudi Arabia's Dumat Al Jandal and Egypt's Gulf of Suez developments.
Large capacity retains volume leadership; Ultra-large holds the steepest expansion curve as auction mechanisms reward scale economies.
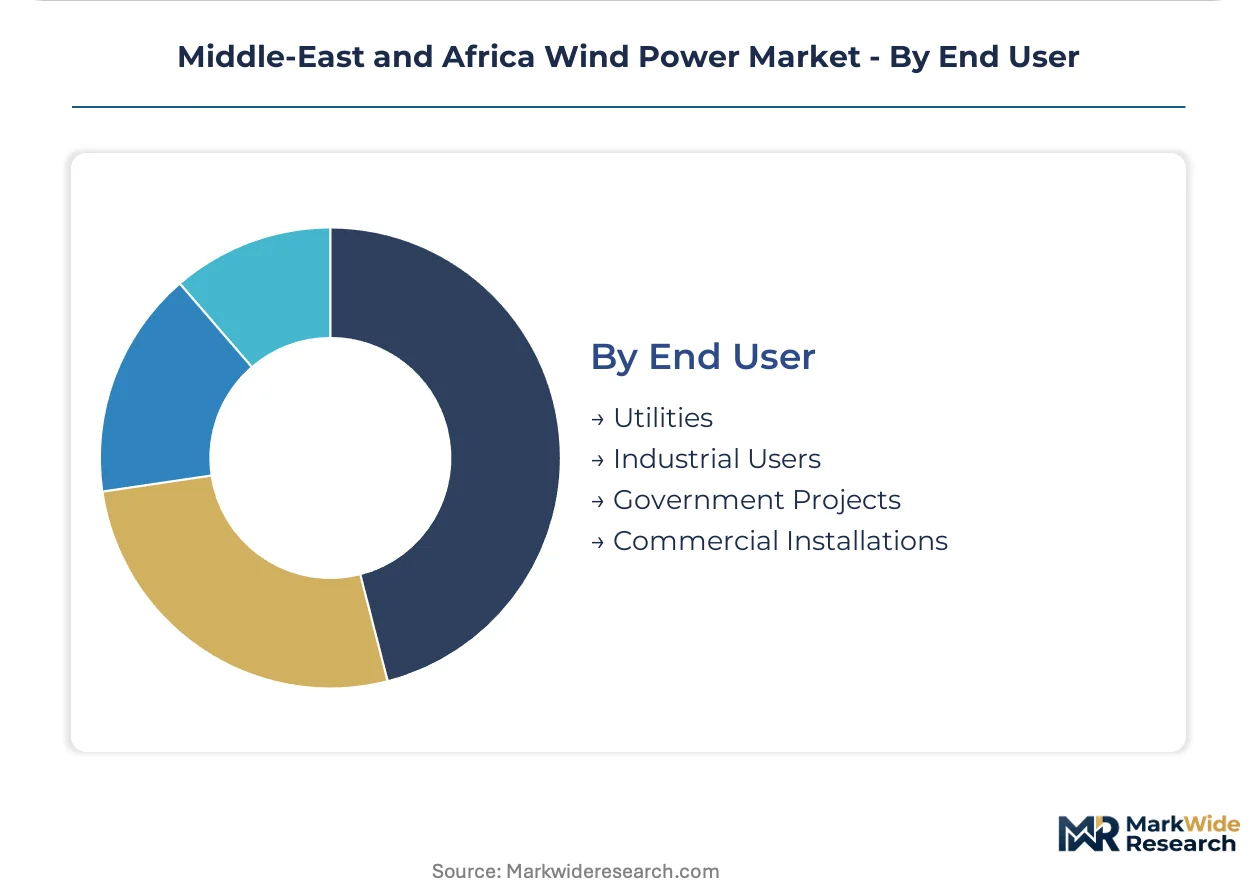
End User:
Customer type dictates risk allocation, with sovereign-backed procurement de-risking long-dated revenue streams that merchant-exposed industrial offtakers cannot replicate.
- Utilities:National grid operators in Saudi Arabia, Egypt, and South Africa dominate capacity procurement through competitive auctions. Saudi Arabia's National Renewable Energy Program and South Africa's REIPPPP framework standardize 20-25 year power purchase agreement tenors that attract international project finance.
- Industrial Users:Phosphate miners in Morocco, aluminum smelters in Egypt, and platinum producers in South Africa pilot tolling structures where developers retain merchant exposure. Variable energy charges replace fixed capacity payments, concentrating credit risk with equipment suppliers.
- Government Projects:Sovereign-backed installations in UAE federal buildings and Saudi municipal facilities prioritize local-content achievement over pure cost minimization.
- Commercial Installations:Shopping malls, data centers, and desalination plants in UAE and Qatar pursue behind-the-meter generation with grid backup.
Utilities retain volume leadership; Industrial Users hold the steepest expansion curve as tolling structures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility buyers concentrate procurement authority within national renewable energy programs that standardize auction terms and de-risk long-dated power purchase agreements. Sovereign-backed offtakers dominate capital allocation decisions across the region's wind corridors.
Saudi Arabia
Dumat Al Jandal and Yanbu wind clusters anchor the kingdom's 16 GW renewable target under the National Renewable Energy Program. The Energy Regulatory Authority sets dynamic tariff ceilings that reward local-content achievement and grid-stabilization capability. NEOM's northwestern development zone pilots floating foundation designs for Red Sea offshore expansion.
Egypt
Gulf of Suez wind farms attract developer capital through superior capacity factors and grid interconnections with Saudi Arabia. The New and Renewable Energy Authority enforces IEC 61400-1 compliance and extends permitting timelines for frequency ride-through testing. Ain Sokhna industrial zone anchors green hydrogen offtake demand for curtailed wind generation.
South Africa
Platinum miners and manganese smelters pilot tolling structures that concentrate merchant exposure with developers. The Renewable Energy Independent Power Producer Procurement Programme standardizes 20-year power purchase agreement tenors that attract international project finance. Eastern Cape wind corridors face transmission congestion that delays grid connection for completed projects.
Morocco
Phosphate mining operations and desalination plants drive industrial offtake in Tarfaya and Essaouira wind zones. MASEN enforces nacelle assembly mandates that force technology transfer and build indigenous O&M capability. Ouarzazate's renewable energy cluster hosts blade repair facilities that reduce expatriate technician dependency.
Jordan
Tafila and Maan wind corridors serve weak rural transmission networks that require grid-forming inverter integration. The Ministry of Energy and Mineral Resources awards concessions through competitive tenders with local-content thresholds. Industrial zones near Aqaba port concentrate EPC contractor activity for cross-border equipment logistics.
Middle-East and Africa Wind Power Market Competitive Landscape
Player mix skews toward European turbine OEMs with established desert-certification capabilities and Gulf-based independent power producers with sovereign balance-sheet backing. Market structure consolidates around three strategic archetypes: integrated turbine manufacturers with blade-testing facilities, regional IPPs with auction-winning track records, and Chinese suppliers competing on rotor-scale economics. Dominant competitive moves include localized nacelle assembly partnerships and grid-forming inverter integration for weak-network stabilization.
Within the integrated manufacturer tier, Siemens Gamesa Renewable Energy and Vestas Wind Systems A/S exemplify archetypes that have built regional qualification timelines through blade-testing infrastructure and load-case documentation for desert conditions. GE Renewable Energy occupies a differentiated position on power electronics integration. Among Gulf-based developers, ACWA Power and Masdar anchor the IPP archetype with auction-winning capacity in Saudi Arabia and Egyptian concessions.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy |
| Vestas Wind Systems A/S |
| GE Renewable Energy |
| Goldwind |
| Envision Energy |
| Nordex |
| ACWA Power |
| Masdar |
| Enercon |
| Others |
Supply & Pricing Matrix
Sixteen-week lead times for pitch bearings from European suppliers concentrate pricing power with incumbent turbine OEMs while compressing EPC contractor margins across Egyptian and Saudi developments. This inventory mismatch between component availability and construction schedules forces developers into premium expedited freight arrangements that inflate installed costs.
Pricing Analysis
Cost-plus contracts with steel and resin indexation dominate turbine supply agreements under Saudi Arabia's National Renewable Energy Program. Price differentiation hinges on IEC 61400-1 certification tier and local-content achievement levels that unlock tariff premiums. Cost compression in the ultra-large turbine segment is intensifying because Chinese suppliers are undercutting European OEMs on rotor-scale economics. Industrial offtakers in phosphate mining and aluminum smelting exhibit the highest price sensitivity, while sovereign-backed utilities prioritize grid-stabilization capability over pure cost minimization.
Supply Chain Analysis
China and Germany anchor blade resin and carbon fiber precursor manufacturing, while Denmark and Spain concentrate nacelle assembly and control system production. Turbine OEMs draw from epoxy formulations, rare-earth permanent magnets, and specialized bearing steel that feed from concentrated chemical and metallurgical supply bases. Single-source vulnerability in carbon fiber tow supply exposes the industry to shipping cost spikes through the Suez Canal. Distribution runs through EPC contractors with established logistics footprints in Jeddah and Aqaba port zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service contracts for blade erosion repair and predictive maintenance are expanding faster than hardware sales as desert operating conditions accelerate component degradation cycles.
For Market Incumbents: Consolidate blade-testing infrastructure and localized nacelle assembly partnerships to defend against Chinese suppliers competing on rotor-scale economics. Deepen backward integration into sand-resistant coating formulation to capture margin that currently flows to specialty chemical providers. Prioritize IEC 61400-1 certification maintenance as regulatory authorities extend compliance timelines. For New Entrants and Emerging Players: Anchor in Red Sea offshore leasing frameworks where floating foundation engineering creates white-space opportunity beyond established onshore corridors. Target Egyptian and Saudi industrial zones with green hydrogen offtake demand for curtailed wind generation. Pursue tolling structure partnerships with phosphate miners and aluminum smelters seeking variable energy charges without balance-sheet liability. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across the ultra-large turbine segment as modular blade designs reduce transport logistics costs. Long-term viability favors developers with auction-winning track records under sovereign-backed procurement programs rather than merchant-exposed industrial offtake structures. Monitor seabed lease framework finalization in Egyptian and Saudi waters as the primary inflection signal for offshore capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Nacelle Assembly Partnerships | Morocco's MASEN mandates force technology transfer that builds indigenous O&M capability and reduces import dependency. |
| Grid-Forming Inverter Integration | Weak transmission networks in rural Jordan and Morocco create pull for advanced power electronics that stabilize voltage frequency. |
| Floating Foundation Pilot Development | Red Sea seabed frameworks in Egyptian and Saudi waters open capacity factors exceeding forty-five percent for offshore expansion. |
| Green Hydrogen Offtake Agreements | NEOM and Ain Sokhna industrial zones anchor demand for curtailed wind generation at sub-transmission voltage levels. |
| Blade Erosion Repair Service Contracts | Desert sand loading degrades leading-edge aerodynamics faster than design assumptions, accelerating aftermarket revenue capture. |
Research Methodology
A standing panel of utility planning officers, IPP project developers, EPC contractors, and grid operators provided ongoing calibration across primary interview rounds. Secondary validation drew from IEA wind energy outlooks, EIA international energy data, national renewable energy program auction disclosures, and project finance database tracking. Bottom-up installation forecasts triangulated against top-down capacity targets issued by Saudi Arabia's Energy Regulatory Authority, Egypt's New and Renewable Energy Authority, and South Africa's Department of Mineral Resources and Energy.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by turbine capacity tier, technology type, end-user category, and regional regulatory framework. CAGRs were derived from regression analysis of auction-awarded capacity against historical commissioning timelines. Forecast inputs incorporated grid interconnection queue depths, currency convertibility risk assessments, and local-content threshold evolution.
Material uncertainties — currency depreciation in Egyptian and Nigerian markets, blade resin supply disruption, and seabed lease framework delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding sovereign offtaker creditworthiness and power purchase agreement tenor standardization. Recalibration cycles align with material shifts in auction mechanism design and macroeconomic volatility indicators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
Brazil Wind Energy Market
Wind Energy Systems
Germany Offshore Wind Energy Market
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
Wind Energy Rescue System Market
Wind Energy Systems
Wind Turbine Blades Market
Wind Energy Systems
Portugal Wind Energy Market
Wind Energy Systems
Dual Rotor Wind Turbine Market
Wind Energy Systems
Iran Wind Energy Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
Wind Turbine Decommissioning Market
Wind Energy Systems
Japan Wind Energy Market
Wind Energy Systems
Sweden Wind Energy Market
Wind Energy Systems
Wind Power Forgings Market
Wind Energy Systems
Europe Wind Power Equipment Market