
 Wind Tower Market | 2026-2036
Wind Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Tower Market Intelligence
Aftermarket service revenue is tilting from corrective maintenance toward predictive analytics and lifetime extension contracts. GE Vernova leverages its digital twin platform to anchor long-term service agreements across installed fleets. Vestas Wind Systems A/S sustains competitive positioning through vertical control over blade-to-tower integration. Siemens Gamesa Renewable Energy specializes in offshore-specific corrosion protection and logistics solutions that command premium contract terms.
A wind tower is a steel or concrete structural column that supports the nacelle and rotor assembly of a wind turbine, typically fabricated from rolled steel plates welded into tapered tubular sections with wall thicknesses ranging from 20 to 50 millimetres and hub heights now exceeding 150 metres for onshore installations. Its primary purpose is to elevate the rotor into stronger, less turbulent wind streams while transferring mechanical loads to foundation structures. Tubular steel towers dominate installed capacity due to manufacturing scalability, though concrete and hybrid designs are capturing share in markets where transport constraints limit single-piece steel delivery. The above 5 MW capacity bracket represents the fastest-growing segment as offshore projects scale turbine ratings, while lattice towers retain niche positions in remote power generation where low-cost deployment outweighs aesthetic considerations.
DNV standards for offshore wind structures, IEC 61400 design requirements, and national building codes in Germany, China, and the United States collectively govern tower certification, fatigue testing, and foundation interface specifications. These frameworks lengthen project development timelines but create barriers that favour manufacturers with established certification track records and in-house testing capabilities. Stakeholders must monitor evolving hub-height regulations, emerging recyclability mandates for steel composites, and port infrastructure bottlenecks that could constrain tower delivery logistics regardless of manufacturing capacity expansion.
Market Dynamics
Offshore wind farm developers are procuring larger-capacity towers that exceed 150 metres in hub height, forcing fabricators to retool coastal facilities for thicker steel plate rolling and modular transport logistics.
Growth Catalysts
- EU Green Deal:Binding renewable targets in Germany, Spain, and Denmark are accelerating auction volumes for North Sea offshore zones, tightening steel sourcing standards for tower fabricators.
- Concrete hybrid designs:Transport-constrained markets in Brazil and India are adopting on-site concrete pouring methods that bypass single-piece steel delivery limitations.
- Great Lakes corridor:Freshwater offshore projects in Michigan and Ontario are creating dedicated manufacturing clusters with ice-load engineering capabilities.
Market Restraints
- Steel plate volatility:Heavy plate prices fluctuate with scrap metal and energy input costs, compressing fabrication margins for independent tower suppliers without captive rolling mills.
- Port infrastructure concentration:North Sea and East Asian offshore zones depend on a limited number of deep-water assembly harbours with heavy-lift crane capacity.
- Fatigue testing timelines:DNV and IEC 61400 certification protocols extend project development cycles by 12-18 months, favouring incumbents with established testing track records.
Strategic Opportunities
- United States offshore expansion:The Inflation Reduction Act production tax credits are unlocking Atlantic Coast projects from Massachusetts to Virginia with domestic content requirements.
- Recyclability mandates:Emerging EU steel composite recycling regulations will reward fabricators with closed-loop material recovery systems and design-for-disassembly protocols.
- Digital twin integration:Convergence of sensor hardware and predictive analytics platforms is enabling lifetime extension contracts that capture 15-20 year revenue streams per installed tower.
Industry Challenges
- Welding technician scarcity:Thick-plate submerged arc welding for offshore towers requires certified specialists that coastal manufacturing clusters in Germany and China struggle to retain.
- Foundation interface complexity:Transition piece engineering for monopile and floating substructures demands simultaneous coordination with marine contractors, compressing installation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Tower Market |
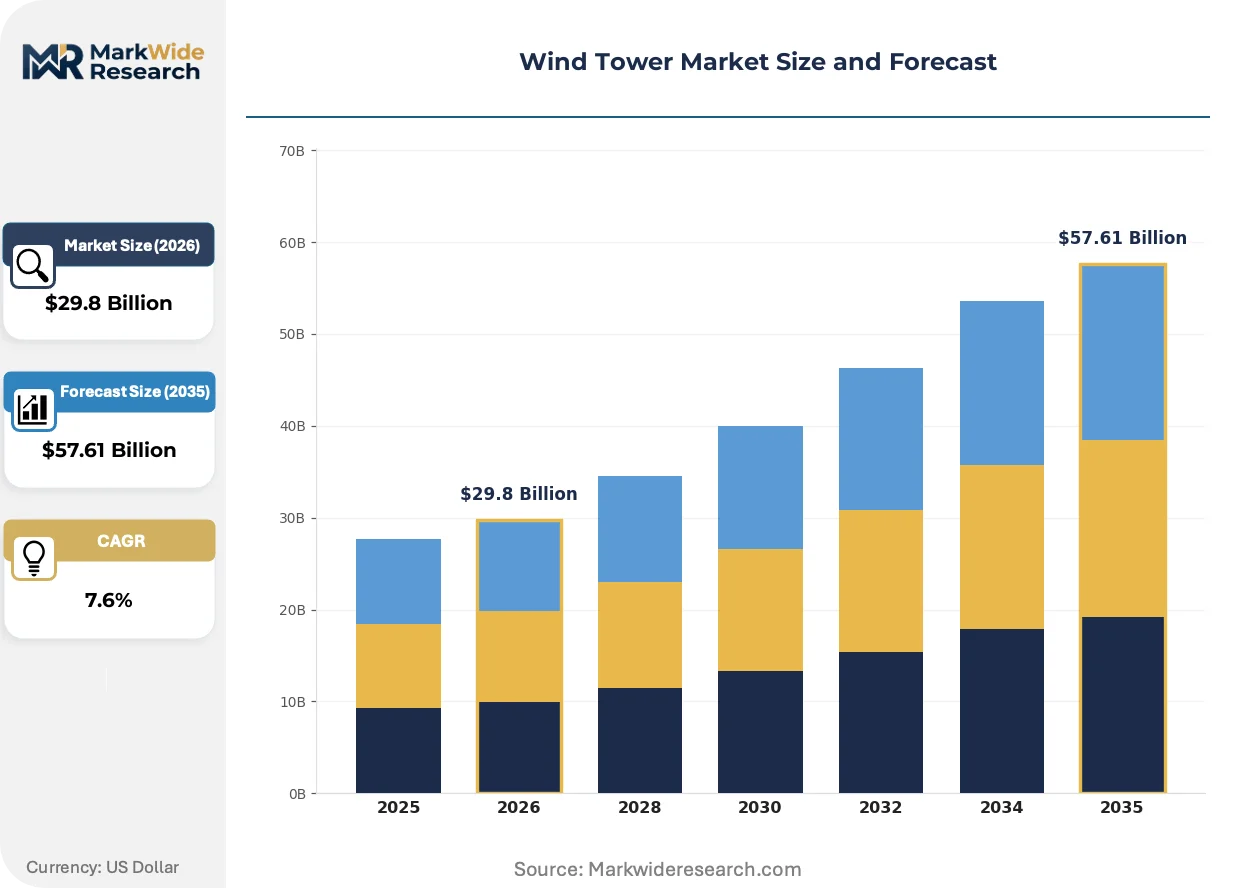
| Market Size in 2026 | $29.8 Billion |
| Market Size in 2035 | $57.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tubular, Lattice, Concrete, Hybrid Capacity: Under 1 MW, 1-3 MW, 3-5 MW, Above 5 MW Application: Onshore Wind Farms, Offshore Wind Farms, Remote Power Generation, Telecom Towers End User: Energy Developers, Independent Power Producers, Renewable Project Contractors, Utilities |
| Companies Covered | GE Vernova, Nordex SE, Vestas Wind Systems A/S, Envision Energy, Mingyang Smart Energy, Siemens Gamesa Renewable Energy, ENERCON GmbH, Sany Renewable Energy Co., Ltd., Goldwind, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Tower Market Strategic Shifts & Innovations
Steel-concrete hybrid tower technology is fragmenting the supplier landscape as fabricators choose between rolled tubular specialisation and on-site concrete integration capabilities.
Concrete-steel hybrid tower systems are hybridizing traditional fabrication models by combining lower steel sections with upper concrete segments that cure at project sites. Offshore developers in transport-constrained markets are piloting these designs to bypass road width and bridge load limits. The technology is hybridizing supply chain geography, shifting production from centralised coastal mills toward distributed regional batching plants.
DNV's updated offshore wind structural standards are mandating enhanced corrosion protection coatings and fatigue-resistant weld geometries for North Sea installations. Fabricators must retool inspection protocols and invest in automated ultrasonic testing equipment. Tower suppliers with in-house metallurgical laboratories are capturing premium contract terms from Danish and German project developers.
Buyers are unbundling tower supply from full-turbine procurement, creating direct contracting relationships with specialised fabricators. Independent tower manufacturers in China and South Korea are securing standalone orders from European and North American developers. This pattern is most visible in offshore auctions where project sponsors seek to optimise capital stacks through component-level financing.
Wind Tower Market Segmentation
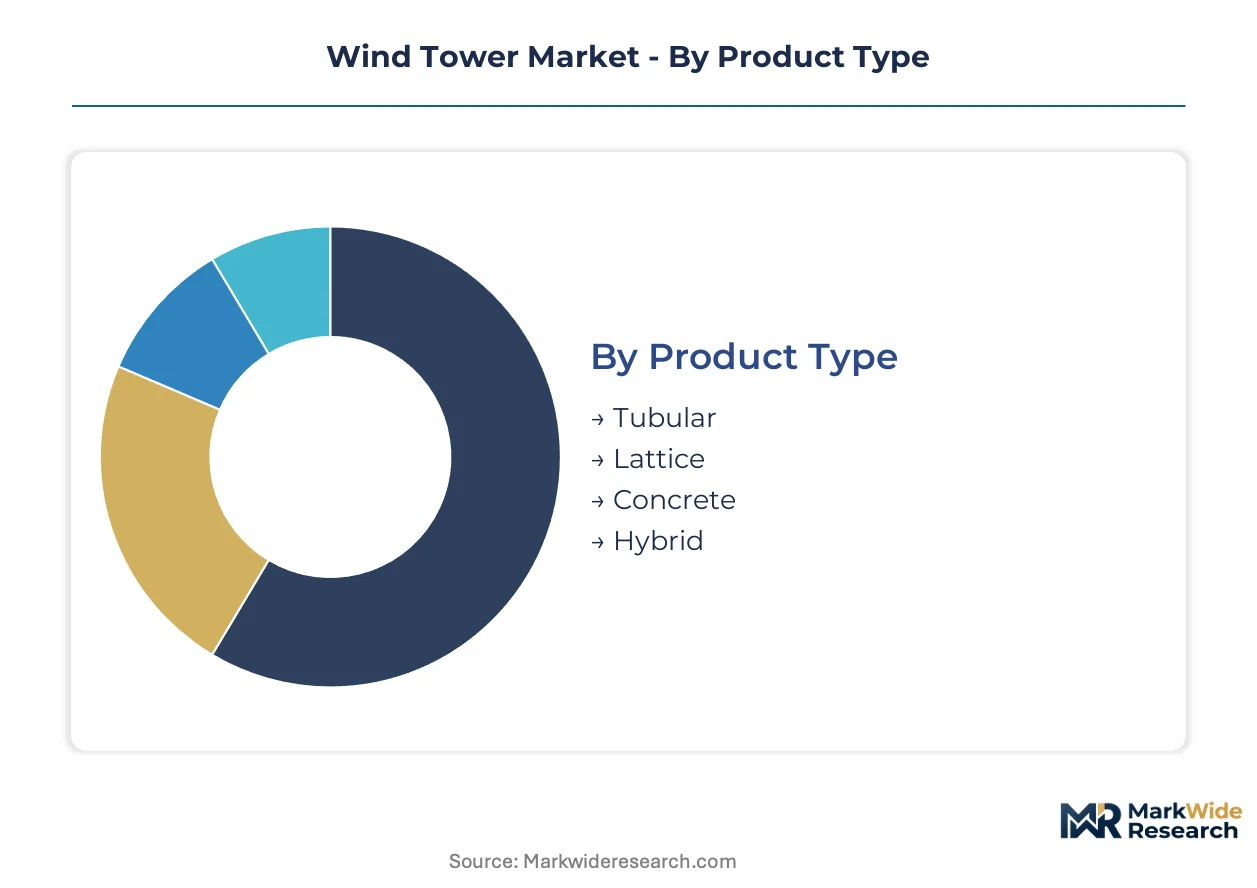
Wind tower segmentation reveals how fabrication economics, turbine scaling, and site constraints fragment procurement strategies across the value chain. Each dimension—product form, capacity rating, deployment setting, and buyer type—carries distinct certification burdens and margin structures that reshape supplier selection criteria.
Product Type:
Cost tier differentiation separates mass-producible steel designs from site-poured alternatives that trade capital intensity for logistics flexibility.
- Tubular:Rolled steel plates welded into tapered cylindrical sections with wall thicknesses of 20-50 millimetres. North Sea and East Asian offshore clusters demand these for their manufacturing scalability and established DNV certification pathways.
- Hybrid:Lower steel sections paired with upper concrete segments cured on-site. Transport-constrained markets in Brazil and India adopt these to bypass road width limits and bridge load restrictions.
- Lattice:Triangular steel truss configurations requiring less material tonnage per metre of height. Remote power generation sites in sub-Saharan Africa and Central Asia specify these where low-cost deployment outweighs aesthetic objections.
- Concrete:Reinforced or pre-stressed concrete monopours fabricated at dedicated batching plants. German onshore repowering projects and Chinese desert installations use these where steel price volatility threatens project returns.
Tubular towers anchor the installed base across coastal manufacturing clusters. Hybrid configurations are climbing the fastest as logistics bottlenecks spread beyond emerging markets into European transport corridors.
Capacity:
Volume concentration tracks turbine scaling curves, with fabrication investment thresholds rising disproportionately above the 5 MW threshold.
- Above 5 MW:Hub heights exceeding 150 metres with nacelle loads requiring 50+ millimetre plate thicknesses. North Sea offshore auctions in Germany and Denmark specify these ratings, forcing retooling at coastal mills for modular transport logistics.
- 3-5 MW:Mid-scale ratings dominating Great Lakes freshwater projects and Chinese intertidal zones. Michigan and Ontario developers favor this bracket for ice-load engineering compatibility with existing port infrastructure.
- 1-3 MW:Established ratings for distributed onshore repowering in Spain and Italy. These leverage existing supply chains without demanding new submerged arc welding certification programs.
- Under 1 MW:Legacy ratings concentrated in remote telecom and rural electrification applications. African and Southeast Asian mini-grid operators specify these where grid connection costs exceed generation asset economics.
The 3-5 MW bracket holds the established volume position. Above 5 MW ratings are expanding most quickly as floating foundation designs unlock deeper water sites.
Application:
Geography and regulatory exposure split demand between coastal offshore zones with premium certification requirements and inland corridors with transport-dominated economics.
- Offshore Wind Farms:Salt-laden environments demanding enhanced corrosion protection and fatigue-resistant weld geometries under DNV standards. Danish and German project developers pay premium contract terms for towers with in-house metallurgical testing capabilities.
- Onshore Wind Farms:Established applications spanning Texas plains, Chinese northern deserts, and Brazilian savanna corridors. These concentrate procurement at rolling mills with captive steel plate supply to hedge input cost volatility.
- Remote Power Generation:Mini-grid and industrial captive power in mining and agricultural processing. Australian and Chilean mining operators specify these for diesel displacement at off-grid extraction sites.
- Telecom Towers:Secondary application repurposing wind tower fabrication capacity for cellular and microwave infrastructure. Indian and Indonesian tower sharing companies source these where renewable mandates intersect with connectivity expansion programs.
Onshore installations retain the volume base across continental manufacturing corridors. Offshore applications are gaining share fastest as auction pipelines in Massachusetts, Virginia, and Taiwan accelerate.
End User:
Customer type determines contracting structure, with integrated turbine OEMs competing against independent fabricators for direct project sponsor relationships.
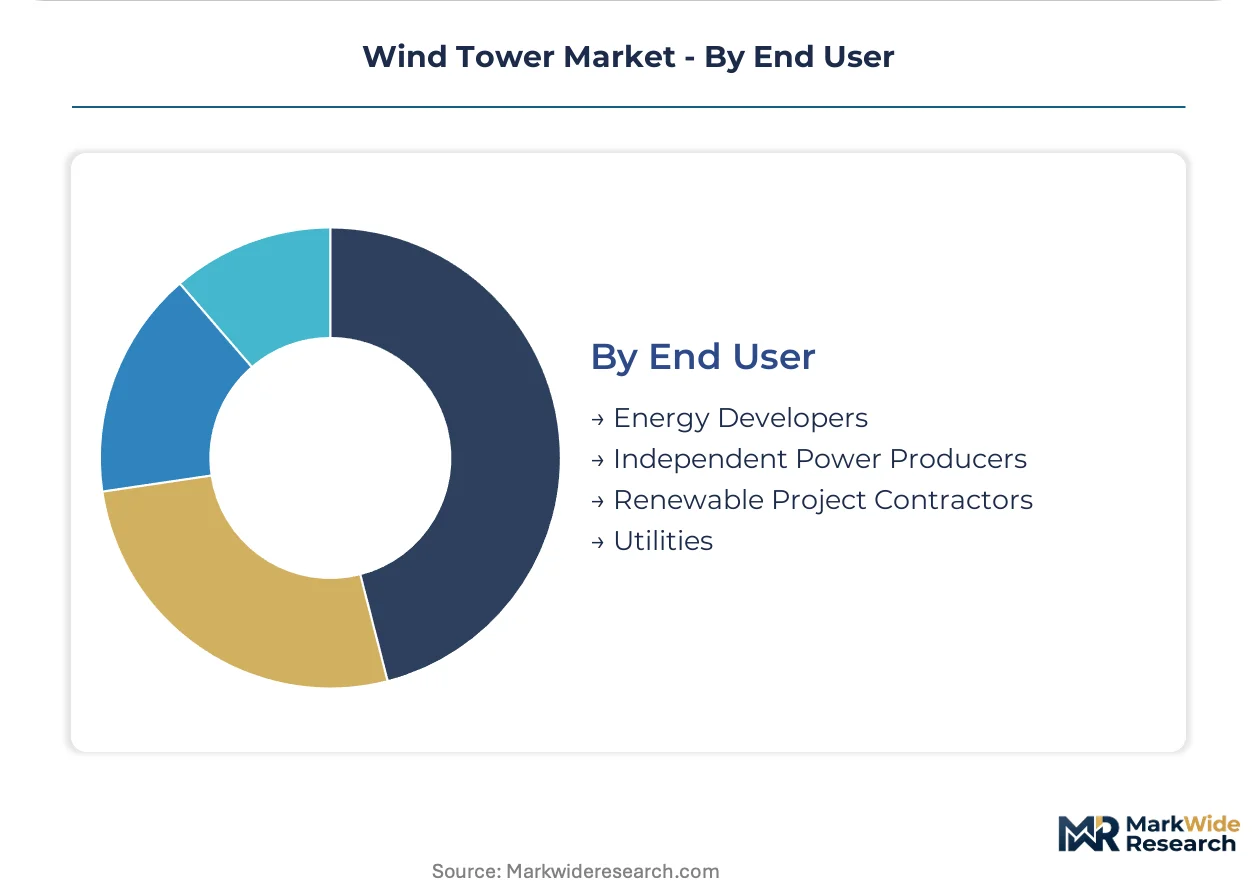
- Energy Developers:Project sponsors unbundling tower supply from full-turbine procurement to optimize capital stacks through component-level financing. Atlantic Coast developers from Massachusetts to Virginia pursue this structure under Inflation Reduction Act domestic content requirements.
- Utilities:Vertically integrated grid operators with captive engineering and procurement capabilities. German and Spanish utilities leverage long-term steel supply agreements to compress fabrication margins.
- Independent Power Producers:Financial investors without in-house technical teams, relying on turnkey engineering-procurement-construction contracts. These favor established fabricators with complete certification track records to satisfy lender due diligence.
- Renewable Project Contractors:Engineering firms assembling project-specific supply chains without long-term manufacturing assets. These drive spot-market demand volatility as they chase auction timelines across multiple geographies simultaneously.
Utilities and established developers command the procurement base through long-term framework agreements. Direct contracting by independent power producers is climbing fastest as offshore project finance structures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Brazil exhibit acute price sensitivity to steel plate volatility, while German and Danish offshore developers prioritize certification track records over unit cost. This elasticity divergence fragments procurement strategies across manufacturing clusters.
United States
Atlantic Coast developers from Massachusetts to Virginia are accelerating tower procurement under Inflation Reduction Act production tax credits with domestic content requirements. FERC interconnection queues and state-level renewable portfolio standards in New York and New Jersey are compressing project timelines. The Great Lakes corridor around Michigan and Ontario anchors freshwater offshore manufacturing with ice-load engineering capabilities.
Germany
North Sea auction volumes are tightening steel sourcing standards under EU Green Deal binding renewable targets. DNV offshore wind structural standards and national building codes mandate enhanced corrosion protection coatings. Coastal fabrication clusters in Bremerhaven and Cuxhaven are retooling for modular transport logistics serving Danish and German joint development zones.
China
East Asian offshore zones in Jiangsu and Fujian provinces are scaling procurement of above-5 MW towers with 50+ millimetre plate thicknesses. MIIT industrial policy and dual carbon goals are accelerating intertidal and deep-water project pipelines. Yangtze River Delta manufacturing bases are capturing volume through integrated steel rolling and submerged arc welding capacity.
Denmark
Danish project developers command premium contract terms for towers with in-house metallurgical testing capabilities under DNV fatigue-resistant weld geometry mandates. National renewable auctions are unbundling tower supply from full-turbine procurement to optimize capital stacks. Esbjerg port infrastructure concentration is creating bottlenecks for heavy-lift crane capacity despite manufacturing expansion.
Brazil
Transport-constrained markets in northeastern savanna corridors are adopting on-site concrete pouring methods that bypass single-piece steel delivery limitations. ANVISA environmental licensing and grid connection regulations are extending project development cycles. Regional batching plants in Ceará and Rio Grande do Norte are displacing centralized coastal mill dependencies.
Wind Tower Market Key Industry Players
Integrated turbine OEMs and independent fabricators split the market between bundled procurement and component-level contracting. The supplier base concentrates around three strategic archetypes: vertically integrated turbine manufacturers with captive tower production, specialized steel fabricators serving unbundled buyers, and hybrid concrete-steel specialists addressing logistics-constrained geographies. Capacity expansion and certification track record accumulation dominate competitive moves, with port-adjacent manufacturing investments and DNV/IEC 61400 testing protocol mastery serving as primary differentiation vectors.
Among European integrated manufacturers, Vestas Wind Systems A/S and Siemens Gamesa Renewable Energy exemplify the turbine-OEM archetype with vertical control over blade-to-tower integration. Chinese fabricators including Mingyang Smart Energy occupy positions within the scale-driven independent supplier tier serving domestic and export offshore demand. GE Vernova represents the digital-service-anchored archetype leveraging predictive analytics platforms for lifetime extension contract capture across installed fleets.
| Leading Market Players |
|---|
| GE Vernova |
| Nordex SE |
| Vestas Wind Systems A/S |
| Envision Energy |
| Mingyang Smart Energy |
| Siemens Gamesa Renewable Energy |
| ENERCON GmbH |
| Sany Renewable Energy Co., Ltd. |
| Goldwind |
| Others |
Cost & Logistics Intelligence
Bremerhaven and Cuxhaven anchor European fabrication capacity where coastal mill retooling for modular offshore towers concentrates supply-side pricing power. German and Danish developers absorb premium contract terms for DNV-certified fatigue-resistant weld geometries while Brazilian and Indian buyers shift toward on-site concrete methods to bypass steel price volatility.
Pricing Analysis
Lifetime extension contracts spanning 15-20 years anchor aftermarket revenue tiers as GE Vernova's digital twin platform captures recurring service streams. Three-tier pricing structure across premium certification-grade, standard fabrication, and economy lattice configurations reflects divergence in metallurgical testing capabilities and corrosion protection specifications. Cost compression in mid-scale tubular segments intensifies as Chinese independent fabricators secure standalone European orders. Energy developers unbundling tower supply from full-turbine procurement exhibit acute price sensitivity, while utility buyers with captive steel agreements prioritize certification track records over unit economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Yangtze River Delta rolling mills are restructuring procurement relationships for independent fabricators lacking captive steel capacity. Heavy plate supply draws from China, Germany, and South Korea where integrated submerged arc welding clusters concentrate fabrication economics. Scrap metal and energy input volatility, port infrastructure bottlenecks at Esbjerg and North Sea harbors, and DNV certification timelines constitute primary structural risks. Distribution runs through coastal manufacturing clusters serving North Sea projects, East Asian offshore zones, and Great Lakes supply corridors with ice-load engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as energy developers unbundle tower supply from turbine OEMs, fragmenting procurement relationships and compressing margins for undifferentiated fabricators without certification track records or metallurgical testing capabilities.
For Market Incumbents: Entrench certification moats through in-house DNV fatigue testing laboratories and automated ultrasonic inspection equipment as independent Chinese fabricators secure standalone Atlantic Coast orders. Anchor long-term service agreements via digital twin platforms capturing predictive analytics revenue streams. Vertical integration into captive steel rolling capacity hedges input cost volatility threatening fabrication margins. For New Entrants and Emerging Players: Transport-constrained markets in Brazil and India represent the most penetrable entry point where on-site concrete batching displaces centralized mill dependencies. Hybrid steel-concrete fabrication capabilities bypass road width and bridge load limits that constrain single-piece steel delivery. Target regional batching plant partnerships with northeastern Brazilian developers seeking ANVISA-compliant environmental licensing pathways. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized coastal fabrication assets and dormant DNV certification relationships. Long-term viability hinges on port-adjacent manufacturing positions serving floating foundation deployment in deeper water sites. Monitor Atlantic Coast auction pipeline acceleration under Inflation Reduction Act domestic content requirements as inflection indicator for component-level financing structures.| Strategic Initiative | Industry Significance |
|---|---|
| DNV Certification Investment | In-house metallurgical testing capabilities command premium contract terms from Danish and German developers. |
| Modular Transport Logistics Retooling | Coastal mills serving North Sea projects adapt thicker plate rolling for above-5 MW tower segments. |
| Digital Twin Platform Deployment | Predictive analytics integration anchors 15-20 year lifetime extension service contracts across installed fleets. |
| Hybrid Concrete-Steel Capability Buildout | On-site pouring methods bypass road width limits in Brazilian and Indian transport-constrained corridors. |
| Great Lakes Manufacturing Cluster Expansion | Ice-load engineering capabilities capture freshwater offshore demand from Michigan and Ontario developers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across turbine OEM procurement teams, independent fabricator engineering directors, offshore project developers, port infrastructure operators, and steel plate sourcing specialists. Primary interview insights triangulated against secondary sources including DNV structural standards documentation, IEC 61400 certification protocols, EU Green Deal regulatory filings, FERC interconnection queue data, and customs trade records for heavy plate imports. Bottom-up project pipeline aggregation and top-down capacity utilization modeling converged on segment-level demand estimates.
Calibration against historical installation data and announced manufacturing capacity expansions anchored volume projections across the analysis window. Segmentation dimensions modeled include product type (tubular, hybrid, lattice, concrete), capacity rating brackets, deployment setting (offshore, onshore, remote), and buyer archetype (energy developers, utilities, independent power producers, contractors). CAGRs derived from regression analysis of auction pipeline announcements, steel price elasticity coefficients, and port infrastructure investment cycles.
Practitioners should monitor EU steel composite recycling regulation finalization, Atlantic Coast domestic content requirement enforcement, and floating foundation technology maturation for early signals of demand trajectory shifts. Forecasts reflect assumptions regarding continued EU Green Deal binding target adherence, MIIT dual carbon policy implementation, and IRA production tax credit continuity. Macroeconomic steel plate volatility, regulatory certification timeline extensions, or technological breakthroughs in alternative tower materials would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Gearbox and Direct Drive Systems Market
Wind Energy Systems
Wind Turbine Forged Tower Flange Market
Wind Energy Systems
Wind Energy Market
Wind Energy Systems
Europe Direct Drive Wind Turbine Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Drive Market
Wind Energy Systems
North America Wind Power Market
Wind Energy Systems
Offshore Wind Anchoring Market
Wind Energy Systems
Portugal Wind Energy Market
Wind Energy Systems
Offshore Wind Cable Market
Wind Energy Systems
Offshore Wind Power Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
China Wind Turbine Rotor Blade Market
Wind Energy Systems
New Zealand Wind Energy Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
Wind Power Couplings Market