
 Europe Large Wind Turbine Market | 2026-2036
Europe Large Wind Turbine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Large Wind Turbine Market Foresight
Utility buyer consolidation across North Sea markets is repositioning procurement leverage toward a handful of European energy majors with multi-gigawatt pipelines. Vestas Wind Systems A/S leverages its Danish manufacturing footprint to anchor supply contracts for onshore repowering cycles. Siemens Gamesa Renewable Energy S.A. competes through offshore turbine scale leadership and blade technology specialization. Nordex SE sustains a differentiated position in medium-scale onshore segments where project developers seek modular installation flexibility.
Europe large wind turbines convert kinetic wind energy into grid-synchronous electricity through rotor assemblies typically exceeding 3 MW rated capacity, with nacelles housing generators, gearboxes or direct-drive permanent-magnet systems, and pitch control mechanisms. Horizontal axis configurations dominate installed capacity due to aerodynamic efficiency and hub-height scalability for both onshore and offshore deployment. Direct drive technology is gaining structural share as offshore projects prioritize reliability and reduced drivetrain maintenance in salt-laden environments. The component segment concentrates margin pools in blades and nacelles where advanced composites and generator architectures command premium pricing.
The EU Green Deal and REPowerEU framework mandate accelerated renewable buildout while the F-Gas Regulation restricts fluorinated greenhouse gases used in switchgear and cooling systems within turbine electrical components. CE marking under the Machinery Directive enforces safety and electromagnetic compatibility standards that shape product design cycles and market access timelines. Stakeholders must monitor seabed licensing rounds, grid connection queue reforms, and evolving domestic content thresholds that will determine project bankability and supplier qualification across European waters.
Market Dynamics
Offshore turbine scaling toward 15 MW-plus rated capacity is compressing unit economics and concentrating procurement authority among North Sea utilities with multi-gigawatt development pipelines.
Growth Catalysts
- REPowerEU framework:The EU's accelerated renewable buildout targets mandate domestic manufacturing content thresholds that secure long-term order visibility for European turbine assemblers.
- Direct-drive permanent-magnet generators:Salt-laden offshore environments favor gearless drivetrain architectures that eliminate gearbox maintenance burdens and extend mean time between failures.
- German seabed leasing rounds:The Bundesnetzagentur's auction schedule for North Sea and Baltic zones underpins gigawatt-scale deployment commitments through 2035.
Market Restraints
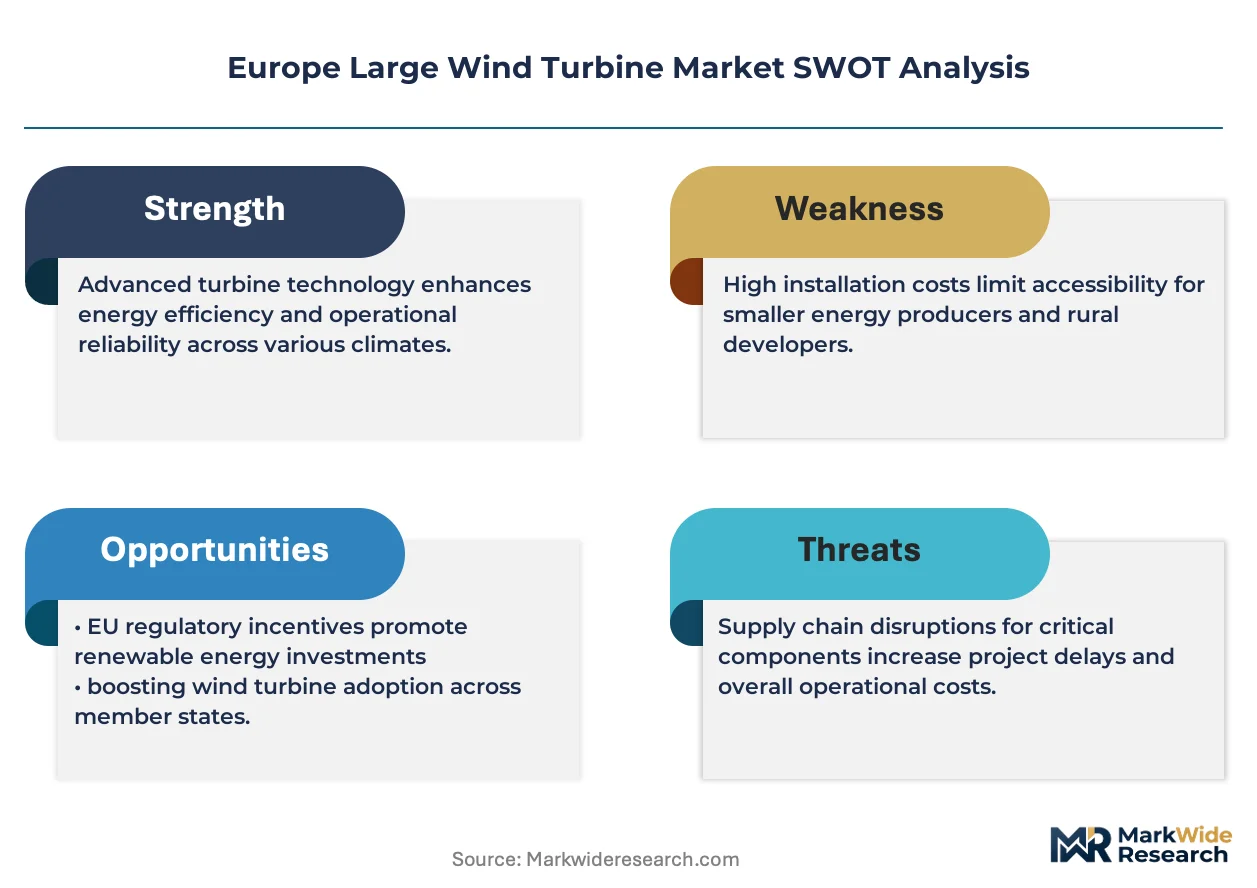
- Rare earth magnet supply concentration:Neodymium and dysprosium processing capacity concentrates in Chinese refining complexes, exposing European generator manufacturers to input cost volatility and geopolitical supply risk.
- F-Gas Regulation restrictions:The EU's phasedown of fluorinated greenhouse gases limits switchgear and cooling system options within turbine electrical components, forcing redesign cycles.
- Monopile foundation steel costs:Thick-walled tubular structures for 80-meter-plus water depths consume heavy plate volumes subject to commodity price swings and mill capacity constraints.
Strategic Opportunities
- Polish Baltic Sea zone:Poland's offshore wind development program targets 18 GW capacity by 2040, creating a new demand geography with limited incumbent supplier relationships.
- Floating foundation technology:Semi-submersible and tension-leg platforms unlock deep-water sites beyond fixed-bottom economic limits in Portuguese and Scottish waters.
- Power-to-X integration:Offshore wind farms coupled to electrolyzer arrays for green hydrogen production access dedicated offtake contracts under EU Hydrogen Bank guarantees.
Industry Challenges
- Installation vessel scarcity:Heavy-lift jack-up units with 1,500-ton-plus crane capacity face construction backlogs that compress project commissioning schedules.
- Grid connection queue reform:Connection request processing delays at transmission system operators stall project energization timelines and strain developer working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Large Wind Turbine Market |
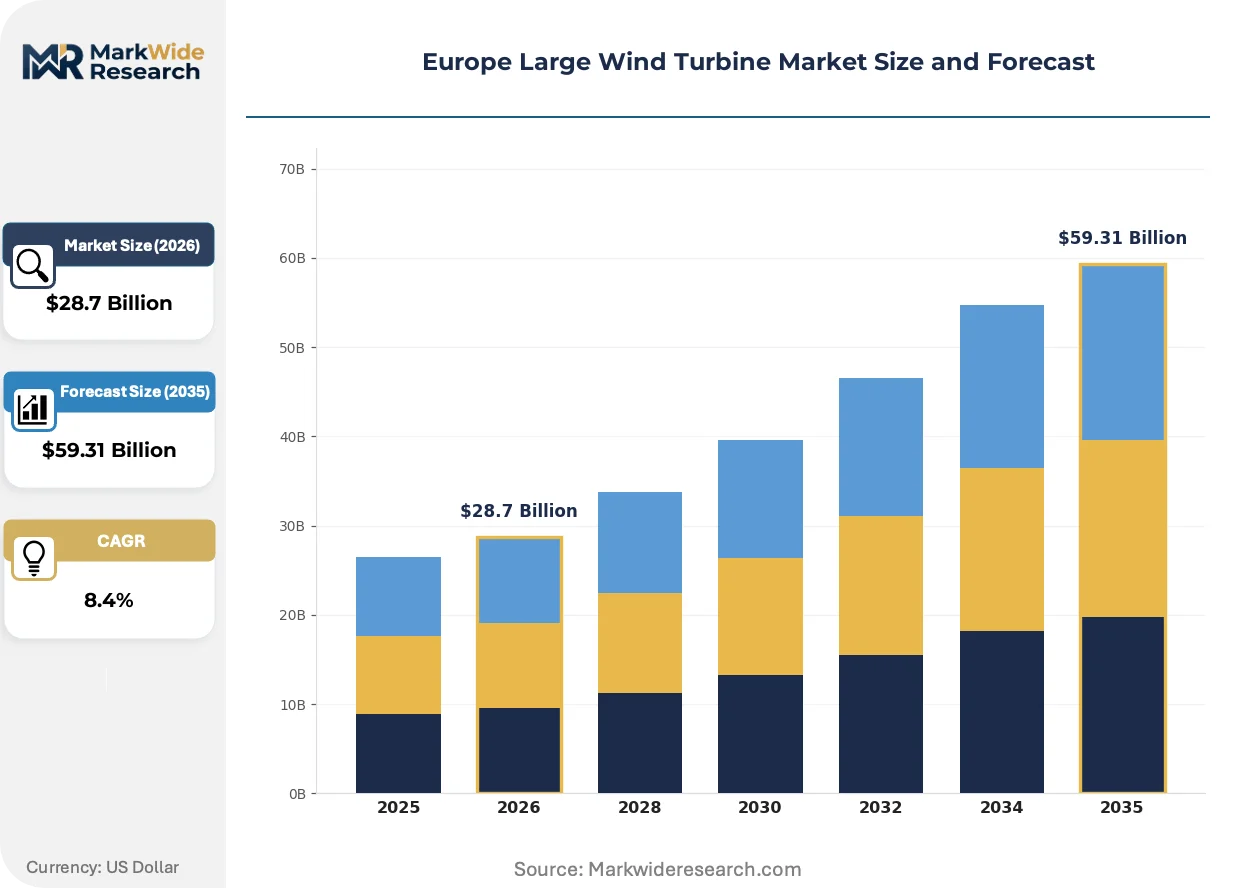
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Horizontal Axis, Vertical Axis, Direct Drive, Gearbox End User: Utilities, Independent Power Producers, Government, Corporate Component: Blades, Nacelles, Towers, Control Systems Deployment: Onshore, Offshore, Hybrid, Distributed |
| Companies Covered | Vestas Wind Systems A/S, Siemens Gamesa Renewable Energy S.A., Nordex SE, Enercon GmbH, GE Vernova, Suzlon Energy Limited, Vensys Energy AG, Envision Energy, JSC NovaWind, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Large Wind Turbine Market Shifts & Advancements
Turbine architecture and deployment models are diverging between onshore repowering cycles and offshore gigascale projects, with distinct technology bets emerging for each pathway.
Modular blade manufacturing using thermoplastic resin systems is decentralizing production footprints away from centralized glass-reinforced epoxy facilities. Vestas and LM Wind Power are piloting weldable thermoplastic composites that enable field repairability and reduce transport constraints for 100-meter-plus blade lengths. This materials transition is compressing logistics costs and enabling regional supply hubs closer to North Sea port infrastructure.
The EU F-Gas Regulation's phasedown schedule is forcing electrical component redesigns across switchgear and converter cooling systems. Turbine OEMs are accelerating adoption of vacuum interrupters and dry-type transformers to eliminate SF6 dependency before 2030 bans tighten. Offshore nacelle architectures face the most acute compliance pressure given sealed-environment thermal management requirements.
Utility procurement consolidation is compressing supplier qualification timelines and unbundling aftermarket service contracts from initial equipment sales. Ørsted, RWE, and Equinor now negotiate multi-project master supply agreements with dedicated maintenance reserve pricing. This buyer behavior shift concentrates order volume among Danish and Spanish manufacturers while squeezing independent service provider margins across German and UK project portfolios.
Europe Large Wind Turbine Market Segmentation
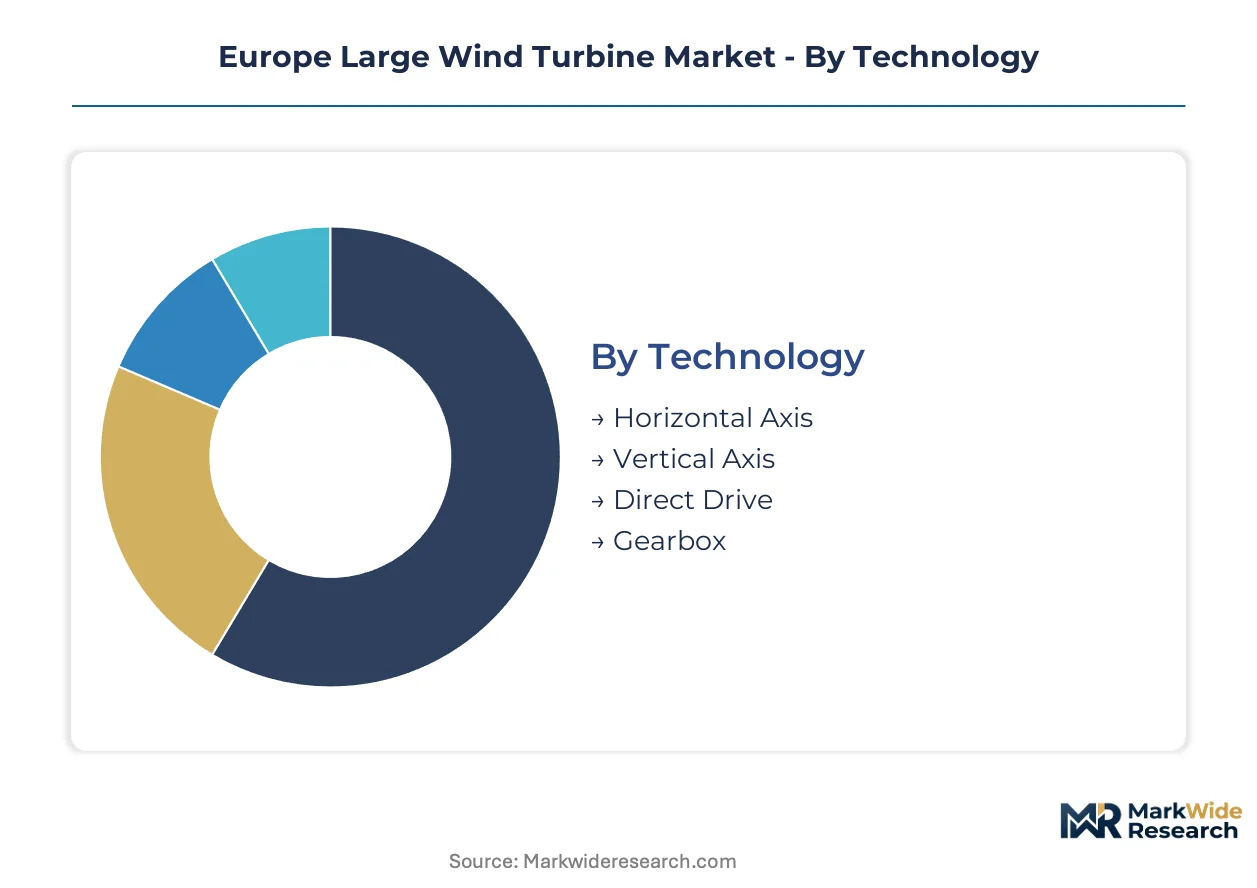
Technology choices in Europe's large wind turbine market determine maintenance regimes, supply chain exposure, and project bankability across divergent seabed and terrain conditions. Procurement patterns cluster around reliability priorities in salt-laden offshore environments versus cost optimization for onshore repowering cycles.
Technology:
Buyers differentiate primarily by drivetrain architecture tradeoffs between gearbox maintenance burdens and rare earth magnet supply exposure.
- Horizontal Axis:Aerodynamic configurations with rotor diameters exceeding 150 meters dominate installed capacity across North Sea arrays and German onshore corridors. Danish and UK developers prioritize hub-height scalability for capacity factor optimization in low-wind sites.
- Direct Drive:Gearless permanent-magnet generators eliminate gearbox failure modes in inaccessible offshore nacelles. German and Spanish OEMs anchor manufacturing footprints to serve Baltic and North Sea lease rounds where mean time between failures drives procurement decisions.
- Vertical Axis:Darrieus and Savonius configurations occupy niche distributed applications where omnidirectional wind capture offsets lower efficiency. Urban installations in Rotterdam and Copenhagen test building-integrated deployments.
- Gearbox:Multi-stage planetary systems retain cost advantages in onshore repowering projects where crane access enables scheduled maintenance. Polish and Romanian developers favor established supply chains for medium-scale installations.
Volume sits with Horizontal Axis; growth tilts toward Direct Drive.
End User:
Contracting authority concentrates among entities with balance sheet capacity to absorb construction risk and grid connection delays.
- Utilities:Vertically integrated European majors including Ørsted, RWE, and Iberdrola negotiate multi-gigawatt master supply agreements with dedicated maintenance reserves. Bundesnetzagentur seabed auctions and UK CfD rounds concentrate procurement authority among five dominant players.
- Independent Power Producers:Project developers without regulated rate bases rely on non-recourse financing and supplier credit support. Spanish and Italian IPPs specialize in repowering aging onshore fleets with modular turbine configurations.
- Government:State-owned enterprises in Poland and France direct offshore development through public procurement frameworks. Polish Energy Group and EDF command preferential grid queue positions for strategic capacity buildout.
- Corporate:Power purchase agreement offtakers including data center operators and industrial manufacturers source renewable attributes for carbon disclosure compliance. Swedish and Finnish forestry and mining conglomerates anchor direct wire projects.
Utilities command current volume; Corporate offtake agreements are expanding most quickly.
Component:
Margin pools concentrate where advanced materials and thermal management complexity create supplier differentiation.
- Blades:Glass-reinforced epoxy and emerging thermoplastic composite structures exceeding 100 meters in length determine rotor swept area and annual energy production. LM Wind Power and Vestas pilot decentralized manufacturing hubs near North Sea port infrastructure to compress logistics costs.
- Nacelles:Sealed enclosures housing generators, converters, and pitch systems face acute F-Gas Regulation compliance pressure for cooling and switchgear redesigns. Siemens Gamesa and Nordex accelerate vacuum interrupter adoption to eliminate SF6 dependency before phasedown deadlines.
- Towers:Tubular steel and hybrid concrete-steel hybrid structures scale hub heights for wind shear optimization. Danish and German fabricators face heavy plate cost volatility from mill capacity constraints.
- Control Systems:Pitch regulation, yaw drives, and condition monitoring hardware integrate SCADA platforms for predictive maintenance. Spanish and German automation specialists supply converter and sensor packages.
Blades capture the largest revenue share; Nacelles face the steepest redesign cycle intensity.
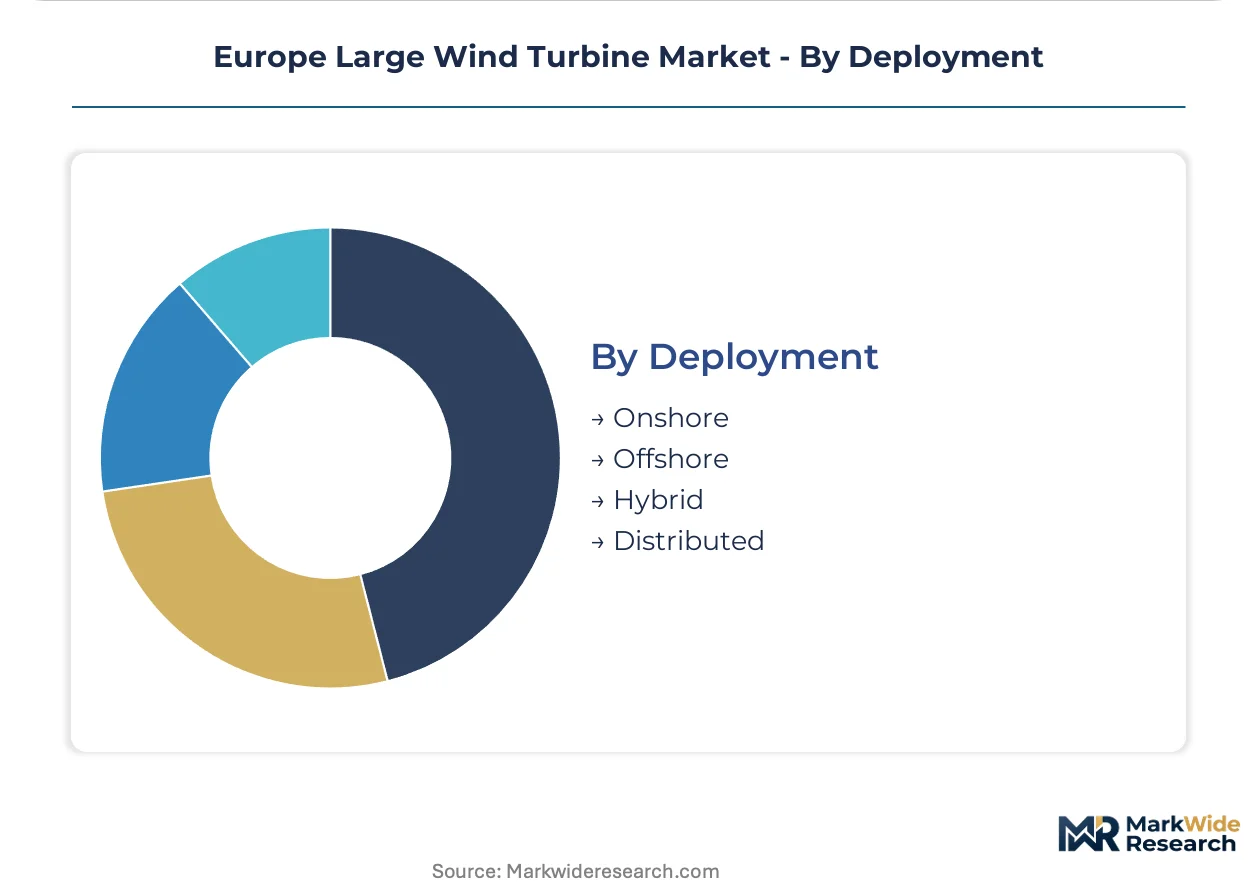
Deployment:
Site selection determines foundation technology, installation vessel requirements, and grid connection topology.
- Offshore:Fixed-bottom monopile and jacket structures in 30-60 meter water depths anchor North Sea and Baltic capacity expansion. Floating semi-submersible platforms unlock Portuguese and Scottish deep-water sites beyond fixed-bottom economic limits.
- Onshore:Greenfield installations and repowering of 1990s-era turbines dominate German, Spanish, and French project pipelines. Hub height and rotor diameter upgrades extract incremental yield from permitted sites.
- Hybrid:Co-located wind and solar generation with shared grid infrastructure and storage integration optimize land use and capacity factor profiles. Greek and Italian islands test hybrid architectures for diesel displacement.
- Distributed:Sub-utility-scale installations behind-the-meter or at distribution voltage levels serve industrial and commercial loads. Danish agricultural cooperatives and German municipal utilities anchor distributed deployment.
Offshore commands capital deployment; Distributed applications are gaining share fastest in grid-constrained regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Sea port infrastructure and Baltic seabed leasing anchor procurement geography for European large wind turbines. Steel plate mills in Germany and heavy-lift vessel clusters in Denmark concentrate supply-side capacity. Grid interconnection investments in the United Kingdom and Poland reshape project bankability timelines.
Germany
Bundesnetzagentur seabed auctions for North Sea and Baltic zones drive multi-gigawatt deployment commitments through 2035. The F-Gas Regulation forces electrical component redesigns across switchgear and converter cooling systems. Bremerhaven and Cuxhaven anchor heavy-lift vessel staging for monopile installation campaigns.
United Kingdom
Contract for Difference rounds concentrate procurement authority among vertically integrated energy majors with balance sheet capacity for construction risk. Crown Estate seabed leasing reforms compress developer qualification timelines. Scottish waters test floating semi-submersible platforms for deep-water sites beyond fixed-bottom economic limits.
Denmark
Ørsted's multi-project master supply agreements reshape supplier qualification and aftermarket service contracting. The EU Green Deal domestic content thresholds secure long-term order visibility for Danish turbine assemblers. Esbjerg port infrastructure expansion supports jack-up vessel mobilization for 15 MW-plus turbine components.
Poland
The Polish Energy Group's offshore wind development program targets 18 GW capacity by 2040, creating new demand geography with limited incumbent supplier relationships. REPowerEU framework mandates accelerate renewable buildout with domestic manufacturing requirements. Baltic Sea port investments in Gdańsk and Świnoujście position for component staging.
France
EDF-directed offshore development through public procurement frameworks commands preferential grid queue positions for strategic capacity buildout. CE marking under the Machinery Directive enforces safety and electromagnetic compatibility standards. Saint-Nazaire and Le Havre industrial clusters support nacelle assembly and blade manufacturing for Atlantic lease zones.
Europe Large Wind Turbine Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue floating foundation technology and power-to-X integration pathways. The vendor base concentrates around Danish and Spanish manufacturers with offshore scale leadership, while German specialists retain positions in medium-scale onshore segments. Two strategic archetypes dominate: vertically integrated energy majors with captive project pipelines, and independent turbine assemblers competing on blade technology and drivetrain reliability. Competitive moves center on multi-project master supply agreements and modular blade manufacturing decentralization near North Sea ports.
Within the offshore scale tier, Vestas Wind Systems A/S and Siemens Gamesa Renewable Energy S.A. occupy positions defined by rotor diameter leadership and nacelle architecture specialization. Nordex SE exemplifies the medium-scale onshore archetype where project developers seek modular installation flexibility. These three anchors represent distinct technology bets between gearbox retention and direct-drive permanent-magnet generator adoption.
| Leading Market Players |
|---|
| Vestas Wind Systems A/S |
| Siemens Gamesa Renewable Energy S.A. |
| Nordex SE |
| Enercon GmbH |
| GE Vernova |
| Suzlon Energy Limited |
| Vensys Energy AG |
| Envision Energy |
| JSC NovaWind |
| Others |
Supply & Pricing Matrix
Heavy plate steel for monopile foundations flows from German and Polish mills through three distinct pricing tiers that separate integrated energy majors with multi-project master supply agreements from independent power producers negotiating single-project terms. Contract structures for 15 MW-plus offshore turbines embed long-term service reserves that compress upfront equipment margins while shifting lifetime value capture toward aftermarket performance guarantees.
Pricing Analysis
Warranty and service bundling unbundling defines competitive positioning as Ørsted, RWE, and Equinor negotiate dedicated maintenance reserve pricing separate from initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates vertically integrated utilities with captive pipelines from credit-constrained independent power producers and municipal offtakers. Price differentiation hinges on direct-drive permanent-magnet generator certification and F-Gas Regulation compliance timing, with independent power producers exhibiting acute price sensitivity due to non-recourse financing constraints. Pricing pressure stems from rare earth magnet cost volatility and installation vessel scarcity that compress project commissioning schedules.
Supply Chain Analysis
Blade refurbishment and nacelle remanufacturing flows are emerging as Danish and Spanish OEMs pilot thermoplastic composite repairability to extend asset lifecycles. Manufacturing concentration rests on Denmark, Germany, and Spain for final assembly with Chinese refining complexes dominating neodymium and dysprosium processing for permanent-magnet generators. Rare earth supply concentration and monopile steel plate mill capacity constraints constitute the primary structural vulnerability. Distribution runs through North Sea port infrastructure at Esbjerg, Bremerhaven, and Cuxhaven with heavy-lift jack-up vessel mobilization determining downstream delivery topology.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's large wind turbine market sits in a technology-transition phase as direct-drive permanent-magnet generators displace gearbox architectures across offshore deployments. This drivetrain shift reconfigures supplier qualification criteria and procurement authority concentration.
For Market Incumbents: To counter rare earth magnet supply concentration and Chinese refining dominance, Vestas and Siemens Gamesa should deepen backward integration into permanent-magnet recycling streams and secure alternative magnet formulations through European processing partnerships. Capacity addition in Baltic Sea corridor fabrication facilities will anchor domestic content compliance under REPowerEU thresholds.
For New Entrants and Emerging Players: Floating foundation technology specialists should target Polish Baltic Sea zone development where 18 GW capacity targets by 2040 create new demand geography with limited incumbent supplier relationships. Semi-submersible platform engineering for Portuguese and Scottish deep-water sites offers the most penetrable white-space with technology licensing to established marine contractors as the primary go-to-market angle.
For Investors and Strategic Acquirers: Polish seabed licensing round acceleration is the leading indicator that Baltic corridor project bankability is crystallizing ahead of grid connection queue reforms. Long-term viability over the next decade favors vertically integrated energy majors with captive pipelines and direct-drive generator technology leadership. Monitor Bundesnetzagentur auction schedule density and Gdańsk port infrastructure commitment levels for early signals of supplier qualification timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Drive Generator Scale-Up | Eliminates gearbox maintenance burdens in salt-laden North Sea nacelles. |
| Thermoplastic Blade Manufacturing | LM Wind Power and Vestas pilot weldable composites enabling field repairability. |
| Floating Foundation Technology | Semi-submersible platforms unlock Portuguese and Scottish deep-water sites. |
| Power-to-X Integration | Offshore wind coupled to electrolyzer arrays accesses EU Hydrogen Bank guarantees. |
| Domestic Content Compliance | REPowerEU thresholds secure long-term order visibility for European assemblers. |
Research Methodology
Regulatory filings from the Bundesnetzagentur, Crown Estate seabed leasing records, and EIA project development databases formed the secondary backbone for this analysis. Primary interviews with utility planning officers at Ørsted and RWE, independent power producer project developers in Poland and Spain, EPC contractors specializing in North Sea installation campaigns, and grid operators managing connection queue reforms provided ground-truth validation. Bottom-up turbine deployment forecasts triangulated against top-down renewable capacity targets from REPowerEU framework documentation.
Historical trendline analysis of seabed auction schedules, grid interconnection investment patterns, and turbine OEM order backlogs established baseline growth trajectories across the analysis window. Segmentation modeling incorporated drivetrain architecture, deployment type, end-user contracting authority, and component-level margin pool dynamics. CAGRs were derived from project pipeline visibility windows and domestic content threshold implementation timelines with rare earth magnet price indices and heavy-lift vessel day-rate curves as industry-specific forecast inputs.
Caveats apply where rare earth supply disruption, F-Gas Regulation phasedown acceleration, or grid connection queue reform delays could materially shift the outlook. Forecasts reflect assumptions about seabed licensing round cadence and transmission system operator processing capacity. Practitioners should monitor Polish Baltic Sea zone port infrastructure commitment levels and installation vessel construction backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Latin America Wind Turbine Market
Wind Energy Systems
Wind Energy Market
Wind Energy Systems
Double-Fed Wind Turbine Market
Wind Energy Systems
Portugal Wind Energy Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
France Wind Energy Market
Wind Energy Systems
Lubricants for Wind Turbine Market
Wind Energy Systems
Wind Power Market
Wind Energy Systems
Sweden Wind Energy Market
Wind Energy Systems
Global Wind Turbine Operations Market
Wind Energy Systems
Wind Turbine Blades Market
Wind Energy Systems
Wind Turbine Gearbox and Direct Drive Systems Market
Wind Energy Systems
Japan Wind Energy Market
Wind Energy Systems
Drone Wind Turbine Blade Inspection Market
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
Wind Turbine Pitch and Yaw Control System Market