
 Global Wind Automation Market | 2026-2036
Global Wind Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wind Automation Market Outlook
Market Context
The EU Green Deal is pivoting the cost-of-entry calculus for wind automation suppliers by mandating stricter grid-code compliance and remote monitoring capabilities. Siemens AG leverages its digital twin portfolio to sustain leadership in turbine control software across European offshore projects. ABB anchors its position through integrated power and automation systems designed for high-voltage direct current transmission links.
Technical Definition and Segment Structure
Wind automation encompasses the hardware, software, and communication layers that enable autonomous operation, condition monitoring, and predictive control of wind turbines and wind farms, typically operating across voltage ranges from 690V at the turbine level to 220kV at the grid connection point. SCADA systems and control systems dominate current revenue pools, while machine learning and IoT solutions represent the fastest-expanding technology tier as operators shift from scheduled to condition-based maintenance protocols. Communication equipment and sensors capture disproportionate margin concentration in offshore applications where subsea cabling and corrosion-resistant instrumentation command premium positioning.
Regulatory Framework
The EU Green Deal, F-Gas Regulation, and IEC 61400 standards collectively shape product certification requirements and market access conditions for automation vendors serving European wind developers. China's dual carbon goals and GB standards for wind turbine grid integration impose parallel compliance burdens on suppliers targeting that market. Stakeholders must monitor evolving cybersecurity mandates for critical energy infrastructure as regulators in multiple jurisdictions harden remote access protocols for SCADA and cloud-connected control systems.
Market Dynamics
Offshore wind farm operators are accelerating adoption of predictive maintenance platforms as turbine scale and remoteness make manual inspection economically unviable. The EU Green Deal's renewable energy directives are tightening grid-code compliance requirements, forcing automation suppliers to embed real-time grid-stabilization capabilities into control systems.
Growth Catalysts
- Floating offshore wind expansion:Germany, Denmark, and China are deploying floating platforms in deeper waters that demand autonomous turbine control systems capable of operating without physical technician access for extended periods.
- EU Green Deal grid-code mandates:Stricter compliance requirements for frequency response and voltage regulation are compelling wind farm developers to upgrade legacy control architectures with advanced automation layers.
- Condition-based maintenance protocols:Machine learning algorithms analyzing vibration, temperature, and oil-degradation sensor data are replacing scheduled maintenance intervals, reducing unplanned downtime and technician dispatch costs.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet generators in direct-drive turbines depend on neodymium and dysprosium processing concentrated in China, exposing turbine manufacturers to input cost volatility and geopolitical supply risk.
- Subsea cable installation bottlenecks:Specialized vessels for laying inter-array and export cables at offshore wind sites face multi-year order backlogs, constraining project commissioning timelines and automation system deployment.
- IEC 61400-25 interoperability gaps:Incomplete standardization of communication protocols between turbine SCADA systems and grid operator control centers creates integration friction and vendor lock-in effects.
Strategic Opportunities
- Japan's floating wind feed-in tariff:METI's enhanced price guarantees for floating offshore projects are attracting automation suppliers to develop control systems tailored to typhoon-resistant turbine designs.
- Digital twin convergence with physics-based modeling:Integration of real-time sensor feeds with finite-element structural models enables predictive load management and extends turbine operational life beyond original design assumptions.
- Direct sales to independent power producers:Bypassing traditional EPC contractors, automation vendors are establishing service contracts with IPPs seeking operational control over turbine performance optimization.
Industry Challenges
- Cybersecurity skill scarcity:Wind farm operators struggle to recruit engineers with combined expertise in industrial control systems and IT security protocols required to harden SCADA networks against remote intrusion.
- Legacy turbine retrofit complexity:Integrating modern condition-monitoring sensors and cloud-connected analytics platforms with 15-20 year old turbine control architectures demands costly hardware adaptations and software middleware development.
Report Scope
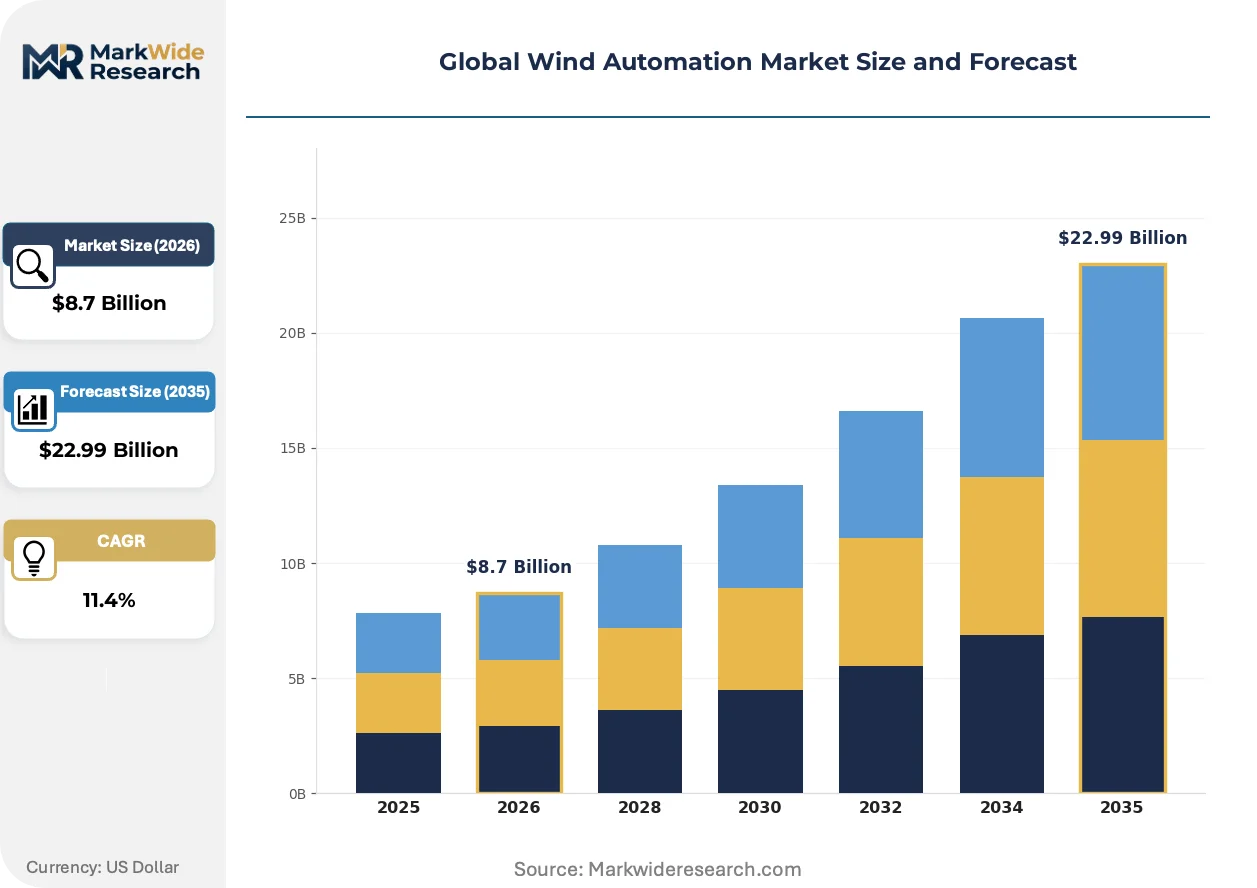
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wind Automation Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SCADA Systems, Control Systems, Communication Equipment, Sensors Technology: IoT Solutions, Big Data Analytics, Cloud Computing, Machine Learning End User: Utilities, EPC Contractors, OEMs, Renewable Energy Developers Application: Monitoring, Control, Maintenance, Energy Management |
| Companies Covered | Siemens AG, Rockwell Automation, Bachmann electronic GmbH, ABB, Schneider Electric, Emerson Electric, Bonfiglioli Riduttori, Mitsubishi Electric, Honeywell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wind Automation Market Strategic Shifts
Edge computing architectures are migrating analytics from centralized cloud servers to turbine-mounted controllers, reducing latency for pitch and yaw decisions while accommodating intermittent offshore connectivity. This shift is compressing the acceptable response window for automation suppliers.
Digital twin technology is rewriting how offshore operators manage turbine fleets. These virtual replicas aggregate SCADA, meteorological, and structural health data to simulate component degradation trajectories. Danish and German developers are deploying twins across floating wind pilot projects. The technology is compressing maintenance planning cycles from quarterly to continuous monitoring regimes.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in switchgear and cooling systems, compelling automation suppliers to redesign power conversion and thermal management components for SF6-free or low-GWP alternatives. Offshore substation projects in the North Sea face accelerated compliance deadlines. Manufacturers are responding with vacuum-interrupter and solid-insulation technologies that eliminate gas-dependent insulation entirely.
Service contract unbundling is fragmenting the traditional EPC model. Independent power producers are separating turbine supply, installation, and long-term automation service agreements to retain operational data ownership. This pattern is most visible in German offshore auctions where bidders specify multi-vendor control architectures. Channel restructuring is elevating specialized automation integrators over full-service OEM packages.
Global Wind Automation Market Segmentation
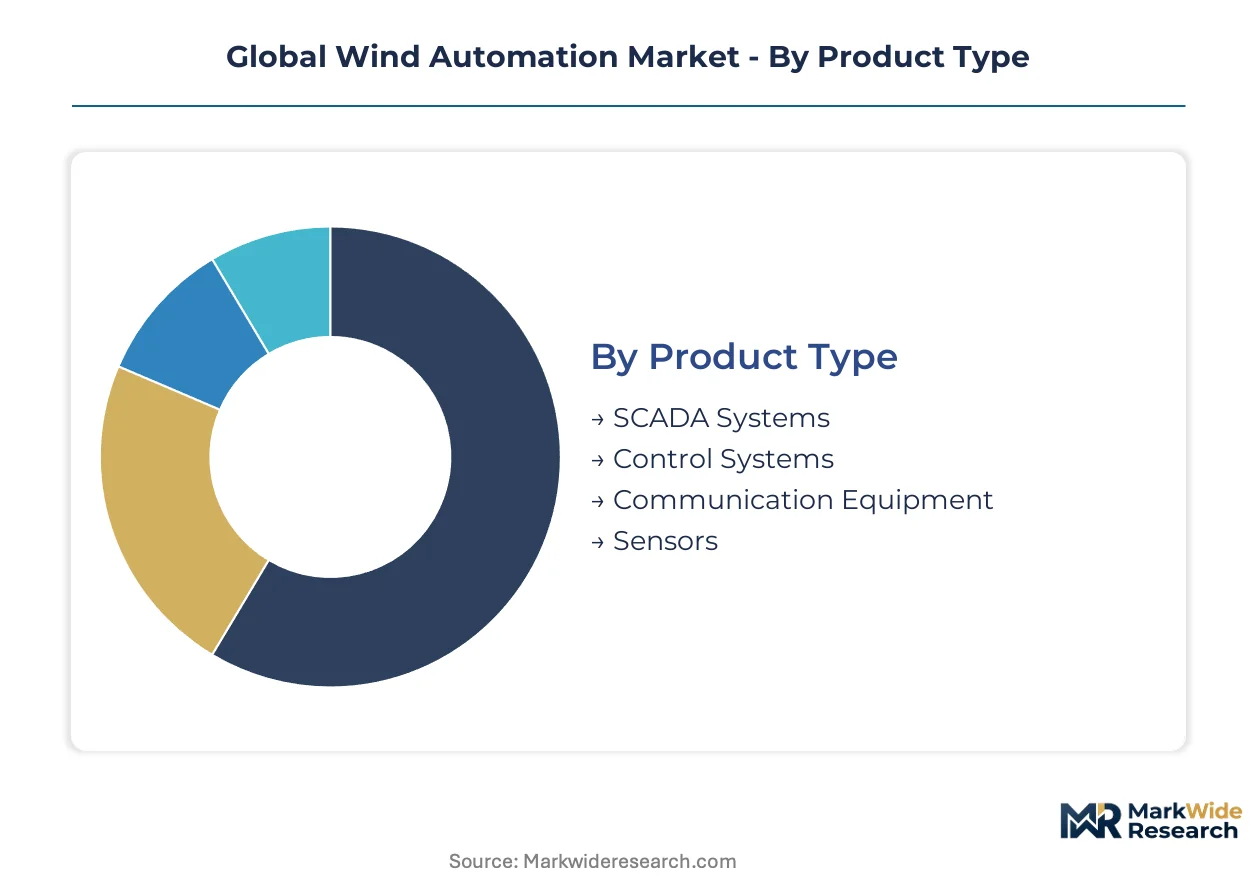
Wind automation suppliers configure product portfolios around four distinct segmentation axes. Each axis reflects different buyer priorities: turbine OEMs prioritize embedded control reliability, while independent power producers emphasize predictive analytics and data sovereignty.
Product Type:
Supply concentration in offshore cabling and corrosion-resistant instrumentation elevates margin capture for specialized hardware tiers over commoditized software layers.
- SCADA Systems:These supervisory control platforms aggregate turbine-level data streams into centralized monitoring dashboards. German and Danish offshore operators mandate IEC 61400-25 compliant architectures for grid-code adherence, driving standardization investments by system integrators.
- Control Systems:Embedded pitch, yaw, and power conversion controllers execute real-time turbine optimization algorithms. Floating wind projects in China require autonomous control loops capable of operating without technician access during extended weather windows.
- Communication Equipment:Subsea fiber-optic and wireless backhaul systems bridge turbine arrays to onshore control centers.
- Sensors:Vibration, temperature, and oil-degradation instrumentation enable condition-based maintenance protocols.
SCADA systems absorb the bulk of installed capacity; sensors are expanding most quickly as predictive maintenance displaces scheduled service intervals.
Technology:
Cost tier differentiation separates enterprise-grade cloud analytics from edge-deployed lightweight models suited to intermittent offshore connectivity.
- Machine Learning:Predictive algorithms trained on historical failure patterns forecast component degradation trajectories. Danish developers deploy these models across floating wind pilot projects to compress maintenance planning cycles from quarterly to continuous regimes.
- IoT Solutions:Distributed sensor networks with edge-computing capabilities reduce latency for critical control decisions. Germany's North Sea installations prioritize localized processing to accommodate bandwidth constraints during storm events.
- Big Data Analytics:Fleet-level pattern recognition across multi-site turbine populations identifies systemic design weaknesses.
- Cloud Computing:Centralized data lakes enable cross-fleet benchmarking and remote software updates.
Machine learning captures disproportionate R&D investment; IoT solutions are climbing the fastest as edge architectures migrate analytics from cloud servers to turbine-mounted controllers.
End User:
Customer type fragmentation is unbundling traditional EPC bundles, with independent power producers increasingly separating turbine supply from long-term automation service agreements.
- Utilities:Grid-connected operators with integrated generation and transmission assets prioritize grid-stabilization capabilities embedded in control systems. EU Green Deal frequency response mandates compel these buyers to upgrade legacy architectures.
- Renewable Energy Developers:Independent power producers seek operational data ownership and multi-vendor control flexibility. German offshore auction structures explicitly enable this unbundling pattern.
- EPC Contractors:Engineering-procurement-construction firms specify integrated automation packages during project development phases.
- OEMs:Turbine manufacturers embed proprietary control software to differentiate hardware offerings and capture recurring service revenue.
Utilities retain the largest installed base; renewable energy developers are gaining share fastest as auction mechanisms restructure procurement patterns.
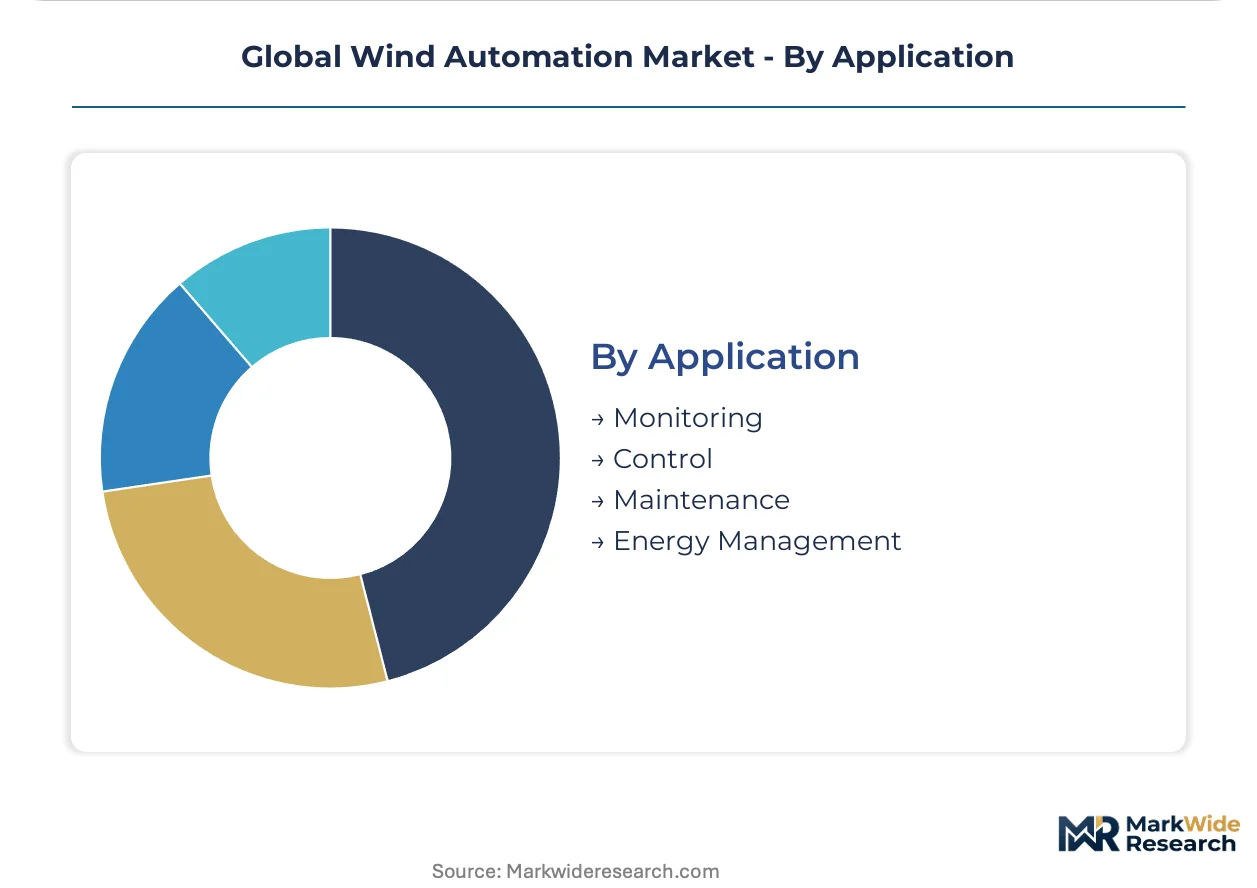
Application:
Application maturity varies sharply, with monitoring and control functions nearing saturation while energy management layers remain underpenetrated in legacy fleets.
- Maintenance:Predictive maintenance platforms aggregate sensor data to forecast component failures before catastrophic damage occurs. Offshore wind farm operators in China and Germany accelerate adoption as turbine scale and remoteness make manual inspection economically unviable.
- Energy Management:Grid-code compliance and power optimization algorithms balance generation against market pricing and grid stability requirements. EU Green Deal directives tighten these specifications, forcing automation suppliers to embed real-time frequency response capabilities.
- Monitoring:Real-time visibility into turbine health and performance metrics forms the baseline automation layer.
- Control:Automated pitch, yaw, and power regulation systems execute turbine-level operational decisions.
Monitoring and control applications absorb the bulk of current deployment; energy management is gaining traction fastest as grid-code compliance requirements harden across European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal special economic zones and Germany's North Sea port clusters concentrate floating wind automation deployment. Tax incentives in these zones attract control system integrators and sensor manufacturers seeking proximity to turbine installation hubs.
Germany
Offshore auctions in the North Sea and Baltic Sea drive demand for grid-code compliant automation architectures. The EU Green Deal mandates real-time frequency response capabilities that force upgrades to legacy SCADA systems. Bremerhaven and Cuxhaven host dense clusters of turbine service vessels and control system integration facilities.
China
Floating wind pilots in Guangdong and Fujian provinces require autonomous control systems for deep-water platforms. The country's dual carbon goals accelerate grid integration standards under GB regulations. Yangjiang and Zhanjiang emerge as manufacturing hubs for corrosion-resistant sensors and subsea communication equipment.
Denmark
Tycho Brahe offshore zone developments prioritize predictive maintenance platforms for technician-free operation. National regulators align with IEC 61400-25 standards for multi-vendor interoperability. Esbjerg anchors North Sea logistics, with control software specialists clustering around port-side turbine staging areas.
United States
Lease auctions off Massachusetts and California coastlines stimulate demand for HVDC-compatible automation systems. FERC interconnection rules and state renewable mandates shape procurement specifications. New Bedford and Humboldt Bay develop specialized port infrastructure for floating platform assembly and control system commissioning.
Japan
METI's enhanced feed-in tariffs for floating wind projects attract automation suppliers developing typhoon-resistant control algorithms. Offshore sites in Akita and Chiba prefectures test autonomous turbine operation during extended weather windows. Nagasaki and Yokohama house marine engineering clusters adapting European control architectures for Pacific typhoon conditions.
Global Wind Automation Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across automation layers. Market structure tilts toward consolidation at the SCADA and power conversion tiers, while sensor and edge-computing niches sustain fragmented specialist ecosystems. Three archetypes dominate: integrated industrial conglomerates with energy divisions, dedicated wind control software houses, and marine-certified hardware specialists. Competitive moves center on strategic partnerships for floating platform integration and geographic expansion into Asia-Pacific offshore zones.
Among European-based industrial conglomerates, Siemens AG and ABB exemplify the integrated archetype, anchoring positions through combined power and automation portfolios. Rockwell Automation represents the North American industrial automation tier, occupying a position between enterprise software and turbine-level control hardware. Japanese electrical manufacturers including Mitsubishi Electric sit within the precision control specialist tier, with heritage in servo systems and power electronics translating to offshore wind applications.
| Leading Market Players |
|---|
| Siemens AG |
| Rockwell Automation |
| Bachmann electronic GmbH |
| ABB |
| Schneider Electric |
| Emerson Electric |
| Bonfiglioli Riduttori |
| Mitsubishi Electric |
| Honeywell |
| Others |
Value Chain & Pricing Dynamics
Edge computing migration to turbine-mounted controllers simultaneously compresses hardware cost curves and concentrates procurement leverage among semiconductor suppliers capable of marine-grade certification. This dual shift rewards automation vendors with captive sensor production while squeezing margins for pure-play software integrators dependent on third-party edge hardware.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent deployment premiums from standard-schedule contract rates across offshore wind automation tiers. Project-based licensing dominates control system transactions, with price differentiation anchored in IEC 61400-25 certification grade and geographic delivery complexity. Cost compression in commoditized SCADA layers is intensifying because Chinese suppliers are scaling GB-standard-compliant platforms for export markets. Independent power producers exhibit acute price sensitivity in sensor procurement, while utilities absorb premium pricing for grid-code-compliant control architectures.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale turbine manufacturer demand, while specialized integrators serve fragmented independent power producer procurement. Component manufacturing concentrates in Germany, China, and Denmark, with subsea fiber-optic cable production drawing from Japanese and Norwegian suppliers. Rare earth magnet processing rests on Chinese neodymium and dysprosium supply chains, exposing direct-drive turbine automation to single-source vulnerability. Distribution runs through EPC contractor bundling for utility-scale projects and unbundled direct contracts for IPP-developed sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's escalating grid-code compliance requirements construct a cost-of-compliance moat that favors established automation vendors with certified European deployment track records over unproven entrants lacking IEC 61400-25 validation history.
For Market Incumbents: Anchor market position through backward integration into marine-certified sensor manufacturing and exclusive service contracts with floating wind developers in Germany and Denmark. Threat exposure from Chinese platform suppliers scaling GB-standard automation for export markets demands defensive certification investments in typhoon-resistant control architectures for Asia-Pacific expansion. For New Entrants and Emerging Players: Machine learning-based predictive maintenance algorithms offer a technology-first wedge into the underserved legacy turbine retrofit segment across European offshore fleets. White-space concentration sits with condition-monitoring sensor deployment on 15-20 year old turbine architectures where incumbent OEMs lack retrofit incentives. Direct sales to independent power producers in German auction structures bypass EPC gatekeepers and capture operational data ownership premiums. For Investors and Strategic Acquirers: Re-rating potential sits with edge-computing hardware specialists given the migration of analytics from cloud servers to turbine-mounted controllers across floating wind deployments. Long-term viability frames around 5-10 year service contract visibility rather than transactional equipment sales. Acquisition target archetype: marine-certified sensor manufacturers with IEC 61400-25-4 communication protocol compliance. The signal to watch is feed-in tariff adjustments for floating wind in Japan and South Korea as inflection indicators for Asia-Pacific automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Marine-Certified Edge Hardware Development | Captures margin compression from cloud-to-turbine analytics migration in North Sea floating projects. |
| Direct IPP Service Contracting | Bypasses EPC bundling to retain operational data ownership in German offshore auction structures. |
| Typhoon-Resistant Control Algorithms | Opens Japan METI tariff-supported floating wind market to European automation architectures. |
| SF6-Free Power Conversion Redesign | Accelerates EU F-Gas Regulation compliance for North Sea substation automation deployments. |
| Digital Twin Platform Integration | Compresses maintenance planning cycles from quarterly to continuous monitoring for Danish developers. |
Study Parameters
Document review covered IEC 61400 standard publications, EU Green Deal regulatory filings, and GB wind grid integration standards, complemented by interviews with utility planning officers, independent power producer project developers, EPC contractor procurement leads, and offshore wind turbine OEM control system engineers. Secondary validation drew from FERC interconnection filings, IEA renewable energy reports, and customs trade data on subsea cable and sensor imports. Bottom-up project pipeline analysis and top-down market sizing triangulated volume estimates.
Cross-reference between historical deployment trajectories and expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, technology tier, end-user archetype, and application function, with additional granularity on offshore versus onshore regulatory framework differentiation. CAGRs were derived through curve-fitting against disclosed project commissioning timelines and stated policy targets. Forecast inputs incorporated floating wind capacity auction schedules and HVDC transmission buildout pipelines.
Several conditions sit outside the modeled scope, including unannounced cybersecurity mandates for critical energy infrastructure and potential rare earth export restrictions affecting permanent magnet generator supply chains. Forecasts reflect documented assumptions on grid-code harmonization timelines and floating platform technology maturation curves. Periodic stress-testing of base assumptions is recommended against actual auction clearing prices and interconnection queue progression rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Europe Wind Power Market
Wind Energy Systems
Wind Energy Equipment Market
Wind Energy Systems
Wind Energy Equipment Logistics Market
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
Europe Small Wind Turbine Market
Wind Energy Systems
Small Wind Turbine Market
Wind Energy Systems
Global Small Wind Power Market
Wind Energy Systems
Wind Turbine Decommissioning Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
Ecuador Wind Energy Market
Wind Energy Systems
Double-Fed Wind Turbine Market
Wind Energy Systems
Global Offshore Wind Market
Wind Energy Systems
Wind Speed Alarm Market