
 North America Wind Power Market | 2026-2036
North America Wind Power Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wind Power Market Analytics
US turbine supply is decoupling from European component dependence as domestic tower and blade factories expand across Texas and Colorado. GE Vernova leverages its integrated nacelle assembly in South Carolina to shorten lead times for Atlantic Coast projects. Vestas Wind Systems A/S anchors its North American footprint through blade manufacturing in Windsor, Colorado and service hubs throughout the Great Plains. Siemens Gamesa Renewable Energy competes primarily on offshore platform scale, with direct-drive technology designed for harsh North Atlantic conditions.
Wind power denotes the conversion of kinetic atmospheric energy into electrical power through aerodynamic rotor blades driving a generator, with modern onshore turbines reaching hub heights exceeding 150 meters and rotor diameters surpassing 160 meters to capture stronger, steadier wind resources aloft. The technology serves as a dispatchable renewable baseload source when paired with storage, displacing fossil generation in wholesale electricity markets. Onshore installations dominate current capacity owing to mature permitting frameworks and lower levelized costs, while floating offshore technology represents the fastest-expanding segment as water depths beyond sixty meters open vast California and Maine lease areas. Turbines and towers command the largest share of component value, though blade innovation around carbon fiber hybrid designs increasingly determines performance differentiation and warranty risk.
The Federal Energy Regulatory Commission governs interstate transmission access and generator interconnection queues that often delay project completion by several years, while the Internal Revenue Service administers IRA tax credit qualification timelines that shape developer financial structuring. State-level renewable portfolio standards in California, New York, and Texas create fragmented but substantial demand mandates that pull capacity into specific regional markets. Stakeholders must monitor interconnection reform proceedings and offshore lease auction schedules as the primary variables determining project timing and capital allocation across the decade ahead.
Market Dynamics
Fifteen-megawatt offshore turbine platforms are compressing project economics while the Inflation Reduction Act's production tax credit extension restructures developer capital stacks across the United States and Canada.
Growth Catalysts
- IRA Production Tax Credit Extension:The Inflation Reduction Act's multi-year credit certainty allows developers to secure lower-cost project finance and accelerate procurement timelines for Atlantic Coast arrays.
- Carbon Fiber Hybrid Blades:Advanced composite designs reduce rotor mass while extending swept area, enabling higher capacity factors in moderate wind regimes across the Great Plains.
- Massachusetts to Virginia Demand Cluster:State-level offshore lease commitments and interconnection queue priority create concentrated procurement pull along the US Atlantic seaboard.
Market Restraints
- Interconnection Queue Delays:Federal Energy Regulatory Commission generator interconnection procedures extend project completion timelines by several years, trapping capital in pre-construction phases.
- Domestic Tower Supply Concentration:Texas and Colorado manufacturing clusters create geographic single-point vulnerability for nacelle assembly and tower component flows.
- Grid Integration Technical Limits:Variable renewable output profile challenges transmission system operators balancing fossil baseload retirement with reliability requirements.
Strategic Opportunities
- California Floating Platform Deployment:Water depths exceeding sixty meters in Pacific lease areas open vast capacity expansion beyond fixed-foundation technical limits.
- Storage-Plus-Wind Dispatch Contracts:Battery co-location enables renewable baseload positioning in wholesale electricity markets, capturing premium capacity payments.
- State Renewable Portfolio Standards:California, New York, and Texas mandates create fragmented but substantial demand pulls that reward early-mover developers with offtake certainty.
Industry Challenges
- Specialized Installation Vessel Shortage:Jones Act-compliant heavy-lift ships for offshore tower and blade erection face construction backlogs extending into the mid-2030s.
- Aviation Radar Mitigation Certification:Federal Aviation Administration lighting and radar coordination requirements add months to project commissioning schedules near military installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wind Power Market |
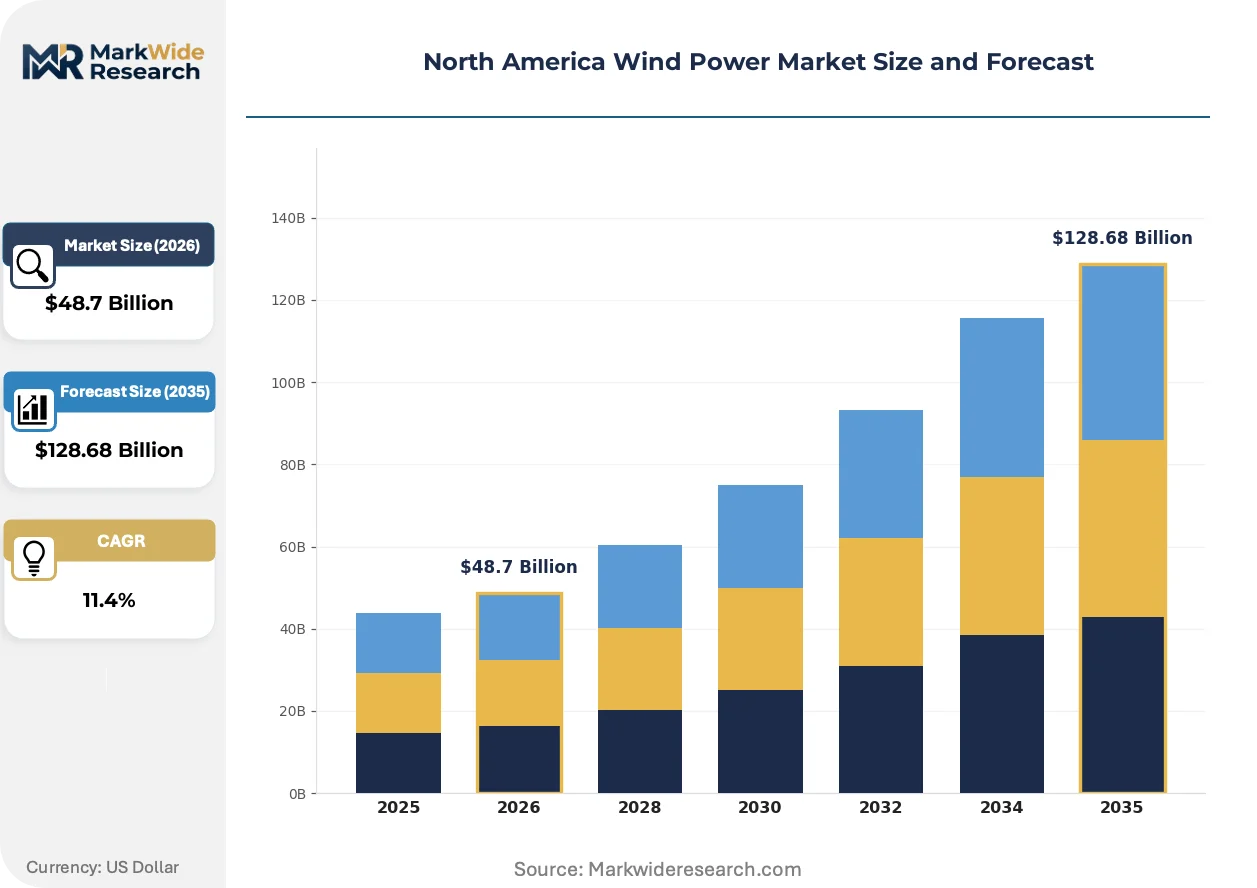
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Onshore, Offshore, Fixed, Floating Component: Turbines, Blades, Gearboxes, Towers End User: Utilities, Independent Power Producers, Renewable Energy Developers, Corporations Installation: Greenfield, Brownfield, Integrated, Remote |
| Companies Covered | Nordex SE, Ørsted AS, Vestas Wind Systems A/S, Pattern Energy Group, Invenergy, GE Vernova, NextEra Energy Inc., Clearway Energy Group, Siemens Gamesa Renewable Energy, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wind Power Market Evolving Landscape
Technology trajectories in the North America wind power market center on turbine scale escalation, federal tax credit optimization, and procurement model restructuring that favors integrated development-to-operation platforms.
Direct-drive permanent magnet generators are overtaking geared drivetrain architectures in offshore applications above ten megawatts. Developers along the Atlantic Coast specify direct-drive units for reduced maintenance exposure in harsh marine environments. This technology compression is eliminating gearbox suppliers from the offshore nacelle value chain.
The Inflation Reduction Act's domestic content bonus credits are reshaping supply chain geography. Treasury Department guidance on qualifying component thresholds forces developers to source towers and blades from Texas, Colorado, or South Carolina facilities. Onshore project pipelines in the Great Plains states are accelerating local content compliance to capture full credit value.
Corporate offtake agreements are displacing traditional utility procurement as the dominant demand channel. Technology and data center companies with net-zero commitments now contract directly with wind developers for bundled renewable energy credits and physical power. This buyer concentration is most visible in Texas and Oklahoma markets where merchant price exposure aligns with corporate risk tolerance.
North America Wind Power Market Segmentation
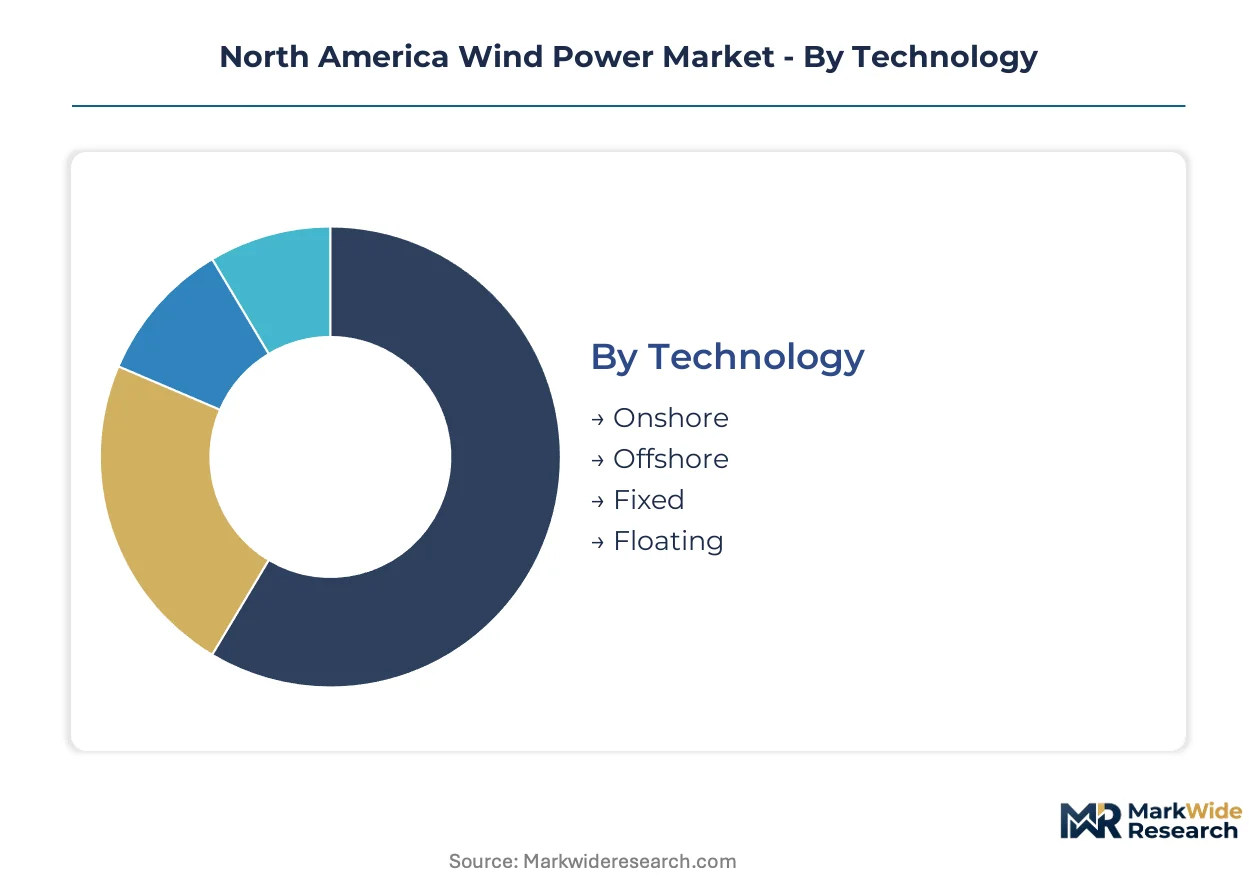
Technology choice determines capital intensity and regulatory exposure for wind power developers across North America. Component sourcing strategies and end-user contracting structures further differentiate competitive positions in this capital-intensive sector.
Technology:
Onshore developers prioritize permitting speed and interconnection access, while offshore players optimize for water depth and lease auction timing.
- Onshore:Turbine hub heights exceeding 150 meters capture stronger wind resources aloft across the Great Plains. Procurement concentrates in Texas and Oklahoma where merchant price exposure aligns with corporate offtake risk tolerance and FERC interconnection queues move fastest.
- Offshore:Fifteen-megawatt platforms compress project economics along the Atlantic seaboard from Massachusetts to Virginia. Lease commitments in state waters drive procurement clustering where BOEM auction schedules and Jones Act vessel availability determine construction sequencing.
- Fixed:Monopile and jacket foundations dominate water depths below sixty meters in established Atlantic lease blocks.
- Floating:Semi-submersible and tension-leg platforms unlock Pacific capacity off California and Maine where seabed depths exceed technical limits for fixed structures.
Volume sits with Onshore; growth tilts toward Floating.
Component:
Supply chain geography shapes domestic content compliance for IRA tax credit optimization.
- Turbines:Integrated nacelle assembly in South Carolina and Colorado facilities shortens lead times for Atlantic Coast arrays. Nacelle value concentration attracts OEM co-location with blade and tower suppliers to minimize logistics costs.
- Blades:Carbon fiber hybrid designs reduce rotor mass while extending swept area for higher capacity factors. Manufacturing concentrates in Windsor, Colorado and Texas facilities where Treasury Department domestic content thresholds force sourcing compliance.
- Gearboxes:Geared drivetrains retain share in onshore applications below ten megawatts where maintenance access is routine.
- Towers:Steel tubular and concrete hybrid structures command significant project value share with fabrication clustering in Texas and Colorado creating geographic supply vulnerability.
Revenue concentrates in Turbines; margin expansion favors Blades.
End User:
Contracting structure determines offtake certainty and capital stack composition for project finance.
- Utilities:Regulated procurement through renewable portfolio standards in California, New York, and Texas creates mandated demand pulls with long-term power purchase agreements providing baseload revenue certainty.
- Independent Power Producers:Merchant exposure strategies concentrate in Texas and Oklahoma markets where wholesale price volatility aligns with sophisticated hedging capabilities.
- Renewable Energy Developers:Integrated development-to-operation platforms capture construction margin and operational cash flows through retained ownership structures.
- Corporations:Net-zero commitments from technology and data center companies displace traditional utility procurement with direct bilateral contracts for bundled renewable energy credits and physical power delivery.
Contract volume flows through Utilities; deal velocity is climbing fastest among Corporations.
Installation:
Site characteristics dictate foundation strategy and grid connection architecture.
- Greenfield:New site development on undeveloped land dominates Great Plains expansion where agricultural lease structures minimize land acquisition friction.
- Brownfield:Repowering existing sites with modern turbine technology captures superior wind resources at established interconnection points.
- Integrated:Co-located storage and solar hybridization enables renewable baseload positioning in wholesale markets.
- Remote:Microgrid and islanded applications serve industrial loads and isolated communities beyond transmission infrastructure reach.
Deployment volume rests with Greenfield; technology upgrade cycles favor Brownfield.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Great Plains wind corridors anchor North American turbine demand. Texas and Oklahoma merchant markets attract corporate offtake concentration. Atlantic seaboard states drive offshore procurement clustering through lease auction timing.
United States
Corporate renewable energy procurement from technology and data center companies displaces traditional utility contracting channels. The Internal Revenue Service administers Inflation Reduction Act production tax credit qualification timelines that reshape developer capital stacks. Massachusetts-to-Virginia offshore lease commitments concentrate demand along the Atlantic seaboard where BOEM auction schedules determine project sequencing.
Canada
Provincial renewable portfolio standards in Ontario and Alberta create mandated demand pulls for wind capacity expansion. Health Canada coordinates with provincial regulators on environmental assessment timelines for large-scale project approvals. Quebec and Saskatchewan host established onshore installations where agricultural lease structures minimize land acquisition friction for greenfield development.
Mexico
Industrial load growth in manufacturing corridors drives private power purchase agreement demand for wind-generated electricity. The country's national energy regulator oversees interconnection queue procedures that shape project completion timelines. Oaxaca and Tamaulipas concentrate operational capacity where isthmus wind resources attract developer interest for export-oriented generation.
North America Wind Power Market Competitive Landscape
Global majors compete with regional champions across technology platform scale and domestic content compliance. The vendor base consolidates around integrated turbine OEMs with captive blade and tower supply chains. Three archetypes dominate: European-headquartered offshore specialists, North American integrated energy conglomerates, and independent renewable power producers with retained development platforms. Competitive moves center on domestic manufacturing co-location for IRA credit capture and offshore installation vessel contracting for Jones Act compliance.
Among European-headquartered turbine OEMs, Vestas Wind Systems A/S and Siemens Gamesa Renewable Energy exemplify the offshore technology specialization archetype through their direct-drive platform positioning for harsh marine environments. GE Vernova occupies a position as the North American-integrated conglomerate representative with South Carolina nacelle assembly anchoring Atlantic Coast project economics. Ørsted AS represents the independent power producer archetype with retained development-to-operation platforms capturing construction margin and long-term operational cash flows.
| Leading Market Players |
|---|
| Nordex SE |
| Ørsted AS |
| Vestas Wind Systems A/S |
| Pattern Energy Group |
| Invenergy |
| GE Vernova |
| NextEra Energy Inc. |
| Clearway Energy Group |
| Siemens Gamesa Renewable Energy |
| Others |
Value Network & Pricing Analysis
Steel plate pricing indices from the American Metal Market cascade through tower fabrication costs into project-level pricing tiers, with domestic content bonus thresholds under Treasury Department IRA guidance forcing developers toward higher-cost regional sourcing over imported alternatives.
Pricing Analysis
Warranty and service bundling separates premium turbine supply contracts from unbundled equipment-only transactions, with OEMs like Vestas and Siemens Gamesa wrapping multi-year maintenance into Atlantic Coast offshore packages while onshore merchants in Texas favor stripped-down hardware procurement. Price differentiation rests on domestic content certification tiers and hub height performance class, with fifteen-megawatt platforms commanding substantial premiums over sub-ten-megawatt units. Cost compression in the onshore segment intensifies as Chinese blade imports undercut Colorado manufacturing on spot markets, though IRA compliance penalties erase that advantage for tax credit-dependent developers. Corporate offtakers show lowest price sensitivity, prioritizing bundled renewable energy credit certainty over per-megawatt-hour savings.
Supply Chain Analysis
Dual-sourcing mandates from major IPPs and utilities require qualification of at least two blade suppliers and two tower fabricators per project, forcing developers to maintain relationships with both Colorado-Windsor manufacturing clusters and emerging Texas facilities. Geographic supply concentration centers on the United States, Denmark, and Spain for nacelle technology, while rare earth permanent magnet inputs draw from Chinese and Australian mining operations. Single-source vulnerability looms in Jones Act-compliant installation vessels, with domestic heavy-lift ship construction backlogs extending equipment availability timelines. Distribution runs through EPC contractors with captive logistics divisions, linking factory gates to project sites across fragmented state regulatory environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America wind power market sits in a technology-transition phase, with direct-drive permanent magnet generators displacing geared drivetrain architectures in offshore applications above ten megawatts and floating platforms unlocking Pacific lease depths beyond fixed-foundation limits.
For Market Incumbents: Anchor Atlantic Coast project pipelines through long-term Jones Act vessel chartering that locks scarce installation capacity ahead of competitor procurement. Secure captive blade supply from Colorado and Texas facilities to guarantee IRA domestic content bonus qualification, while accelerating carbon fiber hybrid R&D to maintain performance differentiation against emerging Chinese OEM entrants targeting the Great Plains merchant market. For New Entrants and Emerging Players: Floating platform technology offers a technology-first wedge into California and Maine lease areas where water depths exceed sixty meters and established European players lack localized deployment experience. Target corporate offtake contracting in Texas and Oklahoma where merchant price exposure tolerance aligns with sophisticated risk management capabilities, bypassing utility procurement queues that trap capital for years. For Investors and Strategic Acquirers: The window for entry favors development-stage platforms with permitted interconnection queue positions in Massachusetts-to-Virginia offshore clusters or secured agricultural lease structures across the Great Plains. Monitor BOEM auction schedule acceleration and FERC interconnection reform rulemaking as the primary inflection signals determining capital deployment timing and project finance availability.| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Installation Vessel Chartering | Long-term Jones Act contracts secure scarce heavy-lift capacity for Atlantic Coast arrays. |
| Domestic Content Compliance Investment | Treasury Department qualification thresholds reshape sourcing toward Texas and Colorado manufacturing. |
| Floating Platform Technology Licensing | Semi-submersible designs unlock Pacific lease depths beyond fixed-foundation technical limits. |
| Corporate Offtake Agreement Structuring | Direct bilateral contracts with technology and data center companies displace traditional utility procurement. |
| Storage Co-location Development | Battery hybridization enables renewable baseload positioning in wholesale electricity markets. |
Research Methodology
Multi-period observation of FERC interconnection queue progression, BOEM lease auction schedules, and IRA tax credit qualification timelines anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from EIA generation capacity databases, FERC filings, IEA renewable energy reports, and project development tracking services. Bottom-up capacity addition modeling triangulated against top-down macroeconomic demand projections.
Segment-weighting approaches distributed value and volume across technology platforms, component categories, end-user contracting structures, and installation types. CAGRs were derived through regression analysis of historical capacity deployment patterns applied to regulatory timeline assumptions across the projection horizon. Forecast inputs incorporated turbine scale escalation curves, domestic manufacturing capacity buildout schedules, and corporate procurement commitment trajectories.
Several conditions sit outside the modeled scope, including unanticipated federal tax credit repeal, abrupt interconnection queue moratoria, and Jones Act vessel construction delays extending beyond current backlogs. Deviation in FERC Order 2023 implementation timelines or Treasury Department domestic content guidance revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Ecuador Wind Energy Market
Wind Energy Systems
Wind Turbine Cables Market
Wind Energy Systems
Global Small Wind Power Market
Wind Energy Systems
Global Wind Power Equipment Market
Wind Energy Systems
Italy Wind Energy Market
Wind Energy Systems
Norway Wind Energy Market
Wind Energy Systems
Denmark Wind Energy Market
Wind Energy Systems
Wind Power Composite Market
Wind Energy Systems
United Kingdom Offshore Wind Energy Market
Wind Energy Systems
Iran Wind Energy Market
Wind Energy Systems
Wind Power SCADA Market
Wind Energy Systems
Europe Small Wind Turbine Market
Wind Energy Systems
Wind Electric Power Generation Market
Wind Energy Systems
Wind Turbine Scrap Market
Wind Energy Systems
South America Wind Power Market
Wind Energy Systems
Wind Turbine Nacelle Market