
 Wind Turbine Rotor Blade Market | 2026-2036
Wind Turbine Rotor Blade Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Rotor Blade Market Intelligence
The direct procurement channel between blade manufacturers and wind farm developers is reconfiguring as project owners consolidate supplier rosters around fewer, larger partners. Vestas Wind Systems leverages its integrated nacelle-blade platform to control delivery timelines across multiple continents. LM Wind Power anchors the supply base for offshore megaprojects through its specialized extra-large blade foundries. Siemens Gamesa Renewable Energy competes by sustaining one of the broadest design-type portfolios in the industry.
A wind turbine rotor blade is an aerodynamic structure typically constructed from fiberglass-reinforced polymer or carbon fiber composite, engineered to capture kinetic energy from wind and transfer rotational torque to the drivetrain generator. The component spans 40 to 120-plus meters depending on turbine rating, with pitch-controlled variable geometry optimizing energy extraction across wind speeds. Fiberglass dominates material demand for onshore units where cost sensitivity prevails, while carbon fiber captures margin pools in extra-large offshore blades where weight reduction directly lifts annual energy production. Horizontal axis designs overwhelmingly lead installed capacity, though vertical axis configurations retain niche positions in distributed urban installations.
The EU F-Gas Regulation and REACH framework restrict fluorinated gas use in blade manufacturing processes, pushing producers toward low-emission curing technologies. China's GB standards and MIIT efficiency mandates shape product specifications for blades entering the world's largest annual installation market. Germany's KBA-equivalent certification protocols for offshore structural integrity create market access thresholds that filter subscale competitors. Stakeholders must monitor evolving recyclability mandates across multiple jurisdictions as blade decommissioning volumes accumulate.
Market Dynamics
Offshore wind farm developers are consolidating supplier rosters around fewer blade manufacturers capable of delivering 100-plus meter structures, compressing procurement timelines and reshaping competitive positioning in the supply base.
Growth Catalysts
- EU F-Gas Regulation:The framework restricting fluorinated gas use in manufacturing processes is accelerating demand for low-emission curing technologies and recyclable thermoplastic resins across European blade production facilities.
- Carbon fiber composite adoption:Offshore turbine ratings climbing past 15 MW are pulling material demand toward carbon fiber where weight reduction directly lifts annual energy production in extra-large blade architectures.
- China's MIIT efficiency mandates:National standards governing wind turbine performance specifications are driving blade design upgrades across the world's largest annual installation market.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations create margin compression for fiberglass-reinforced polymer blade manufacturers serving cost-sensitive onshore segments.
- Foundry concentration in Denmark and China:Extra-large blade production capacity clusters in limited geographic zones, exposing project timelines to single-point logistics disruptions.
- REACH framework compliance costs:European chemical registration requirements impose documentation burdens on composite material suppliers serving EU wind farm developers.
Strategic Opportunities
- United States offshore lease auctions:Bureau of Ocean Energy Management lease rounds along the Atlantic coast are opening demand for specialized blade logistics and installation capabilities.
- Blade recycling infrastructure:Thermoplastic resin technologies enabling end-of-life material recovery present service revenue pools as decommissioning volumes accumulate across European wind fleets.
- Digital twin integration:Convergence of structural sensor arrays with predictive maintenance platforms is creating aftermarket service contracts tied to blade performance guarantees.
Industry Challenges
- Non-destructive testing technician scarcity:Specialized ultrasound and thermography inspection skills required for 80-plus meter blade quality assurance outpace vocational training pipeline output.
- Offshore structural certification timelines:German KBA-equivalent integrity protocols for extra-large blades extend product validation cycles, delaying revenue recognition for new designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Rotor Blade Market |
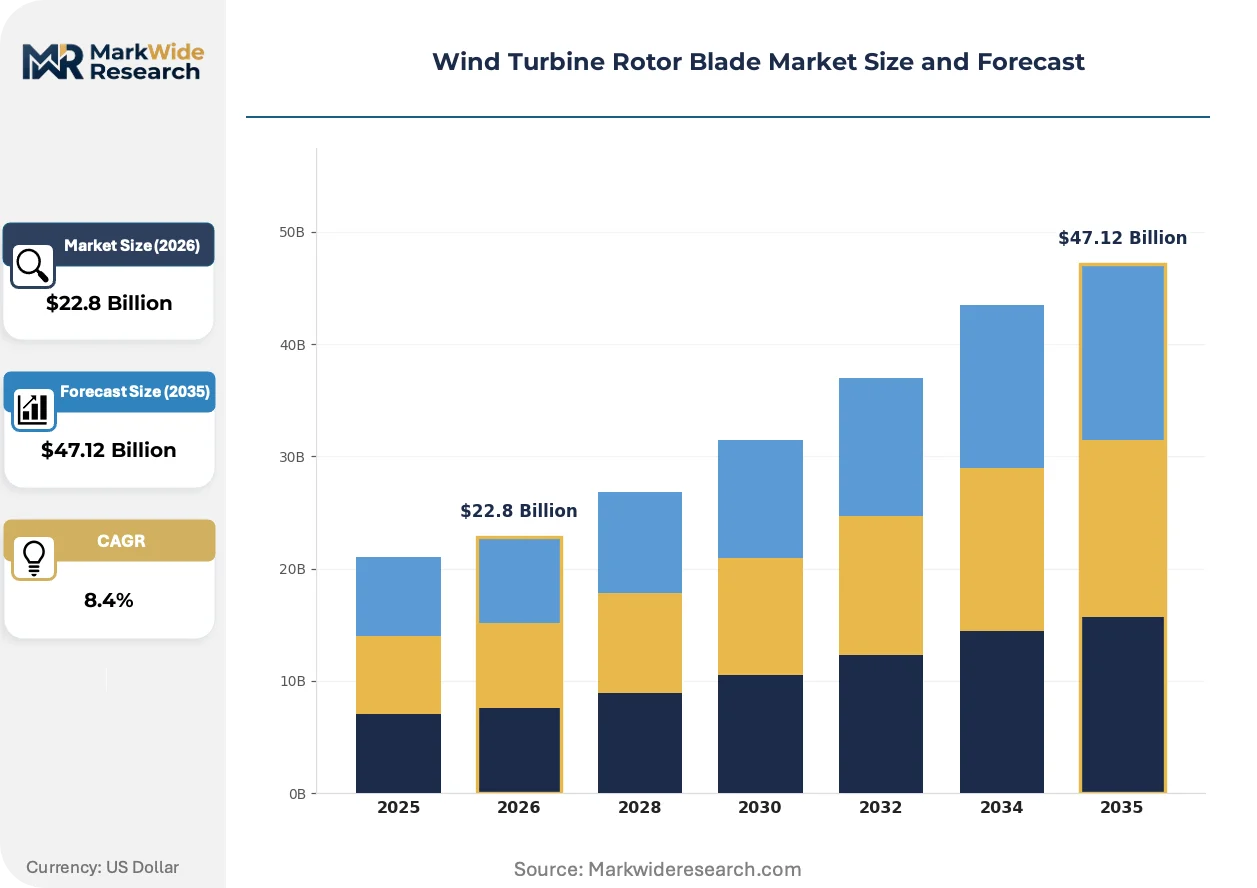
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Fiberglass, Carbon Fiber, Wood, Metal Size: Small, Medium, Large, Extra Large Design Type: Horizontal Axis, Vertical Axis, Darrieus, Savonius End User: Utilities, Independent Power Producers, Offshore Installations, Onshore Installations |
| Companies Covered | Vestas Wind Systems, Goldwind Science & Technology, LM Wind Power, Suzlon Energy Limited, MingYang Smart Energy Group, Siemens Gamesa Renewable Energy, Nordex SE, Enercon GmbH, TPI Composites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Rotor Blade Market Strategic Shifts & Innovations
Material science breakthroughs and manufacturing process automation are compressing blade production cycles while regulatory pressure on lifecycle emissions reshapes composite chemistry roadmaps.
Thermoplastic resin systems are hybridizing with conventional thermoset matrices in hybrid blade architectures. Offshore wind farm developers in Northern Europe are piloting these structures for 12-15 MW turbine classes. The technology is hybridizing supply chain relationships as chemical suppliers assume greater design partnership roles alongside traditional blade manufacturers.
REACH and the EU F-Gas Regulation are tightening chemical disclosure requirements for composite manufacturing emissions. Blade producers are reformulating resin systems and shifting curing processes to low-temperature methods. Offshore blade foundries in Denmark and Germany face the steepest compliance investment curves as they serve markets with the most stringent enforcement timelines.
Direct procurement contracts between wind farm developers and blade manufacturers are displacing tiered distributor networks. Engineering-procurement-construction firms are consolidating supplier rosters around integrated nacelle-blade platform providers. This concentration is most visible in Chinese and European offshore markets where project scale justifies dedicated manufacturing lines.
Wind Turbine Rotor Blade Market Segmentation
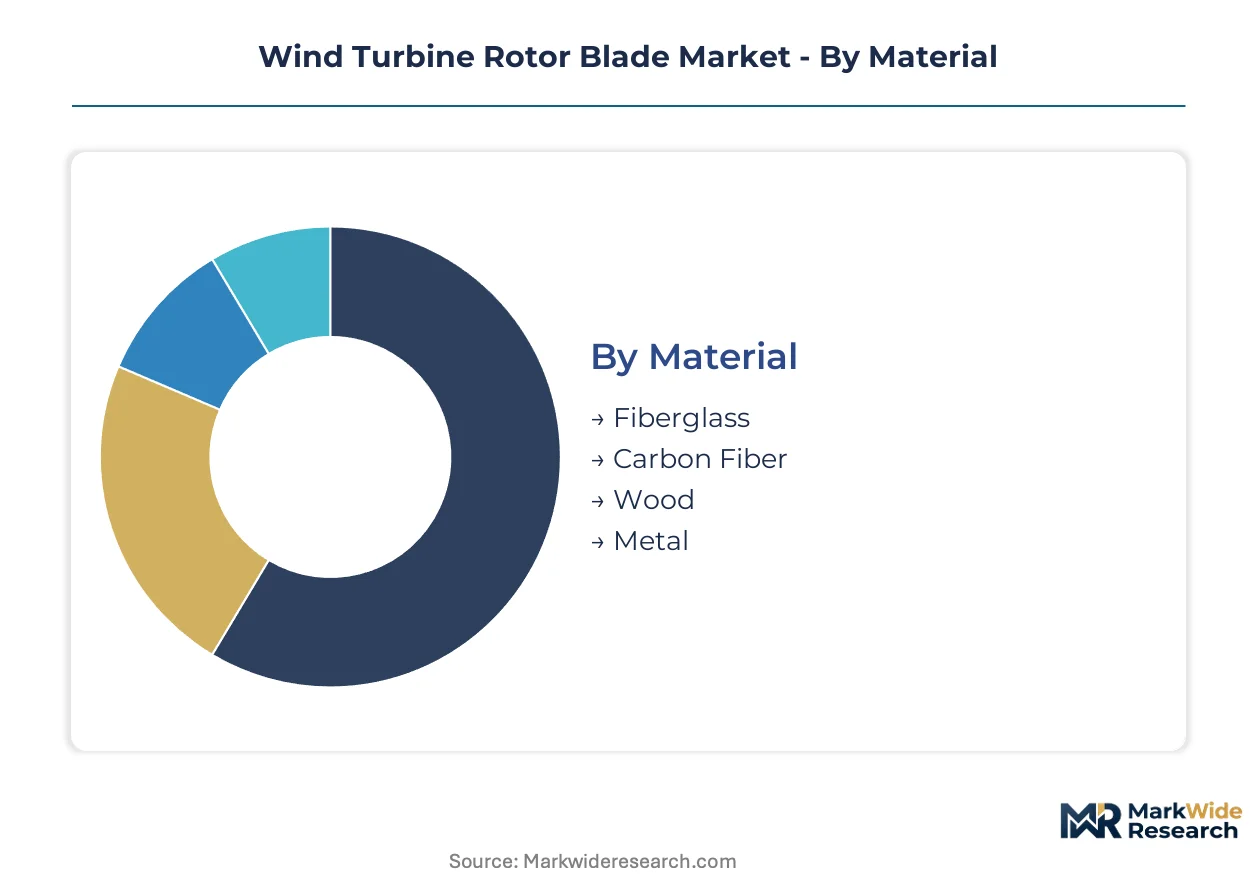
Blade segmentation reveals how material selection, dimensional scaling, and architectural design align with distinct deployment economics across onshore and offshore wind farms. Procurement patterns diverge sharply between cost-optimized utility portfolios and performance-driven offshore megaprojects.
Material:
Material chemistry governs the trade-off between structural efficiency and manufacturing cost across turbine rating tiers.
- Fiberglass:Glass-reinforced polymer composites dominate blade construction for onshore turbines below 5 MW, where resin transfer molding keeps unit economics competitive against steel alternatives. Chinese and Indian manufacturers source fiberglass from domestic petrochemical suppliers to serve cost-sensitive utility procurement in Asia-Pacific markets. Established volume favors fiberglass; emerging adoption favors carbon fiber.
- Carbon Fiber:Carbon fiber-reinforced polymers reduce blade mass by 20-30% versus fiberglass equivalents, enabling longer spans without drivetrain load penalties in 10-plus MW offshore turbines. Denmark and Germany concentrate carbon fiber blade foundries serving North Sea lease developments where annual energy production premiums justify material cost multiples.
- Wood:Laminated timber cores appear in niche distributed wind applications and heritage turbine retrofits, leveraging regional forestry supply chains in Scandinavia and Central Europe for carbon-negative credentials.
- Metal:Aluminum and steel alloys persist in small-scale vertical axis designs and experimental segmented blade prototypes where recyclability mandates drive metallic substitution research.
Cost tier stratification places fiberglass at utility-scale volume leadership; carbon fiber claims margin concentration in offshore premium segments.
Size:
Dimensional categories map directly to turbine power classes and the logistics infrastructure required for site delivery.
- Small:Blades under 20 meters serve sub-100 kW distributed turbines and rural electrification microgrids, with demand clustering in India, Brazil, and African markets where grid extension economics favor decentralized generation.
- Medium:Spans of 20-40 meters equip 1-3 MW turbines common in European and North American repowering projects, where existing tower infrastructure constrains maximum blade length.
- Large:40-70 meter blades dominate current onshore installations across China, the United States, and Australia, matching 3-6 MW drivetrains to wind resource profiles in 7-10 meter-per-second average sites.
- Extra Large:100-plus meter structures for 15-plus MW offshore turbines concentrate production in specialized foundries along Denmark's west coast and China's Jiangsu province, where deepwater port access enables direct vessel loading.
Medium and large categories anchor current installation volumes; extra large represents the steepest expansion trajectory as floating offshore platforms commercialize.
Design Type:
Aerodynamic architecture determines energy capture efficiency and structural load distribution across operating conditions.
- Horizontal Axis:Upwind three-blade configurations capture over 95% of installed capacity, with pitch control systems optimizing angle of attack across variable wind speeds. Vestas and Siemens Gamesa refine horizontal axis airfoil profiles through proprietary computational fluid dynamics pipelines.
- Vertical Axis:Omnidirectional designs eliminate yaw mechanisms, reducing maintenance burden in urban and remote installations where technician access is constrained.
- Darrieus:Eggbeater-shaped vertical axis variants achieve higher tip-speed ratios than Savonius alternatives, finding application in small-scale community wind projects across France and Quebec.
- Savonius:Drag-based vertical axis rotors prioritize starting torque over efficiency, serving water pumping and battery-charging applications in off-grid African and Southeast Asian markets.
Horizontal axis dominates utility-scale deployment; vertical axis variants retain defensible niches in distributed and urban contexts.
End User:
Customer type shapes procurement specifications, financing structures, and blade performance guarantee terms.
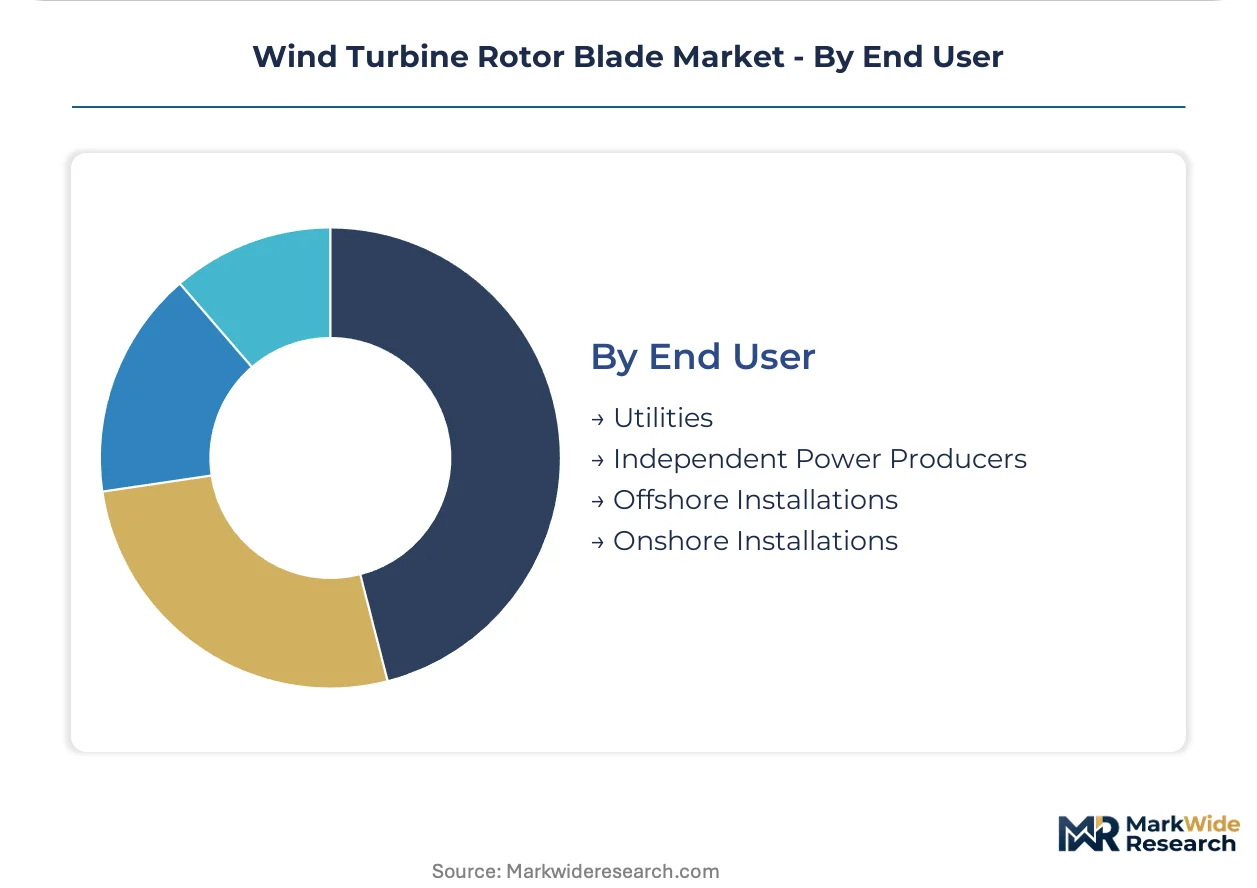
- Utilities:Vertically integrated electric utilities in China, Germany, and Spain specify blades through framework agreements spanning multiple project vintages, leveraging balance-sheet strength for volume pricing.
- Independent Power Producers:Project finance-dependent developers in the United States, United Kingdom, and Australia prioritize blade availability guarantees and liquidated damages clauses to protect construction timeline covenants.
- Offshore Installations:Specialized offshore wind farm developers in Denmark, the Netherlands, and Taiwan contract dedicated blade production lines, with Siemens Gamesa and LM Wind Power capturing dominant supply positions.
- Onshore Installations:Regional developers across Brazil, Mexico, and South Africa source blades through equipment procurement tenders tied to local content requirements and import tariff structures.
Utility procurement anchors manufacturing scale; independent power producer and offshore installation segments are concentrating supplier relationships around integrated platform providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Port of Esbjerg's deepwater quayside infrastructure underwrites Denmark's dominance in extra-large blade logistics, while China's Jiangsu province foundries feed the world's largest annual turbine installation pipeline.
China
MIIT efficiency mandates and dual carbon goals drive blade design upgrades across 3-6 MW onshore installations. GB standards govern composite material specifications for turbines entering domestic wind farms. Jiangsu province hosts specialized foundries producing 100-plus meter structures for offshore megaprojects, with direct vessel loading capabilities at Taicang and Nantong port facilities.
Denmark
North Sea lease developments pull demand for carbon fiber blades in 15-plus MW turbine classes. EU F-Gas Regulation accelerates low-emission curing technology adoption at Esbjerg and Ringkøbing production facilities. Vestas and LM Wind Power anchor blade manufacturing clusters along the west coast, serving European offshore developers through dedicated production lines.
United States
Bureau of Ocean Energy Management Atlantic lease auctions open demand for specialized blade logistics and installation capabilities. FERC interconnection queues shape project timelines for blade procurement contracts. Gulf Coast assembly facilities in Texas and Louisiana position for East Coast offshore wind farm supply, leveraging port infrastructure at Corpus Christi and New Orleans.
Germany
KBA-equivalent certification protocols for offshore structural integrity create market access thresholds filtering subscale competitors. REACH framework compliance costs reshape composite material supplier relationships serving EU developers. Bremerhaven and Cuxhaven harbor zones concentrate extra-large blade validation and staging operations for North Sea installations.
India
CEA renewable purchase obligations and state-level wind energy tenders drive blade demand for 2-3 MW repowering projects. BIS standards govern fiberglass-reinforced polymer specifications for domestic turbine manufacturers. Gujarat and Tamil Nadu host blade fabrication clusters serving western and southern wind resource zones, with Mundra and Tuticorin ports enabling coastal logistics.
Wind Turbine Rotor Blade Market Key Industry Players
On the supply side, the industry is consolidating around integrated platform providers capable of delivering 100-plus meter structures, compressing procurement timelines and reshaping vendor relationships. Three strategic archetypes dominate: European integrated turbine-blade platforms, Chinese scale-driven manufacturers, and specialized extra-large blade foundries. Competitive moves center on backward integration into carbon fiber supply chains and dedicated production line partnerships with offshore developers.
Among European integrated platforms, Vestas Wind Systems and Siemens Gamesa Renewable Energy exemplify the nacelle-blade coordination archetype, while LM Wind Power occupies a position as the specialized extra-large blade foundry serving multiple turbine OEMs. Chinese manufacturers including Goldwind Science & Technology and MingYang Smart Energy Group represent the domestic scale-driven tier, with Suzlon Energy Limited anchoring the India-focused regional specialist position.
| Leading Market Players |
|---|
| Vestas Wind Systems |
| Goldwind Science & Technology |
| LM Wind Power |
| Suzlon Energy Limited |
| MingYang Smart Energy Group |
| Siemens Gamesa Renewable Energy |
| Nordex SE |
| Enercon GmbH |
| TPI Composites |
| Others |
Cost & Logistics Intelligence
Carbon fiber prepreg supply concentrates in Japanese and German chemical conglomerates, anchoring margin capture in downstream extra-large blade architectures where weight reduction commands performance premiums. Procurement officers at offshore wind farm developers face asymmetric negotiating leverage against these feedstock suppliers, while fiberglass-reinforced polymer blade manufacturers absorb petrochemical volatility through contract pass-through clauses.
Pricing Analysis
Volume-discount tiering structures dominate blade procurement, with framework agreements spanning multiple project vintages capturing 15-20% unit cost reductions against spot purchases. Price differentiation rests on certification grade—German KBA-equivalent structural validation commands 12-18% premiums over baseline CE-marked alternatives—and geographic delivery cost differentials between coastal foundries and inland assembly sites. Cost compression in onshore fiberglass segments is intensifying because Chinese manufacturers are scaling domestic resin production, eroding European foundry cost positions. Independent power producers exhibit highest price sensitivity due to project finance covenant pressure, while utility offtakers prioritize availability guarantees over unit economics.
Supply Chain Analysis
Epoxy resin and carbon fiber tow feedstock supply draws from petrochemical complexes in China, Japan, and Germany, with bisphenol-A and acrylonitrile intermediates subject to crude oil indexation. Raw material dependencies include fiberglass roving from Chinese state-owned enterprises, carbon fiber from Toray-Mitsubishi-SGL oligopoly structures, and specialized tooling from Danish maritime engineering clusters. Single-source vulnerability concentrates in 100-plus meter mold fabrication, where three European suppliers control ultra-large thermoset curing equipment. Distribution runs through direct procurement contracts between blade foundries and wind farm developers, displacing tiered equipment distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of qualified non-destructive testing technicians for 80-plus meter blade quality assurance is constraining foundry throughput expansion, forcing procurement officers to accept extended delivery timelines or degraded inspection protocols. This capability gap rewards early movers in vocational training partnerships and automated inspection technology deployment.
For Market Incumbents: Insulate carbon fiber blade margins through backward integration into prepreg supply partnerships with Japanese chemical suppliers, locking in feedstock allocation before capacity expansion cycles. Foundry operators should secure dedicated production line contracts with North Sea offshore developers, creating revenue visibility buffers against epoxy resin price volatility. Certification investment in German KBA-equivalent structural protocols filters subscale competitors from premium offshore segments.
For New Entrants and Emerging Players: United States Gulf Coast assembly facilities represent underpenetrated white-space for Atlantic offshore lease round supply, where specialized blade logistics capabilities lag project development timelines. Brazilian and Mexican onshore wind markets offer penetrable entry points through local content compliance partnerships with regional EPC contractors. Go-to-market positioning should emphasize thermoplastic resin blade architectures that satisfy EU F-Gas Regulation compliance timelines ahead of thermoset incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized extra-large blade foundries with established port-loading infrastructure and carbon fiber handling expertise, as floating offshore platform commercialization accelerates 100-plus meter structure demand. Long-term viability favors assets with dedicated production line relationships to European and East Asian offshore developers. Monitor Bureau of Ocean Energy Management lease auction velocity as inflection indicator for Atlantic coast blade procurement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Supply | Captures margin pools from Toray and SGL oligopoly structures serving 15-plus MW offshore blade architectures. |
| Thermoplastic Resin Technology Transition | Positions manufacturers ahead of EU F-Gas Regulation enforcement timelines and end-of-life recycling mandates. |
| Dedicated Production Line Partnerships | Locks in revenue visibility with Siemens Gamesa and Vestas for North Sea floating platform developments. |
| Automated Non-Destructive Testing Deployment | Addresses technician scarcity constraining 80-plus meter blade quality assurance throughput. |
| Gulf Coast Assembly Facility Buildout | Positions for Bureau of Ocean Energy Management Atlantic lease round logistics requirements. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wind farm development executives, blade foundry operations directors, EPC contractor procurement leads, and composite materials R&D specialists. Secondary validation drew from MIIT efficiency mandate filings, EIA wind installation databases, FERC interconnection queue records, and EU ETS emissions disclosure repositories. Bottom-up blade production volume estimates were triangulated against top-down wind capacity addition forecasts across the analysis window.
Calibration approaches anchored volume projections to disclosed foundry capacity expansions at Esbjerg, Jiangsu, and Gulf Coast port zones. Segmentation dimensions modeled include material chemistry tiers, dimensional categories, aerodynamic design architectures, and end-user procurement structures. CAGRs were derived from regression analysis against historical installation correlations with crude oil price indices and carbon credit valuation trajectories. Forecast inputs incorporated floating offshore platform commercialization timelines and thermoplastic resin adoption curves.
Practitioners should monitor epoxy resin spot price volatility, EU F-Gas Regulation enforcement acceleration, and Bureau of Ocean Energy Management lease auction cadence for early signals of forecast revision. Cross-checking against IEA Wind Technology Collaboration Programme installation benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
South Korea Wind Energy Market
Wind Energy Systems
Wind Services Market
Wind Energy Systems
Germany Wind Energy Market
Wind Energy Systems
Sweden Wind Power Market
Wind Energy Systems
North America Large Wind Turbine Market
Wind Energy Systems
Brazil Wind Energy Market
Wind Energy Systems
Drone Wind Turbine Blade Inspection Market
Wind Energy Systems
Wind Turbine Tower Market
Wind Energy Systems
Asia-Pacific Wind Power Equipment Market
Wind Energy Systems
Global Wind Automation Market
Wind Energy Systems
Thailand Wind Energy Market
Wind Energy Systems
Wind Power Hubcap Market
Wind Energy Systems
Double-Fed Wind Turbine Market
Wind Energy Systems
Iran Wind Energy Market
Wind Energy Systems
Wind Turbine Decommissioning Market
Wind Energy Systems
United Kingdom Wind Energy Market