
 South America Wind Power Market | 2026-2036
South America Wind Power Market Size, Share, and Industry Trends Forecast 2026-2036
South America Wind Power Market Analytics
Modular turbine-plus-service bundling is rebalancing procurement economics for independent power producers across the Andean foothills. Vestas Wind Systems AS leverages its integrated service platform to extend contract tenures with Brazilian utilities. Neoenergia SA anchors its position through captive transmission access in the Northeast corridor. Siemens Gamesa Renewable Energy SA competes on rotor diameter scale, specializing in platforms suited to low-wind regimes.
South America wind power encompasses the generation of electricity from kinetic airflow via horizontal-axis turbines, typically sited at 80–150 meter hub heights with rotor spans exceeding 130 meters for utility-scale units. Onshore turbines dominate installed capacity, though floating installation concepts gain feasibility study traction off southern Brazil where bathymetry drops sharply. Variable-speed technology leads new orders, as direct-drive architectures displace geared units in projects targeting reduced OPEX over twenty-year asset lives. End-user concentration tilts toward utilities, which control interconnection queues and long-term offtake structures.
Brazil's ANEEL governs grid access tariffs and dispatch priority rules that shape project finance viability across state boundaries. Argentina's SEGBA legacy restructuring and Chile's SEC transmission standards create divergent compliance burdens for cross-border equipment suppliers. EMA guidelines from Mercosur harmonize emerging safety protocols for blade transport and erection crews. Stakeholders must monitor auction calendar density and local-content rule evolution to time manufacturing commitments and supplier qualification cycles.
Market Dynamics
The displacement of geared drivetrains by direct-drive permanent-magnet generators is compressing OPEX curves and resetting supplier qualification criteria across Brazilian and Argentine procurement cycles.
Growth Catalysts
- Brazil's Leilao de Energia Nova:Auction calendars channel long-term offtake commitments toward utility-scale onshore clusters, de-risking project finance for variable-speed turbine deployments in Piaui and Rio Grande do Norte.
- Variable-speed turbine technology:Direct-drive architectures eliminate gearbox maintenance burdens, extending asset life assumptions and improving debt service coverage ratios for independent power producers.
- Argentina's RenovAr program:Competitive bidding mechanisms under this framework allocate grid access rights to lowest-cost renewable bids, accelerating capacity additions in Patagonian wind corridors.
Market Restraints
- Neodymium supply concentration:Rare-earth magnet dependency for direct-drive generators ties turbine economics to Chinese processing capacity, exposing projects to input cost volatility.
- Transmission queue congestion:ANEEL interconnection backlogs in Brazil's Northeast corridor delay commercial operation dates and erode sponsor returns.
- Legacy thermal baseload contracts:Existing natural gas and coal power purchase agreements with take-or-pay clauses obstruct grid dispatch priority for new wind capacity.
Strategic Opportunities
- Chilean SEC transmission standardization:Harmonized grid codes across the Andean region enable equipment platform standardization, reducing supplier qualification costs for cross-border developers.
- Floating offshore feasibility:Bathymetric drop-offs off southern Brazil's Santa Catarina coast create viable deep-water sites for tension-leg platform demonstrations beyond fixed-foundation limits.
- Corporate PPA origination:Mining and industrial offtakers in Peru and Chile seek direct renewable supply contracts, bypassing utility intermediaries and capturing green premium valuations.
Industry Challenges
- Blade technician certification gaps:EMA Mercosur safety protocols lack harmonized training reciprocity, forcing redundant crew qualification for multi-country project portfolios.
- Capex intensity for grid reinforcement:Weak transmission infrastructure in Argentina's Comahue region requires sponsor-funded substation upgrades, inflating all-in project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Wind Power Market |
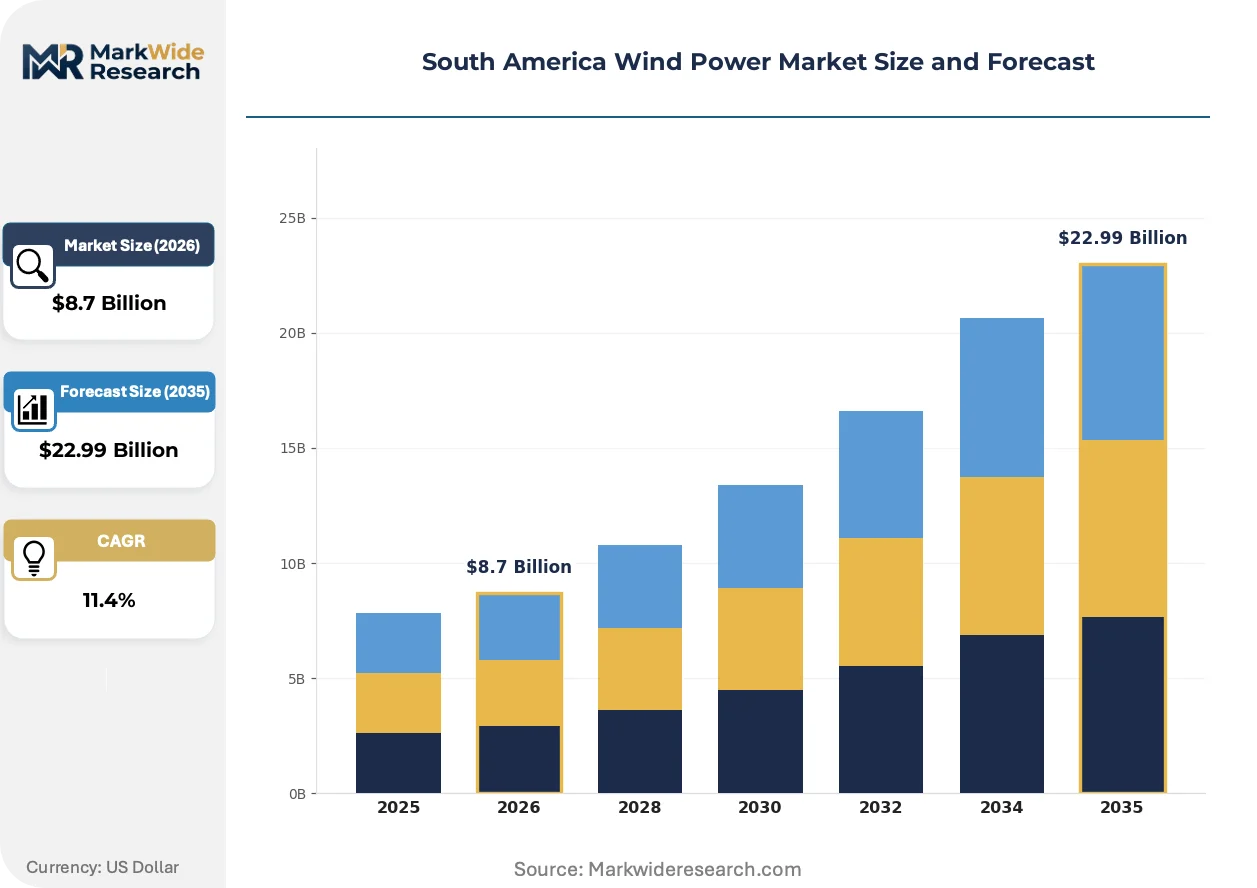
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Onshore Turbines, Offshore Turbines, Rotor Blades, Gearboxes Installation Type: Ground Mounted, Floating, Fixed, Hybrid End User: Utilities, Independent Power Producers, Government, Commercial Technology: Variable Speed, Fixed Speed, Direct Drive, Grid Connected |
| Companies Covered | Acciona Energia SA, General Electric Company, Vestas Wind Systems AS, Neoenergia SA, Nordex SE, Siemens Gamesa Renewable Energy SA, EDF SA, ABB Ltd, Xinjiang Goldwind Science & Technology Co. Ltd, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Wind Power Market Evolving Landscape
Technology convergence between turbine OEMs and digital service platforms is compressing traditional equipment-plus-maintenance procurement models into unified performance contracts.
Direct-drive permanent-magnet generators eliminate gearbox components entirely, converting rotor kinetic energy through full-power converters. Brazilian utilities with 20-year asset ownership horizons favor this architecture for its reduced lubricant and bearing replacement schedules. The technology is rewriting supplier economics by shifting revenue recognition from upfront equipment sales toward long-term availability guarantees.
Brazil's ANEEL has tightened grid code compliance requirements for frequency response and low-voltage ride-through, mandating advanced power electronics in all new interconnection requests. These rules disqualify legacy fixed-speed turbine models from auction participation. Northeast corridor developers now specify converter-rated platforms as minimum viable technology, forcing fleet standardization across sponsor portfolios.
Power purchase agreement structures are unbundling energy and environmental attribute streams, enabling mining sector offtakers in Chile to contract directly for renewable supply while utilities retain regulatory renewable energy certificates. This bifurcation disrupts traditional utility-centric procurement channels. The pattern concentrates in Atacama Desert mining clusters where energy costs dominate operational expenditures.
South America Wind Power Market Segmentation
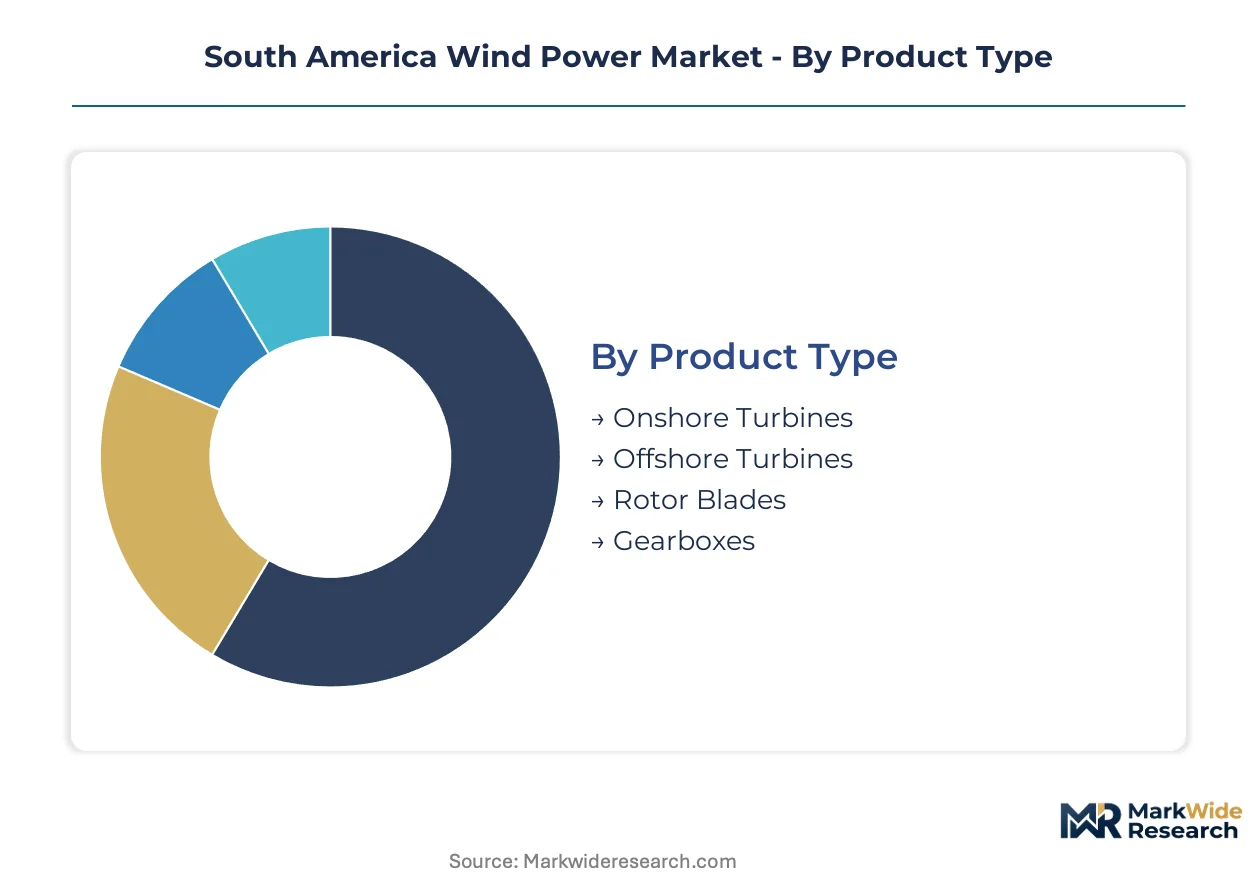
Segmentation in South American wind power reveals how technology choices, installation constraints, and buyer economics intersect across Brazil's Northeast corridor and Argentina's Patagonian zones. Equipment specifications and procurement channels diverge sharply between utility-scale auctions and corporate offtake arrangements.
Product Type:
Upgrade cycles from geared to direct-drive architectures are redefining component procurement priorities across Brazilian and Argentine project pipelines.
- Onshore Turbines:Horizontal-axis units with hub heights of 80–150 meters and rotor spans exceeding 130 meters dominate utility-scale procurement. Brazilian developers in Piaui and Rio Grande do Norte specify variable-speed platforms to meet ANEEL grid code requirements for frequency response and low-voltage ride-through.
- Offshore Turbines:Floating foundation concepts are advancing feasibility studies off Santa Catarina where bathymetry drops sharply beyond fixed-foundation limits. Prototype deployments await transmission infrastructure commitments and port logistics investment.
- Rotor Blades:Composite structures exceeding 70 meters in length require specialized transport corridors and erection protocols under EMA Mercosur safety guidelines.
- Gearboxes:Geared drivetrains face displacement as direct-drive permanent-magnet generators eliminate maintenance-intensive components from new orders.
Volume placements concentrate in Onshore Turbines; the faster expansion belongs to Offshore Turbines.
Installation Type:
Site-specific geotechnical and bathymetric conditions dictate foundation selection and capital deployment patterns across the region's diverse terrain.
- Ground Mounted:Fixed-base concrete foundations anchor the vast majority of installed capacity across Brazil's Northeast wind corridor and Argentina's Comahue region. Standardized designs reduce civil engineering costs for repeat developers with established supplier relationships.
- Floating:Tension-leg and semi-submersible platforms enable deep-water access where seabed slopes exceed fixed-foundation economic limits. Southern Brazil's steep continental shelf creates viable demonstration zones pending regulatory framework finalization.
- Fixed:Monopile and jacket structures dominate near-shore applications with water depths below 60 meters. Port infrastructure constraints limit assembly options outside specialized Brazilian facilities.
- Hybrid:Co-located wind-plus-storage configurations address grid stability concerns in remote Argentine installations with weak transmission interconnection.
Ground Mounted foundations retain dominant share; Floating platforms are climbing the fastest as bathymetric constraints reshape site selection economics.
End User:
Buyer concentration and procurement authority determine technology specification, financing structure, and long-term service contract terms.
- Utilities:State-controlled and private utilities control interconnection queues and auction participation rights across Brazil's Leilao de Energia Nova mechanism. Their 20-year asset ownership horizons favor direct-drive architectures with reduced OPEX profiles.
- Independent Power Producers:IPPs compete for grid access through competitive bidding and originate corporate PPAs with mining sector offtakers in Chile's Atacama Desert. Their capital constraints drive modular turbine-plus-service bundling to de-risk project finance.
- Government:Public sector procurement supports rural electrification and state-owned generation assets in peripheral Argentine provinces.
- Commercial:Direct renewable supply contracts bypass utility intermediaries for energy-intensive industrial operations seeking green premium valuations.
Utilities command current volume leadership; Independent Power Producers are gaining share fastest through corporate PPA origination.
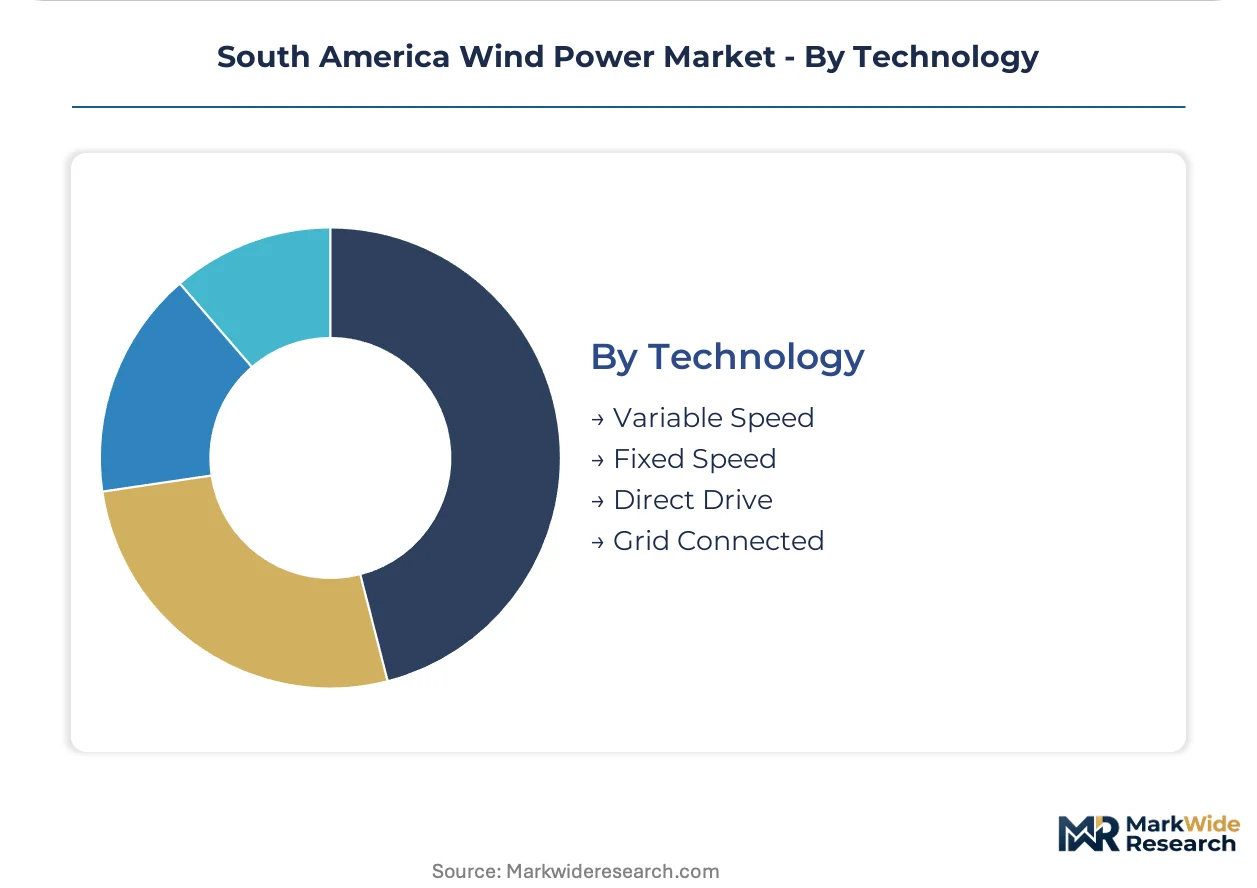
Technology:
Grid code compliance requirements and maintenance cost reduction priorities are eliminating legacy architectures from new procurement cycles.
- Variable Speed:Full-power converter systems enable precise frequency response and maximize energy capture across wind speed variations. ANEEL mandates disqualify fixed-speed alternatives from Brazilian auction participation.
- Direct Drive:Permanent-magnet generators eliminate gearbox components entirely, converting rotor kinetic energy through advanced power electronics. Rare-earth magnet dependency ties economics to Chinese neodymium processing capacity.
- Fixed Speed:Induction generator architectures with minimal power electronics face obsolescence as grid codes tighten fault-ride-through requirements.
- Grid Connected:Synchronous and asynchronous interconnection standards vary across ANEEL, SEC Chile, and Argentine regulatory frameworks, forcing equipment customization for cross-border suppliers.
Grid Connected systems anchor current deployments; Direct Drive platforms are expanding most quickly as OPEX reduction reshapes supplier economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil generates surplus wind capacity from its Northeast corridor while Argentina and Chile absorb cross-border technology transfers. Domestic production concentrates in turbine assembly and blade fabrication, with component imports bridging supply gaps.
Brazil
Piauí and Rio Grande do Norte states anchor installed capacity growth through Leilao de Energia Nova auction allocations. ANEEL governs grid access tariffs and dispatch priority rules that determine project finance timelines. Northeast wind clusters host densest project pipelines as utilities replace aging thermal baseload with variable-speed turbine fleets.
Argentina
Patagonian wind corridors in Chubut and Santa Cruz provinces attract RenovAr program competitive bidding for lowest-cost renewable capacity. The country's national energy regulator administers grid access rights under legacy SEGBA restructuring frameworks. Comahue region developers face sponsor-funded substation upgrades due to weak transmission infrastructure.
Chile
Atacama Desert mining clusters drive corporate PPA origination as energy-intensive operations seek direct renewable supply contracts. SEC transmission standards create compliance frameworks that enable equipment platform standardization across Andean projects. Antofagasta and Calama sub-regions concentrate offtake demand from copper extraction operations.
Peru
Andean foothills independent power producers scale modular turbine-plus-service bundling to de-risk project finance against currency volatility. The country's national electricity regulator oversees rural electrification programs and grid interconnection queues. Southern highland provinces host emerging wind feasibility studies for mining sector offtake arrangements.
Uruguay
Small-scale grid-connected installations supplement hydroelectric baseload through fixed-speed turbine retrofits and hybrid wind-plus-storage configurations. The national power utility manages interconnection standards aligned with Mercosur EMA safety protocols. Coastal departments concentrate early-stage floating platform feasibility assessments for deep-water resource access.
South America Wind Power Market Competitive Landscape
The competitive structure tilts toward integrated turbine-plus-service platforms over standalone equipment vendors. European and Chinese OEMs dominate auction participation through direct-drive technology portfolios, while regional utilities anchor procurement through captive transmission access. Three archetypes define positioning: full-stack technology licensors, utility-affiliated developers with grid queue control, and modular service bundlers targeting independent power producers. Capacity expansion and long-term availability guarantees constitute the dominant competitive moves reshaping contract economics.
Among European-headquartered OEMs, Vestas Wind Systems AS and Siemens Gamesa Renewable Energy SA exemplify integrated platform strategies spanning equipment supply and multi-decade service contracts. Neoenergia SA occupies a position as a utility-affiliated developer leveraging transmission access in Brazil's Northeast corridor. Chinese turbine fabricators including Xinjiang Goldwind Science & Technology Co. Ltd represent cost-optimized direct-drive architectures competing on rotor diameter scale for low-wind regime suitability.
| Leading Market Players |
|---|
| Acciona Energia SA |
| General Electric Company |
| Vestas Wind Systems AS |
| Neoenergia SA |
| Nordex SE |
| Siemens Gamesa Renewable Energy SA |
| EDF SA |
| ABB Ltd |
| Xinjiang Goldwind Science & Technology Co. Ltd |
| Others |
Value Network & Pricing Analysis
Brazil's ANEEL local-content mandates gate qualified supply access and premium-tier pricing for turbine-plus-service bundles across the Northeast corridor. These requirements compress procurement economics for developers unable to demonstrate domestic assembly thresholds, forcing price stratification between compliant and non-compliant supplier tiers.
Pricing Analysis
Margin tightening in utility-scale contracts reflects direct-drive generator cost premiums and rare-earth magnet price volatility. Three-tier pricing structure across premium, standard, and economy levels separates integrated service platforms from standalone equipment sales. Price differentiation hinges on ANEEL certification status and captive transmission access arrangements. Mining sector offtakers in Chile exhibit lowest price sensitivity due to energy cost dominance in operational expenditures, while rural electrification programs in peripheral Argentine provinces face acute budget constraints.
Supply Chain Analysis
Refurbishment flows for gearbox components from decommissioned geared turbines create secondary supply channels for maintenance-intensive legacy fleets. Component sourcing concentrates in China for rare-earth magnet processing, Denmark for blade design engineering, and Brazil for nacelle assembly. Raw material dependencies span neodymium for permanent magnets, carbon fiber for blade structures, and copper for power electronics. Single-source vulnerability in Chinese magnet processing exposes project economics to export restriction risks. Distribution runs through EPC contractors with established port logistics capabilities at Pecém and Suape.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America wind power market is consolidating around integrated turbine-plus-service platforms as ANEEL grid code compliance costs eliminate standalone equipment vendors. Direct-drive technology migration and local-content mandates are forcing weaker capitalized players toward exit or acquisition.
For Market Incumbents: Anchor market position through captive transmission access in Brazil's Northeast corridor and backward integration into blade fabrication. Siemens Gamesa and Vestas should expand service contract tenures to lock in utility relationships against Chinese OEM price competition. Defensive consolidation into nacelle assembly capacity within Mercosur trade zones preserves tariff-advantaged supply positioning. For New Entrants and Emerging Players: Launch via corporate PPA origination with Chilean mining sector offtakers in Atacama Desert clusters where energy cost sensitivity creates immediate value propositions. Floating offshore feasibility studies off Santa Catarina represent the most penetrable white space, pending regulatory framework finalization. Modular turbine-plus-service bundling de-risks project finance for independent power producers with limited balance sheet capacity. For Investors and Strategic Acquirers: Argentina's RenovAr auction calendar density is the leading indicator that Patagonian wind corridors are approaching investment-grade scale. Acquisition targets should display utility-affiliated developer positioning with established grid queue access rather than pure equipment manufacturing exposure. Monitor ANEEL interconnection backlog clearance rates as the signal for sponsor return recovery and debt market reopening.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Direct-drive turbine deployment in Piaui and Rio Grande do Norte accelerates utility procurement cycles under Leilao de Energia Nova. |
| Power Purchase Agreement | Corporate PPAs with Antofagasta mining operations bypass utility intermediaries and capture green premium valuations. |
| Technology Licensing | Floating foundation patents from European OEMs enable deep-water access where Santa Catarina bathymetry drops sharply. |
| Backward Integration | Captive blade fabrication within Brazil satisfies ANEEL local-content thresholds and insulates against import tariff exposure. |
| Green Certification Program | EMA Mercosur safety protocol harmonization reduces redundant crew qualification costs for multi-country project portfolios. |
Research Methodology
Independent corroboration across utility planning officers, IPP project developers, EPC contractors, and grid operators underwrites the qualitative findings presented in this analysis. Primary interviews with ANEEL regulatory affairs leads and SEC Chile transmission standards engineers combined with secondary validation from EIA data, IEA renewable energy reports, FERC comparable market filings, and project development databases. Bottom-up capacity addition tracking and top-down auction allocation analysis triangulate to segment-level outputs.
Rate-of-change decomposition across the analysis window separates volume growth from price evolution in direct-drive turbine procurement. The analytical framework models segmentation by fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type. CAGRs derive from installed capacity buildout trajectories and auction calendar density patterns. Forecast inputs incorporate ANEEL interconnection queue clearance rates and neodymium price index movements.
Regulatory calendar delays, rare-earth export restriction triggers, and transmission infrastructure commitment shortfalls are the dominant revision risks to the forecast framework. Practitioners should monitor ANEEL auction schedule density, Chinese magnet processing capacity utilization, and Brazil's Northeast corridor substation commissioning timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
Global Offshore Wind Market
Wind Energy Systems
Wind Power Market
Wind Energy Systems
Offshore Wind Turbine Blade Leading-Edge Defect Inspection Equipment Market
Wind Energy Systems
Asia-Pacific Wind Power Equipment Market
Wind Energy Systems
Wind Energy Market
Wind Energy Systems
Wind Turbine Decommissioning Market
Wind Energy Systems
Wind Turbine Nacelle Market
Wind Energy Systems
United Kingdom Renewable Energy Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
Portugal Wind Energy Market
Wind Energy Systems
Airborne Wind Turbines Market
Wind Energy Systems
Iran Wind Energy Market
Wind Energy Systems
Wind Turbine Market
Wind Energy Systems
Wind Cones Market
Wind Energy Systems
Global Small Wind Market