
 Wind Power SCADA Market | 2026-2036
Wind Power SCADA Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Power SCADA Market Analytics
The capability gap between full-stack platform providers and component specialists is rotating capital allocation across the competitive landscape. Siemens leverages its industrial software heritage to anchor integrated turbine-to-grid offerings. GE Renewable Energy sustains offshore-focused SCADA architectures through its service footprint in North Sea installations. Bachmann electronic GmbH specializes in ruggedized control hardware for harsh-environment turbine nacelles.
Wind Power SCADA denotes supervisory control and data acquisition systems purpose-built for wind energy assets, typically integrating programmable logic controllers, fiber-optic or wireless communication links, and human-machine interfaces capable of millisecond-level turbine parameter polling. These systems enable centralized fleet management, predictive maintenance scheduling, and grid-compliant power output regulation across dispersed generation portfolios. Monitoring systems capture the largest installed base given their role in warranty compliance and insurance validation, while edge computing architectures represent the fastest-expanding technology dimension as latency-sensitive pitch and yaw control migrates toward turbine-level processing. Cloud computing platforms increasingly host long-term analytics and machine learning model training, creating distinct margin pools separate from real-time operational layers.
IEC 61400-25 standardization from the International Electrotechnical Commission shapes data model interoperability across multi-vendor wind farms, while China's GB standards and NMPA-equivalent grid access rules enforce cybersecurity hardening for domestic installations. The EU AI Act and GDPR frameworks impose algorithmic transparency and data residency requirements on predictive analytics modules deployed across European wind fleets. Stakeholders must evaluate whether to build proprietary edge-to-cloud stacks or adopt open-architecture platforms that accommodate evolving certification requirements across jurisdictions.
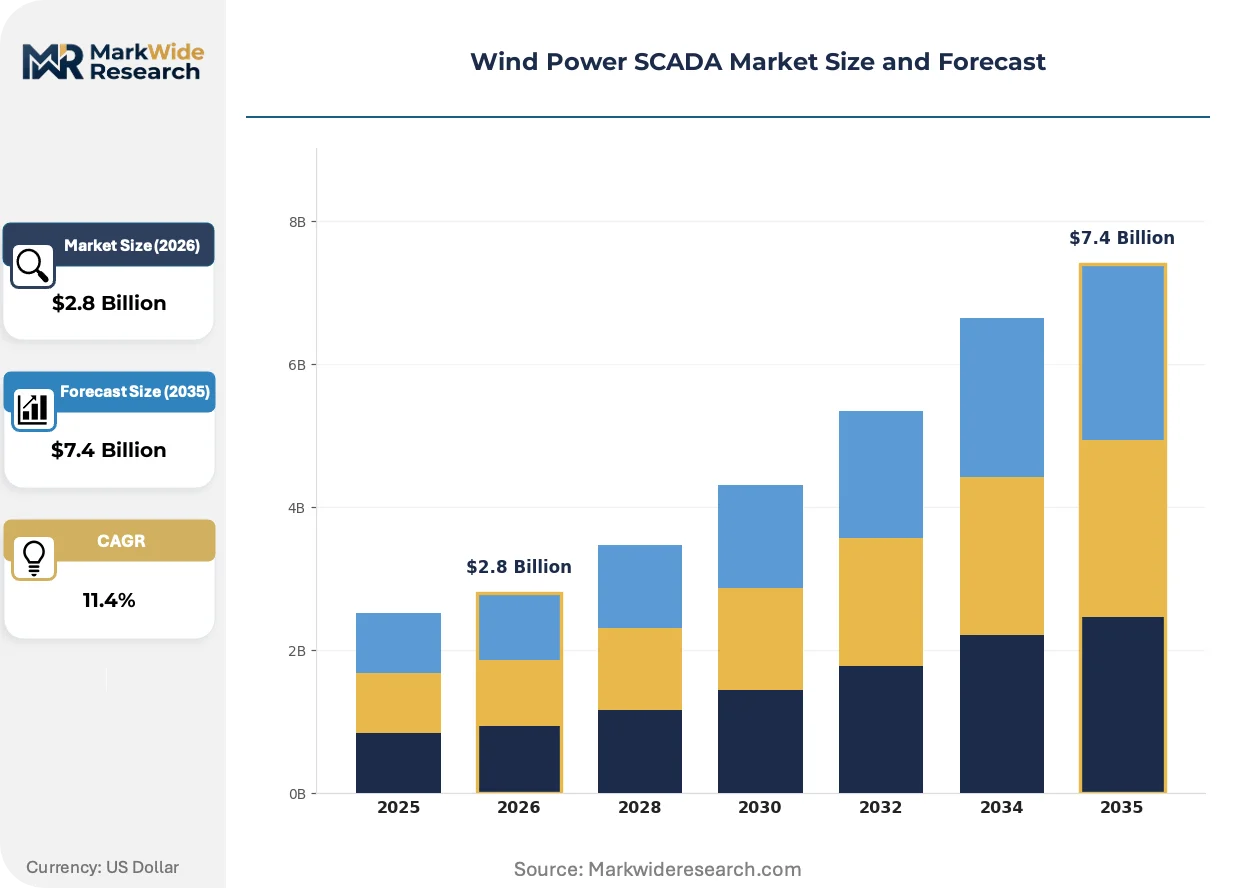
Market Dynamics
The offshore wind buildout is compressing SCADA procurement cycles as developers seek unified turbine-to-grid platforms capable of sub-second fault response across geographically dispersed arrays.
Growth Catalysts
- EU grid code harmonization:Network operators in Germany, Denmark, and the Netherlands now require IEC 61400-25-compliant data interoperability, forcing multi-vendor fleet standardization and replacement of legacy proprietary systems.
- China's dual carbon mandate:Provincial energy bureaus enforce real-time monitoring for grid access certification, accelerating SCADA deployment across Inner Mongolia and coastal offshore zones.
- Edge-to-cloud architecture migration:Turbine OEMs and independent service providers are rebuilding control hierarchies to process pitch regulation locally while streaming telemetry to centralized analytics platforms.
Market Restraints
- Semiconductor supply concentration:Industrial-grade PLCs and fiber-optic transceivers depend on foundry capacity concentrated in Taiwan and South Korea, exposing lead times to geopolitical disruption.
- Cybersecurity compliance layering:China's GB standards, the EU AI Act, and US FERC supply chain rules impose overlapping certification requirements that fragment vendor development roadmaps.
- Skilled commissioning engineer scarcity:Specialized technicians capable of integrating turbine-level controllers with substation SCADA remain concentrated in Northern European and Chinese coastal labor markets.
Strategic Opportunities
- Floating offshore wind expansion:Dynamic cable and platform motion monitoring create demand for hardened SCADA architectures in Portuguese, Scottish, and Japanese demonstration projects.
- Predictive maintenance module unbundling:Insurance underwriters and independent asset managers are procuring condition monitoring analytics separately from OEM control systems.
- Green hydrogen co-location:Electrolyzer integration requires SCADA platforms capable of arbitrating power flows between grid export, curtailment, and hydrogen production scheduling.
Industry Challenges
- Multi-decade software lifecycle management:Twenty-five-year asset lives exceed vendor support commitments for embedded control firmware, forcing owner-operators to maintain deprecated codebases or fund expensive migrations.
- Interoperability testing complexity:Each new turbine model introduction requires recertification against existing SCADA installations, compressing deployment windows for fleet expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Power SCADA Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Systems, Control Systems, Data Acquisition Systems, Security Systems Technology: SCADA Software, Communication Protocols, Cloud Computing, Edge Computing End User: Utilities, Independent Power Producers, Government Agencies, Industrial Users Installation: Onshore, Offshore, Hybrid, Retrofitting |
| Companies Covered | Emerson Electric, Bachmann electronic GmbH, Siemens, Envision, Shanghai Electric, GE Renewable Energy, Goldwind, Gamesa, Vestas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Power SCADA Market Evolving Landscape
Control architecture decisions are splitting the vendor landscape between integrated platform providers and modular component specialists as latency requirements diverge across application layers.
Edge computing deployment is bifurcating SCADA hardware procurement. Turbine manufacturers embed millisecond-response controllers directly into nacelle systems for pitch and yaw regulation. Fleet operators simultaneously contract cloud-hosted analytics platforms for long-term performance benchmarking. This functional split is compressing margins for mid-tier integrators lacking strength in either real-time control or machine learning infrastructure.
GDPR and the EU AI Act are reshaping algorithmic transparency requirements. Predictive maintenance modules deployed across European wind fleets must now document training data provenance and decision audit trails. German and Danish operators are prioritizing SCADA vendors with pre-certified explainability frameworks, displacing black-box anomaly detection systems that dominated early deployments.
Service contract structures are unbundling hardware from analytics subscriptions. Independent power producers in Texas and the UK are negotiating SCADA procurement as separate control infrastructure and software-as-a-service agreements. This purchasing pattern shifts vendor revenue toward recurring data platform fees and compresses upfront system integration margins.
Wind Power SCADA Market Segmentation
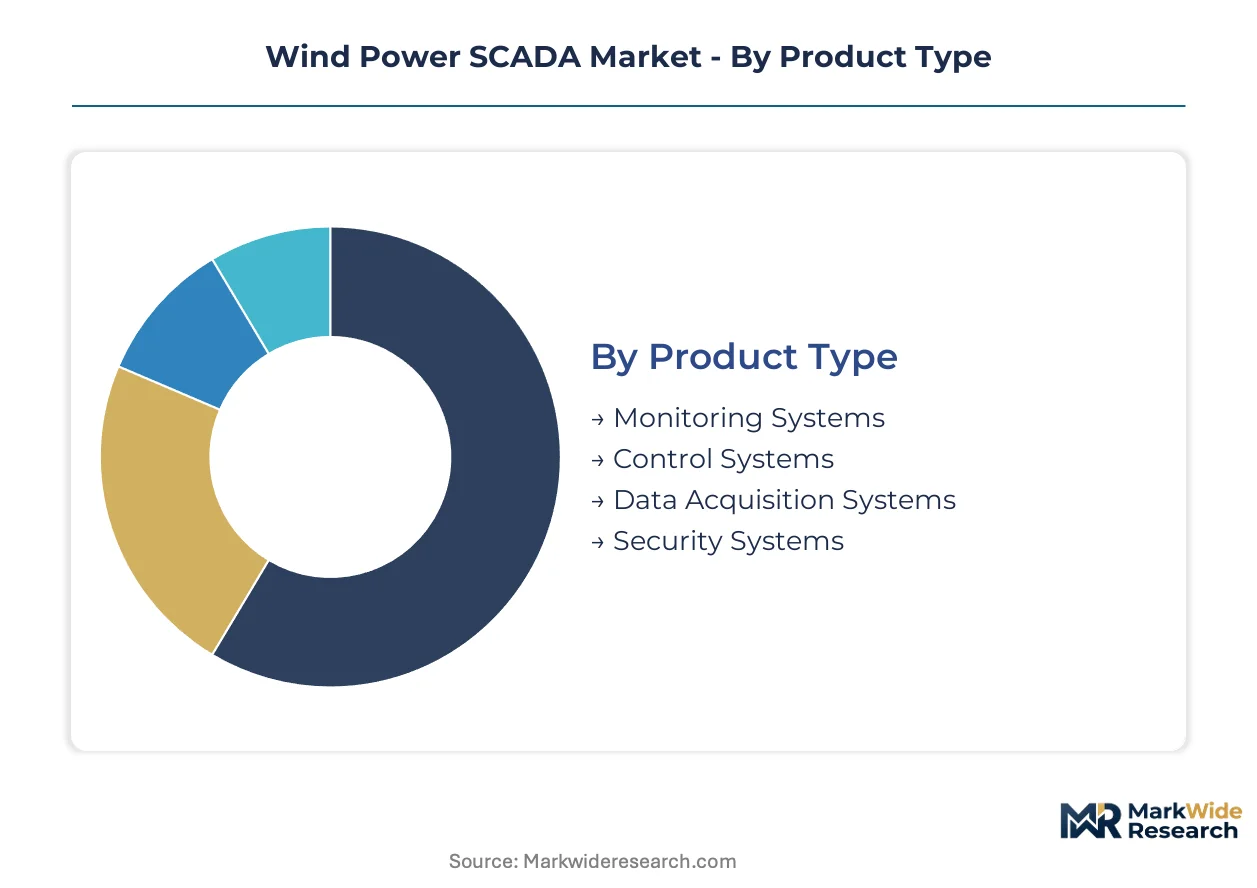
SCADA procurement patterns diverge sharply across turbine scale and operational environment, with offshore operators demanding hardened architectures that onshore fleets rarely require. Technology choices cascade through twenty-year asset lifecycles, locking owner-operators into specific vendor ecosystems and interoperability constraints.
Product Type:
Monitoring Systems face intensifying substitution pressure from third-party condition monitoring platforms that bypass OEM control hierarchies entirely.
- Monitoring Systems:These platforms aggregate vibration, temperature, and power curve data for warranty compliance and insurance validation. Demand concentrates among independent power producers in Texas and the UK seeking to unbundle analytics from turbine purchase agreements.
- Control Systems:Programmable logic controllers execute millisecond-level pitch and yaw regulation directly within turbine nacelles. German and Danish offshore operators prioritize IEC 61400-25-compliant architectures to enable multi-vendor fleet standardization.
- Data Acquisition Systems:Fiber-optic and wireless sensor networks stream telemetry from turbine-level controllers to centralized dispatch centers.
- Security Systems:Cybersecurity modules enforce GB standards in China and GDPR-aligned data residency in European installations.
Monitoring Systems anchors the volume base while Control Systems gains share at the steepest rate as latency requirements tighten for offshore arrays.
Technology:
Cost tier differentiation separates premium real-time control stacks from commoditized cloud analytics platforms.
- SCADA Software:Human-machine interface suites and historian databases manage alarm workflows and long-term performance archiving. Utilities in Germany and the United States favor subscription-based licensing to decouple software costs from hardware procurement cycles.
- Communication Protocols:IEC 61400-25, OPC UA, and proprietary fiber-optic standards govern turbine-to-substation data exchange. China's provincial energy bureaus mandate protocol compliance for grid access certification across Inner Mongolia wind zones.
- Cloud Computing:Centralized platforms host machine learning model training and fleet-wide performance benchmarking.
- Edge Computing:Turbine-embedded processors execute fault-ride-through and power regulation without cloud latency.
SCADA Software dominates current procurement value while Edge Computing expands most quickly as pitch control migrates toward nacelle-level processing.
End User:
Application requirements fragment across customer types with divergent risk tolerances and regulatory exposure.
- Utilities:Vertically integrated grid operators deploy SCADA across owned generation portfolios to meet NERC CIP and FERC supply chain compliance. Procurement emphasizes twenty-five-year support commitments and spare parts availability.
- Independent Power Producers:Non-utility developers negotiate separate control infrastructure and analytics subscriptions to preserve financing flexibility. Texas and UK IPPs drive unbundling of hardware from software-as-a-service agreements.
- Government Agencies:State-owned enterprises in China coordinate SCADA deployment with provincial dual carbon targets and real-time monitoring mandates.
- Industrial Users:Corporate offtakers integrate wind assets behind-the-meter with on-site electrolyzer or manufacturing loads.
Utilities anchors the volume base while Independent Power Producers gains share at the steepest rate as merchant wind development accelerates.
Installation:
Geography and seabed conditions dictate hardware specifications more than any other segmentation dimension.
- Onshore:Established turbine configurations in flat terrain and moderate climates require standard PLC architectures with wireless backhaul. Demand concentrates in China's northern provinces and the US Great Plains where installed capacity additions continue.
- Offshore:Salt spray, dynamic cables, and platform motion monitoring necessitate ruggedized control hardware and redundant communication links. Portuguese, Scottish, and Japanese demonstration projects pioneer floating foundation SCADA integration.
- Hybrid:Co-located solar-wind-storage assets share SCADA platforms for unified dispatch and grid interconnection.
- Retrofitting:Legacy turbine fleets upgrade proprietary systems to IEC 61400-25-compliant architectures for multi-vendor interoperability.
Onshore anchors the volume base while Offshore gains share at the steepest rate as buildout accelerates in North Sea and East Asian waters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in German offshore SCADA deployments runs 40-50% above comparable Chinese onshore installations, reflecting certification complexity and labor specialization premiums. This asymmetry channels vendor investment toward North Sea service capabilities while compressing margins in standardized domestic markets.
China
Provincial energy bureaus in Inner Mongolia and coastal offshore zones enforce real-time monitoring mandates under dual carbon targets. GB standards and NMPA-equivalent grid access rules require cybersecurity hardening for domestic SCADA installations. Shanghai Electric and Goldwind anchor manufacturing clusters in the Yangtze River Delta, supplying integrated turbine-to-grid platforms for provincial wind zones.
Germany
North Sea offshore operators demand IEC 61400-25-compliant architectures for multi-vendor fleet standardization. The EU AI Act and GDPR impose algorithmic transparency requirements on predictive analytics modules deployed across German wind fleets. Siemens leverages industrial software heritage from Bavaria to anchor integrated offerings serving Danish and Dutch interconnected arrays.
United States
Independent power producers in Texas drive unbundling of hardware from software-as-a-service agreements. FERC supply chain rules and NERC CIP compliance shape utility procurement emphasizing twenty-five-year support commitments. GE Renewable Energy sustains offshore-focused architectures through service footprints in Atlantic Coast demonstration projects.
United Kingdom
Scottish floating offshore demonstration projects pioneer dynamic cable and platform motion monitoring for hardened SCADA architectures. The UK regulator enforces data residency requirements aligned with GDPR frameworks for North Sea installations. Vestas and Gamesa service clusters concentrate in Hull and Aberdeen, supporting Dogger Bank and Moray East array commissioning.
Denmark
Network operators require sub-second fault response capabilities across geographically dispersed offshore arrays. Danish labor markets concentrate specialized commissioning engineers capable of integrating turbine-level controllers with substation SCADA. Ørsted's Bornholm Energy Island project tests edge-to-cloud architectures for Baltic Sea floating foundation integration.
Wind Power SCADA Market Competitive Landscape
Concentration sits with diversified industrial conglomerates possessing embedded software heritage and offshore service infrastructure. The vendor base spans three tiers: full-stack platform providers integrating turbine-to-grid offerings, component specialists in ruggedized control hardware, and regional turbine OEMs with captive SCADA development. Siemens and GE Renewable Energy exemplify the integrated archetype, while Bachmann electronic GmbH occupies the specialist tier. Competitive moves center on strategic partnerships for floating offshore certification and portfolio diversification into predictive maintenance analytics.
Within the integrated platform tier, Siemens and GE Renewable Energy exemplify vendors leveraging industrial software heritage and offshore service footprints respectively. Bachmann electronic GmbH anchors the component specialist archetype through ruggedized control hardware capabilities. Chinese turbine OEMs including Envision, Goldwind, and Shanghai Electric occupy a distinct tier built on domestic volume scale and provincial certification relationships. Emerson Electric represents the automation conglomerate archetype, applying cross-industrial control expertise to wind-specific latency requirements. Vestas and Gamesa sit within the European turbine OEM cluster, bundling SCADA with turbine supply agreements across North Sea markets.
| Leading Market Players |
|---|
| Emerson Electric |
| Bachmann electronic GmbH |
| Siemens |
| Envision |
| Shanghai Electric |
| GE Renewable Energy |
| Goldwind |
| Gamesa |
| Vestas |
| Others |
Value Network & Pricing Analysis
Long-term service agreements lock in both semiconductor supply access and price visibility for wind farm operators negotiating twenty-five-year SCADA support commitments across German and Chinese installations.
Pricing Analysis
Configured-to-order pricing for IEC 61400-25-compliant offshore architectures commands substantial premiums over standardized onshore PLC configurations. Subscription-based SaaS licensing for cloud analytics platforms is displacing perpetual software licenses as independent power producers in Texas and the UK unbundle hardware procurement from recurring data platform fees. Certification-grade differentiation separates premium ruggedized control systems meeting GB standards and GDPR frameworks from economy-tier monitoring-only deployments. Price differentiation stems from cybersecurity hardening requirements and edge computing latency specifications. Margins are tightening in commoditized cloud analytics tiers as hyperscaler infrastructure costs compress vendor profitability.
Supply Chain Analysis
Taiwan and South Korea anchor foundry production of industrial-grade PLCs and fiber-optic transceivers essential for turbine nacelle controllers. China concentrates manufacturing of ruggedized control hardware and wireless sensor networks serving domestic wind zones. Germany specializes in precision-engineered substation SCADA integration components for North Sea arrays. The supply chain draws from rare earth elements for magnetic components in pitch control systems, copper for power electronics, and specialized polymers for cable insulation. Single-source vulnerability concentrates in advanced semiconductor nodes for real-time processing chips. Distribution runs through turbine OEM captive channels, independent system integrators, and direct utility procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commissioning engineers capable of integrating turbine-level controllers with substation SCADA remain scarce across Northern European and Chinese coastal labor markets, constraining deployment velocity for floating offshore expansion projects.
For Market Incumbents: Compound software heritage advantages by deepening predictive maintenance analytics capabilities and securing IEC 61400-25 certification pre-approvals for emerging floating foundation architectures. Vertically integrate edge computing hardware production to defend against component specialists encroaching on nacelle control margins. Prioritize twenty-five-year support commitment structures that lock out independent service providers from aftermarket revenue pools. For New Entrants and Emerging Players: GB standards fast-track certification for domestic Chinese installations offers the most penetrable entry pathway for specialized cybersecurity module developers. Target floating offshore demonstration projects in Portugal and Japan where hardened SCADA architectures face limited incumbent saturation. Pursue insurance underwriter partnerships for condition monitoring analytics unbundled from OEM control hierarchies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with pre-certified explainability frameworks aligned with EU AI Act algorithmic transparency requirements. Long-term viability favors platforms combining real-time edge control with cloud-hosted machine learning infrastructure across the analysis window. Acquisition targets should demonstrate spare parts availability commitments spanning full asset lifecycles. Monitor FERC supply chain rule enforcement intensity as an inflection indicator for utility procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-to-Cloud Architecture Migration | Enables millisecond pitch regulation at turbine level while streaming telemetry to centralized analytics platforms across dispersed North Sea arrays. |
| IEC 61400-25 Certification Investment | Unlocks multi-vendor fleet standardization opportunities mandated by German, Danish, and Dutch network operators for offshore interoperability. |
| Predictive Maintenance Module Unbundling | Captures insurance underwriter and independent asset manager procurement separate from OEM control system bundling in Texas and UK markets. |
| Floating Offshore SCADA Development | Addresses dynamic cable and platform motion monitoring requirements for Portuguese, Scottish, and Japanese demonstration projects. |
| Green Hydrogen Integration Capability | Supports power flow arbitration between grid export, curtailment, and electrolyzer scheduling for co-located renewable hydrogen production. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FERC filings, IEA wind deployment databases, IEC standardization documentation, and provincial energy bureau procurement records. Primary interviews engaged utility planning officers, independent power producer project developers, EPC contractors specializing in offshore arrays, grid operators enforcing real-time monitoring mandates, and turbine OEM control system architects. Bottom-up triangulation aggregated individual project SCADA procurement values while top-down validation cross-checked against national wind capacity addition targets and technology cost trajectories.
Segmentation dimensions modeled span product type, technology architecture, end-user category, and installation environment across the projection horizon. Analytical framework incorporated edge computing adoption curves, cloud platform migration rates, and regulatory compliance layering effects. CAGRs were derived from installed capacity forecasts, technology substitution elasticity estimates, and pricing trajectory assumptions for hardware versus software revenue mix. Industry-specific inputs included offshore buildout pipelines, floating foundation demonstration timelines, and hydrogen co-location project announcements.
Underlying assumptions cover semiconductor supply normalization, certification timeline adherence, and skilled labor availability, with deviation risk concentrated in geopolitical disruption to Taiwan and South Korea foundry capacity. Forecasts reflect these conditions without guarantee of realization. Recalibration cycles align with material shifts in EU grid code harmonization, China's dual carbon enforcement intensity, and floating offshore commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Brazil Wind Energy Market
Wind Energy Systems
Chile Wind Energy Market
Wind Energy Systems
Wind Power Converter Systems Market
Wind Energy Systems
Small Scale Single and Multi-Rotor Wind Turbine Market
Wind Energy Systems
Boat Wind Turbine Market
Wind Energy Systems
Wind Power Forgings Market
Wind Energy Systems
Egypt Wind Energy Market
Wind Energy Systems
Multi-Rotor Wind Turbine Market
Wind Energy Systems
Wind Turbine Rotor Blade Market
Wind Energy Systems
Portugal Wind Energy Market
Wind Energy Systems
Latin America Wind Turbine Market
Wind Energy Systems
Poland Wind Energy Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Wind Power Couplings Market
Wind Energy Systems
Spain Wind Energy Market
Wind Energy Systems
South Korea Wind Energy Market