
 Steel Wind Tower Market | 2026-2036
Steel Wind Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Wind Tower Market Outlook
A shift from outsourced plate sourcing to captive steel supply is recalibrating cost structures across the tower supply chain. CS Wind Corporation leverages integrated Korean and Vietnamese production bases to anchor its position in Asian offshore contracts. EEW Group sustains heavy-plate rolling capacity at its Rostock facility, dominating North European demand for monopile transition pieces. Valmont Industries competes through domestic US tower fabrication, controlling logistics costs for utility-scale onshore projects.
Steel wind towers are welded tubular or lattice structures fabricated from high-strength structural steel plate, typically S355 or S460 grade, with wall thickness exceeding 80 millimeters at base sections to withstand cyclic wind and wave loading. Their primary purpose is to elevate nacelle-and-rotor assemblies to optimal wind capture heights while transferring mechanical loads to foundation substructures. Tubular towers occupy the bulk of installed capacity, though lattice designs retain share in emerging markets where transport weight limits constrain monopole delivery. Offshore technology commands premium engineering intensity due to corrosion protection and dynamic load specifications, while onshore installations sustain volume leadership across utility and independent power producer procurement channels.
The EU Green Deal and F-Gas Regulation are tightening embodied-carbon thresholds for imported steel, reshaping supplier qualification criteria for European project tenders. China's MIIT dual carbon goals and GB standards on structural steel are accelerating domestic electric-arc furnace capacity expansion for tower-grade plate. ISO welding certification and IEC 61400 structural design standards govern market access for fabricators serving international developers. Stakeholders must monitor evolving domestic content rules and carbon-border adjustment mechanisms to secure long-term offtake visibility.
Market Dynamics
The tower supply chain is consolidating around captive steel plate production as developers demand certified low-carbon sourcing and domestic fabrication under tightening EU Green Deal content rules.
Growth Catalysts
- EU Green Deal domestic content mandates:European offshore auctions now require 50-65% locally fabricated steel content, redirecting procurement toward integrated mills with blast furnace or EAF capacity near port clusters.
- High-strength S460 grade plate adoption:Advanced metallurgy permits thinner wall sections at equivalent load-bearing capacity, reducing transport weight and enabling taller hub heights for stronger wind resource capture.
- Offshore wind farm scale-up:Gigawatt-scale North Sea projects are driving demand for monopile transition pieces exceeding 2,000 tonnes, concentrating orders at heavy-plate rolling facilities with dedicated quayside access.
Market Restraints
- Scrap-fed EAF capacity constraints:Tower-grade structural plate requires controlled chemistry that legacy electric-arc furnaces struggle to achieve, limiting low-carbon steel supply expansion.
- North Sea port congestion:Specialized heavy-lift vessels and dedicated storage yards at Rostock, Cuxhaven, and Esbjerg face scheduling bottlenecks during installation windows.
- High-strength steel fatigue certification:IEC 61400-1 design standards impose extended testing protocols for welded S460 joints, lengthening qualification timelines for new fabricators.
Strategic Opportunities
- US Inflation Reduction Act manufacturing credits:Section 45X advanced manufacturing production credits are incentivizing domestic tower fabrication investments to serve Great Lakes and Atlantic offshore lease areas.
- Floating foundation transition piece integration:Convergence of dynamic cable systems and tower-to-platform connection engineering is opening design contracts for hybrid steel-concrete structures.
- Direct developer-mill contracting:Long-term offtake agreements between project sponsors and integrated steel producers are bypassing traditional distributor channels, capturing margin and securing supply priority.
Industry Challenges
- Certified welder scarcity:ISO 3834 and EN 1090-2 qualified welders for thick-section S355 and S460 tubular joints are concentrated at established North European yards, constraining capacity expansion.
- Corrosion protection system complexity:Offshore towers require thermal-sprayed aluminum, duplex coating systems, and cathodic protection integration that extends fabrication cycles and demands specialized applicator networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Wind Tower Market |
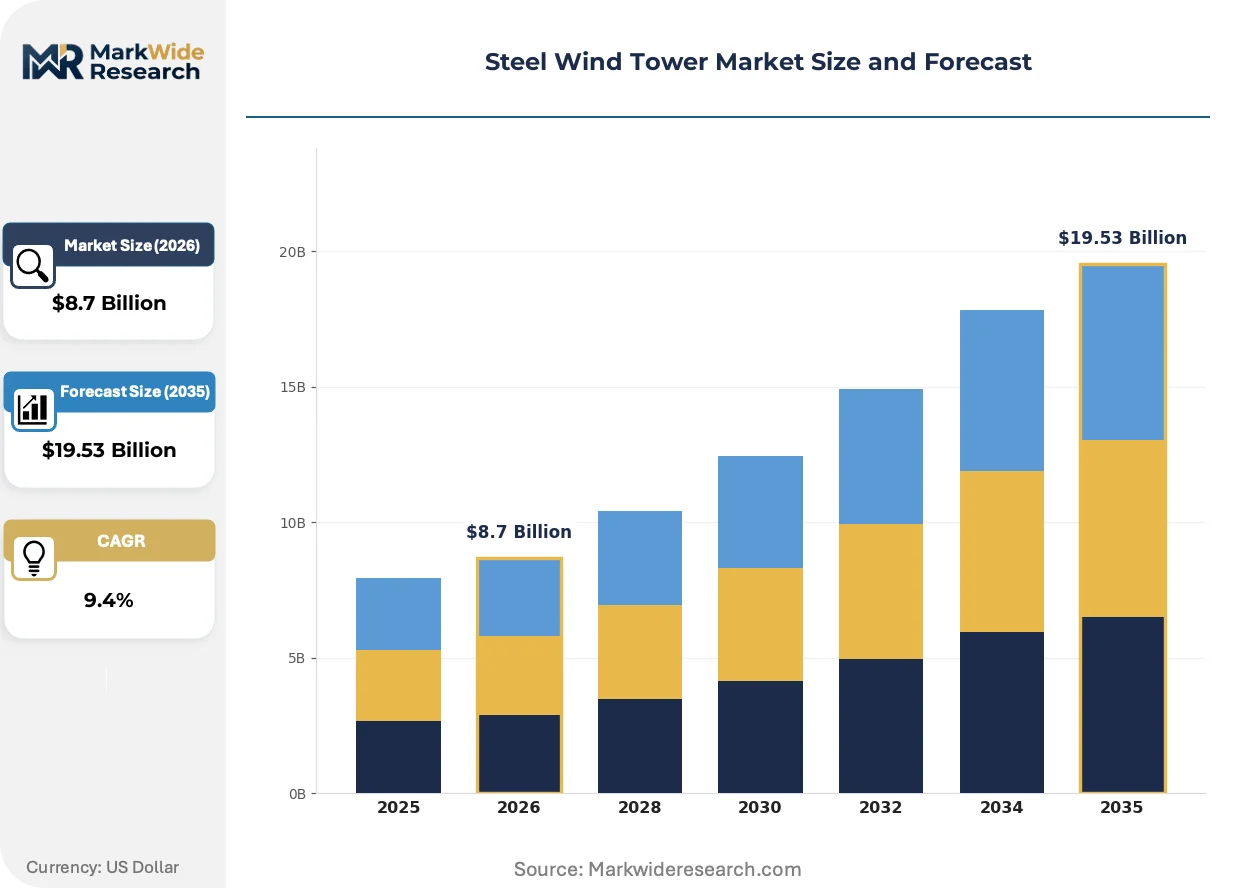
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopole, Lattice, Hybrid, Tubular Technology: Horizontal Axis, Vertical Axis, Offshore, Onshore Installation Type: Fixed, Floating, Mobile, Modular End User: Utilities, Independent Power Producers, Government, Commercial |
| Companies Covered | EEW Group, GRI Renewable Industries, CS Wind Corporation, Valmont Industries Inc., Ventower Industries, Arcosa Wind Towers, Inc., Marmen, US Forged Rings Inc., Titan Wind Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Wind Tower Market Strategic Shifts
Steel wind tower engineering is converging with advanced manufacturing and carbon-accounting systems as developers optimize for lifecycle emissions and installation logistics simultaneously.
Hybrid tower designs combining steel tubular lower sections with concrete or composite upper segments are unifying transport efficiency with hub height extension. European offshore developers are specifying these configurations for sites with weight-restricted road access. The approach is compressing total project steel tonnage while maintaining structural performance at 150-meter-plus hub heights.
REACH and the EU F-Gas Regulation are tightening embodied-carbon disclosure requirements for imported steel components. European fabricators must now document Scope 3 emissions through certified environmental product declarations to qualify for auction-backed projects. Tower suppliers with integrated EAF-based plate production are capturing preferential scoring in German and Danish tender evaluations.
Buyers are consolidating procurement under multi-project master service agreements that bundle tower supply with installation logistics and long-term inspection services. Danish and German offshore developers are leading this contracting evolution, replacing discrete purchase orders with decade-spanning partnership frameworks. The shift compresses supplier negotiation overhead while locking in capacity allocation through construction cycles.
Steel Wind Tower Market Segmentation
Steel wind tower procurement patterns diverge sharply across product configurations and installation environments. Capital deployment, logistics constraints, and regulatory compliance requirements reshape supplier selection criteria within each segment boundary.
Product Type:
Capital intensity escalates with unit weight and fabrication complexity, concentrating investment decisions on transport logistics and quayside handling capabilities.
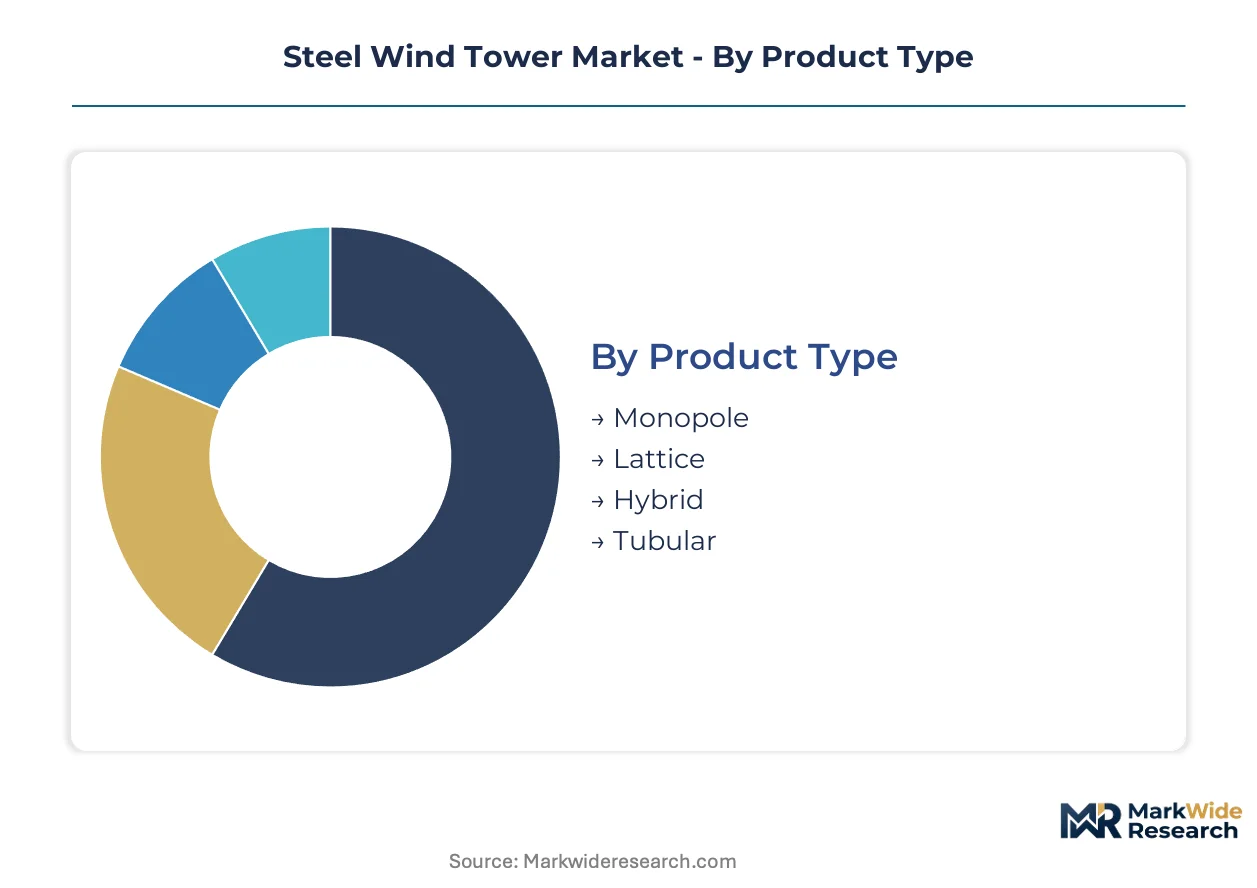
- Monopole:Welded tubular structures fabricated from thick-section S355 or S460 plate, typically 80-120 millimeters at base sections to withstand cyclic loading. German and Danish North Sea projects dominate procurement, driven by EU Green Deal domestic content mandates requiring locally fabricated steel. These units absorb the heaviest capital allocation per megawatt due to specialized rolling mills and dedicated heavy-lift port infrastructure.
- Tubular:Conical or cylindrical steel shells produced through automated longitudinal welding and flange integration. Onshore utility-scale developers in the US and China concentrate demand, prioritizing domestic fabrication to control logistics costs and qualify for Section 45X manufacturing credits or MIIT dual carbon procurement preferences.
- Lattice:Triangular or quadrilateral truss configurations assembled from angular steel sections. Emerging markets with weight-restricted road networks in India and Brazil sustain residual demand, where modular component transport outweighs hub height limitations.
- Hybrid:Lower steel tubular sections married to concrete or composite upper segments. European developers facing site access constraints specify these configurations, compressing total steel tonnage while maintaining structural performance at extended hub heights.
Monopole configurations absorb the bulk of installed capacity; hybrid designs are expanding most quickly as developers optimize transport efficiency against height targets.
Technology:
Engineering intensity and certification burden vary substantially across axis orientation and deployment environment, redistributing margin capture between fabricators and specialized contractors.
- Horizontal Axis:Dominant nacelle-and-rotor orientation with upwind or downwind blade positioning. Onshore utility procurement across Germany, China, and the US sustains volume leadership, with IEC 61400-1 structural design standards governing market access.
- Offshore:Salt-resistant coating systems, cathodic protection, and dynamic load specifications elevate fabrication complexity. North Sea project sponsors in Denmark, Germany, and the Netherlands concentrate orders at heavy-plate facilities with integrated corrosion protection applicator networks.
- Onshore:Standardized tubular tower designs serving utility and independent power producer channels. Chinese GB standards and US FAA obstruction lighting requirements shape regional specification divergence.
- Vertical Axis:Darrieus or Savonius configurations capturing omnidirectional wind resources. Niche urban and distributed applications in Japan and South Korea sustain limited commercial deployment.
Horizontal axis technology commands the greatest installed base; offshore specifications are climbing the fastest as auction pipelines mature.
Installation Type:
Foundation engineering and marine logistics differentiate capital structures, with floating systems demanding entirely distinct supply chain competencies from fixed-bottom fabrication.
- Fixed:Monopile or jacket substructures anchored directly to seabed or bedrock. German and Danish North Sea developments concentrate procurement, requiring specialized piling vessels and geotechnical survey coordination.
- Floating:Semi-submersible, tension-leg, or spar platforms enabling deep-water deployment. French and Portuguese Atlantic lease areas are driving design contracts for hybrid steel-concrete transition pieces integrating dynamic cable systems.
- Modular:Bolted or flanged tower sections enabling field assembly without heavy-lift cranes. Indian and Australian onshore projects with restricted site access specify these configurations to bypass transport weight limits.
- Mobile:Temporary or redeployable tower systems serving measurement campaigns or emergency replacement. Limited commercial scale concentrates demand with specialized rental operators.
Fixed installations retain the dominant share of cumulative capacity; floating foundations are gaining share fastest as water depth constraints push development frontiers.
End User:
Procurement scale and contracting sophistication diverge between centralized utilities and fragmented independent developers, reshaping payment terms and long-term service bundling.
- Utilities:Vertically integrated power companies with multi-gigawatt procurement programs. German and Danish offshore developers lead consolidation under decade-spanning master service agreements bundling tower supply with installation logistics.
- Independent Power Producers:Project-specific sponsors financing through construction debt and tax equity. US Great Lakes and Atlantic lease holders leverage Section 45X credits to anchor domestic fabrication investments.
- Government:State-owned or municipally directed renewable energy procurement. Chinese provincial SOEs and Indian state discoms channel demand through centralized tender mechanisms with domestic content requirements.
- Commercial:Corporate offtake agreements and on-site generation for industrial facilities. C&I procurement in Japan and South Korea sustains smaller-diameter tower demand for distributed installations.
Utilities absorb the bulk of installed capacity; independent power producers are expanding most quickly as auction mechanisms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-grade structural steel plate from integrated mills in Germany, South Korea, and China anchors fabrication capacity across three continents. Port-proximate rolling facilities command premium positioning due to quayside heavy-lift requirements for monopile transition pieces.
Germany
North Sea offshore auctions under the EU Green Deal mandate 50-65% domestic steel content, concentrating orders at Rostock and Cuxhaven fabrication yards. The Federal Network Agency's tender designs award preferential scoring to bidders with certified low-carbon supply chains. EEW Group's heavy-plate rolling capacity at Rostock dominates monopile transition piece production for Danish and German project sponsors.
China
Provincial SOEs channel demand through centralized tenders with MIIT dual carbon procurement preferences favoring EAF-based plate producers. GB standards on structural steel S460 grade accelerate metallurgical upgrades at Yangtze River Delta mills. CS Wind Corporation leverages integrated Korean and Vietnamese production bases to anchor Asian offshore contract execution.
United States
Great Lakes and Atlantic offshore lease holders leverage IRA Section 45X advanced manufacturing credits to anchor domestic tower fabrication investments. FAA obstruction lighting requirements shape regional specification divergence for utility-scale onshore projects. Valmont Industries controls logistics costs through domestic fabrication serving Midwest and Plains states utility procurement.
Denmark
Esbjerg port infrastructure faces scheduling bottlenecks during North Sea installation windows, tightening capacity allocation for gigawatt-scale developments. National renewable energy auctions enforce domestic content thresholds parallel to EU Green Deal frameworks. Heavy-plate facilities with dedicated quayside access concentrate orders for monopile foundations exceeding 2,000 tonnes.
Vietnam
Korean-owned fabrication yards exploit ASEAN trade preferences to serve Asian offshore developers with cost-optimized tubular tower production. Port infrastructure upgrades at specialized heavy-lift terminals support export logistics for regional wind farm construction. CS Wind Corporation's Vietnamese production base captures contract flow from Southeast Asian auction pipelines.
Steel Wind Tower Market Competitive Environment
Global majors compete with regional champions across integrated steel supply and port-proximate fabrication capacity. The vendor base stratifies between captive plate producers with blast furnace or EAF capacity and specialized tower fabricators dependent on external steel sourcing. Three archetypes dominate: integrated mills with quayside rolling facilities, domestic fabricators leveraging IRA or MIIT policy incentives, and modular specialists serving emerging markets with transport-constrained logistics. Competitive intensity centers on long-term offtake agreements and master service agreements bundling supply with installation logistics.
Within the integrated-mill tier, EEW Group and CS Wind Corporation exemplify contrasting geographic anchoring strategies. EEW's Rostock facility represents European heavy-plate concentration under EU Green Deal content rules. CS Wind occupies a position spanning Korean metallurgical expertise and Vietnamese cost-optimized fabrication. Valmont Industries anchors the domestic-US archetype, controlling logistics costs for utility-scale onshore procurement through geographically distributed fabrication.
| Leading Market Players |
|---|
| EEW Group |
| GRI Renewable Industries |
| CS Wind Corporation |
| Valmont Industries Inc. |
| Ventower Industries |
| Arcosa Wind Towers, Inc. |
| Marmen |
| US Forged Rings Inc. |
| Titan Wind Energy |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal domestic content mandates requiring 50-65% locally fabricated steel content are forcing developers toward integrated mills with captive plate production, compressing margins for distributors and elevating pricing power at port-proximate rolling facilities with blast furnace or EAF capacity.
Pricing Analysis
Long-term installation logistics and inspection service bundling under master service agreements now separates premium-tier suppliers from unbundled transactional vendors. Price differentiation rests on ISO 3834 welding certification tier and S460 grade metallurgical qualification. Cost compression in standard-grade S355 tubular towers is intensifying because Chinese and Vietnamese fabricators exploit ASEAN trade preferences. Independent power producers in the US Great Lakes region exhibit the highest price sensitivity due to construction debt financing constraints, while German utilities under decade-spanning procurement frameworks show the least.
Supply Chain Analysis
Dual-sourcing requirements mandated by North Sea project sponsors for monopile transition pieces exceeding 2,000 tonnes are fragmenting order allocation across Germany, Denmark, and Vietnam. Raw material feeds draw from high-strength structural steel plate, thermal-sprayed aluminum coating systems, and cathodic protection anodes. Single-source vulnerability concentrates at Rostock and Cuxhaven heavy-lift terminals facing scheduling bottlenecks during installation windows. Distribution runs through direct developer-mill contracting channels that bypass traditional steel distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The steel wind tower market is executing a technology transition from S355 to S460 grade plate metallurgy, with thinner wall sections at equivalent load-bearing capacity displacing legacy specifications across European and Asian procurement channels.
For Market Incumbents: Cement market position through captive EAF-based plate production investments near North Sea port clusters to satisfy EU Green Deal embodied-carbon thresholds. Secure ISO 3834 and EN 1090-2 welding certification expansion to counter certified welder scarcity constraining capacity growth. Prioritize long-term offtake agreements with Danish and German utilities bundling tower supply with installation logistics. For New Entrants and Emerging Players: Floating foundation transition piece integration technology offers a technology-first wedge into French and Portuguese Atlantic lease areas where hybrid steel-concrete structures remain underpenetrated. Target modular tower configurations for Indian and Australian onshore projects with weight-restricted road access. Pursue joint development agreements with dynamic cable system specialists to anchor go-to-market credibility. For Investors and Strategic Acquirers: The window for entry favors integrated mills with quayside heavy-plate rolling capacity and established corrosion protection applicator networks. Long-term viability across the projection horizon rests on positioning ahead of carbon-border adjustment mechanism implementation. Watch F-Gas Regulation Scope 3 disclosure enforcement as the inflection indicator for supplier qualification criteria tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Captive EAF Steel Production | Secures low-carbon plate supply for EU Green Deal auction qualification at Rostock and Cuxhaven. |
| Master Service Agreement Consolidation | Bundles tower supply with installation logistics under decade-spanning Danish and German utility frameworks. |
| S460 Grade Metallurgical Upgrade | Enables thinner wall sections reducing transport weight for 150-meter-plus hub height projects. |
| Floating Foundation Transition Piece Development | Captures design contracts for hybrid steel-concrete structures in French and Portuguese Atlantic lease areas. |
| Corrosion Protection System Integration | Extends fabrication cycles with thermal-sprayed aluminum and cathodic protection for North Sea offshore specifications. |
Study Parameters
Independent corroboration across project developer procurement officers, heavy-plate mill operations directors, and offshore installation contractors underwrites the qualitative findings. Primary fieldwork engaged EPC contractor project managers, port authority heavy-lift coordinators, and wind farm asset managers across Germany, Denmark, China, and the United States. Secondary validation drew from EU auction documentation, FERC interconnection filings, IEA renewable energy project databases, and SEC manufacturing credit disclosures. Bottom-up capacity modeling at individual fabrication yards was triangulated against top-down procurement pipeline aggregation.
Rate-of-change decomposition across the analysis window isolates volume drivers by product configuration, installation environment, and end-user contracting sophistication. Segmentation dimensions modeled include monopile versus tubular versus hybrid tower designs, fixed versus floating foundation types, and utility versus independent power producer procurement channels. CAGRs were derived from installation capacity buildout trajectories and steel tonnage intensity per megawatt. Forecast inputs incorporated EU Green Deal domestic content threshold evolution and IRA Section 45X credit utilization patterns.
Several conditions sit outside the modeled scope, including unannounced auction pipeline cancellations, abrupt F-Gas Regulation Scope 3 disclosure deadline acceleration, and breakthrough composite tower material substitution. Deviation in certified welder training program throughput would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
India Wind Industry Market
Wind Energy Systems
Wind Turbine Pitch Systems Market
Wind Energy Systems
Asia-Pacific Wind Power Market
Wind Energy Systems
Denmark Wind Energy Market
Wind Energy Systems
Europe Small Wind Turbine Market
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
Global Wind Power Equipment Market
Wind Energy Systems
Global Wind LIDAR Market
Wind Energy Systems
Asia-Pacific Large Wind Turbine Market
Wind Energy Systems
Wind Energy Equipment Market
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
New Zealand Wind Energy Market
Wind Energy Systems
Wind Turbine Operation and Maintenance Market
Wind Energy Systems
Wind Turbine Brakes Market
Wind Energy Systems
Spain Wind Energy Market
Wind Energy Systems
Chile Wind Energy Market