
 Ireland Wind Energy Market | 2026-2036
Ireland Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland Wind Energy Market Foresight
Marine engineering specialist availability is unwinding as a bottleneck for offshore construction schedules. SSE Renewables leverages its Irish Sea project pipeline to anchor early-mover advantage in floating foundation trials. Statkraft competes through its Norwegian hydropower balance-sheet capacity to finance long-dated Irish offshore developments. Vestas Wind Systems dominates onshore repowering with its large-rotor platform optimized for Ireland's low-to-moderate wind-speed sites.
Ireland wind energy encompasses electricity generation from kinetic airflow through horizontal-axis turbines with rotor diameters now exceeding 150 meters and hub heights surpassing 130 meters, converting mechanical rotation via doubly-fed induction generators or direct-drive permanent-magnet systems into grid-synchronous power. The primary commercial purpose is decarbonizing Ireland's electricity mix while displacing fossil fuel imports for power generation. Onshore installations retain structural dominance in annual capacity additions yet face margin compression from grid congestion and community opposition, whereas offshore segments command premium developer returns due to higher capacity factors and proximity to Dublin's demand center. Utility end users represent the deepest procurement pool, though industrial offtake agreements are gaining traction as corporate renewable energy buyers seek long-term price hedges.
The Commission for Regulation of Utilities shapes market access through grid connection policy and renewable electricity auction design, while the Environmental Protection Agency enforces habitat assessments under the EU Habitats Directive that constrain project siting in Natura 2000 zones. EirGrid's DSO and TSO functions determine curtailment risk and reinforcement timelines that directly shape investor returns. Stakeholders must weigh the pace of floating offshore commercialization against fixed-bottom cost trajectories when committing capital to Irish Sea lease rounds.
Market Dynamics
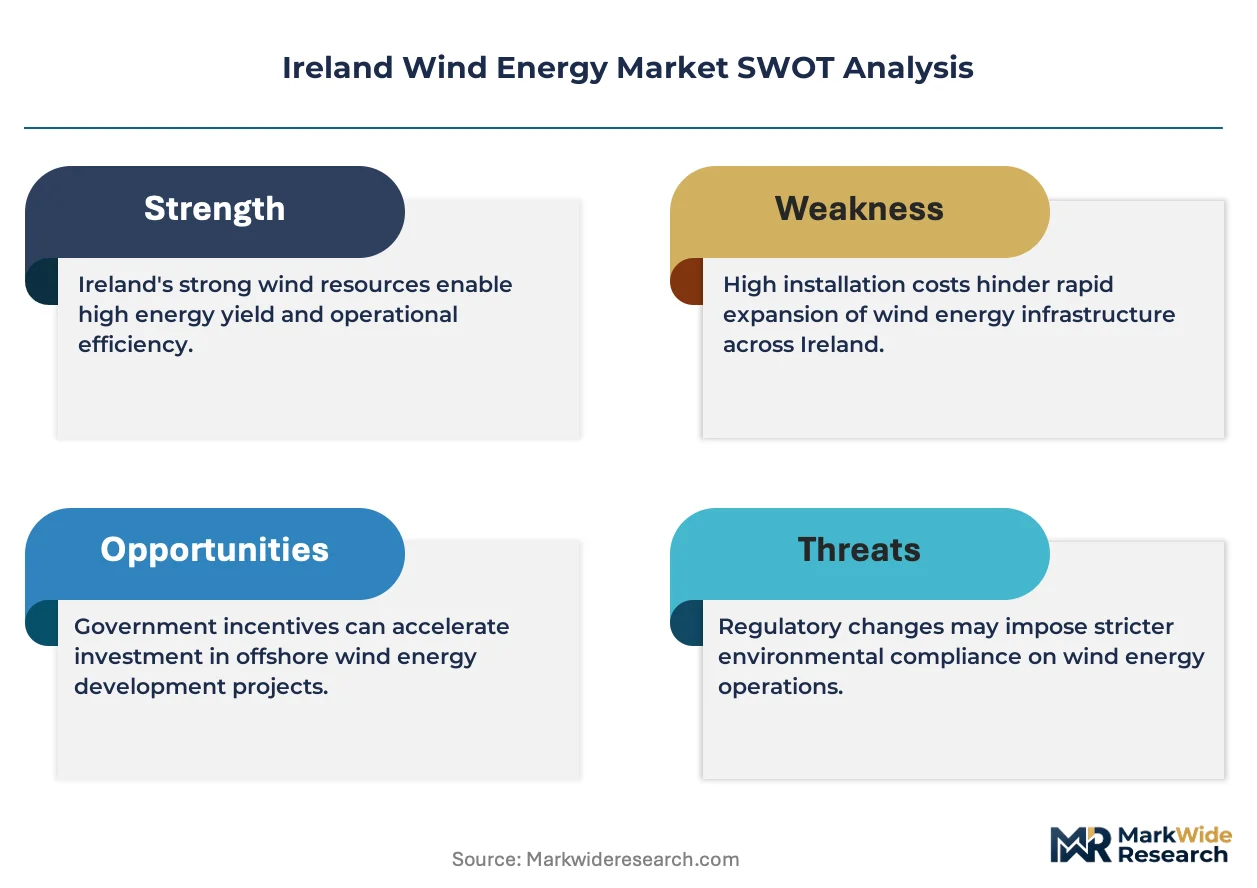
The Ireland Wind Energy Market pivots on EirGrid's transmission reinforcement timelines, which compress or extend developer returns more sharply than turbine technology advances. Grid access queues now stretch seven years, forcing capital allocation toward offshore lease rounds where seabed licensing outpaces onshore planning bottlenecks.
Growth Catalysts
- Ireland's Climate Action Plan:Binding renewable electricity targets accelerate project permitting timelines and anchor utility procurement mandates.
- Floating foundation trials:Marine engineering specialists deploy novel substructure designs in Irish Sea deep-water zones previously inaccessible to fixed-bottom turbines.
- Corporate power purchase agreements:Industrial offtake contracts from pharmaceutical and data center operators displace traditional utility-only demand pools.
Market Restraints
- Steel and rare-earth input volatility:Direct-drive permanent-magnet generator supply chains concentrate in Chinese processing facilities, exposing turbine OEMs to price swings.
- Natura 2000 habitat assessments:EPA enforcement under the EU Habitats Directive blocks project siting in protected zones across the midlands and western seaboard.
- Grid congestion curtailment:EirGrid's DSO reinforcement lag forces operational spillage at onshore wind farms during high-generation periods.
Strategic Opportunities
- Floating offshore commercialization:Deep-water Irish Sea corridors from Dublin to Wexford offer untapped capacity factors exceeding fixed-bottom economics.
- Repowering low-to-moderate wind-speed sites:Large-rotor platforms replace aging onshore turbines without greenfield permitting delays.
- Corporate renewable hedging:Long-term price certainty contracts attract multinational manufacturing and cloud computing facilities to the Republic.
Industry Challenges
- Marine construction specialist scarcity:Jack-up vessel and cable-lay crew availability constrains offshore installation windows.
- Community opposition coordination:Local planning objections delay onshore projects despite national policy alignment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland Wind Energy Market |
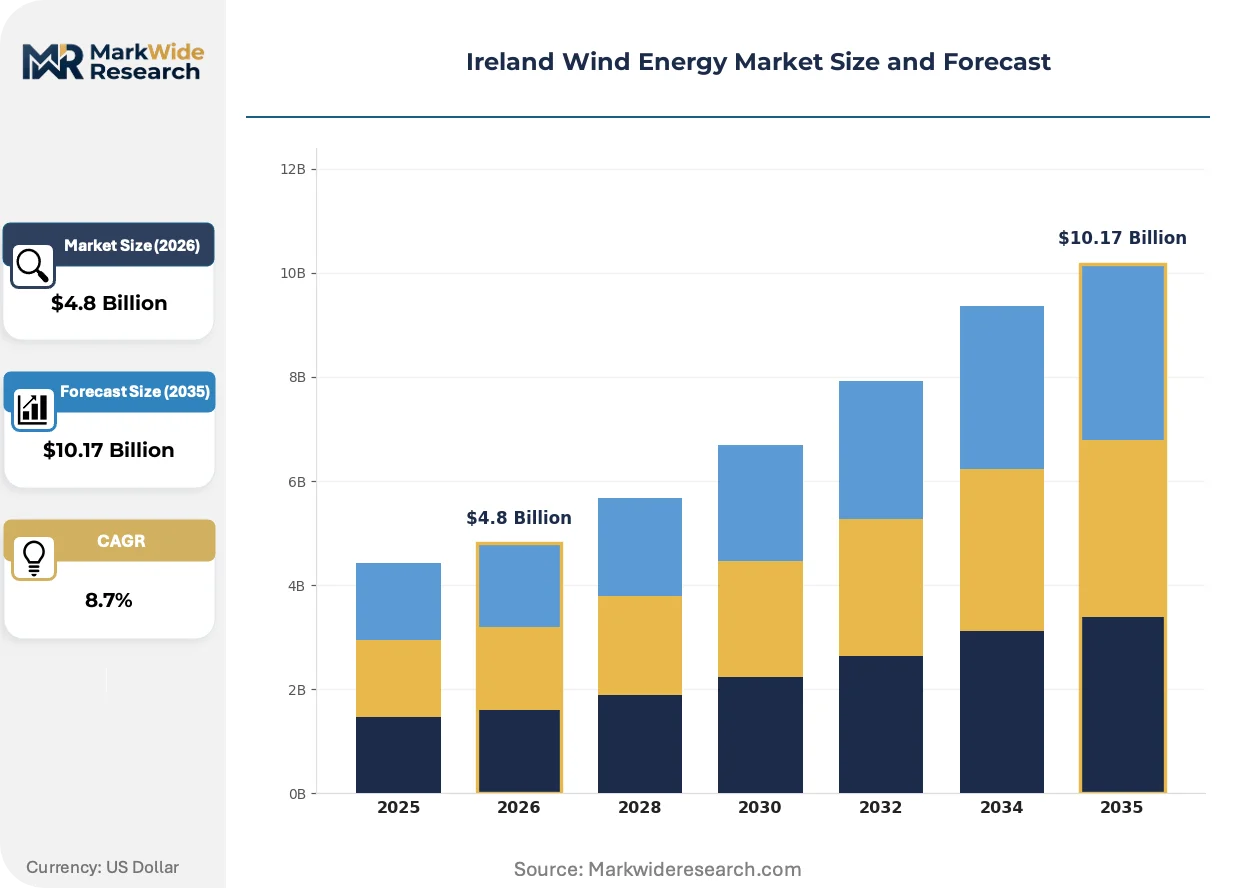
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Onshore, Offshore, Turbine Type, Hybrid Systems Installation Type: New Installations, Upgrades, Repowering, Maintenance End User: Utilities, Industrial, Commercial, Residential Project Size: Small Scale, Medium Scale, Large Scale, Community Projects |
| Companies Covered | Siemens Gamesa Renewable Energy, Vestas Wind Systems, General Electric Company, Statkraft, EDF Renewables, SSE Renewables, Electricity Supply Board, RWE Renewables Ireland, Nordex SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland Wind Energy Market Shifts & Advancements
Turbine scaling and foundation engineering are fragmenting competitive positions across Irish project pipelines. Technology trajectories diverge between repowering existing onshore assets and pioneering floating offshore architectures.
Doubly-fed induction generator architectures face displacement by direct-drive permanent-magnet systems in new Irish installations. Utility-scale developers favor the latter for reduced gearbox maintenance and improved availability in salt-laden coastal environments. This technology shift is fragmenting service contract structures, as OEMs capture long-term service revenue through integrated powertrain warranties rather than third-party maintenance providers.
EU Green Deal implementation tightens habitat assessment protocols for Natura 2000 zones, extending EPA review timelines for onshore projects. The industrial consequence compresses developer margins and redirects capital toward offshore lease rounds where marine spatial planning offers clearer permitting pathways. Fixed-bottom projects in shallow Irish Sea waters respond by accelerating construction schedules ahead of anticipated floating technology cost convergence.
Corporate buyers now negotiate sleeved power purchase agreements that bypass traditional utility intermediaries. Data center operators in Dublin and Cork procure directly from offshore wind farms, displacing utility-managed green tariff programs. This pattern concentrates most visibly in the Greater Dublin Area, where hyperscale facility energy demand outstocks available grid-connected renewable supply.
Ireland Wind Energy Market Segmentation
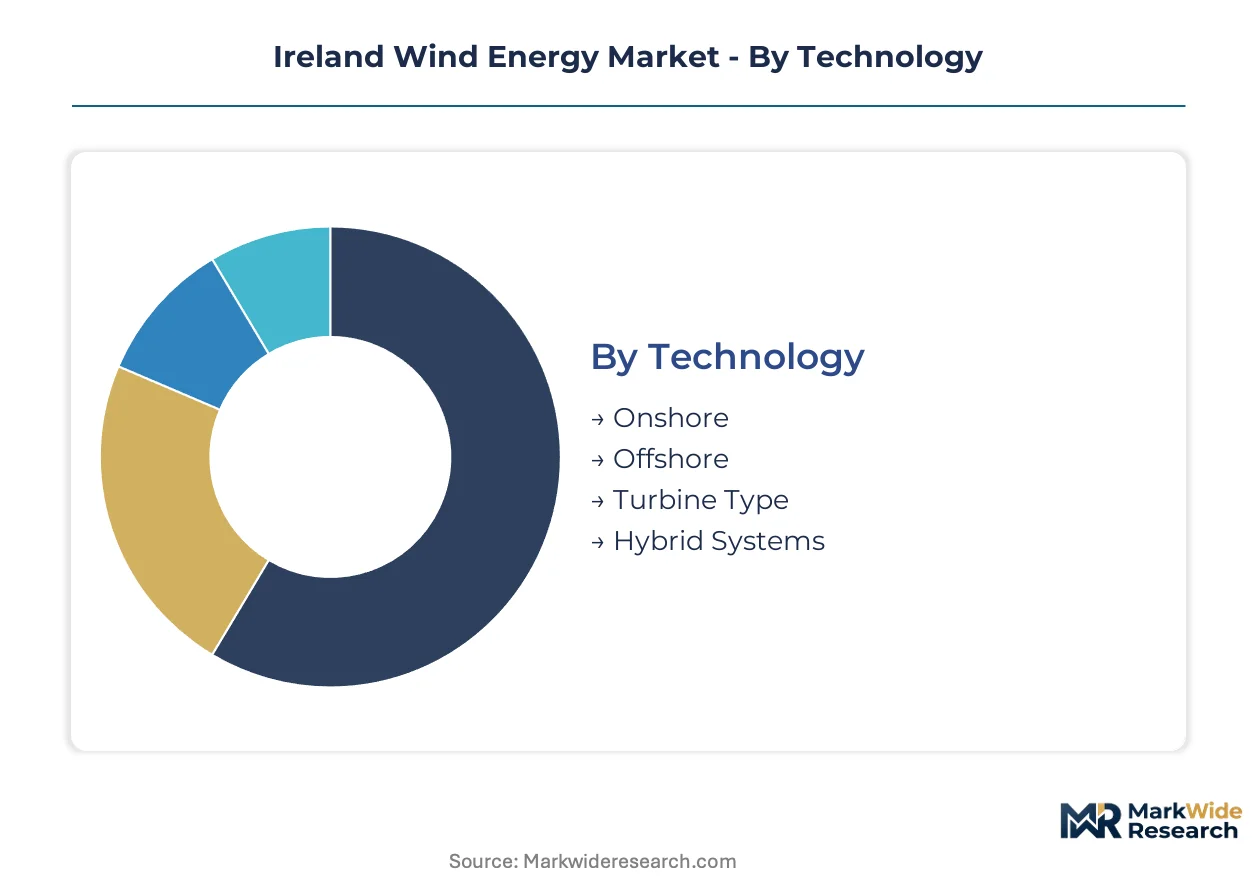
Segmentation in the Ireland wind energy market exposes where capital allocation shifts under grid congestion and permitting pressure. Technology and installation choices determine exposure to EirGrid reinforcement timelines and EPA habitat assessments.
Technology:
Offshore platforms face substitution pressure from onshore repowering as grid queues stretch and marine construction costs escalate.
- Onshore:Horizontal-axis turbines with rotor diameters exceeding 150 meters dominate existing capacity. Demand concentrates in the midlands for repowering aging assets, though Natura 2000 assessments block greenfield expansion in protected western zones.
- Offshore:Fixed-bottom foundations in shallow Irish Sea waters anchor current development, with floating trials targeting deep-water corridors from Dublin to Wexford where capacity factors exceed onshore economics.
- Turbine Type:Direct-drive permanent-magnet systems displace doubly-fed induction generators for reduced gearbox maintenance in salt-laden coastal environments.
- Hybrid Systems:Co-located battery storage paired with wind generation mitigates curtailment risk during high-generation periods.
Onshore retains volume leadership; offshore holds the steepest expansion curve.
Installation Type:
Cost tier stratification separates capital-intensive new builds from lower-capex maintenance and upgrade cycles.
- New Installations:Greenfield projects require seven-year grid connection queues and EPA habitat clearances, compressing developer returns relative to faster-cycle alternatives.
- Upgrades:Control system and blade extension retrofits extend asset life without full permitting resets, attracting mid-scale operators.
- Repowering:Large-rotor platforms replace aging turbines at existing sites, bypassing greenfield delays while lifting capacity factors at low-to-moderate wind-speed locations.
- Maintenance:OEM-integrated service contracts capture long-term revenue as direct-drive architectures fragment third-party provider access.
Repowering captures the tightest supply-demand balance; new installations face the longest capital recovery timelines.
End User:
Customer type diversification shifts procurement patterns away from utility-centric models toward direct corporate contracting.
- Utilities:ESB and SSE Airtricity anchor procurement through renewable electricity auctions mandated by Ireland's Climate Action Plan, though grid reinforcement lag constrains portfolio growth.
- Industrial:Pharmaceutical and data center operators negotiate sleeved power purchase agreements bypassing traditional utility intermediaries for long-term price hedges.
- Commercial:Mid-sized manufacturing facilities in Cork and Galway adopt aggregated green tariff programs where direct offtake remains uneconomic.
- Residential:Distributed small-scale installations face margin compression from grid connection costs and planning objections despite national policy alignment.
Utilities retain procurement volume dominance; industrial offtake is climbing the fastest.
Project Size:
Volume concentration stratifies developer specialization and capital access requirements across the pipeline.
- Large Scale:Utility-scale offshore arrays exceeding 500 MW command premium financing through Norwegian hydropower balance-sheet capacity and institutional infrastructure funds.
- Medium Scale:Onshore clusters between 50-200 MW face curtailment risk where EirGrid DSO reinforcement lags generation capacity.
- Small Scale:Distributed assets under 50 MW struggle with grid connection queue positioning relative to larger projects.
- Community Projects:Locally owned developments encounter planning coordination challenges despite streamlined permitting pathways under national renewable targets.
Large scale retains capital flow concentration; community projects are gaining share fastest through policy preference mechanisms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ireland's wind energy consumption pattern diverges from continental European markets through its heavy offshore orientation toward the Irish Sea corridor, whereas onshore-reliant neighbors prioritize land-based repowering. This maritime concentration shapes infrastructure investment and regulatory priorities across the island.
Dublin-Wexford Corridor
Offshore lease concentration drives capital flows along the east coast, where water depths and grid access favor turbine clustering. The Commission for Regulation of Utilities shapes seabed licensing timelines through marine spatial planning frameworks. SSE Renewables anchors early development at Arklow Bank, leveraging proximity to the capital's demand center.
Midlands Region
Onshore repowering activity concentrates where aging turbine fleets face replacement cycles without greenfield permitting delays. EPA enforcement under the EU Habitats Directive constrains new siting in Natura 2000 zones across Laois and Offaly. Vestas Wind Systems dominates retrofit deployments with large-rotor platforms optimized for low-to-moderate wind-speed terrain.
Western Seaboard
Atlantic exposure yields higher capacity factors but triggers stricter habitat assessments under marine conservation designations. EirGrid's DSO reinforcement lag forces curtailment risk at Mayo and Galway clusters during high-generation periods. Community opposition coordination delays several medium-scale projects despite streamlined national permitting pathways.
Northern Ireland
Cross-border grid integration shapes procurement patterns between the Republic and UK jurisdictions. The Utility Regulator oversees auction design that must align with Republic of Ireland renewable targets under all-island market frameworks. RWE Renewables Ireland positions across both jurisdictions to capture arbitrage in connection queue positioning.
Ireland Wind Energy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with offshore developers commanding premium returns through balance-sheet capacity while turbine OEMs fragment across onshore repowering niches. The market structure concentrates around three archetypes: Norwegian hydropower-backed developers, integrated European utilities, and Danish turbine specialists. Dominant competitive moves include seabed lease accumulation ahead of floating technology maturation and long-term service contract capture through direct-drive generator warranties.
Within the integrated utility tier, SSE Renewables and Statkraft exemplify divergent capital deployment strategies, with the former anchoring Irish Sea project pipelines and the latter leveraging Nordic hydropower balance sheets for long-dated offshore financing. Vestas Wind Systems occupies a distinct position as the onshore repowering anchor, its large-rotor platform representing the technology standard for aging fleet replacement.
| Leading Market Players |
|---|
| Siemens Gamesa Renewable Energy |
| Vestas Wind Systems |
| General Electric Company |
| Statkraft |
| EDF Renewables |
| SSE Renewables |
| Electricity Supply Board |
| RWE Renewables Ireland |
| Nordex SE |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with utility and corporate buyers lock in turbine supply allocation and price visibility across the decade-long project development cycle, insulating Irish developers from spot steel and rare-earth volatility while anchoring EPC financing.
Pricing Analysis
Project-based capacity payments dominate procurement between developers and ESB or SSE Airtricity, with price differentiation driven by seabed lease premiums for floating-ready sites and after-sales service bundling through OEM-integrated powertrain warranties. Pricing pressure stems from steel input volatility and jack-up vessel day-rate spikes, compressing developer margins on fixed-bottom projects. Industrial offtakers from pharmaceutical and data center sectors exhibit lowest price sensitivity due to long-term hedging requirements, while community-owned developments face acute cost compression from grid connection queue positioning fees.
Supply Chain Analysis
Port congestion at Belfast and Dublin harbors elevates inbound logistics costs for nacelle and blade components sourced from Denmark, Germany, and China, where direct-drive permanent-magnet generator manufacturing concentrates. Rare-earth processing dependencies rest on Chinese separation facilities, exposing turbine OEMs to export quota volatility. Single-source vulnerability in jack-up vessel availability constrains offshore installation windows. Distribution runs through EPC contractor-led project logistics rather than merchant inventory channels, with Vestas and Siemens Gamesa maintaining captive service fleets for Irish Sea corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from integrated powertrain warranties and predictive maintenance contracts is expanding faster than hardware sales, as direct-drive architectures fragment third-party provider access and OEMs capture twenty-year revenue streams.
For Market Incumbents: Compound defensive positioning through backward integration into floating foundation engineering capabilities and exclusive jack-up vessel charter arrangements, countering emerging Norwegian hydropower-backed developers with balance-sheet depth for long-dated Irish Sea lease accumulation. For New Entrants and Emerging Players: Lead with sleeved corporate power purchase agreements targeting data center operators in Greater Dublin, where hyperscale facility demand outstocks available grid-connected renewable supply and bypasses traditional utility intermediaries entirely. For Investors and Strategic Acquirers: Capital is best deployed toward developers with secured seabed leases in the Dublin-Wexford corridor and demonstrated floating platform pilot credentials, with grid connection queue advancement timelines serving as the critical inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Foundation Commercialization | Unlocks deep-water Irish Sea capacity factors exceeding fixed-bottom economics for SSE Renewables and Statkraft pipelines. |
| Integrated Service Contract Capture | Vestas anchors long-term revenue through direct-drive powertrain warranties that exclude third-party maintenance providers. |
| Corporate PPA Sleeved Structures | Data center operators in Dublin procure directly from offshore wind farms, displacing utility-managed green tariff programs. |
| Grid Reinforcement Alignment | EirGrid transmission timelines compress or extend developer returns more sharply than turbine technology advances. |
| Repowering Platform Deployment | Large-rotor retrofits at aging midlands sites bypass greenfield permitting delays under EPA Natura 2000 assessments. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, IPP project developers, EPC contractors, and marine construction specialists and refined through secondary validation against EirGrid transmission development plans, EPA environmental impact statements, CRU auction design documents, and IEA renewable energy market reports. Bottom-up project pipeline enumeration triangulated with top-down macroeconomic demand modeling.
Variance decomposition across technology, installation type, end user, and project scale segments shaped the analytical framework throughout the forecast period. CAGRs were derived from capacity addition trajectories and capital cost learning curves, with specific inputs including EirGrid DSO reinforcement timelines and floating platform cost convergence assumptions.
The analysis sits within stated boundaries; outcomes outside sustained EirGrid transmission investment, stable seabed licensing timelines, and floating technology cost reduction would require recalibration. Forecasts reflect documented assumptions regarding marine construction specialist availability and rare-earth supply chain stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Japan Wind Energy Market
Wind Energy Systems
Wind Turbine Cables Market
Wind Energy Systems
Taiwan Wind Energy Market
Wind Energy Systems
Asia-Pacific Large Wind Turbine Market
Wind Energy Systems
Offshore Wind Anchoring Market
Wind Energy Systems
Europe Wind Power Equipment Market
Wind Energy Systems
Greece Wind Energy Market
Wind Energy Systems
Wind Power Bolts Market
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
Airborne Wind Turbines Market
Wind Energy Systems
Wind Turbine Control System Market
Wind Energy Systems
South America Wind Power Market
Wind Energy Systems
Global Wind Power Coatings Market
Wind Energy Systems
Germany Wind Energy Market
Wind Energy Systems
Europe Large Wind Turbine Market
Wind Energy Systems
Portugal Wind Energy Market