
 Jerry Cans Market | 2026-2036
Jerry Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Jerry Cans Market Intelligence
Aftermarket refurbishment revenue is narrowing as OEMs tighten control over container lifecycle services. Greif Inc. leverages its integrated reconditioning network across North American industrial corridors. Mauser Packaging Solutions anchors European chemical logistics through its IBC and jerry can pooling systems. Time Technoplast Ltd. dominates India's automotive fluids segment with multi-layer polymer designs.
A jerry can is a portable liquid container, typically manufactured through blow-molding of high-density polyethylene or seam-welded steel, designed to transport fuels, chemicals, and agricultural inputs with leak-proof seals and stackable geometry. Plastic cans lead volume due to corrosion resistance and lower tare weight in chemical and agriculture end uses, while metal cans retain structural share in oil and gas field operations where impact resistance and static discharge control matter. The 20-25 liter capacity band captures the bulk of industrial procurement, though 5-10 liter formats grow fastest in automotive aftermarket and e-commerce channels.
EPA and OSHA standards in the United States mandate specific closure and labeling for flammable liquid containers, while ECHA REACH compliance in Europe restricts certain polymer additives and mandates recyclability documentation. India's BIS certification and China's GB standards create parallel compliance tracks that shape export-oriented manufacturing footprints. Stakeholders must monitor how extended producer responsibility frameworks in the European Union and select U.S. states reshape cost structures for multi-trip container programs.
Market Dynamics
Extended producer responsibility frameworks in the European Union are compressing container lifecycle economics and forcing OEMs to internalize reconditioning networks rather than outsource to third-party refurbishers.
Growth Catalysts
- REACH compliance documentation:German chemical processors now mandate cradle-to-grave recyclability certification for all inbound containers, accelerating demand for standardized multi-trip designs that reduce per-use compliance costs.
- Automotive fluid logistics:India's expanding vehicle manufacturing corridors are driving procurement of 5-10 liter formats for precision dosing in assembly line operations.
- High-density polyethylene reformulation:Advanced barrier-layer blow-molding is extending chemical compatibility ranges, opening substitution pathways into agrochemical segments previously served by metal cans.
Market Restraints
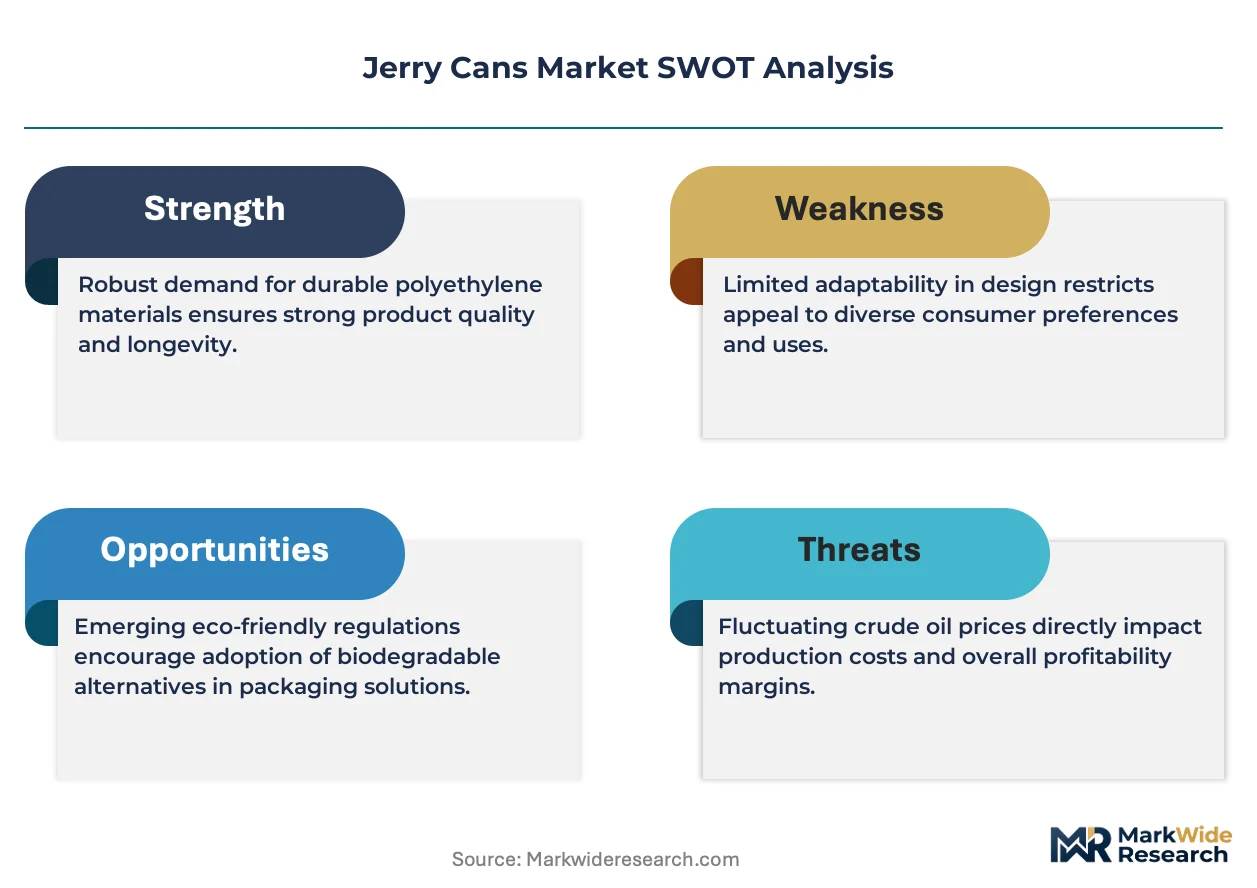
- Feedstock volatility:Crude-derived polyethylene resin prices fluctuate with naphtha cracking margins, compressing margin stability for blow-molding specialists without captive polymer supply.
- Single-source steel supply:European tinplate producers concentrate in the Ruhr industrial cluster, creating geographic chokepoints for seam-welded metal can fabrication.
- Static discharge limitations:Plastic cans face technical barriers in oilfield operations where NFPA 77 grounding requirements favor conductive metal construction.
Strategic Opportunities
- Brazilian agrochemical distribution:ANVISA registration pathways for reusable containers remain underdeveloped, creating first-mover advantage for pooling system operators.
- E-commerce chemical fulfillment:UN-certified 5-liter formats with integrated spout designs are capturing share in direct-to-farmer channels previously served by bulk drum distribution.
- EU Green Deal packaging mandates:Mandatory recycled content thresholds for plastic packaging create premium positioning for post-consumer HDPE sourcing capabilities.
Industry Challenges
- Multi-standard certification timelines:Simultaneous BIS, GB, and EPA approvals for a single SKU extend product launch cycles by 14-18 months.
- Legacy ERP integration:Container tracking systems for deposit-return schemes require API connectivity with customer warehouse management platforms that many mid-tier chemical distributors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jerry Cans Market |
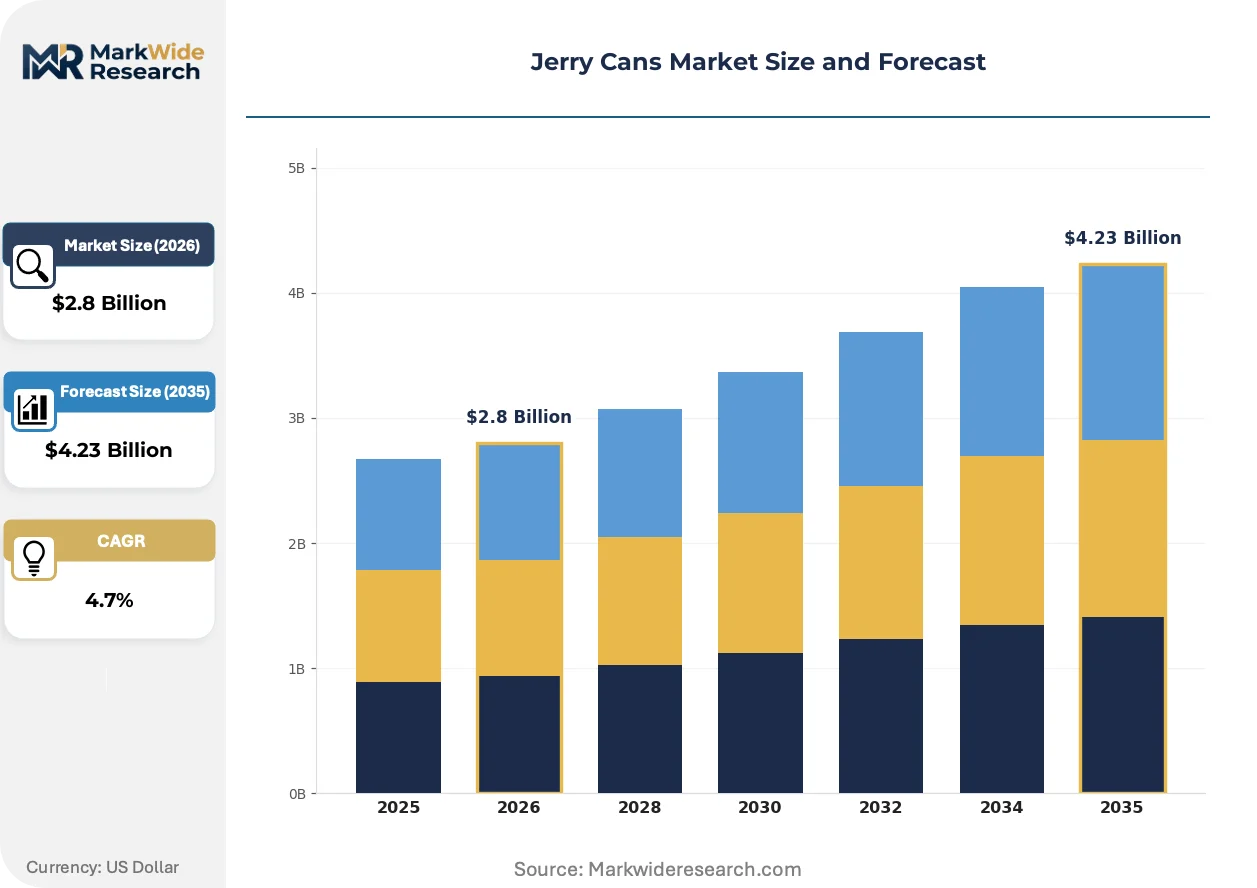
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Cans, Metal Cans, Composite Cans, Flexible Cans End Use Industry: Automotive, Agriculture, Chemical, Oil & Gas Capacity: 5 Liters, 10 Liters, 20 Liters, 25 Liters Distribution Channel: Online Retail, Supermarkets, Distributor Networks, Wholesale |
| Companies Covered | Scepter Manufacturing, Eagle Manufacturing, Greif Inc., Wilkinson Containers Ltd., Berry Global Group Inc., Mauser Packaging Solutions, Time Technoplast Ltd., AST Kunststoffverarbeitung GmbH, SCHÜtz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jerry Cans Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory stringency are converging to compress traditional product lifecycles while opening new performance tiers previously unreachable with conventional construction methods.
Co-extruded barrier technology is collapsing the performance gap between polymer and metal containers. Six-layer HDPE constructions with EVOH oxygen barriers now achieve chemical permeation resistance within 15% of tinplate standards. Agricultural chemical formulators in France and Germany are validating these designs for pesticide concentrates previously restricted to steel jerry cans. The technology is collapsing the historical segmentation between corrosion-resistant plastics and impact-resistant metals.
ECHA's 2024 microplastics restriction is forcing additive reformulation across European supply chains. Polymer stabilizers containing long-chain perfluorinated compounds face phase-out timelines, compelling compounders to validate calcium-zinc and organotin alternatives. Blow-molding operations in Poland and the Czech Republic are most exposed due to their concentration in automotive chemical packaging where thermal stability requirements are most stringent.
Leasing models for IBC and jerry can fleets are displacing outright purchase in chemical logistics. German specialty chemical distributors now specify per-trip pricing with integrated washing and inspection services. The shift compresses capital deployment for mid-volume processors while concentrating fleet ownership among pooling specialists with dense depot networks. This pattern is most visible in the Rhine-Ruhr chemical corridor where container turnaround times drive total cost optimization.
Jerry Cans Market Segmentation
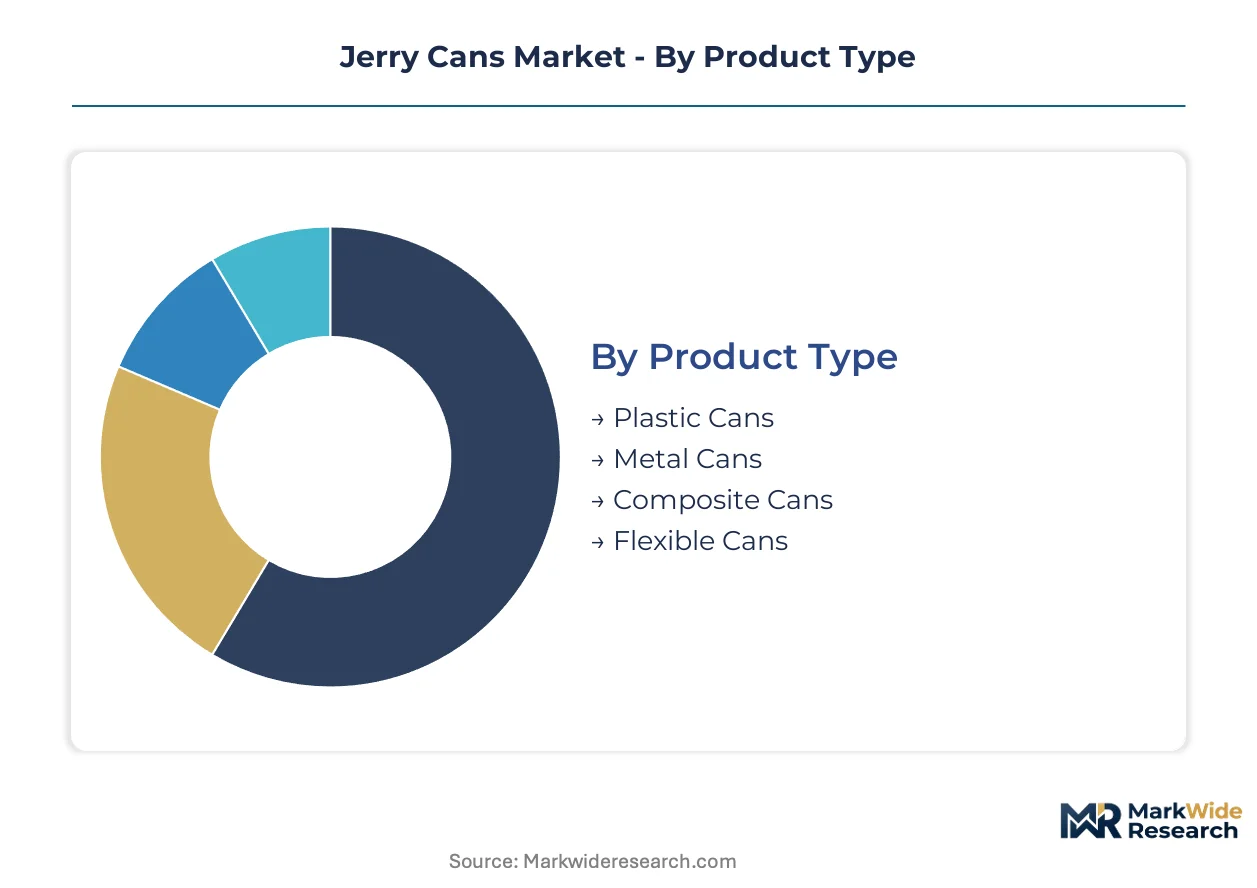
Jerry can procurement patterns diverge sharply by container specification, with cycle times ranging from single-use agricultural chemical disbursement to multi-year industrial fluid logistics. Understanding these velocity differentials enables suppliers to align inventory positioning and reconditioning infrastructure with actual turnover economics.
Product Type:
Plastic cans turn over fastest in agricultural distribution networks, while metal cans command extended replacement cycles in oilfield operations where impact damage drives slower attrition.
- Plastic Cans:High-density polyethylene blow-molding delivers corrosion resistance and sub-2-kilogram tare weights for chemical and agricultural logistics. China's coastal manufacturing provinces concentrate procurement for export-oriented chemical processors seeking ECHA REACH-compliant barrier-layer constructions.
- Metal Cans:Seam-welded tinplate construction withstands NFPA 77 grounding mandates in oil and gas field operations. European tinplate sourcing from the Ruhr cluster creates supply concentration for conductive static-control designs.
- Composite Cans:Hybrid polymer-metal laminates address niche pharmaceutical and high-purity chemical applications.
- Flexible Cans:Collapsible polymer bladders serve military and emergency response logistics where empty container volume reduction matters.
Plastic cans anchor the volume base while composite cans gain share at the steepest rate among specialized chemical applications.
End Use Industry:
Cost tier differentiation separates commodity automotive fluid procurement from premium chemical logistics specifications requiring integrated tracking and deposit-return compliance.
- Automotive:Precision dosing requirements in assembly line operations drive 5-10 liter format demand. India's expanding vehicle manufacturing corridors specify multi-layer polymer designs from Time Technoplast for coolant and brake fluid logistics.
- Chemical:German specialty chemical distributors now mandate per-trip pricing with cradle-to-grave recyclability certification under ECHA frameworks. Greif Inc.'s integrated reconditioning network captures value from tight OEM control over container lifecycle services.
- Agriculture:Seasonal disbursement patterns concentrate demand in Brazil's agrochemical distribution networks.
- Oil & Gas:Impact resistance and static discharge control requirements preserve metal can preference despite higher unit costs.
Chemical end use commands premium pricing tiers while automotive procurement expands most quickly through precision-format adoption.
Capacity:
Volume concentration patterns reflect handling infrastructure constraints across industrial versus retail channels.
- 20 Liters:Industrial procurement standard for chemical and agricultural bulk transfer. Rhine-Ruhr chemical corridor distributors optimize total cost through container turnaround time minimization at this capacity band.
- 25 Liters:Maximum manual handling threshold for warehouse operations without mechanical assist equipment.
- 5 Liters:UN-certified formats with integrated spout designs penetrate direct-to-farmer e-commerce channels.
- 10 Liters:Mid-tier capacity serves automotive aftermarket and smaller-scale agricultural operations.
Twenty-liter formats dominate procurement volume while five-liter designs climb the fastest through e-commerce chemical fulfillment expansion.
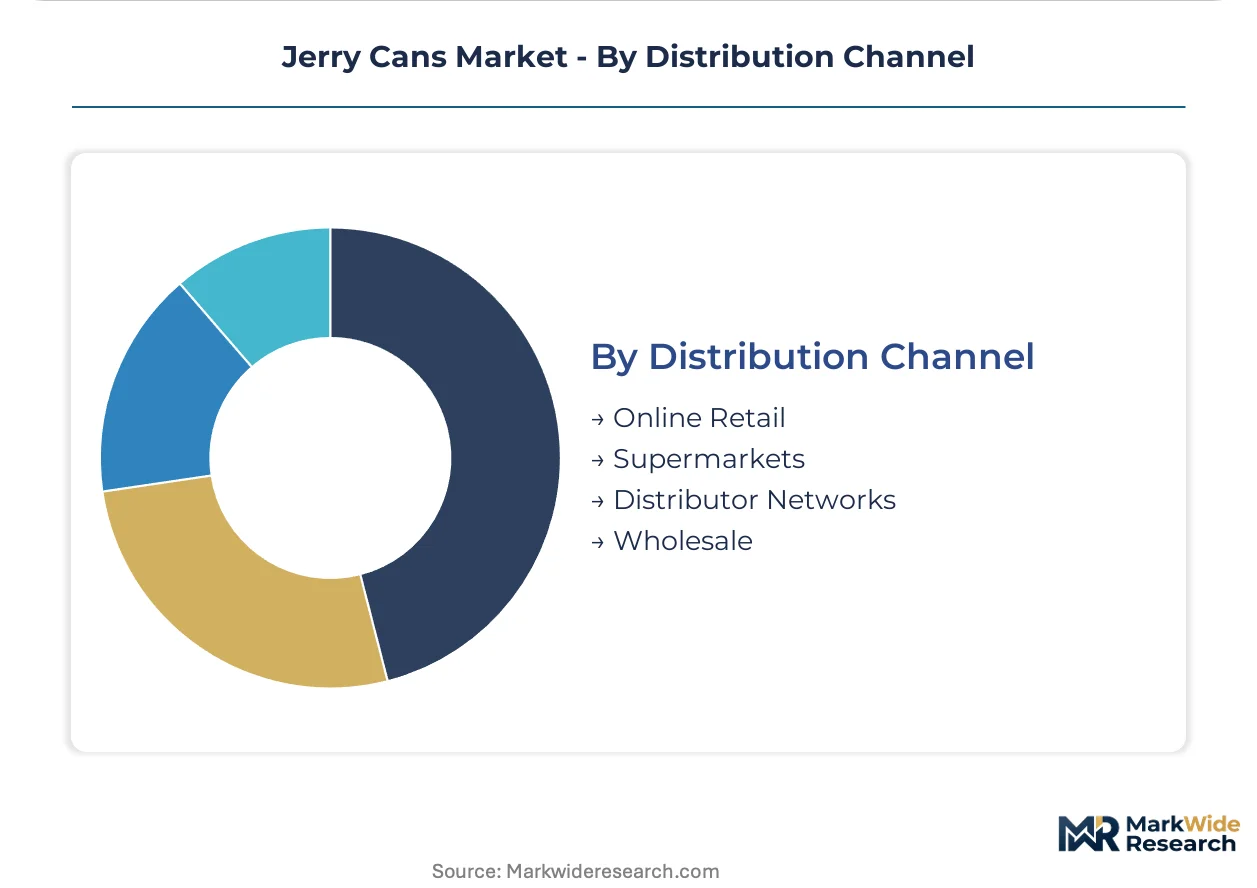
Distribution Channel:
Customer type separation distinguishes capital-intensive fleet leasing from transactional spot purchasing.
- Distributor Networks:Mauser Packaging Solutions anchors European chemical logistics through IBC and jerry can pooling systems with dense depot infrastructure. German specialty chemical processors specify integrated washing and inspection services alongside container provision.
- Wholesale:Bulk procurement for agricultural cooperatives and industrial processors maintains traditional volume concentration.
- Online Retail:Direct-to-farmer channels require UN-certified packaging with simplified handling features.
- Supermarkets:Consumer-format automotive fluids and household chemicals drive retail-facing specifications.
Distributor networks retain volume leadership while online retail exhibits the steepest expansion trajectory among emerging fulfillment channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's automotive corridors show the sharpest price elasticity for 5-10 liter formats, while German chemical processors absorb premium pricing for cradle-to-grave certified containers without volume attrition.
United States
Automotive fluid distributors in the Southeast and Midwest drive steady procurement of precision-dosing formats. EPA and OSHA closure mandates for flammable liquid containers tighten compliance documentation burdens. Houston's petrochemical corridor anchors metal can demand for oilfield operations requiring NFPA 77 grounding compliance.
Germany
Specialty chemical distributors along the Rhine-Ruhr corridor specify per-trip pricing with integrated washing services. ECHA REACH recyclability certification requirements compress supplier qualification timelines. Cologne-Düsseldorf logistics hubs concentrate pooling system depots where Mauser Packaging Solutions optimizes container turnaround economics.
China
Coastal manufacturing provinces in Jiangsu and Zhejiang concentrate export-oriented blow-molding capacity for barrier-layer HDPE designs. GB standards and dual carbon goals reshape polymer additive specifications. Shanghai-Ningbo port clusters handle the bulk of REACH-compliant container shipments bound for European chemical processors.
India
Expanding vehicle manufacturing corridors in Maharashtra and Tamil Nadu accelerate 5-10 liter format adoption for assembly line precision dosing. BIS certification requirements extend product launch cycles for multi-standard SKUs. Pune-Chennai industrial belts anchor Time Technoplast's multi-layer polymer supply to automotive fluid logistics.
Brazil
Seasonal agrochemical disbursement patterns in São Paulo and Mato Grosso create concentrated demand spikes for 20-liter distribution formats. ANVISA registration pathways for reusable containers remain underdeveloped versus mature markets. Campinas-Sorocaba distribution clusters present first-mover openings for pooling system operators.
Jerry Cans Market Key Industry Players
Capability concentration sits with integrated reconditioning specialists; scale advantage sits with diversified packaging conglomerates. The vendor base stratifies across three tiers: global pooling operators with dense depot networks, regional blow-molding specialists with captive polymer supply, and niche metal fabricators serving oilfield static-control requirements. Dominant competitive moves include backward integration into polymer compounding and geographic expansion of washing-inspection depot infrastructure.
Within the integrated reconditioning tier, Greif Inc. and Mauser Packaging Solutions exemplify the depot-network archetype through North American and European chemical corridor presence. Time Technoplast Ltd. occupies a distinct position among Asia-Pacific polymer specialists serving automotive fluid logistics. SCHÜtz and AST Kunststoffverarbeitung GmbH represent Germanic engineering-focused fabricators with technical barrier-layer capabilities.
| Leading Market Players |
|---|
| Scepter Manufacturing |
| Eagle Manufacturing |
| Greif Inc. |
| Wilkinson Containers Ltd. |
| Berry Global Group Inc. |
| Mauser Packaging Solutions |
| Time Technoplast Ltd. |
| AST Kunststoffverarbeitung GmbH |
| SCHÜtz |
| Others |
Cost & Logistics Intelligence
Overcapacity in China's Jiangsu and Zhejiang blow-molding corridors is compressing export pricing for barrier-layer HDPE jerry cans while simultaneously accelerating supplier consolidation around REACH-compliant compounders. This utilization dynamic forces mid-tier molders to absorb resin volatility or cede share to integrated operators with captive polymer supply.
Pricing Analysis
Aftermarket refurbishment revenue from container lifecycle services drives lifetime value capture for depot-network operators. Three-tier pricing structure across premium cradle-to-grave certified, standard multi-trip, and economy single-use levels separates German chemical distributors from Brazilian agrochemical cooperatives. Cost compression in standard-tier polymer cans is intensifying because naphtha-derived resin margins fluctuate with cracking economics. Brazilian agrochemical buyers exhibit the sharpest price elasticity, while Rhine-Ruhr specialty chemical processors absorb premium positioning without volume attrition.
Supply Chain Analysis
Contract blow-molding concentration rests with coastal Chinese operators serving export REACH compliance, Ruhr-cluster tinplate fabricators for conductive metal construction, and Indian multi-layer polymer specialists anchored in Maharashtra. Raw material dependencies center on high-density polyethylene resin, tinplate steel from European rolling mills, and EVOH barrier-layer feedstock. Single-source vulnerability concentrates in European tinplate supply from the Ruhr industrial cluster. Distribution runs through Mauser Packaging Solutions' depot networks in chemical corridors and Greif Inc.'s integrated reconditioning infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward German specialty chemical distributors and Indian automotive OEMs as procurement consolidates around cradle-to-grave certification requirements and precision-dosing format standardization.
For Market Incumbents: Pre-empt margin erosion from naphtha resin volatility by securing backward integration into polymer compounding or captive supply agreements with Middle Eastern feedstock producers. Defend depot-network density in Rhine-Ruhr and Houston corridors against pooling system entrants by embedding IoT tracking for deposit-return compliance. Certification investment in simultaneous BIS-GB-EPA multi-standard SKUs creates switching costs for mid-tier chemical distributors lacking legacy ERP integration.
For New Entrants and Emerging Players: Pursue underdeveloped ANVISA registration pathways for reusable container pooling in Brazil's Campinas-Sorocaba agrochemical distribution clusters. Target direct-to-farmer e-commerce channels with UN-certified 5-liter formats featuring integrated spout designs previously served by bulk drum distribution. Go-to-market execution should anchor on per-trip pricing with washing-inspection bundling to displace outright purchase economics.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among depot-network operators with dense reconditioning infrastructure and long-term chemical logistics contracts. Long-term viability across the analysis window favors acquisition of mid-cap blow-molding specialists with REACH-compliant barrier-layer capabilities and established automotive fluid supply relationships. Watch for inflection in ECHA microplastics restriction enforcement timelines that would accelerate additive reformulation capex requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Greif Inc. and Mauser Packaging Solutions reduce resin cost exposure through captive supply of REACH-compliant HDPE compounds. |
| Multi-Standard Certification Investment | Simultaneous BIS, GB, and EPA approvals compress product launch cycles for export-oriented molders serving Indian and Chinese automotive corridors. |
| Depot Network Expansion | Mauser Packaging Solutions anchors Rhine-Ruhr chemical logistics through dense washing-inspection infrastructure with sub-48-hour turnaround economics. |
| Barrier-Layer Technology Migration | Time Technoplast Ltd. extends six-layer EVOH constructions into agrochemical segments previously restricted to tinplate corrosion resistance. |
| E-Commerce Format Development | UN-certified 5-liter integrated spout designs capture direct-to-farmer channels in Brazilian agrochemical distribution networks. |
Research Approach
Initial hypotheses were tested against primary input from blow-molding plant managers, chemical distributor procurement leads, automotive fluid logistics coordinators, and ECHA regulatory affairs specialists and refined through secondary validation. Customs and trade data from European and Asian port authorities, SEC 10-K filings from packaging conglomerates, and BIS certification registries anchored quantitative sizing. Bottom-up capacity modeling across Jiangsu-Zhejiang manufacturing clusters triangulated with top-down chemical industry consumption estimates.
Demand-supply balance dynamics across the projection horizon anchored volume forecasts, with segmentation by material construction, capacity band, end-use industry, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and replacement cycle compression in multi-trip container programs. Forecast inputs incorporated polymer additive reformulation timelines under ECHA microplastics restrictions and automotive assembly line precision-dosing format adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed compounders or accelerated EU Green Deal packaging mandates would shift outcomes beyond modeled ranges. Quarterly review of naphtha cracking margin spreads, ANVISA reusable container registration progress, and EVOH barrier-layer technology validation in French agrochemical trials is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
PP Container Liner Market
Containers
Container Coating Market
Containers
Conipack Pails Market
Containers
Single Wall Jars Market
Containers
EPS Shippers Market
Containers
PVC Container Market
Containers
Takeaway Containers Market
Containers
Metal Crates Market
Containers
Wet Wipes Canister Market
Containers
2 Piece Cans Market
Containers
Two Compartment Bottles Market
Containers
Vacuum Formed Tray Market
Containers
Sandwich Containers Market
Containers
Asia and Africa Food Cans Market
Containers
HDPE Containers Market
Containers
PUR Containers Packaging Market