
 ISO Ocean Containers Market | 2026-2036
ISO Ocean Containers Market Size, Share, and Industry Trends Forecast 2026-2036
ISO Ocean Containers Market Insights
The capital-intensity divergence between integrated steel producers and specialized reefer assemblers is unwinding as alloy prices fluctuate and energy-efficient insulation becomes a cost center. China International Marine Containers leverages its captive steel supply and port-adjacent fabrication yards to sustain margin control across dry and refrigerated output. CXIC Group Containers competes through geographic dominance in northern China manufacturing clusters, while Maersk Container Industry differentiates via technology leadership in reefer monitoring systems and remote temperature management.
ISO ocean containers are standardized steel or aluminum enclosures built to International Organization for Standardization dimensional and strength specifications, typically fabricated from corten steel with corner castings designed for crane lifting and stacking loads. These units enable intermodal cargo movement across vessel, rail, and truck networks without intermediate handling of contents. Dry containers occupy the mature volume base where margin pools have compressed to single-digit percentages, while refrigerated containers command premium positioning due to compressor unit complexity and pharmaceutical cold-chain compliance requirements. Composite material adoption is accelerating fastest among 40-foot high-cube variants where weight reduction translates directly to fuel savings on Asia-Europe routes.
The International Maritime Organization enforces carbon intensity indicator ratings that penalize inefficient vessel operations, indirectly tightening container specifications through weight and insulation mandates. ISO standards themselves govern corner fitting dimensions, stacking strength, and weatherproofing thresholds that determine market access for any new manufacturer. Classification societies including Lloyd's Register and DNV verify compliance through type-approval processes that add certification costs but protect against liability in multi-modal transit chains. Stakeholders must monitor how IMO 2025-2030 carbon benchmark escalations will reshape material specifications and whether composite adoption rates justify retooling existing steel-dominant production lines.
Market Dynamics
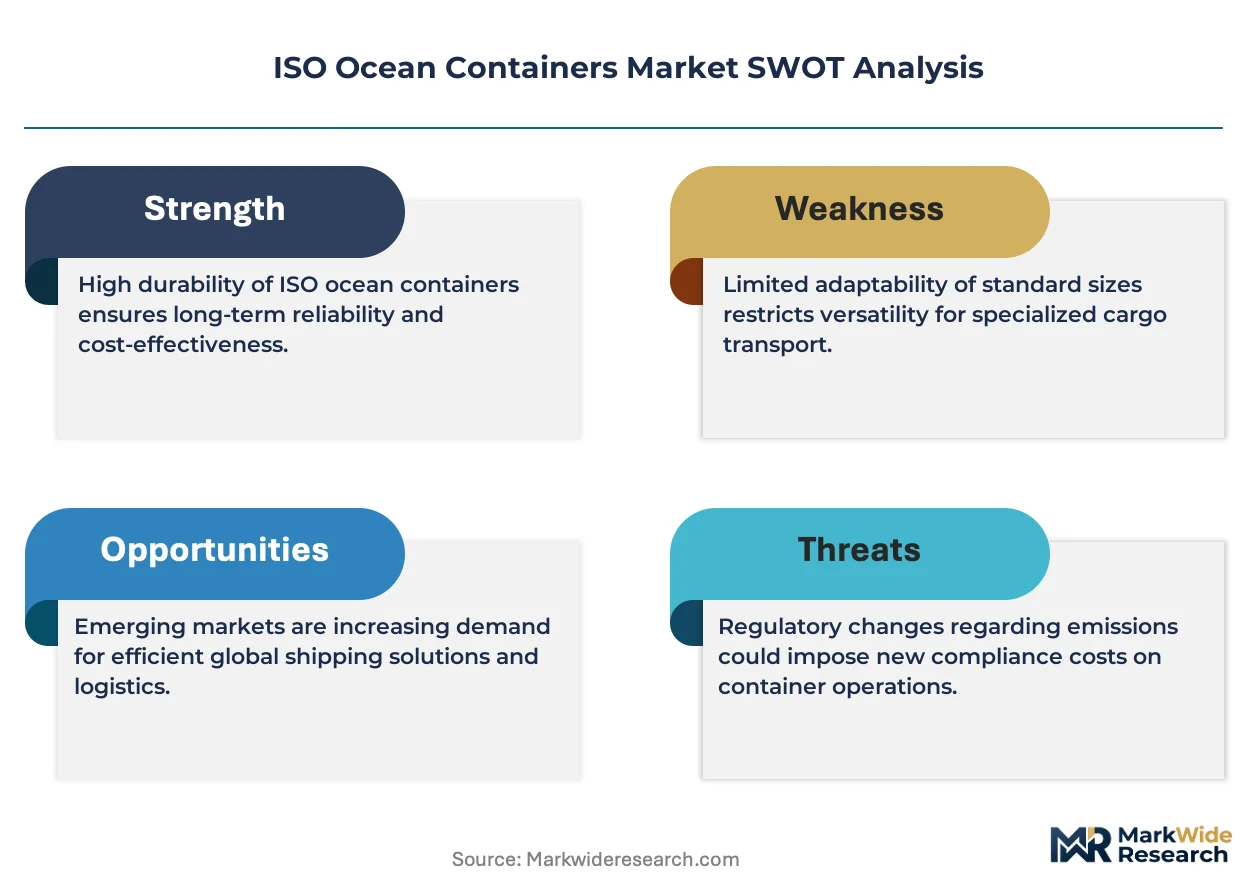
The International Maritime Organization's carbon intensity indicator (CII) framework is compressing fleet economics toward lighter container specifications and energy-intensive reefer investments, forcing carriers to rebalance capital allocation between dry and refrigerated assets.
Growth Catalysts
- Pharmaceutical cold-chain mandates:FDA and EMA temperature-validity requirements for biologics transport are expanding reefer fleet orders among specialized logistics operators.
- Dual carbon goals (China):MEE enforcement of port electrification and shore power is accelerating demand for plug-in capable refrigerated units at Shenzhen and Shanghai terminals.
- Corten steel substitution:Composite sandwich panels using fiber-reinforced polymers are penetrating 40-foot high-cube production lines at Busan and Rotterdam fabricators seeking fuel-efficiency premiums.
Market Restraints
- Aluminum-copper price volatility:Compressor unit manufacturing faces margin pressure from London Metal Exchange commodity swings affecting reefer BOM costs.
- Classification society concentration:Lloyd's Register and DNV certification bottlenecks in Hamburg and Singapore delay new entrant market access by 8-14 months.
- Steel-grade supply consolidation:Corten and weathering steel production concentrates among integrated mills in Hebei province, creating input dependency for non-Chinese fabricators.
Strategic Opportunities
- Underpenetrated African corridor:Mombasa and Dar es Salaam port modernization is opening leasing demand for used 20-foot dry containers from retiring Asia-Europe fleets.
- Remote monitoring convergence:IoT sensor integration with blockchain custody records is creating premium service tiers for pharmaceutical shippers requiring audit trails.
- EU F-Gas Regulation phase-down:Hydrofluorocarbon refrigerant restrictions are forcing reefer compressor retrofits, generating aftermarket retrofit kit demand through 2030.
Industry Challenges
- Welding automation skill scarcity:Corten-to-corner-casting robotic seam welding requires certified technicians absent in emerging fabrication clusters like Vietnam and Indonesia.
- IMO 2025 CII tier escalation:Carriers face compressed vessel upgrade cycles that mismatch with 15-year container asset depreciation schedules.
- Multi-modal liability fragmentation:Rail-road-sea handoffs create insurance coverage gaps when temperature excursions occur in intermodal custody transfers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ISO Ocean Containers Market |
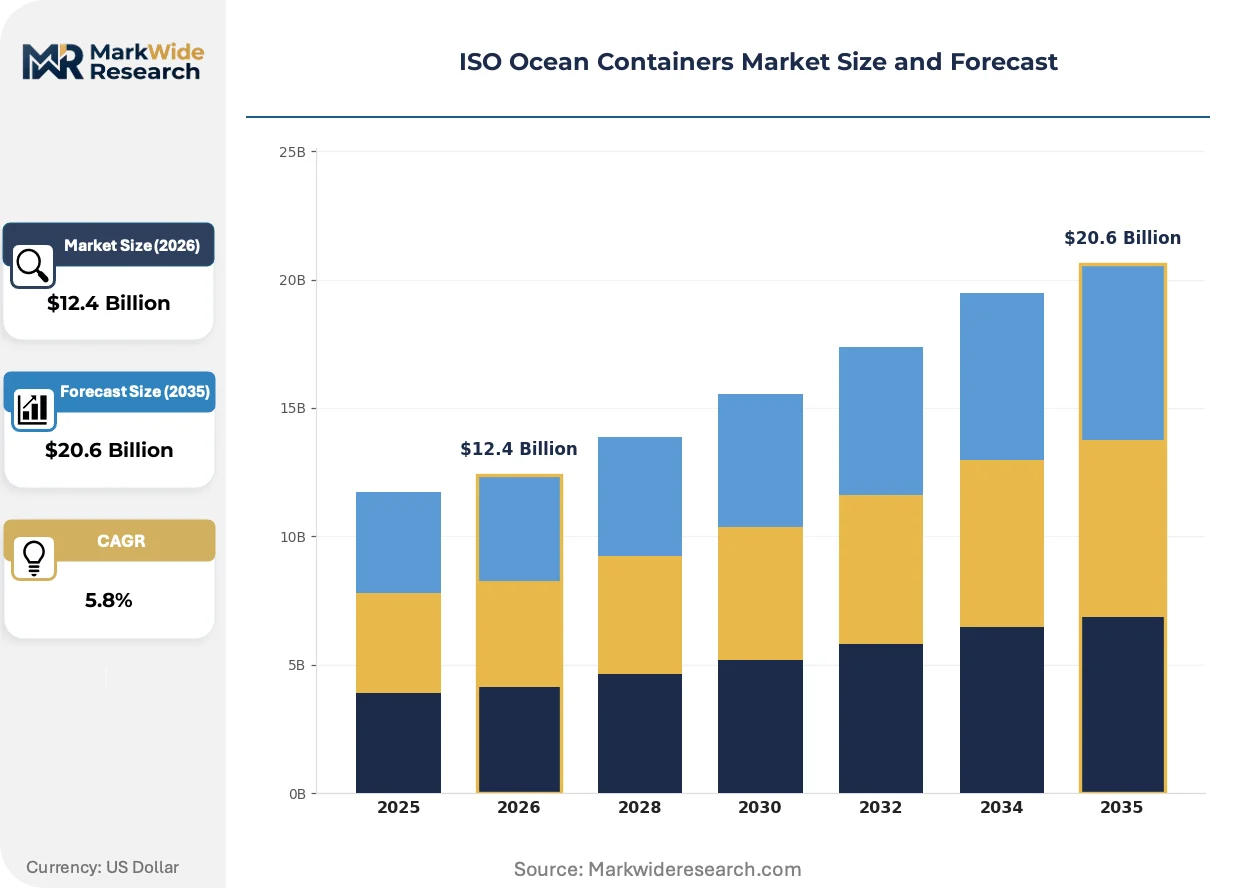
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Containers, Refrigerated Containers, Open Top Containers, Flat Rack Containers Use Case: Shipping, Storage, Intermodal Transport, Export Material: Steel, Aluminum, Composite, Plastic Size: 20 Feet, 40 Feet, 45 Feet, High Cube |
| Companies Covered | China International Marine Containers, CXIC Group Containers, Singamas Container Holdings, Dong Fang International Containers, Maersk Container Industry, Stolt-Nielsen, HOYER Group, NewPort Tank, Bertschi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ISO Ocean Containers Market Trends and Innovations
Container fabricators are racing to reconcile weight-reduction imperatives with structural integrity standards as fuel economics and carbon accounting converge on material selection decisions.
Composite sandwich panels with fiber-reinforced polymer skins are displacing conventional corten steel in 40-foot high-cube dry container production. Mediterranean Shipping and Hapag-Lloyd are specifying these units for Asia-Europe routes where tare weight reductions translate to measurable bunker savings. The technology is displacing legacy steel-dominant procurement patterns among volume buyers seeking CII rating protection.
REACH and the EU F-Gas Regulation are tightening refrigerant specifications for reefer units operating in European Economic Area ports. Compressor manufacturers must now certify alternative cooling chemistries that maintain pharmaceutical temperature bands across ambient extremes. Reefer assemblers with pre-certified low-GWP unit portfolios are capturing premium positioning in Hamburg and Rotterdam leasing pools.
Leasing companies are unbundling maintenance from capital charges, shifting risk to operators through per-voyage service agreements. This model is displacing traditional long-term bareboat charters among mid-tier shipping lines seeking balance-sheet flexibility. The transformation is most visible in Singapore and Dubai hub markets where container trading velocity supports usage-based pricing mechanics.
ISO Ocean Containers Market Segmentation
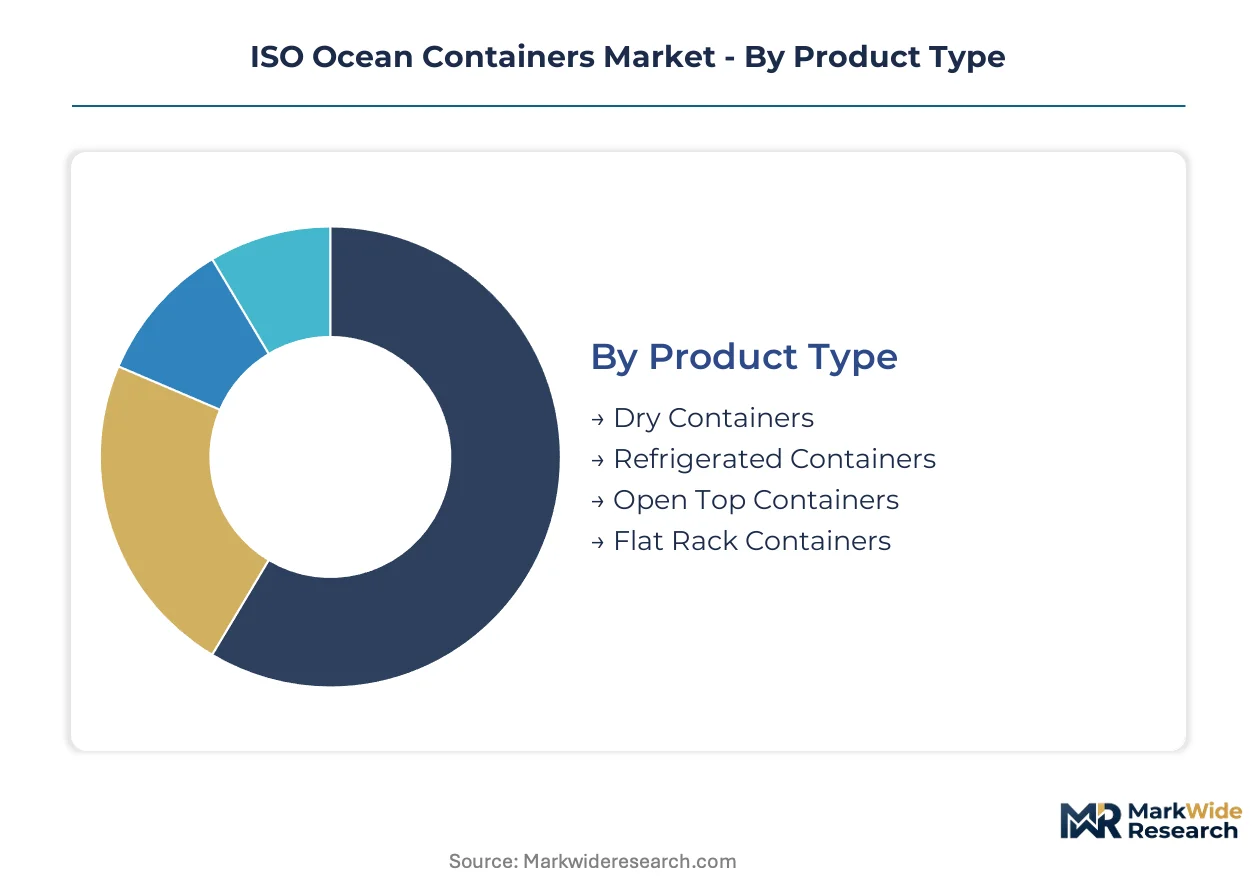
Container specifications diverge sharply across trade lanes, with pharmaceutical cold-chain mandates reshaping reefer procurement while dry units face commoditization pressure. Material selection and dimensional choices now carry carbon-intensity implications under IMO vessel rating frameworks.
Product Type:
Dry containers dominate domestic procurement in China and India where port infrastructure investments absorb high volumes from adjacent fabrication yards. Refrigerated units concentrate in export-led orders to European and North American pharmaceutical logistics operators.
- Dry Containers:Fabricated from corten steel with weather-resistant corner castings, these units handle non-temperature-sensitive cargo across bulk commodity and retail supply chains. Demand concentrates in China where CIMC and CXIC Group supply regional shipping lines with 20-foot and 40-foot standards for intra-Asia routes.
- Refrigerated Containers:Integrated compressor units with remote temperature monitoring capabilities serve biologics and perishable food transport. European leasing pools in Hamburg and Rotterdam command premium positioning due to EU F-Gas Regulation compliance requirements and pharmaceutical validation standards.
- Open Top Containers:Removable tarpaulin roofs accommodate heavy machinery and bulk mineral cargo with overhead loading requirements.
- Flat Rack Containers:Collapsible end walls enable oversized cargo including construction equipment and industrial components.
Dry containers command the established base. The steepest expansion runs through refrigerated units.
Use Case:
Shipping applications absorb volume production at thin margins, while storage and intermodal transport create aftermarket revenue streams for leasing companies.
- Shipping:Vessel-borne cargo movement across deep-sea routes drives fleet renewal cycles tied to carrier CII rating pressures.
- Storage:On-site inventory holding at manufacturing plants and distribution centers repurposes retired containers.
- Intermodal Transport:Rail-road-sea handoffs require corner-casting compatibility across modal equipment standards.
- Export:Cross-border merchandise trade generates specialized demand for customs-sealed units with tamper-evident features.
Shipping anchors volume procurement. Storage applications are gaining share fastest as leasing models unbundle maintenance from capital charges.
Material:
Steel retains cost advantage for high-volume production, while composite adoption accelerates among carriers seeking fuel-efficiency premiums on Asia-Europe routes.
- Steel:Corten and weathering grades provide structural integrity at lowest unit cost, with Hebei province mills supplying integrated fabricators.
- Aluminum:Lightweight properties reduce tare weight for air cargo compatibility and premium express logistics.
- Composite:Fiber-reinforced polymer sandwich panels penetrate 40-foot high-cube production at Busan and Rotterdam facilities seeking CII rating protection.
- Plastic:Modular portable units serve temporary storage and construction site applications with lower durability requirements.
Steel dominates existing fleet composition. Composite materials are climbing the fastest as bunker economics justify material substitution.
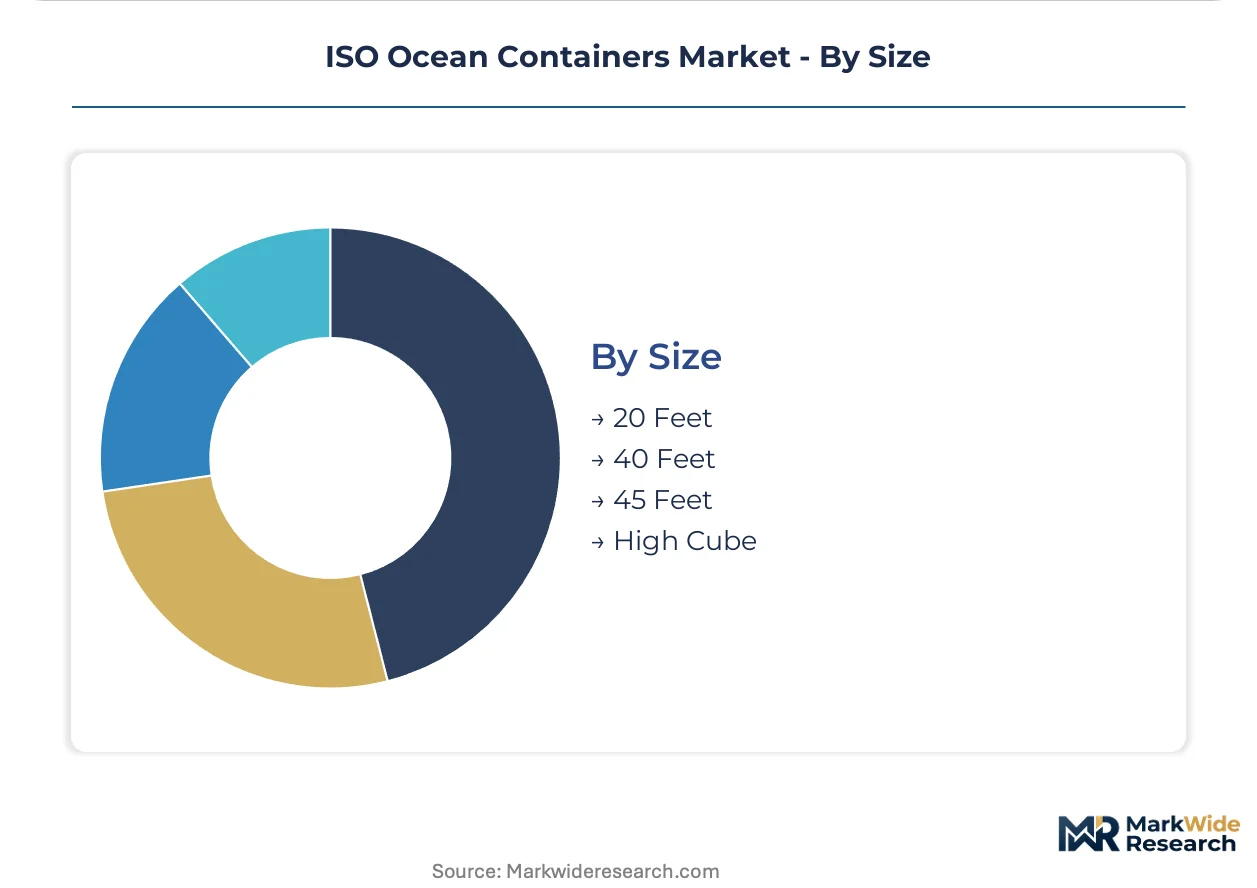
Size:
Twenty-foot units align with domestic trucking regulations in Japan and South Korea, while forty-foot variants optimize vessel slot utilization on long-haul routes.
- 20 Feet:Standard dry boxes match chassis length limits in dense Asian port cities and serve last-mile distribution.
- 40 Feet:Double the capacity of twenty-foot units with minimal handling cost increment, preferred for Asia-Europe and trans-Pacific lanes.
- 45 Feet:Extended length accommodates lightweight volumetric cargo including furniture and consumer electronics.
- High Cube:Additional nine inches of internal height optimizes air freight conversion and garment-on-hanger applications.
Forty-foot specifications command the established base. High cube variants are expanding most quickly as e-commerce volumetric cargo reshapes load factors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan exhibit the lowest price elasticity, prioritizing carbon-efficient specifications and pharmaceutical-grade compliance over unit cost. Chinese and Indian shipping lines remain highly price-sensitive, driving procurement toward standardized dry containers from adjacent fabrication clusters.
China
Port infrastructure investments at Shenzhen and Shanghai terminals are absorbing record container volumes from regional manufacturing bases. MEE enforcement of dual carbon goals mandates shore power compatibility for refrigerated units entering major harbors. CIMC and CXIC Group operate fabrication yards across Guangdong and Shandong provinces, supplying domestic shipping lines with cost-optimized 20-foot and 40-foot standards for intra-Asia routes.
Germany
Pharmaceutical logistics operators in Hamburg and Bremen command premium reefer leasing pools with stringent EU F-Gas Regulation compliance requirements. REACH chemical safety standards govern composite material certification for lightweight container variants entering European Economic Area ports. Industrial clusters along the Elbe River concentrate reefer maintenance facilities and classification society offices serving North Sea trade lanes.
United States
Import-dependent retail supply chains at Los Angeles and Long Beach ports drive dry container demand with compressed margin tolerance. FDA temperature-validity mandates for biologics transport are expanding specialized reefer fleet orders among cold-chain logistics operators. Gulf Coast fabrication yards near Houston serve domestic intermodal rail-road networks with weather-resistant corten steel specifications.
South Korea
Busan port modernization is attracting composite panel fabricators seeking CII rating protection for Asia-Europe route carriers. MFDS pharmaceutical transport guidelines align with international cold-chain standards, validating reefer monitoring system investments. Heavy industrial zones in Ulsan and Gwangyang host steel-intensive production lines integrated with nearby integrated mill complexes.
Netherlands
Rotterdam's Europoort container terminals are prioritizing plug-in capable reefers compliant with EU Green Deal electrification timelines. ECHA chemical regulations restrict fiber-reinforced polymer formulations used in lightweight sandwich panel production. Randstad logistics corridors connect port-adjacent leasing pools with inland barge-rail intermodal terminals serving German industrial demand.
ISO Ocean Containers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure with limited overlap between premium and volume segments. Integrated steel producers with captive raw material supply compete against specialized reefer assemblers on divergent margin models. Three archetypes dominate: port-adjacent fabricators leveraging geographic proximity, technology-focused specialists commanding certification premiums, and diversified industrial conglomerates with backward integration into steel production. Capacity expansion and portfolio diversification toward refrigerated units constitute the primary competitive moves as carriers rebalance asset allocation.
Among Chinese fabricators, China International Marine Containers and CXIC Group Containers exemplify the port-adjacent archetype with integrated steel supply chains. Maersk Container Industry occupies a position representing technology-focused specialists, anchoring premium positioning through remote monitoring capabilities. These three companies illustrate how geographic clustering and capability specialization segment competitive terrain without requiring identical strategic postures.
| Leading Market Players |
|---|
| China International Marine Containers |
| CXIC Group Containers |
| Singamas Container Holdings |
| Dong Fang International Containers |
| Maersk Container Industry |
| Stolt-Nielsen |
| HOYER Group |
| NewPort Tank |
| Bertschi AG |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization rates above 85% at Hebei province integrated mills compress margin buffers for non-Chinese fabricators while reinforcing price floors for corten steel inputs. This scale concentration simultaneously anchors supply-side bargaining power and limits downstream pricing flexibility for specialized reefer assemblers lacking captive raw material access.
Pricing Analysis
After-market service contracts and compressor retrofit kits now generate lifetime value multiples exceeding initial unit sales for reefer manufacturers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and commodity dry containers separates buyers by certification burden and monitoring capability requirements. Pricing pressure stems from aluminum-copper London Metal Exchange volatility affecting reefer bill-of-materials. Chinese domestic shipping lines exhibit highest price sensitivity, while German pharmaceutical logistics operators accept premium positioning for EU F-Gas Regulation compliance.
Supply Chain Analysis
Strategic stockpiling of corten steel coils prevails among port-adjacent fabricators anticipating Hebei mill production quotas, while just-in-time composite panel sourcing characterizes Rotterdam and Busan facilities serving CII-sensitive carriers. Manufacturing gravity centers on China, South Korea, and Germany for finished containers, with Hebei province mills, Japanese aluminum smelters, and German compressor specialists feeding component dependencies. Single-source vulnerability concentrates in weathering steel supply from integrated Chinese producers. Distribution runs through leasing company hub networks at Singapore, Dubai, and Hamburg before vessel deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon intensity regulations are disrupting fleet economics faster than container asset depreciation schedules can absorb, compressing replacement cycles and reallocating capital toward lightweight materials and energy-efficient reefers.
For Market Incumbents: Secure backward integration into composite panel production or captive steel supply to defend margin structure against alloy price volatility. Anchor certification relationships with Lloyd's Register and DNV to maintain type-approval velocity as regulatory timelines compress. Prioritize reefer monitoring system R&D to sustain technology premiums against Chinese volume competitors.
For New Entrants and Emerging Players: Classification society fast-track partnerships in Singapore or Hamburg accelerate market access timelines against incumbent certification backlogs. Target African port modernization corridors in Mombasa and Dar es Salaam with refurbished 20-foot dry container leasing models. Lead with remote IoT monitoring capabilities to differentiate from commodity dry container producers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among reefer lessors with unbundled per-voyage service agreements and aftermarket compressor retrofit exposure. Five-to-ten year viability favors fabricators with port-adjacent yards and dual carbon goal compliance positioning in Chinese harbors. Monitor IMO CII tier escalation announcements as inflection indicators for composite adoption rate acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Production Scale-Up | Busan and Rotterdam fabricators capture CII rating premiums on Asia-Europe routes. |
| Reefer Monitoring System Certification | Maersk Container Industry anchors pharmaceutical leasing pools through remote temperature validation. |
| Port-Adjacent Fabrication Expansion | CIMC and CXIC Group sustain margin control via Guangdong and Shandong yard proximity. |
| Aftermarket Retrofit Kit Development | EU F-Gas Regulation phase-down generates compressor replacement demand through 2030. |
| Leasing Model Unbundling | Singapore and Dubai hub markets shift risk to operators through usage-based pricing mechanics. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with container fleet managers at Mediterranean Shipping and Hapag-Lloyd, procurement directors at CIMC and CXIC Group, leasing company executives in Singapore and Hamburg, and classification society surveyors at Lloyd's Register and DNV. Secondary validation drew from IMO CII regulatory filings, EU F-Gas Regulation implementation notices, London Metal Exchange commodity data, and customs trade statistics. Bottom-up volume estimates triangulated against top-down carrier fleet renewal projections.
Across the analysis window, the forecasting framework modeled container demand by product type (dry, refrigerated, specialized), material specification (steel, aluminum, composite), size category, and end-use application. CAGRs were derived from regression analysis against trade lane volume growth, carbon regulation stringency indices, and fuel price elasticity assumptions. Reefer penetration rates and composite adoption curves served as industry-specific demand drivers.
Decision-makers should treat outputs as directional under assumptions of sustained IMO CII enforcement and stable Hebei steel supply; material deviation in regulatory timelines or trade lane volumes would warrant model refresh. Specific risks include tariff disruption affecting corten steel flows, welding automation skill scarcity delaying capacity expansion, and refrigerant chemistry transitions invalidating existing compressor inventories. Revision becomes warranted when carbon benchmark escalations cross thresholds that accelerate vessel scrapping cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Global Cardboard Box and Container Market
Containers
Takeaway Containers Market
Containers
Slotted Containers Market
Containers
Lever Lid Tinplate Containers Market
Containers
Foam Containers Market
Containers
Water Resistant Packing Cubes Market
Containers
Wooden Barrels Market
Containers
Light Resistant Containers Market
Containers
In-Mold Labelled Containers Market
Containers
Twist Up Stick Container Market
Containers
Acrylic Container Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Popcorn Containers Market
Containers
Stack and Nest Containers Market
Containers
HDPE Bottles Market
Containers
Club Store Packaging Tray Market