
 Middle East and Africa Plastic Bottles and Containers Market | 2026-2036
Middle East and Africa Plastic Bottles and Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Plastic Bottles and Containers Market Foresight
Beverage bottlers is reorganizing procurement priorities away from commodity converters toward partners with integrated preform-to-bottle capabilities. ALPLA Group anchors its regional position through captive resin compounding and blow-molding operations in Egypt and South Africa. SABIC leverages its petrochemical feedstock position in Saudi Arabia to supply specialized polyethylene grades for high-density container applications. MPact Group competes through dedicated dairy and juice packaging formats tailored to Southern African retail chains.
Middle East and Africa plastic bottles and containers comprise hollow-formed packaging vessels manufactured via extrusion blow molding, injection blow molding, or stretch blow molding from thermoplastic resins, with wall thicknesses typically ranging from 0.25mm to 1.5mm depending on barrier requirements and stacking loads. These vessels serve primary functions of product containment, shelf-life extension through gas barrier properties, and brand differentiation via label adhesion surfaces and custom geometries. PET dominates the product type landscape due to its clarity, recyclability infrastructure, and suitability for carbonated beverage pressure retention, while HDPE captures industrial and household chemical applications where chemical resistance and impact strength outweigh optical requirements. The 500ml-1L capacity band holds the largest volume share across beverage and personal care segments, though smaller formats below 250ml are gaining traction in travel-size personal care and pharmaceutical unit-dose packaging.
South Africa's National Regulator for Compulsory Specifications and Egypt's Egyptian Organization for Standardization and Quality impose mandatory migration limits and recycled content declarations on food-contact polyethylene and polypropylene containers. The Gulf Standardization Organization coordinates technical regulations across GCC member states for PET bottle wall thickness and closure integrity standards, creating a partial harmonization zone that reduces cross-border compliance costs. Stakeholders must monitor evolving extended producer responsibility frameworks in Kenya and Nigeria, where draft regulations threaten to reshape collection infrastructure economics and resin sourcing requirements for multinational brand owners operating across the region.
Market Dynamics
Beverage bottlers across the Gulf Cooperation Council are consolidating procurement around converters with captive preform manufacturing, compressing margins for standalone blow-molders without upstream resin compounding capabilities.
Growth Catalysts
- Extended Producer Responsibility frameworks:Kenya's draft regulations mandate producer-funded collection infrastructure, creating guaranteed feedstock streams for mechanical recyclers serving food-contact applications.
- Carbonated soft drink expansion:PET pressure-retention grades are capturing share from glass in Egypt's Alexandria beverage corridor due to lightweighting benefits and reduced breakage rates in distribution.
- Pharmaceutical unit-dose formats:Blow-fill-seal technology penetration is accelerating demand for sub-100ml polypropylene containers in Nigeria's Lagos-Ibadan manufacturing cluster.
Market Restraints
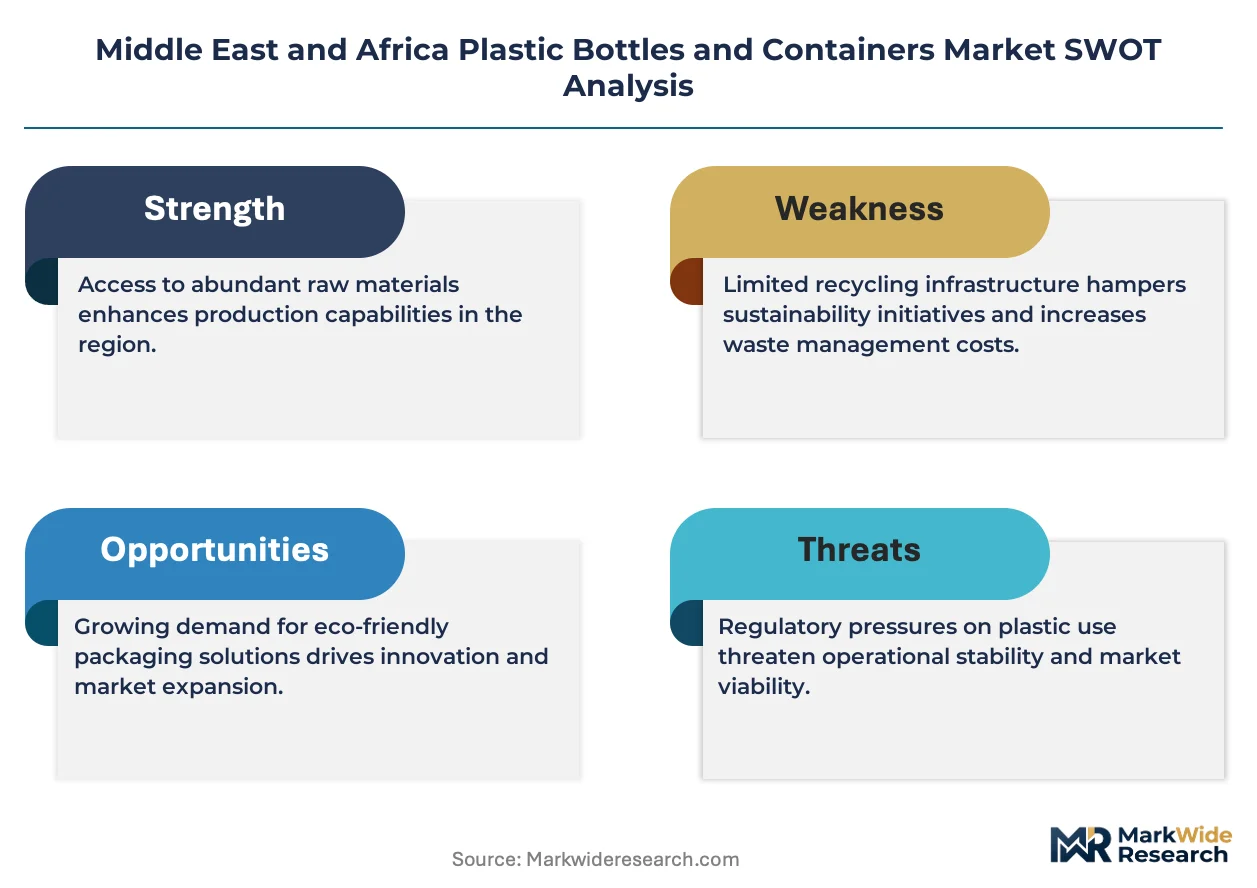
- Ethylene feedstock concentration:Saudi Arabia's SABIC and UAE's Borouge control regional polyethylene supply, exposing converters to monomer price volatility without alternative sourcing.
- Barrier property limitations:Standard PET wall structures require supplemental oxygen scavenger layers for sensitive dairy applications, adding processing complexity and material cost.
- Closure integrity failures:Gulf Standardization Organization testing protocols for carbonated beverage seals create compliance friction for imported closure systems from non-GCC suppliers.
Strategic Opportunities
- East African dairy packaging:Kenya's formal retail expansion is creating unmet demand for HDPE milk bottles with tamper-evident features currently supplied from South Africa at premium freight costs.
- Chemical recycling integration:Pyrolysis-derived feedstocks are enabling food-contact compliance for post-consumer resin in Egypt's Egyptian Organization for Standardization and Quality regulated markets.
- Direct-to-retail distribution:E-commerce platforms are bypassing traditional West African distributor networks, requiring smaller lot sizes and faster design iteration from converters.
Industry Challenges
- Blow-molding technician scarcity:South Africa's Mpact Group and competitors face recruitment gaps for stretch blow-molding process engineers capable of optimizing preform heating profiles for lightweighted designs.
- Migration testing timelines:Egypt's food-contact compliance documentation requires six-month stability studies that delay new product launches for personal care brand owners.
- Legacy injection molding retrofit costs:Converters with existing equipment face capital intensity barriers when transitioning to all-electric machines required for thin-wall pharmaceutical container production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Plastic Bottles and Containers Market |
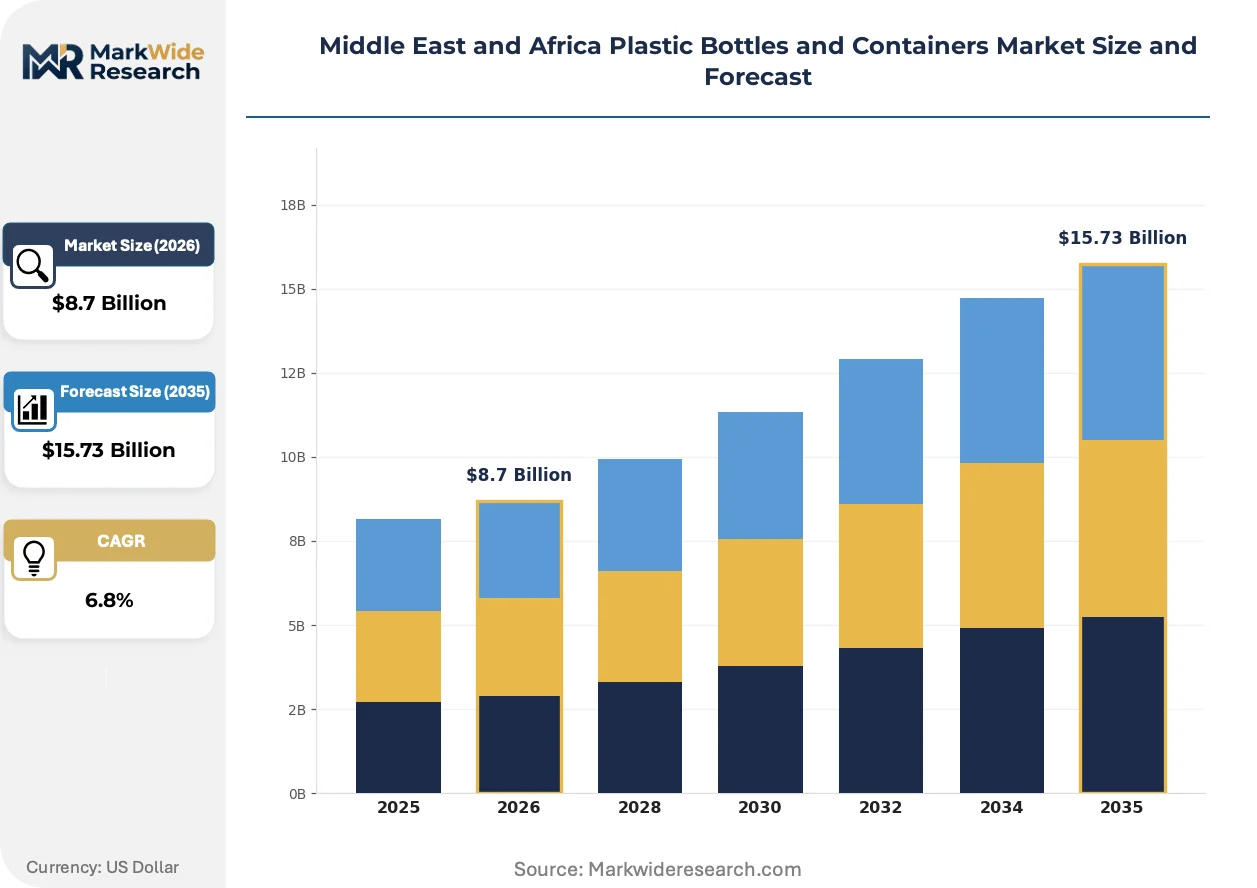
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PP End Use Industry: Beverages, Personal Care, Household Goods, Healthcare Capacity: Less than 250ml, 250ml-500ml, 500ml-1L, More than 1L Closure Type: Screw Caps, Flip Tops, Tamper Evident, Others |
| Companies Covered | Amcor PLC, ALPLA Group, Graham Packaging Company, Plastipak Holdings Inc., Berry Global Inc., Arabian Plastic Industrial Co. (APICO), Bericap Holding GmbH, MPact Group, SABIC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Plastic Bottles and Containers Market Shifts & Advancements
Active and intelligent packaging integration is reshaping competitive positioning among converters serving temperature-sensitive pharmaceutical and premium beverage segments across the region.
Mono-material polyethylene structures with embedded oxygen scavenger additives are supplanting multilayer barrier constructions in dairy and juice applications. South African retail chains are specifying these formats for private-label products to simplify post-consumer sorting. The shift is compressing demand for ethylene vinyl alcohol copolymer tie-layer resins previously imported from European suppliers.
Gulf Standardization Organization harmonization of PET bottle wall thickness minimums is eliminating sub-0.3mm lightweighting experiments that risked top-load failure in stacked distribution. Egyptian and Saudi converters are recalibrating preform designs to meet the unified specification ahead of mandatory adoption timelines. The regulatory convergence is favoring regional scale players with dedicated metrology laboratories over smaller importers.
Brand owners in Nigeria's consumer goods sector are unbundling design and manufacturing relationships, retaining creative agencies for structural packaging innovation while awarding production to lowest-qualified bidders. This bifurcation is eroding long-term converter partnerships that previously secured capacity allocation. The pattern is most visible in Lagos-based personal care distributors competing for shelf space in expanding supermarket formats.
Middle East and Africa Plastic Bottles and Containers Market Segmentation
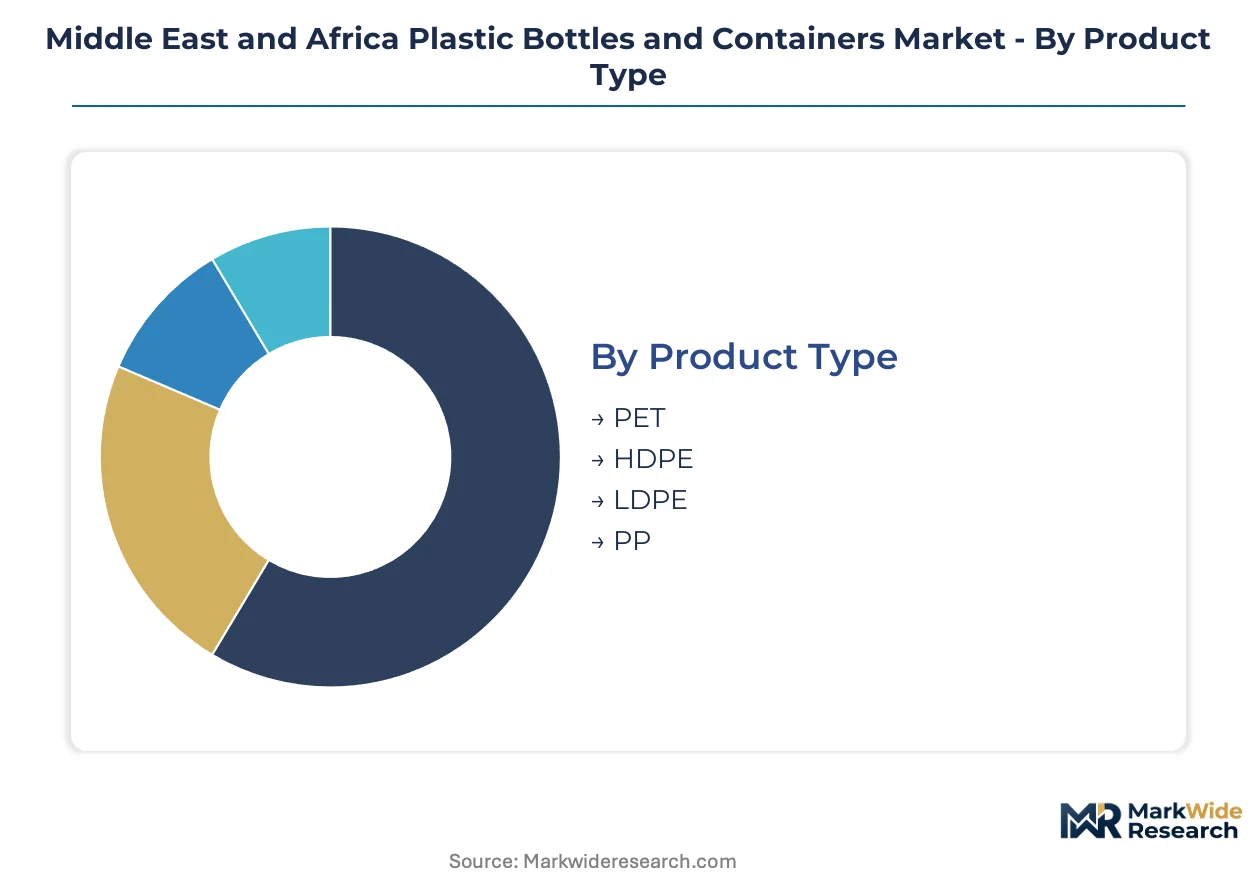
Resin selection and capacity banding in Middle East and Africa plastic bottles and containers reflect divergent compliance burdens across Egyptian food-contact rules, South African recycling mandates, and GCC technical standards. Converters must align production configurations with these regulatory fault lines to secure shelf placement in formal retail channels.
Product Type:
Egypt's Egyptian Organization for Standardization and Quality and South Africa's National Regulator for Compulsory Specifications impose distinct migration limits and recycled content thresholds that reshape resin procurement economics across converter operations.
- PET:Clarity and pressure-retention characteristics make this resin indispensable for carbonated beverages and bottled water throughout the Gulf Cooperation Council. Saudi Arabian beverage bottlers are consolidating procurement around converters with captive preform manufacturing capabilities to secure supply continuity.
- HDPE:Chemical resistance and impact strength position this material for industrial and household chemical containers. South Africa's compulsory recycling specifications favor HDPE formats for dairy applications where post-consumer content thresholds apply.
- LDPE:Flexibility characteristics serve squeeze bottles and dispensing closures across Nigeria's Lagos-Ibadan manufacturing corridor.
- PP:Heat resistance enables hot-fill applications and microwaveable containers in Egypt's processed food sector.
Established volume favors PET; emerging adoption favors PP.
End Use Industry:
Application-specific barrier requirements and closure integrity standards fragment converter specialization across temperature-sensitive and pressure-retention use cases.
- Beverages:Carbonated soft drink expansion across Egypt's Alexandria corridor and GCC markets drives demand for pressure-rated PET structures. Lightweighting benefits and reduced breakage rates are displacing glass in premium water segments.
- Personal Care:Travel-size formats below 250ml are gaining traction in Nigeria's supermarket expansion, requiring faster design iteration from converters serving direct-to-retail distribution channels.
- Household Goods:Chemical resistance specifications favor HDPE containers for detergents and cleaning products across South African retail chains.
- Healthcare:Blow-fill-seal technology penetration is accelerating demand for sub-100ml polypropylene containers in Nigeria's pharmaceutical manufacturing cluster.
Beverage applications command the deepest converter integration; healthcare represents the steepest expansion trajectory.
Capacity:
Distribution economics and retail format evolution are reshaping optimal capacity banding across traditional trade and modern grocery channels.
- Less than 250ml:Unit-dose pharmaceutical and travel-size personal care formats are expanding fastest in Nigeria's formal retail growth. E-commerce platforms are bypassing distributor networks with smaller lot size requirements.
- 250ml-500ml:Premium beverage positioning and on-the-go consumption patterns concentrate demand in Egypt's urban centers and South African metropolitan markets.
- 500ml-1L:This band holds the largest volume share across beverage and personal care segments throughout the region. Standardization benefits reduce converter tooling costs for multinational brand owners.
- More than 1L:Family-size formats and institutional catering applications concentrate in Kenya's formal retail expansion and South African wholesale channels.
The 500ml-1L band anchors converter capacity planning; sub-250ml formats are climbing the fastest.
Closure Type:
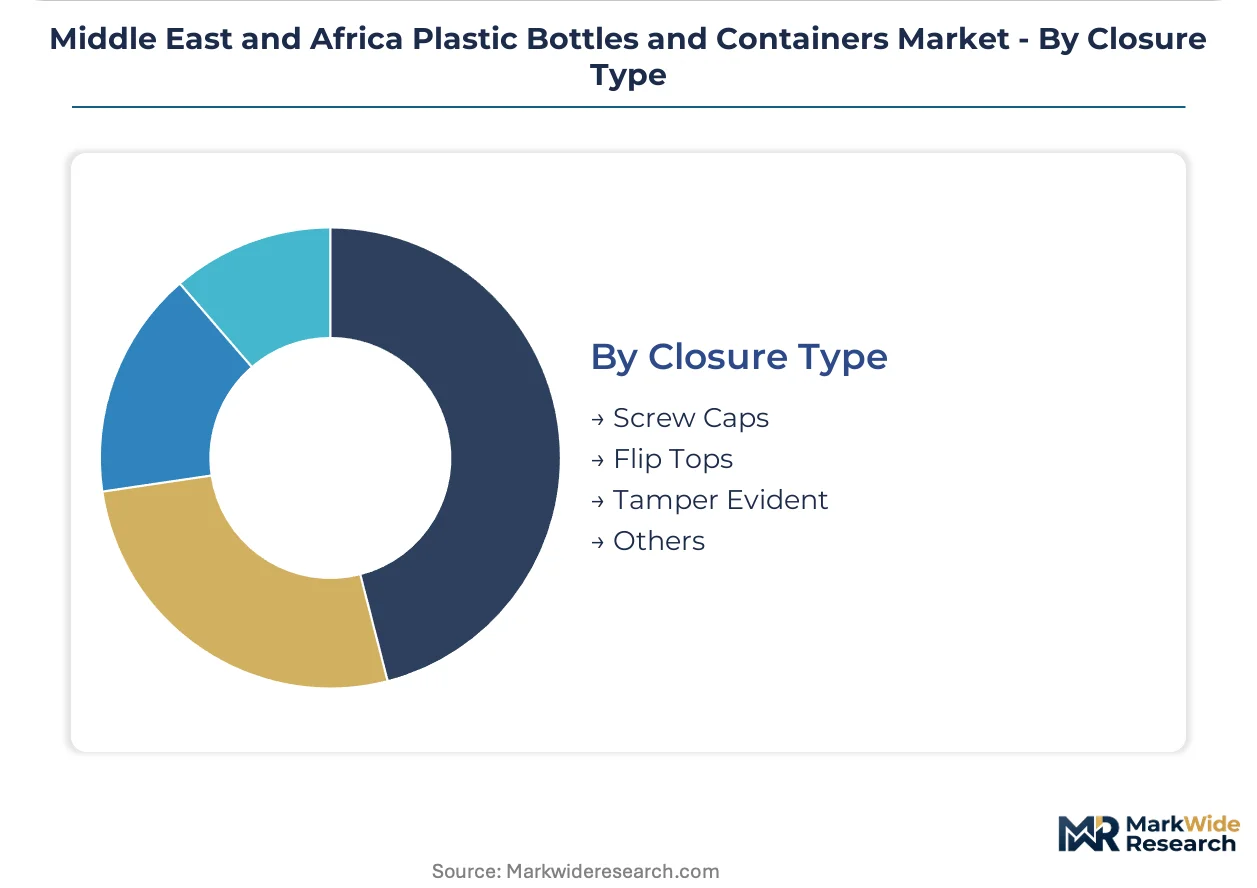
Gulf Standardization Organization testing protocols for seal integrity are eliminating non-compliant imported closure systems and favoring regional specification development.
- Screw Caps:Universal application across beverage and chemical segments with established torque specification standards throughout GCC markets.
- Flip Tops:Convenience positioning serves personal care and condiment applications in South African retail private-label programs.
- Tamper Evident:Regulatory mandates for food-contact and pharmaceutical safety are expanding this specification across Egypt and Kenya. Kenya's dairy packaging demand is creating unmet need for tamper-evident HDPE bottles currently supplied from South Africa at premium freight costs.
- Others:Dispensing pumps and trigger sprayers serve household chemical applications with specialized actuator requirements.
Screw caps dominate procurement volumes; tamper-evident features are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South African converters export HDPE dairy containers to Kenya's formal retail sector, while Egyptian PET preform manufacturers supply Libya and Sudan through Alexandria's port infrastructure.
Saudi Arabia
Carbonated beverage bottlers in Riyadh and Jeddah are consolidating procurement around converters with captive resin compounding capabilities. The Saudi Food and Drug Authority enforces migration limits on food-contact polyethylene containers. The Eastern Province petrochemical cluster feeds specialized polyethylene grades to high-density container applications serving GCC distribution networks.
South Africa
Formal retail expansion in Johannesburg and Cape Town is driving demand for tamper-evident HDPE milk bottles. The National Regulator for Compulsory Specifications mandates recycled content thresholds for polyethylene containers. The Durban-Gauteng manufacturing corridor hosts blow-molding capacity serving Southern African consumer goods distributors with dairy and juice packaging formats.
Egypt
Alexandria's beverage corridor is displacing glass with PET pressure-retention grades for carbonated soft drinks and premium water. The Egyptian Organization for Standardization and Quality imposes six-month stability studies for food-contact compliance documentation. The Cairo-Suez industrial zone concentrates injection blow-molding operations for pharmaceutical unit-dose containers.
Nigeria
Supermarket format expansion in Lagos is accelerating demand for travel-size personal care formats below 250ml. Draft extended producer responsibility regulations threaten to reshape collection infrastructure economics for multinational brand owners. The Lagos-Ibadan manufacturing corridor serves West African consumer goods distributors with blow-molded capacity for squeeze bottles and dispensing closures.
Kenya
Formal retail growth in Nairobi is creating unmet demand for HDPE milk bottles currently imported from South Africa at premium freight costs. Draft regulations mandate producer-funded collection infrastructure for mechanical recyclers. The Mombasa-Nairobi logistics corridor channels imported preforms to domestic blow-molders serving East African dairy packaging requirements.
Middle East and Africa Plastic Bottles and Containers Market Competitive Landscape
Listed leaders compete with private specialists across resin integration and geographic coverage dimensions. The vendor base clusters around petrochemical-backed converters with captive feedstock access and independent blow-molders serving niche format requirements. Three archetypes dominate: integrated resin-to-bottle operators, standalone converters with design capabilities, and regional specialists in pharmaceutical or dairy segments. Capacity expansion and backward integration into preform manufacturing represent the dominant competitive moves.
Within the integrated operator tier, ALPLA Group and SABIC exemplify divergent strategic positions. ALPLA anchors regional presence through captive operations in Egypt and South Africa, representing the converter-led integration model. SABIC occupies a feedstock-dominant position, leveraging Saudi petrochemical infrastructure to supply specialized polyethylene grades. Among independent specialists, MPact Group sits within the Southern African dairy and juice packaging segment, demonstrating format-specific competitive positioning against broader-based rivals.
| Leading Market Players |
|---|
| Amcor PLC |
| ALPLA Group |
| Graham Packaging Company |
| Plastipak Holdings Inc. |
| Berry Global Inc. |
| Arabian Plastic Industrial Co. (APICO) |
| Bericap Holding GmbH |
| MPact Group |
| SABIC |
| Others |
Supply & Pricing Matrix
Long-term resin offtake contracts between Saudi Arabian petrochemical producers and Egyptian blow-molders lock in polyethylene supply access while capping price volatility exposure across the Cairo-Alexandria manufacturing corridor. These arrangements bind converters to minimum volume commitments in exchange for feedstock cost predictability that standalone operators cannot replicate.
Pricing Analysis
Current-generation all-electric blow-molding equipment commands a 15-20% capital premium over hydraulic legacy systems, yet delivers unit cost advantages through energy efficiency and faster cycle times that reshape converter competitiveness. Pricing stratifies across premium, standard, and economy tiers based on barrier performance certification and recycled content compliance grade. Cost compression in standard-grade PET beverage containers is intensifying because Gulf Cooperation Council bottlers are consolidating procurement around integrated preform-to-bottle suppliers. Small-scale Nigerian converters serving West African distributor networks exhibit the highest price sensitivity, while Saudi pharmaceutical packaging specialists prioritize seal integrity over unit economics.
Supply Chain Analysis
Strait of Hormuz transit underwrites regional polyethylene feedstock flows, with any disruption immediately pressuring Egyptian and South African converter operations dependent on Gulf-sourced resin. Supply concentration centers on Saudi Arabia's Eastern Province petrochemical cluster, the UAE's Borouge facilities, and South Africa's Sasol polymer operations. Raw material dependencies span ethylene monomer, specialized PET resin grades for carbonated beverage pressure retention, and imported oxygen scavenger additives for dairy barrier applications. Single-source vulnerability runs through SABIC's regional polyethylene supply dominance, which exposes converters to monomer price spikes without alternative sourcing. Distribution feeds from integrated converter plants directly to GCC beverage bottlers, South African retail chains, and Lagos-based consumer goods distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against aluminum can and aseptic carton substitution in premium beverage segments where sustainability positioning and shelf-life extension are reshaping procurement criteria. Glass displacement in carbonated soft drinks remains incomplete, creating vulnerability for PET-heavy converters.
For Market Incumbents: Consolidate captive preform manufacturing capabilities to secure supply continuity as Gulf Cooperation Council bottlers reorganize procurement around integrated partners. Backward integration into resin compounding, exemplified by ALPLA Group's Egyptian and South African operations, defends margin position against standalone blow-molders facing feedstock cost volatility. Certification investment in Egypt's Egyptian Organization for Standardization and Quality food-contact compliance documentation creates switching costs that bind multinational brand owners.
For New Entrants and Emerging Players: Design-to-delivery speed gaps in Nigeria's Lagos-Ibadan corridor, where e-commerce platforms demand smaller lot sizes and faster iteration than established converters provide, open white-space opportunities. Kenya's formal retail expansion for dairy packaging represents the most penetrable geography, with tamper-evident HDPE milk bottles currently imported from South Africa at freight premiums that local production can undercut. A go-to-market angle anchored in direct-to-retail distribution partnerships, bypassing traditional West African distributor networks, captures share from legacy players optimized for bulk shipments.
For Investors and Strategic Acquirers: Capital is best deployed toward converters with demonstrated regulatory navigation capabilities across Egyptian, South African, and Gulf Standardization Organization jurisdictions, as compliance complexity rises as a competitive moat. The five-to-ten year viability window favors integrated resin-to-bottle operators over standalone blow-molders facing margin compression from upstream consolidation. The signal to watch as an inflection indicator is Kenya's final extended producer responsibility regulation, which would reshape collection infrastructure economics and resin sourcing requirements for multinational brand owners operating across the region.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Manufacturing | Captive preform production secures supply continuity for GCC beverage bottlers consolidating procurement. |
| Chemical Recycling Feedstock Adoption | Pyrolysis-derived resins enable Egyptian converters to meet Egyptian Organization for Standardization and Quality food-contact compliance for post-consumer content. |
| Tamper-Evident Closure Specification Development | Kenya's dairy packaging demand creates first-mover advantage for converters investing in HDPE bottle security features. |
| All-Electric Machine Fleet Conversion | Thin-wall pharmaceutical container production in Egypt's Cairo-Suez zone requires capital-intensive equipment upgrades. |
| Direct-to-Retail Distribution Partnership | E-commerce platform relationships in Nigeria's Lagos market bypass traditional distributor networks with smaller lot capabilities. |
Research Methodology
A standing panel of blow-molding plant managers, resin procurement leads at Egyptian and South African converters, Gulf Cooperation Council beverage bottler supply chain directors, and pharmaceutical packaging regulatory affairs specialists provided ongoing calibration across the primary research phase. Secondary validation drew from customs and trade data tracking polyethylene and PET resin flows, Gulf Standardization Organization technical regulation filings, Egyptian Organization for Standardization and Quality compliance documentation, and SEC filings of listed packaging companies. Bottom-up capacity assessments at individual converter facilities were triangulated against top-down demand estimates derived from beverage production volumes and retail channel expansion data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with modeled segmentation spanning resin type, capacity band, end-use industry, and closure specification. The analytical framework incorporated converter utilization rates, preform import dependencies, and extended producer responsibility implementation timelines as industry-specific forecast inputs. CAGRs were derived from fitted growth curves applied to baseline capacity and demand estimates, with cross-referencing to petrochemical feedstock expansion plans and retail format evolution patterns.
Underlying assumptions cover regulatory implementation timelines in Kenya and Nigeria, recycled content threshold enforcement in South Africa, and Gulf Standardization Organization harmonization adoption rates, with deviation risk concentrated in draft extended producer responsibility frameworks that could accelerate or delay collection infrastructure investment. Practitioners should keep alternative scenarios live as Kenyan and Nigerian regulatory finalization and chemical recycling technology cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Pail Lids Market
Containers
Wire Containers Market
Containers
Club Store Packaging Tray Market
Containers
Jug Shipper Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
Collapsible Crate Market
Containers
In-Mold Labelled Containers Market
Containers
Lever Lid Tinplate Containers Market
Containers
Rotomolded Containers Market
Containers
Injection Molding Containers Market
Containers
Cups and Lids Market
Containers
Container Stacking Machine Market
Containers
Trigger Sprayer Market
Containers
Global Flexitanks Market
Containers
Stainless Steel Cask Market
Containers
Mini Spray Bottles Market