
 Foam Hinged Take-Out Containers Market | 2026-2036
Foam Hinged Take-Out Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Hinged Take-Out Containers Market Foresight
The foam hinged take-out container market is consolidating around a sharp split between premium biodegradable grades and commodity polystyrene lines. Dart Container Corporation leverages its captive resin sourcing and massive North American manufacturing footprint to dominate cost-sensitive volume segments. Genpak LLC differentiates through specialized biodegradable foam formulations that command price premiums in regulated coastal markets. Huhtamaki Oyj anchors its position with European foodservice customers facing stringent packaging mandates.
Foam hinged take-out containers are single-piece, fold-over food packaging units molded from expanded polystyrene, polyethylene, or polypropylene foam, typically featuring an integrated lid connected by a flexible hinge along one edge and designed to maintain food temperature during transport. Polystyrene retains the largest installed base due to its insulating properties and low unit cost, though biodegradable foam represents the fastest-growing material category as operators preempt regulatory restrictions. Quick-service restaurants and food trucks together absorb the dominant share of medium and large portion capacities, while family-size formats remain concentrated in catering channels where order values justify higher per-unit packaging spend.
The EPA and FDA govern food-contact safety standards for foam packaging in the United States, while the EU Green Deal and F-Gas Regulation constrain hydrocarbon blowing-agent chemistry across European production lines. State-level polystyrene bans in California, New York, and Maine are fragmenting permissible product specifications and forcing distributors to maintain dual inventory pools. Stakeholders must monitor the trajectory of biodegradable foam cost curves against enforcement timelines to decide whether to accelerate conversion investments or extract remaining value from legacy polystyrene assets.
Market Dynamics
Regulatory bifurcation between legacy polystyrene and biodegradable foam alternatives is fragmenting procurement specifications and forcing distributors to maintain dual inventory pools across incompatible state mandates.
Growth Catalysts
- EU Single-Use Plastics Directive:Foodservice operators across Germany, France, and Italy are accelerating conversion timelines to avoid supply disruptions as enforcement deadlines approach.
- Quick-service restaurant delivery expansion:Chains are standardizing medium-format hinged containers for hot-food transport, creating pull-through demand for insulated foam grades.
- Biodegradable foam chemistry:PLA-starch blends and mycelium-based formulations are achieving functional parity with expanded polystyrene in thermal retention tests.
Market Restraints
- Resin cost volatility:Benzene feedstock prices for polystyrene production fluctuate with crude oil markets, compressing margins on commodity-grade containers.
- Regional supply concentration:North American molded-foam capacity clusters in the southeastern United States, exposing distributors to hurricane-related production interruptions.
- Technical performance gaps:Biodegradable alternatives exhibit inferior grease resistance above 70°C, limiting adoption for fried-food applications.
Strategic Opportunities
- India foodservice modernization:Organized quick-service chains in Mumbai and Bangalore are adopting standardized take-out packaging as delivery platforms scale.
- California AB 1200 compliance:Operators seeking PFAS-free alternatives are creating entry points for mineral-filled polypropylene foam substitutes.
- Cloud kitchen consolidation:Shared commercial kitchen facilities are centralizing procurement, enabling direct supplier relationships that bypass traditional distribution tiers.
Industry Challenges
- Dual-track certification burden:Manufacturers must secure separate FDA food-contact approvals for legacy and biodegradable product lines, extending new-product launch cycles.
- Legacy equipment retrofit costs:Converting polystyrene molding lines to process PLA-based foams requires capital outlays for modified extrusion and cooling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Hinged Take-Out Containers Market |
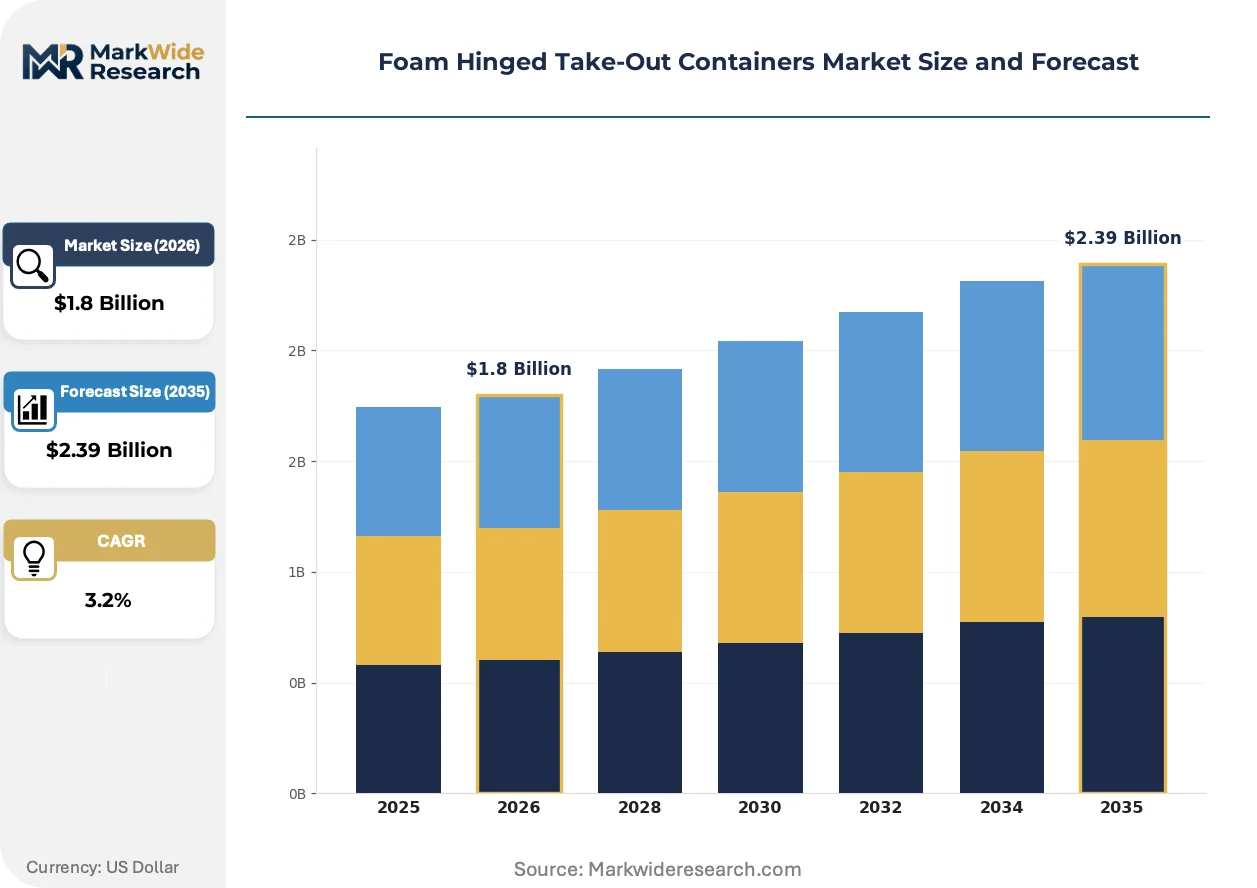
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polystyrene, Polyethylene, Polypropylene, Biodegradable Foam, Foam Laminates, Expanded Polyethylene Packaging Capacity: Small Portion, Medium Portion, Large Portion, Extra-Large Portion, Family Size End User: Food Trucks, Quick-Service Restaurants, Catering Services, Cafeterias, Street Vendors Distribution Channel: Wholesale Distributors, Online Retailers, Direct Manufacturer Sales, Foodservice Suppliers, Institutional Buyers |
| Companies Covered | Dart Container Corporation, Genpak LLC, Pactiv Evergreen Inc., Huhtamaki Oyj, Sabert Corporation, Placon Corporation, Anchor Packaging Inc., Great Northern Corporation, Novolex Holdings LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Hinged Take-Out Containers Market Shifts & Advancements
Material science breakthroughs and regulatory enforcement timelines are compressing the window for conventional foam economics while opening premium positioning for compliant alternatives.
High-speed robotic de-nesting and lid-attachment systems are automating post-mold handling for hinged-container production lines. Tier-one converters in the United States and Germany are deploying vision-guided pick-and-place equipment to reduce labor content per thousand units. This capital deployment is automating throughput scaling without proportional headcount expansion, tightening unit economics for high-volume contracts.
The EU F-Gas Regulation is phasing out hydrocarbon blowing agents with high global-warming potential across European production lines. Molded-foam manufacturers are retrofitting extrusion equipment to accommodate CO₂-based physical foaming or water-blown chemical systems. Container producers serving French and German foodservice accounts are absorbing compliance costs earlier than competitors to secure multi-year supply agreements.
Consolidated procurement through foodservice management companies is displacing fragmented distributor purchasing for institutional accounts. Aramark, Compass Group, and Sodexo are centralizing packaging specifications across their North American and European operations. This concentration is most visible in university and healthcare contracts, where sustainability scorecards now override incumbent supplier relationships.
Foam Hinged Take-Out Containers Market Segmentation
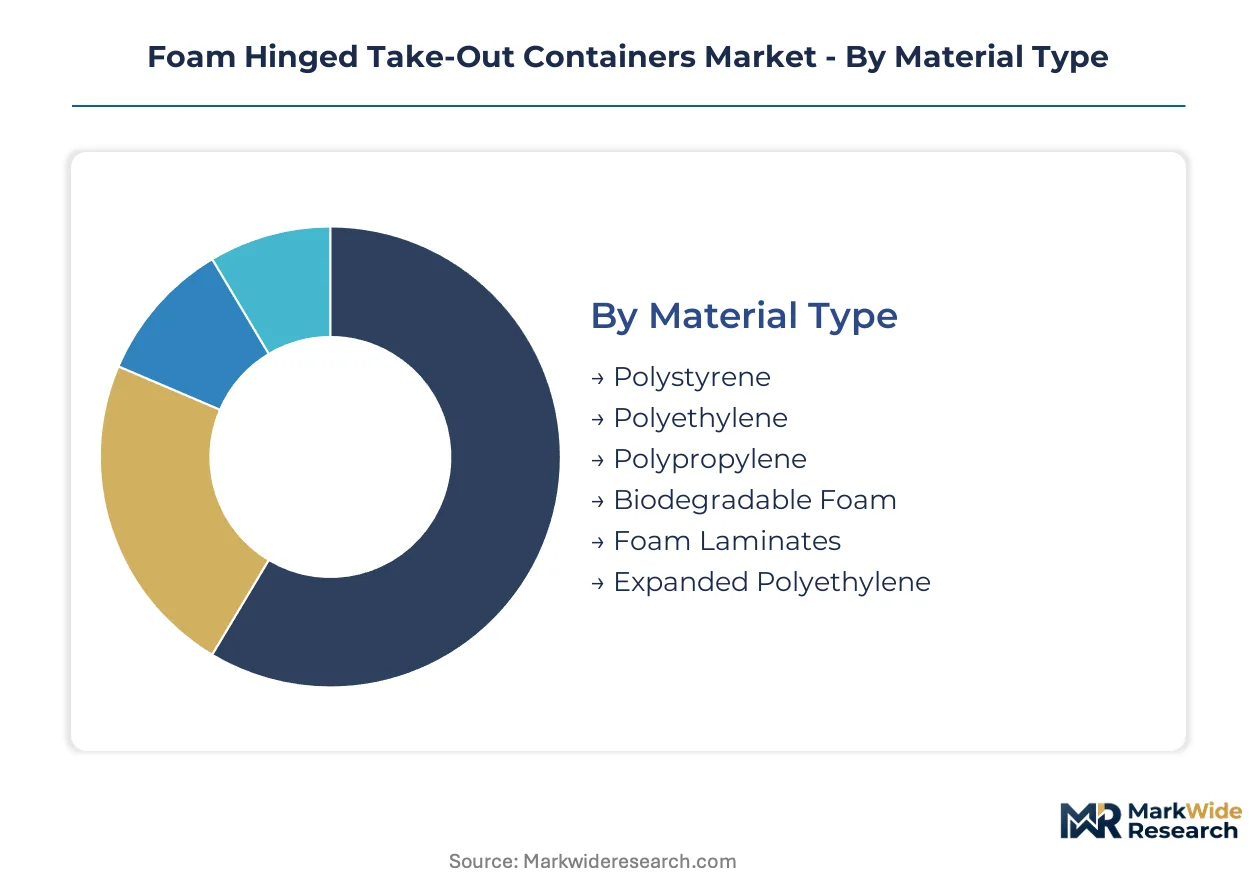
Segmentation in foam hinged take-out containers reveals how material chemistry, portion sizing, and channel structure determine procurement economics. Each dimension carries distinct margin profiles and regulatory exposure that shape supplier positioning.
Material Type:
Integration depth varies sharply: polystyrene and polyethylene serve as standalone commodity inputs, while biodegradable foams and laminates embed proprietary formulations requiring technical partnership.
- Polystyrene:Expanded polystyrene foam delivers thermal insulation through trapped air pockets in a closed-cell structure. Quick-service restaurants in Texas and Florida rely on this grade for fried-food transport where grease resistance exceeds 85°C, though California's statewide ban forces distributors to exclude this material from coastal supply pools.
- Biodegradable Foam:PLA-starch and mycelium-based formulations achieve functional parity with conventional foams in temperature retention testing. German and French foodservice operators facing EU Single-Use Plastics Directive deadlines are converting procurement specifications to this grade fastest, accepting 15-25% unit cost premiums for compliance certainty.
- Polyethylene:Cross-linked PE foam offers superior moisture barrier properties for sauced dishes.
- Polypropylene:Mineral-filled PP grades meet California AB 1200 PFAS-free mandates without full biodegradability.
- Foam Laminates:Multi-layer constructions bond insulation cores with printable outer skins for branded applications.
- Expanded Polyethylene:EPE provides intermediate cushioning for premium catering presentations.
Volume placements concentrate in Polystyrene; the faster expansion belongs to Biodegradable Foam.
Packaging Capacity:
Cost tiering separates commodity high-rotation formats from specialized event-scale units with distinct tooling amortization profiles.
- Medium Portion:The 24-32 ounce format dominates quick-service restaurant standardization for combo meals and single entrees. Cloud kitchen operators in Atlanta and Dallas specify this capacity for delivery platform orders where thermal retention during 20-30 minute transport windows determines customer satisfaction scores.
- Family Size:Multi-compartment hinged designs accommodate 4-6 serving portions for catering and holiday orders. Institutional buyers in university and healthcare channels absorb this segment's higher per-unit cost through centralized procurement contracts that prioritize portion control and presentation over disposable packaging spend.
- Small Portion:8-16 ounce units target side dishes and children's meals.
- Large Portion:40-48 ounce formats serve entree-plus-side combinations.
- Extra-Large Portion:Oversized containers handle bulk protein orders from barbecue and seafood specialists.
Procurement weight falls heaviest on Medium Portion; Family Size commands the steepest expansion trajectory as catering channels professionalize.
End User:
Customer type determines specification complexity: fragmented street-level operators purchase spot quantities while consolidated chains negotiate multi-year supply agreements with embedded sustainability clauses.
- Quick-Service Restaurants:National chains standardize hinged container specifications across thousands of locations, creating concentrated demand pools for approved suppliers. Burger and chicken chains in the southeastern United States specify medium-format polystyrene or biodegradable alternatives depending on state regulatory status, with procurement decisions centralized at headquarters level.
- Catering Services:Event and corporate caterers demand family-size formats with premium presentation characteristics. New York and Los Angeles catering operators are converting to biodegradable laminates fastest to align with client sustainability scorecards and venue packaging restrictions.
- Food Trucks:Mobile operators prioritize space-efficient nesting and rapid lid closure for speed-of-service.
- Cafeterias:Institutional feeding operations balance cost control with volume throughput requirements.
- Street Vendors:Unorganized small-scale purchasers drive spot market demand for commodity grades.
Order concentration sits with Quick-Service Restaurants; Catering Services generate the most rapid specification upgrading.
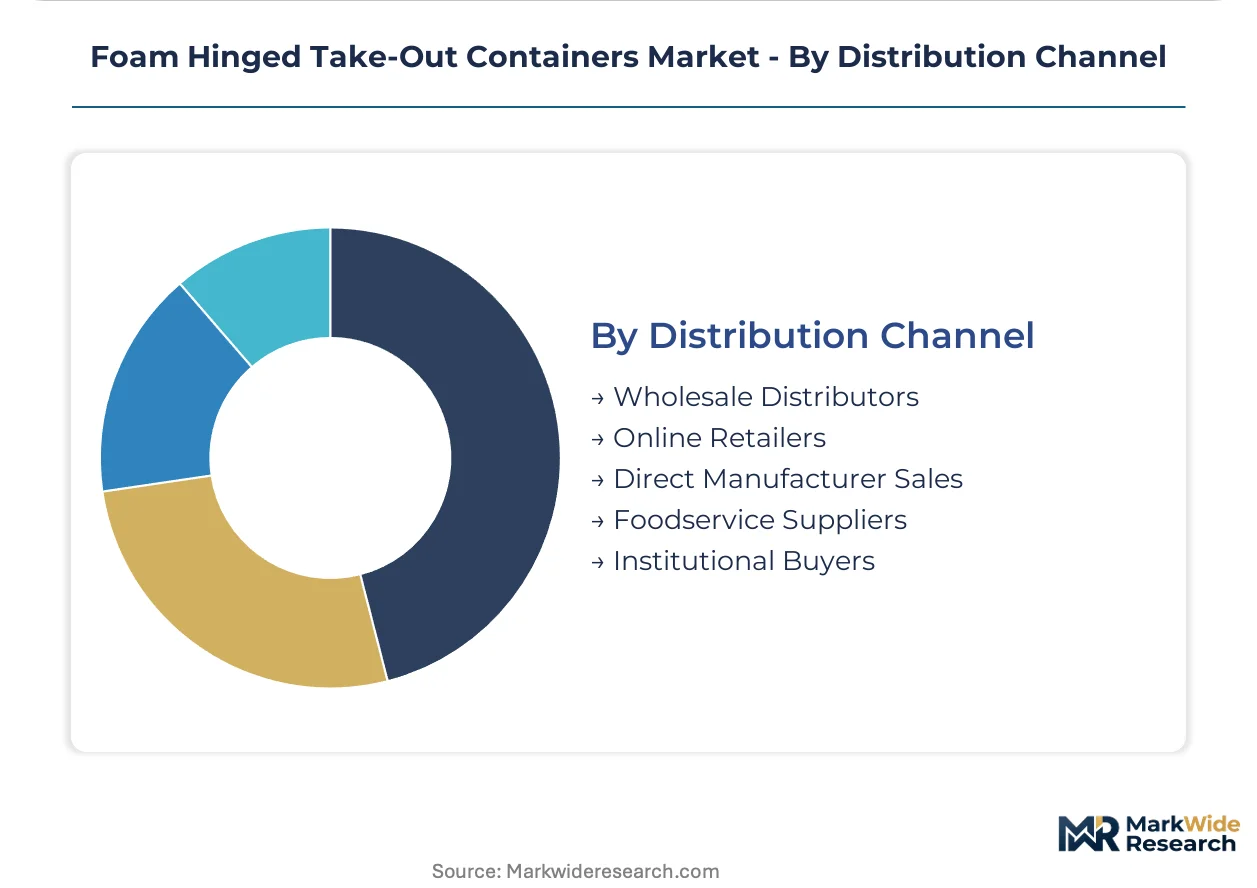
Distribution Channel:
Channel structure maps directly to customer scale: direct relationships bypass distributor margins for volume accounts, while fragmented endpoints rely on intermediary stocking.
- Wholesale Distributors:Regional distributors maintain dual inventory pools of polystyrene and biodegradable grades to serve customers across incompatible state mandates. Southeast distributors face hurricane-related supply interruptions from concentrated molded-foam production capacity, forcing safety stock investments.
- Direct Manufacturer Sales:Large foodservice management companies negotiate direct supply agreements that bypass traditional distribution tiers. Aramark, Compass Group, and Sodexo centralize packaging specifications across North American operations, consolidating formerly fragmented purchasing into single-source contracts with sustainability compliance requirements.
- Online Retailers:E-commerce platforms serve small operators with minimum-order-quantity flexibility.
- Foodservice Suppliers:Broadline distributors bundle containers with equipment and consumables.
- Institutional Buyers:Government and educational purchasing cooperatives leverage collective negotiation power.
Transaction volume flows predominantly through Wholesale Distributors; Direct Manufacturer Sales are climbing fastest as procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atlanta anchors North American molded-foam production capacity, with southeastern manufacturing clusters supplying quick-service restaurant chains across Texas, Florida, and Georgia. Regulatory fragmentation between state-level polystyrene bans and permissive jurisdictions forces distributors to maintain dual inventory pools.
United States
Quick-service restaurant delivery expansion in Dallas and Houston drives demand for medium-format hinged containers. The EPA and FDA govern food-contact safety standards, while California's statewide polystyrene ban fragments permissible specifications. Southeast production facilities in Georgia and Alabama concentrate molded-foam capacity, exposing supply chains to hurricane-related interruptions.
Germany
French and Italian foodservice operators source compliant packaging through German distribution hubs. The EU F-Gas Regulation phases out hydrocarbon blowing agents, forcing extrusion equipment retrofits. Industrial clusters in North Rhine-Westphalia process CO₂-based physical foaming systems for export to regulated European markets.
China
Organized quick-service chains in Shanghai and Shenzhen adopt standardized take-out packaging as delivery platforms scale. The country's national packaging regulator enforces evolving food-contact material standards. Manufacturing corridors in Guangdong Province supply biodegradable foam formulations for export to European and North American customers.
India
Cloud kitchen consolidation in Mumbai and Bangalore creates centralized procurement demand for insulated containers. The Food Safety and Standards Authority of India governs food-contact packaging compliance. Western Maharashtra industrial zones develop local molded-foam capacity to serve quick-service restaurant expansion.
France
Catering operators in Paris and Lyon convert procurement specifications to biodegradable grades fastest. The EU Single-Use Plastics Directive enforcement timeline accelerates operator conversion decisions. Packaging converters in the Île-de-France region absorb compliance costs early to secure multi-year supply agreements with institutional foodservice accounts.
Foam Hinged Take-Out Containers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material certification tiers, with biodegradable foam specialists commanding price premiums in regulated coastal markets. The vendor base organizes around three strategic archetypes: integrated resin-to-container producers with captive feedstock control, specialized biodegradable formulators with proprietary chemistry partnerships, and regional converters serving spot-market demand. Dominant competitive moves include backward integration into resin sourcing and geographic expansion to bypass distributor tiers.
Within the integrated producer tier, Dart Container Corporation and Pactiv Evergreen Inc. exemplify scale-driven positioning through North American manufacturing footprints. Genpak LLC occupies a position among specialized biodegradable formulators, while Huhtamaki Oyj anchors the European compliance-focused segment serving foodservice customers facing stringent packaging mandates.
| Leading Market Players |
|---|
| Dart Container Corporation |
| Genpak LLC |
| Pactiv Evergreen Inc. |
| Huhtamaki Oyj |
| Sabert Corporation |
| Placon Corporation |
| Anchor Packaging Inc. |
| Great Northern Corporation |
| Novolex Holdings LLC |
| Others |
Supply & Pricing Matrix
Material-grade bifurcation between legacy polystyrene and certified biodegradable foam creates divergent margin pools that reshape procurement economics across incompatible regulatory zones. California's statewide polystyrene ban and the EU Single-Use Plastics Directive force distributors to maintain dual inventory pools, with compliant grades commanding 15-25% unit premiums while commodity lines face cost compression from benzene feedstock volatility.
Pricing Analysis
Throughput-based contract structures dominate as quick-service restaurant chains negotiate multi-year supply agreements tied to delivery volume guarantees. Price differentiation rests on certification tier—FDA food-contact approval for legacy grades versus EU-compliant biodegradable formulations—and geographic delivery cost to hurricane-exposed southeastern production clusters. Cost compression in polystyrene lines is intensifying because crude-linked resin volatility squeezes commodity margins, while cloud kitchen operators show lowest price sensitivity as they prioritize thermal performance consistency over per-unit packaging spend.
Supply Chain Analysis
Dual-sourcing requirements from consolidated foodservice management companies mandate qualified backup suppliers across incompatible material grades, fragmenting procurement specifications. Manufacturing concentrates in the United States, Germany, and China, with Guangdong Province supplying biodegradable formulations for export markets. Raw material dependencies include benzene feedstock for polystyrene, PLA-starch resin blends, and mineral-filled polypropylene compounds. Single-source vulnerability runs through southeastern US molded-foam capacity exposed to hurricane-related interruptions. Distribution runs through wholesale distributors maintaining dual inventory pools, though direct manufacturer sales are climbing as Aramark, Compass Group, and Sodexo centralize procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The foam hinged take-out container market functions as a cost-of-compliance story where the EU Single-Use Plastics Directive and California's statewide polystyrene ban erect barrier-to-entry moats for players with certified biodegradable production lines and multi-jurisdiction regulatory expertise.
For Market Incumbents: Extend certification coverage across the EU F-Gas Regulation and California AB 1200 mandates to preempt competitor entry, while consolidating southeastern US manufacturing capacity to mitigate hurricane-related supply interruption risks. Backward integration into captive PLA-starch resin sourcing secures margin control as feedstock volatility threatens commodity-grade profitability. For New Entrants and Emerging Players: Cloud kitchen operators in Dallas and Houston represent the most penetrable buyer segment given their centralized procurement structure and sustainability scorecard requirements. Target biodegradable foam formulations for quick-service restaurant delivery expansion in India, where organized chains in Mumbai and Bangalore are adopting standardized take-out packaging as delivery platforms scale. Pursue direct supply agreements that bypass traditional wholesale distribution tiers. For Investors and Strategic Acquirers: Re-rating potential sits with specialized biodegradable formulators given EU Single-Use Plastics Directive enforcement timelines accelerating operator conversion decisions. The five-to-ten-year viability window favors acquisition targets with proprietary mycelium-based chemistry partnerships and existing FDA food-contact approvals. Watch for biodegradable foam cost curves intersecting with legacy polystyrene economics as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Formulation Scale-Up | PLA-starch blend capacity expansion secures multi-year supply agreements with French and German foodservice operators facing directive deadlines. |
| Backward Integration into Resin Sourcing | Captive feedstock control insulates margin structures from benzene price volatility linked to crude oil markets. |
| CO₂-Based Physical Foaming Retrofit | Extrusion equipment conversion satisfies EU F-Gas Regulation mandates while positioning for premium pricing in regulated European markets. |
| Direct Manufacturer Sales Expansion | Bypassing wholesale distribution tiers captures margin from consolidated procurement by Aramark, Compass Group, and Sodexo. |
| Cloud Kitchen Supply Agreement | Centralized procurement through shared commercial kitchen facilities enables volume commitments without distributor intermediation. |
Research Methodology
Multi-period observation of regulatory enforcement timelines, resin cost curves, and quick-service restaurant delivery expansion anchored the trend analysis, supplemented by interviews with plant managers at molded-foam converters, procurement leads at foodservice management companies, distribution channel partners, and technical R&D directors specializing in biodegradable formulations. Secondary validation drew from FDA food-contact filings, EU F-Gas Regulation implementation reports, SEC 10-K disclosures from packaging converters, and customs/trade data on polystyrene and PLA-starch resin flows. Bottom-up volume modeling triangulated against top-down market sizing across material grades and end-use segments.
Segment-weighting approaches distributed value and volume across material type, packaging capacity, end user category, and distribution channel dimensions throughout the forecast period. CAGRs derived from regression analysis against foodservice delivery platform growth, regulatory compliance cost trajectories, and substitution elasticity between polystyrene and biodegradable alternatives. Industry-specific forecast inputs included cloud kitchen facility openings and EU Single-Use Plastics Directive enforcement phase-in schedules.
Caveats apply where accelerated biodegradable foam cost reduction or delayed regulatory enforcement could materially shift the outlook. Forecasts reflect assumptions regarding resin price stability, hurricane frequency affecting southeastern US production, and foodservice operator willingness to absorb unit cost premiums for compliance certainty. Deviation in EU F-Gas Regulation implementation timing or California AB 1200 PFAS-free mandate expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Wet Wipes Canister Market
Containers
Rotomolded Containers Market
Containers
Grab and Go Containers Market
Containers
Straight Sided Glass Jar Market
Containers
Vials Market
Containers
Collapsible Food Packaging Containers Market
Containers
Lift-Off Lid Box Market
Containers
Hinged Deli Containers Market
Containers
Tottle Containers Market
Containers
2 Piece Cans Market
Containers
Container Market
Containers
Shipping Container Liners Market
Containers
Disposable Cups and Lids Market
Containers
PET Containers Market
Containers
Wooden Barrels Market
Containers
Corrugated Open-Head Drums Market