
 Feeder Containers Market | 2026-2036
Feeder Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Feeder Containers Market Foresight
ISO 668 certification for freight container construction specifications is bifurcating the competitive landscape between qualified operators and marginal entrants. Samskip Netherlands B.V. leverages its integrated North Sea barge-rail network to sustain frequency advantages in the Benelux corridor. X-Press Feeders Singapore Pte. Ltd. dominates intra-Asia strings with high vessel utilization on secondary port rotations. Unifeeder Group A/S anchors its position through terminal equity stakes at Scandinavian hub ports.
Feeder containers are standardized intermodal cargo units designed for short-sea and inland waterway transport, typically constructed from corten steel with corner castings engineered to ISO 1161 dimensions for crane and spreader compatibility; their primary function is to aggregate containerized cargo from secondary ports for relay to deep-sea mother vessels. The 40 ft size category leads volume due to optimal stowage efficiency on feeder vessels under 2,500 TEU capacity. Metal construction sustains pricing premiums against plastic alternatives in chemical and pharmaceutical end uses where UN portable tank compliance is mandatory. Flat rack configurations represent the fastest-growing container type for project cargo and out-of-gauge machinery moving through the Agriculture and Chemicals end-user segments.
The International Maritime Organization's SOLAS verified gross mass requirement and the EU Green Deal's emissions monitoring protocols are reshaping fleet renewal decisions across European operators. EPA marine diesel engine Tier 4 standards in the United States and China's MEE domestic emission control area rules are forcing engine retrofit investments or vessel replacement cycles. Stakeholders must monitor how the EU AI Act's automated port scheduling provisions alter slot allocation economics for feeder operators before committing to terminal service agreements.
Market Dynamics
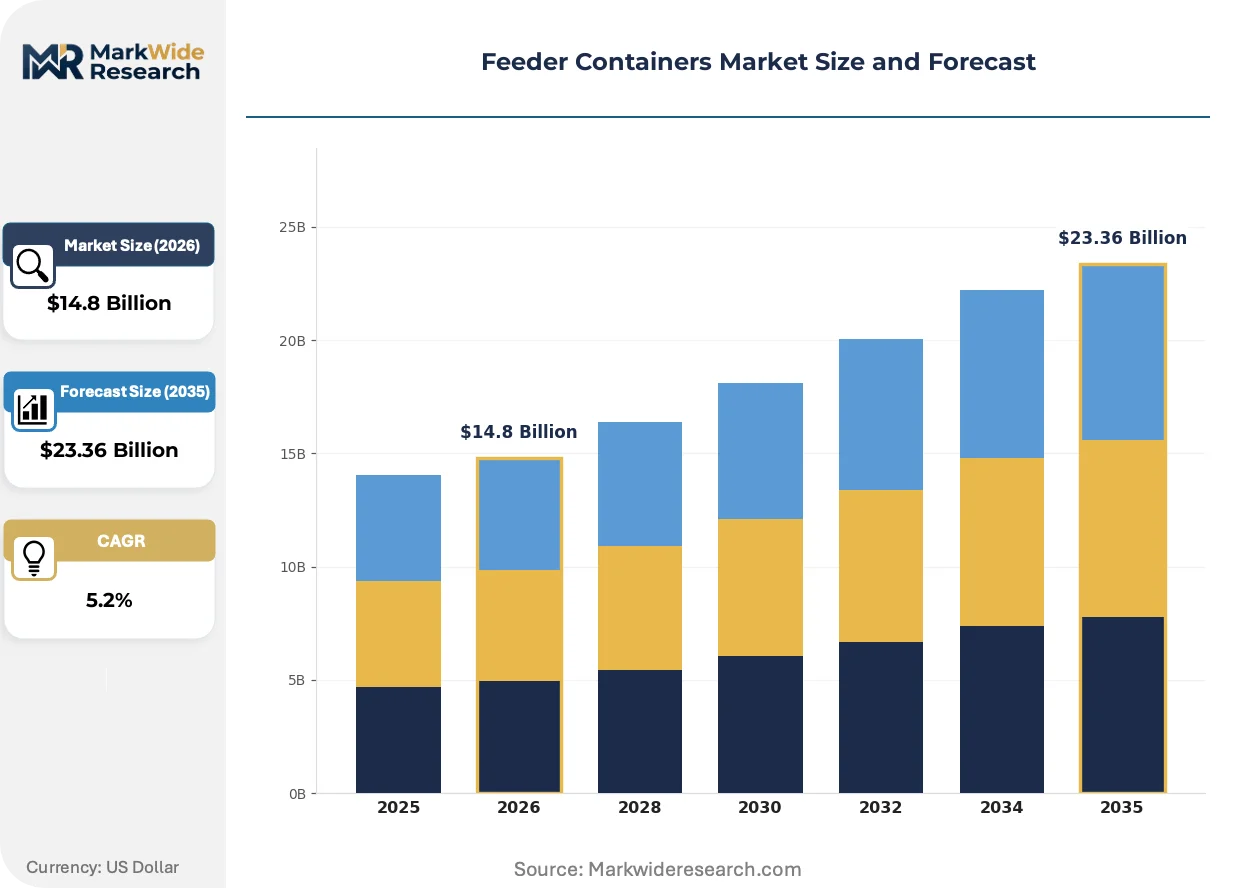
The Feeder Containers Market operates under acute pressure from the EU Green Deal's emissions monitoring protocols and the International Maritime Organization's SOLAS verified gross mass requirements, which are accelerating fleet renewal cycles and reshaping procurement specifications across European short-sea networks.
Growth Catalysts
- Rhine-Ruhr Port Cluster Expansion:Inland waterway connectivity improvements in Germany are aggregating chemical manufacturer demand for intermodal liquid transport solutions.
- EU F-Gas Regulation:Tightening material specifications for refrigerated container units are qualifying specialized corten steel suppliers for premium procurement tiers.
- ISO 668 Certification Bifurcation:Freight container construction standard enforcement is separating qualified operators from marginal entrants, consolidating volume among certified fleet managers.
Market Restraints
- Corten Steel Price Volatility:Raw material input swings for corner casting and wall panel fabrication compress margin predictability for container lessors.
- Engine Retrofit Capex Burden:EPA marine diesel engine Tier 4 standards and China's MEE domestic emission control area rules force vessel replacement or expensive powertrain overhauls.
- Plastic Alternative Substitution:Lower-weight polymer container designs threaten metal unit dominance in non-hazardous cargo segments where UN portable tank compliance is not mandated.
Strategic Opportunities
- Benelux Barge-Rail Integration:North Sea corridor operators can capture frequency advantages through synchronized terminal scheduling and inland waterway feeder connections.
- Flat Rack Project Cargo:Out-of-gauge machinery transport for agriculture and chemicals end-users represents underserved demand within standard container fleet configurations.
- EU AI Act Automated Scheduling:Port slot allocation algorithm provisions create first-mover advantage for feeder operators securing terminal service agreements before competitive saturation.
Industry Challenges
- ISO 1161 Corner Casting Welding Certification:Specialized crane and spreader compatibility testing extends production timelines for new container manufacturing.
- Legacy Fleet Integration Complexity:Retrofitting existing feeder vessels under 2,500 TEU capacity with emissions monitoring hardware conflicts with original stowage engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feeder Containers Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.36 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Open Top, Closed Top, Flat Rack, Tank Material: Plastic, Metal, Wood, Composite Size: 20 ft, 40 ft, 45 ft, Custom End User: Agriculture, Chemicals, Food & Beverage, Pharmaceuticals |
| Companies Covered | Samskip Netherlands B.V., SeaLead Shipping S.A., Unifeeder Group A/S, M2 Lines Pvt. Ltd., Interasia Lines S.A., X-Press Feeders Singapore Pte. Ltd., Feedertech Shipping Ltd., Newport Shipping Limited, Containerships GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feeder Containers Market Shifts & Advancements
Feeder container engineering is pivoting toward weight reduction and sensor integration as operators balance payload maximization against regulatory compliance burdens. Material science advances and digital tracking convergence are redefining fleet management economics.
Composite-reinforced corner casting assemblies are miniaturizing structural load distribution while maintaining ISO 1161 dimensional compliance. Chemical manufacturers deploying these units for intermodal liquid transport report improved crane handling efficiency at secondary port rotations. The technology is miniaturizing the trade-off between container wall thickness and internal cubic capacity.
China's MEE domestic emission control area rules are forcing engine retrofit investments across Asia-Pacific feeder fleets. Vessel operators face compressed replacement cycles or expensive Tier 4 powertrain upgrades to maintain port access rights. Intra-Asia string operators with secondary port rotations absorb the steepest compliance cost concentration.
Terminal equity stakes are displacing pure slot charter arrangements as the dominant competitive mechanism in Scandinavian hub ports. Unifeeder-type integrated operators secure preferential berthing windows that pure vessel providers cannot match. This consolidation pattern concentrates procurement leverage among vertically aligned fleet managers.
Feeder Containers Market Segmentation
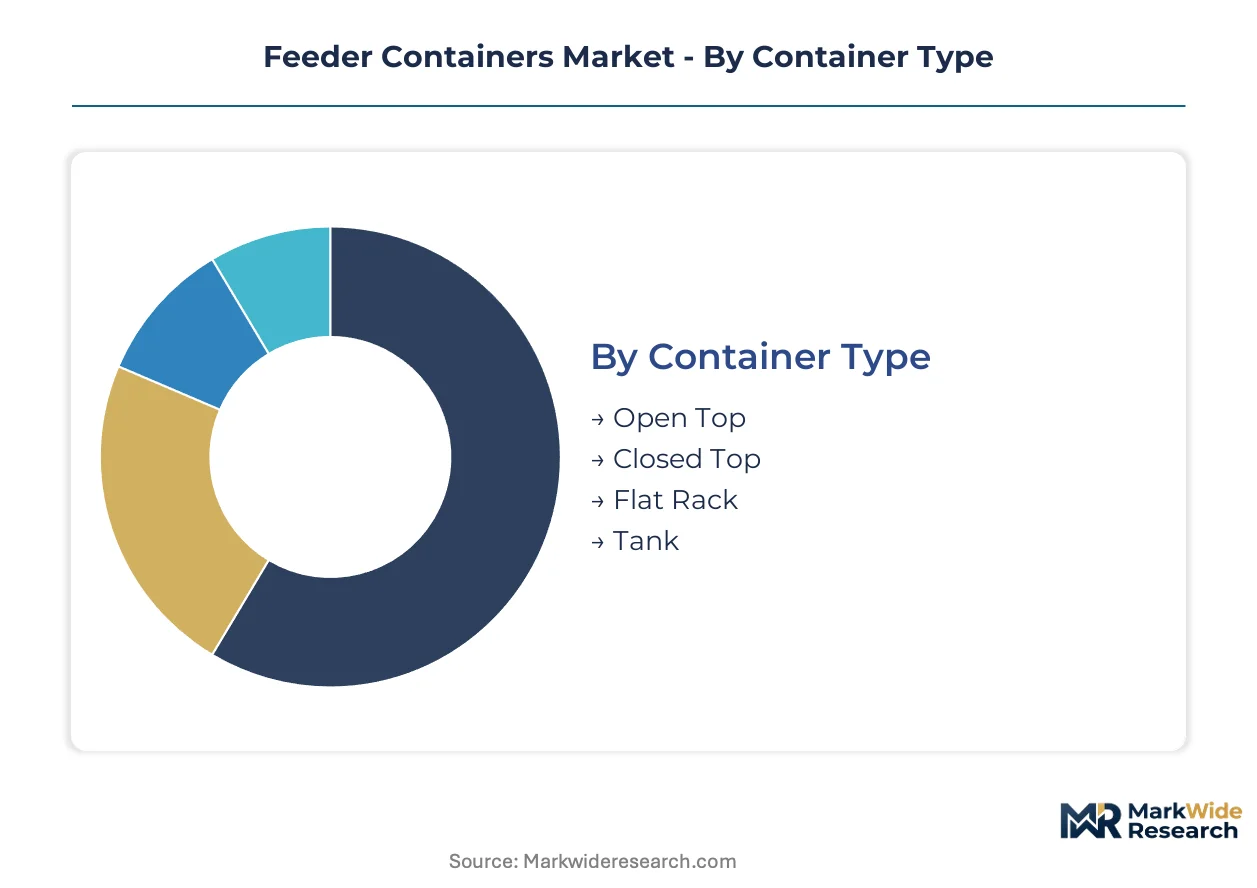
Feeder container procurement decisions bifurcate sharply between hazardous cargo requiring UN-certified metal construction and general freight where polymer alternatives compress unit economics. Container lessors must align fleet composition with the divergent compliance burdens and handling specifications across chemical, pharmaceutical, and agricultural supply chains.
Container Type:
Flat rack and tank configurations face acute substitution pressure from specialized breakbulk handling equipment in project cargo segments, while standard box containers defend their position through intermodal transfer efficiency.
- Open Top:Roofless steel construction enables crane loading of bulk commodities and heavy machinery without door width constraints. Rhine-Ruhr chemical manufacturers deploy these units for resin and pellet transport where top-loading efficiency outweighs weather exposure risks.
- Closed Top:Standard dry freight boxes with corrugated corten steel walls and locking bar door mechanisms dominate general cargo throughput. Benelux barge operators prioritize these units for their stackability and compatibility with automated terminal handling systems.
- Flat Rack:Collapsible end-wall platforms accommodate out-of-gauge machinery and construction equipment exceeding standard container dimensions. Agricultural equipment exporters in Germany's inland waterway network are expanding procurement of these units as project cargo volumes concentrate on Rhine corridor routes.
- Tank:Cylindrical pressure vessels mounted within ISO frames transport liquids, gases, and powders under UN portable tank regulations. Chemical manufacturers mandate these units for intermodal liquid transport where F-Gas Regulation compliance requires specialized valve and gasket specifications.
Closed top containers anchor the volume base while flat rack configurations gain share at the steepest rate.
Material:
Cost tier stratification separates premium corten steel certified for hazardous cargo from economy polymer units serving non-regulated freight streams.
- Plastic:High-density polyethylene and fiberglass-reinforced polymer shells reduce tare weight by 30-40% versus metal equivalents. Food & beverage distributors in Scandinavian short-sea networks favor these units for refrigerated cargo where thermal insulation properties offset structural durability trade-offs.
- Metal:Corten steel construction with weathering-grade corrosion resistance sustains structural integrity across saltwater and inland waterway exposure cycles. EU F-Gas Regulation mandates metal wall panels for refrigerated pharmaceutical transport, qualifying specialized steel suppliers for premium procurement tiers.
- Wood:Plywood-paneled containers serve niche agricultural applications where biodegradability and customs inspection accessibility outweigh durability requirements. These units face declining procurement as ISPM-15 phytosanitary treatment costs erode cost advantages.
- Composite:Fiber-reinforced polymer and aluminum honeycomb sandwiches deliver strength-to-weight ratios between metal and plastic alternatives. Terminal operators at Rotterdam and Antwerp are trialing these units for weight-sensitive barge connections where draft restrictions limit payload.
Metal construction commands the premium tier while plastic alternatives expand most quickly in non-hazardous cargo segments.
Size:
Volume concentration patterns reflect the stowage engineering constraints of feeder vessels under 2,500 TEU capacity and the crane reach limitations at secondary port rotations.
- 20 ft:Standard twenty-foot equivalent units optimize weight distribution for heavy cargo commodities and navigate draft-restricted inland waterways. German chemical manufacturers deploy these units for dense liquid transport where mass limits rather than cube constraints determine payload.
- 40 ft:Forty-foot high-cube and standard configurations maximize slot utilization on feeder vessels and dominate deep-sea relay aggregation. The ISO 668 certification requirement for corner casting specifications ensures crane compatibility across the Benelux and Scandinavian terminal networks.
- 45 ft:Extended length units accommodate European pallet dimensions and road trailer interoperability for combined transport operations. These containers face deployment constraints where rail loading gauges and barge hatch dimensions limit acceptance.
- Custom:Non-standard dimensions serve project cargo and specialized industrial equipment where ISO frame compatibility is sacrificed for cargo-specific optimization. Agricultural machinery manufacturers commission these units for combine harvester and tractor export from Rhine-Ruhr production clusters.
Forty-foot units anchor the volume base while custom dimensions gain share at the steepest rate in project cargo segments.
End User:
Customer type differentiation separates regulated pharmaceutical and chemical segments requiring UN certification from agricultural and food service freight with lighter compliance burdens.
- Agriculture:Grain, seed, and fertilizer transport demands ventilated and lined containers to prevent moisture damage and contamination. Flat rack configurations are expanding most quickly for agricultural machinery export through improved Rhine corridor barge connectivity.
- Chemicals:Hazardous and non-hazardous chemical transport mandates UN portable tank and IMDG code compliance for container construction and cleaning protocols. The EU F-Gas Regulation is tightening material specifications for refrigerated chemical transport, consolidating procurement among certified fleet operators.
- Food & Beverage:Temperature-controlled supply chains require reefer containers with integrated genset power or shore power connectivity. Scandinavian hub ports are prioritizing terminal service agreements with feeder operators guaranteeing reefer plug availability during vessel calls.
- Pharmaceuticals:Cold chain integrity and GDP compliance drive demand for validated thermal packaging and real-time temperature monitoring. MDR regulatory frameworks in Europe are extending container qualification requirements to secondary packaging and distribution equipment.
Chemical transport anchors the volume base while agricultural machinery logistics gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical manufacturers and agricultural exporters dominate procurement decisions across the feeder container network. Port clusters with inland waterway connectivity command premium slot allocations. Regulatory compliance costs vary sharply by jurisdiction.
Germany
Rhine-Ruhr chemical producers and Bavarian machinery exporters drive flat rack and tank container demand. EU F-Gas Regulation mandates metal wall specifications for refrigerated pharmaceutical transport. Duisburg's trimodal terminal anchors Europe's largest inland container handling volume.
Netherlands
Rotterdam-Antwerp barge operators prioritize 40 ft high-cube units for automated terminal efficiency. EU AI Act port scheduling provisions reward early-mover feeder operators securing service agreements. Samskip's integrated North Sea network exemplifies synchronized barge-rail frequency advantages.
Singapore
Intra-Asia string operators absorb steep MEE emission control area compliance costs on secondary port rotations. X-Press Feeders dominates high-utilization vessel deployment across Southeast Asian hub-and-spoke networks. The port authority's digital slot allocation system reshapes terminal access economics.
United States
Gulf Coast chemical exporters and Pacific Northwest agricultural shippers split procurement between tank and ventilated dry units. EPA Tier 4 marine diesel standards force engine retrofit investments or vessel replacement cycles. Houston's Bayport terminal expansion concentrates intermodal liquid transport infrastructure.
China
Yangtze River Delta manufacturers commission custom-dimension containers for industrial equipment export. MEE domestic emission control area rules compress feeder fleet replacement timelines. Shanghai's Yangshan deep-water port aggregates cargo for relay to secondary coastal rotations.
Feeder Containers Market Competitive Landscape
Player mix skews toward integrated logistics operators with terminal equity stakes and pure vessel providers competing on frequency. Consolidation pressure intensifies as ISO 668 certification requirements separate qualified fleet managers from marginal entrants. Strategic archetypes include barge-rail integrators, intra-Asia string specialists, and Scandinavian hub port anchor tenants. Dominant competitive moves encompass terminal equity acquisitions and emissions-compliant fleet renewal programs.
Among European integrated operators, Samskip Netherlands B.V. and Unifeeder Group A/S represent contrasting geographic anchoring strategies. Samskip exemplifies Benelux corridor dominance through synchronized inland waterway connections, while Unifeeder occupies a position anchored by Scandinavian hub port terminal stakes. X-Press Feeders Singapore Pte. Ltd. sits within the intra-Asia specialist tier, demonstrating scale-driven vessel utilization on secondary port rotations.
| Leading Market Players |
|---|
| Samskip Netherlands B.V. |
| SeaLead Shipping S.A. |
| Unifeeder Group A/S |
| M2 Lines Pvt. Ltd. |
| Interasia Lines S.A. |
| X-Press Feeders Singapore Pte. Ltd. |
| Feedertech Shipping Ltd. |
| Newport Shipping Limited |
| Containerships GmbH |
| Others |
Supply & Pricing Matrix
Forty-five to sixty-day production lead times for ISO 668-certified corten steel units concentrate pricing power with qualified manufacturers in Germany and China while marginal entrants absorb margin compression from raw material volatility.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange corten steel futures dominate procurement between container lessors and chemical manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates UN-certified tank containers from general freight boxes and plastic alternatives. Price differentiation hinges on ISO 1161 corner casting certification grade and after-sales maintenance bundling. Cost compression in the polymer segment is intensifying because food distributors prioritize thermal insulation over structural durability. Agricultural exporters exhibit highest price sensitivity; pharmaceutical cold chain operators show least.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows for Southeast Asian corten steel fabrication serving intra-Asia feeder networks. Manufacturing concentrates in China, South Korea, and Germany. Production draws from nickel-alloyed steel coil, corner casting forgings, and marine-grade paint systems. Single-source vulnerability in specialized welding equipment for ISO 1161 certification creates chokepoint exposure. Distribution runs through terminal-operating lessors with vessel fleet integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified ISO 668 certification capacity remains scarce relative to fleet renewal demand from EU Green Deal compliance, compressing returns for uncertified operators while concentrating margin capture among accredited manufacturers.
For Market Incumbents: Shield terminal equity positions at Rhine-Ruhr and Scandinavian hub ports against pure vessel competitors by securing EU AI Act automated scheduling agreements before competitive saturation. Deepen backward integration into corten steel coil supply through long-term offtake with German and Chinese mills. ISO 668 certification investment represents the priority defensive lever against marginal entrants. For New Entrants and Emerging Players: Accelerated ISO 1161 corner casting welding certification through European Notified Body partnerships unlocks procurement access to chemical manufacturer segments. Target flat rack configurations for agricultural machinery export through Rhine corridor barge connections. White-space concentration sits in custom-dimension project cargo serving Yangtze River Delta industrial equipment exporters. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified shipping conglomerates with under-optimized feeder container fleets lacking terminal equity stakes. Five-to-ten-year viability favors vertically integrated operators with barge-rail synchronization capabilities. Monitor EU F-Gas Regulation enforcement stringency as inflection indicator for refrigerated container demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Equity Acquisition | Preferential berthing windows at Rotterdam and Antwerp secure frequency advantages against pure vessel competitors. |
| ISO 668 Certification Investment | Regulatory separation between qualified operators and marginal entrants consolidates volume among accredited fleet managers. |
| Flat Rack Fleet Expansion | Agricultural machinery export growth through Rhine corridor routes captures underserved project cargo demand. |
| Composite Corner Casting Adoption | Fiber-reinforced assemblies reduce tare weight while maintaining ISO 1161 crane compatibility at secondary ports. |
| Benelux Barge-Rail Integration | Synchronized inland waterway connections capture chemical manufacturer procurement for intermodal liquid transport. |
Research Methodology
Initial hypotheses were tested against primary input from container fleet managers, terminal operators, chemical procurement directors, and maritime regulatory specialists and refined through secondary validation against customs trade data, ISO certification registries, SEC filings from listed shipping conglomerates, and EU MRV emissions monitoring records. Bottom-up vessel deployment counts triangulated against top-down trade lane volume estimates.
Variance decomposition across container type, material grade, size category, and end-user industry segments anchored the analytical framework over the projection horizon. CAGRs derived from regression-adjusted trend extrapolation incorporating fleet renewal cycle timing and regulatory compliance cost absorption rates. Specific inputs included Rhine-Ruhr port cluster throughput statistics and MEE emission control area enforcement timelines.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal implementation and stable corten steel input costs; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
PVC Container Market
Containers
North America Insulated Shipping Containers Market
Containers
ISO Ocean Containers Market
Containers
Bulk Containers Market
Containers
Lever Lid Cans Market
Containers
Bulk Container Packaging Market
Containers
Food Grade Stainless Steel Container Market
Containers
Europe Plastic Bottles and Containers Market
Containers
Vials Market
Containers
Light Resistant Containers Market
Containers
Half Height Containers Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Gable Top Container Market
Containers
Screw Top Lids Market
Containers
Wet Wipes Canister Market
Containers
Kuwait Container Glass Market