
 Global Container Monitoring Market | 2026-2036
Global Container Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Container Monitoring Market Foresight
Lightweight composite sensor housings is recalibrating hardware economics for container monitoring devices, cutting unit weight and extending battery life in remote deployments. Datadog, Inc. leverages cloud-native observability architectures to anchor enterprise container monitoring spend. Sysdig, Inc. specializes in runtime security for Kubernetes workloads, competing against broader IT monitoring platforms.
Container monitoring encompasses the continuous measurement, logging, and analysis of physical container conditions—location, temperature, humidity, shock, and door status—through embedded IoT sensors transmitting via cellular, satellite, or mesh networks to centralized dashboards. These systems prevent cargo spoilage, detect tampering, and optimize multimodal handoffs across supply chains. IoT Sensors dominates hardware value pools due to silicon integration and calibration complexity, while Cold Chain Monitoring represents the fastest-expanding application segment as biopharmaceutical logistics tighten. Cloud-Based deployment leads among mid-market logistics providers seeking scalable telemetry without capital expenditure.
FCC certification requirements govern radio transmission modules in US-bound container hardware, while REACH compliance in Europe restricts hazardous substances in sensor manufacturing. The EU AI Act introduces algorithmic transparency obligations for predictive maintenance software used in fleet management platforms. Stakeholders must weigh regulatory certification timelines against product refresh cycles when selecting sensor suppliers.
Market Dynamics
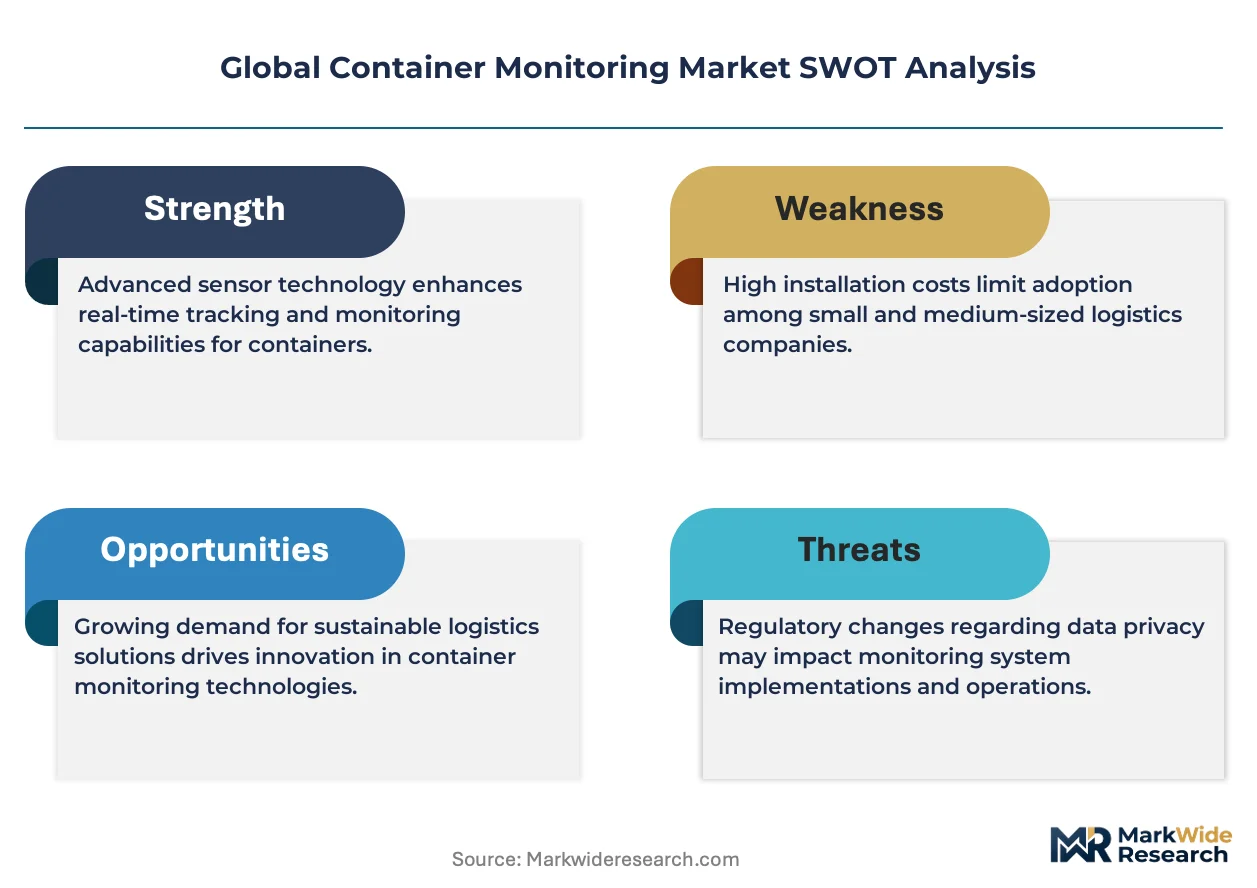
Lightweight composite sensor housings are compressing hardware costs while extending battery life, enabling mass deployment across remote maritime routes where cellular coverage remains intermittent.
Growth Catalysts
- EU Digital Product Passport:Mandates embedded traceability sensors for all goods entering European markets by 2030, forcing container hardware retrofits across pharmaceutical and electronics supply chains.
- Biopharmaceutical cold chain:Temperature-sensitive biologics now constitute the majority of high-value ocean freight, requiring continuous environmental monitoring from manufacturing to patient delivery.
- German port automation clusters:Hamburg and Bremerhaven deploy real-time container tracking at berth-to-yard handoffs, establishing operational templates adopted by Rotterdam and Singapore terminals.
Market Restraints
- Lithium battery supply concentration:Cell production for IoT sensors concentrates in Chinese manufacturing zones, exposing hardware vendors to export control volatility and input cost spikes.
- Satellite connectivity tariffs:Iridium and Orbcomm pricing structures impose recurring costs that deter adoption among small freight forwarders operating thin-margin routes.
- FCC certification timelines:Radio module approvals for US-bound hardware average fourteen months, delaying product launches and compressing effective sales windows.
Strategic Opportunities
- India pharmaceutical exports:CDSCO cold chain mandates for vaccine shipments create first-mover advantage for sensor vendors establishing local calibration facilities.
- AI-driven predictive maintenance:Convergence of edge computing and vibration analysis enables failure prediction for reefer compressor units before cargo spoilage occurs.
- Direct-to-shipper SaaS models:Bypassing traditional 3PL intermediaries, hardware vendors now offer subscription telemetry directly to beneficial cargo owners.
Industry Challenges
- Embedded systems firmware talent:Shortage of engineers skilled in ultra-low-power programming for maritime IoT devices delays product roadmaps.
- REACH substance compliance:ECHA restrictions on sensor housing materials force reformulation cycles that conflict with eighteen-month hardware refresh timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Container Monitoring Market |
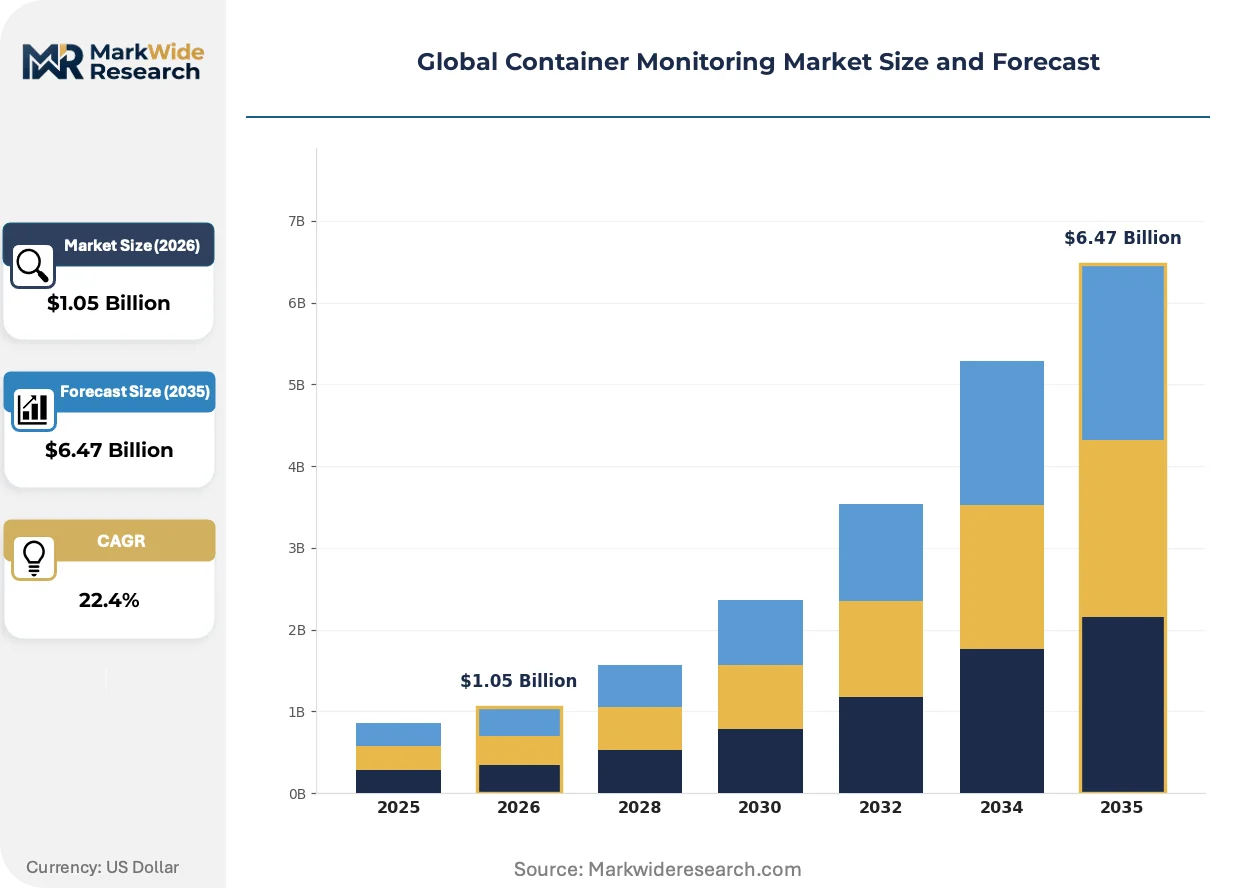
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $6.47 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, GPS Tracking, IoT Sensors, Wireless Sensor Networks, Bluetooth Low Energy, NFC Application: Cold Chain Monitoring, Asset Tracking, Security & Theft Prevention, Supply Chain Optimization, Environmental Monitoring, Fleet Management End User: Logistics Providers, Freight Forwarders, Port Operators, Customs Authorities, Retail Warehouses, Distribution Centers Deployment Type: Cloud-Based, On-Premises, Hybrid Solutions, SaaS Platforms |
| Companies Covered | New Relic, Inc., SolarWinds Worldwide, LLC, Datadog, Inc., AppDynamics LLC, Broadcom Inc., Dynatrace, LLC, Sysdig, Inc., Grafana Labs, Inc., Splunk Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Container Monitoring Market Shifts & Advancements
Sensor miniaturization and edge intelligence are collapsing the cost-performance frontier for container monitoring, enabling tiered deployment strategies that match hardware sophistication to cargo value density.
Mesh networking protocols operating on sub-GHz spectrum bands are rewriting connectivity economics for multi-container convoys. Mining and agricultural shippers in Australian bulk corridors deploy these self-healing networks across train-mounted container sets, eliminating per-unit satellite subscription fees while maintaining location granularity.
REACH compliance deadlines in Europe are accelerating material substitution in sensor manufacturing. German industrial sensor producers now qualify halogen-free PCB substrates and bio-based potting compounds, passing certification costs to premium product tiers while standard lines face margin compression.
Beneficial cargo owners increasingly contract telemetry separately from freight services, unbundling visibility from transportation. Pharmaceutical manufacturers in Switzerland and Massachusetts now mandate that carriers accept customer-owned sensor hardware, shifting data ownership and creating interoperability demands that challenge proprietary 3PL platforms.
Global Container Monitoring Market Segmentation
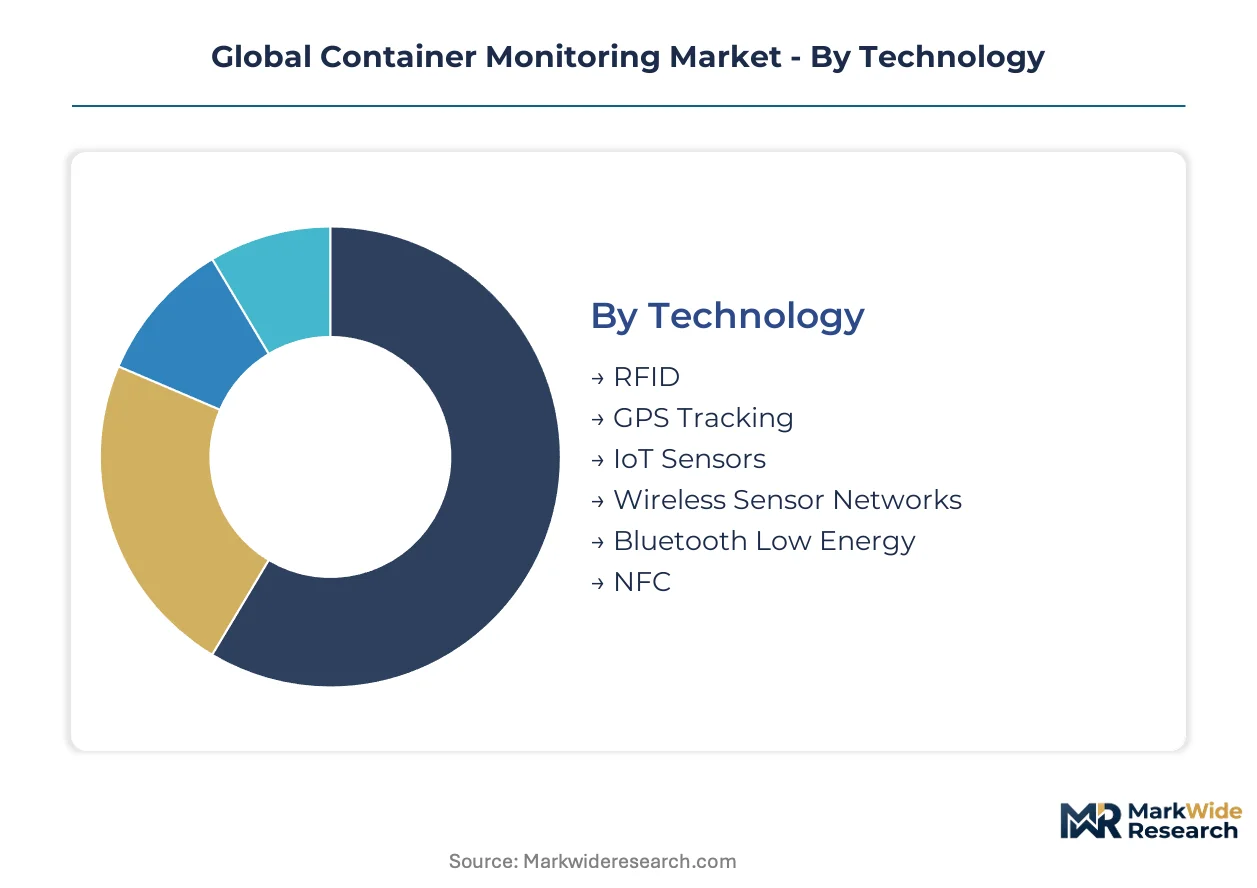
Container monitoring vendors configure hardware portfolios around cargo value density and connectivity constraints. Upgrade cycles vary dramatically across technology tiers, with sensor hardware refreshing every 18-24 months while cloud platforms iterate quarterly.
Technology:
Hardware refresh timelines differentiate technology tiers, with premium silicon commanding 3-year replacement cycles versus 5-7 years for legacy radio modules.
- IoT Sensors:Multi-parameter devices integrate temperature, humidity, shock, and door-status detection in single silicon packages. German pharmaceutical shippers and Indian vaccine exporters drive specification demands for calibration accuracy under CDSCO and EMA guidelines.
- GPS Tracking:Dual-band receivers with GLONASS and Galileo augmentation deliver meter-level precision in port yards. Demand clusters in Hamburg and Singapore automation projects where berth-to-yard handoffs require sub-minute location granularity.
- RFID:Passive UHF tags enable gate-throughput scanning without battery maintenance.
- Wireless Sensor Networks:Self-healing mesh topologies eliminate per-unit satellite fees in Australian bulk corridors.
- Bluetooth Low Energy:Short-range protocols support last-mile yard operations with smartphone-based interrogation.
- NFC:Proximity authentication secures high-value electronics against tampering at distribution checkpoints.
IoT Sensors sits at the top of the volume ranking, with GPS Tracking climbing the fastest.
Application:
Margin structures diverge sharply across use cases, with compliance-driven cold chain commanding premium pricing over commodity asset tracking.
- Cold Chain Monitoring:Continuous temperature logging with automated excursion alerting prevents biologics spoilage across ocean freight legs. Swiss and Massachusetts pharmaceutical manufacturers now mandate shipper-owned sensor hardware, bypassing traditional 3PL visibility platforms.
- Security & Theft Prevention:Door-breach detection and geofencing algorithms trigger law enforcement coordination in high-risk corridors. South African platinum and copper concentrate shippers anchor demand following port pilferage incidents.
- Asset Tracking:Location breadcrumbing supports inventory reconciliation across multimodal handoffs.
- Supply Chain Optimization:Dwell-time analytics identify bottlenecks at Rotterdam and Bremerhaven terminal interfaces.
- Environmental Monitoring:Vibration and shock logging protects precision electronics from handling damage.
- Fleet Management:Aggregated telemetry informs reefer compressor maintenance scheduling before cargo compromise.
Cold Chain Monitoring captures the highest margin tier, while Fleet Management is expanding most quickly through predictive maintenance adoption.
End User:
Customer concentration patterns reflect procurement sophistication, with beneficial cargo owners unbundling telemetry from freight contracts.
- Logistics Providers:Third-party operators deploy white-label platforms across heterogeneous shipper bases. DHL and Kuehne+Nagel standardize on API-first architectures that accommodate customer-owned sensor hardware.
- Freight Forwarders:Intermediary margins constrain hardware selection to mid-tier cellular devices. Southeast Asian NVOCCs prioritize dual-SIM modules for carrier redundancy across thin-margin routes.
- Port Operators:Terminal automation projects in Hamburg and Bremerhaven establish real-time tracking templates adopted by Rotterdam and Singapore.
- Customs Authorities:Revenue protection applications leverage tamper-evident seals with blockchain-anchored chain of custody.
- Retail Warehouses:Inbound visibility supports just-in-time replenishment for seasonal demand spikes.
- Distribution Centers:Cross-dock operations use short-range location for yard management optimization.
Logistics Providers dominates procurement volume, with Freight Forwarders gaining share fastest through SaaS telemetry unbundling.
Deployment Type:
Capital intensity thresholds separate deployment models, with subscription economics displacing perpetual licenses in mid-market segments.
- Cloud-Based:Scalable telemetry ingestion without infrastructure capital attracts mid-market logistics providers. AWS and Azure IoT Hub integrations support million-device fleets with automatic failover across availability zones.
- SaaS Platforms:Direct-to-shipper subscriptions bypass 3PL intermediaries, transferring data ownership to beneficial cargo owners. Swiss pharmaceutical manufacturers and Massachusetts biotech firms mandate these arrangements.
- On-Premises:Air-gapped installations satisfy defense and classified cargo requirements.
- Hybrid Solutions:Edge processing with cloud aggregation balances latency against analytics depth.
Cloud-Based leads deployment volume, with SaaS Platforms showing the steepest expansion trajectory as shippers reclaim telemetry control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German port automation clusters anchor container monitoring hardware demand through Hamburg and Bremerhaven terminal digitization programs. FCC certification timelines in the United States compress effective sales windows for radio module vendors. CDSCO cold chain mandates in India reshape pharmaceutical export compliance requirements.
United States
Beneficial cargo owners in Massachusetts and California unbundle telemetry from freight contracts, mandating shipper-owned sensor hardware. FDA pharmaceutical distribution guidelines and FCC radio transmission certifications govern hardware deployment. Boston-area biotech firms drive cloud-based platform subscriptions for cold chain integrity.
Germany
EMA pharmaceutical logistics standards and the EU Digital Product Passport regulation force embedded traceability retrofits across supply chains. Hamburg and Bremerhaven port automation projects establish real-time tracking templates adopted by Rotterdam and Singapore terminals. REACH compliance deadlines accelerate halogen-free PCB substrate qualification.
India
CDSCO mandates continuous temperature monitoring for vaccine exports, creating calibration facility demand. The PLI scheme for electronics manufacturing supports domestic sensor assembly capacity. Maharashtra pharmaceutical exporters anchor first-mover opportunities for vendors establishing local service infrastructure.
Switzerland
Swissmedic pharmaceutical distribution rules and beneficial cargo owner telemetry mandates reshape carrier relationships. Swiss pharmaceutical manufacturers in Basel and Geneva now require customer-owned sensor hardware acceptance. Precision electronics shippers drive NFC-based tamper-evident seal specifications.
Australia
Mining and agricultural bulk shippers deploy mesh networking protocols across train-mounted container sets in Western Australian corridors. TGA pharmaceutical cold chain guidelines align with international biologics distribution standards. Self-healing sub-GHz networks eliminate per-unit satellite subscription fees for remote route coverage.
Global Container Monitoring Market Competitive Landscape
Global majors compete with regional champions across cloud-native observability and specialized runtime security dimensions. The vendor base stratifies between consolidated platform providers and point-solution specialists. Three archetypes dominate: horizontal IT monitoring platforms, cloud-native observability pure-plays, and container-centric security specialists. M&A activity concentrates on telemetry data aggregation capabilities, while strategic partnerships target hybrid cloud deployment architectures.
Within the cloud-native observability tier, Datadog, Inc. and Grafana Labs, Inc. exemplify platform-first positioning, while Sysdig, Inc. occupies a specialized runtime security position for Kubernetes workloads. These three entities represent divergent strategic bets on whether container monitoring converges with broader infrastructure observability or fragments into security-centric verticals.
| Leading Market Players |
|---|
| New Relic, Inc. |
| SolarWinds Worldwide, LLC |
| Datadog, Inc. |
| AppDynamics LLC |
| Broadcom Inc. |
| Dynatrace, LLC |
| Sysdig, Inc. |
| Grafana Labs, Inc. |
| Splunk Inc. |
| Others |
Supply & Pricing Matrix
Beneficial cargo owners in pharmaceutical and electronics verticals concentrate procurement leverage, driving subscription-based SaaS telemetry pricing that unbundles visibility from freight contracts and transfers data ownership upstream.
Pricing Analysis
Input-cost pass-through from lithium cell pricing and halogen-free PCB substrate qualification compresses margins at the hardware tier while cloud platform economics expand. Pricing stratifies across premium, standard, and economy tiers based on calibration accuracy under CDSCO and EMA guidelines and after-sales service bundling. Cost compression in standard-tier cellular modules is intensifying because Chinese battery export controls generate input volatility. Small freight forwarders operating thin-margin Southeast Asian routes exhibit highest price sensitivity, while Swiss pharmaceutical manufacturers accept premium positioning for shipper-owned hardware mandates.
Supply Chain Analysis
Freight cost exposure in maritime IoT logistics concentrates hardware assembly in Chinese manufacturing zones for radio modules and lithium cells, with German industrial sensor producers qualifying alternative substrates for REACH compliance. The supply chain draws from rare earth magnet feedstocks for GPS receivers, composite resin systems for lightweight housings, and silicon wafer supply for multi-parameter sensor integration. Single-source vulnerability in Chinese cell production exposes vendors to export control disruption. Distribution runs through direct-to-shipper SaaS channels that bypass traditional 3PL intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container monitoring offers margin expansion through lightweight composite sensor housings that cut unit costs and extend battery life, enabling tiered hardware deployment matched to cargo value density.
For Market Incumbents: Acquire telemetry data aggregation capabilities to consolidate fragmented shipper-owned sensor interoperability demands. Incorporate edge computing vibration analysis for predictive reefer maintenance before cargo spoilage occurs. Defend against emerging cloud-native observability platforms by anchoring enterprise spend through API-first architectures that accommodate customer-owned hardware. For New Entrants and Emerging Players: Capture India pharmaceutical export compliance opportunities by establishing local calibration facilities under CDSCO cold chain mandates for vaccine shipments. Target Australian mining and agricultural bulk corridors with sub-GHz mesh networking protocols that eliminate per-unit satellite fees. Lead with direct-to-shipper SaaS subscriptions that bypass 3PL intermediaries and transfer data ownership to beneficial cargo owners. For Investors and Strategic Acquirers: Cloud-native observability pure-plays are the most active acquirer in this space, seeking telemetry data aggregation capabilities to anchor hybrid cloud deployment architectures. Long-term viability centers on convergence between physical container monitoring and broader infrastructure observability platforms. Watch for beneficial cargo owner hardware mandate adoption rates in Swiss and Massachusetts pharmaceutical clusters as inflection indicator for SaaS platform expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Telemetry Data Aggregator | Consolidates shipper-owned sensor interoperability demands challenging proprietary 3PL platforms. |
| Platform Integration with Hyperscaler IoT Hub | AWS and Azure integrations support million-device fleets with automatic failover across availability zones. |
| Geographic Expansion into Indian Calibration Facilities | CDSCO vaccine export mandates create first-mover advantage for local service infrastructure. |
| Product Launch of Edge-Intelligent Sensor Hardware | Vibration analysis enables reefer compressor failure prediction before biologics spoilage occurs. |
| Strategic Partnership with Port Automation Consortium | Hamburg and Bremerhaven templates establish real-time tracking standards adopted by Rotterdam and Singapore. |
Research Methodology
Direct dialogue with IoT hardware engineering directors, pharmaceutical supply chain managers, freight forwarder procurement leads, and port automation project officers grounded qualitative findings in operational reality. Primary insights combined with secondary validation from FCC equipment authorization databases, ECHA REACH substance restriction updates, CDSCO cold chain guidance documents, and customs trade flow statistics. Bottom-up sensor shipment tallies and top-down logistics telemetry spend estimates underwent cross-triangulation to anchor volume assumptions.
Bottom-up modeling of hardware refresh cycles and cloud subscription attach rates across the projection horizon informed value projections. Segmentation dimensions span technology tier, application use case, deployment architecture, and regional regulatory cluster. CAGRs derived from fitted adoption curves incorporating EU Digital Product Passport compliance deadlines and biopharmaceutical cold chain expansion trajectories. Forecast inputs included lithium battery supply concentration indices and satellite connectivity tariff structures.
Export control volatility in Chinese cell manufacturing, REACH substance compliance deadline shifts, and beneficial cargo owner hardware mandate adoption rates are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding hardware refresh timelines and SaaS pricing elasticity. A model refresh is warranted upon material change in EU Digital Product Passport implementation schedules or CDSCO calibration facility accreditation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Belgium Container Glass Market
Containers
ISO Container Market
Containers
Flexible Water Tanks Market
Containers
Light Density Polyethylene (LDPE) Bottles Market
Containers
Stack and Nest Containers Market
Containers
Trays Market
Containers
Edible Oil Cans Market
Containers
HDPE Containers Market
Containers
Spout Containers Market
Containers
Single Wall Jars Market
Containers
Reconditioned IBC Market
Containers
Oblong Jar Market
Containers
Container Mouth Inner Seal Market
Containers
Modular Container Market
Containers
Sanitary Cans Market
Containers
Algeria Container Glass Market