
 Metal Crates Market | 2026-2036
Metal Crates Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Crates Market Foresight
Direct-to-manufacturer distribution is rewriting procurement patterns for industrial packaging buyers. Mauser Packaging Solutions leverages its circular-service model to sustain long-term lease contracts with automotive OEMs. Grief anchors North American supply through captive steel sourcing and regional mill partnerships. Crown Holdings competes on lightweight alloy formulations that reduce transport costs for beverage logistics providers.
Metal crates are rigid, reusable containers fabricated from aluminum, carbon steel, or stainless steel sheet stock, typically formed through press-brake bending, welding, and surface finishing to achieve load ratings between 500 kg and 2,000 kg for stackable deployment. Their primary purpose is to protect goods through repeated shipping cycles while eliminating single-use packaging waste in closed-loop supply chains. Foldable crates command premium positioning due to their return-trip density advantage, whereas heavy-duty carbon steel variants dominate margin pools in automotive and aerospace part transport where durability thresholds are non-negotiable. Stainless steel grades are gaining fastest in food and pharmaceutical logistics where washdown compatibility and corrosion resistance override upfront cost premiums.
The EPA Resource Conservation and Recovery Act shapes cradle-to-cradle accountability for packaging reuse in the United States, while the EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds that directly alter steel sourcing specifications for crate manufacturers. ISO 18613 testing protocols for returnable transport items determine market access for exporters serving multinational automotive and electronics assembly networks. Stakeholders must monitor how evolving extended producer responsibility frameworks in the European Union and emerging state-level packaging legislation in the United States will recalibrate total cost-of-ownership models for reusable metal container programs.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is tightening reuse targets across member states. Automotive manufacturers are expanding reusable metal crate programs for inbound parts logistics. Demand is concentrating in Germany's automotive supply corridor.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandated reuse targets are forcing automotive OEMs to replace single-use packaging with returnable metal containers in closed-loop supply chains.
- Aluminum alloy lightweighting:Beverage logistics providers are adopting foldable aluminum crates to reduce transport fuel costs and maximize return-trip payload density.
- Germany's automotive corridor:Tier-1 suppliers in Baden-Württemberg and Bavaria are standardizing on stainless steel crates for just-in-sequence delivery to assembly plants.
Market Restraints
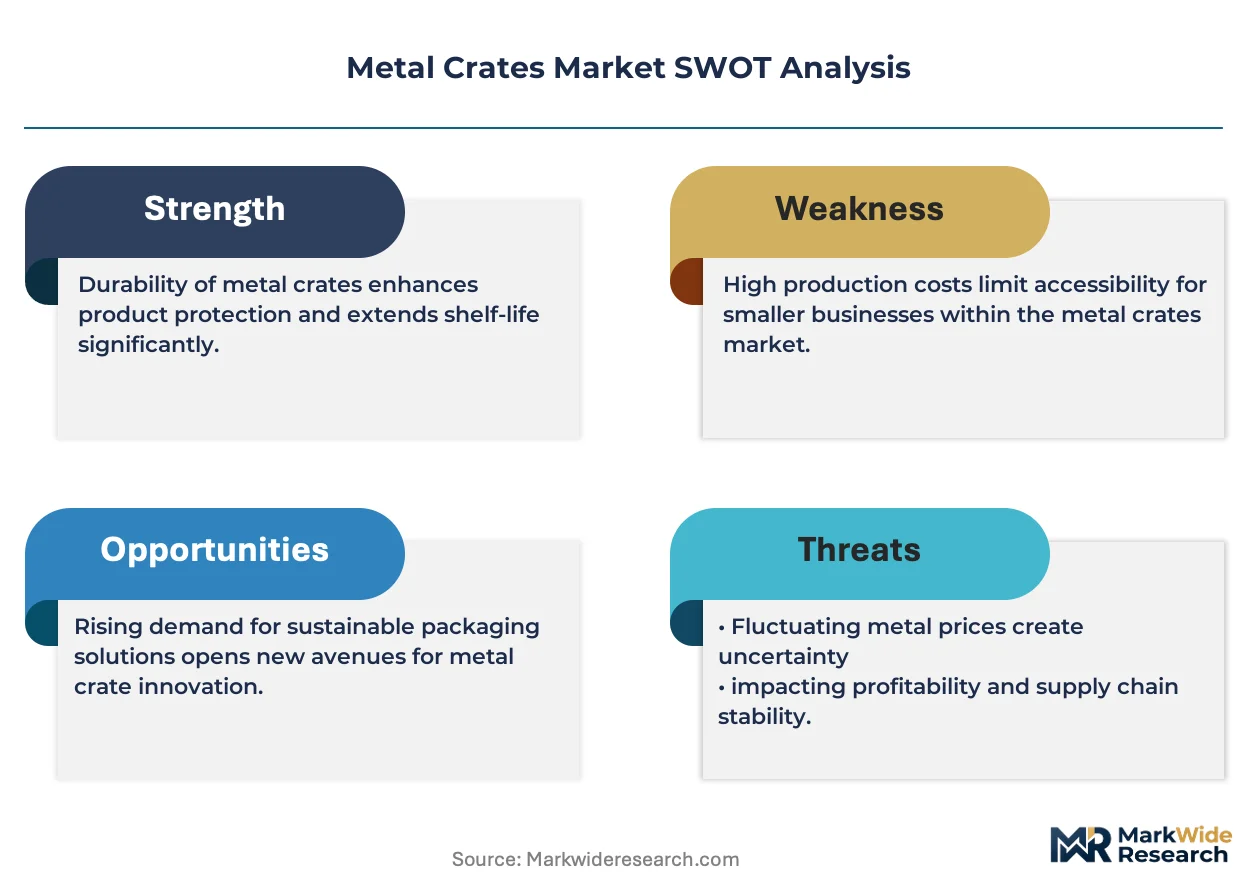
- Steel price volatility:Carbon steel sheet input costs fluctuate with scrap metal markets and energy-intensive electric arc furnace production economics.
- Chinese mill concentration:Global stainless steel coil supply clusters in Jiangsu and Shanxi provinces, creating geopolitical exposure for European crate fabricators.
- Plastic foldable crate substitution:Polypropylene alternatives achieve lower per-trip costs in short-loop distribution where load ratings below 500 kg suffice.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic manufacturing incentives are attracting crate leasing operators to establish regional pooling networks around Chennai and Pune.
- Pharmaceutical cold chain integration:Insulated stainless steel crates with embedded temperature logging are penetrating vaccine distribution networks requiring washdown sterilization.
- Outcome-based leasing models:Per-trip pricing contracts are replacing capital purchase agreements for fleet operators managing variable seasonal volumes.
Industry Challenges
- ISO 18613 certification timelines:Returnable transport item testing protocols delay market access for exporters serving multinational automotive assembly networks by six to eighteen months.
- Weld automation skill gaps:Press-brake programming and robotic seam welding expertise shortages constrain capacity expansion at mid-tier fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Crates Market |
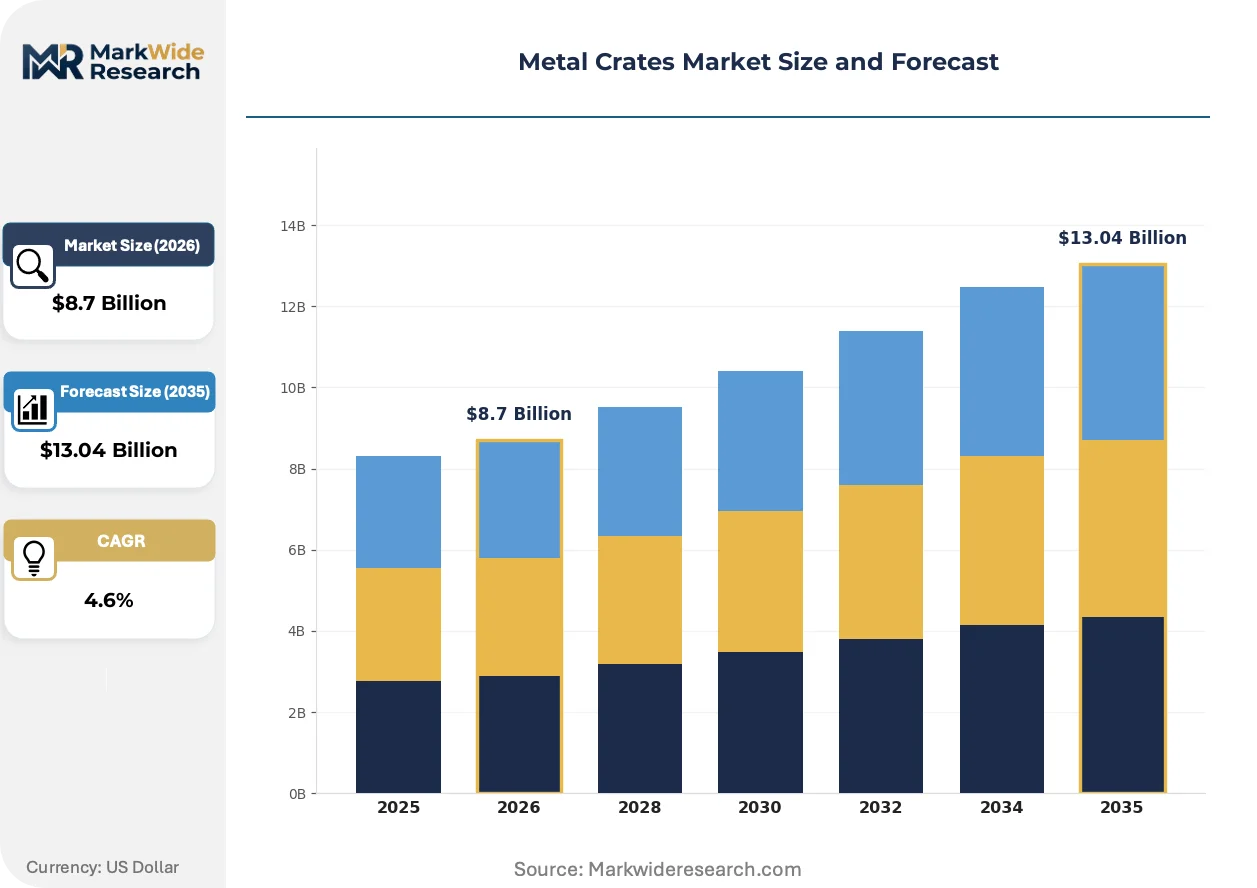
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stackable Crates, Foldable Crates, Regular Crates, Heavy-Duty Crates Material: Aluminum, Carbon Steel, Stainless Steel, Alloy Application: Retail Storage, Industrial Transport, Agricultural Use, Shipping End User: Manufacturers, Distributors, Retailers, Logistics Providers |
| Companies Covered | Mauser Packaging Solutions, Grief, Ball Corporation, Crown Holdings, Ardagh Group, Silgan Holdings, CAN-PACK Group, Trivium Packaging, DS Containers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Crates Market Shifts & Advancements
Digital tracking integration and alloy formulation advances are compressing total cost-of-ownership calculations for fleet operators. Washdown-compatible designs are penetrating food and pharmaceutical verticals previously served by disposable packaging.
Smart crate technology embedding RFID tags and IoT sensors is migrating from high-value aerospace component logistics to mainstream automotive applications. Tier-1 suppliers in Germany and Japan are piloting real-time location tracking to optimize pool management and reduce asset loss. This visibility infrastructure is enabling dynamic pricing models that charge by actual utilization rather than fleet size.
The EPA Resource Conservation and Recovery Act is reshaping cradle-to-cradle accountability for packaging reuse in the United States. Manufacturers must now document recovery rates and recycled content percentages in steel sourcing specifications. Automotive assembly plants in Michigan and Ohio are responding by mandating certified recycled steel grades in supplier crate procurement contracts.
Leasing contracts are displacing outright purchase agreements among mid-sized manufacturers managing demand volatility. Third-party pooling operators in France and Italy now maintain regional crate fleets that manufacturers access through per-trip subscriptions. This asset-light approach is most visible in seasonal agricultural machinery supply chains where peak shipping windows concentrate demand.
Metal Crates Market Segmentation
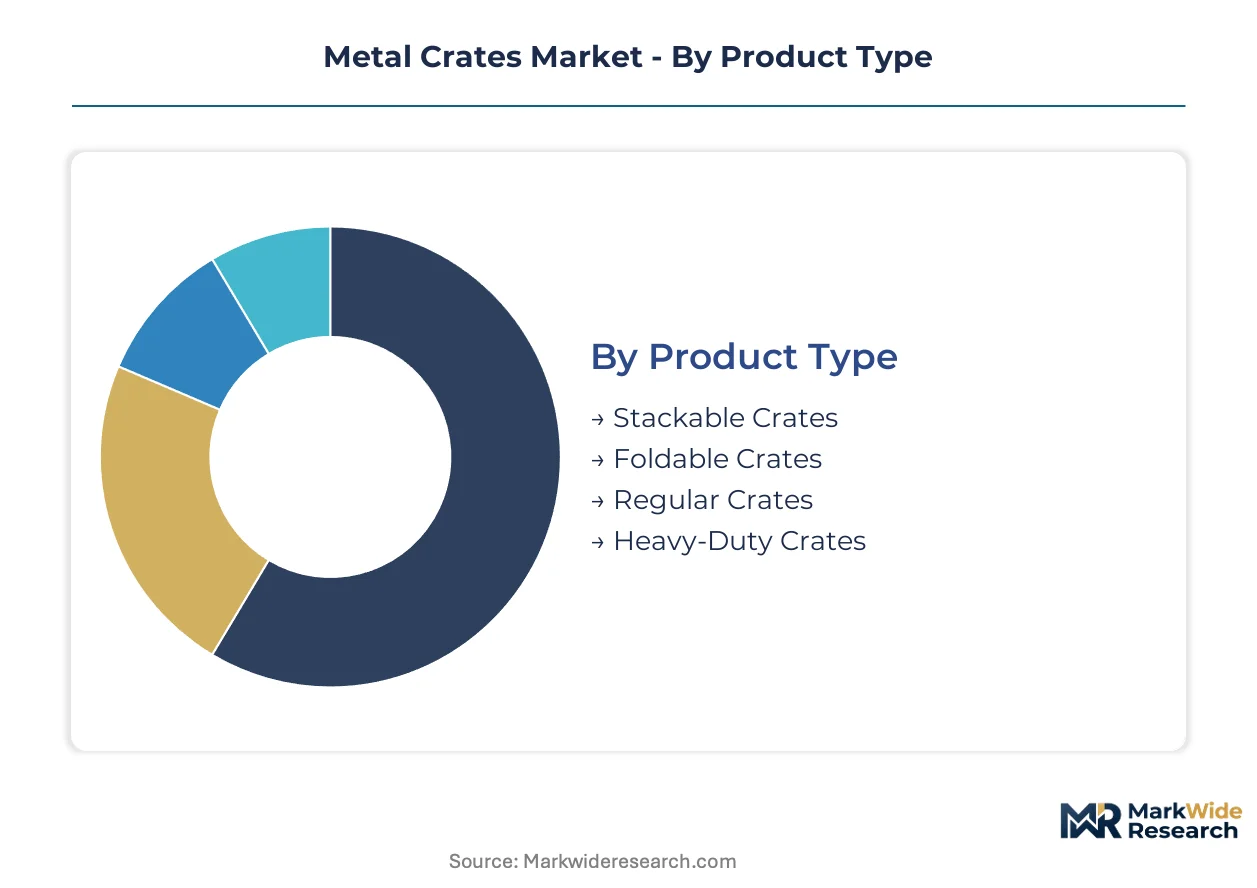
Segmentation in metal crates reveals how load specifications, corrosion resistance, and return-trip economics drive purchasing decisions across automotive, food, and pharmaceutical supply chains. Each dimension captures distinct technical trade-offs between upfront capital, lifecycle durability, and regulatory compliance.
Product Type:
Product variety spans the use-case spectrum from high-frequency rotation in closed-loop automotive logistics to single-direction bulk shipment in agricultural commodity chains.
- Stackable Crates:Interlocking corner posts and reinforced base rails enable vertical loading up to six units high in warehouse racking systems. Automotive OEMs in Germany's Baden-Württemberg corridor specify these for just-in-sequence engine component delivery where floor space optimization drives total cost calculations.
- Foldable Crates:Collapsible side walls reduce return-trip volume by 70%, cutting empty-mile fuel costs for beverage distributors running long-haul routes between bottling plants and retail depots. Aluminum variants command premium positioning due to weight savings on outbound loaded legs.
- Regular Crates:Fixed-wall construction suits short-loop distribution where return frequency exceeds weekly cycles and collapse mechanisms add unnecessary cost.
- Heavy-Duty Crates:Reinforced carbon steel framing with cross-braced corners handles 2,000 kg load ratings for aerospace turbine blade transport where deformation tolerance is near-zero.
The dominant share belongs to Stackable Crates, while Foldable Crates is closing the gap fastest.
Material:
Material selection maps directly to corrosion exposure severity and washdown protocol intensity across end-use environments.
- Aluminum:5052-H32 alloy sheet delivers strength-to-weight ratios that reduce tare weight by 40% versus carbon steel equivalents. Beverage logistics providers in the United States specify aluminum foldable crates to maximize payload on weight-restricted interstate highways.
- Carbon Steel:Hot-rolled coil formed through press-brake bending achieves lowest per-unit cost for automotive parts bins in high-volume, indoor-only deployment where humidity exposure is minimal.
- Stainless Steel:304 and 316 grades withstand caustic washdown cycles in pharmaceutical cold chains where FDA validation requires surface finishes that eliminate microbial harborage points.
- Alloy:Hybrid formulations combining aluminum cores with stainless wear surfaces target niche aerospace applications requiring both lightweighting and chemical resistance.
Carbon Steel holds volume leadership, though Stainless Steel is expanding most quickly in food and pharmaceutical verticals.
Application:
Application segmentation tracks how load frequency, environmental exposure, and handling automation reshape crate specification requirements.
- Retail Storage:Painted carbon steel crates with label holders support back-of-house inventory organization in big-box distribution centers where forklift penetration is limited and manual handling dominates.
- Industrial Transport:Heavy-duty welded construction withstands repeated forklift impacts in tier-1 automotive supplier networks moving powertrain components between machining centers and assembly plants.
- Agricultural Use:Galvanized finishes resist fertilizer and pesticide exposure during seasonal harvest windows where equipment sits idle in open yards for extended periods.
- Shipping:ISO 18613-certified designs enable intermodal transfer between truck, rail, and ocean freight without repacking, serving exporters in Japan's automotive supply base.
Industrial Transport commands the largest deployment base, while Shipping is gaining share fastest as exporters seek containerization standardization.
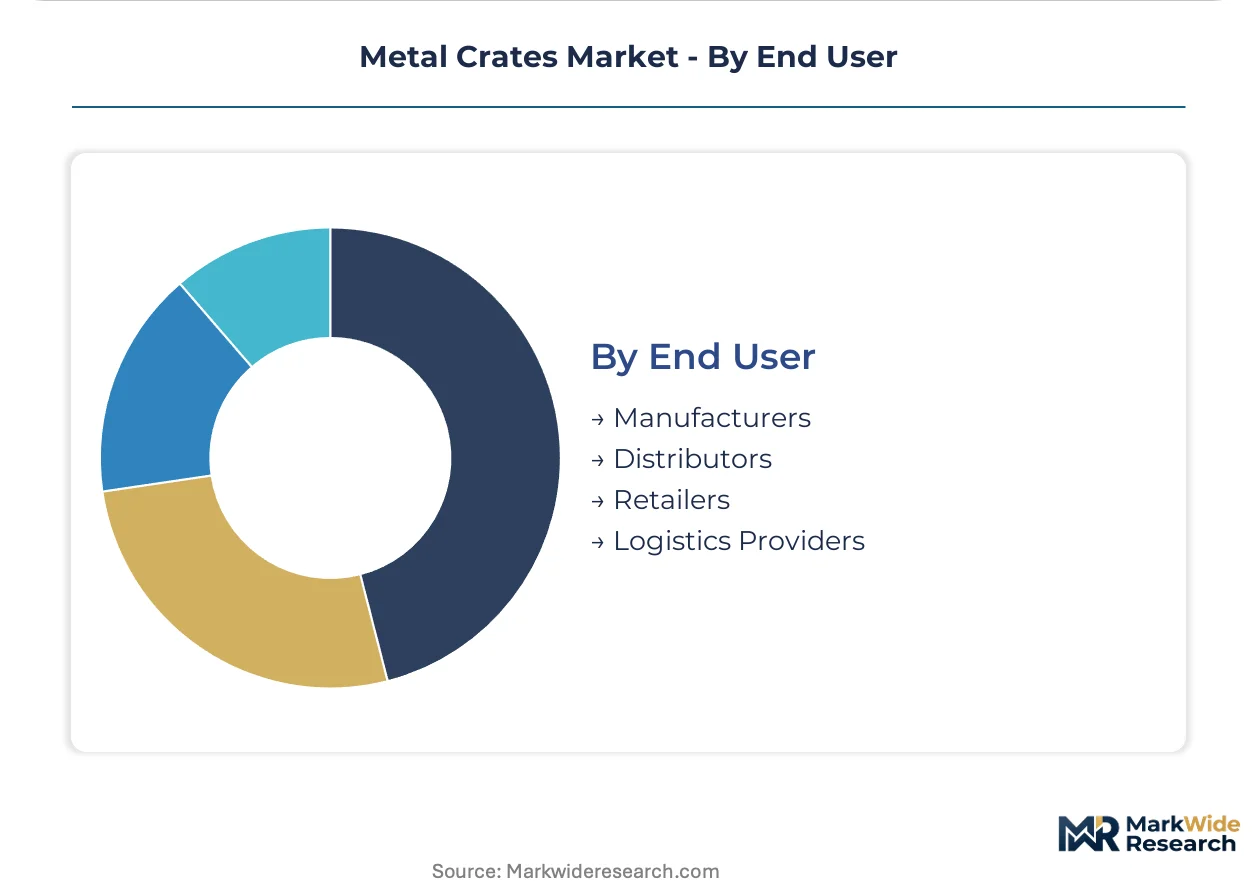
End User:
End-user categories reflect divergent procurement models ranging from capital purchase to third-party leasing across fleet scale and demand predictability.
- Manufacturers:Automotive and electronics assemblers operate captive crate fleets sized to production schedules, with procurement teams negotiating multi-year steel supply contracts to hedge input cost volatility.
- Distributors:Third-party logistics operators in France and Italy maintain regional pooling networks accessed through per-trip subscriptions, converting fixed asset ownership to variable operating expense.
- Retailers:Grocery and general merchandise chains deploy stackable crates for inter-store transfer of promotional inventory where seasonal demand spikes strain warehouse capacity.
- Logistics Providers:Dedicated contract carriers customize crate specifications to shipper requirements, embedding RFID tracking infrastructure for real-time visibility compliance.
Manufacturers retain the deepest fleet ownership, while Logistics Providers are climbing the fastest as outsourcing consolidates packaging asset management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators extract pricing premiums from automotive OEMs while Chinese mills compete on carbon steel sheet input costs. This asymmetry shapes procurement patterns across three continents.
United States
EPA Resource Conservation and Recovery Act mandates cradle-to-cradle documentation for packaging reuse programs. Michigan and Ohio assembly plants now require certified recycled steel grades in supplier contracts. Detroit-Windsor automotive corridor operators are consolidating captive crate fleets to hedge steel price volatility.
Germany
EU Packaging and Packaging Waste Regulation reuse targets force tier-1 suppliers to standardize on returnable stainless steel containers. KBA vehicle certification protocols indirectly validate container durability standards. Baden-Württemberg and Bavaria automotive clusters dominate just-in-sequence delivery specifications for engine component logistics.
China
Jiangsu and Shanxi province stainless steel coil concentration creates supply-side leverage for domestic fabricators. MEE environmental compliance standards tighten electric arc furnace production economics. Yangtze River Delta pooling operators are expanding regional leasing networks to serve export-oriented electronics manufacturers.
India
PLI scheme incentives for auto component manufacturing attract crate leasing operators to establish captive fleets. BIS quality certification requirements delay market entry for imported container designs. Chennai and Pune automotive hubs are standardizing foldable aluminum crates for powertrain component distribution.
Japan
METI circular economy guidelines promote standardized returnable transport item specifications across automotive supply chains. JIS testing protocols align with ISO 18613 for multinational assembly network access. Nagoya and Toyota City manufacturing clusters maintain strict deformation tolerance requirements for turbine blade transport containers.
Metal Crates Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fabrication and alloy supply. The vendor base stratifies between multinational leasing operators with circular-service infrastructure and regional mill-adjacent fabricators. Three archetypes dominate: captive steel integrators, third-party pooling operators, and lightweight alloy formulators. Capacity expansion and strategic partnerships represent the primary competitive vectors as players secure long-term automotive OEM contracts.
Among North American packaging integrators, Mauser Packaging Solutions and Grief exemplify platform-scale operators with established circular-service models. Crown Holdings occupies a position within the lightweight alloy formulation tier. These three anchors illustrate how geographic proximity to steel sourcing and automotive assembly corridors determines competitive positioning in procurement negotiations.
| Leading Market Players |
|---|
| Mauser Packaging Solutions |
| Grief |
| Ball Corporation |
| Crown Holdings |
| Ardagh Group |
| Silgan Holdings |
| CAN-PACK Group |
| Trivium Packaging |
| DS Containers |
| Others |
Supply & Pricing Matrix
Overcapacity in Jiangsu province electric arc furnace operations is compressing carbon steel sheet margins and forcing crate fabricators toward value-added stainless grades or extended payment concessions to retain automotive OEM contracts.
Pricing Analysis
The customization-premium spread separates configured-to-order foldable aluminum crates from standard carbon steel stackables by a factor reflecting weld automation programming and alloy certification costs. Contract-based long-term offtake dominates procurement, with price differentiation driven by ISO 18613 certification tier and volume scale commitments. Pricing pressure stems from polypropylene foldable alternatives achieving lower per-trip costs in sub-500 kg applications. Tier-1 automotive suppliers demonstrate lowest price sensitivity due to just-in-sequence delivery penalties, while agricultural distributors exhibit highest sensitivity given seasonal demand volatility.
Supply Chain Analysis
Extended payment terms from 60 to 90 days have become standard for Jiangsu and Shanxi province stainless coil suppliers serving European fabricators, with supply-chain finance facilities absorbing working capital strain. Raw material sourcing draws from Chinese hot-rolled coil, German cold-rolled precision strip, and Indian secondary aluminum scrap. Distribution runs through captive OEM fleets in Germany's automotive corridor, third-party pooling networks in France and Italy, and regional leasing operators around Chennai and Pune. Single-source vulnerability concentrates in Jiangsu province 304-grade stainless supply, exposing fabricators to MEE environmental compliance disruptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polypropylene foldable crate substitution represents the core threat incumbents must neutralize through durability differentiation and regulatory alignment on reuse targets.
For Market Incumbents: Pre-empt plastic substitution by embedding RFID tracking infrastructure that polypropylene cannot economically replicate, locking in automotive OEM visibility requirements. Deepen backward integration into certified recycled steel grades to satisfy EPA Resource Conservation and Recovery Act documentation mandates in Michigan and Ohio assembly plants. Secure KBA-validated designs in Germany's Baden-Württemberg corridor to create switching costs for tier-1 suppliers.
For New Entrants and Emerging Players: India's PLI scheme auto component hubs around Chennai and Pune offer the most penetrable white space, with domestic crate leasing operators yet to establish regional density. Target pharmaceutical cold chain integration in vaccine distribution networks, where washdown sterilization requirements favor stainless steel over plastic alternatives. Pursue outcome-based leasing models with per-trip pricing to convert capital-constrained mid-tier manufacturers from purchase to subscription.
For Investors and Strategic Acquirers: Long-term, this sits as a circular-service infrastructure play because automotive OEM consolidation around returnable transport item standardization will concentrate pooling operator economics. Acquisition targets should display captive steel sourcing relationships or established ISO 18613 certification capabilities. Monitor EU Packaging and Packaging Waste Regulation enforcement intensity as the signal for reuse target acceleration and metal crate demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Steel Sourcing | Captive supply of EPA-compliant recycled grades secures Michigan and Ohio automotive contracts. |
| ISO 18613 Certification Investment | Testing protocol compliance enables access to multinational automotive assembly networks in Germany and Japan. |
| RFID Tracking Infrastructure Deployment | Real-time visibility capability differentiates against polypropylene substitutes in tier-1 supplier evaluations. |
| Regional Pooling Network Expansion | Asset-light per-trip subscriptions convert seasonal agricultural machinery demand in France and Italy. |
| Pharmaceutical Cold Chain Partnership | Insulated stainless designs with temperature logging penetrate FDA-validated vaccine distribution channels. |
Research Methodology
A standing panel of tier-1 automotive procurement directors, crate leasing fleet managers, steel mill technical sales leads, and pharmaceutical cold chain logistics coordinators provided ongoing calibration across primary interview rounds. Secondary validation drew from EPA enforcement documentation, EU Packaging and Packaging Waste Regulation draft texts, KBA vehicle certification protocols, and Japanese METI circular economy guidelines. Bottom-up fabrication capacity estimates triangulated against top-down automotive OEM packaging spend allocations.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling across product type, material grade, application intensity, and end-user procurement model. CAGRs derived from steel input cost trajectory assumptions, automotive production scheduling patterns, and regulatory reuse target phase-in schedules. Foldable crate adoption curves and pharmaceutical cold chain penetration rates served as industry-specific demand inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed fabricators or accelerated EU reuse target enforcement would shift outcomes. Macroeconomic steel price volatility, geopolitical disruption to Jiangsu province stainless supply, or breakthrough polypropylene load rating improvements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Oblong Tub Lids Market
Containers
Lift-Off Lid Box Market
Containers
Old Corrugated Containers (OCC) Market
Containers
Corrugated Bin Boxes Market
Containers
Global Cardboard Box and Container Market
Containers
Car Lube Container Market
Containers
ISO Container Market
Containers
Cubitainer Market
Containers
Thin Wall Containers Market
Containers
Disposable Lids Market
Containers
Rotomolded Containers Market
Containers
Wooden Barrels Market
Containers
Lever Lid Tinplate Containers Market
Containers
Insert Trays Market
Containers
HDPE Crates Market
Containers
Trigger Sprayer Market