
 Steel Containers Market | 2026-2036
Steel Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Containers Market Analytics
ISO 9001 certification is redrawing competitive boundaries in steel container manufacturing, forcing smaller fabricators toward costly quality system upgrades. SCHÄFER Container Systems leverages captive engineering capabilities across European automotive supply chains. American Containers anchors North American chemical drum demand through backward integration into cold-rolled steel sourcing. Eagle Stainless specializes in electropolished pharmaceutical vessels that command premium positioning.
Steel containers are fabricated pressure-rated vessels, typically from austenitic stainless steel grades 304 or 316, formed through deep drawing or welding processes and engineered to store, transport, or process liquids, powders, and gases under controlled conditions. Drums and barrels retain the largest volume share in chemical and petroleum logistics, though margin pools concentrate in custom pharmaceutical tanks where surface finish specifications reach Ra 0.5 micrometers. The food and beverage end use segment shows the steepest trajectory, driven by brewery expansion and dairy processor modernization across multiple continents.
EPA hazardous waste container regulations, EU REACH substance restrictions, and FDA cGMP guidelines for pharmaceutical contact materials collectively determine product design, material selection, and market access eligibility across major economies. China's GB standards for food-contact metals and India's BIS certification for pressure vessels add further compliance layers for exporters. Stakeholders must monitor evolving carbon border adjustment mechanisms that threaten to reprice imported steel containers against regionally produced alternatives.
Market Dynamics
ISO 9001 certification is redrawing competitive boundaries in steel container manufacturing, forcing smaller fabricators toward costly quality system upgrades while rewarding captive engineering capabilities across consolidated supply chains.
Growth Catalysts
- Brewery modernization:Food and beverage processors are expanding stainless steel tank procurement for aseptic liquid storage across multiple continents.
- EU F-Gas Regulation:Tightening emissions standards for insulated container systems are accelerating replacement cycles in cold-chain logistics.
- Rhine-Ruhr concentration:Demand is concentrating in Germany's industrial corridor, creating procurement gravity for specialized fabricators.
Market Restraints
- Nickel price volatility:Austenitic stainless steel grades 304 and 316 face input cost pressure from nickel market swings.
- Chinese supply dominance:Cold-rolled steel sourcing concentrates among a limited set of integrated mills.
- Aluminum substitution:Lightweight alternative materials threaten drum and barrel segments in non-corrosive chemical transport.
Strategic Opportunities
- Pharmaceutical surface finish:Electropolished vessels with Ra 0.5 micrometer specifications command premium positioning in biologics storage.
- Carbon border adjustments:Emerging mechanisms threaten to reprice imported containers against regionally produced alternatives.
- India BIS certification:Pressure vessel standardization creates compliance-driven demand for certified exporters.
Industry Challenges
- Welding certification backlog:ASME and pressure vessel code compliance timelines stretch qualified fabricator capacity.
- Electropolishing capacity scarcity:Pharmaceutical-grade surface treatment requires capital-intensive cleanroom infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Containers Market |
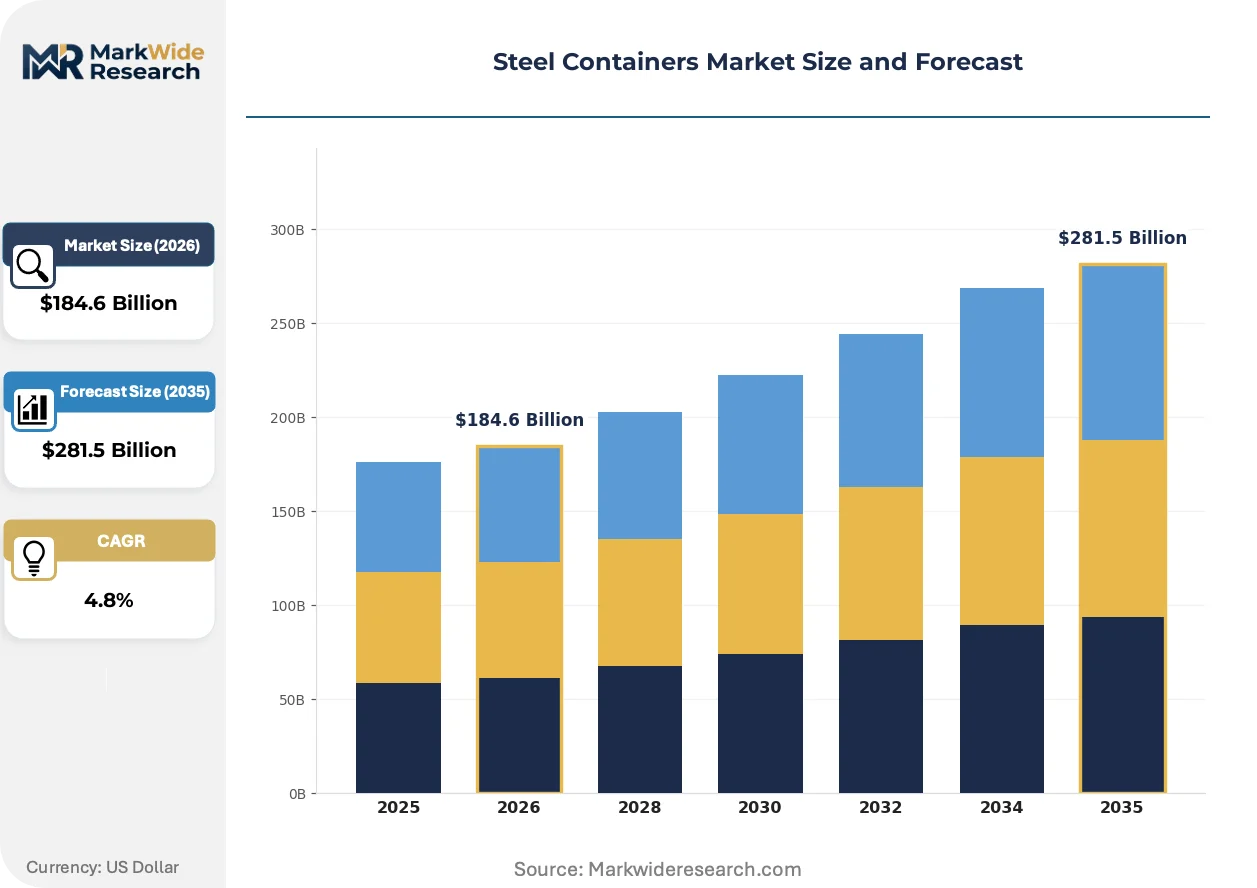
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $281.5 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drums, Barrels, Cans, Tanks End Use Industry: Food & Beverage, Chemicals, Oil & Gas, Pharmaceuticals Package Size: Small, Medium, Large, Custom Distribution Channel: Retail, Wholesale, Direct Sales, Online |
| Companies Covered | Ability Fabricators, La Nuova Sansone, SCHÄFER Container Systems, Cromar Building Products, Wada Stainless Kogyo, Unique Steel, Müller, American Containers, Eagle Stainless, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Containers Market Evolving Landscape
Advanced manufacturing methods and regulatory tightening are compressing product lifecycles while elevating performance specifications across container categories.
Hybrid composite-steel construction is fragmenting traditional market boundaries between metallic and non-metallic pressure vessels. Chemical processors with moderate corrosion requirements are adopting glass-reinforced plastic liners bonded to steel structural shells. This convergence is fragmenting procurement decisions that previously defaulted to solid stainless specifications.
REACH substance restrictions are eliminating legacy coating chemistries from food-contact and pharmaceutical applications. ECHA's evolving candidate list is forcing reformulation of drum interior linings and tank passivation protocols. European dairy processors are responding by specifying electropolished 316L surfaces without secondary coatings.
Consolidated procurement by multinational beverage groups is compressing supplier qualification cycles. Brewery engineering teams now mandate ISO 9001 certification and captive metallurgical testing as baseline vendor requirements. This pattern is most visible in North American craft brewery roll-ups and Latin American dairy processor modernization programs.
Steel Containers Market Segmentation
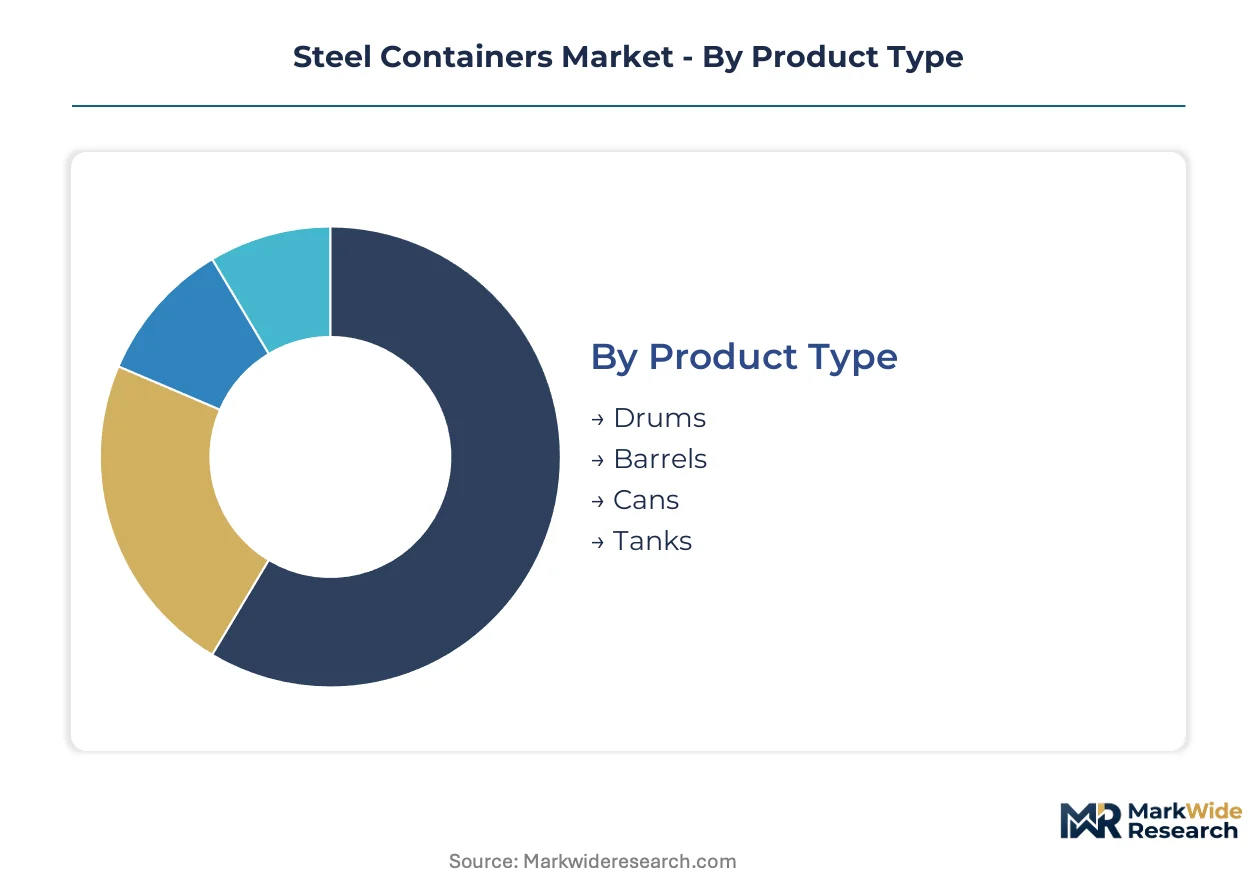
Steel container procurement patterns diverge sharply across product specifications and end-use requirements. Material grade selection, surface finish tolerances, and pressure rating certifications create distinct margin pools that resist simple volume-based segmentation.
Product Type:
Aluminum and composite alternatives exert uneven substitution pressure across metallic vessel categories, with lower-value cylindrical formats facing the most severe displacement risk.
- Drums:Standardized cylindrical vessels typically fabricated from cold-rolled carbon steel with interior epoxy or phenolic linings for chemical compatibility. Demand concentrates in petroleum logistics and hazardous waste handling across the US Gulf Coast refining corridor, where EPA container regulations mandate specific wall thickness and closure specifications. Drums retain volume leadership; tanks hold the steepest expansion curve.
- Barrels:Traditional tight-head and open-head configurations constructed from hot-rolled steel with rolled seams or welded chime construction. European wine and spirits producers drive specification tightening in Bordeaux and Burgundy clusters, requiring UN-certified transport ratings for export compliance.
- Cans:Two-piece and three-piece drawn containers for food preservation and aerosol propellant storage. Beverage can sheet specifications from Nippon Steel and POSCO dominate thin-gauge supply, with interior lacquer systems governed by FDA 21 CFR food-contact substance approvals.
- Tanks:Pressure-rated vessels from austenitic stainless grades 316L or 304L, engineered for aseptic liquid storage and clean-in-place protocols. Brewery engineering teams in Germany's Rhine-Ruhr corridor and India's Maharashtra state specify electropolished surfaces without secondary coatings as REACH restrictions eliminate legacy epoxy formulations.
Tanks command the widest margin spreads through pharmaceutical surface finish premiums; drums face the most acute aluminum substitution threat in non-corrosive chemical transport.
End Use Industry:
Regulatory stringency and surface finish requirements stratify profitability across customer categories, with contact-material compliance costs acting as a natural market filter.
- Food & Beverage:Dairy processors and brewery operations specify 316L stainless with Ra 0.5 micrometer electropolished surfaces for aseptic storage. India's FSSAI food-contact metal standards and China's GB standards for food-grade stainless create parallel compliance tracks for exporters.
- Chemicals:Corrosive substance handling demands specialized linings or solid alloy construction, with EPA hazardous waste container regulations dictating drum wall thickness and closure integrity for US market access.
- Oil & Gas:Lubricant and petroleum product logistics favor carbon steel drums with phenolic or epoxy interior coatings, where cost efficiency outweighs corrosion resistance requirements in non-aggressive service environments.
- Pharmaceuticals:Biologics storage and API processing require ASME-certified pressure vessels with documented surface finish validation, electropolishing capacity scarcity stretching qualified fabricator lead times.
Food & Beverage drives the fastest capacity additions; Pharmaceuticals captures the highest unit margins through certification barriers.
Package Size:
Volume scale determines fabrication method and supply chain configuration, with custom formats commanding engineering premiums that standard sizes cannot match.
- Small:Sub-20 liter containers for laboratory reagents and specialty chemical sampling, typically fabricated from 304 stainless with threaded closures and gasket seals.
- Medium:20-200 liter standardized drums and intermediate bulk containers serving chemical distribution networks.
- Large:Above-ground and underground storage tanks exceeding 1000 liters, requiring structural engineering certification and foundation anchoring specifications.
- Custom:Dimensionally specialized vessels for pharmaceutical autoclave integration or cleanroom material handling, where ASME welding certification and surface finish documentation justify 3-5x standard pricing multiples.
Medium formats dominate unit shipments; Custom specifications expand most quickly as pharmaceutical outsourcing deepens.
Distribution Channel:
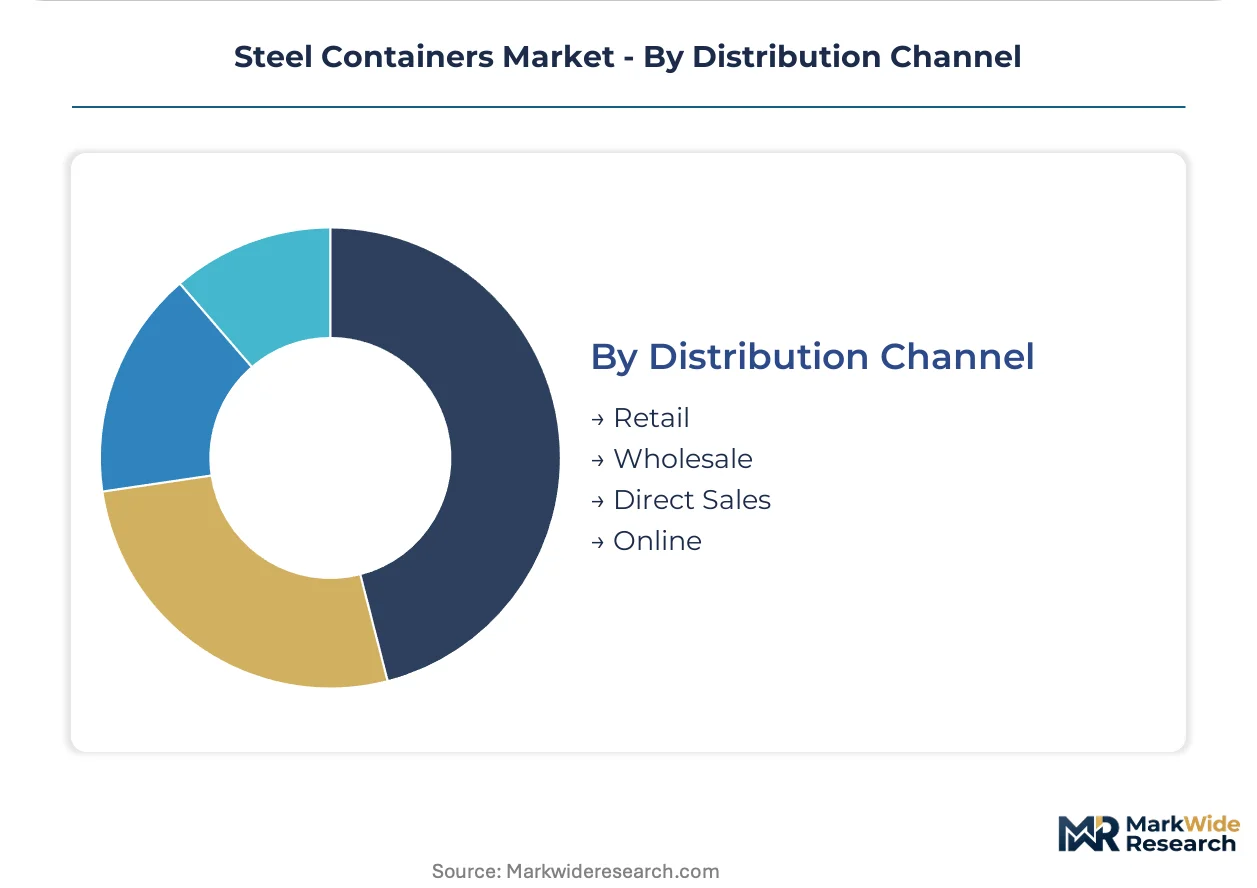
Channel selection reflects buyer scale and specification complexity, with direct relationships displacing intermediaries in technically demanding segments.
- Retail:Standardized drums and small containers through industrial supply distributors, serving maintenance shops and small-batch chemical users.
- Wholesale:Volume drum procurement by petroleum distributors and chemical logistics operators, where palletized delivery and inventory holding terms determine supplier selection.
- Direct Sales:Engineered tank systems sold through captive technical sales teams, with brewery and dairy processor modernization programs mandating metallurgical testing and ISO 9001 certification as baseline vendor requirements.
- Online:Emerging procurement channel for standardized drum specifications, though pressure vessel and pharmaceutical-grade containers remain relationship-driven purchases.
Direct Sales commands the highest value per transaction; Online channels are gaining share fastest in commoditized drum categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial Rhine-Ruhr corridor concentrates procurement gravity for specialized fabricators serving brewery modernization programs. India's BIS certification requirements for pressure vessels create compliance-driven demand for certified exporters. China's GB standards for food-contact metals add further compliance layers for regional producers.
Germany
Brewery engineering teams in the Rhine-Ruhr corridor specify electropolished 316L surfaces without secondary coatings as EU REACH restrictions eliminate legacy epoxy formulations. The EU F-Gas Regulation tightens emissions standards for insulated container systems. Bavarian dairy processors drive specification tightening for aseptic liquid storage tanks.
United States
EPA hazardous waste container regulations dictate drum wall thickness and closure specifications for petroleum logistics across the Gulf Coast refining corridor. FDA cGMP guidelines govern pharmaceutical contact materials for biologics storage vessels. American Containers anchors North American chemical drum demand through backward integration into cold-rolled steel sourcing.
India
Maharashtra state brewery operations and dairy processor modernization programs mandate ISO 9001 certification as baseline vendor requirements. FSSAI food-contact metal standards create parallel compliance tracks for domestic and export markets. Gujarat's chemical processing clusters drive demand for pressure-rated vessels with BIS certification.
China
GB standards for food-grade stainless and food-contact metals govern domestic production and import requirements. SAMR oversight of pressure vessel safety creates certification barriers for market access. Yangtze River Delta manufacturing bases concentrate thin-gauge steel can production for beverage packaging.
Japan
METI industrial standards and JIS certification requirements shape domestic procurement specifications for precision-fabricated vessels. PMDA guidelines influence pharmaceutical-grade surface finish requirements for biologics storage. Kansai region chemical processors adopt hybrid composite-steel construction for moderate corrosion applications.
Steel Containers Market Competitive Landscape
Player mix skews toward mid-cap specialists with captive metallurgical testing capabilities and tier-one fabricators with ASME welding certification. The vendor base separates into three strategic archetypes: integrated steel processors controlling cold-rolled feedstock, electropolishing specialists serving pharmaceutical surface finish specifications, and regional drum fabricators competing on logistics proximity. Dominant competitive moves include backward integration into steel sourcing and ISO 9001 certification investments that redraw supplier qualification boundaries.
Within the electropolishing specialist tier, Eagle Stainless occupies a position exemplifying premium pharmaceutical vessel fabrication. Among European-based fabricators, SCHÄFER Container Systems and La Nuova Sansone represent archetypes of regional engineering capability leveraged across consolidated supply chains. American Containers anchors the North American integrated processor segment. Wada Stainless Kogyo exemplifies Japanese precision fabrication standards for regulated end-use applications.
| Leading Market Players |
|---|
| Ability Fabricators |
| La Nuova Sansone |
| SCHÄFER Container Systems |
| Cromar Building Products |
| Wada Stainless Kogyo |
| Unique Steel |
| Müller |
| American Containers |
| Eagle Stainless |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between brewery engineering teams and specialized fabricators lock in electropolished 316L tank supply while fixing nickel surcharge visibility against LME volatility. These contracts concentrate procurement gravity in Germany's Rhine-Ruhr corridor and India's Maharashtra state, where ISO 9001 certification acts as a non-negotiable entry filter.
Pricing Analysis
Certification level creates the primary spread across the steel container market, with ISO 9001 and ASME pressure vessel code compliance commanding 40-60% premiums over uncertified alternatives. Three-tier pricing structure across pharmaceutical-grade electropolished surfaces, food-grade 316L tanks, and standard carbon steel drums reflects surface finish tolerance and documentation burden. Cost compression in commodity drum segments is intensifying because Chinese cold-rolled steel sourcing concentrates among integrated mills. Chemical logistics operators show highest price sensitivity, while biologics processors accept premium positioning for Ra 0.5 micrometer surface validation.
Supply Chain Analysis
Strategic stockpiling of nickel-bearing austenitic grades dominates inventory strategy among qualified fabricators facing ASME welding certification backlogs. Supply concentrates in China for cold-rolled feedstock, Germany for precision-engineered brewery tanks, and India for BIS-certified pressure vessels. Raw material dependencies rest on nickel ore from Indonesia and the Philippines, chromium from South Africa, and specialty cold-rolled sheet from Nippon Steel and POSCO. Single-source vulnerability in electropolishing cleanroom infrastructure threatens pharmaceutical lead times. Distribution runs through direct technical sales teams for engineered tanks and wholesale petroleum distributors for standardized drums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation deepens as REACH substance restrictions and carbon border adjustment mechanisms fragment procurement decisions that previously defaulted to solid stainless specifications. This regulatory layering creates defendable niches for certified specialists against commodity drum fabricators.
For Market Incumbents: Shield margin pools in pharmaceutical-grade electropolished vessels by deepening captive metallurgical testing capabilities and expanding ASME welding certification capacity. Aluminum substitution in non-corrosive chemical transport threatens drum segment profitability; backward integration into cold-rolled steel sourcing anchors feedstock security against Chinese mill concentration.
For New Entrants and Emerging Players: Aftermarket electropolishing service gaps in North American biologics storage create white-space entry points. Target India's Gujarat chemical processing clusters with BIS-certified pressure vessel fabrication, where domestic capacity scarcity stretches qualified fabricator lead times. Lead with ISO 9001 certification as baseline vendor credential to bypass brewery procurement gatekeeping.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap electropolishing specialists with cleanroom infrastructure and documented pharmaceutical surface finish validation. Long-term viability in this market hinges on regulatory compliance moats rather than volume scale. Watch for carbon border adjustment mechanism implementation in the EU as inflection indicator repricing import competition.
| Strategic Initiative | Industry Significance |
|---|---|
| ASME Welding Certification Expansion | Addresses capacity scarcity stretching qualified fabricator lead times for pharmaceutical vessels. |
| Backward Integration into Cold-Rolled Steel | Anchors American Containers' North American chemical drum demand against Chinese supply dominance. |
| Electropolishing Cleanroom Infrastructure | Captures premium positioning in biologics storage where Ra 0.5 micrometer specifications command pricing power. |
| ISO 9001 Certification Investment | Redraws competitive boundaries forcing smaller fabricators toward costly quality system upgrades. |
| Hybrid Composite-Steel Construction Development | Fragments procurement decisions for moderate corrosion applications in Kansai region chemical processing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from integrated steel processors, and EU ECHA regulatory submissions. Interviews with brewery engineering directors, pharmaceutical procurement managers, pressure vessel fabricators, and chemical logistics operators informed demand-side validation. Secondary sources include BIS certification registries, FDA cGMP guidance documents, and EPA hazardous waste container enforcement data. Bottom-up tank and drum shipment analysis triangulates against top-down steel consumption models.
Segmentation dimensions modeled span product type, end-use industry, package size, and distribution channel across the projection horizon. Food and beverage procurement patterns, pharmaceutical surface finish specifications, and regional regulatory clusters drove analytical framework construction. CAGRs derive from regression analysis against brewery modernization spend, dairy processor capital investment cycles, and REACH restriction implementation timelines.
Underlying assumptions cover nickel price stability, ASME certification capacity expansion, and carbon border adjustment mechanism scope, with deviation risk concentrated in Chinese cold-rolled steel export policy and EU F-Gas Regulation enforcement intensity. Revision becomes warranted when aluminum substitution rates in chemical transport cross material displacement thresholds or when electropolishing cleanroom capacity additions accelerate beyond current scarcity conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Global Food Containers Market
Containers
Water Resistant Packing Cubes Market
Containers
Feeder Containers Market
Containers
Canning Jars Market
Containers
Intermediate Bulk Container (IBC) Market
Containers
Screw Top Pails Market
Containers
HDPE Blow Molding and Injection Molding Containers Market
Containers
Corrugated Bin Boxes Market
Containers
Dispensing Jug Market
Containers
Containerboard Market
Containers
Mini Spray Bottles Market
Containers
Hinged Lid Tins Market
Containers
Gable Top Container Market
Containers
Thermoformed Shallow Trays Market
Containers
Popcorn Containers Market
Containers
Snap-Lock Container Market