
 Popcorn Containers Market | 2026-2036
Popcorn Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Popcorn Containers Market Analytics
Direct-to-cinema supply chains is rewriting procurement patterns for concession packaging. Berry Global Inc. leverages its North American manufacturing footprint to control bulk polymer supply for plastic tub programs. Graphic Packaging International, LLC anchors the paperboard segment with integrated cartonboard mills serving multiplex chains. Divan Packaging LLC competes on custom-printed flexible formats for regional cinema circuits.
Popcorn containers are engineered food-contact vessels, typically constructed from coated paperboard, injection-molded polypropylene, or tin-plated steel, with grease-resistant barriers rated for temperatures exceeding 90 degrees Celsius to maintain structural integrity during butter-oil exposure. Their primary commercial function centers on portion-controlled dispensing, brand display, and thermal handling in high-volume entertainment and retail foodservice environments. Paper-based formats lead unit volume across cinema and event channels, while plastic containers capture margin pools through reusable and collectible designs. The end-user split between cinemas and events shows the fastest structural expansion, as outdoor entertainment formats and pop-up retail installations multiply container throughput outside traditional theater footprints.
The US FDA regulates food-contact substances under 21 CFR, while the EU enforces the Single-Use Plastics Directive and REACH compliance for chemical migration limits; these frameworks compel material transitions toward certified compostable substrates and recycled-content polymers. China's SAMR and GB standards for food packaging impose additional testing protocols on export-bound container manufacturers. Stakeholders must monitor evolving extended-producer-responsibility mandates and decide between regional material certification investments versus centralized global specification platforms.
Market Dynamics
The EU's Single-Use Plastics Directive is forcing material transitions across European cinema chains, while multiplex operators in the United States accelerate container refresh cycles to capture premium concession margins. These dual pressures are compressing supplier lead times and fragmenting procurement specifications between compostable paperboard and recycled-content polymer formats.
Growth Catalysts
- Cinema attendance recovery:Theater operators in the United States are expanding concession packaging programs to offset ticket revenue volatility, driving container throughput at multiplex locations.
- REACH compliance migration:European manufacturers are certifying grease-resistant coatings under EU chemical safety standards, opening certified substrate supply to cinema chains under ECHA oversight.
- Outdoor entertainment expansion:Pop-up retail installations and drive-in formats are multiplying container demand outside traditional theater footprints, creating new volume channels for flexible packaging suppliers.
Market Restraints
- Polymer price volatility:Injection-molded polypropylene container producers face margin compression from fluctuating bulk resin contracts tied to naphtha feedstock indices.
- Coated paperboard supply concentration:Integrated cartonboard mill capacity clusters in the Upper Midwest and Southeastern United States, creating geographic vulnerability for regional cinema circuits.
- Compostable barrier limitations:Current PLA and PHA substrates exhibit thermal deformation below 85 degrees Celsius, restricting hot-butter-oil applications in premium tub formats.
Strategic Opportunities
- India multiplex buildout:PVR-INOX and Cinepolis India are expanding screen counts in Tier-2 cities under FSSAI food-contact packaging standards, creating first-mover positioning for certified suppliers.
- Reusable collectible formats:Limited-edition plastic tub designs tied to franchise film releases command premium pricing and repeat theater visits from collector demographics.
- SAMR certification arbitrage:China's national food packaging standards impose testing protocols on export-bound manufacturers, creating compliance-service revenue streams for testing laboratories serving dual-market producers.
Industry Challenges
- Migration testing bottlenecks:FDA 21 CFR food-contact substance notifications face 180-day review timelines, delaying new coating formulations for butter-resistant paperboard launches.
- Legacy equipment retrofit costs:Cinema concession stands operate fixed-fill-volume dispensers calibrated to legacy tub dimensions, complicating format transitions to sustainable alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Popcorn Containers Market |
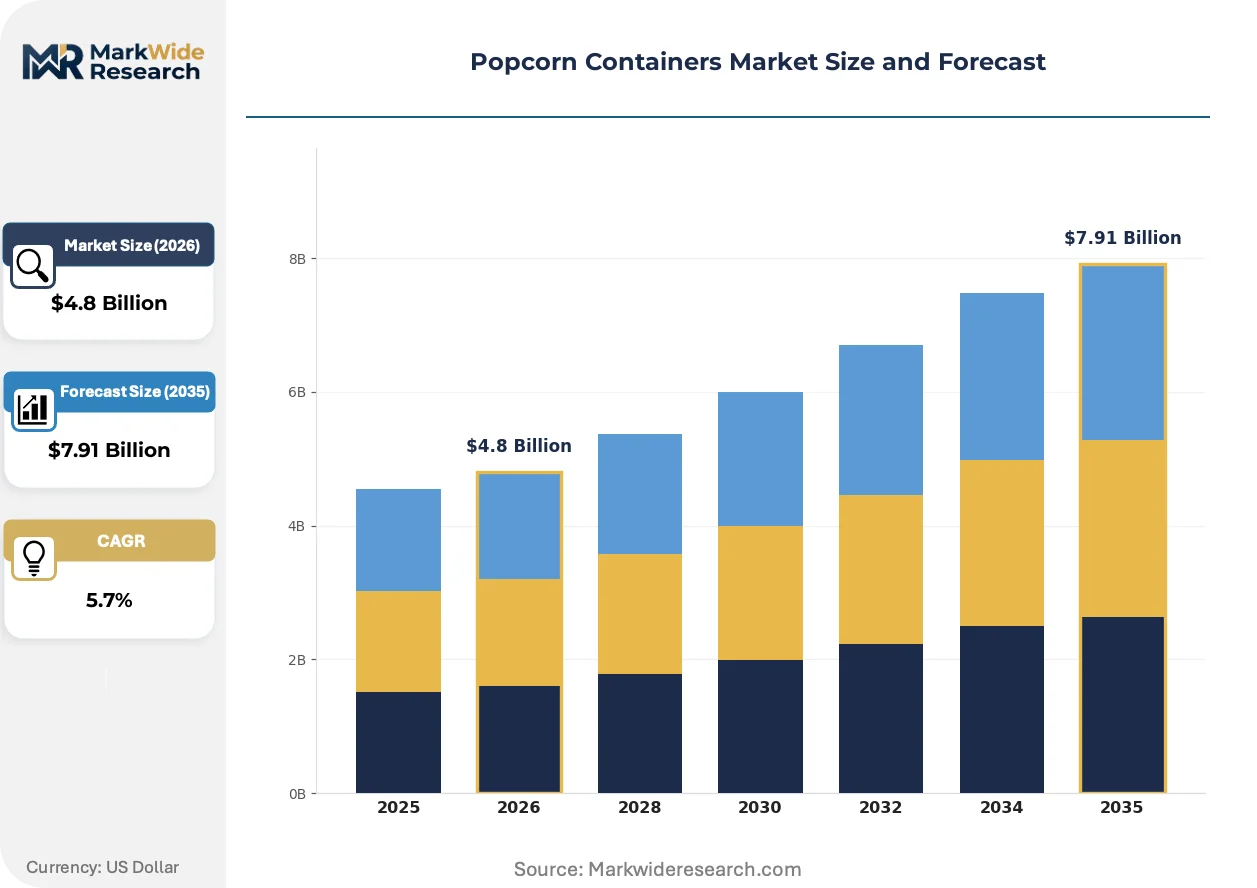
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
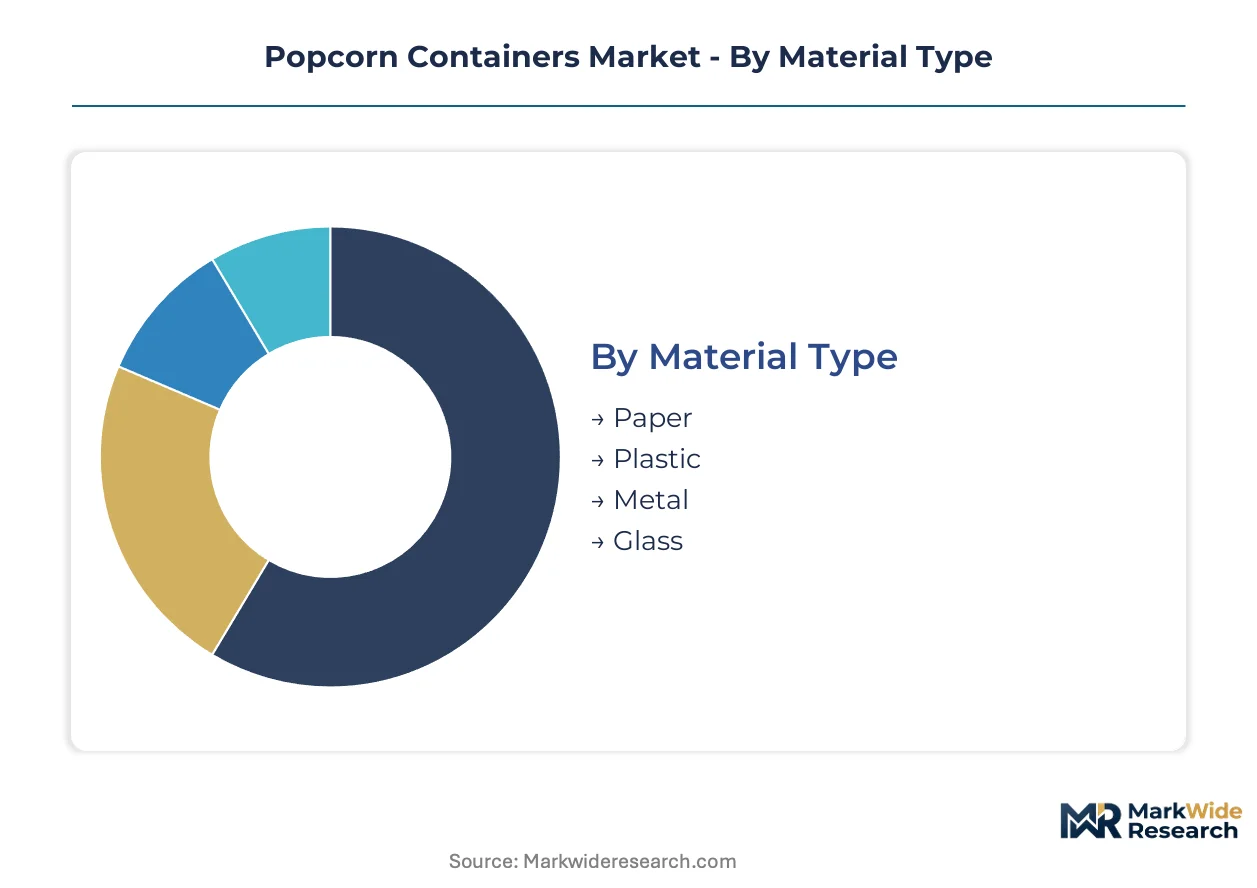
| Segmentation | Material Type: Paper, Plastic, Metal, Glass Distribution Channel: Retail Stores, Online Stores, Wholesalers, Supermarkets End User: Cinemas, Snack Shops, Grocery Stores, Events Size: Small, Medium, Large, Extra Large |
| Companies Covered | Berry Global Inc., Graphic Packaging International, LLC, Divan Packaging LLC, Kai Lai Packaging, Hutzler Manufacturing Co, Inc., Wuhan Yoon Import & Export Co., Ltd., Paper Cup Company, ISHWARA, Susitra Agencies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Popcorn Containers Market Evolving Landscape
Material science breakthroughs and regulatory phase-outs are converging to transform popcorn container specifications across cinema and retail channels. Suppliers must now engineer for dual compliance regimes while meeting portion-control and brand-display functions.
Water-based grease-resistant coatings are replacing fluorochemical treatments in coated paperboard production. Major multiplex chains in California and New York are mandating PFAS-free substrates ahead of state-level bans. This transition is rendering obsolete legacy fluorinated barrier chemistries that dominated cinema packaging for two decades.
The EU's Single-Use Plastics Directive mandates recycled content minimums and extended producer responsibility schemes for foodservice packaging. Member states are transposing these rules into national enforcement frameworks with varying timelines. German and French cinema operators face the strictest compliance deadlines, accelerating shifts toward certified compostable formats and deposit-return collection systems.
Direct-to-cinema supply contracts are displacing traditional distributor intermediaries in North American procurement. Multiplex chains now negotiate polymer supply agreements directly with resin producers, while paperboard specifications flow from integrated mill operations to concession packaging programs. This consolidation is most visible in the United States, where Regal, AMC, and Cinemark operate centralized procurement functions controlling container specifications across thousands of screens.
Popcorn Containers Market Segmentation
Popcorn container specifications diverge sharply across material platforms and channel structures. Each segment carries distinct regulatory footprints, thermal performance requirements, and procurement economics that reshape supplier positioning.
Material Type:
After-sales-service intensity varies dramatically by substrate chemistry, with coated paperboard demanding coating requalification support and polymer formats requiring mold maintenance programs.
- Paper:Coated paperboard dominates cinema procurement through grease-resistant barriers rated above 90 degrees Celsius. United States multiplex operators are mandating PFAS-free substrates ahead of state-level bans, compressing coating reformulation timelines.
- Plastic:Injection-molded polypropylene captures collectible and reusable formats with thermal stability exceeding butter-oil exposure thresholds. European cinema chains face recycled-content minimums under the EU Single-Use Plastics Directive, fragmenting resin sourcing strategies.
- Metal:Tin-plated steel persists in premium gift formats and heritage cinema branding programs.
- Glass:Specialty popcorn retail in gourmet channels uses glass for portion-controlled sampling displays.
By volume, Paper leads. By growth pace, Plastic is ahead.
Distribution Channel:
Cost tier separation between direct cinema contracts and retail intermediaries determines margin capture and specification control.
- Retail Stores:Branded home-use containers move through party supply and housewares channels with seasonal demand concentration around holiday entertainment periods.
- Online Stores:E-commerce platforms aggregate specialty and collectible formats for home theater enthusiasts, with fulfillment economics favoring lightweight collapsible designs.
- Wholesalers:Bulk procurement for event rental companies and concession equipment distributors concentrates in regional supply hubs.
- Supermarkets:Private-label microwave popcorn sleeves and ready-to-eat tubs drive high-volume, low-margin throughput with shelf-life barrier requirements.
By volume, Supermarkets lead. By margin capture, Online Stores is climbing fastest.
End User:
Application environment dictates structural engineering priorities, from fixed-fill dispensers in cinemas to portable handling in outdoor events.
- Cinemas:Multiplex operators specify portion-controlled tubs calibrated to legacy dispenser volumes, with brand display surfaces optimized for dark-environment visibility.
- Snack Shops:Specialty popcorn retailers demand custom-printed flexible formats with shorter run lengths and rapid graphic turnaround.
- Grocery Stores:Private-label programs require food-contact compliance at scale with minimal coating cost premiums.
- Events:Outdoor entertainment and pop-up retail formats multiply container throughput outside traditional theater footprints, favoring lightweight disposable substrates.
By volume, Cinemas leads. By expansion trajectory, Events is gaining share fastest.
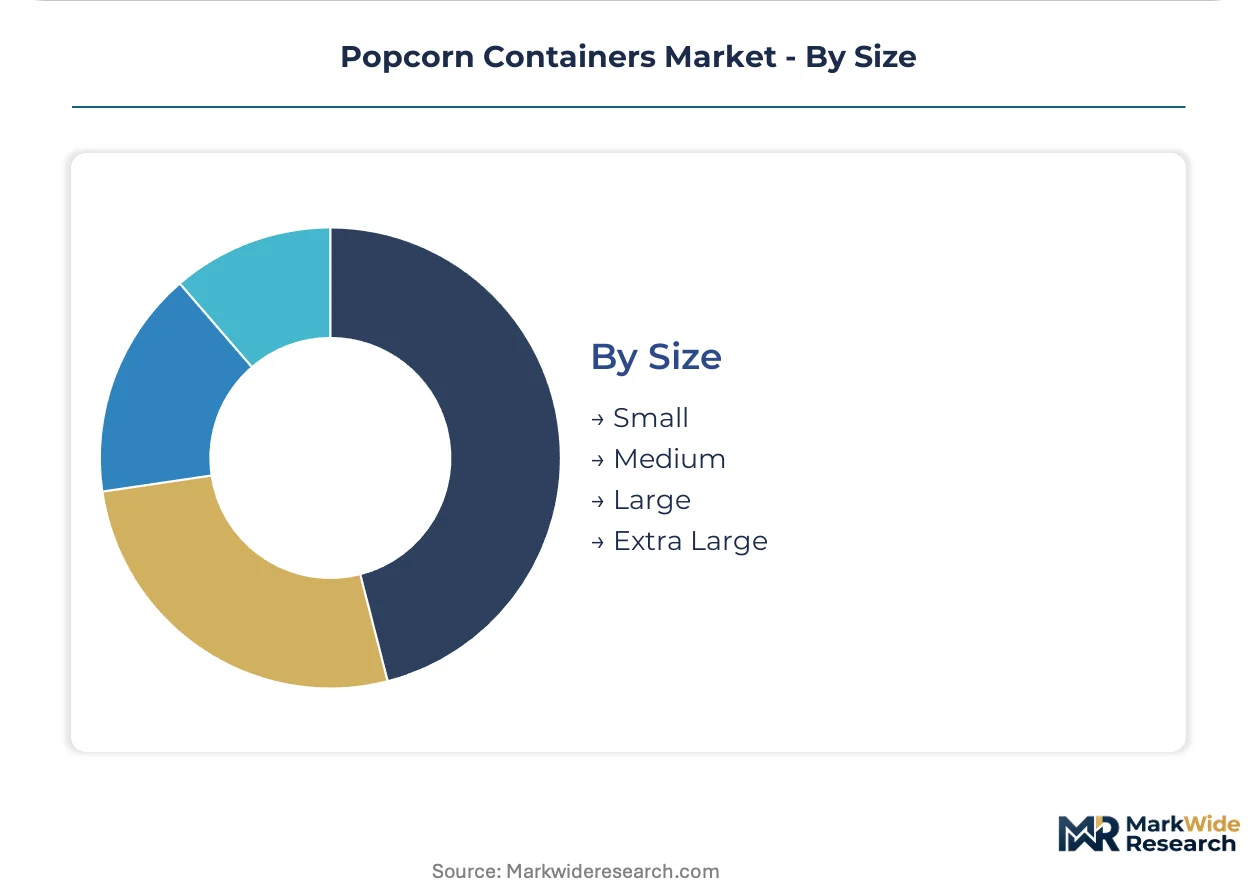
Size:
Customer type stratification across individual, family, and group consumption occasions segments pricing and material specification tiers.
- Small:Single-serve formats align with sampler programs and dietary portion control, common in specialty snack shops.
- Medium:Standard individual portions dominate cinema concession throughput with optimized fill-to-weight ratios.
- Large:Family-sharing formats command premium pricing in multiplex environments with collectible branding potential.
- Extra Large:Group and event-sized containers require reinforced structural ribs for transport stability in outdoor entertainment settings.
By volume, Medium leads. By pricing power, Extra Large shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium concession pricing in the United States commands margins that European cinema chains cannot replicate under stricter material compliance costs. This pricing-power asymmetry is reshaping supplier investment priorities across developed markets.
United States
Multiplex operators in Texas and California are expanding container refresh cycles to capture premium snack margins. FDA 21 CFR food-contact substance notifications govern coating formulations for butter-resistant paperboard. Integrated cartonboard mill capacity clusters in the Upper Midwest and Southeastern states, serving Regal, AMC, and Cinemark procurement networks.
Germany
Cinema chains face accelerated compliance deadlines under the EU Single-Use Plastics Directive transposition. ECHA oversees grease-resistant coating certifications under REACH chemical safety standards. Industrial packaging concentration in North Rhine-Westphalia supports rapid format transitions to certified compostable substrates.
China
Export-bound manufacturers serving dual markets are certifying under SAMR national food packaging standards. GB standards impose additional testing protocols on container chemistry and migration limits. Yangtze River Delta manufacturing hubs are expanding capacity for microwave popcorn sleeve production.
India
PVR-INOX and Cinepolis India are building screen counts in Tier-2 cities under FSSAI food-contact packaging standards. The national regulator mandates specific barrier performance for hot-oil exposure applications. Maharashtra and Karnataka host the primary flexible packaging converter clusters serving regional cinema circuits.
United Kingdom
Multiplex operators are mandating PFAS-free substrates ahead of anticipated national bans. The Environment Agency enforces extended producer responsibility schemes for foodservice packaging waste. London and Southeast England concentrate import distribution for European-coated paperboard supply.
Popcorn Containers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material and coating supply. The market structures around three tiers: integrated paperboard mills with captive converting, polymer resin producers with downstream molding operations, and flexible packaging converters serving regional circuits. Two strategic archetypes dominate—backward-integrated substrate manufacturers and specialty coating formulators. Competitive moves concentrate on direct-to-cinema contract consolidation and PFAS-free coating reformulation pipelines.
Among North American packaging conglomerates, Berry Global Inc. and Graphic Packaging International, LLC exemplify the integrated mill-to-converter archetype, while Divan Packaging LLC occupies a position within the specialty flexible segment serving regional cinema circuits.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Graphic Packaging International, LLC |
| Divan Packaging LLC |
| Kai Lai Packaging |
| Hutzler Manufacturing Co, Inc. |
| Wuhan Yoon Import & Export Co., Ltd. |
| Paper Cup Company |
| ISHWARA |
| Susitra Agencies |
| Others |
Value Network & Pricing Analysis
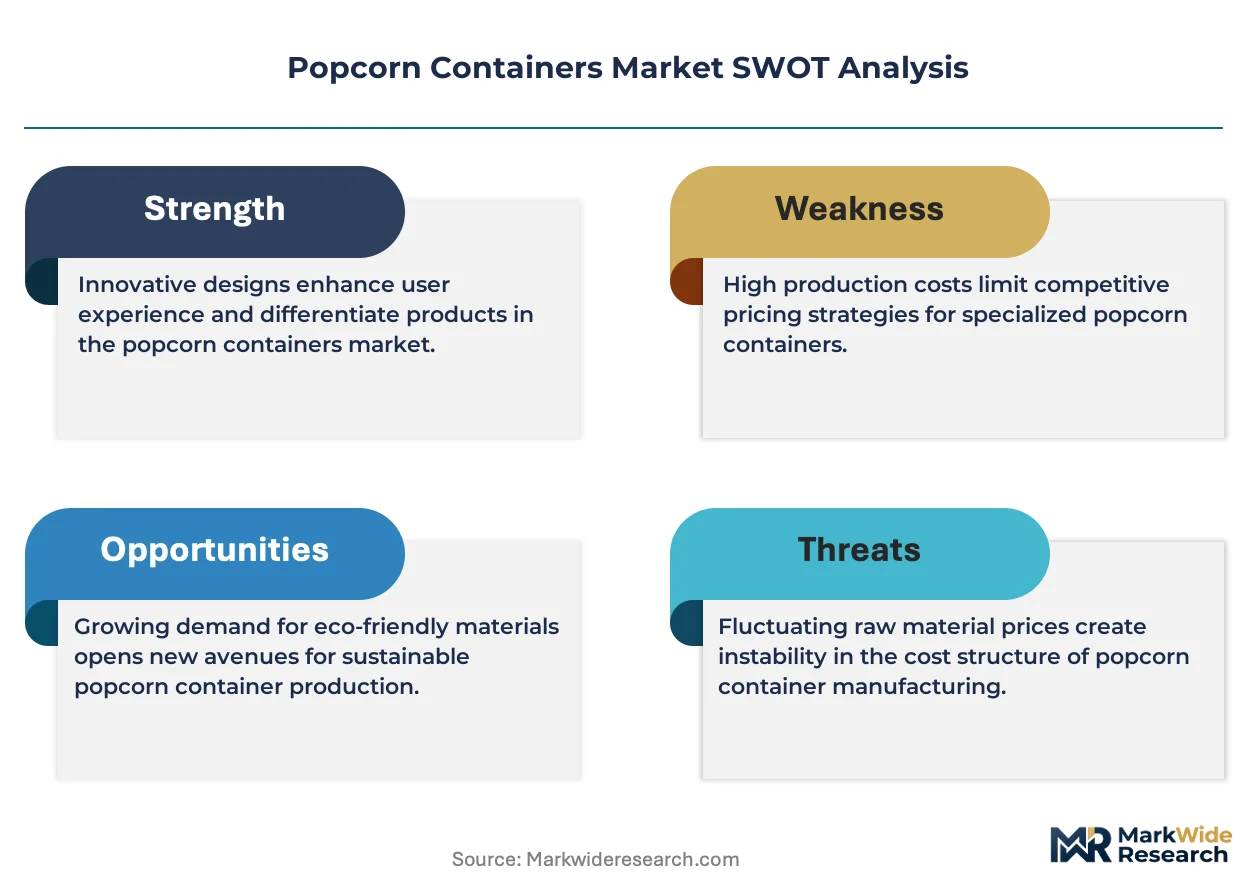
Overcapacity in Upper Midwest cartonboard mills is compressing coating cost premiums while forcing suppliers toward direct-to-cinema contract consolidation. This utilization dynamic simultaneously erodes spot-market pricing power and accelerates backward integration into captive polymer supply for injection-molded formats.
Pricing Analysis
Configured-to-order pricing for custom-printed flexible formats commands spreads against standard coated paperboard tubs. Three-tier pricing structure across premium collectible, standard cinema, and economy event tiers separates margin pools by thermal performance and brand display surface. Price differentiation rests on PFAS-free certification status and volume scale commitments from multiplex procurement networks. Cost compression in economy-tier PLA substrates is intensifying because compostable barrier thermal limitations restrict hot-butter-oil applications.
Supply Chain Analysis
Contract-manufacturing concentration for injection-molded polypropylene sits with Berry Global's North American molding operations and regional flexible packaging converters serving cinema circuits. Geographic supply draws from United States integrated mills, Chinese Yangtze River Delta microwave sleeve producers, and Indian Maharashtra flexible converter clusters. Raw material dependencies center on bulk polymer resin contracts, fluorochemical-free coating formulations, and tin-plate steel for premium gift formats. Single-source vulnerability concentrates in Upper Midwest cartonboard capacity. Distribution runs through direct-to-cinema supply contracts displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to theater attendance volatility and concession packaging refresh cycles. Multiplex operators expand container programs to offset ticket revenue instability.
For Market Incumbents: Pre-empt PFAS-free coating formulation pipelines ahead of state-level bans in California and New York. Backward integration into water-based grease-resistant barrier chemistry secures supply security against coating requalification bottlenecks under FDA 21 CFR review timelines. Consolidate direct-to-cinema procurement relationships before regional flexible converters capture Tier-2 multiplex expansion.
For New Entrants and Emerging Players: Pursue certified compostable substrate supply for European cinema chains facing accelerated EU Single-Use Plastics Directive compliance deadlines. India multiplex buildout in Tier-2 cities under FSSAI standards offers the most penetrable geography. Lead with SAMR certification services for export-bound manufacturers serving dual China-US markets.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across flexible packaging conversion as digital printing shortens graphic turnaround requirements. Long-term viability favors coating formulators with certified barrier pipelines over commodity substrate producers. Target acquisition archetypes include PFAS-free coating specialists and regional cinema-circuit distributors. Monitor ECHA grease-resistant certification backlogs as inflection signal for European supply constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Coating Reformulation | California and New York state bans render legacy fluorinated barriers obsolete across multiplex procurement. |
| Direct-to-Cinema Contract Consolidation | Regal, AMC, and Cinemark centralized procurement functions displace distributor intermediaries in North America. |
| Recycled-Content Polymer Sourcing | EU Single-Use Plastics Directive mandates fragment resin sourcing strategies for European cinema chains. |
| India Tier-2 Multiplex Expansion | PVR-INOX and Cinepolis India screen buildouts create first-mover positioning under FSSAI standards. |
| Reusable Collectible Format Development | Limited-edition plastic tub designs tied to franchise releases command premium pricing from collector demographics. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR food-contact substance notifications, EU ECHA coating certification databases, and trade customs records for polymer resin imports. Primary interviews engaged procurement directors at multiplex chains, technical R&D leads at integrated cartonboard mills, regulatory affairs managers at flexible packaging converters, and concession equipment distributors. Secondary validation drew from SEC 10-K filings of North American packaging conglomerates, SAMR GB standard testing protocols, and FSSAI food-contact packaging compliance circulars. Bottom-up volume triangulation against top-down market sizing anchored projection frameworks.
Forecast inputs span material type segmentation across paperboard, polymer, and metal substrates; distribution channel structures from direct cinema contracts to retail intermediaries; and end-user applications across cinemas, events, and grocery channels. Modeled variables include thermal performance tier, certification status, and geographic regulatory cluster. CAGRs derive from elasticity-adjusted volume trajectories tied to theater attendance recovery patterns and concession packaging refresh cycle frequency. Industry-specific inputs incorporate coating reformulation pipeline timelines and extended producer responsibility scheme adoption rates.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending and polymer feedstock indices would shift the trajectory. Forecasts reflect documented assumptions on regulatory phase-out schedules and multiplex capital expenditure continuity. Supply concentration in Upper Midwest cartonboard and Yangtze River Delta microwave sleeve capacity represents specific vulnerability factors. Quarterly review of FDA food-contact notification backlogs and ECHA certification queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
PET Containers Market
Containers
Containerboard Market
Containers
Jerry Cans Market
Containers
EPS Shippers Market
Containers
Asia and Africa Food Cans Market
Containers
Thin Wall Containers Market
Containers
Global Food Containers Market
Containers
Dispensing Jug Market
Containers
Conipack Pails Market
Containers
Foldable Container Market
Containers
PS Containers Market
Containers
Injection Molding Containers Market
Containers
Food Grade Stainless Steel Container Market
Containers
Twist Up Stick Container Market
Containers
High Density Polyethylene (HDPE) Bottles Market
Containers
North America Plastic Bottles and Containers Market