
 Thermoformed Lids Market | 2026-2036
Thermoformed Lids Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoformed Lids Market Outlook
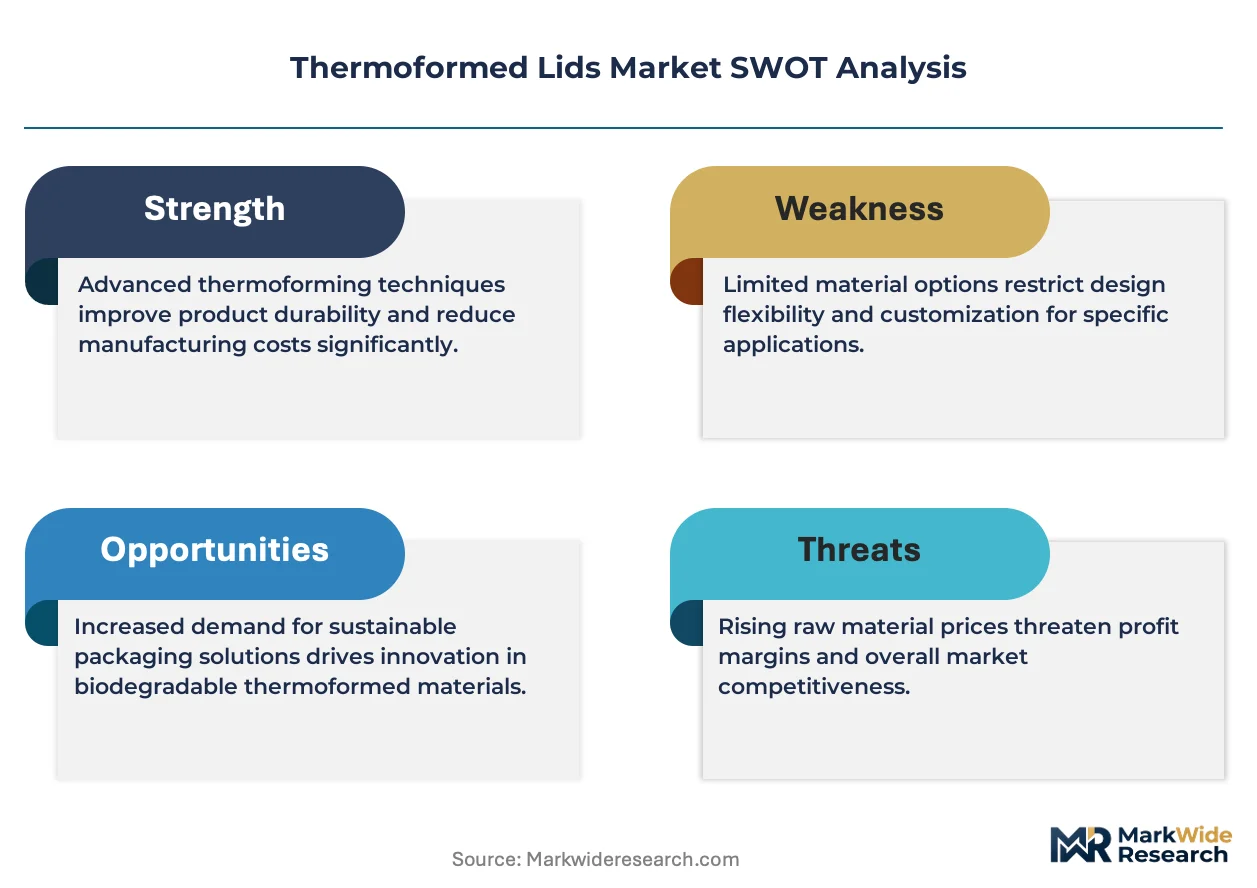
Modular lid-and-tray configurations are broadening buyer choice across foodservice and retail channels. Amcor plc leverages vertical integration across resin sourcing and thermoforming operations to control cost variability. Berry Global Group, Inc. anchors North American supply through high-volume production infrastructure for dome and flat lid formats. Huhtamaki Oyj differentiates via specialty lid designs tailored to European bakery and deli segments.
Thermoformed lids are rigid plastic closures produced by heating and vacuum-forming sheets of polypropylene, PET, or polystyrene into precise geometries, typically spanning 0.010 to 0.040 inches in wall thickness, designed to seal trays, cups, and containers against leakage and contamination. Flat lids dominate commodity food packaging where cost minimization governs procurement, while custom lids command margin pools in medical device and premium food applications where dimensional tolerances and tamper-evident integration are specified. PET material grades are displacing PVC across multiple end users as recyclability becomes a contractual requirement from major food brands.
The FDA regulates food-contact substances under 21 CFR 177, while the EU REACH framework restricts phthalate plasticizers in PVC lid formulations, and California's SB 54 mandates recycled content thresholds that reshape material procurement for suppliers serving the US West Coast. The EU F-Gas Regulation and emerging state-level extended producer responsibility laws in New York and Washington will tighten compliance burdens for non-recyclable PS lids. Stakeholders must monitor regulatory divergence between North American and European recycling infrastructure standards when siting capacity or reformulating material portfolios.
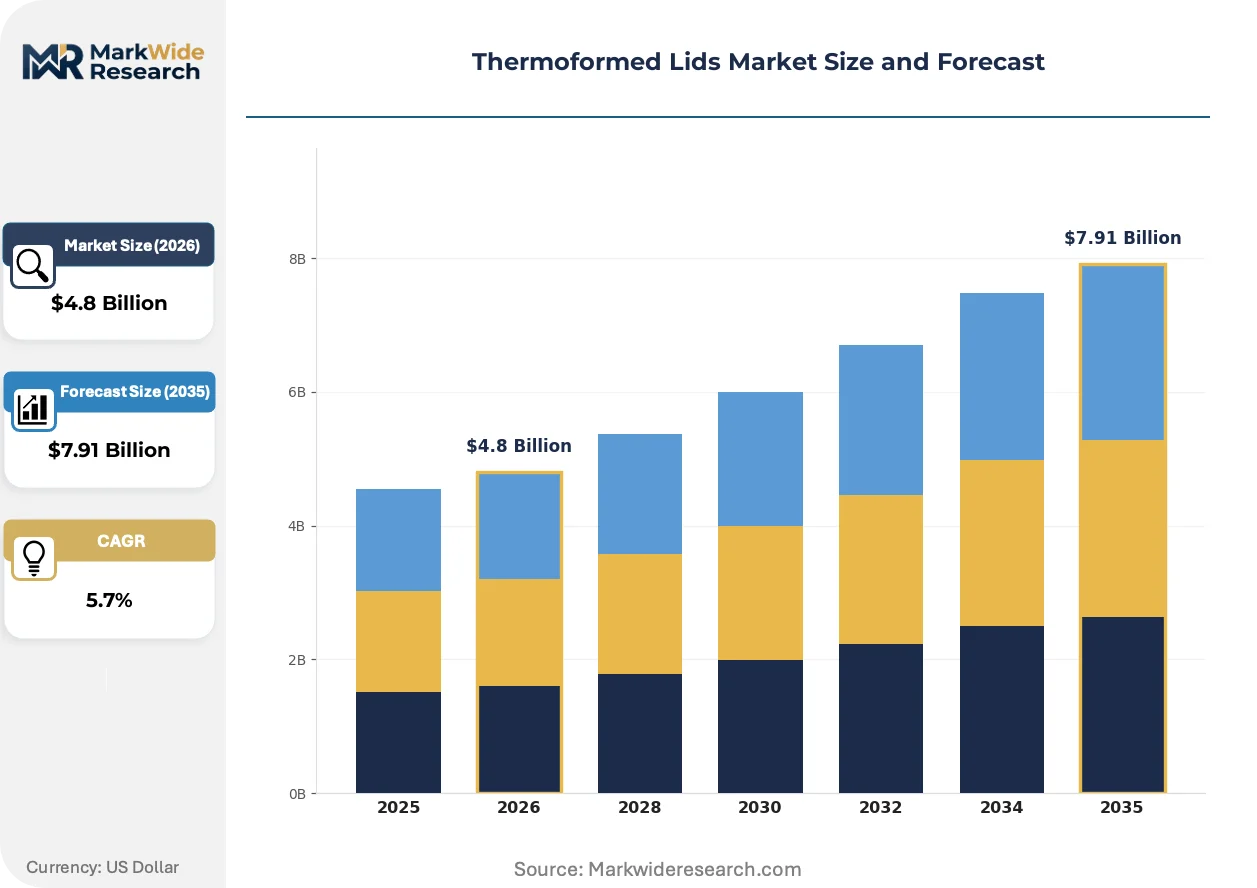
Market Dynamics
Material substitution pressure from California's SB 54 and the EU Single-Use Plastics Directive is compressing PVC and polystyrene demand while expanding rPET procurement specifications across foodservice supply chains.
Growth Catalysts
- EU Single-Use Plastics Directive:The framework bans expanded polystyrene food containers and mandates design-for-recycling standards, redirecting thermoformed lid procurement toward PET and polypropylene substrates with established recycling pathways.
- Foodservice automation:Robotic assembly lines in quick-service restaurants require dimensional precision and tamper-evident features that thermoformed lids provide, driving volume specifications for dome and flat formats.
- Cold-chain retail expansion:Supermarket deli and prepared-meal sections in Germany and the United States are scaling MAP-compatible lid procurement to extend shelf life and reduce food waste.
Market Restraints
- Resin price volatility:Polypropylene and PET feedstock costs fluctuate with crude oil and paraxylene markets, compressing converter margins and complicating annual contract pricing with food brands.
- Recycling infrastructure gaps:Mixed-waste streams in the United States lack uniform sorting capabilities for black thermoformed PET, limiting closed-loop supply claims despite material recyclability.
- Competing formats:Injection-molded lids with integrated snap features threaten flat lid segments where premium sealing performance commands price premiums.
Strategic Opportunities
- Indian foodservice growth:Quick-service restaurant chains and cloud kitchens in Mumbai and Bangalore are adopting Western-format packaging, creating first-mover advantage for thermoformed lid suppliers establishing local thermoforming capacity.
- California recycled content mandates:SB 54 thresholds escalate through 2030, positioning post-consumer rPET lid producers to capture preferential procurement from brands with West Coast distribution.
- Smart packaging integration:RFID-enabled lids for pharmaceutical cold-chain tracking combine thermoforming with printed electronics, opening medical-device adjacent revenue pools.
Industry Challenges
- Thermoforming tool lead times:Custom aluminum molds for complex geometries require 12-16 week fabrication cycles, constraining rapid product development for seasonal food promotions.
- Multi-jurisdictional compliance:Suppliers serving both EU and US markets must maintain parallel material certifications under REACH and FDA 21 CFR 177, duplicating testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoformed Lids Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Lids, Dome Lids, Custom Lids, Specialty Lids Material: Polypropylene, PET, PVC, PS End User: Food Packaging, Medical Devices, Consumer Goods, Industrial Applications Feature: Recyclable, Tamper-Evident, Airtight, UV-Resistant |
| Companies Covered | Amcor plc, Berry Global Group, Inc., Sonoco Products Company, Sealed Air Corporation, Huhtamaki Oyj, Pactiv Evergreen Inc., WestRock Company, Display Pack, Inc., Placon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoformed Lids Market Strategic Shifts
Active packaging functionality and circular material flows are restructuring competitive advantage away from commodity volume toward certified sustainability credentials and precision engineering capabilities.
rPET sheet extrusion with optical brightener elimination is electrifying food-contact applications by delivering clarity and mechanical properties matching virgin resin. Major quick-service brands in the United States and Germany have specified rPET lids in procurement tenders released since 2023. This material transition is compressing virgin PET resin demand while fragmenting supplier bases between integrated recyclers and conventional converters.
California's SB 54 mandates 30% recycled content thresholds by 2028, escalating to 65% by 2032 for plastic packaging. Thermoformed lid producers serving the US West Coast are reformulating material portfolios and securing post-consumer flake supply agreements. The regulation most directly affects flat lid segments where cost minimization previously favored virgin polystyrene.
Direct procurement relationships between food brands and specialized thermoformers are displacing distributor intermediaries in premium segments. Large bakery and deli chains now specify lid geometry, material grade, and recycling compatibility in master service agreements rather than accepting distributor-assigned stock. This channel compression concentrates most visibly in Germany's organized retail sector and US coastal metropolitan markets.
Thermoformed Lids Market Segmentation
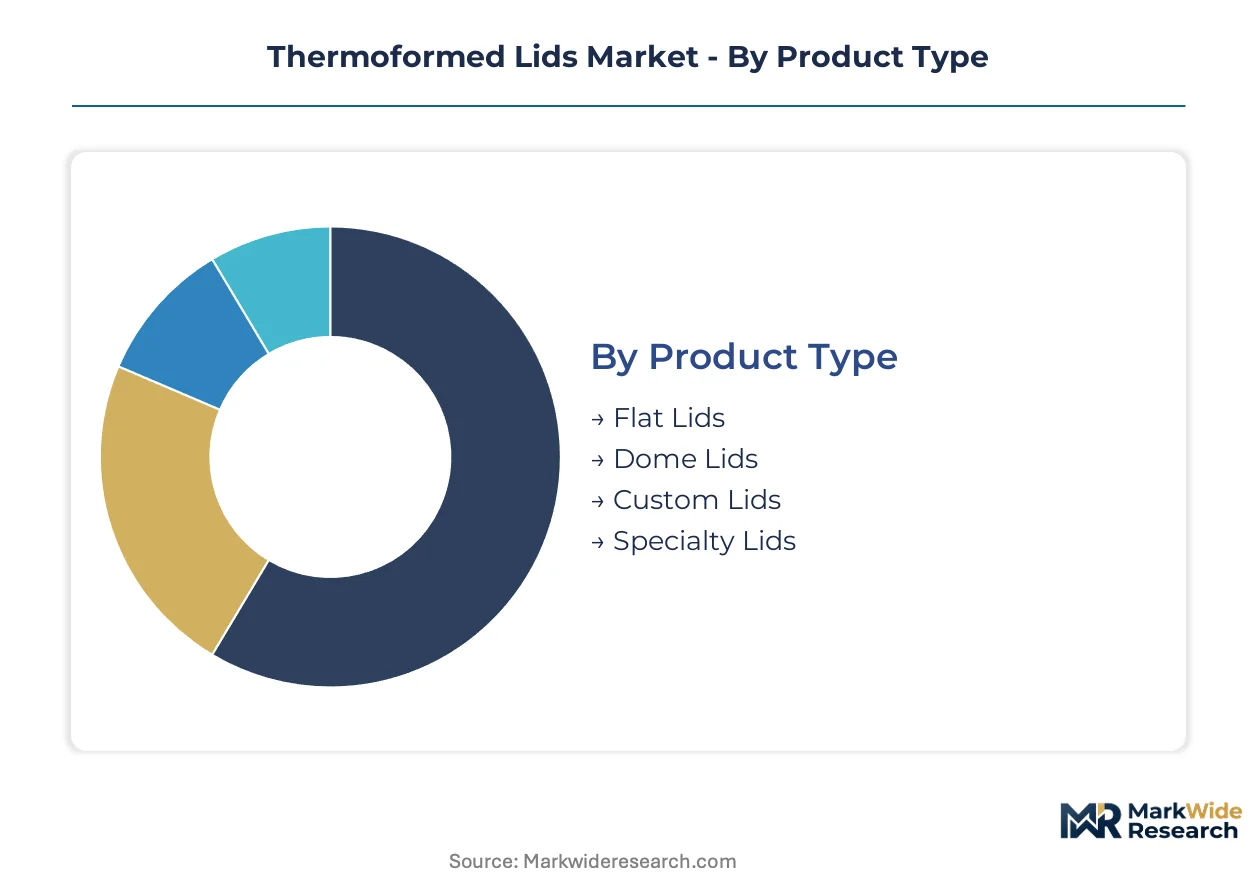
Thermoformed lid procurement varies sharply by application requirements and regulatory exposure. Buyers prioritize material compliance, dimensional precision, or cost minimization depending on end-use context. Segmentation reveals where margin pools concentrate versus where volume commoditization dominates.
Product Type:
Cost tier determines supplier selection more than any other factor across foodservice and retail channels.
- Flat Lids:Thin-gauge polystyrene or polypropylene constructions dominate quick-service restaurant and supermarket deli applications where unit cost minimization governs procurement. Demand concentrates in the United States and Germany, where high-volume foodservice automation requires consistent stacking geometry and reliable heat-seal compatibility with PP trays.
- Dome Lids:Vacuum-formed PET or clear PP structures provide headspace for frosted bakery items and stacked prepared meals while maintaining visual product presentation. Cold-chain retail expansion in Germany and California is accelerating dome lid specifications for MAP-compatible applications requiring extended shelf life.
- Custom Lids:Engineered geometries with integrated snap-fit or threaded closures serve medical device and pharmaceutical packaging where dimensional tolerances are specified.
- Specialty Lids:Modified atmosphere and anti-fog surface treatments target premium food retail segments in European bakery and deli channels.
Volume sits with flat lids across commodity foodservice; growth tilts toward dome lids as cold-chain retail formats expand.
Material:
Regulatory pressure on recyclability is restructuring procurement specifications across all end-use categories.
- PET:Virgin and recycled grades deliver optical clarity, mechanical strength, and established recycling infrastructure compatibility that satisfies EU Single-Use Plastics Directive requirements. Food brands in Germany and California have specified rPET content thresholds in procurement tenders, displacing PVC and PS in flat and dome lid applications.
- Polypropylene:High melt-flow homopolymer and copolymer grades offer heat resistance for hot-fill applications and microwaveable ready-meal packaging. Quick-service chains in the United States specify PP lids for soup and hot beverage formats where dimensional stability at elevated temperatures is required.
- PVC:Phthalate plasticizer restrictions under EU REACH and FDA scrutiny are compressing food-contact applications to specialized industrial uses.
- PS:Expanded and crystal grades face bans under EU Single-Use Plastics Directive and California SB 54 recycled content mandates, limiting growth to non-food industrial segments.
PET captures the steepest expansion trajectory as recyclability becomes a contractual requirement; polypropylene defends position in heat-resistant applications.
End User:
Application maturity and margin structure vary dramatically across customer categories.
- Food Packaging:Ready-to-eat meals, fresh produce, and bakery applications drive the highest absolute volume with standardized geometries and high production runs.
- Medical Devices:Sterile barrier systems and pharmaceutical cold-chain packaging command premium pricing for validated manufacturing processes and lot traceability.
- Consumer Goods:Cosmetic and personal care applications require decorative finishing and custom color matching with lower volume per SKU.
- Industrial Applications:Chemical and automotive component packaging prioritizes chemical resistance and structural rigidity over optical properties.
Food packaging anchors current volume; medical devices offer the most favorable margin expansion potential.
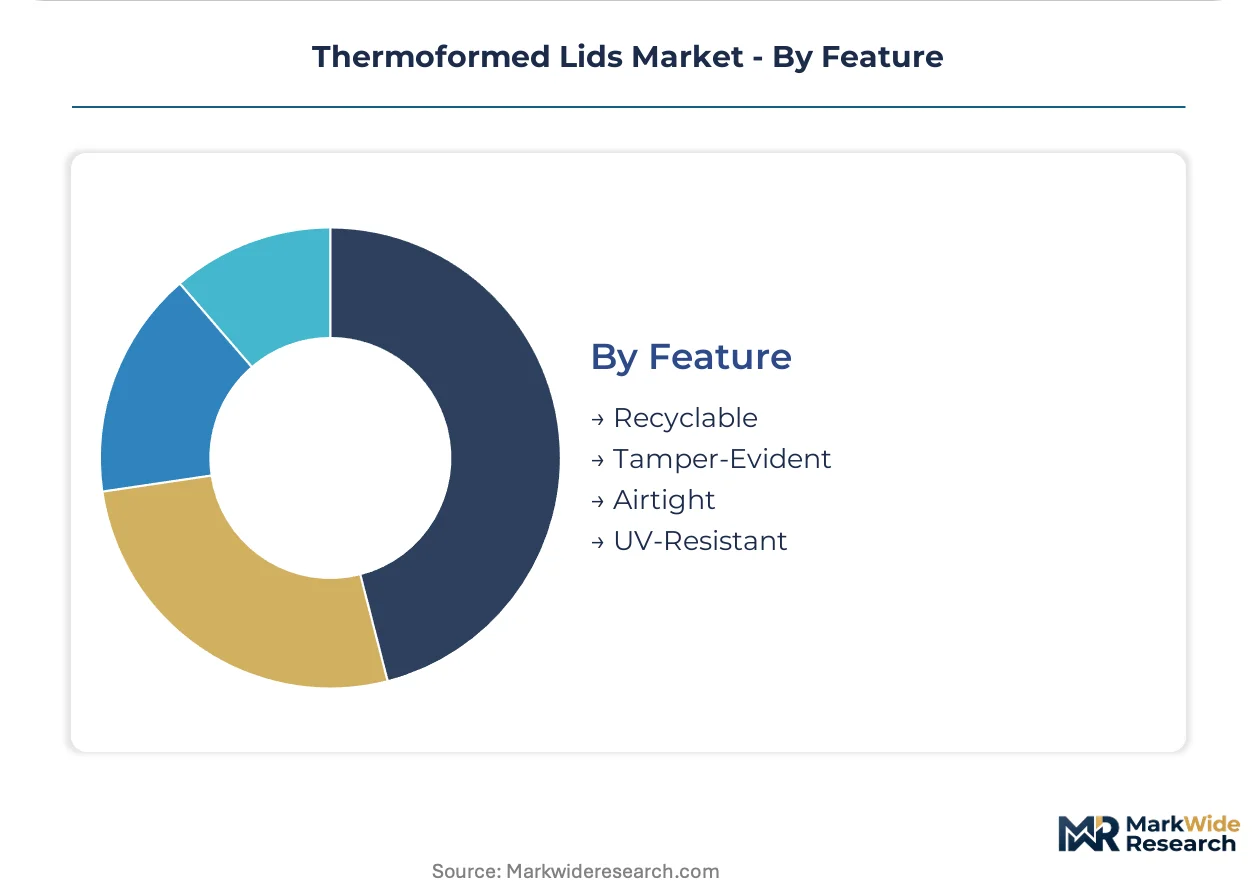
Feature:
Functional differentiation increasingly determines supplier selection in premium segments.
- Recyclable:Design-for-recycling standards and post-consumer content certification are becoming mandatory in EU and California procurement specifications.
- Tamper-Evident:Break-tab and shrink-band integrations protect pharmaceutical and high-value food applications against contamination and diversion.
- Airtight:Modified atmosphere compatibility extends shelf life for fresh protein and prepared meal applications in German and US retail.
- UV-Resistant:Stabilized PET and PP formulations protect light-sensitive pharmaceuticals and nutraceuticals during distribution.
Recyclable features are becoming baseline requirements; tamper-evident integration commands the strongest price premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermoformed lid production concentrates in Germany, China, and the United States, while consumption spreads across developed foodservice markets with diverging regulatory timelines on recyclability mandates.
United States
Quick-service restaurant automation and cold-chain retail expansion in California and New York drive dome and flat lid procurement. California's SB 54 mandates escalating recycled content thresholds through 2032, forcing material reformulation toward rPET. The Midwest manufacturing corridor around Chicago anchors high-volume thermoforming capacity serving national foodservice distribution networks.
Germany
Organized retail chains and bakery-delicatessen formats in Munich and Hamburg specify MAP-compatible dome lids for extended shelf-life prepared meals. The EU Single-Use Plastics Directive and F-Gas Regulation restrict polystyrene and mandate design-for-recycling standards. Bavaria's packaging machinery cluster supplies precision thermoforming equipment across European converter networks.
China
Food delivery platform growth in Shanghai and Beijing accelerates disposable lid consumption for ready-to-eat formats. The country's national standards regulator enforces food-contact safety protocols under GB standards while local governments pilot extended producer responsibility schemes. The Yangtze River Delta region hosts integrated resin-to-converter operations serving domestic quick-service chains.
India
Cloud kitchen proliferation in Mumbai and Bangalore adopts Western-format packaging for premium food delivery segments. The Food Safety and Standards Authority of India regulates food-contact materials while import duties on virgin resin shape local sourcing decisions. Gujarat's petrochemical corridor supplies polypropylene feedstock to emerging thermoforming operations targeting foodservice growth.
Japan
Convenience store chains in Tokyo and Osaka maintain stringent specifications for tamper-evident and airtight lid functionality in bento and prepared meal applications. The Ministry of Economy, Trade and Industry promotes plastic recycling infrastructure investment under circular economy targets. The Kansai industrial region hosts specialized converters serving pharmaceutical and premium food packaging segments.
Thermoformed Lids Market Competitive Environment
The competitive structure tilts toward integrated multinational packaging conglomerates with captive resin sourcing and high-volume thermoforming infrastructure. Three archetypes dominate: vertically integrated resin-to-converter operators controlling cost variability, regional specialists capturing premium niches through custom geometry capabilities, and diversified packaging groups leveraging cross-selling into foodservice accounts. Capacity expansion and material portfolio diversification toward rPET represent the dominant competitive moves as regulatory deadlines approach.
Among integrated packaging conglomerates, Amcor plc exemplifies the resin-sourcing archetype through backward integration into polymer supply chains. Berry Global Group, Inc. and Huhtamaki Oyj occupy positions within the high-volume converter tier, with the latter representing specialty design capabilities tailored to European bakery and deli specifications. These three entities anchor the competitive landscape by demonstrating how scale and material control differentiate procurement positioning across diverging regulatory environments.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Group, Inc. |
| Sonoco Products Company |
| Sealed Air Corporation |
| Huhtamaki Oyj |
| Pactiv Evergreen Inc. |
| WestRock Company |
| Display Pack, Inc. |
| Placon Corporation |
| Others |
Value Chain & Pricing Dynamics
rPET sheet extrusion technology adoption is compressing virgin resin premiums while concentrating procurement leverage among integrated recyclers who control flake-to-sheet conversion. This production-method transition simultaneously elevates capital barriers for conventional converters and shifts pricing power toward suppliers with backward integration into post-consumer collection networks.
Pricing Analysis
Cost-down pressure on flat lid tiers accelerates because California SB 54 mandates and EU Single-Use Plastics Directive compliance costs are being absorbed by converters rather than passed through to foodservice buyers. Pricing stratifies across premium custom lids, standard dome formats, and economy flat lids, with differentiation driven by rPET certification grade and volume scale. Quick-service restaurant chains exhibit highest price sensitivity, while pharmaceutical and medical device buyers prioritize dimensional precision over unit cost.
Supply Chain Analysis
Transoceanic freight rate volatility shapes raw material landed costs for European and North American converters sourcing virgin PET and polypropylene from Gulf Coast and Middle Eastern petrochemical complexes. Supply concentrates in Germany, the United States, and China, with resin feedstock dependencies on paraxylene and propylene monomer markets. Single-source vulnerability around specialized thermoforming tool fabrication in Bavaria and Chicago creates bottlenecks for custom geometry orders. Distribution runs through direct procurement relationships between food brands and converters, displacing distributor intermediaries in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoformed lid production is transitioning from virgin polystyrene commodity supply to rPET circular material systems, with regulatory deadlines forcing capital reallocation toward recycling infrastructure and optical brightener elimination capabilities.
For Market Incumbents: Deploy captive rPET flake supply agreements to defend margin position against resin price volatility and emerging recycler competition. Integrate thermoforming operations with post-consumer collection partnerships in California and Germany to secure preferential procurement from brands facing SB 54 and EU Single-Use Plastics Directive deadlines. Add precision tooling capacity in Bavaria to capture medical device lid specifications.
For New Entrants and Emerging Players: Capture cloud kitchen lid demand in Mumbai and Bangalore by establishing local thermoforming capacity with PP heat-resistant formulations for hot-fill applications. Target Indian quick-service chains with Western-format dome and flat lid geometries specified by multinational franchise operators. Partner with Gujarat petrochemical suppliers to secure polypropylene feedstock cost advantages against import-dependent competitors.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of specialized European converters with MAP-compatible dome lid capabilities and FDA 21 CFR 177 certifications. Long-term viability favors integrated operators with rPET sheet extrusion and food-contact validation expertise rather than commodity polystyrene-dependent assets. Monitor California SB 54 enforcement actions as inflection indicator for rPET procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| rPET Sheet Extrusion Capacity Expansion | Captures California SB 54 and EU directive compliance premiums from food brands. |
| Backward Integration into Flake Supply | Secures post-consumer feedstock against resin price volatility and supply interruptions. |
| Precision Tooling Investment | Enters medical device and pharmaceutical lid segments with dimensional tolerance requirements. |
| Geographic Manufacturing Footprint | Establishes local thermoforming in India to serve cloud kitchen and quick-service growth. |
| Direct Brand Procurement Relationships | Displaces distributor intermediaries and captures specification influence in premium segments. |
Study Parameters
Trade databases, regulatory filings, and industry association reports formed the secondary backbone, supplemented by primary interviews with thermoforming plant managers, food brand procurement leads, packaging machinery engineers, and resin distribution specialists. Bottom-up volume modeling across product type, material grade, end-use application, and geographic market triangulated against top-down macroeconomic indicators to establish market sizing.
Historical trendline analysis of foodservice automation adoption, cold-chain retail expansion, and regulatory implementation timelines informed projection assumptions across the modeling period. Segmentation dimensions included lid geometry category, substrate material, end-use vertical, functional feature integration, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating rPET substitution rates and tooling capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to recycling infrastructure buildout pace and resin feedstock price volatility. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging
Global Plastic Container Market
Packaging
Disposable Plastic Pallet Market
Packaging
Global Pressure Labels Market
Packaging
Plastic Toilet Paper Dispenser Market
Packaging
Vinyl Electrical Tapes Market
Packaging
Mattress and Furniture Bags Market
Packaging
Pre-Assembled Packaging Market
Packaging
Global Thermoplastic Films Market
Packaging
MENA Industrial Packaging Market
Packaging
Pharmaceuticals Pouch Market
Packaging
MDO-PE Films Market
Packaging
Cutterbox Films Market
Packaging
Polybag Mailers Market
Packaging
France Glass Packaging Market
Packaging
Beauty Supplements Packaging Market
Packaging
Burger Boxes Market