
 Compartment Take-Out Container Market | 2026-2036
Compartment Take-Out Container Market Size, Share, and Industry Trends Forecast 2026-2036
Compartment Take-Out Container Market Outlook
Cloud kitchens and ghost kitchen operators are reorganizing demand patterns for compartment take-out containers, shifting volume away from traditional dine-in establishments toward delivery-optimized formats. Dart Container Corporation sustains manufacturing scale across multiple substrate categories, from foam to molded fiber. Huhtamaki Oyj anchors its position through geographic breadth and sustainability-certified product lines. Pactiv LLC competes aggressively in the premium tamper-evident and compostable closure segments.
A compartment take-out container is a multi-cavity foodservice vessel engineered to separate menu components during transport, typically manufactured through thermoforming, injection molding, or pressed-fiber processes with wall thicknesses calibrated for heat retention and structural integrity under load. The primary commercial purpose is to preserve food presentation quality, temperature differentials, and portion control across off-premise consumption channels. Plastic and biodegradable materials are diverging in growth trajectory, with biodegradable formulations capturing premium positioning as operators face extended producer responsibility frameworks. Rectangular and square shapes dominate operational efficiency in bagging and stacking logistics, while tamper-evident closures command margin premiums in healthcare and institutional channels.
The FDA governs food-contact substance compliance in the United States, while the EU REACH regulation and F-Gas framework constrain certain polymer chemistries and foaming agents in European production. California's SB 54 and Canada's proposed single-use plastics restrictions are cascading into supplier qualification requirements and material substitution timelines. Stakeholders must monitor evolving state-level packaging EPR legislation and certify fiber sourcing through FSC or SFI chain-of-custody protocols to maintain channel access.
Market Dynamics
Cloud kitchens and third-party delivery platforms are reorganizing procurement patterns for compartment take-out containers, pulling volume away from traditional dine-in establishments toward delivery-optimized formats that demand superior thermal retention and structural integrity during transport.
Growth Catalysts
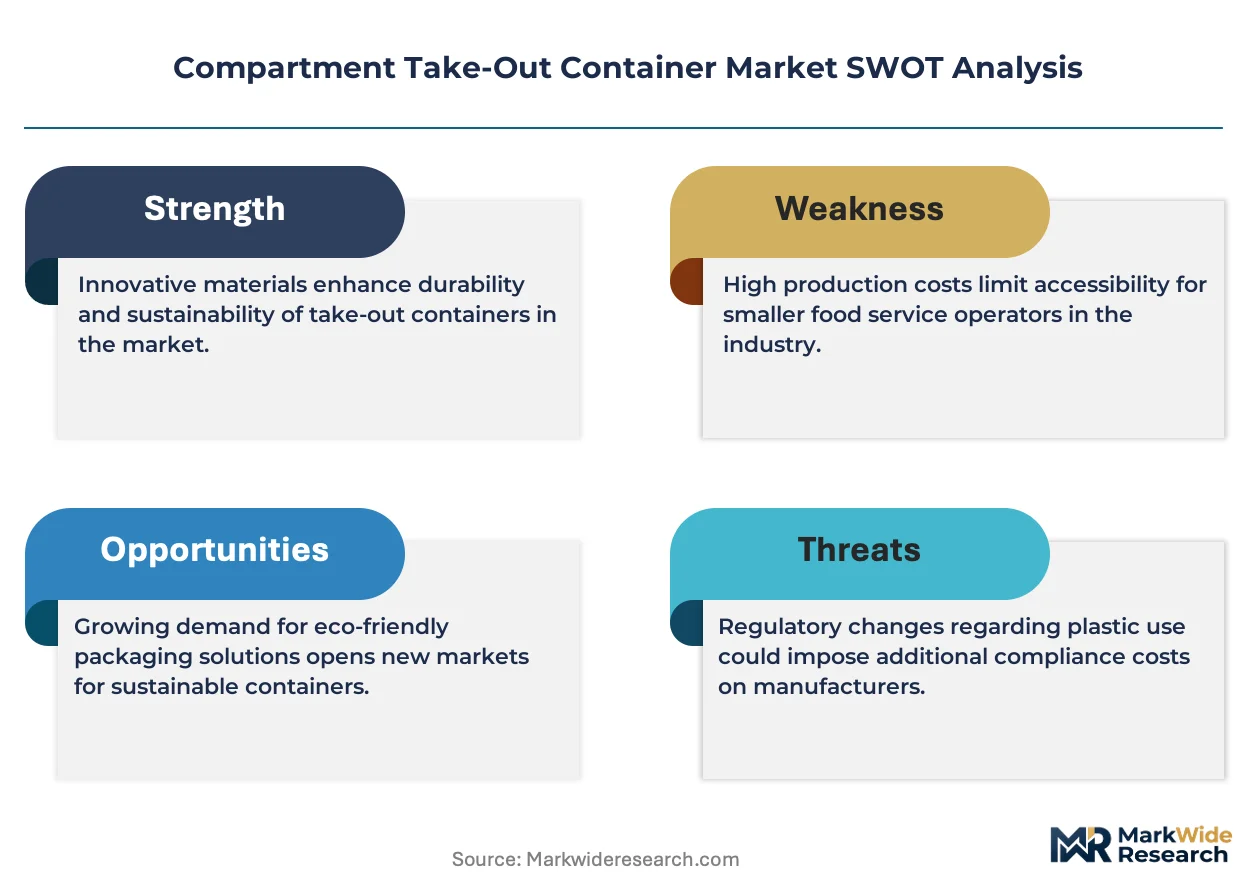
- EU Single-Use Plastics Directive:This framework accelerates material substitution timelines across European foodservice operations, creating immediate pull-through for fiber-based and biodegradable alternatives in quick-service and institutional channels.
- Cloud kitchen proliferation:Ghost kitchen operators in the United States are standardizing multi-cavity container specifications to preserve food presentation quality across extended delivery windows, concentrating procurement at specialized distributors.
- Pressed-fiber molding advances:Improvements in pulp processing and heat-press automation are lowering unit costs for molded fiber containers, enabling competitive displacement of conventional plastics in mid-tier foodservice segments.
Market Restraints
- Pulp fiber cost volatility:Agricultural residue and recycled paper feedstock prices fluctuate with weather patterns and Chinese import policies, compressing margins for biodegradable container manufacturers without long-term supply contracts.
- Technical performance gaps:Molded fiber and bioplastic alternatives exhibit inferior grease resistance and heat retention compared to polypropylene and expanded polystyrene, limiting adoption in high-temperature sauce and fried food applications.
- Extended producer responsibility frameworks:California's SB 54 and Canada's proposed single-use plastics restrictions impose compliance costs and material certification burdens that smaller regional converters struggle to absorb.
Strategic Opportunities
- Healthcare and institutional channels:Hospitals, senior living facilities, and correctional institutions require tamper-evident, portion-controlled meal delivery systems where premium pricing tolerates higher material costs for certified compostable or recyclable formats.
- Smart packaging convergence:Integration of RFID tags and temperature-sensitive inks with compartment containers enables real-time tracking and quality verification for high-value prepared meal subscriptions and pharmaceutical foodservice.
- India's organized foodservice expansion:Quick-service restaurant chains and centralized kitchen operators in Mumbai, Bangalore, and Delhi are scaling standardized container programs as delivery penetration accelerates in tier-1 and tier-2 cities.
Industry Challenges
- FSC and SFI chain-of-custody certification:Fiber sourcing documentation requirements for European and North American buyers demand specialized procurement staff and supplier audit capabilities that mid-tier converters lack.
- Thermoforming tooling capex cycles:Transition from polystyrene to crystallized PLA or PP alternatives requires mold redesign and press reconfiguration, straining capital allocation for manufacturers serving price-sensitive casual dining segments.
- Legacy ERP integration with traceability systems:Batch-level material tracking for regulatory compliance conflicts with existing inventory management platforms, forcing expensive middleware development or system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compartment Take-Out Container Market |
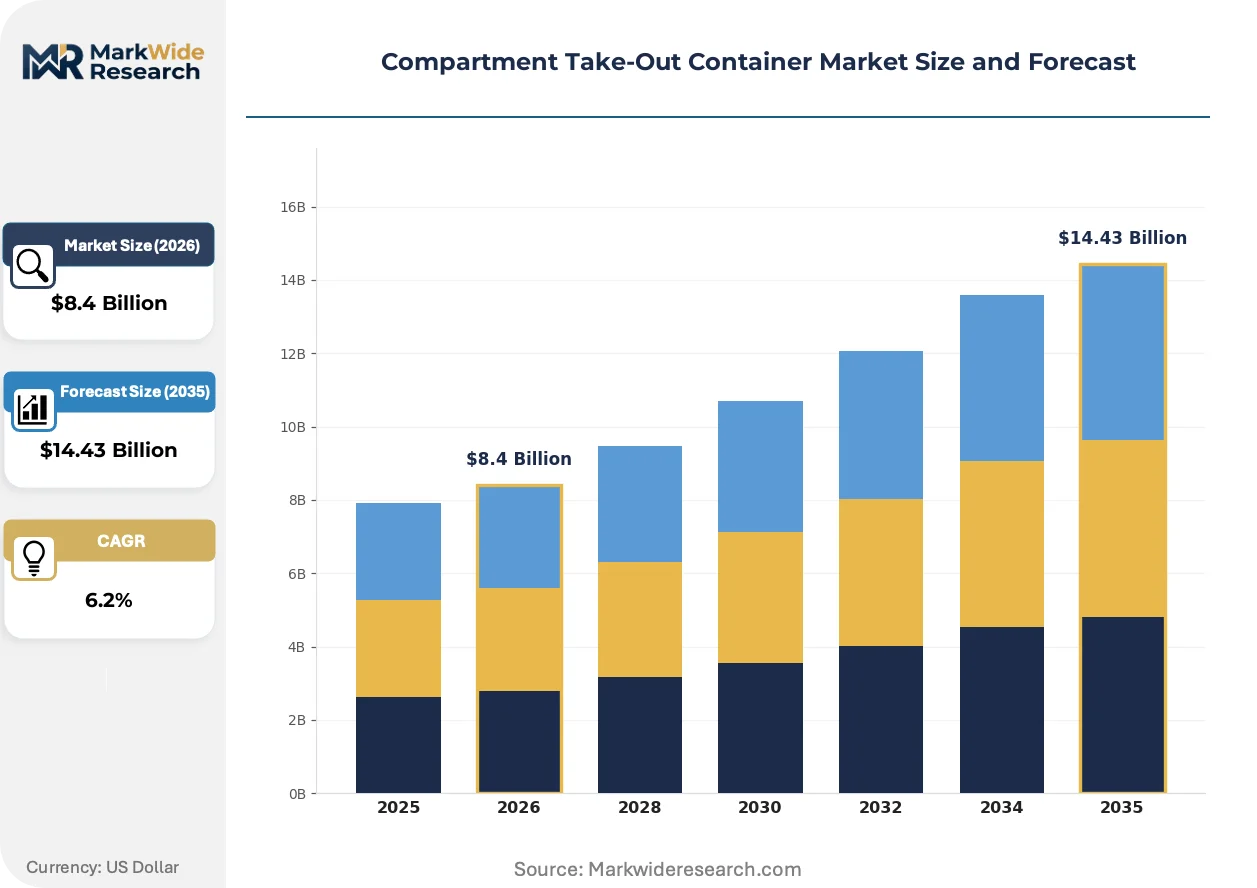
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Foam, Aluminum, Biodegradable Shape: Round, Square, Rectangular, Triangular Size: Small, Medium, Large, Extra Large Closure Type: Lid, Snap-on, Tamper-evident, Compostable |
| Companies Covered | Dart Container Corporation, Huhtamaki Oyj, Pactiv LLC, Genpak LLC, Georgia-Pacific LLC, Sabert Corporation, Anchor Packaging Inc., Biopac India Corporation, Landaal Packaging Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compartment Take-Out Container Market Strategic Shifts
Material science breakthroughs and regulatory pressure are compressing traditional substrate hierarchies, while digital ordering infrastructure reshapes how container specifications propagate through foodservice supply chains.
Pressed-fiber and agricultural residue composites are fragmenting the conventional plastic-dominated container landscape by delivering structural performance approaching thermoformed polymers at competitive unit economics. Quick-service chains with aggressive sustainability commitments are piloting these materials in limited menu categories before system-wide rollout. The resulting substrate diversification is fragmenting supplier relationships as operators qualify multiple material platforms rather than single-source dependence.
REACH regulation constraints on specific polymer chemistries and the EU F-Gas framework limiting foaming agents are forcing European manufacturers toward water-based forming processes and alternative blowing agents. Industrial consequence includes accelerated R&D spending on fiber-based insulation layers and double-wall constructions that replicate foam performance without prohibited inputs. Foodservice operators in Germany, France, and the Netherlands are responding by consolidating procurement around converters with verified regulatory compliance documentation.
Centralized procurement through third-party delivery platforms is compressing buyer fragmentation as DoorDash, Uber Eats, and regional aggregators negotiate container specifications on behalf of thousands of independent restaurants. This channel consolidation displaces traditional broadline distributor relationships and shifts specification authority toward platform-employed supply chain engineers. The phenomenon is most visible in United States metropolitan markets where platform-mediated delivery exceeds thirty percent of off-premise foodservice volume.
Compartment Take-Out Container Market Segmentation
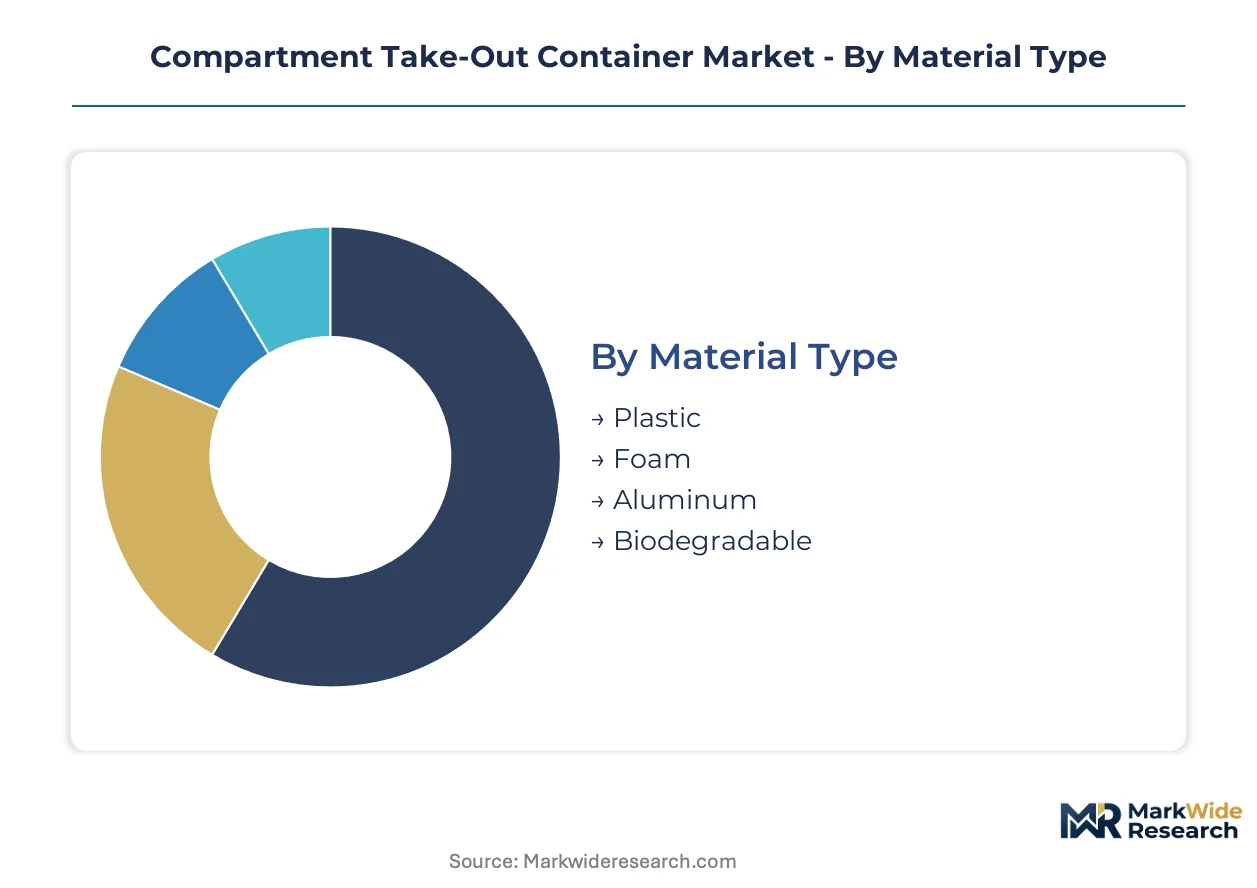
Compartment take-out container specifications fragment across material chemistry, dimensional geometry, and security features. Procurement decisions at cloud kitchen operators and institutional foodservice chains cascade through these segment boundaries, reshaping supplier qualification requirements and volume concentration patterns.
Material Type:
Domestic manufacturing capacity concentrates in plastic and foam substrates across the United States, while biodegradable alternatives draw heavily on European and Asian import supply chains for pulp fiber feedstocks.
- Plastic:Polypropylene and crystallized PLA formulations dominate quick-service restaurant procurement through thermoforming and injection molding processes. United States-based chains specify these materials for grease resistance and microwave compatibility, though California SB 54 compliance timelines are forcing accelerated substitution trials.
- Biodegradable:Molded fiber and agricultural residue composites capture premium positioning at healthcare and corporate catering operators with certified composting infrastructure. European demand, particularly in Germany and France, concentrates procurement around converters with ECHA REACH documentation and FSC chain-of-custody certification.
- Foam:Expanded polystyrene retains cost-sensitive casual dining volume in regions without single-use plastics restrictions.
- Aluminum:Foil-based compartment trays serve high-temperature applications and airline catering channels.
Plastic commands the established base. The steepest expansion runs through biodegradable.
Shape:
Operational efficiency in automated bagging and stacking systems favors angular geometries, while round formats retain niche positioning in ethnic cuisine and premium meal kit applications.
- Rectangular:Standardized dimensions optimize pallet utilization and third-party delivery platform logistics across United States metropolitan markets. Cloud kitchen operators in New York, Los Angeles, and Chicago specify these formats for conveyor compatibility and thermal bag packing density.
- Square:Modular footprint enables nested storage and portion-scaling flexibility for institutional meal prep operations. Hospital and correctional facility foodservice contractors in Texas, Florida, and Pennsylvania consolidate procurement around these specifications for inventory simplification.
- Round:Curved walls suit bowl-based menu categories and Asian cuisine delivery formats.
- Triangular:Specialized geometry addresses corner-fit applications and novelty presentation requirements.
Rectangular formats anchor current volume. Square configurations are gaining share fastest in institutional channels.
Size:
Portion control standardization at quick-service chains compresses SKU proliferation, though healthcare and senior living operators demand expanded size ranges for therapeutic diet differentiation.
- Medium:Single-entrée specifications satisfy the core transaction volume at burger, sandwich, and bowl concepts across United States drive-thru and delivery channels. National chain operators standardize around this tier to reduce distributor complexity and inventory carrying costs.
- Large:Family-style and catering formats capture bulk meal occasions and workplace lunch programs. Corporate foodservice contractors in Atlanta, Dallas, and Seattle specify these dimensions for group ordering platforms and conference meal delivery.
- Small:Snack and children's menu portions address downsized meal occasions.
- Extra Large:Bulk catering and institutional tray service applications require reinforced wall construction.
Medium sizes dominate transaction economics. Large formats are expanding most quickly in corporate catering.
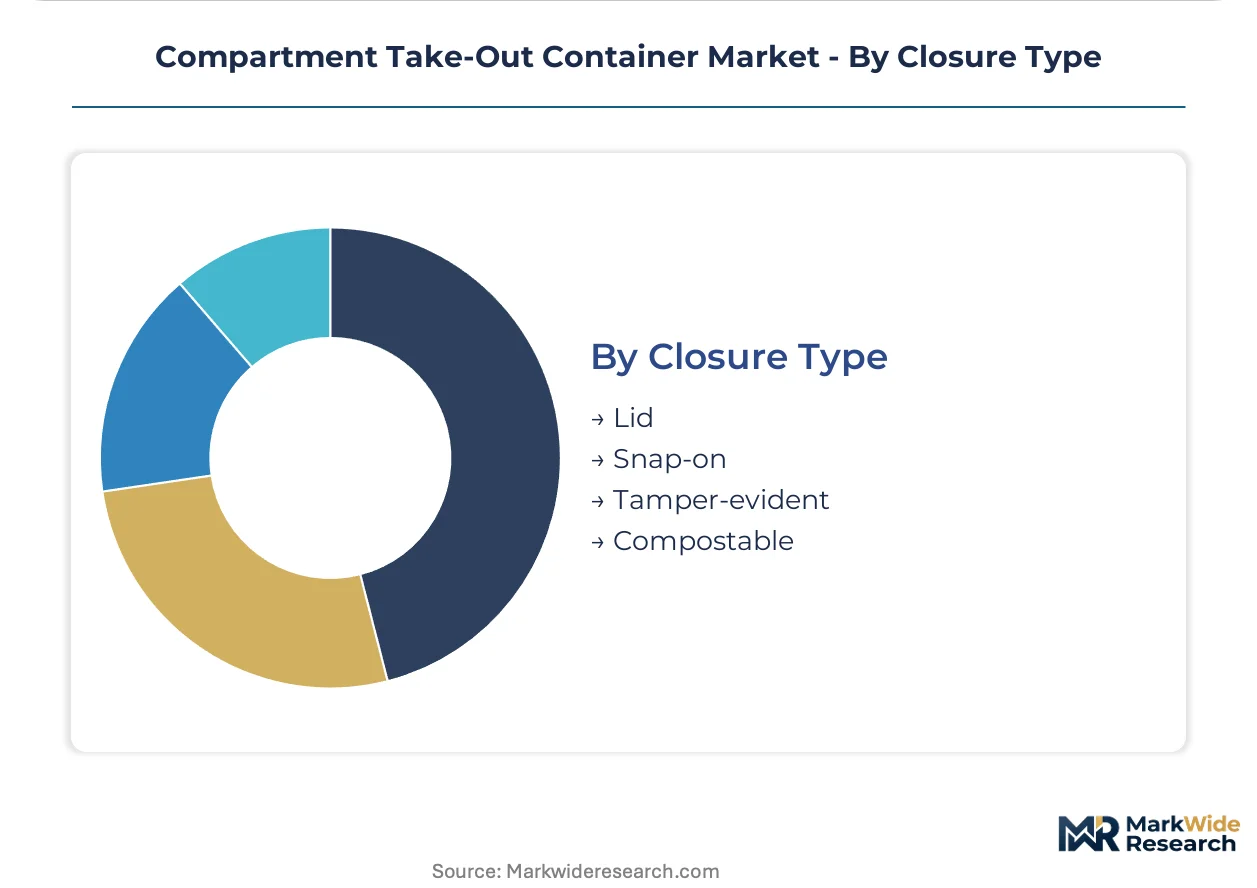
Closure Type:
Security and sustainability certifications fragment procurement authority between operations teams seeking logistics efficiency and compliance officers managing regulatory documentation.
- Tamper-evident:Mechanical or adhesive security features satisfy healthcare, pharmaceutical foodservice, and high-value meal subscription requirements. Hospital systems in California, Massachusetts, and Ohio mandate these specifications for patient safety protocols and liability risk mitigation.
- Compostable:Bio-based lid formulations align with corporate sustainability commitments and municipal composting infrastructure availability. University and corporate campus dining operators in Washington, Oregon, and Vermont concentrate procurement here to meet zero-waste targets.
- Lid:Conventional snap-fit covers retain broadline distributor volume in price-sensitive segments.
- Snap-on:Press-fit designs balance security with operational speed in high-volume quick-service environments.
Lid and snap-on formats retain the installed base. Tamper-evident specifications are climbing the fastest in regulated channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput infrastructure underwrites European supply chain access for molded fiber feedstocks, while the Port of Los Angeles anchors trans-Pacific resin imports serving North American thermoforming operations.
United States
Quick-service restaurant chains and cloud kitchen operators in New York, Los Angeles, and Chicago are standardizing multi-cavity container specifications for delivery-optimized formats. The FDA governs food-contact substance compliance, while California's SB 54 imposes extended producer responsibility frameworks with material substitution timelines. Georgia-Pacific LLC maintains manufacturing presence across the Southeast, supplying institutional foodservice contractors with fiber-based alternatives.
Germany
Healthcare and senior living facility operators in Berlin, Munich, and Hamburg concentrate procurement around tamper-evident, portion-controlled meal delivery systems. The EU REACH regulation and F-Gas framework constrain specific polymer chemistries and foaming agents in domestic production. The Rhine-Ruhr industrial corridor hosts converters specializing in double-wall fiber constructions that replicate foam performance without prohibited inputs.
China
Pressed-fiber molding equipment manufacturers in the Yangtze River Delta are lowering unit costs for molded fiber containers through heat-press automation advances. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate water-based forming process adoption. Zhejiang and Jiangsu province clusters export agricultural residue composites to European quick-service chains with aggressive sustainability commitments.
India
Quick-service restaurant chains and centralized kitchen operators in Mumbai, Bangalore, and Delhi are scaling standardized container programs as delivery penetration accelerates in tier-1 and tier-2 cities. The Food Safety and Standards Authority of India regulates food-contact materials, while the Production Linked Incentive scheme supports domestic manufacturing capacity. Biopac India Corporation anchors local supply of biodegradable alternatives for corporate catering and institutional channels.
Canada
Healthcare foodservice contractors in Toronto, Vancouver, and Montreal mandate certified compostable formats for patient meal delivery and liability risk mitigation. Health Canada and the proposed single-use plastics restrictions cascade into supplier qualification requirements and material certification timelines. Ontario-based converters are qualifying fiber sourcing through FSC chain-of-custody protocols to maintain channel access across provincial healthcare procurement systems.
Compartment Take-Out Container Market Competitive Environment
Concentration sits with diversified packaging conglomerates and specialized foodservice converters. Three to five integrated manufacturers control substrate technology and geographic breadth, while mid-tier regional converters compete on customization speed and local distribution relationships. Strategic archetypes include scale-driven substrate generalists, sustainability-certified specialists, and healthcare-focused security-format providers. Competitive moves center on capacity expansion in molded fiber automation and strategic partnerships with third-party delivery platforms for specification consolidation.
Among North American-based fabricators, Dart Container Corporation and Pactiv LLC exemplify the scale-driven substrate generalist archetype, spanning foam through compostable closures. Huhtamaki Oyj represents the geographic breadth model with sustainability-certified product lines anchoring European regulatory compliance. These three occupy positions across the premium tamper-evident, institutional healthcare, and cloud kitchen procurement channels without single-source dependence.
| Leading Market Players |
|---|
| Dart Container Corporation |
| Huhtamaki Oyj |
| Pactiv LLC |
| Genpak LLC |
| Georgia-Pacific LLC |
| Sabert Corporation |
| Anchor Packaging Inc. |
| Biopac India Corporation |
| Landaal Packaging Systems |
| Others |
Value Chain & Pricing Dynamics
FSC and SFI chain-of-custody certification gates supplier qualification in European and North American procurement systems while simultaneously enabling price premiums for documented fiber sourcing. This dual function compresses margins for uncertified converters and concentrates pricing power among integrated manufacturers with captive pulp supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale. Premium tiers capture healthcare and institutional channels demanding tamper-evident compostable formats with full chain-of-custody documentation. Cost compression in economy foam and conventional plastic segments is intensifying because Chinese resin import policies and agricultural residue price volatility squeeze converter margins. Quick-service restaurant chains exhibit highest price sensitivity, while hospital systems tolerate material cost premiums for liability mitigation.
Supply Chain Analysis
Just-in-time inventory strategies dominate quick-service procurement, though institutional contractors maintain strategic stockpiles of certified compostable formats to ensure continuity under supply disruption. Feedstock supply concentrates in China, the United States, and Brazil for pulp fiber, petroleum-derived resins, and agricultural residue respectively. Raw material dependencies include recycled paper pulp, polypropylene resin, and bagasse fiber. Single-source vulnerability runs through Yangtze River Delta pressed-fiber equipment manufacturers. Distribution runs through broadline foodservice distributors and third-party delivery platform consolidation hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pressed-fiber molding automation and extended producer responsibility frameworks are compressing traditional substrate hierarchies faster than incumbent cost structures can absorb. This technological-regulatory inflection creates asymmetric opportunity for positioned operators.
For Market Incumbents: Consolidate molding capacity in the United States Southeast and Midwest to capture cloud kitchen volume concentration while accelerating FSC certification coverage across fiber supply basins. Defensive capacity addition in molded fiber automation offsets polystyrene substitution risk from California SB 54 compliance timelines.
For New Entrants and Emerging Players: Lead with tamper-evident compostable formats in Canadian and German healthcare procurement channels where certification barriers filter incumbent competition. White-space concentration sits in Indian tier-2 city cloud kitchen infrastructure and European double-wall fiber insulation layers replicating foam performance.
For Investors and Strategic Acquirers: California SB 54 implementation reshapes the acquisition landscape toward converters with verified regulatory compliance documentation and established healthcare channel relationships. Long-term viability centers on fiber-based substrate technology with defensible certification moats. Watch for platform-mediated delivery volume exceeding critical thresholds in metropolitan markets as inflection signal for specification consolidation plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Molded Fiber Capacity Expansion | Captures substitution demand from polystyrene restrictions in California and Canadian healthcare systems. |
| FSC Chain-of-Custody Certification | Unlocks European quick-service procurement and institutional channel access at premium pricing tiers. |
| Third-Party Delivery Platform Partnership | Consolidates specification authority across thousands of independent restaurant operators. |
| Backward Integration into Pulp Supply | Insulates margins from agricultural residue price volatility and Chinese import policy shifts. |
| Tamper-Evident Format Development | Addresses healthcare liability protocols and pharmaceutical foodservice quality verification requirements. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with foodservice procurement directors, cloud kitchen supply chain engineers, molded fiber plant managers, and institutional foodservice contractors. Secondary validation drew from FDA food-contact substance filings, ECHA REACH registration databases, FSC chain-of-custody audit records, and trade flow data for pulp fiber and resin imports. Bottom-up volume modeling triangulated against top-down market sizing across material type, shape geometry, and closure category dimensions.
Across the analysis window, projections incorporated segment-specific growth trajectories for biodegradable alternatives, plastic substitution timelines under regulatory frameworks, and cloud kitchen penetration curves. Modeled dimensions spanned material chemistry, dimensional geometry, closure security features, and end-use channel concentration. CAGRs were derived from regression analysis of historical volume patterns and elasticity estimates for regulatory-driven substitution events. Forecast inputs included pressed-fiber automation cost curves and third-party delivery platform market share trajectories.
Forecasts assume regulatory continuity in California SB 54 implementation, EU Single-Use Plastics Directive enforcement, and Canadian single-use plastics restrictions; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Two Compartment Bottles Market
Containers
Global Food Containers Market
Containers
Vacuum Formed Tray Market
Containers
Acrylic Container Market
Containers
Spout Containers Market
Containers
Pail Lids Market
Containers
Pails Market
Containers
Dispensing Jug Market
Containers
Slotted Containers Market
Containers
Global Cardboard Box and Container Market
Containers
Wide Mouth Jars Market
Containers
Trays Market
Containers
Multi-Layer Blow Molded Containers Market
Containers
PUR Containers Packaging Market
Containers
Intermediate Bulk Container Liner Market
Containers
Light Resistant Containers Market