
 Multi Cavity Tray Market | 2026-2036
Multi Cavity Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Multi Cavity Tray Market Outlook
Asset-light leasing models for thermoforming equipment is rewriting competitive entry dynamics in the multi cavity tray sector. Sonoco Products Company leverages captive fiber supply to anchor its paperboard tray operations across North American protein packaging. Huhtamaki Oyj sustains geographic dominance in European fresh-food retail through localized thermoforming capacity. Pactiv Evergreen Inc. differentiates via integrated resin-to-tray verticality that controls cost volatility in polystyrene and PET formats.
Multi cavity trays are thermoformed or pressed containers featuring multiple discrete compartments, typically manufactured through vacuum forming, pressure forming, or injection molding processes with wall thicknesses ranging from 0.010 to 0.080 inches depending on structural load requirements. These trays serve primary functions in product segregation, portion control, and automated handling compatibility across high-speed packaging lines. Plastic variants dominate current volume owing to cost efficiency and barrier tunability, though paperboard segments are capturing margin pools as retail brands pursue shelf-ready display functionality. Custom cavity configurations represent the fastest-growing form factor dimension, driven by pharmaceutical serialization requirements and electronics component nesting precision.
The FDA enforces strict material migration limits for food-contact polymers under 21 CFR, directly shaping resin selection and multi-layer coextrusion investments by tray converters. EFSA and the EU Packaging and Packaging Waste Regulation jointly drive fiber tray innovation through recyclability thresholds and extended producer responsibility fee structures. China's SAMR implements GB standards for food packaging safety that govern import access for foreign tray suppliers. Stakeholders must monitor evolving state-level recycled-content mandates and pharmaceutical track-and-trace compatibility standards to preserve market access and pricing power.
Market Dynamics
Pharmaceutical cold-chain logistics is expanding uptake of aluminum and PET cavity formats, while the EU Packaging and Packaging Waste Regulation tightens recyclability mandates that push converters toward fiber-based and mono-material tray designs.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability thresholds and extended producer responsibility fee structures drive fiber tray innovation across European fresh-food retail channels.
- Pharmaceutical serialization requirements:Custom cavity configurations capture margin pools as contract packers demand precision nesting for track-and-trace compatibility.
- Rhine-Ruhr manufacturing belt:Food processors and pharma contract packers cluster around this German industrial corridor, concentrating demand for high-volume thermoforming capacity.
Market Restraints
- Polystyrene resin volatility:Integrated converters with captive resin supply control cost swings that squeeze independent thermoformers operating on spot purchases.
- Aluminum supply concentration:Primary aluminum smelting capacity concentrates in specific geographies, exposing tray manufacturers to energy-linked input price spikes.
- Multi-layer coextrusion technical limits:Barrier tunability in plastic variants requires capital-intensive equipment that blocks mid-tier entrants from pharmaceutical-grade certification.
Strategic Opportunities
- Asset-light leasing models:Thermoforming equipment leasing rewrites competitive entry dynamics for regional converters lacking balance sheet depth.
- Shelf-ready display functionality:Paperboard segments capture margin pools as retail brands abandon plain plastic for fiber-based merchandising formats.
- China GB standards compliance:Foreign tray suppliers meeting SAMR food packaging safety requirements unlock import access to pharmaceutical and fresh-protein channels.
Industry Challenges
- Pharmaceutical track-and-trace integration:Serialization compatibility standards require IT infrastructure upgrades that strain legacy thermoforming operations.
- Recycled-content mandate compliance:State-level recycled-content thresholds force rapid supply chain reconfiguration without guaranteed feedstock availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi Cavity Tray Market |
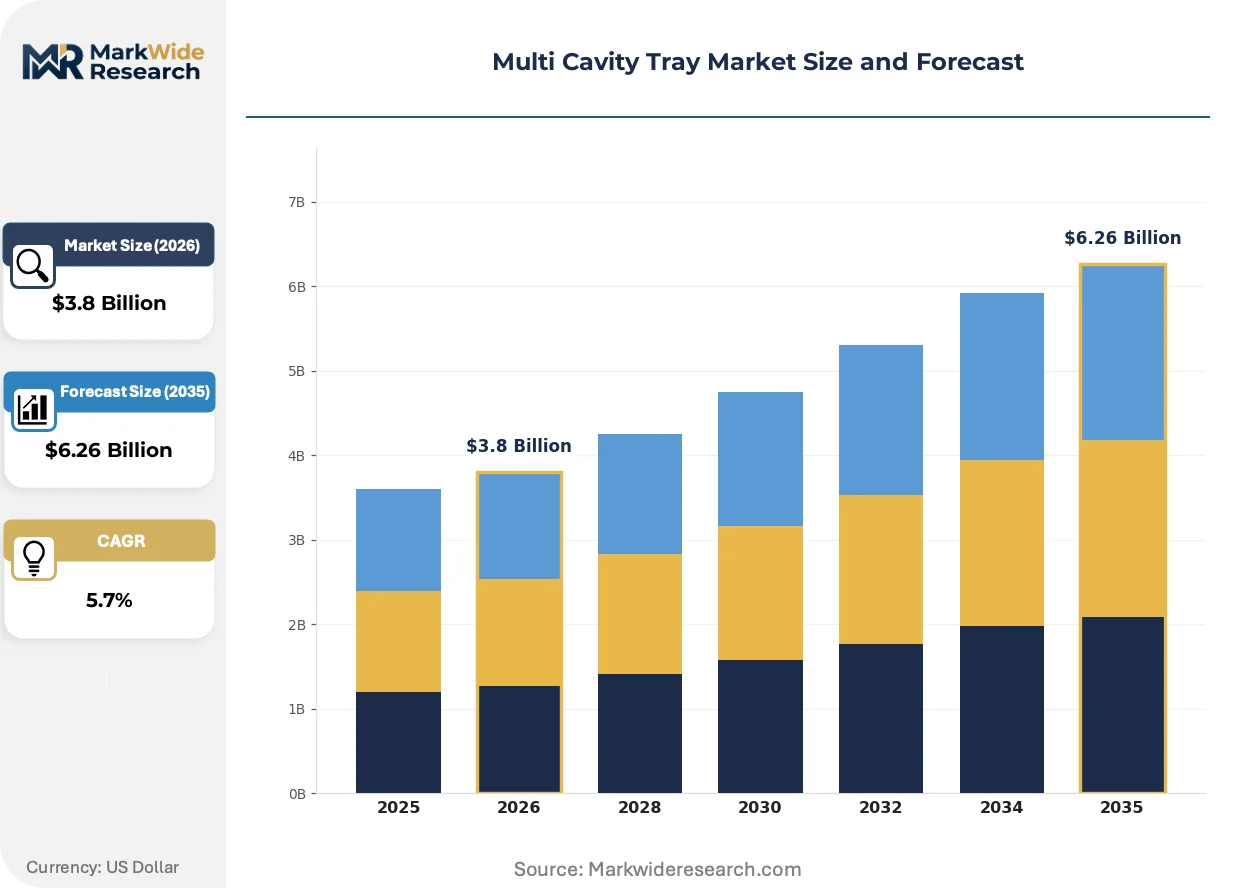
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tray Type: Plastic, Aluminum, Paperboard, PET End User: Food Industry, Pharmaceutical Sector, Electronics, Consumer Goods Form Factor: Standard Cavity, Custom Cavity, Stackable, Folding Functionality: Packaging, Transport, Display, Storage |
| Companies Covered | Sonoco Products Company, Pactiv Evergreen Inc., Huhtamaki Oyj, Amcor Limited, DS Smith Plc, Winpak Ltd., Genpak LLC, Cascades Inc., Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi Cavity Tray Market Strategic Shifts
Mono-material tray architectures and automated handling compatibility specifications are compressing traditional multi-layer designs out of high-speed packaging lines.
Pressure forming with in-mold labeling is collapsing the cost gap between commodity thermoforming and injection-molded precision for pharmaceutical blister applications. Contract packers in Germany and Switzerland are adopting these systems at accelerated replacement cycles. The technology is collapsing legacy equipment amortization schedules and forcing regional converters into earlier capital refresh decisions.
REACH substance restrictions and the EU Green Deal's packaging recyclability targets are tightening material migration limits for food-contact polymers. EFSA guidance on mineral oil saturated hydrocarbons in recycled fiber is redirecting converter R&D spend toward virgin pulp alternatives and barrier coating innovations. Fresh-food retail channels across France and the Netherlands are responding with SKU rationalization toward certified mono-material formats.
Leasing-based equipment access is displacing ownership models among mid-tier protein packers seeking flexibility without balance sheet encumbrance. Third-party logistics providers are inserting themselves as financing intermediaries, bundling tray supply with line integration services. This pattern concentrates in North American beef and poultry processing regions where volume volatility rewards variable cost structures over fixed asset commitments.
Multi Cavity Tray Market Segmentation
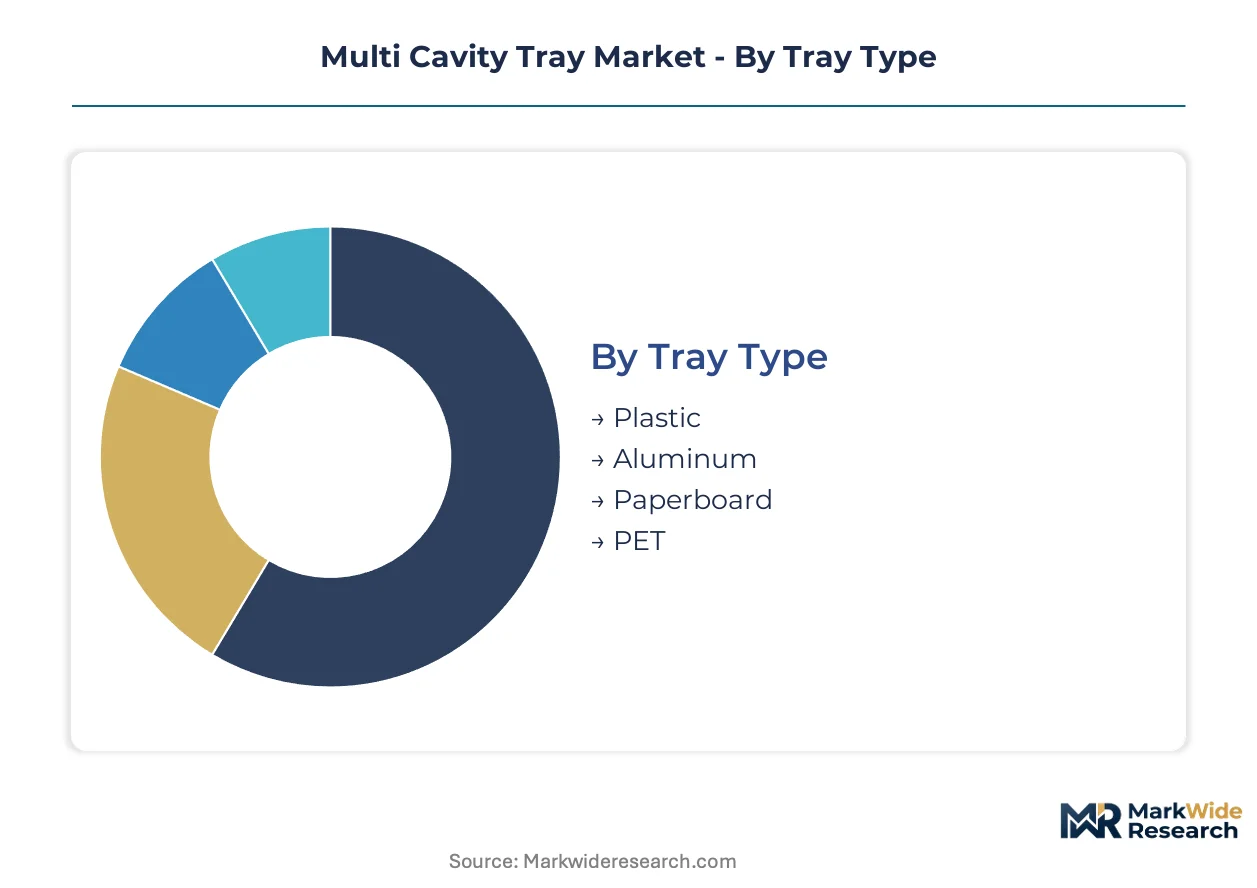
Multi cavity tray segmentation reveals divergent margin structures across material classes and functional specifications. Pharmaceutical serialization requirements and EU recyclability mandates are reshaping demand concentration within each dimension, forcing converters to align capacity with high-certification end uses.
Tray Type:
Cost tier differentiation separates commodity resin formats from barrier-tunable premium substrates in thermoforming operations.
- Plastic:Polystyrene and polypropylene variants dominate unit economics through vacuum forming efficiency. Food processors in Germany's Rhine-Ruhr belt consume high volumes for fresh-protein portioning, though EFSA migration limits are compressing allowable resin grades.
- PET:Crystalline clarity and moisture barrier properties position this substrate for pharmaceutical cold-chain logistics. Contract packers in Switzerland specify PET for track-and-trace blister compatibility where barrier tunability exceeds fiber alternatives.
- Aluminum:Formed foil trays serve temperature-extreme applications with complete light and gas barrier performance.
- Paperboard:Fiber-based formats capture shelf-ready display functionality as retail brands abandon plain plastic for merchandising compliance with EU Green Deal targets.
Plastic holds installed capacity. PET is rotating up the share rankings.
End User:
Application-specific certification requirements fragment converter capabilities across pharmaceutical, food, and electronics channels.
- Pharmaceutical Sector:Serialization mandates demand custom cavity precision for unit-dose tracking. FDA 21 CFR material migration limits and EU MDR technical documentation requirements filter supplier pools to thermoformers with validated cleanroom operations.
- Food Industry:Fresh-protein and ready-meal channels drive volume throughput with standardized cavity configurations. Germany's retail consolidation around private-label brands concentrates procurement power with converters offering mono-material recyclability credentials.
- Electronics:Component nesting precision requires anti-static formulations and ESD-safe handling specifications.
- Consumer Goods:Cosmetic and personal care applications prioritize visual differentiation through pressure-formed clarity and in-mold labeling compatibility.
Food Industry anchors volume throughput. Pharmaceutical Sector commands the steepest expansion trajectory.
Form Factor:
Volume scalability versus customization depth defines competitive positioning across cavity standardization levels.
- Custom Cavity:Precision-engineered compartment geometries serve pharmaceutical serialization and electronics component nesting where automated handling compatibility is non-negotiable. Swiss and German contract packers pay premiums for cavity-specific tooling amortized across shorter production runs.
- Standard Cavity:Off-the-shelf configurations minimize tooling investment for food industry volume plays. Protein processors in North American beef and poultry channels specify standard formats compatible with legacy thermoforming lines.
- Stackable:Nesting ratio optimization reduces cube utilization in downstream logistics.
- Folding:Flat-ship designs compress inbound freight costs for retail display assembly.
Standard Cavity retains tooling amortization advantages. Custom Cavity is climbing the fastest as serialization spreads.
Functionality:
Customer type separation distinguishes pure-play packaging converters from integrated supply-chain service providers.
- Packaging:Primary containment functions dominate unit economics with barrier specifications tuned to product shelf-life requirements. FDA and EFSA material migration limits directly shape resin selection and multi-layer coextrusion investments.
- Display:Shelf-ready merchandising functionality commands margin premiums in European fresh-food retail. Fiber-based formats with certified recyclability credentials capture SKU rationalization trends in France and the Netherlands.
- Transport:Structural load specifications drive wall thickness engineering for automated handling compatibility.
- Storage:Long-duration archival applications emphasize chemical stability and stack-load retention.
Packaging absorbs baseline capacity. Display is gaining share fastest as retail brands prioritize merchandising compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters extract premium pricing for pharmaceutical-grade certification that US protein packers cannot command for commodity formats. Swiss cold-chain logistics operators pay cavity-specific tooling premiums unavailable in standardized North American beef channels. This asymmetry reflects divergent regulatory stringency and end-use certification requirements across major demand centers.
Germany
Rhine-Ruhr manufacturing belt concentration drives thermoforming capacity for fresh-protein portioning and pharma contract packing. EFSA material migration limits and EU Packaging and Packaging Waste Regulation recyclability thresholds filter supplier pools to converters with validated cleanroom operations. Düsseldorf and Cologne host dense clusters of food processors and pharmaceutical packers demanding mono-material tray credentials.
Switzerland
Pharmaceutical serialization mandates from Swissmedic propel custom cavity precision for unit-dose track-and-trace compatibility. REACH substance restrictions tighten material selection for cold-chain logistics applications. Basel and Zurich pharmaceutical hubs concentrate demand for PET barrier formats that exceed fiber alternatives in moisture protection.
United States
Beef and poultry processors in the Midwest and Southeast specify standard cavity configurations compatible with legacy thermoforming lines. FDA 21 CFR enforcement shapes resin selection for food-contact polymers. Kansas and Nebraska protein packing corridors drive volume throughput where leasing-based equipment access displaces ownership models.
China
SAMR GB standards compliance governs import access for foreign tray suppliers targeting pharmaceutical and fresh-protein channels. Dual carbon goals accelerate fiber tray substitution in premium retail segments. Yangtze River Delta manufacturing zones concentrate thermoforming capacity for electronics component nesting precision.
France
Fresh-food retail channels respond to EU Green Deal packaging recyclability targets with SKU rationalization toward certified mono-material formats. ANSM pharmaceutical guidance aligns with EMA technical documentation requirements for barrier specifications. Paris and Lyon retail consolidation concentrates procurement power with converters offering shelf-ready display functionality.
Multi Cavity Tray Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying resin, fiber, and tooling to converters lacking captive material access. The vendor base stratifies across integrated multinationals with resin-to-tray verticality, regional thermoformers leasing equipment for flexibility, and paperboard specialists leveraging fiber supply advantages. Three archetypes dominate: resin-integrated volume players, fiber-based sustainability specialists, and precision-focused pharmaceutical-grade converters. Capacity expansion and strategic partnerships represent the dominant competitive moves, with asset-light leasing models rewriting entry dynamics for mid-tier regional operators.
Among North American integrated packaging conglomerates, Sonoco Products Company and Pactiv Evergreen Inc. occupy positions reflecting divergent material strategies—fiber supply anchoring versus resin verticality. Huhtamaki Oyj exemplifies the European geographic dominance archetype through localized thermoforming capacity serving fresh-food retail channels. These three entities represent distinct competitive positioning vectors: captive fiber integration, resin-to-tray cost control, and continental-scale localized manufacturing networks.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Pactiv Evergreen Inc. |
| Huhtamaki Oyj |
| Amcor Limited |
| DS Smith Plc |
| Winpak Ltd. |
| Genpak LLC |
| Cascades Inc. |
| Sealed Air Corporation |
| Others |
Value Chain & Pricing Dynamics
Rhine-Ruhr freight corridors anchor cost dynamics for polystyrene resin inbound from Rotterdam and fiber pulp from Nordic mills, compressing margin structures for independent thermoformers while amplifying pricing power for integrated converters with captive material access and direct rail siding contracts.
Pricing Analysis
The customization-premium spread separates commodity standard cavity formats from pharmaceutical-grade custom configurations. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and barrier tunability requirements. Cost compression in polystyrene spot markets is intensifying because integrated resin-to-tray players control input volatility that squeezes independent converters. Food processors in North American beef channels exhibit highest price sensitivity, while Swiss pharmaceutical contract packers show lowest sensitivity due to serialization compliance premiums.
Supply Chain Analysis
Upstream feedstock concentration centers on Saudi Arabia and South Korea for virgin polystyrene resin, with Nordic pulp mills supplying kraft fiber for paperboard tray operations. Raw material dependencies rest on aluminum ingot from GCC smelters, PET chip from Asian polymerization plants, and barrier coatings from German chemical specialists. Single-source vulnerability runs through pharmaceutical-grade PET supply where Swissmedic certification requirements filter qualified resin grades. Distribution runs through third-party logistics providers bundling tray supply with line integration services across North American protein processing regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around Germany's retail consolidation and North American beef processor oligopoly, fragmenting converter margins as procurement committees extract mono-material recyclability commitments at volume-discounted terms.
For Market Incumbents: Insulate pharmaceutical-grade certification premiums by accelerating cleanroom capacity additions in Basel and Düsseldorf corridors before REACH substance restrictions tighten further. Backward integration into captive fiber pulp supply secures margin defense against EFSA mineral oil guidance redirecting R&D spend toward virgin alternatives. Threat substitution from pressure-formed PET with in-mold labeling demands earlier capital refresh cycles than legacy equipment amortization schedules allow. For New Entrants and Emerging Players: China's Yangtze River Delta electronics nesting precision represents underpenetrated white space where SAMR GB compliance barriers filter foreign competition less aggressively than pharmaceutical channels. Leasing-based thermoforming equipment access unlocks regional protein packing corridors in Nebraska and Kansas without balance sheet encumbrance. Go-to-market angle: bundle tray supply with automated handling line integration services mirroring third-party logistics provider financing intermediation. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated packaging conglomerates divesting non-core thermoforming assets to focus on resin verticality or fiber-based sustainability positioning. Long-term viability favors precision-focused pharmaceutical-grade converters with validated cleanroom operations and Swissmedic technical documentation capabilities over commodity protein packers facing polystyrene resin volatility. Signal to watch: accelerated replacement cycles for pressure forming with in-mold labeling systems collapsing legacy equipment amortization schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Asset-Light Equipment Leasing | Third-party logistics providers bundle tray supply with line integration services across Midwest beef corridors. |
| Mono-Material Format Certification | EU Packaging and Packaging Waste Regulation recyclability thresholds filter supplier pools to validated converters. |
| Pharmaceutical Cleanroom Expansion | Swissmedic serialization mandates propel custom cavity precision investments in Basel pharmaceutical hubs. |
| Captive Fiber Supply Integration | Nordic pulp mill contracts anchor paperboard tray cost control against EFSA mineral oil saturated hydrocarbon guidance. |
| Pressure Forming Technology Refresh | In-mold labeling compatibility collapses cost gap with injection molding for German contract packers. |
Study Parameters
Initial hypotheses were tested against primary input from thermoforming plant managers, pharmaceutical contract packer procurement leads, retail category buyers, and barrier coating R&D directors and refined through secondary validation against FDA 21 CFR filings, EFSA scientific opinions, EU Packaging and Packaging Waste Regulation impact assessments, and customs trade data for polystyrene and PET resin flows. Bottom-up capacity modeling across German Rhine-Ruhr and Swiss Basel manufacturing belts triangulated with top-down demand aggregation from food processor and pharma packer clusters.
Demand-supply-balance framing anchored volume projections across the analysis window, with segmentation dimensions spanning material class, cavity configuration standardization, end-use certification requirements, and regional regulatory cluster stringency. CAGRs were derived from installed thermoforming capacity utilization rates cross-referenced with pharmaceutical serialization mandate implementation timelines and EU Green Deal packaging recyclability target compliance curves.
Macroeconomic conditions sit as an overlay; deviation in energy-linked aluminum smelting costs and ocean freight rates for Asian PET chip would shift the trajectory. Cross-checking against EPC contractor equipment order backlogs and thermoforming machinery OEM lead times is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
High Density Polyethylene (HDPE) Bottles Market
Containers
Sample Containers Market
Containers
Club Store Packaging Tray Market
Containers
Safety Bottle Tote Carriers Packaging Market
Containers
Injection Molding Containers Market
Containers
Packaging Bins Market
Containers
Flexible Water Tanks Market
Containers
Compartment Take-Out Container Market
Containers
Old Corrugated Containers (OCC) Market
Containers
Acrylic Container Market
Containers
Composite Ibcs System Market
Containers
Clear Hinged Container Market
Containers
Container Coating Market
Containers
EPS Container Market
Containers
Child-Resistant Containers Market
Containers
Dual-Ovenable Trays and Containers Market